
 Sustainable Clothing Brand Market | 2026-2036
Sustainable Clothing Brand Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Clothing Brand Market Insights
Millennial and Gen Z purchasing power is hardening as the dominant demand vector for sustainable apparel, shifting brand investment toward digital-first engagement and resale platform integration. Patagonia leverages its repair-and-resale infrastructure to sustain premium positioning without seasonal discounting. Stella McCartney anchors luxury credibility through decade-long partnerships with material innovators like Bolt Threads and Mylo. PANGAIA differentiates via science-communicated product narratives that command full-price sell-through rates.
Sustainable clothing brands design, manufacture, and distribute apparel using certified organic, recycled, or bio-based fibers with verified supply chain transparency, typically incorporating closed-loop dye processes and carbon-offset logistics to minimize environmental footprint. The primary commercial purpose centers on capturing value from consumers who prioritize verified environmental accountability over fast-fashion convenience. Organic cotton and Tencel dominate unit volumes as these fibers offer scalable certification pathways and established farmer networks, while recycled polyester leads growth rates tied to ocean plastic recovery programs and athleticwear demand. Direct-to-Consumer channels capture the deepest margin pools by eliminating wholesale markups, though specialty stores remain critical for tactile validation of premium fabric claims.
The EU Green Deal's textile strategy and ECHA REACH chemical restrictions are tightening fiber traceability mandates, forcing brands to restructure supplier audits or face market exclusion across Europe. The US Federal Trade Commission's Green Guides and California's SB 657 transparency requirements create a dual-compliance burden for cross-border operators. Stakeholders must monitor whether emerging bio-fabrication certifications achieve regulatory equivalence with established organic standards before committing capital to next-generation material platforms.
Market Dynamics
Extended producer responsibility frameworks across the European Union are forcing apparel brands to internalize end-of-life garment costs, fundamentally restructuring sourcing economics and supplier qualification protocols.
Growth Catalysts
- EU Green Deal textile strategy:Mandatory fiber traceability requirements are accelerating certified organic cotton adoption across supplier networks.
- Gen Z digital-native purchasing:Resale platform integration creates recurring revenue streams without seasonal discounting pressure.
- Ocean plastic recovery programs:Recycled polyester feedstock from marine waste recovery is scaling athleticwear production volumes.
Market Restraints
- Organic cotton price volatility:Weather-dependent yields in India and Turkey create input cost instability for certified fiber contracts.
- Biomaterial certification gaps:Mylo and Bolt Threads products lack regulatory equivalence with established organic standards, delaying wholesale adoption.
- Dual-compliance burden:Cross-border operators face simultaneous FTC Green Guides and California SB 657 audit requirements.
Strategic Opportunities
- South Korea circular fashion ecosystem:Government-backed textile recycling infrastructure creates favorable entry conditions for certified brands.
- Direct-to-consumer channel expansion:Eliminating wholesale markups captures margin pools while enabling transparent supply chain storytelling.
- Bio-fabrication regulatory convergence:Early alignment with emerging ECHA certification pathways secures first-mover positioning in next-generation materials.
Industry Challenges
- Closed-loop dye process engineering:Technical talent scarcity in waterless coloration systems constrains production scaling.
- Carbon-offset logistics verification:Third-party audit complexity extends certification timelines for shipping emissions claims.
- Legacy ERP integration:Supplier traceability data standards conflict with existing enterprise resource planning architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Clothing Brand Market |
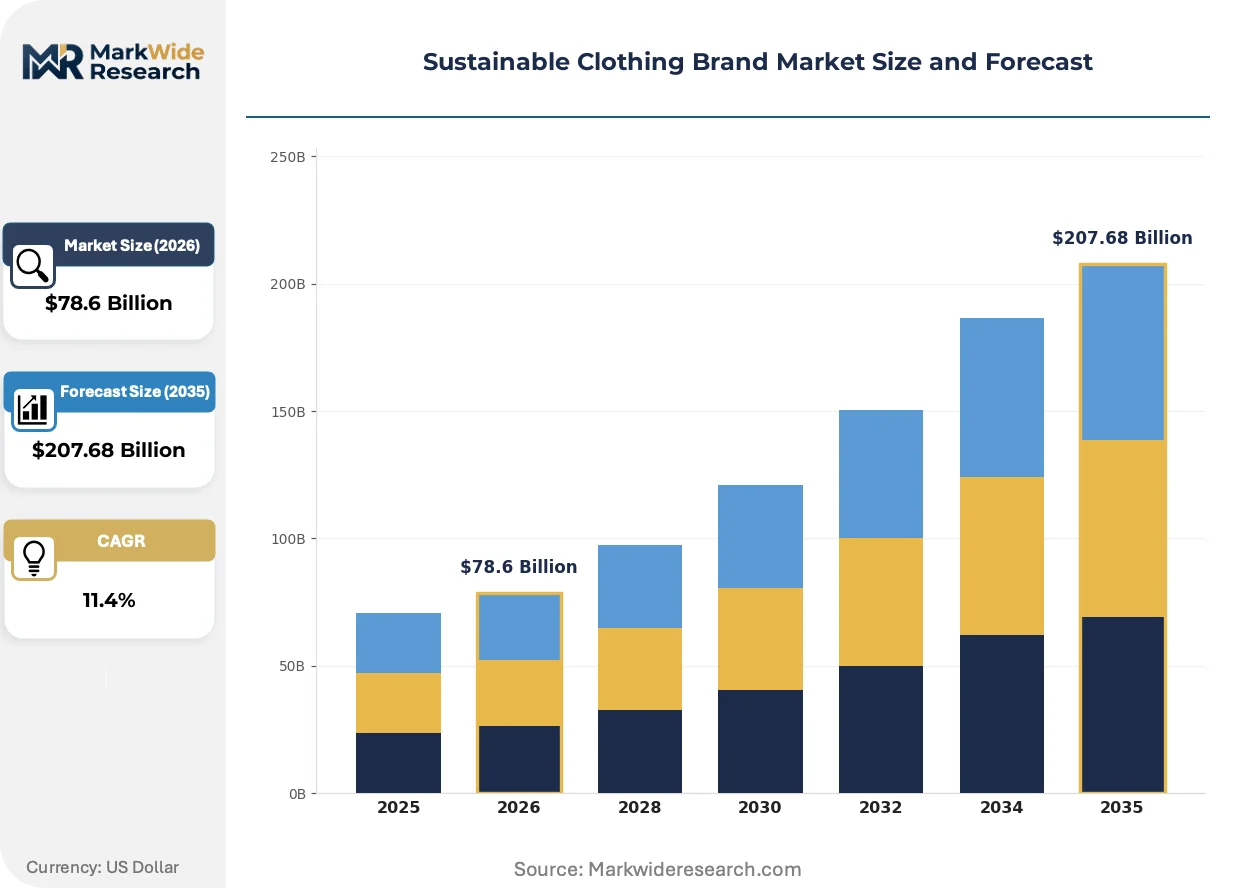
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $207.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Cotton, Recycled Polyester, Hemp, Tencel Distribution Channel: Online Retail, Specialty Stores, Direct-to-Consumer, Wholesale Price Tier: Luxury, Mid-Range, Budget, Premium Target Audience: Eco-Conscious Consumers, Fashion Enthusiasts, Athletes, Kids |
| Companies Covered | Patagonia, Stella McCartney, PANGAIA, Outerknown, Eileen Fisher, Wholesome Culture, Christy Dawn, Finisterre, Vuori, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Clothing Brand Market Trends and Innovations
Bio-fabrication technologies and circular service models are compressing traditional seasonal production cycles while elevating transparency requirements across every tier of the apparel value chain.
Mylo mycelium leather is rewriting material substitution economics in luxury accessories and footwear categories. Premium fashion houses are adopting Bolt Threads' bio-fabricated alternatives at pilot scale for handbag and shoe collections. This technology is rewriting competitive positioning by decoupling premium pricing from petroleum-based synthetic dependencies.
ECHA REACH chemical restrictions are tightening permissible substance thresholds in textile finishing processes. Dye houses across Germany and the Netherlands are retrofitting facilities to eliminate per- and polyfluoroalkyl substances ahead of enforcement deadlines. Athleticwear brands with synthetic-heavy portfolios face the steepest reformulation costs and are accelerating partnerships with waterless dye technology providers.
Digital product passports are displacing static hangtag claims as the primary consumer trust mechanism. Specialty retailers in Berlin and Copenhagen are piloting QR-code-linked supply chain visualization tools that validate organic certification at point of sale. Germany's mature circular fashion infrastructure is producing the highest adoption rates for blockchain-anchored transparency systems.
Sustainable Clothing Brand Market Segmentation
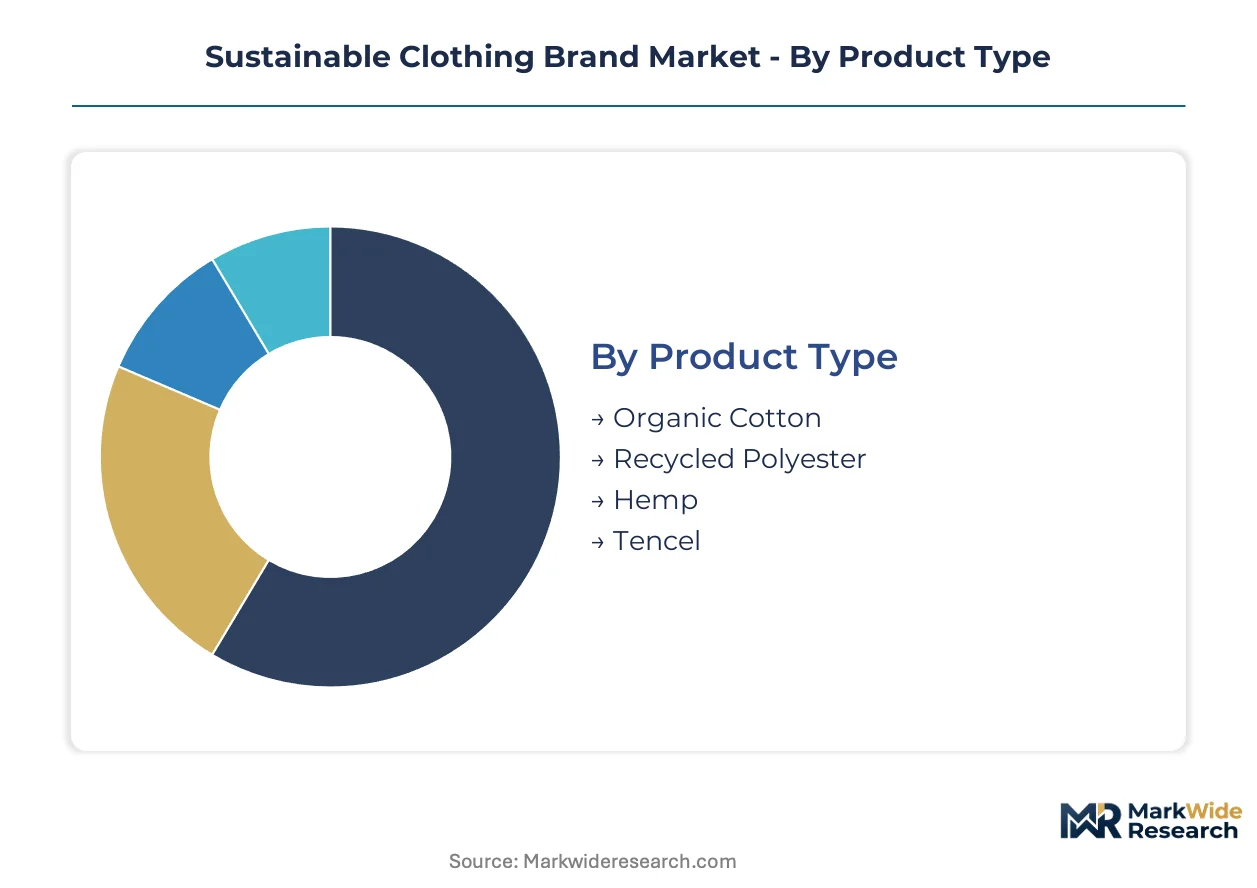
Segmentation in sustainable apparel reveals how fiber certification, channel economics, and price architecture interact to determine margin capture. Each dimension carries distinct compliance burdens and storytelling requirements that shape brand positioning strategies.
Product Type:
Standardization dominates at the fiber level through certification protocols, while customization emerges in blended compositions and finish treatments that differentiate end-use performance.
- Organic Cotton:Certified fiber grown without synthetic pesticides or fertilizers under USDA National Organic Program or EU organic regulations. Demand concentrates in Germany and the United States where EU Green Deal traceability mandates and California SB 657 transparency requirements drive verified sourcing contracts.
- Recycled Polyester:Post-consumer and ocean-recovered PET reprocessed into textile-grade filament. Athleticwear brands in South Korea and the United States scale volumes through marine plastic recovery partnerships that satisfy ESG disclosure requirements.
- Hemp:Low-input bast fiber requiring minimal irrigation and no pesticide application. European textile mills in the Netherlands and France pioneer decortication infrastructure for apparel-grade softness.
- Tencel:Lyocell fiber produced via closed-loop solvent recovery systems at Lenzing's Austrian and Chinese facilities. Austrian-engineered production achieves near-complete chemical recycling.
Leading the category by volume: Organic Cotton. Growing fastest: Recycled Polyester.
Distribution Channel:
Margin architecture varies sharply across channels, with direct relationships capturing value that wholesale relationships surrender to intermediary markups.
- Online Retail:Third-party marketplace listings on platforms with established sustainability filters and verification badges. Zalando's sustainability flagging system in Germany drives discovery for certified brands.
- Specialty Stores:Curated physical environments enabling tactile validation of fabric claims and certification documentation. Berlin and Copenhagen boutiques pilot blockchain-anchored QR code verification at point of sale.
- Direct-to-Consumer:Brand-controlled digital storefronts eliminating wholesale markups while enabling transparent supply chain storytelling. Patagonia's repair-and-resale integration sustains full-price positioning.
- Wholesale:Department store and multi-brand boutique relationships requiring margin sacrifice for reach expansion. ECHA REACH compliance documentation burdens constrain smaller brand participation.
Direct-to-Consumer commands the deepest margin pools. Specialty Stores deliver the highest conversion rates for first-time sustainable purchasers.
Price Tier:
Certification depth and supply chain transparency investment separate tiers, with verification costs creating natural floor pricing that budget positioning struggles to absorb.
- Luxury:Hand-finished garments with blockchain-verified fiber provenance and artisan atelier documentation. Stella McCartney's Bolt Threads partnerships anchor material innovation credibility.
- Premium:Full-price positioning supported by repair infrastructure and resale platform integration. PANGAIA's science-communicated narratives command sell-through without discounting.
- Mid-Range:Accessible sustainability through certified organic basics and limited capsule collections. H&M's Conscious line navigates FTC Green Guides compliance for mass-market scaling.
- Budget:Entry-level certified products with reduced verification depth and simpler fiber compositions. Shein's emerging sustainability tier faces EU Green Deal due diligence scrutiny.
Premium captures the fastest expansion trajectory. Luxury maintains the highest per-unit margins.
Target Audience:
Digital-native purchasing behaviors concentrate in generational cohorts, while performance requirements drive material specifications in athletic segments.
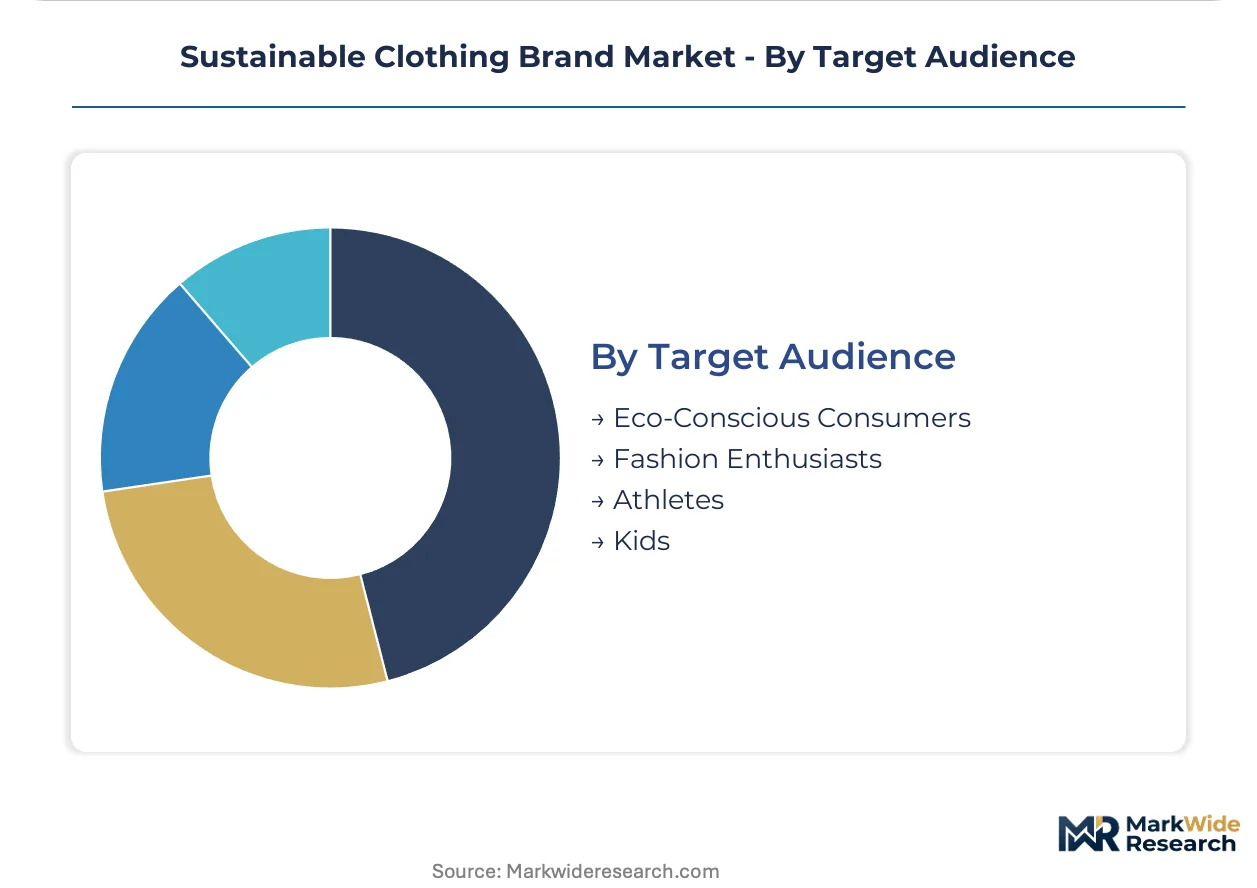
- Eco-Conscious Consumers:Primary demand vector spanning Millennial and Gen Z cohorts with willingness-to-pay premiums for verified accountability. German and South Korean markets show highest adoption rates for circular fashion services.
- Fashion Enthusiasts:Trend-responsive purchasers prioritizing aesthetic novelty within sustainability constraints. Copenhagen Fashion Week's sustainability requirements reshape designer brand collections.
- Athletes:Performance-driven demand for moisture-wicking recycled polyester and compression fabrics. Ocean plastic recovery programs supply feedstock for athleticwear expansion.
- Kids:Parental purchasing decisions prioritizing chemical safety and durability for extended wear cycles. OEKO-TEX Standard 100 certification dominates this segment's trust architecture.
Eco-Conscious Consumers anchor category volume. Athletes represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Asian textile hubs while consumption clusters in Western markets with mature sustainability infrastructure. Germany, the United States, and South Korea anchor demand through circular fashion policy frameworks. Supply chain transparency investments separate premium positioning from mass-market participation.
United States
Millennial and Gen Z purchasing power drives direct-to-consumer platform adoption. California's SB 657 transparency requirements mandate supply chain disclosure for retailers operating in the state. Los Angeles hosts emerging sustainable denim clusters where waterless dye facilities attract venture-backed brand headquarters.
Germany
EU Green Deal textile traceability mandates accelerate certified organic cotton contracting. ECHA REACH chemical restrictions force reformulation of textile finishing processes ahead of enforcement deadlines. Berlin specialty retailers pilot blockchain-anchored digital product passports at point of sale.
South Korea
Government-backed textile recycling infrastructure creates favorable entry conditions for certified brands. MFDS chemical safety standards align with EU regulatory convergence trends. Seoul's fashion district integrates resale platform partnerships into premium brand flagship operations.
Netherlands
Circular fashion pilot programs in Amsterdam drive closed-loop service model experimentation. National extended producer responsibility frameworks internalize end-of-life garment costs for operating brands. Rotterdam logistics corridors enable carbon-offset shipping verification for direct-to-consumer distribution.
France
Luxury heritage houses anchor bio-fabrication partnerships for material innovation credibility. ANSM chemical oversight extends to textile finishing substance thresholds. Paris Fashion Week sustainability requirements reshape designer collection planning cycles.
Sustainable Clothing Brand Market Competitive Landscape
Top-tier vendors anchor premium positioning through repair infrastructure and material science partnerships, while mid-range players navigate FTC Green Guides compliance for mass-market scaling. The vendor base stratifies across certification depth tiers rather than consolidating around scale advantages. Three archetypes dominate: heritage outdoor brands with resale platform integration, luxury houses with bio-fabrication alliances, and digital-native labels with science-communicated product narratives. Competitive moves center on strategic partnerships with material innovators and backward integration into supplier traceability systems.
Within the heritage outdoor archetype, Patagonia occupies a position defined by repair-and-resale infrastructure investment. Stella McCartney exemplifies the luxury bio-fabrication vector through decade-long material innovation partnerships. PANGAIA represents the digital-native science-communication model with full-price positioning strategies.
| Leading Market Players |
|---|
| Patagonia |
| Stella McCartney |
| PANGAIA |
| Outerknown |
| Eileen Fisher |
| Wholesome Culture |
| Christy Dawn |
| Finisterre |
| Vuori |
| Others |
Pricing and Supply Chain Analysis
Family-owned textile mills in Portugal and Turkey anchor mid-tier sustainable apparel supply, translating generational supplier relationships into pricing discipline that resists commodity volatility. Their patient capital structures enable long-dated organic cotton contracting that insulates premium brands from spot-market swings while locking in margin stability.
Pricing Analysis
Margin tightening in the mid-range tier reflects dual-compliance burdens from simultaneous FTC Green Guides and California SB 657 audit requirements. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-verified luxury positioning from entry-level certified basics. Cost-down pressure on organic cotton basics accelerates because weather-dependent yields in India and Turkey create input instability. Budget-tier purchasers show highest price sensitivity, while luxury buyers demonstrate inelastic demand for verified provenance.
Supply Chain Analysis
Carbon-offset shipping verification through Rotterdam logistics corridors adds documentation overhead to trans-Atlantic freight economics. Manufacturing concentrates in Portugal, Turkey, and Vietnam, with raw material dependencies on Indian organic cotton, Austrian Tencel feedstock, and ocean-recovered PET from Southeast Asian marine collection programs. Single-source vulnerability in Indian cotton fiber exposes brands to monsoon-driven yield shocks. Distribution runs through direct-to-consumer brand storefronts and Berlin-Copenhagen specialty retail clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU Green Deal textile traceability mandates erect barrier-to-entry moats favoring incumbent players with established certification infrastructure.
For Market Incumbents: Anticipate biomaterial certification gaps delaying Mylo and Bolt Threads wholesale adoption, then accelerate backward integration into supplier traceability systems before ECHA equivalence standards crystallize. Lock in multi-year organic cotton offtake agreements in Turkey and India to defend fiber cost position against emerging digital-native competitors.
For New Entrants and Emerging Players: Capture white-space opportunity in South Korea's government-backed circular fashion ecosystem, where textile recycling infrastructure reduces capital requirements for certified brand entry. Target the athleticwear segment with ocean-plastic-recovered polyester positioning, leveraging marine waste recovery partnerships as differentiated go-to-market narrative.
For Investors and Strategic Acquirers: Distressed-cycle entries favor repair-and-resale infrastructure specialists in Germany and the United States, where circular service models command premium valuations. Monitor ECHA bio-fabrication certification pathway convergence as inflection signal for next-generation material platform viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Repair-and-Resale Platform Integration | Patagonia's infrastructure sustains full-price positioning without seasonal discounting pressure. |
| Bio-Fabrication Partnership | Stella McCartney's Bolt Threads alliance anchors luxury credibility through decade-long material innovation. |
| Digital Product Passport Deployment | Berlin retailers pilot blockchain-anchored QR verification displacing static hangtag claims. |
| Direct-to-Consumer Channel Expansion | PANGAIA's science-communicated narratives capture margin pools through transparent supply chain storytelling. |
| Organic Cotton Supplier Integration | Long-dated contracting with Turkish and Indian growers insulates against weather-driven yield volatility. |
Research Methodology
Independent corroboration across brand sustainability officers, textile mill procurement directors, and specialty retail buyers underwrites the qualitative findings in this study. Primary fieldwork with certified fiber suppliers, dye house technical directors, and resale platform operators combined with secondary validation from EU ECHA regulatory filings, USDA National Organic Program certification databases, and California SB 657 disclosure records. Bottom-up segment sizing and top-down market reconciliation triangulate volume estimates.
Rate-of-change decomposition across fiber type, distribution channel, price tier, and target audience dimensions structures the analytical framework over the projection horizon. CAGRs derive from segment-level growth trajectory modeling incorporating certified organic cotton adoption curves, recycled polyester scaling from ocean plastic recovery programs, and direct-to-consumer penetration rates. Industry-specific inputs include EU Green Deal implementation timelines and ECHA REACH chemical restriction enforcement schedules.
The model holds under sustained regulatory tightening in Europe and North America; deviation in biomaterial certification equivalence or cotton yield stability would shift fiber mix assumptions and margin projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Stamp Pad Market
Consumer Goods
Smart Audio Devices Market
Consumer Goods
Reusable Makeup Remover Pad Market
Consumer Goods
North America Electric Fireplace Market
Consumer Goods
Electric Heated Shoes Market
Consumer Goods
Asia-Pacific Pet Food Market
Consumer Goods
Infant Care and Baby Care Equipment Market
Consumer Goods
Loungewear Market
Consumer Goods
Italy Vegan Cosmetics Market
Consumer Goods
Global Organic Hair Color Market
Consumer Goods
Pet Tick and Flea Prevention Market
Consumer Goods
North America Gaming Headsets Market
Consumer Goods
Gaming PC Market
Consumer Goods
Global 4K TV Market
Consumer Goods
Global Smokeless Tobacco Market
Consumer Goods
Wearable Gaming Technology Market