
 Special Education Software Market | 2026-2036
Special Education Software Market Size, Share, and Industry Trends Forecast 2026-2036
Special Education Software Market Analysis
Cloud infrastructure investment across North American ed-tech vendors is realigning how special education software reaches school districts. PowerSchool leverages its established K-12 administrative platform to extend into individualized education plan workflows. Frontline Education competes through specialized compliance modules that anchor state-level reporting requirements. Tobii Dynavox dominates augmentative communication hardware-software integration for students with complex disabilities.
Special education software encompasses digital platforms engineered to administer, track, and individualize learning interventions for students with disabilities under mandated regulatory frameworks. These systems integrate assessment engines, behavioral analytics, and compliance documentation tools to satisfy federal entitlement requirements while adapting instructional content to specific learning profiles. Learning Management System deployments lead product-type adoption where districts consolidate fragmented point solutions, though Assessment Tool modules capture disproportionate margin pools through recurring psychometric licensing. Cloud-Based delivery models are displacing On-Premises installations as cybersecurity standards mature and total cost of ownership advantages compound across multi-site district networks.
The US Department of Education enforces IDEA compliance timelines that shape procurement urgency, while the FDA regulates assistive communication devices that interface with software platforms for students with speech impairments. State education agencies layer additional reporting mandates that fragment vendor certification requirements across jurisdictions. Stakeholders must monitor whether federal special education funding formulas shift toward outcome-based reimbursement mechanisms that would privilege software with embedded progress-monitoring capabilities.
Market Dynamics
Federal IDEA compliance enforcement is compressing procurement cycles for individualized education plan management platforms as districts face audit exposure from paper-based tracking failures.
Growth Catalysts
- IDEA Compliance Timelines:The US Department of Education's strict enforcement of mandated documentation deadlines forces districts to digitize IEP workflows or risk federal funding penalties.
- Cloud Migration:Maturing cybersecurity standards for educational data enable multi-site district networks to consolidate fragmented point solutions onto centralized SaaS architectures.
- Psychometric Assessment Demand:School psychologists require embedded progress-monitoring engines to satisfy state-level reporting mandates for disability identification accuracy.
Market Restraints
- State Reporting Fragmentation:Non-standardized data exchange requirements across state education agencies force vendors to maintain jurisdiction-specific certification modules.
- Assistive Device Integration Costs:FDA-regulated augmentative communication hardware demands proprietary software interfaces that limit vendor interoperability.
- District IT Budget Volatility:Reliance on federal special education funding streams creates procurement hesitation when appropriations face congressional uncertainty.
Strategic Opportunities
- Behavioral Analytics Convergence:Integration of biometric sensors with IEP platforms enables real-time intervention triggering for students with emotional disturbance classifications.
- Outcome-Based Reimbursement Pivot:Proposed federal funding formula shifts would privilege platforms demonstrating measurable student progress against individualized goals.
- Rural District Underservice:Teletherapy-enabled software modules address specialist shortages in non-urban geographies lacking school psychologist density.
Industry Challenges
- Specialized Implementation Talent:Districts struggle to hire personnel capable of configuring assessment engines to match specific disability category workflows.
- Legacy Student Information System Integration:Proprietary data formats in incumbent administrative platforms create API friction during special education module deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Special Education Software Market |
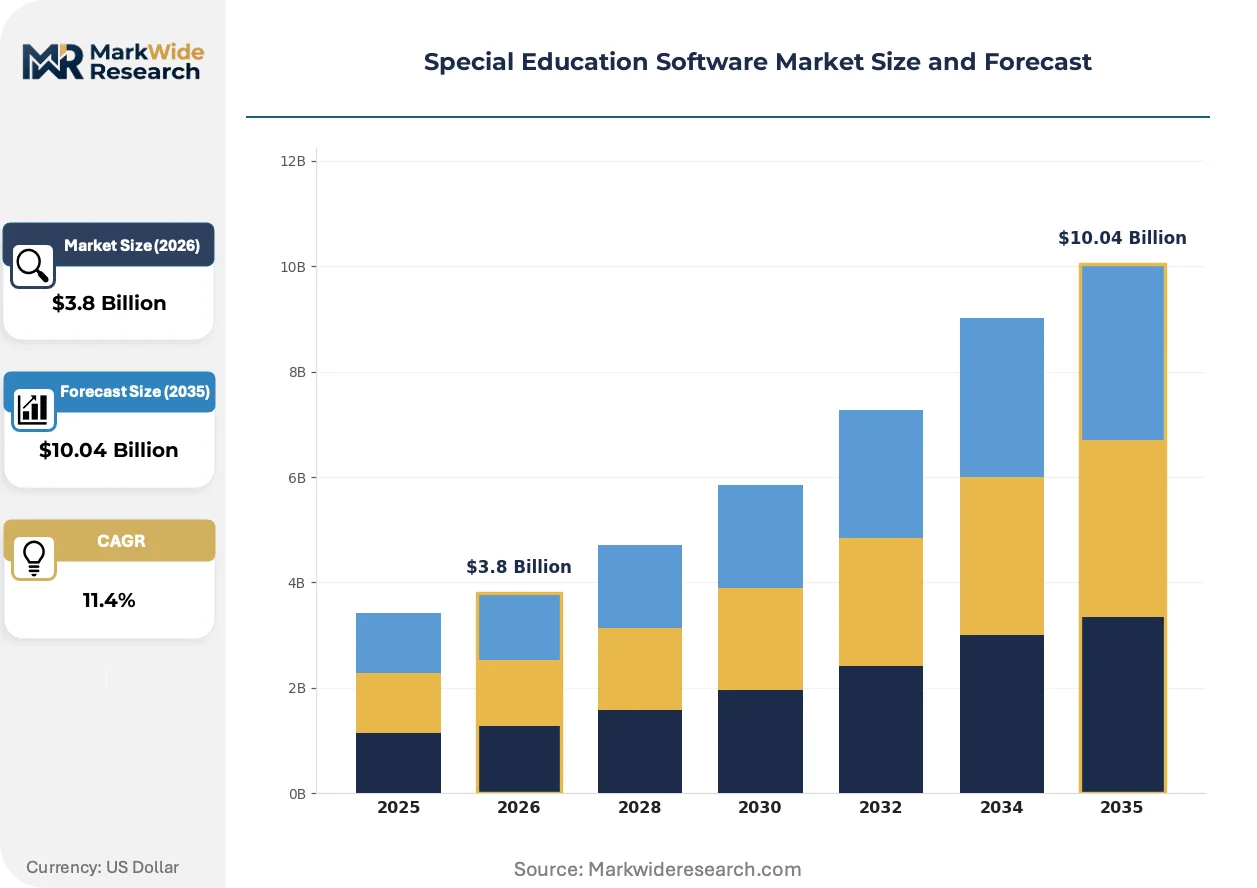
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Learning Management System, Assessment Tool, Communication Software, Compliance Management End User: Schools, Tutors, Therapists, Parents Delivery Model: Cloud-Based, On-Premises, Hybrid, Subscription-Based Application: Behavior Tracking, Lesson Planning, Resource Allocation, Individualized Education Plans |
| Companies Covered | PowerSchool, Frontline Education, Infinite Campus, eSped, Special Education Software, SEAS Education, Excent Corporation, Kurzweil Education, Tobii Dynavox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Special Education Software Market Emerging Trajectories
Artificial intelligence is penetrating special education workflows through adaptive content engines that reshape how individualized interventions are prescribed and monitored in real time.
Machine learning assessment engines are unifying previously siloed evaluation processes. School districts in high-compliance states deploy these tools to automate discrepancy calculations between ability and achievement scores. The technology is unifying psychometric interpretation with instructional planning, compressing the timeline from evaluation to service delivery.
The US Department of Education's Office of Special Education Programs intensifies monitoring of state compliance with IDEA's procedural safeguards. Districts must now produce timestamped documentation of parental notification and consent workflows. Vulnerable segments include those relying on manual paper trails, which face disproportionate audit failure rates.
District technology directors now bundle special education software procurement with broader administrative platform renewals. This consolidation displaces standalone IEP point solutions that dominated prior procurement cycles. The pattern concentrates most visibly in large unified districts seeking vendor consolidation to reduce contract management overhead.
Special Education Software Market Segmentation
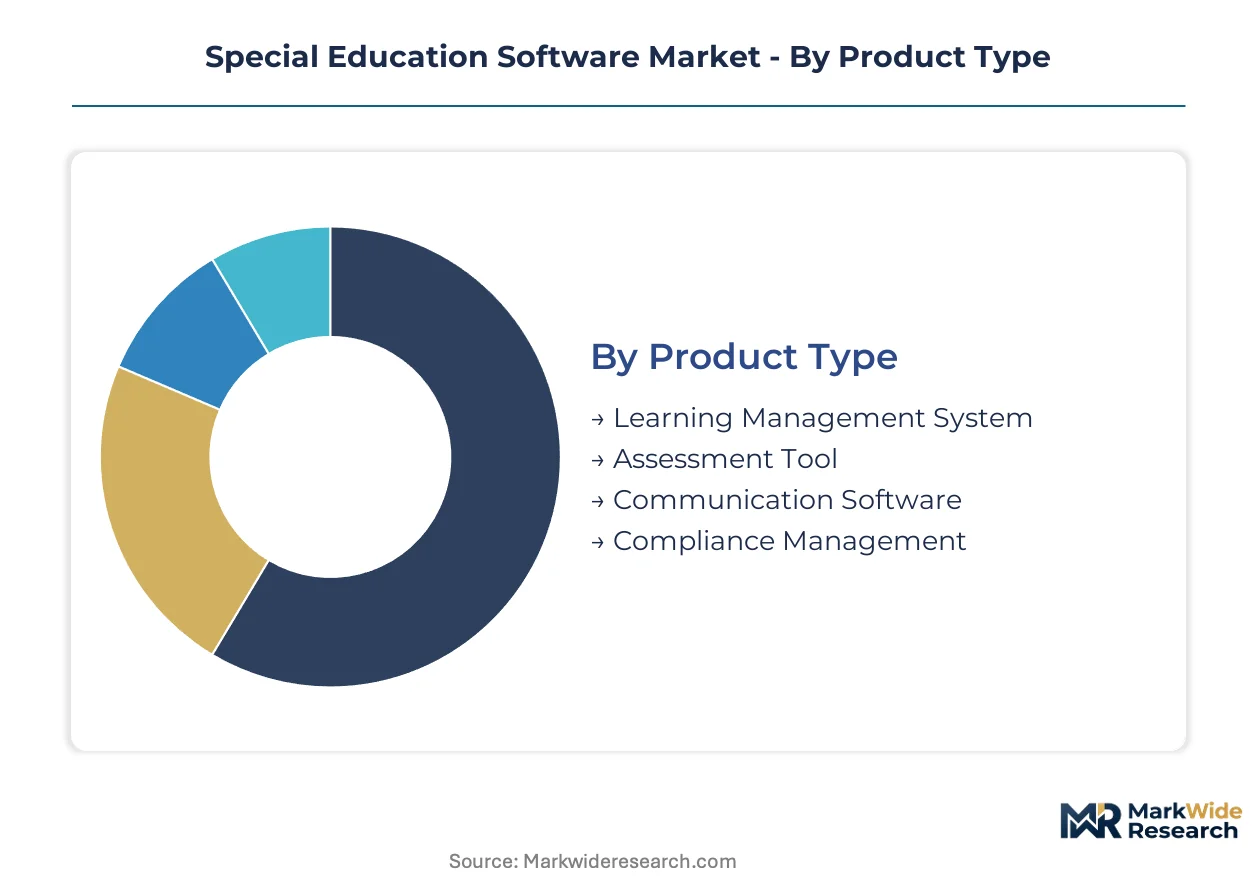
Special education software procurement splits across distinct technical and operational dimensions. District technology directors weight integration complexity against compliance mandates when selecting platform architectures. Each segmentation axis reveals divergent cost structures and implementation timelines that reshape vendor competitive positioning.
Product Type:
Capital intensity concentrates in platforms requiring psychometric engine development and multi-tenant cloud infrastructure. Vendors must amortize substantial R&D across recurring licensing models.
- Learning Management System:Unified instructional delivery platforms integrate curriculum sequencing with disability-specific accommodations. Districts in high-compliance states like California and Texas prioritize these systems to consolidate fragmented point solutions under single administrative dashboards.
- Assessment Tool:Psychometric engines automate discrepancy calculations between cognitive ability and academic achievement scores. School psychologists in Florida and New York districts drive demand for embedded progress-monitoring capabilities that satisfy state reporting mandates.
- Communication Software:Augmentative and alternative communication interfaces bridge speech-impaired students with instructional content.
- Compliance Management:Timestamped documentation workflows satisfy IDEA procedural safeguard requirements.
Learning Management Systems absorb the bulk of installed capacity; Assessment Tools are expanding most quickly.
End User:
Procurement authority varies sharply across stakeholder types, with budget scale and regulatory exposure determining platform sophistication requirements.
- Schools:K-12 districts deploy enterprise-grade platforms serving hundreds to thousands of IEP-eligible students simultaneously. Large unified districts in Illinois and Pennsylvania anchor volume demand through multi-year administrative platform renewals.
- Tutors:Individual practitioners require lightweight, mobile-optimized tools for session documentation and progress tracking.
- Therapists:Speech-language pathologists and occupational therapists prioritize HIPAA-compliant teletherapy modules.
- Parents:Guardian-facing portals enable real-time IEP monitoring and consent workflow participation.
Schools dominate current procurement volume; Parents represent the steepest expansion trajectory as federal mandates strengthen family engagement requirements.
Delivery Model:
Total cost of ownership calculations now favor operational expenditure models over capital-intensive perpetual licensing.
- Cloud-Based:Multi-tenant SaaS architectures eliminate on-site server maintenance while enabling automatic regulatory update deployment. District technology directors in Ohio and Georgia cite cybersecurity standard maturation as the decisive factor in cloud migration decisions.
- On-Premises:Self-hosted installations persist where data sovereignty concerns override cost considerations.
- Hybrid:Split deployments maintain sensitive student records locally while leveraging cloud analytics.
- Subscription-Based:Per-seat monthly pricing aligns district expenditures with enrollment fluctuations.
Cloud-Based deployments command the largest share of new implementations; Hybrid models are climbing the fastest among mid-size districts with legacy infrastructure investments.
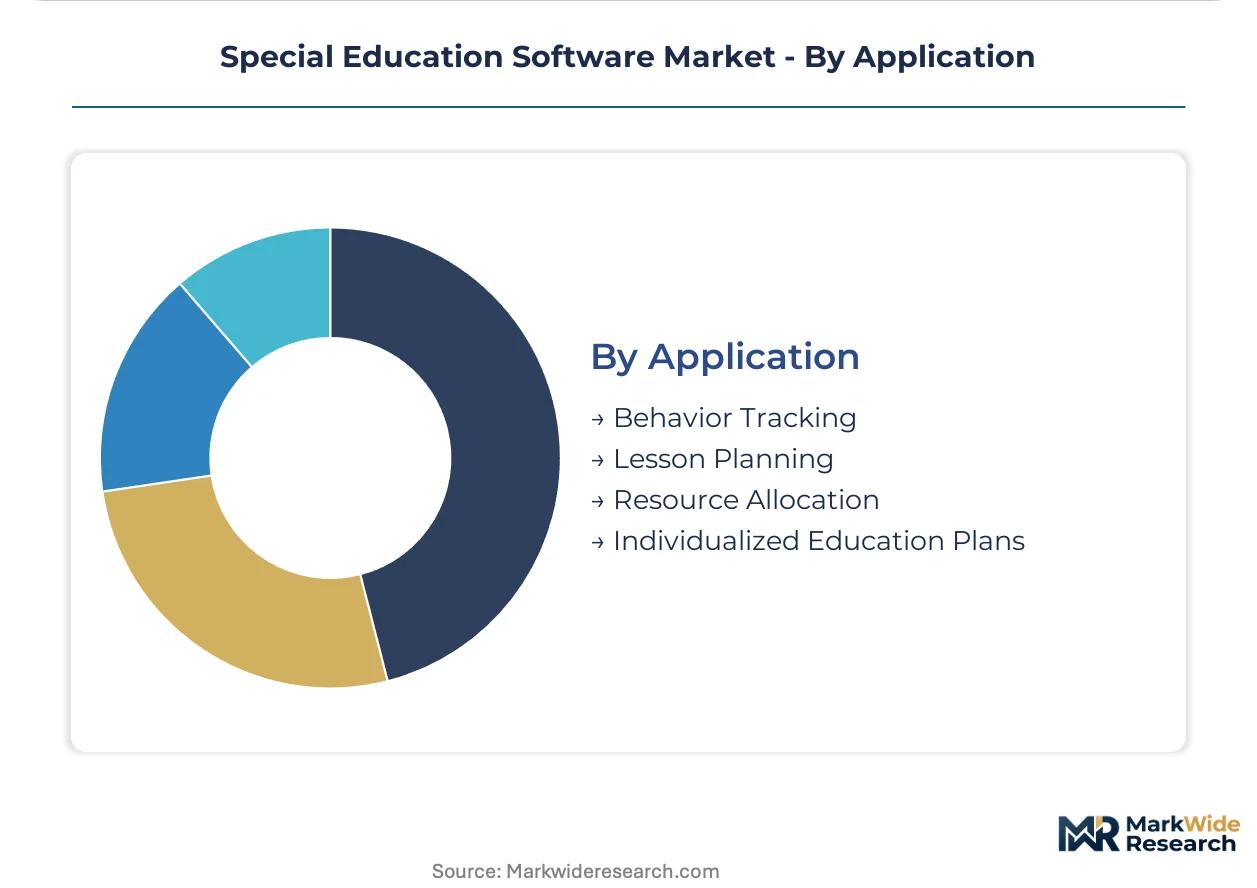
Application:
Functional specialization determines integration depth with existing student information systems and administrative workflows.
- Individualized Education Plans:Core compliance engines document present levels of performance, annual goals, and service minutes. Federal audit exposure in Arizona and Washington state districts accelerates digitization of IEP drafting and parental notification workflows.
- Behavior Tracking:Biometric sensor integration enables real-time intervention triggering for students with emotional disturbance classifications.
- Lesson Planning:Differentiated instruction tools align curricular content with specific disability accommodations.
- Resource Allocation:Caseload balancing algorithms optimize special education staff deployment across school sites.
Individualized Education Plans anchor functional demand; Behavior Tracking is gaining share fastest as districts expand multi-tiered system of supports implementations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal funding streams in the United States anchor procurement volume for special education software, while developed compliance frameworks in other jurisdictions shape regional adoption patterns.
United States
K-12 districts in California and Texas drive enterprise platform deployments serving thousands of IEP-eligible students simultaneously. The US Department of Education enforces IDEA compliance timelines that compress procurement cycles and expose paper-based tracking systems to audit failure. Chicago Public Schools and Los Angeles Unified anchor volume demand through multi-year administrative platform consolidations.
Canada
Provincial education ministries in Ontario and British Columbia are digitizing individualized education plan workflows to satisfy strengthened accountability mandates. Health Canada regulates assistive communication devices that interface with software platforms for students with speech impairments. Toronto District School Board and Vancouver School Board lead procurement of cloud-based compliance management systems.
United Kingdom
Local authorities in England and Scotland are consolidating fragmented special education point solutions under unified administrative dashboards. The country's national education regulator monitors compliance with statutory assessment timelines for students with education, health and care plans. Greater London and West Midlands anchor software adoption through academy trust networks seeking vendor consolidation.
Germany
Länder education ministries in Bavaria and North Rhine-Westphalia are expanding digital documentation for students with special educational needs. The country's federal data protection authority shapes cybersecurity requirements for educational data processing. Munich and Cologne metropolitan districts drive demand for assessment tool modules that automate psychometric interpretation.
Australia
State education departments in New South Wales and Victoria are replacing legacy paper-based disability tracking with centralized SaaS architectures. The country's national curriculum authority layers additional reporting mandates that shape vendor certification requirements. Sydney and Melbourne school systems anchor regional demand through multi-site district networks.
Special Education Software Market Vendor Landscape
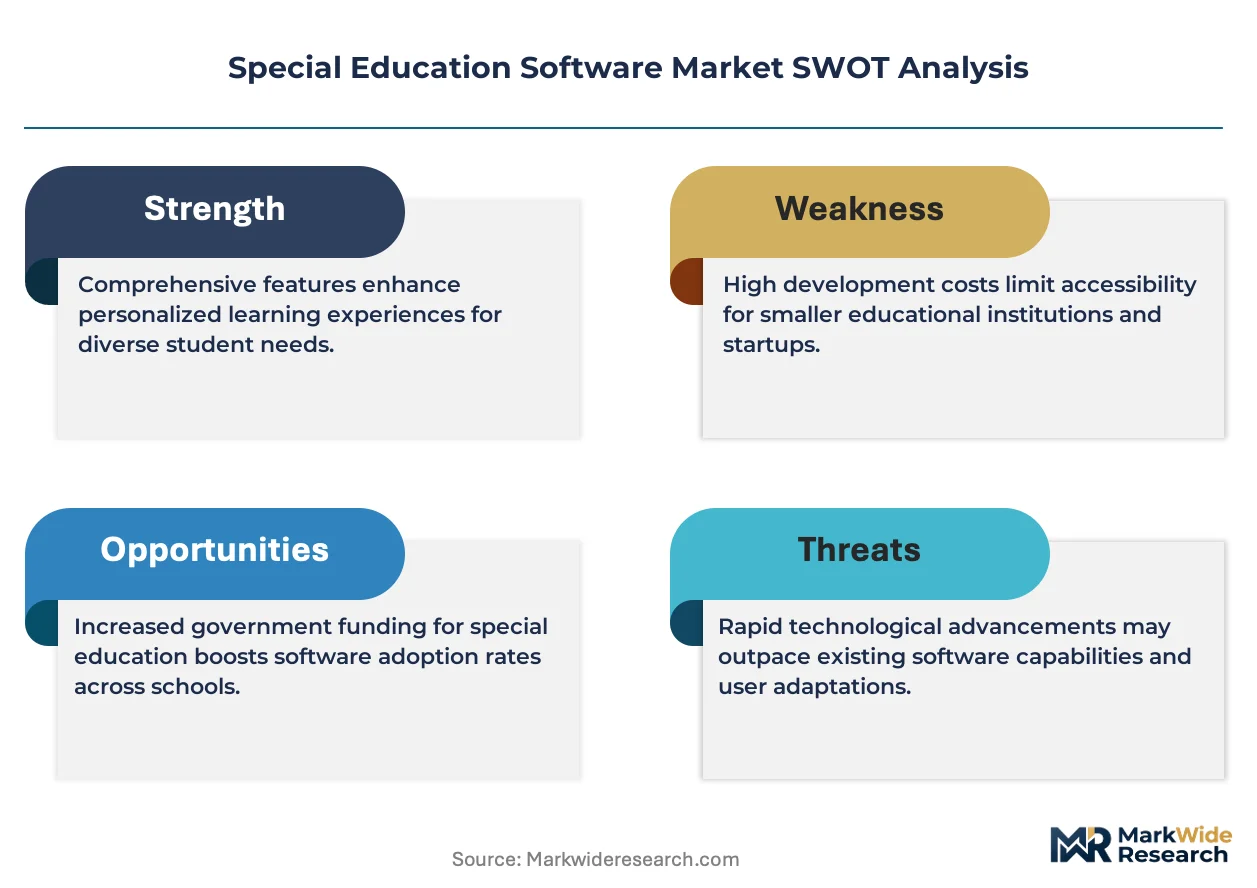
Global majors compete with regional champions across compliance specialization and platform breadth, producing a tiered structure where scale-driven administrative vendors coexist with disability-category specialists. The vendor base organizes around three strategic archetypes: K-12 administrative platform extenders, specialized IEP workflow developers, and assistive communication hardware-software integrators. Dominant competitive moves include strategic partnerships with state education agencies and portfolio diversification into adjacent compliance modules.
Within the administrative platform tier, PowerSchool and Infinite Campus exemplify scale-driven vendors that leverage established K-12 footprints to extend into individualized education plan workflows. Frontline Education occupies a position among specialized compliance developers, anchoring state-level reporting requirements through modular certification engines. Tobii Dynavox represents the assistive communication integration archetype, bridging FDA-regulated hardware with proprietary software interfaces for students with complex disabilities.
| Leading Market Players |
|---|
| PowerSchool |
| Frontline Education |
| Infinite Campus |
| eSped |
| Special Education Software |
| SEAS Education |
| Excent Corporation |
| Kurzweil Education |
| Tobii Dynavox |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure cost indices cascade through special education software supply chains, compressing margins for on-premises vendors while enabling subscription-tier expansion for SaaS-native providers serving multi-site K-12 districts.
Pricing Analysis
Warranty and implementation support bundling separates premium-tier vendors from unbundled economy offerings in this market. Three-tier pricing structure across premium, standard, and economy levels reflects psychometric engine sophistication and state certification coverage breadth. Cost compression in the economy tier is intensifying because district IT directors increasingly demand automatic regulatory update inclusion. Small rural districts exhibit highest price sensitivity, while large unified districts in California and Texas prioritize compliance breadth over per-seat cost.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler cloud infrastructure providers concentrated in the United States, as AWS and Azure dominance creates concentration risk for SaaS-dependent special education platforms. Software development draws from Indian engineering services, U.S.-based psychometric content specialists, and Canadian data hosting facilities. Tariff exposure on assistive communication hardware components imported from China threatens margin stability for augmentative communication integrators. Distribution runs through direct enterprise sales teams targeting district technology directors, supplemented by state education agency partnership channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with embedded state certification engines, as IDEA compliance complexity forces smaller point-solution providers toward acquisition or exit.
For Market Incumbents: Extend platform breadth through modular acquisition of behavioral analytics startups before district procurement consolidates under single-vendor contracts. PowerSchool and Frontline Education anchor positions through state-level reporting certification depth that emerging entrants cannot replicate quickly. API friction with legacy student information systems remains the critical integration lever for defensive positioning. For New Entrants and Emerging Players: IDEA's strengthened procedural safeguard enforcement in Washington and Arizona opens a window for compliance-native platforms without technical debt from paper-based workflow migration. Rural district teletherapy modules represent the most penetrable white space, given specialist shortages in non-urban geographies lacking school psychologist density. Go-to-market execution should anchor on state education agency pilot partnerships rather than direct district sales cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized IEP workflow developers with embedded psychometric engines in the United States Midwest, where district consolidation is accelerating vendor rationalization. Five-to-ten-year viability hinges on outcome-based reimbursement pivot readiness. The signal to watch is federal funding formula shifts toward progress-monitoring demonstration requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidation under PowerSchool and Infinite Campus administrative footprints reduces district contract management overhead. |
| State Certification Partnership | Frontline Education anchors reporting requirements through modular engines tailored to Florida and New York mandates. |
| Assistive Hardware-Software Convergence | Tobii Dynavox bridges FDA-regulated augmentative communication devices with proprietary instructional interfaces. |
| Behavioral Analytics Acquisition | Biometric sensor integration enables real-time intervention triggering for emotional disturbance classifications. |
| Teletherapy Module Expansion | Rural district specialist shortages create demand for HIPAA-compliant remote service delivery platforms. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with district technology directors, school psychologists, state education agency compliance officers, and special education software product managers. SEC 10-K disclosures, U.S. Department of Education IDEA monitoring reports, and state procurement databases supplied quantitative benchmarks. Bottom-up district-level adoption estimates triangulated against top-down vendor revenue aggregation.
Segment-level modeling tracked deployment model, district enrollment tier, application functional area, and regional compliance framework complexity across the analysis window. CAGRs derived from slope-log regression on annualized adoption curves, with psychometric licensing renewal rates and cloud migration velocity as industry-specific demand drivers. Cross-segment validation ensured internal consistency between product-type and end-user projections.
The model assumes a particular technology adoption path; alternative pathways for on-premises-to-cloud migration would alter the outlook if cybersecurity standard maturation stalls or federal funding volatility extends procurement cycles. Forecasts reflect documented assumptions about IDEA enforcement intensity and state reporting harmonization progress. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Global Virtual Classroom Market
Education & Training
Kindergarten Books Market
Education & Training
Online Tutoring Market
Education & Training
AI in K-12 Education Market
Education & Training
Corporate eLearning Market
Education & Training
Europe E-Learning Market
Education & Training
Research Publication Support Service Market
Education & Training
Test Paper Market
Education & Training
Flipped Classroom Market
Education & Training
Global Digital English Language Learning Market
Education & Training
Back to School Market
Education & Training
Executive Education Program Market
Education & Training
Poland Higher Education Market
Education & Training
Digital Classroom Market
Education & Training
United States HR Professional Service Market
Education & Training
Augmented and Virtual Reality in Education Market