
 South America Nutraceuticals Market | 2026-2036
South America Nutraceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
South America Nutraceuticals Market Analytics
Multi-vitamin bundling into single-dose formats is consolidating buyer preference across pharmacy and supermarket channels in South America. Nestle SA leverages its dairy and beverage infrastructure to distribute fortified nutritional powders through Brazil's retail networks. Herbalife International of America Inc. sustains its direct-sales model with personalized supplement coaching across Colombia and Peru. Bayer AG anchors its position through pharmacy-exclusive mineral complexes that compete on clinical positioning rather than price.
Nutraceuticals encompass bioactive compounds, vitamins, minerals, herbal extracts, and amino acids formulated for physiological benefit beyond basic nutrition, typically manufactured through spray-drying, microencapsulation, or cold-pressing to preserve bioavailability. These products serve preventive health, performance optimization, and disease-risk reduction across consumer and clinical settings. Vitamin formulations occupy the largest revenue pool due to established daily-supplement habits, while herbal extracts represent the fastest-expanding category as ayahuasca-derived and Amazonian botanicals gain functional-food traction. Tablet and capsule formats dominate manufacturing scale, though powder sachets are capturing share among sports enthusiasts seeking customizable dosing.
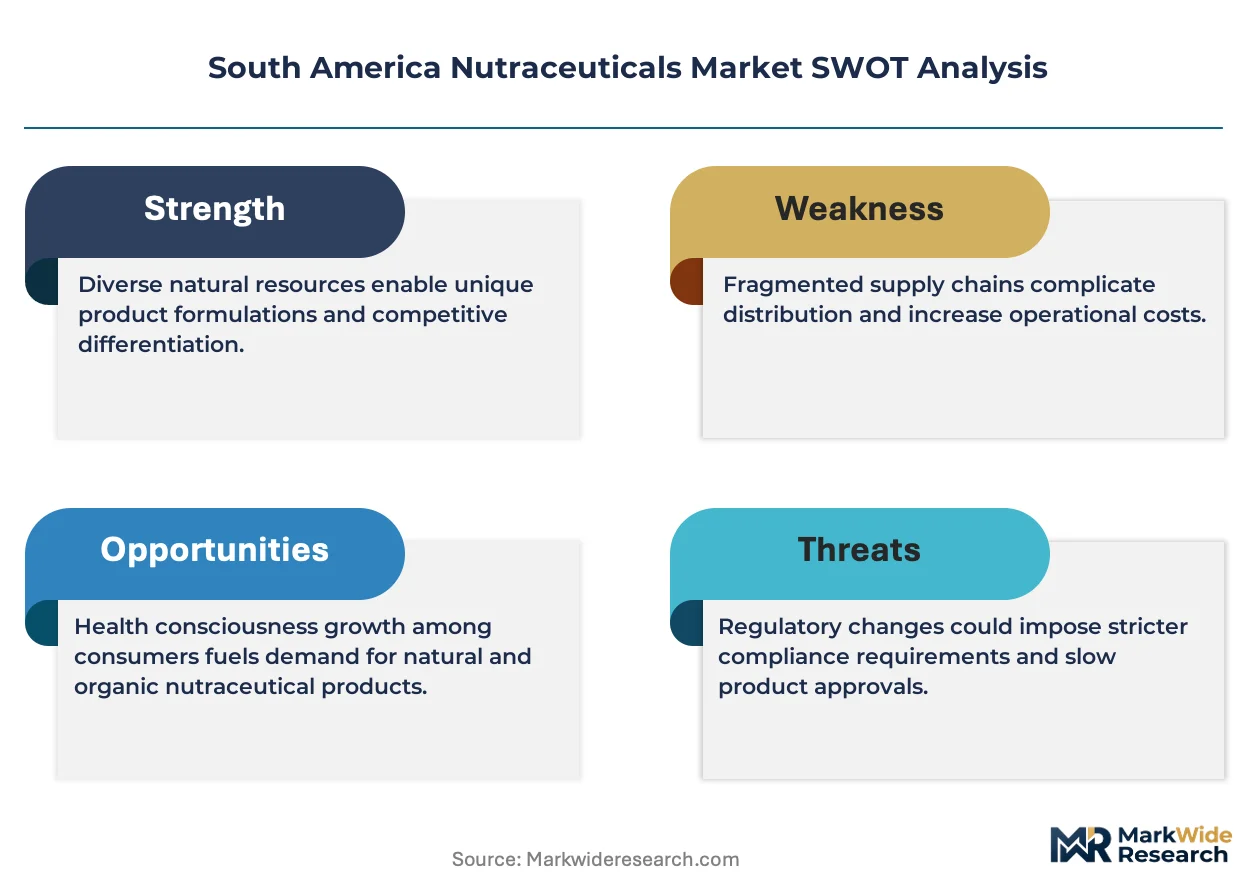
ANVISA in Brazil enforces strict stability-testing and health-claim substantiation for all imported and domestically produced nutraceuticals, creating a compliance moat that favors large manufacturers with in-house regulatory teams. Argentina's national food code and Chile's Ministry of Health labeling standards further fragment market access requirements across the continent. Stakeholders must monitor evolving mercosur harmonization talks, as unified standards would reshape which product configurations achieve cross-border scale.
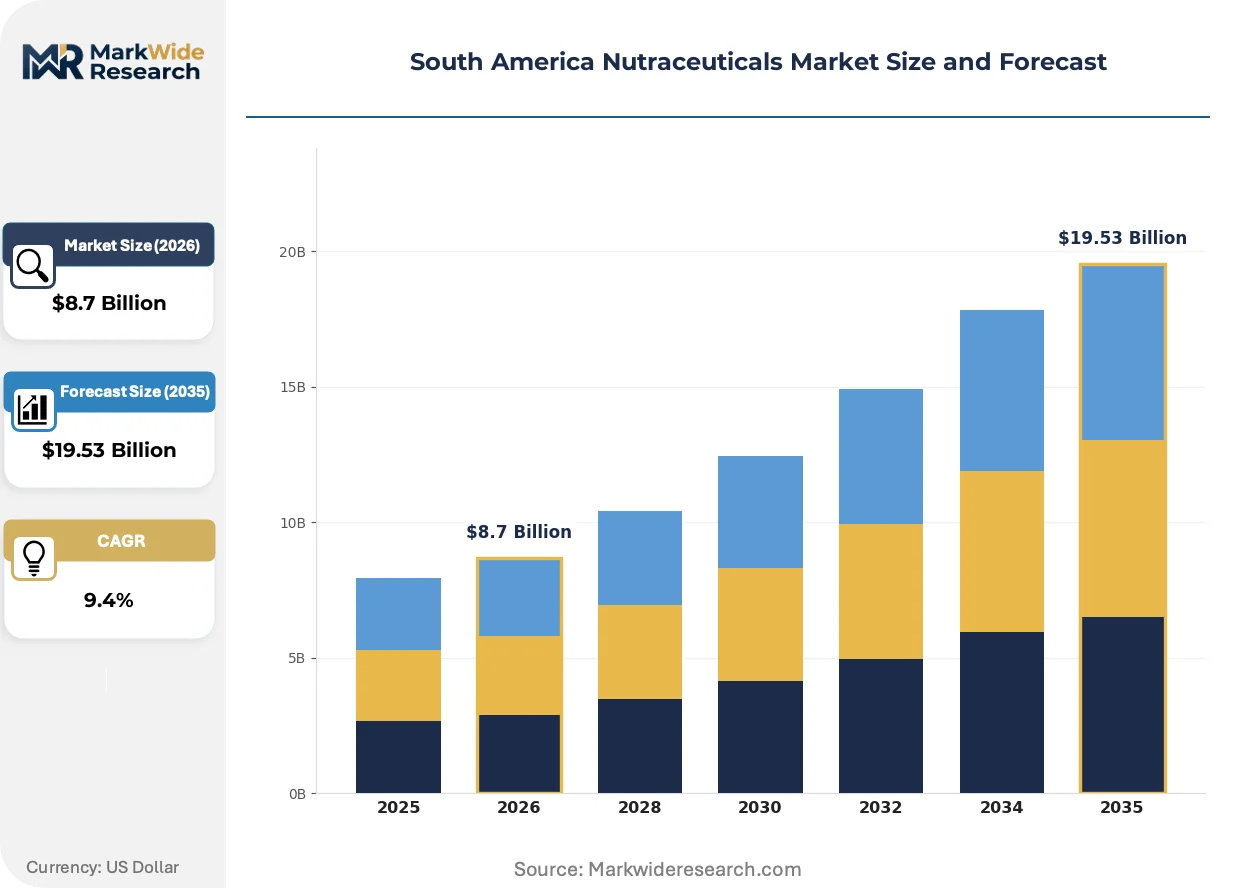
Market Dynamics
ANVISA's tightened label-claim verification protocols are forcing importers to rebuild compliance infrastructure around stability-testing documentation, consolidating competitive advantage toward manufacturers with captive regulatory teams.
Growth Catalysts
- Sports nutrition expansion:Protein fortification and recovery formulations are pulling new consumer cohorts into daily supplement routines across Brazil and Colombia.
- Amazonian botanical commercialization:Ayahuasca-derived and rainforest-sourced extracts are electrifying functional food innovation pipelines.
- ANVISA harmonization momentum:Pending Mercosur standard convergence is creating pathway for cross-border product registration scale.
Market Restraints
- Import compliance cost escalation:Brazil's ANVISA verification requirements impose documentation burdens that squeeze mid-tier importer margins.
- Raw material concentration:Specialty Amazonian botanical supply chains cluster in remote extraction zones with limited processing infrastructure.
- Tablet format commoditization:Mature vitamin-complex manufacturing faces price compression from undifferentiated private-label competition.
Strategic Opportunities
- Peru herbal extract underpenetration:Direct-to-consumer coaching models remain nascent outside Lima and Cusco corridors.
- Microencapsulation convergence:Cold-pressing technology integration with spray-drying is opening shelf-stable probiotic powder formats.
- Chile pharmacy channel expansion:Specialized health store networks in Santiago and Valparaíso lack dense fortified-beverage distribution.
Industry Challenges
- Regulatory affairs talent scarcity:Qualified ANVISA submission specialists command premium compensation in São Paulo.
- Legacy system integration friction:Direct-sales distributors migrating to e-commerce face CRM-platform reconfiguration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Nutraceuticals Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Extracts, Amino Acids End User: Health-conscious Individuals, Sports Enthusiasts, Elderly, Patients Form: Tablets, Capsules, Powders, Liquids Distribution Channel: Health Stores, E-commerce, Pharmacies, Supermarkets |
| Companies Covered | Red Bull GmbH, PepsiCo Inc., Nestle SA, General Mills Inc., Herbalife International of America Inc., The Kellogg Company, Pfizer Inc., Amway Corp., Bayer AG, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Nutraceuticals Market Evolving Landscape
Technology convergence between extraction methods and delivery formats is compressing product development cycles while regulatory fragmentation forces parallel compliance track investments.
Cold-pressed microencapsulation is electrifying bioavailability preservation in heat-sensitive botanical formulations. Sports enthusiasts in Brazil's southeastern states are adopting these formats at accelerating velocity. The technology is electrifying market segmentation between premium stability-tested offerings and conventional tablet alternatives.
ANVISA's health-claim substantiation mandates are tightening evidentiary standards for functional food positioning. Domestic manufacturers with in-house toxicology laboratories are capturing shelf space from import-dependent competitors. Powder sachet categories face the steepest documentation burden as dosage-flexibility claims trigger enhanced scrutiny.
Pharmacy chain consolidation across São Paulo state is concentrating buyer power among three dominant retail networks. Smaller specialized health stores are losing shelf-access negotiation leverage. Colombia's Bogotá corridor exhibits parallel channel compression as pharmacy banners acquire independent supplement retailers.
South America Nutraceuticals Market Segmentation
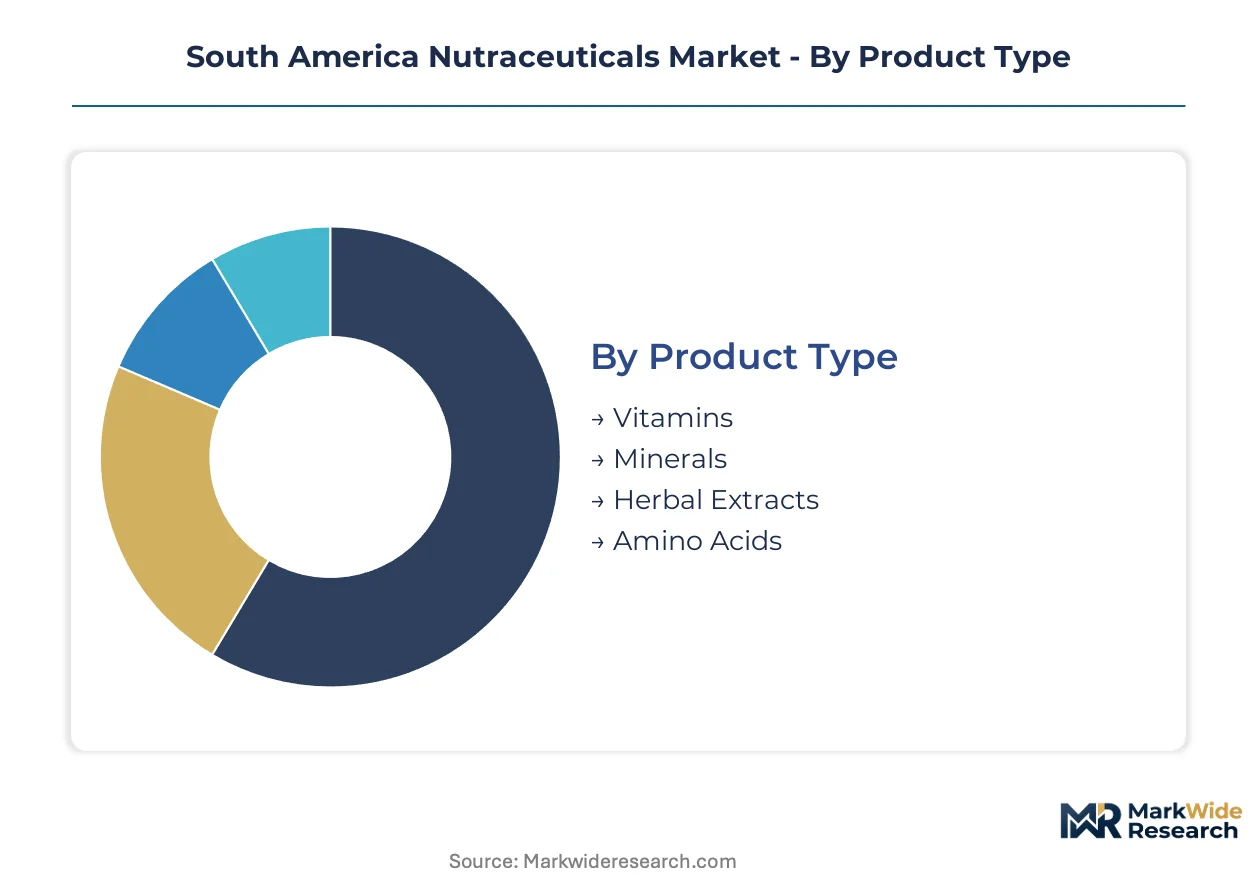
Segmentation in South America reflects divergent capital requirements across extraction technologies, regulatory compliance burdens, and channel infrastructure investments. Manufacturers prioritize segments where ANVISA documentation costs can be amortized across volume scale.
Product Type:
Capital intensity clusters around extraction infrastructure and stability-testing laboratories, with botanical processing demanding specialized equipment investments.
- Vitamins:Synthetic and fermentation-derived compounds requiring spray-drying towers and coating lines for tablet production. São Paulo pharmacy chains anchor demand as daily-supplement habits concentrate in Brazil's southeastern corridor, though price compression from private-label competition squeezes margin expansion.
- Herbal Extracts:Amazonian botanical sourcing demands cold-pressing and microencapsulation investments to preserve bioactive stability. Colombia and Peru direct-sales networks drive adoption as ayahuasca-derived formulations gain functional-food positioning, constrained by remote extraction zone infrastructure gaps.
- Minerals:Chelated and inorganic complexes manufactured through granulation and compression equipment with lower technical barriers.
- Amino Acids:Fermentation-based or synthetic production requiring bioreactor capital and downstream purification systems.
Vitamin formulations absorb the bulk of installed capacity; herbal extracts are expanding most quickly.
End User:
Customer acquisition economics vary sharply across coaching-intensive segments versus self-directed purchase behaviors.
- Sports Enthusiasts:Protein fortification and recovery formulation demand pulls consumers into customizable powder sachet categories. Brazil's southeastern states exhibit the steepest adoption velocity as gym culture and endurance event participation expand, driving microencapsulation technology investments for heat-sensitive ingredients.
- Health-conscious Individuals:Preventive supplement routines concentrate in urban professional cohorts with pharmacy channel loyalty. São Paulo and Bogotá corridors dominate as disposable income thresholds support premium positioning, though e-commerce migration disrupts traditional replenishment patterns.
- Elderly:Mineral complex and joint-support categories with pharmacy-dependent trust dynamics and clinical positioning requirements.
- Patients:Condition-specific formulations prescribed or recommended through clinical channels with substantiation documentation burdens.
Sports enthusiasts command the highest customer lifetime value; health-conscious individuals deliver the broadest addressable base.
Form:
Manufacturing flexibility and shelf-stability requirements determine equipment utilization rates across format categories.
- Tablets:High-speed rotary press operations with film-coating lines dominate manufacturing scale. Mature vitamin-complex production faces commoditization pressure as undifferentiated private-label competition concentrates in Brazilian supermarket channels.
- Powders:Spray-drying and blending equipment serves sports nutrition and customizable dosing demand. Cold-pressed microencapsulation integration is opening shelf-stable probiotic formats as technology convergence accelerates development cycles.
- Capsules:Gelatin and vegetable-shell encapsulation with lower capital intensity than tablet coating infrastructure.
- Liquids:Aseptic filling lines and preservative system validation for pediatric and geriatric compliance applications.
Tablets retain the largest production footprint; powders are climbing the fastest on sports nutrition tailwinds.
Distribution Channel:
Channel selection dictates working capital intensity, margin structure, and regulatory documentation exposure.
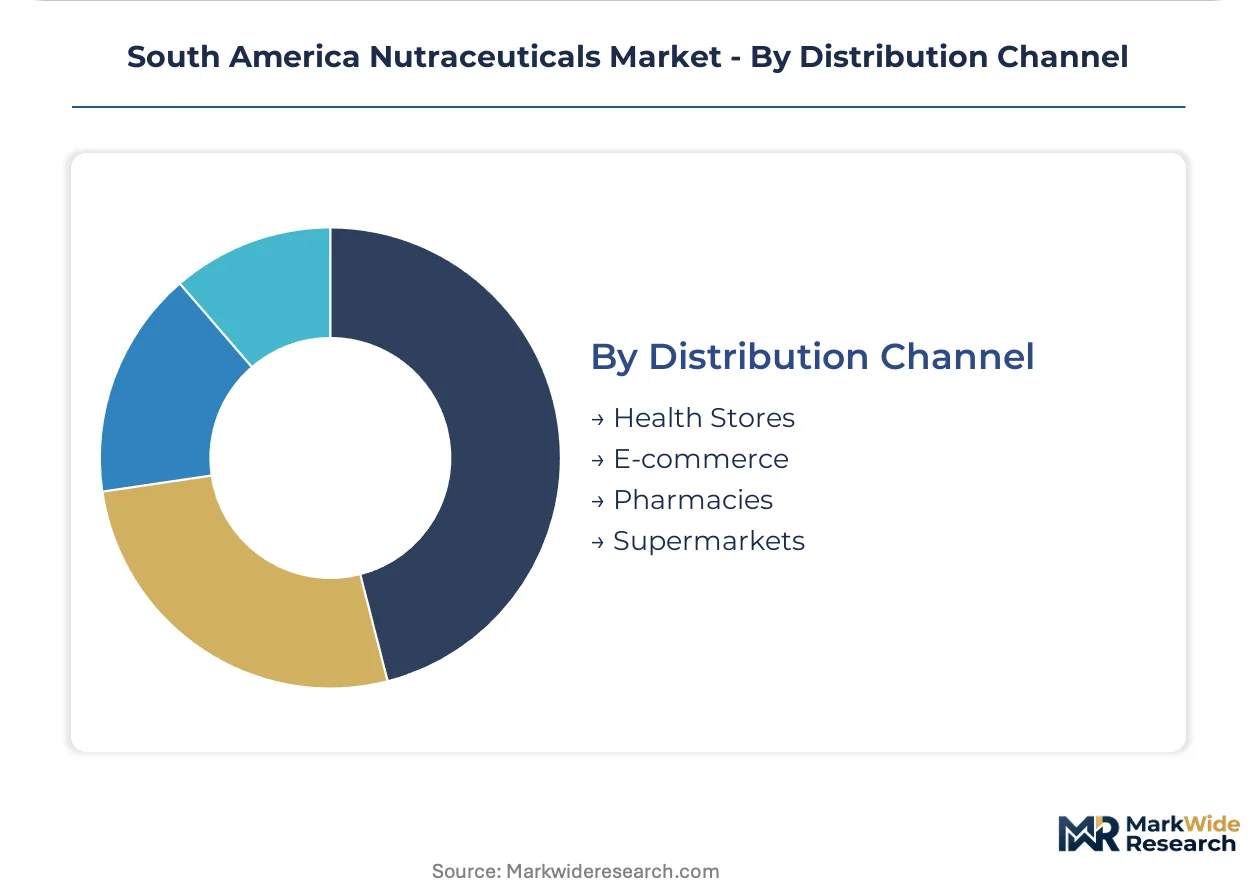
- Pharmacies:Pharmacy-exclusive mineral complexes compete on clinical positioning with trained staff recommendation leverage. São Paulo state consolidation among three dominant retail networks concentrates buyer power and squeezes shelf-access terms for smaller specialized health stores.
- E-commerce:Direct-to-consumer coaching models sustain personalized supplement advisory with CRM-platform reconfiguration costs for legacy direct-sales distributors. Peru outside Lima and Cusco corridors remains underpenetrated for herbal extract categories.
- Health Stores:Specialized supplement retail with staff expertise dependency and localized inventory depth requirements.
- Supermarkets:Mass-market vitamin and mineral placement with high-volume, low-margin economics and private-label substitution risk.
Pharmacies capture the premium pricing tier; e-commerce is gaining share fastest on logistics network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone incentives concentrate pharmaceutical and food processing infrastructure in Brazil's northwest, drawing extractors and formulators seeking duty advantages on imported equipment and raw materials.
Brazil
São Paulo state anchors continental consumption through consolidated pharmacy chains and specialized health stores. ANVISA's tightened label-claim verification protocols elevate compliance costs for importers while favoring domestic manufacturers with captive regulatory teams. The southeastern corridor from São Paulo to Curitiba drives sports nutrition adoption as gym culture and endurance event participation expand.
Argentina
Urban professional cohorts in Buenos Aires sustain preventive supplement routines despite macroeconomic volatility affecting import channels. The national food code imposes distinct labeling standards that fragment market access requirements relative to Mercosur neighbors. Rosario and Córdoba industrial zones host blending and packaging operations serving regional distribution networks.
Colombia
Bogotá corridor concentrates pharmacy banner consolidation and direct-sales coaching model penetration for herbal extract categories. The Ministry of Health maintains separate substantiation requirements for functional food positioning that complicate cross-border product registration. Medellín's manufacturing base supplies Andean region distribution with vitamin complex and mineral formulations.
Chile
Santiago and Valparaíso health store networks exhibit underpenetration in fortified-beverage distribution relative to pharmacy channel density. The Ministry of Health labeling standards create documentation burdens for powder sachet categories with dosage-flexibility claims. Concepción's processing infrastructure supports southern region supply with tablet and capsule manufacturing scale.
Peru
Lima and Cusco corridors concentrate direct-to-consumer coaching model adoption for Amazonian botanical extracts. Ayahuasca-derived formulation demand pulls remote extraction zone supply chains with limited processing infrastructure into commercial pipelines. Arequipa's emerging health store networks remain nascent for personalized supplement advisory penetration.
South America Nutraceuticals Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation categories, with beverage and dairy infrastructure holders leveraging retail network density against direct-sales coaching specialists. Market structure exhibits tiered concentration where large manufacturers amortize ANVISA compliance costs across volume scale while mid-tier importers face margin compression. Three archetypes dominate: multinational CPG conglomerates with captive distribution, direct-sales coaching specialists with personalized advisory models, and pharmaceutical-origin mineral complex formulators with clinical positioning. Competitive moves concentrate on pharmacy chain shelf-access negotiation and microencapsulation technology licensing for bioavailability preservation.
Within the multinational CPG tier, Nestle SA leverages dairy and beverage infrastructure for fortified nutritional powder distribution through Brazil's retail networks. Herbalife International of America Inc. exemplifies the direct-sales coaching archetype with personalized supplement advisory across Colombia and Peru. Bayer AG anchors the pharmaceutical-origin positioning through pharmacy-exclusive mineral complexes competing on clinical credibility rather than price sensitivity.
| Leading Market Players |
|---|
| Red Bull GmbH |
| PepsiCo Inc. |
| Nestle SA |
| General Mills Inc. |
| Herbalife International of America Inc. |
| The Kellogg Company |
| Pfizer Inc. |
| Amway Corp. |
| Bayer AG |
| Others |
Value Network & Pricing Analysis
Pharmacy chain consolidation across São Paulo state is compressing supplier margins as three dominant retail networks extract steeper shelf-access terms, forcing manufacturers to absorb documentation costs or cede volume to private-label alternatives. This buyer concentration reshapes procurement economics toward scale-dependent players capable of amortizing ANVISA compliance investments across high-volume contracts.
Pricing Analysis
Short lead-time premiums attach to cold-pressed microencapsulated botanicals as sports nutrition buyers prioritize bioavailability over cost minimization. The market operates through contract-based long-term offtake for vitamin complexes serving pharmacy chains, while spot inventory discounts clear undifferentiated tablet stock through supermarket channels. Price differentiation rests on ANVISA certification tier and stability-testing documentation depth, with import-dependent competitors facing the steepest compression. Health-conscious urban professionals exhibit lowest price sensitivity for clinically positioned mineral complexes, whereas supermarket vitamin shoppers drive aggressive private-label substitution.
Supply Chain Analysis
ANVISA stability-testing certification gates access to Brazil's pharmacy channel, filtering suppliers through in-house toxicology laboratory requirements. Raw material supply concentrates in Brazil's southeastern manufacturing corridor, Peru's remote Amazonian extraction zones, and Colombia's Bogotá processing hub. Supply chains draw from ayahuasca-derived botanicals, chelated mineral precursors, and fermentation-based amino acid feedstocks. Single-source vulnerability runs through specialty Amazonian botanical corridors lacking redundant processing infrastructure. Distribution feeds from Manaus Free Trade Zone formulators through consolidated retail networks and direct-sales coaching channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA documentation burdens are accelerating market consolidation as mid-tier importers exit under compliance cost pressure, leaving volume scale to manufacturers with captive regulatory capabilities.
For Market Incumbents: Anchor shelf position through exclusive pharmacy chain partnerships in São Paulo's consolidated retail networks, while backward integration into Amazonian botanical extraction secures supply continuity against remote zone infrastructure gaps. Invest in microencapsulation capacity additions to defend premium positioning as cold-pressed formats displace conventional tablets among sports enthusiasts. For New Entrants and Emerging Players: Sports enthusiasts in Chile's Santiago-Valparaíso corridor represent an underserved buyer archetype with limited fortified-beverage penetration and pharmacy channel density gaps. Target direct-to-consumer coaching models for herbal extract categories outside Lima and Cusco, leveraging e-commerce logistics expansion to bypass consolidated retail gatekeepers. For Investors and Strategic Acquirers: The window for entry favors domestic manufacturers with established ANVISA submission capabilities and in-house stability-testing infrastructure. Long-term viability hinges on regulatory compliance moats deepening over the projection horizon. Watch Mercosur standard harmonization progress as the inflection signal determining which product configurations achieve cross-border scale economics.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Cold-pressed integration preserves bioavailability in heat-sensitive Amazonian botanical formulations for sports nutrition. |
| ANVISA Compliance Infrastructure Buildout | In-house toxicology laboratories capture pharmacy shelf space from documentation-burdened import competitors. |
| Direct-to-Consumer Coaching Platform | Personalized supplement advisory sustains margin extraction in Peru's underpenetrated corridors beyond Lima. |
| Amazonian Extraction Zone Partnership | Upstream control over ayahuasca-derived supply chains mitigates single-source vulnerability in remote processing areas. |
| Pharmacy Chain Exclusive Distribution | Consolidated São Paulo retail network access anchors volume scale for stability-tested vitamin and mineral complexes. |
Research Methodology
Multi-period observation of ANVISA submission volumes, pharmacy chain SKU consolidation patterns, and sports nutrition format adoption rates anchored the trend analysis, supplemented by interviews with regulatory affairs directors at domestic manufacturers, procurement managers at consolidated São Paulo retail networks, direct-sales coaching specialists in Colombia and Peru, and botanical extraction operators in Amazonian processing zones. Secondary validation drew from ANVISA registration databases, Mercosur harmonization documentation, customs import records for nutritional ingredients, and stability-testing laboratory capacity reports. Bottom-up segment sizing triangulated against top-down macroeconomic health expenditure trends.
Segment-weighting approaches distributed value estimates across product type, end-user archetype, delivery format, and distribution channel dimensions throughout the forecast period. CAGRs were derived from elasticity-adjusted demand projections incorporating gym culture penetration rates in Brazil's southeastern states and direct-sales coaching model expansion trajectories. Industry-specific inputs included ANVISA approval queue durations, cold-pressed microencapsulation technology licensing fees, and pharmacy chain buyer concentration indices.
Revisions become necessary when Mercosur regulatory harmonization materially advances, Amazonian botanical supply disruptions emerge, or pharmacy chain consolidation accelerates beyond modeled thresholds. Forecasts reflect documented assumptions regarding stability-testing cost trajectories and sports nutrition adoption velocity. A model refresh is warranted upon material change in ANVISA enforcement intensity or direct-sales distributor e-commerce migration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Bovine Collagen Peptide Market
Nutritional Supplements
Global Oncology Nutrition Market
Nutritional Supplements
Food Grade Beta-Alanine Market
Nutritional Supplements
Global Nutraceutical Ingredients Market
Nutritional Supplements
Lutein Market
Nutritional Supplements
Europe Vegan Supplements Market
Nutritional Supplements
Omega-3 Concentrates Market
Nutritional Supplements
Global Corn Germs Supplements Market
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
North and South America Mineral Supplement Tablets Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Food Market
Nutritional Supplements
Middle-East and Africa Dietary Supplement Market
Nutritional Supplements
Red Ginseng Market
Nutritional Supplements
Nutrition Therapy Market
Nutritional Supplements
Asia-Pacific Digestive Health Supplements Market