
 South America Flavored Milk Market | 2026-2036
South America Flavored Milk Market Size, Share, and Industry Trends Forecast 2026-2036
South America Flavored Milk Market Analytics
Aseptic carton filling technology is tilting production economics toward longer shelf-life formats with lower refrigeration dependency. Nestlé S.A. leverages its pan-regional dairy network to secure raw milk supply across multiple South American countries. Danone S.A. anchors its portfolio in probiotic-infused flavored milk variants targeting health-conscious consumers. Grupo Lala competes through deep distribution reach into Mexico and Central America, creating cross-border procurement advantages.
Flavored milk comprises pasteurized or UHT-treated dairy beverages with added flavoring agents, sweeteners, and stabilizers, typically containing between 80-90% milk content with protein levels standardized at 2.9-3.4% for nutritional equivalence to plain milk. Chocolate formulations dominate volume due to entrenched consumer preference and breakfast consumption rituals, while coffee-flavored variants represent the fastest-expanding margin pool as adult-oriented positioning commands premium pricing. Tetra Pak packaging controls the structural cost advantage through ambient distribution capability, though plastic bottles retain strength in immediate-convenience channels where portability drives purchase decisions.
ANVISA enforces front-of-package warning labels for high-sugar beverages, compelling manufacturers to reformulate recipes or accept restricted retail placement. Brazil's Ministry of Agriculture (MAPA) oversees dairy plant inspections and raw milk quality standards that determine export eligibility to Mercosur partners. Argentina's National Food Commission (CAA) mandates specific protein and fat declarations that affect cross-border product standardization. Stakeholders must monitor evolving sugar taxation proposals across Andean nations and assess whether regional harmonization of nutritional thresholds will simplify formulation strategies or fragment compliance requirements.
Market Dynamics
ANVISA's front-of-package warning label mandate is compressing formulation timelines across Brazil's flavored milk sector, forcing manufacturers to re-engineer recipes before enforcement deadlines or face retail placement restrictions in major supermarket chains.
Growth Catalysts
- Fortified School Nutrition Procurement:Brazil's Ministry of Education is expanding dairy beverage acquisition through the PNAE school feeding program, creating institutional volume anchors for regional processors.
- ANVISA Reformulation Pressure:The regulator's sugar threshold warnings are accelerating clean-label innovation, rewarding early movers with preferential shelf positioning in São Paulo's retail corridors.
- Cold-Chain Infrastructure Maturation:Refrigerated logistics networks in Minas Gerais and Paraná are extending distribution reach for pasteurized formats previously confined to metropolitan cores.
Market Restraints
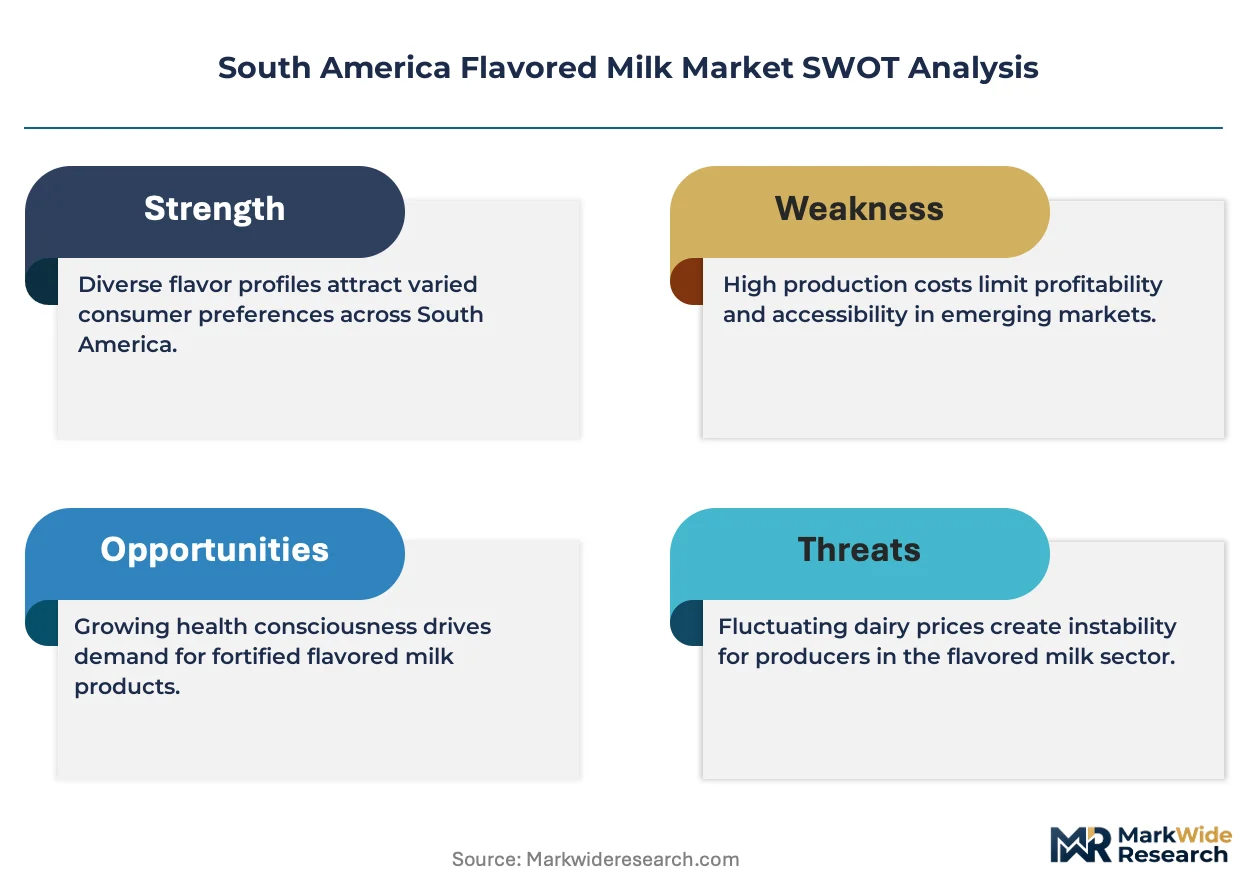
- Raw Milk Input Volatility:Seasonal production fluctuations across Argentina's Pampas dairy belt create feedstock pricing instability that compresses processor margins during low-yield quarters.
- Cross-Border Regulatory Friction:Argentina's CAA mandates divergent protein-fat declaration standards from Brazil's MAPA requirements, fragmenting product standardization for Mercosur-exposed manufacturers.
- Sugar Tax Contagion Risk:Andean nations are advancing beverage taxation proposals that threaten to replicate Mexico's price-elasticity collapse in adjacent markets.
Strategic Opportunities
- Underpenetrated Northeast Brazil:Bahia and Pernambuco states exhibit per-capita flavored milk consumption gaps exceeding 40% versus southeastern benchmarks, offering whitespace for ambient-stable UHT formats.
- Adult-Oriented Coffee Infusion:Premium-positioned café con leche variants targeting workplace consumption occasions command margin multiples above chocolate-based equivalents.
- Probiotic Strain Convergence:Lactobacillus fortification combined with aseptic processing is enabling shelf-stable functional claims previously restricted to chilled yogurt drinks.
Industry Challenges
- Reformulation Technical Complexity:Sugar reduction targets are forcing simultaneous rebalancing of stabilizer systems and flavor masking agents, extending R&D validation cycles.
- Legacy Cold-Chain Asset Stranding:Investments in refrigerated distribution infrastructure face utilization pressure as ambient-format adoption accelerates in secondary cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Flavored Milk Market |
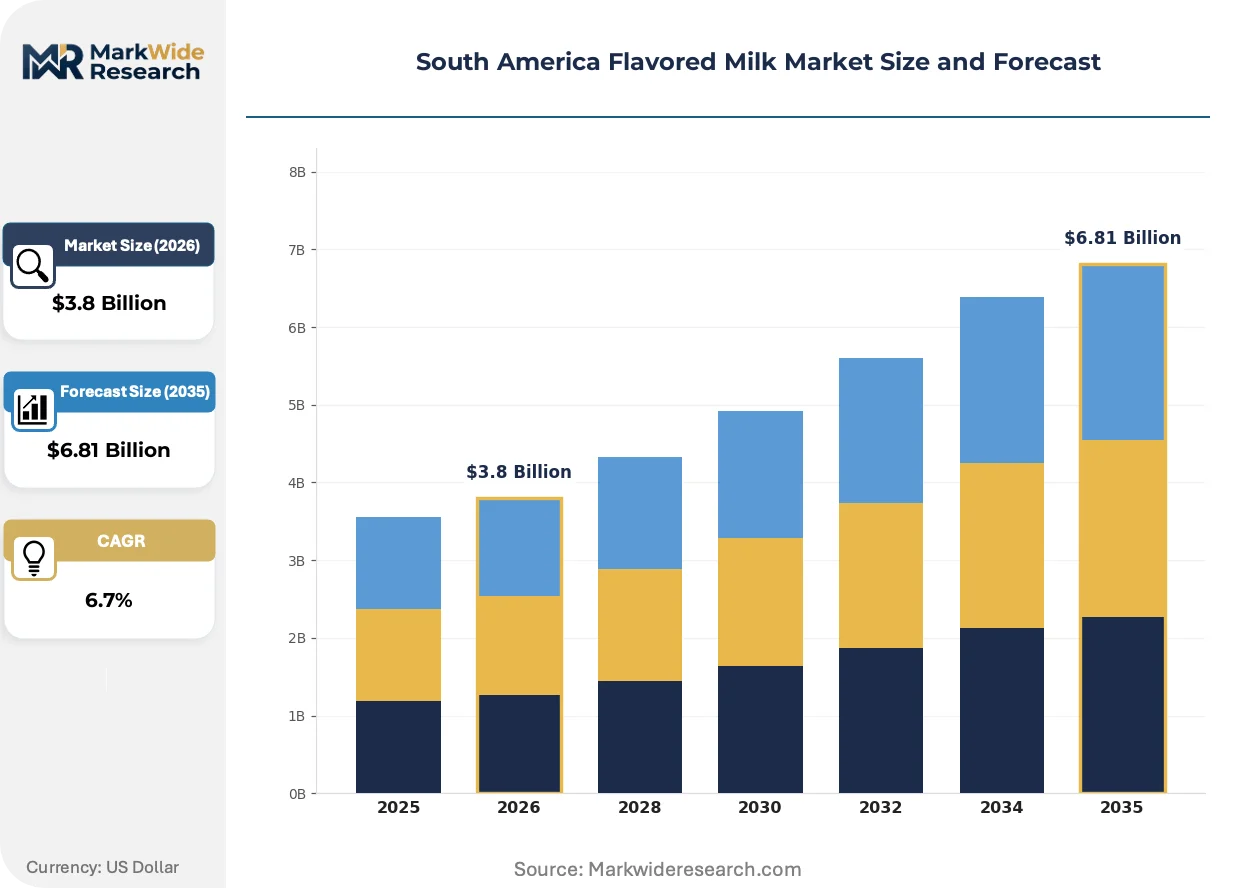
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Strawberry, Vanilla, Coffee Customer Type: Children, Teenagers, Adults, Seniors Packaging Type: Tetra Pak, Glass Bottles, Plastic Bottles, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores |
| Companies Covered | Nestlé S.A., Danone S.A., Arla Foods, Mococa S.A. Produtos Alimenticios, CBL Alimentos S.A., The Coca-Cola Company, Grupo Lala, Vigor Alimentos, Itambé Alimentos S.A., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Flavored Milk Market Evolving Landscape
Reformulation imperatives are converging with packaging technology evolution to reshape competitive advantage in South America's flavored milk sector, with sustainability credentials and nutritional transparency emerging as non-negotiable purchase criteria.
Aseptic carton filling technology is hybridizing production economics across Brazil's dairy processing network. Tetra Pak's barrier material systems enable 180-day ambient shelf stability without refrigeration dependency. Mid-sized processors in Paraná are adopting these lines to bypass cold-chain investments entirely. The technology is compressing the historical premium between pasteurized and UHT formats while expanding distribution into Brazil's interior municipalities.
ANVISA's updated food labeling regulations are forcing disclosure granularity that exceeds Mercosur baseline standards. The October 2022 resolution mandates octagonal warning icons for sugar-dense beverages exceeding 10% added sugars by volume. Brazilian supermarket chains are responding with preferential planogram placement for reformulated products bearing reduced-sugar claims. Argentina's CAA is monitoring this regulatory divergence for potential harmonization pressure.
Breakfast ritual displacement is rotating consumption occasions toward afternoon snacking and post-workout recovery in São Paulo and Buenos Aires metropolitan corridors. Convenience store channels are capturing this behavioral shift through single-serve plastic bottle formats positioned near checkout zones. Gym and fitness center micro-distribution partnerships represent the fastest-proliferating channel innovation for protein-fortified variants targeting adult consumers.
South America Flavored Milk Market Segmentation
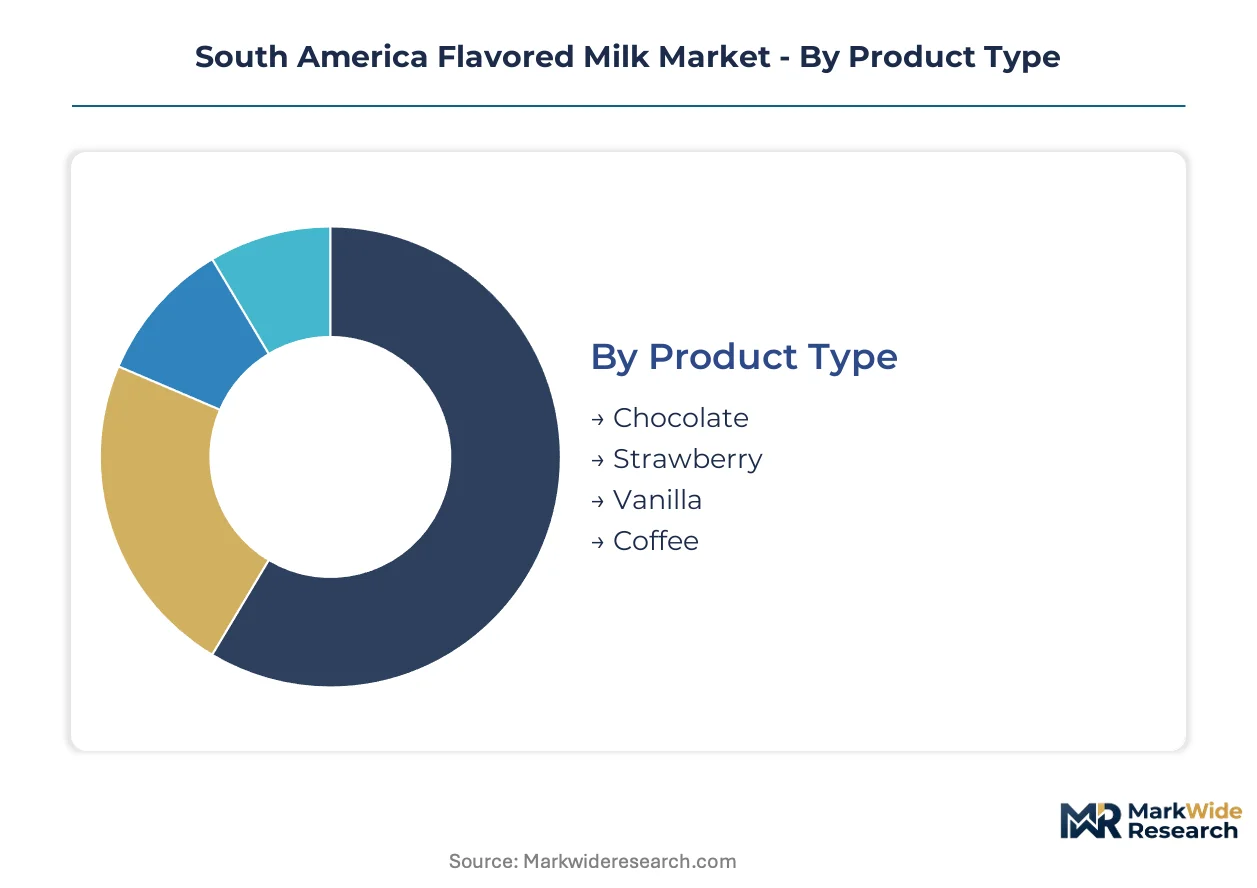
Segmentation in South America's flavored milk sector reveals how formulation choices, packaging economics, and channel access determine competitive positioning across Brazil, Argentina, and neighboring markets. Understanding these divides exposes where margin pools concentrate and where infrastructure gaps create whitespace.
Product Type:
Flavor profiles segment the market along entrenched consumption rituals versus emerging adult-oriented positioning, with cost-tier differentiation separating mass-market staples from premium innovations.
- Chocolate:Formulations contain 80-90% milk content with cocoa solids standardized at 1.5-2.5% for color stability and mouthfeel. Demand concentrates in Brazil's southeastern school nutrition corridors where PNAE procurement anchors institutional volumes. ANVISA's sugar warning thresholds are forcing cocoa-intensity increases to maintain palatability during reformulation.
- Coffee:Café con leche variants integrate soluble coffee extracts at 0.8-1.2% concentration with elevated fat content (3.0-3.5%) for texture compensation. São Paulo's workplace consumption occasions and Buenos Aires metropolitan snacking rituals are driving premium positioning. Cold-chain infrastructure in Paraná and Minas Gerais supports distribution of chilled formats previously limited to coffee-shop channels.
- Strawberry:Fruit-flavored formulations rely on natural and artificial flavor systems with anthocyanin-based colorants for visual appeal. Children's breakfast occasions in Brazilian households dominate procurement patterns.
- Vanilla:Vanilla extract and vanillin variants target consumers seeking milder flavor profiles as alternatives to chocolate dominance. Argentine dairy processors emphasize this segment for cross-border Mercosur standardization.
Chocolate commands the established base. The steepest expansion runs through Coffee.
Customer Type:
Age-based segmentation maps nutritional need states against purchasing authority, with volume concentration in dependent segments and margin extraction in autonomous adult decision-makers.
- Children:Target demographic for fortified formulations with calcium and vitamin D enrichment at 15-30% daily value per serving. Brazil's PNAE school feeding program and parental breakfast rituals in São Paulo households concentrate demand. ANVISA's front-of-package warning labels are restricting high-sugar placements in retail environments frequented by family shoppers.
- Adults:Protein-fortified variants (4-6g per 200ml serving) and reduced-sugar formulations address post-workout recovery and workplace snacking needs. Gym micro-distribution partnerships in Buenos Aires and convenience store placement near São Paulo financial districts are expanding channel access. Coffee-flavored positioning commands price multiples above child-oriented chocolate equivalents.
- Teenagers:Single-serve portability and social consumption occasions drive purchase decisions in secondary school environments and recreational settings.
- Seniors:Digestive health claims and lactose-free processing target aging populations in Argentina's urban centers with specific nutritional supplementation requirements.
Children anchor volume procurement through institutional channels. Adults generate the fastest margin expansion through premium functional positioning.
Packaging Type:
Material and format choices segment along refrigeration dependency, shelf-life requirements, and portability needs, with technology investments determining geographic reach.
- Tetra Pak:Aseptic carton systems with aluminum barrier layers enable 180-day ambient stability without cold-chain dependency. Brazil's northeastern expansion into Bahia and Pernambuco relies entirely on this format to bypass refrigerated logistics gaps. Paraná processors are converting production lines to capture interior municipality access previously unreachable with pasteurized alternatives.
- Plastic Bottles:HDPE and PET formats dominate immediate-convenience channels where portability drives impulse purchase decisions. São Paulo and Buenos Aires metropolitan convenience store networks favor single-serve 250ml configurations for checkout zone placement. Refrigeration requirements limit distribution radius but enable fresh-taste positioning.
- Glass Bottles:Premium positioning and reuse-system compatibility support environmental credential claims in Argentine and southern Brazilian markets with established return infrastructure.
- Pouches:Flexible laminate formats reduce material cost and shipping weight for price-sensitive mass-market distribution, particularly in Brazil's informal retail channels.
Tetra Pak captures infrastructure-constrained expansion. Plastic bottles defend the highest-margin convenience channel.
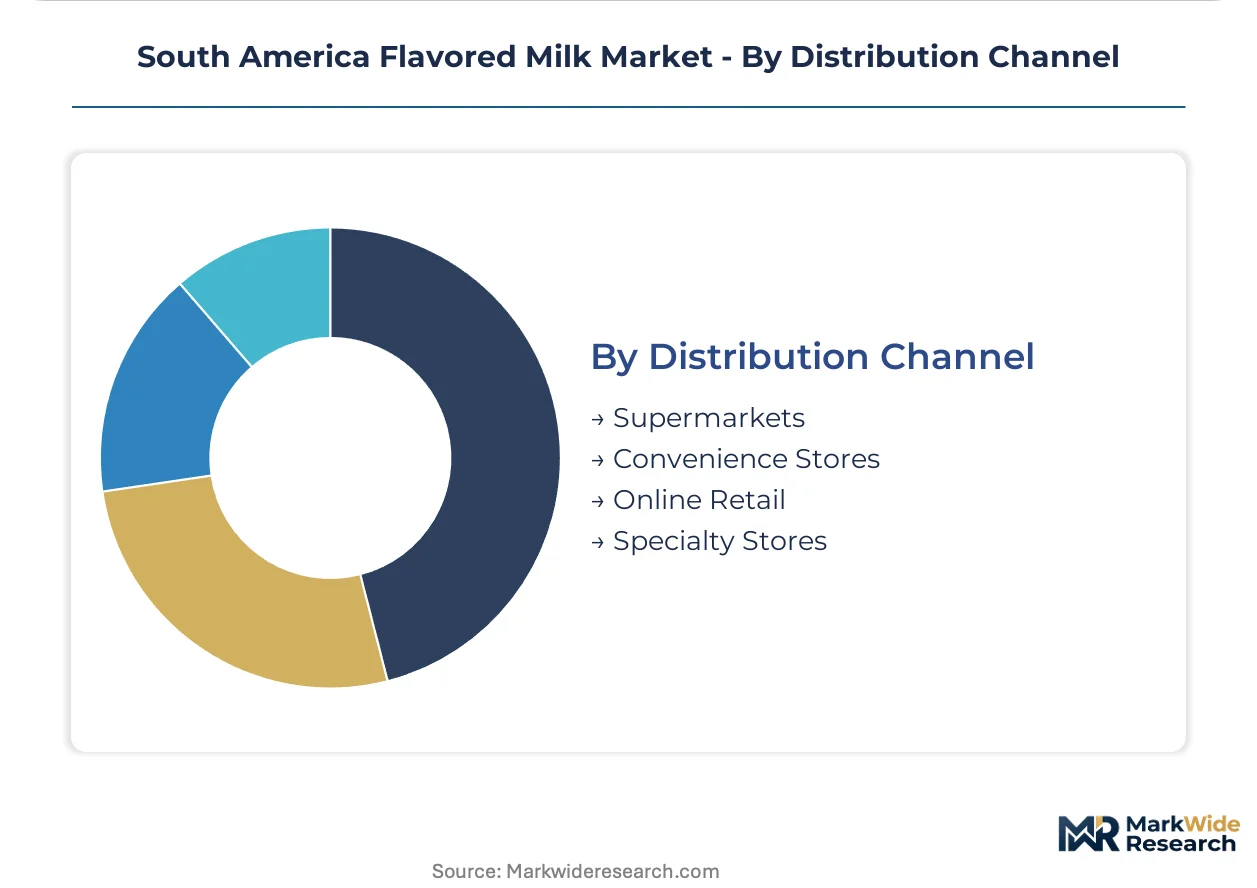
Distribution Channel:
Channel segmentation reflects cold-chain maturity, purchase occasion timing, and regulatory exposure to sugar-warning placement restrictions.
- Supermarkets:Multi-format shelf sets in São Paulo and Rio de Janeiro chains accommodate ambient Tetra Pak, chilled plastic bottle, and premium glass formats simultaneously. ANVISA's warning label enforcement is compressing planogram space for non-reformulated products, rewarding early movers with eye-level positioning. Brazil's southeastern retail concentration supports category management investments that secondary channels cannot replicate.
- Convenience Stores:Refrigerated single-serve placement captures afternoon snacking and post-workout recovery occasions in metropolitan corridors. São Paulo's 24-hour network and Buenos Aires' kiosk culture support premium pricing for immediate consumption needs. Checkout zone positioning drives impulse trial of coffee-flavored adult variants.
- Online Retail:E-commerce penetration remains constrained by refrigerated last-mile costs for fresh formats, though ambient-stable multi-packs gain traction in subscription models.
- Specialty Stores:Health food and fitness-oriented retailers concentrate probiotic-fortified and protein-enhanced variants for consumer segments with explicit nutritional targeting.
Supermarkets anchor volume through format breadth. Convenience stores are climbing fastest through occasion-based premium extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
School nutrition buyers and health-conscious adults concentrate demand in Brazil's southeastern corridor, with Argentine institutional procurement and Chilean convenience channels anchoring secondary volume pools across the continent.
Brazil
São Paulo and Minas Gerais households drive breakfast and afternoon snacking occasions for chocolate and coffee variants. ANVISA's front-of-package sugar warning labels are compressing formulation timelines for processors serving PNAE school feeding contracts. Paraná's dairy processing clusters are converting to aseptic carton lines to reach Bahia and Pernambuco without refrigerated logistics.
Argentina
Buenos Aires metropolitan consumers anchor café con leche consumption rituals in workplace and convenience channels. The National Food Commission mandates divergent protein-fat declarations that fragment cross-border standardization with Brazilian counterparts. Santa Fe and Córdoba dairy belts supply raw milk to processors facing seasonal yield volatility that compresses margins during low-production quarters.
Chile
Santiago convenience store networks capture impulse purchases of single-serve plastic bottle formats for post-workout recovery occasions. The national food safety regulator monitors sugar taxation proposals advancing in neighboring Andean markets. Valparaíso's port infrastructure supports dairy ingredient imports that enable flavor system innovation for adult-oriented positioning.
Colombia
Bogotá and Medellín retail corridors concentrate demand for ambient-stable UHT formats bypassing cold-chain gaps in mountainous terrain. The national health ministry is evaluating beverage taxation frameworks that threaten price-elasticity compression similar to Mexican precedents. Antioquia's dairy cooperatives are expanding processing capacity to capture Andean market share from Brazilian imports.
South America Flavored Milk Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Brazil's flavored milk sector, producing a tiered structure where scale-driven multinationals anchor supermarket volumes while regional cooperatives defend institutional procurement relationships. Three archetypes dominate: pan-regional dairy networks with raw milk security, probiotic-focused health-positioning specialists, and cross-border distributors leveraging Central American logistics. Competitive moves concentrate on reformulation speed to meet ANVISA deadlines and cold-chain infrastructure investments in southeastern states.
Among Swiss-anchored multinationals, Nestlé S.A. exemplifies the pan-regional network archetype through dairy supply integration across multiple South American countries. French-based Danone S.A. occupies the functional-positioning tier with probiotic-infused portfolio emphasis. Mexican-originated Grupo Lala represents the cross-border distribution archetype with Central American logistics reach creating procurement advantages. These three anchors illustrate how geographic origin and structural positioning determine competitive options in a reformulation-pressured market.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Danone S.A. |
| Arla Foods |
| Mococa S.A. Produtos Alimenticios |
| CBL Alimentos S.A. |
| The Coca-Cola Company |
| Grupo Lala |
| Vigor Alimentos |
| Itambé Alimentos S.A. |
| Others |
Value Network & Pricing Analysis
ANVISA's front-of-package sugar warning thresholds compress margin structures across Brazil's flavored milk sector, forcing processors to absorb reformulation costs or surrender retail placement in São Paulo's supermarket chains. This regulatory chokepoint widens spreads between reformulated premium tiers and legacy formulations while redirecting capital toward aseptic packaging lines that bypass cold-chain investments entirely.
Pricing Analysis
Cost-plus contracts indexed to Brazil's CEPEA raw milk price benchmark dominate procurement between Paraná processors and Pampas dairy cooperatives. Price differentiation rests on cocoa intensity and probiotic fortification tiers, with coffee-flavored adult variants commanding multiples above chocolate-based equivalents. Pricing pressure intensifies as ANVISA's warning label enforcement compresses planogram space for high-sugar formulations. Institutional buyers through PNAE school feeding contracts exhibit lowest price sensitivity, while informal retail channels in Northeast Brazil demand economy-tier positioning.
Supply Chain Analysis
Export-control regimes on aseptic filling technology from European suppliers constrain production line expansion timelines for Brazilian mid-sized processors. Raw milk supply concentrates in Argentina's Santa Fe and Córdoba belts alongside Brazil's Minas Gerais and Paraná clusters. Stabilizer systems and flavor masking agents draw from Chinese and European chemical suppliers. Single-source vulnerability in Tetra Pak barrier material systems threatens production continuity. Distribution runs through refrigerated logistics networks in southeastern states and ambient-stable corridors into Bahia and Pernambuco.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive advantage in South America's flavored milk sector, as Nestlé's pan-regional dairy network and Danone's probiotic strain libraries create interoperability moats that smaller processors cannot replicate without ecosystem partnerships.
For Market Incumbents: Insulate PNAE contract relationships through accelerated reformulation timelines that secure preferential supermarket placement before ANVISA enforcement deadlines. Deepen backward integration into Minas Gerais raw milk sourcing to buffer CEPEA index volatility. Prioritize aseptic line conversions in Paraná to capture Northeast Brazil expansion without stranded cold-chain assets.
For New Entrants and Emerging Players: Workplace convenience channels in São Paulo's financial districts represent the most penetrable entry point for coffee-flavored adult variants with premium positioning. Underpenetrated gym micro-distribution partnerships in Buenos Aires offer whitespace for protein-fortified formulations. Pursue private-label manufacturing relationships with regional supermarket chains lacking in-house dairy processing capabilities.
For Investors and Strategic Acquirers: ANVISA's October 2022 resolution reshapes the acquisition landscape toward reformulation-capable assets with clean-label R&D infrastructure. Long-term viability favors processors with dual-format flexibility across chilled and ambient-stable production. Monitor sugar taxation proposals across Andean nations as early signals of margin compression contagion beyond Brazil.
| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation Acceleration | ANVISA-compliant recipes secure preferential retail placement in São Paulo supermarket chains. |
| Aseptic Line Conversion | Tetra Pak technology enables distribution into Bahia and Pernambuco without refrigerated logistics. |
| Probiotic Strain Integration | Lactobacillus fortification commands premium positioning in adult-oriented convenience channels. |
| Backward Integration | Captive raw milk supply from Minas Gerais buffers CEPEA price index volatility. |
| Gym Micro-Distribution | Post-workout recovery occasions in Buenos Aires extract margin multiples above traditional retail. |
Research Methodology
Initial hypotheses were tested against primary input from dairy processing executives, ANVISA regulatory affairs specialists, supermarket category buyers, and PNAE program procurement officers and refined through secondary validation against customs records, CEPEA agricultural price databases, MAPA inspection reports, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down macroeconomic projections.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include flavor profile, customer age cohort, packaging format, and distribution channel alongside regional cold-chain infrastructure maturity. CAGRs were derived through regression analysis of historical consumption patterns and elasticity-adjusted price scenarios. Forecast inputs incorporated PNAE procurement expansion timelines and aseptic packaging adoption curves.
Practitioners should monitor ANVISA enforcement rigor and Andean sugar taxation legislative progress for early signals of structural margin compression. Forecasts reflect assumptions on regulatory harmonization trajectories and cold-chain infrastructure buildout rates. Material shifts in Mercosur cross-border dairy trade protocols or CEPEA raw milk price volatility regimes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
GCC Cheese Market
Dairy Products
Mascarpone Cheese Market
Dairy Products
White Cheese Market
Dairy Products
Cheddar Cheese Market
Dairy Products
Hydrolyzed Casein Market
Dairy Products
Lactose Free Probiotic Yogurt Market
Dairy Products
Global Lipolyzed Butter Fat Market
Dairy Products
Low Cholesterol Cheese Market
Dairy Products
Clotted Cream Market
Dairy Products
Butter Fat Fraction Market
Dairy Products
United States Dairy Market
Dairy Products
Canada Milk Protein Market
Dairy Products
Middle East and Africa Flavored Milk Market
Dairy Products
Lactose Free Butter Market
Dairy Products
Oman Dairy Products and Juice Market
Dairy Products
Milk Protein Crisps Market