
 South Africa Asphalt Market | 2026-2036
South Africa Asphalt Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Asphalt Market Intelligence
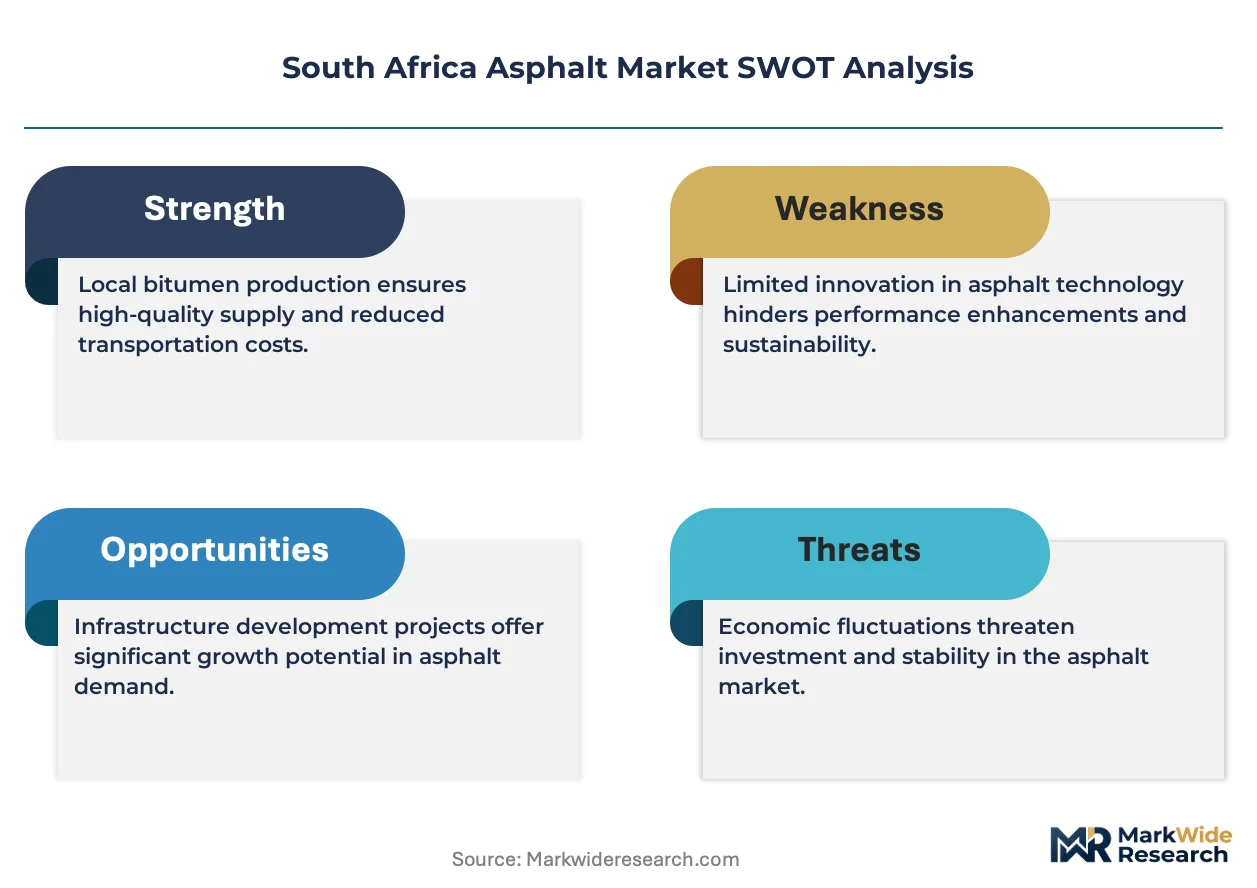
Polymer modified binders is expanding its share in high-stress pavement applications across South Africa's national road network. Much Asphalt leverages vertical integration from refinery sourcing to on-site laydown across multiple provinces. Donnstein Asphalts anchors its position in KwaZulu-Natal through specialized airport runway contracts. Apex Asphalt competes on reclaimed asphalt pavement technology leadership, reducing virgin bitumen dependence.
South Africa asphalt comprises bituminous binder mixed with mineral aggregate, typically designed to Marshall stability specifications exceeding 8 kN for heavy-duty highways, forming the primary wearing course for flexible pavements. Hot mix asphalt dominates volume through SANRAL and provincial road agency procurement, while polymer modified asphalt commands premium positioning on structurally critical routes. Reclaimed asphalt pavement technology is gaining structural acceptance as agencies revise tender specifications to incorporate recycled content quotas.
The South African National Roads Agency (SANRAL) enforces COLTO standard specifications for pavement design, while the South African Bureau of Standards (SABS) certifies bitumen grades under SANS 4001: Bitumen and Bituminous Products. These frameworks mandate performance-graded binders for heavy traffic categories, directly shaping product development priorities among domestic blenders. Stakeholders must monitor provincial infrastructure budget allocations and polymer supply chain localization requirements as determinants of competitive positioning.
Market Dynamics
SANRAL's revised COLTO specifications for performance-graded binders are compressing product development cycles across South Africa's asphalt blending sector. Provincial road agencies now mandate Marshall stability thresholds exceeding 8 kN for heavy-duty corridors, forcing rapid reformulation of conventional hot mix designs.
Growth Catalysts
- Provincial infrastructure budgets:Gauteng and KwaZulu-Natal road agencies are expanding rehabilitation contracts on the Johannesburg-Durban freight corridor, concentrating demand for polymer modified binders in high-stress applications.
- SANS 4001 certification:The South African Bureau of Standards bitumen grading framework mandates performance-graded binders for heavy traffic categories, creating structural pull for advanced blending capabilities.
- Reclaimed asphalt pavement quotas:Tender specifications now incorporate recycled content minimums, accelerating technology adoption among contractors serving SANRAL and provincial networks.
Market Restraints
- Bitumen import dependence:Domestic refineries supply limited volumes of penetration-grade bitumen, exposing blenders to crude-linked price volatility and exchange rate risk on imported binder.
- Polymer supply concentration:Styrene-butadiene-styrene and ethylene-vinyl-acetate modifiers rely on petrochemical imports, with localization requirements creating sourcing friction.
- Substitution by concrete:Cement-based rigid pavements compete for structurally critical routes, particularly where agencies prioritize 40-year design life over initial capital cost.
Strategic Opportunities
- Eastern Cape underpenetration:The province maintains lower asphalt intensity per kilometer of national road than Gauteng or Western Cape, presenting white space for contractors with mobile blending plants.
- Warm mix asphalt convergence:Foaming technologies combined with chemical additives reduce production temperatures, opening energy cost savings for producers facing carbon pricing pressure.
- Airport runway specialization:Specialized Marshall stability and fuel resistance specifications for aviation surfaces command premium positioning, with OR Tambo and King Shaka expansions driving specification upgrades.
Industry Challenges
- Skilled pavement engineer scarcity:Mix design certification for heavy-duty highways requires specialized training, with provincial agencies competing for limited SANRAL-accredited personnel.
- Capex intensity for polymer blending:In-line modification equipment and heated storage infrastructure demand capital deployment that mid-scale producers struggle to finance.
- Legacy specification fragmentation:Provincial agencies maintain divergent tender formats, forcing contractors to maintain multiple compliance workflows for equivalent material grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Asphalt Market |
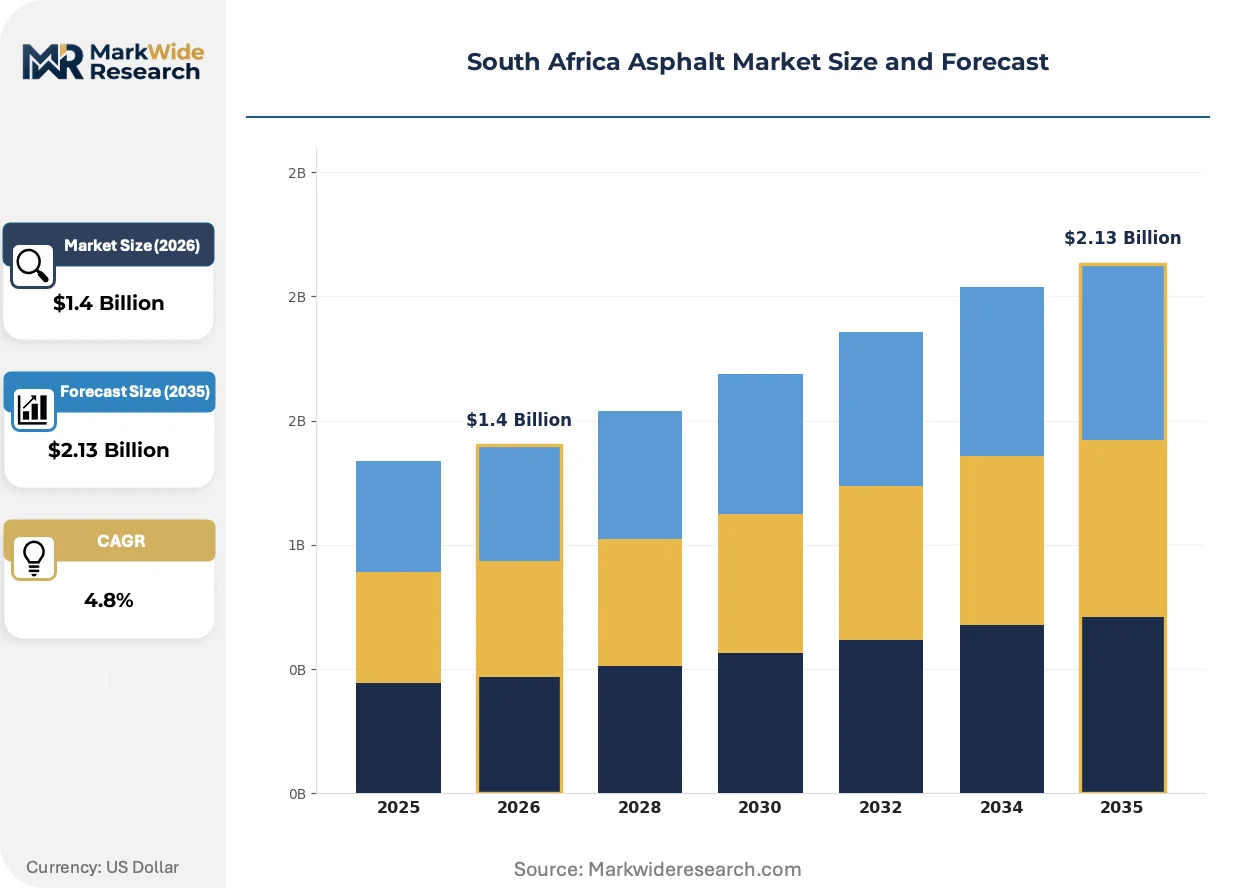
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Mix Asphalt, Warm Mix Asphalt, Cold Mix Asphalt, Polymer Modified Asphalt Application: Road Construction, Parking Lots, Airport Runways, Waterproofing End User: Construction Companies, Government Agencies, Infrastructure Developers, Private Developers Technology: Conventional, Reclaimed Asphalt Pavement, Warm Mix Technology, Intelligent Compaction |
| Companies Covered | Apex Asphalt, Matwal Projects, Much Asphalt, Donnstein Asphalts, Moriel Tarmac Solutions, SA Paving, Tar Surfaces Company, GrooveTech, SA Asphalt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Asphalt Market Strategic Shifts & Innovations
Digital compaction control and real-time density monitoring are compressing quality assurance timelines on South African road projects. These technologies intersect with evolving procurement models to reshape contractor-competency requirements.
Warm mix asphalt foaming technology is decentralizing production geography across South Africa's asphalt supply base. Contractors in remote provinces adopt low-temperature processes to extend haul distances without thermal segregation. Mobile foaming units enable on-site blending near aggregate sources, reducing transport cost exposure for projects beyond 100 kilometers from fixed plants.
SANRAL's implementation of performance-based contractor development regulations is restructuring qualification requirements for road maintenance tenders. The framework mandates enterprise development spend and skills transfer commitments, elevating compliance burden for foreign-owned engineering groups. Domestic mid-tier contractors with established black economic empowerment credentials capture disproportionate share of emerging contractor tier allocations.
Agency procurement is consolidating around design-build-maintain contracts, compressing traditional separation between material supply and construction execution. SANRAL and provincial road agencies bundle 20-year performance warranties with initial construction awards, shifting lifecycle cost accountability to integrated consortia. Gauteng and Western Cape agencies lead this transition, with KwaZulu-Natal piloting similar frameworks on N3 corridor segments.
South Africa Asphalt Market Segmentation
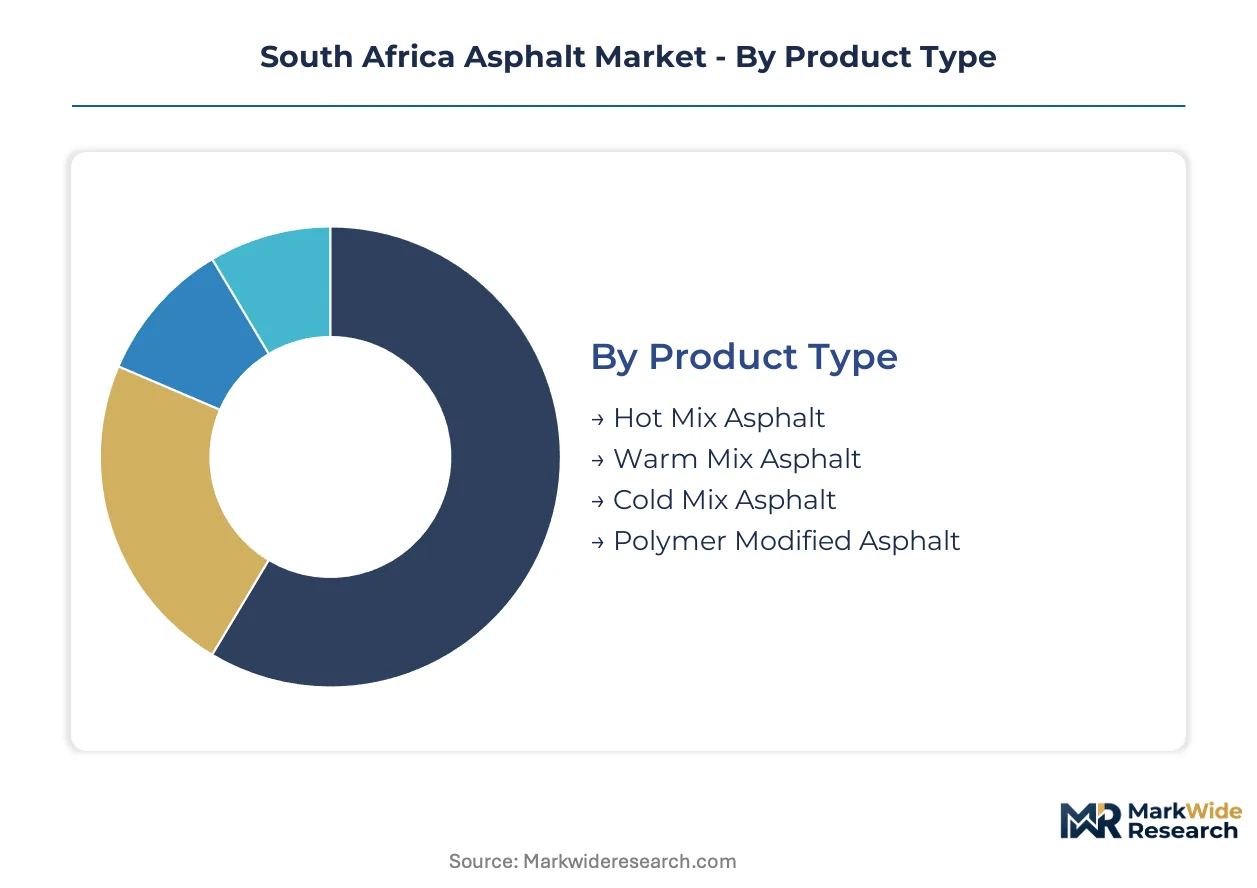
Segmentation in South Africa's asphalt market reveals how procurement specifications, material performance requirements, and contractor capabilities intersect. Each dimension carries distinct implications for blending technology investments and geographic deployment strategies across provincial road networks.
Product Type:
Supply concentration among domestic blenders favors hot mix formulations, while polymer modification capabilities remain concentrated in Gauteng and KwaZulu-Natal production clusters.
- Hot Mix Asphalt:Conventional bituminous binder combined with mineral aggregate at elevated temperatures, designed to Marshall stability specifications. SANRAL and provincial road agencies specify this grade for standard highway rehabilitation contracts across the Johannesburg-Durban freight corridor, where volume procurement compresses margins.
- Polymer Modified Asphalt:Styrene-butadiene-styrene or ethylene-vinyl-acetate modifiers enhance binder elasticity for heavy traffic loading. Demand concentrates on structurally critical N3 corridor segments where 40-year design life requirements displace conventional formulations.
- Warm Mix Asphalt:Foaming technologies reduce production temperatures by 20-40°C, extending haul radii for remote Eastern Cape projects.
- Cold Mix Asphalt:Emulsion-based formulations enable stockpiling and emergency patching without heated plant infrastructure.
Today's leader: Hot Mix Asphalt. Tomorrow's challenger: Polymer Modified Asphalt.
Application:
Cost tier differentiation separates high-specification aviation surfaces from commodity road construction, with airport contracts commanding premium positioning through specialized fuel resistance requirements.
- Road Construction:Flexible pavement wearing courses for national highways and provincial roads, governed by COLTO specifications and SANS 4001 bitumen grading. Gauteng and KwaZulu-Natal agencies drive volume through the Johannesburg-Durban freight corridor rehabilitation program.
- Airport Runways:Marshall stability thresholds exceeding 12 kN combined with jet fuel resistance specifications. OR Tambo and King Shaka expansions pull specialized polymer modified formulations from accredited blenders.
- Parking Lots:Lower traffic loading permits conventional hot mix designs with reduced binder grades.
- Waterproofing:Bituminous membranes for bridge decks and building applications, sourced from specialized coating formulations rather than pavement-grade production.
Road Construction anchors current procurement volume. Airport Runways deliver the steepest margin expansion trajectory.
End User:
Customer type determines contract structure complexity, with government agencies bundling long-term performance warranties that reshape supplier qualification requirements.
- Government Agencies:SANRAL and provincial road agencies mandate enterprise development commitments and black economic empowerment credentials under performance-based contractor development regulations.
- Construction Companies:Tier-1 contractors serving design-build-maintain contracts require integrated material supply and laydown capabilities.
- Infrastructure Developers:Private toll road concessions specify lifecycle cost-optimized pavement designs with extended maintenance intervals.
- Private Developers:Commercial and industrial projects prioritize initial capital cost over long-term performance, accepting conventional specifications.
Agency procurement dominates contract flow. Integrated contractor consortia are gaining share fastest in bundled service awards.
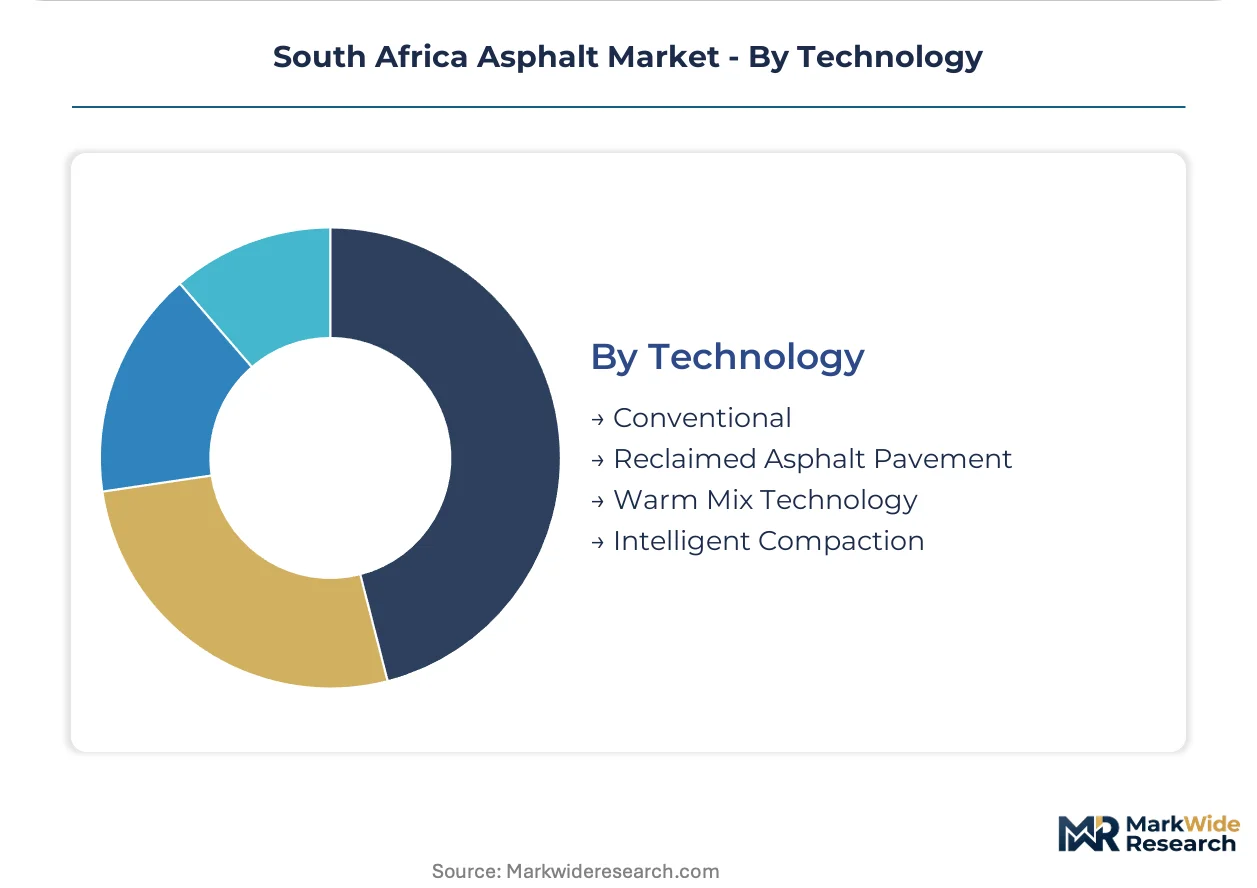
Technology:
Maturity gradients separate established mixing methods from emerging processes, with reclaimed content quotas accelerating adoption curves among SANRAL-accredited suppliers.
- Reclaimed Asphalt Pavement:Milled existing pavement reprocessed with virgin binder and aggregate, now mandated through tender recycled content minimums. Technology adoption accelerates as agencies revise specifications for circular material flows.
- Warm Mix Technology:Chemical additives and foaming processes reduce production energy intensity. Mobile units enable on-site blending near aggregate sources beyond 100 kilometers from fixed plants.
- Conventional:Traditional hot mixing without modification or recycling, still specified for lowest-bid provincial contracts.
- Intelligent Compaction:Real-time density monitoring and GPS-integrated roller control, compressing quality assurance timelines on high-specification projects.
Conventional methods retain volume leadership. Reclaimed Asphalt Pavement is climbing the fastest as regulatory quotas harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Johannesburg-Durban freight corridor anchors South Africa's asphalt demand concentration, with provincial road agencies driving procurement volume through rehabilitation programs on the N3 corridor and connecting national routes.
Gauteng
SANRAL's head office in Pretoria coordinates national procurement standards, while the provincial roads agency concentrates rehabilitation contracts on the Johannesburg-Durban corridor. The South African National Roads Agency enforces COLTO specifications that mandate performance-graded binders for heavy traffic categories. Johannesburg and Pretoria industrial zones host the densest clustering of polymer blending capacity serving structurally critical routes.
KwaZulu-Natal
Durban's port infrastructure positions the province as the entry point for imported bitumen and polymer modifiers, creating supply chain advantages for coastal blenders. Provincial tender specifications align with SANRAL's recycled content quotas, accelerating reclaimed asphalt pavement adoption. The King Shaka International Airport expansion and N3 corridor upgrades pull specialized formulations from accredited local producers.
Western Cape
The provincial transport department maintains distinct tender formats from Gauteng agencies, forcing contractors to maintain separate compliance workflows for equivalent material grades. Cape Town's urban road network drives steady demand for conventional hot mix designs on municipal contracts. The N1 and N2 corridor maintenance programs concentrate blending activity in the Bellville-Paarl industrial corridor.
Eastern Cape
Lower asphalt intensity per kilometer of national road creates white space for contractors deploying mobile blending plants to serve remote projects. The provincial roads agency specifications lag Gauteng and Western Cape adoption curves for warm mix technologies. Port Elizabeth and East London anchor limited fixed-plant infrastructure, with haul distances exceeding 100 kilometers for many rural contracts.
Free State
The N1 corridor through Bloemfontein connects Gauteng and Western Cape demand centers, positioning the province as a transit route rather than primary demand source. Provincial agency budgets concentrate on agricultural road rehabilitation with lower specification requirements than freight corridors. Limited local blending capacity forces reliance on Gauteng-sourced material for high-performance applications.
South Africa Asphalt Market Key Industry Players
Global majors compete with regional champions across technology tiers and geographic coverage, with domestic blenders holding structural advantages in SANRAL accreditation and black economic empowerment credentials. The vendor base organizes around three archetypes: vertically integrated refinery-linked producers, specialized polymer modification specialists, and mobile plant operators serving remote provinces. Consolidation pressure intensifies as design-build-maintain contracts bundle material supply with construction execution. Dominant competitive moves include backward integration into aggregate sourcing and strategic partnerships for polymer supply security.
Within the vertically integrated tier, Much Asphalt exemplifies refinery-linked scale advantages spanning multiple provinces. Apex Asphalt and Donnstein Asphalts occupy differentiated positions through technology specialization—reclaimed asphalt pavement leadership and airport runway expertise respectively. These three anchors represent distinct strategic postures: captive supply chain control, circular material innovation, and premium specification mastery.
| Leading Market Players |
|---|
| Apex Asphalt |
| Matwal Projects |
| Much Asphalt |
| Donnstein Asphalts |
| Moriel Tarmac Solutions |
| SA Paving |
| Tar Surfaces Company |
| GrooveTech |
| SA Asphalt |
| Others |
Cost & Logistics Intelligence
SANRAL's performance-graded binder mandates for heavy traffic categories are compressing conventional hot mix margins while elevating premium tiers. Blenders must absorb polymer modifier costs or cede structurally critical N3 corridor contracts to accredited competitors with in-house modification capability.
Pricing Analysis
Imported bitumen and polymer modifier costs pass through directly to tender pricing, with exchange rate volatility amplifying margin pressure on non-vertically integrated blenders. Three-tier pricing structure across premium, standard, and economy levels separates polymer modified formulations from conventional hot mix and emulsion-based cold mix. Cost compression in the standard tier is intensifying because provincial agencies bundle 20-year performance warranties with initial awards. Construction companies serving design-build-maintain contracts show least price sensitivity, while municipal procurement departments drive aggressive lowest-bid competition.
Supply Chain Analysis
Single-source vulnerability sits with Middle Eastern and Asian bitumen exporters, as domestic South African refineries supply limited penetration-grade volumes. Geographic supply concentration spans Saudi Arabia, Iran, and Singapore for base bitumen, with styrene-butadiene-styrene modifiers drawing from South Korea and Germany. Tariff exposure runs through polymer import channels where localization requirements create sourcing friction. Distribution runs through Durban port infrastructure for coastal blenders, with Gauteng producers relying on rail and road haulage from coastal terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Warm mix asphalt adoption and reclaimed content quotas create margin-expansion pathways for technology leaders. Energy cost savings from reduced production temperatures offset carbon pricing exposure while recycled content mandates reduce virgin bitumen dependence.
For Market Incumbents: Anticipate provincial agency consolidation of design-build-maintain contracts by securing SANRAL accreditation for polymer modification and reclaimed asphalt pavement processing. Cement-based rigid pavement substitution on 40-year design life routes threatens flexible pavement share on structurally critical corridors. Backward integration into aggregate quarries near the Johannesburg-Durban freight corridor secures supply security for high-volume contracts. For New Entrants and Emerging Players: Begin with mobile warm mix foaming units serving Eastern Cape rehabilitation contracts beyond 100 kilometers from fixed plants. The province maintains lower asphalt intensity per kilometer than Gauteng or Western Cape, presenting accessible white space. Partner with provincial roads agencies on pilot recycled content quota compliance to establish SANRAL accreditation credentials. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier contractors holding black economic empowerment credentials and established provincial agency relationships. Long-term viability hinges on positioning for bundled 20-year performance warranty contracts as agency procurement consolidates. Watch for SANRAL implementation of enterprise development spend mandates as the inflection signal for qualification tier restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Blending Capacity Expansion | Gauteng and KwaZulu-Natal production clusters capture N3 corridor premium tier demand. |
| Reclaimed Asphalt Pavement Technology Investment | Agency recycled content quotas accelerate circular material flow adoption among accredited suppliers. |
| Warm Mix Foaming Unit Deployment | Mobile units extend haul radii for Eastern Cape contracts beyond fixed plant reach. |
| Aggregate Quarry Backward Integration | Captive supply secures material security for high-volume provincial rehabilitation programs. |
| SANRAL Accreditation Maintenance | Performance-based contractor development regulations elevate compliance burden for market access. |
Research Approach
Multiple input streams — technical discussions with asphalt plant managers, procurement leads at provincial road agencies, SANRAL specification engineers, and polymer modifier distribution specialists — were reconciled against customs trade records, SABS certification databases, and COLTO specification documentation. Bottom-up volume estimates from provincial tender awards were triangulated with top-down bitumen import flow analysis.
Data-stream reconciliation across product type, application grade, end-user contract structure, and technology adoption maturity shaped the analytical framework. CAGRs were derived from modeled provincial infrastructure budget allocations and specification upgrade trajectories. Forecast inputs incorporated polymer supply chain localization requirements and reclaimed content quota implementation timelines.
Several conditions sit outside the modeled scope, including abrupt exchange rate movements affecting bitumen import costs and unanticipated cement pavement substitution on major corridor upgrades. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Rock Drill Shank Adaptor Market
Construction and Engineering
NDT Inspection Services Market
Construction and Engineering
North America Anchors and Grouts Market
Construction and Engineering
India Particle Board Market
Construction and Engineering
France Prefab Homes Market
Construction and Engineering
Warm Mix Asphalt Market
Construction and Engineering
Global Operating Equipment Room Market
Construction and Engineering
Hand Tools Market
Construction and Engineering
North America Gypsum Board Market
Construction and Engineering
Canada Commercial HVAC Market
Construction and Engineering
Pervious Concrete Market
Construction and Engineering
Pocket Door Market
Construction and Engineering
Global HVAC Controls Market
Construction and Engineering
Trailer Winch Market
Construction and Engineering
Port Material Handling Equipment Vehicle Market
Construction and Engineering
Fire Hydrants Market