
 Smart Finance Hardware Market | 2026-2036
Smart Finance Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Finance Hardware Market Intelligence
Aftermarket service revenue is fragmenting across terminal maintenance, software update subscriptions, and remote diagnostics contracts. Diebold Nixdorf leverages its global service footprint to capture recurring revenue from ATM fleets. NCR Corporation sustains competitive pressure through integrated point-of-sale and digital banking platforms. Fujitsu anchors its position in the Asia-Pacific corridor with specialized biometric authentication terminals.
Smart finance hardware encompasses physical devices engineered for financial transaction processing, incorporating secure element chips rated at Common Criteria EAL4+ or higher, tamper-resistant enclosures, and encrypted communication protocols for real-time payment authorization. Point-of-Sale Terminals and Mobile Payment Devices command the dominant share of hardware shipments as retailers and transit operators replace legacy magnetic-stripe infrastructure. Wireless NFC and Bio-metric Authentication represent the fastest-expanding technology categories, driven by contactless transaction limits and fraud-reduction mandates from card networks.
The US Federal Reserve and NIST set hardware security baseline requirements for payment terminals, while PCI DSS certification governs device eligibility for card network acceptance across North America and Europe. India's RBI mandates EMV migration timelines for domestic debit cards, forcing hardware upgrades at merchant locations nationwide. Stakeholders must weigh cloud-based deployment architectures against hybrid system investments as regulatory data-sovereignty rules tighten across multiple jurisdictions.
Market Dynamics
PCI DSS compliance deadlines and EMV chip mandates are forcing synchronized hardware refresh cycles across merchant fleets, compressing replacement timelines from seven-year cycles to four-year cycles and redistributing purchasing power toward certified terminal manufacturers with integrated service capabilities.
Growth Catalysts
- India EMV Migration:RBI-mandated chip-card deadlines for domestic debit networks are compelling nationwide terminal upgrades at merchant locations, creating concentrated demand for contactless-enabled POS infrastructure.
- Biometric Authentication Modules:Fingerprint and iris-scanning terminals are penetrating transit and banking applications as card networks tighten fraud-liability rules for non-compliant authentication methods.
- Southeast Asia Retail Expansion:Banking networks across Indonesia, Thailand, and Vietnam are deploying self-service terminal fleets to extend financial inclusion into underbanked urban corridors.
Market Restraints
- Secure Element Chip Concentration:Production of Common Criteria EAL4+ certified chips concentrates among three semiconductor foundries, exposing hardware vendors to allocation delays during demand spikes.
- Copper and Rare Earth Input Volatility:Tamper-resistant enclosure manufacturing depends on copper alloy and neodymium magnet supplies subject to export restriction risks from primary producer jurisdictions.
- Cloud Data Sovereignty Friction:Brazil's central bank data-localization requirements and India's RBI storage mandates are fragmenting cloud-connected terminal architectures and raising compliance engineering costs.
Strategic Opportunities
- Transit-Integrated Payment Convergence:Open-loop contactless acceptance in metro systems across Singapore, Hong Kong, and Kuala Lumpur is creating demand for dual-purpose transit-retail terminals.
- Software-Defined Terminal Platforms:Android-based POS operating systems are enabling application marketplaces that transform hardware into recurring-revenue service delivery vehicles.
- Brazil PIX Instant Payment Infrastructure:Central bank real-time settlement mandates are accelerating QR-code terminal deployment at micro-merchant locations previously excluded from electronic payments.
Industry Challenges
- EMV Certification Timeline Compression:Laboratory testing queues for Level 1 and Level 2 compliance are extending hardware launch schedules by six to nine months, delaying revenue recognition.
- Legacy System Integration Complexity:Hybrid deployment architectures requiring seamless handoff between cloud-based transaction routing and on-premise settlement systems are elevating field engineering costs.
- Embedded Firmware Talent Scarcity:Shortage of engineers with secure boot and trusted execution environment expertise is constraining product development velocity at mid-tier hardware vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Finance Hardware Market |
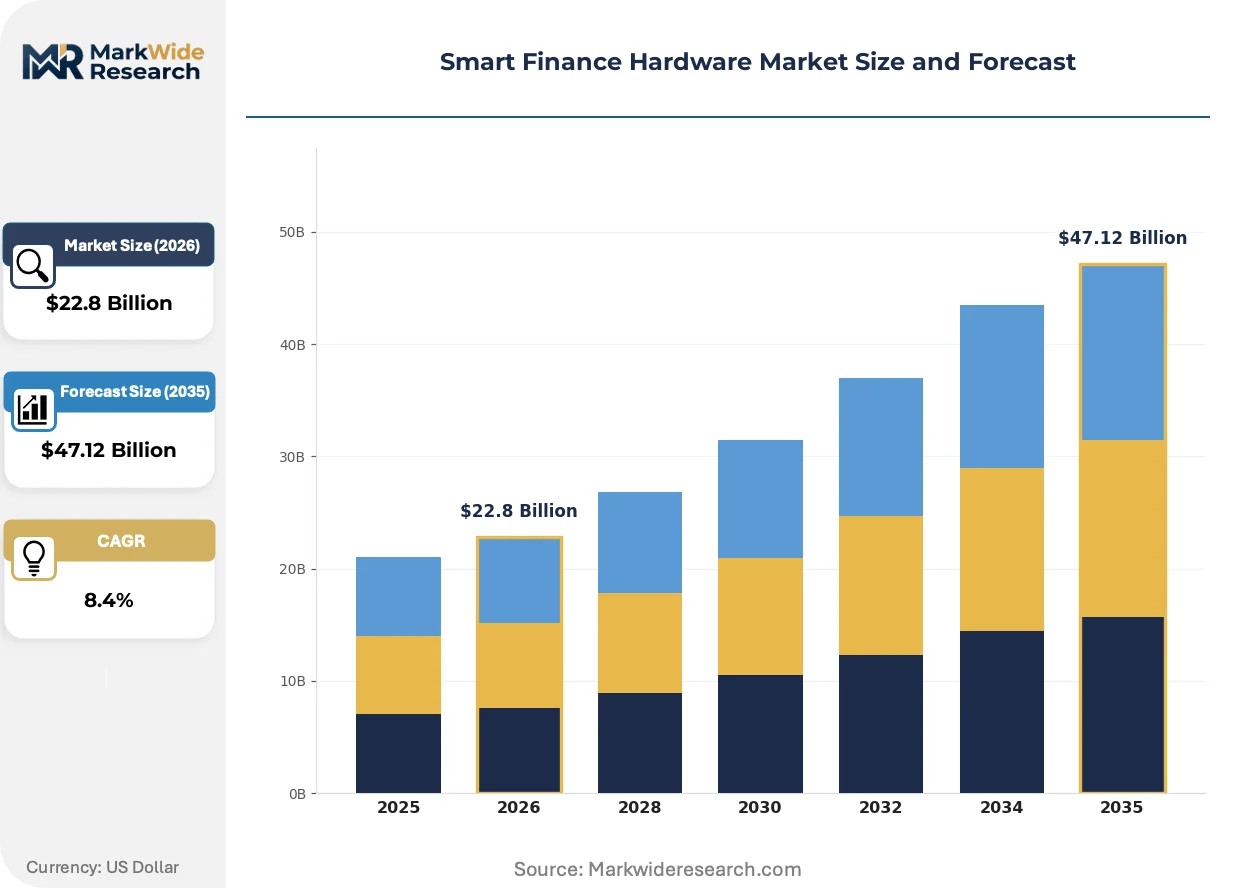
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Point-of-Sale Terminals, Card Readers, Cash Counters, Mobile Payment Devices Technology: Wireless NFC, RFID, Bluetooth, Bio-metric Authentication End User: Retailers, Banks, Investment Firms, E-commerce Platforms Deployment: On-premise, Cloud-based, Hybrid Systems, Mobile Solutions |
| Companies Covered | Diebold Nixdorf, NCR Corporation, Intel Corporation, Fujitsu, Hyosung TNS, GRG Banking Equipment, PAX Technology, Microchip Technology, Digi International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Finance Hardware Market Strategic Shifts & Innovations
Payment terminal architecture is bifurcating between ultra-commoditized Android-based devices and hardened proprietary platforms, with the boundary between hardware and software value capture shifting decisively toward operating system and application layer control.
SoftPOS technology is collapsing the distinction between dedicated payment terminals and general-purpose mobile devices. Retailers and gig-economy merchants are adopting smartphone-based card acceptance without separate hardware investment. This convergence is compressing addressable market volume for traditional POS terminal shipments while expanding total transaction-processing addressable market through lower barrier-to-entry deployment models.
EU CSRD sustainability disclosure requirements and REACH substance restrictions are mandating modular terminal designs with replaceable components and documented end-of-life recycling pathways. Hardware manufacturers are redesigning enclosure assemblies to eliminate restricted substances and enable component-level refurbishment. Banking procurement departments in Germany, France, and the Netherlands are now weighting circularity metrics at fifteen to twenty percent of vendor evaluation scores.
Merchant acquiring banks are unbundling terminal supply from payment processing contracts, reversing decade-long bundled pricing conventions. Independent software vendors and specialized terminal lessors are capturing hardware procurement decisions previously controlled by processor-owned distribution arms. This disintermediation is most visible in the UK and Australia, where open-banking frameworks have accelerated processor-switching and weakened captive hardware lock-in.
Smart Finance Hardware Market Segmentation
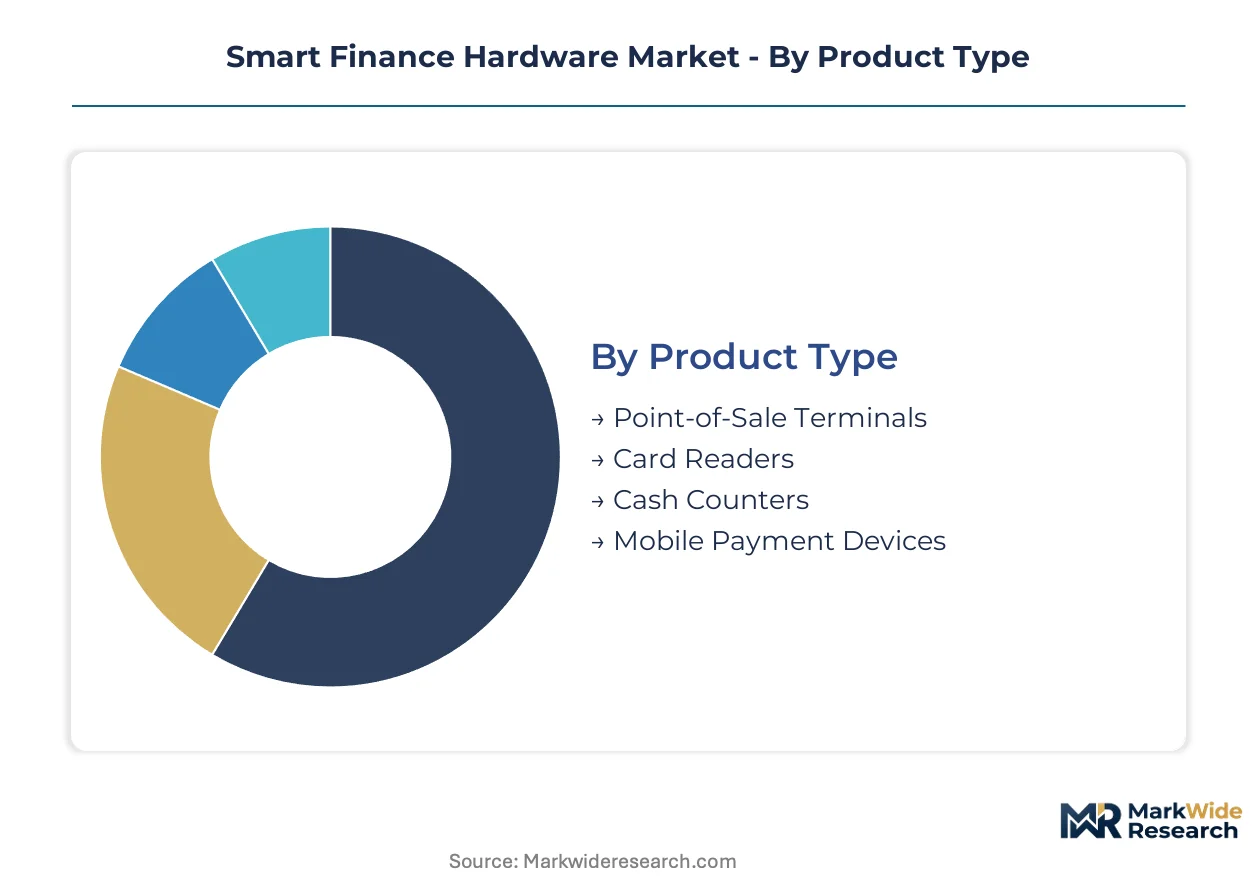
Smart finance hardware segmentation reveals divergent technology maturity curves and compliance requirements across product categories. Hardware procurement decisions increasingly hinge on certification grade, connectivity architecture, and service integration depth rather than unit cost alone.
Product Type:
Cost tier stratification separates merchant-grade infrastructure from consumer-facing peripherals and back-office equipment.
- Point-of-Sale Terminals:These devices integrate secure element chips rated Common Criteria EAL4+ with tamper-resistant enclosures and encrypted communication protocols. Demand concentrates in India's merchant fleet upgrades driven by RBI-mandated EMV migration timelines for domestic debit networks.
- Mobile Payment Devices:Portable terminals with wireless connectivity and battery-optimized form factors serve gig-economy merchants and transit operators. Brazil's PIX instant payment infrastructure is accelerating QR-code terminal deployment at micro-merchant locations previously cash-dependent.
- Card Readers:Compact peripheral devices attach to smartphones or tablets via audio jack or Bluetooth. SoftPOS technology is collapsing the distinction between dedicated terminals and general-purpose mobile devices.
- Cash Counters:Back-office machines automate currency authentication and batch processing for high-volume retail and banking operations. These units face longer replacement cycles than customer-facing equipment.
Point-of-Sale Terminals holds installed capacity. Mobile Payment Devices is rotating up the share rankings.
Technology:
Application-specific performance requirements determine authentication method selection across transit, retail, and banking environments.
- Wireless NFC:Near-field communication enables contactless transaction completion under 500 milliseconds with encrypted token exchange. Open-loop contactless acceptance in Singapore, Hong Kong, and Kuala Lumpur metro systems is creating demand for dual-purpose transit-retail terminals.
- Bio-metric Authentication:Fingerprint and iris-scanning modules penetrate high-value banking and transit applications as card networks tighten fraud-liability rules. Fingerprint and iris-scanning terminals are penetrating transit and banking applications as card networks tighten fraud-liability rules for non-compliant authentication methods.
- RFID:Radio-frequency identification supports inventory-integrated payment systems and closed-loop campus or corporate environments. Retailers deploy RFID for item-level tracking combined with checkout automation.
- Bluetooth:Short-range wireless connects peripherals to host devices in environments where NFC field interference occurs. Bluetooth modules serve backup connectivity roles in hybrid terminal architectures.
Wireless NFC maintains dominant transaction volume. Bio-metric Authentication is climbing the fastest among authentication categories.
End User:
Customer type dictates procurement scale, service integration requirements, and compliance stringency across deployment scenarios.
- Retailers:Merchant acquirers are unbundling terminal supply from payment processing contracts, reversing decade-long bundled pricing conventions. Independent software vendors capture hardware procurement decisions previously controlled by processor-owned distribution arms.
- Banks:Financial institutions deploy self-service terminal fleets to extend inclusion into underbanked urban corridors across Indonesia, Thailand, and Vietnam. Banking procurement departments in Germany, France, and the Netherlands weight circularity metrics at fifteen to twenty percent of vendor evaluation scores.
- Investment Firms:Trading floor infrastructure demands low-latency transaction confirmation and multi-factor authentication for high-value transfers. These deployments prioritize security certification over unit economics.
- E-commerce Platforms:Online merchants require hardware for physical pop-up locations, returns processing, and omnichannel fulfillment integration. E-commerce platforms drive demand for portable, software-defined terminal platforms.
Retailers command the largest unit shipments. Banks is rotating up the share rankings on replacement cycle compression.
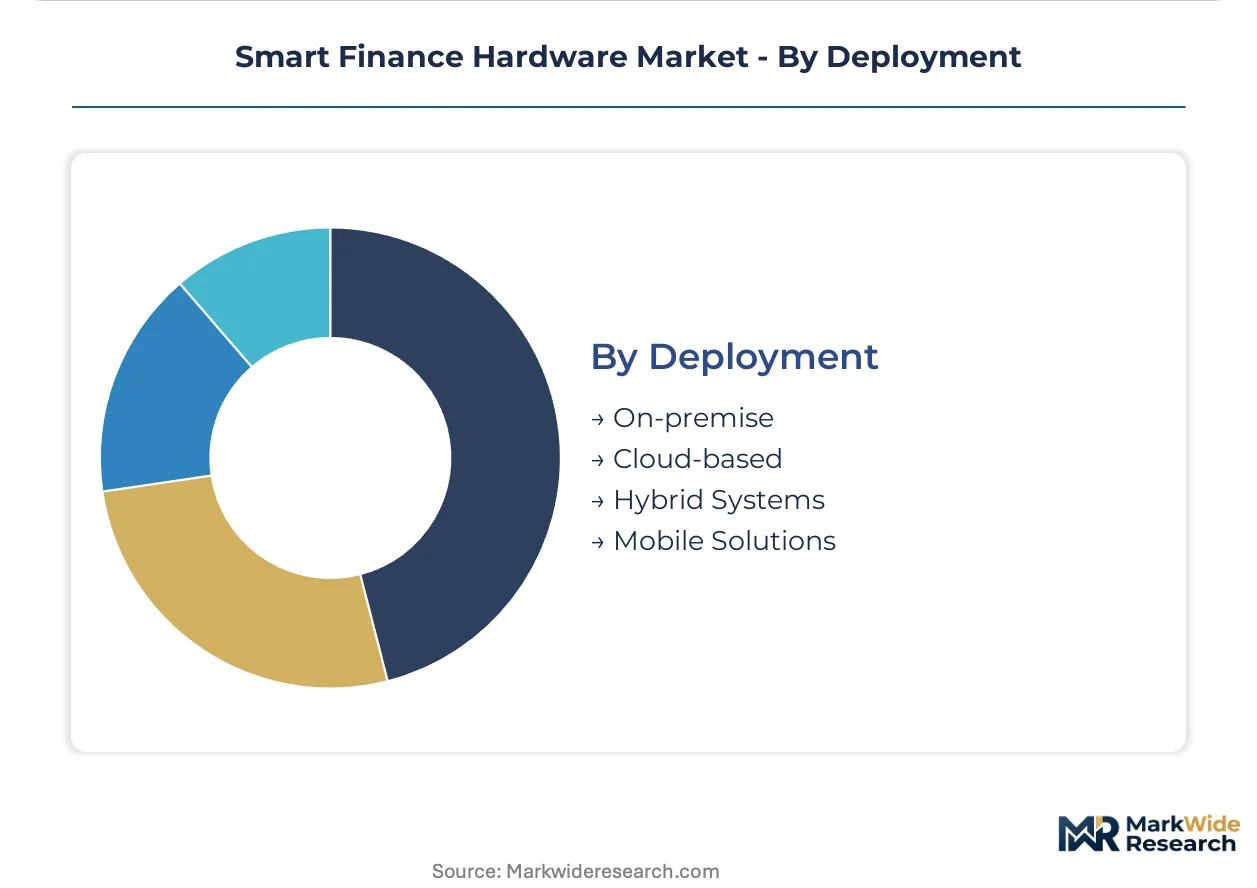
Deployment:
Architecture selection reflects data sovereignty constraints, latency requirements, and legacy system integration complexity.
- Cloud-based:Terminals route transactions through remote servers with centralized software management and over-the-air updates. Brazil's central bank data-localization requirements and India's RBI storage mandates are fragmenting cloud-connected terminal architectures.
- Hybrid Systems:Architectures requiring seamless handoff between cloud-based transaction routing and on-premise settlement systems are elevating field engineering costs. Hybrid deployments dominate in jurisdictions with strict data-residency rules.
- On-premise:Fully localized processing maintains transaction data within merchant or bank physical infrastructure. On-premise systems persist in markets with underdeveloped telecommunications infrastructure.
- Mobile Solutions:Smartphone-based acceptance without separate hardware investment expands total transaction-processing addressable market through lower barrier-to-entry deployment models. SoftPOS technology is collapsing the distinction between dedicated payment terminals and general-purpose mobile devices.
Hybrid Systems holds installed capacity. Cloud-based is rotating up the share rankings despite sovereignty friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and Brazil exhibit the highest demand elasticity as regulatory mandates compress replacement cycles, while the United States and Germany show lower price sensitivity due to premium-tier procurement standards and integrated service requirements.
United States
Merchant acquirers and banking networks drive steady refresh demand for PCI DSS-certified terminal infrastructure. The Federal Reserve and NIST establish hardware security baselines that elevate compliance costs for non-domestic suppliers. Terminal deployment concentrates in New York and Chicago financial corridors where integrated POS-digital banking platforms dominate procurement decisions.
India
RBI-mandated EMV migration timelines for domestic debit networks are compelling nationwide terminal upgrades at millions of merchant locations. The central bank's chip-card deadlines force four-year replacement cycles rather than traditional seven-year horizons. Hardware procurement clusters in Mumbai and Bangalore where banking networks expand self-service terminal fleets into underbanked urban corridors.
Brazil
Central bank PIX instant payment infrastructure accelerates QR-code terminal deployment at micro-merchant locations previously excluded from electronic payments. Data-localization requirements from the central bank fragment cloud-connected terminal architectures and raise compliance engineering costs. São Paulo anchors terminal manufacturing and distribution networks serving Latin American markets.
Germany
EU CSRD sustainability disclosure requirements and REACH substance restrictions mandate modular terminal designs with documented end-of-life recycling pathways. Banking procurement departments weight circularity metrics at fifteen to twenty percent of vendor evaluation scores. Industrial concentration in Bavaria and Baden-Württemberg supports precision manufacturing of tamper-resistant enclosure assemblies.
Singapore
Open-loop contactless acceptance in metro systems creates demand for dual-purpose transit-retail terminals serving both payment environments. The city-state's financial regulator enforces strict data-sovereignty rules for cloud-connected payment infrastructure. Hardware deployment concentrates in the central business district and Changi Airport corridor where transit-integrated payment convergence drives specialized terminal specifications.
Smart Finance Hardware Market Key Industry Players
Capability concentration sits with specialized secure-element and biometric authentication developers; scale advantage sits with integrated platform vendors possessing global service footprints. The market structure exhibits tiered consolidation around three to five dominant hardware manufacturers with certified production capacity, while mid-tier vendors compete on regional customization and faster certification turnaround. Two strategic archetypes predominate: vertically integrated terminal manufacturers with captive semiconductor sourcing, and software-defined platform specialists leveraging Android-based operating systems. M&A activity targets biometric authentication module developers and regional service networks, while portfolio diversification into recurring-revenue service contracts displaces pure hardware sales models.
Among North American-headquartered platform vendors, Diebold Nixdorf and NCR Corporation exemplify the integrated-service archetype, leveraging global maintenance footprints to capture recurring revenue from ATM and POS terminal fleets. Fujitsu occupies a position within the Asia-Pacific specialized-authentication tier, anchoring regional demand for biometric-enabled terminals in transit and banking applications. These three manufacturers represent contrasting strategic positions: Diebold Nixdorf and NCR Corporation sit within the scale-driven, service-integrated segment, while Fujitsu exemplifies capability concentration in high-assurance authentication hardware.
| Leading Market Players |
|---|
| Diebold Nixdorf |
| NCR Corporation |
| Intel Corporation |
| Fujitsu |
| Hyosung TNS |
| GRG Banking Equipment |
| PAX Technology |
| Microchip Technology |
| Digi International |
| Others |
Cost & Logistics Intelligence
Undercapacity at Common Criteria EAL4+ certified foundries in Taiwan and South Korea drives allocation rationing and elevates spot pricing for secure element chips, compressing margins for terminal manufacturers while pushing procurement toward long-term offtake contracts with volume guarantees.
Pricing Analysis
Aftermarket service revenue tiers spanning terminal maintenance subscriptions, remote diagnostics contracts, and firmware update packages now drive lifetime value capture beyond hardware margins. Three-tier pricing structure across premium, standard, and economy certification levels separates PCI DSS Level 1 compliant terminals from regional-specification devices and unlicensed gray-market imports. Cost compression in economy-tier POS hardware is intensifying because SoftPOS technology collapses entry barriers for micro-merchants. Retail banking networks exhibit lowest price sensitivity due to integrated service requirements, while gig-economy merchants in Brazil and India demonstrate highest sensitivity to upfront hardware costs.
Supply Chain Analysis
Contract manufacturing concentration sits with Foxconn, Jabil, and Flex holding certified production capacity for tamper-resistant enclosure assembly. Secure element chip fabrication concentrates in Taiwan, South Korea, and Germany; enclosure manufacturing draws from China, Mexico, and Vietnam. Copper alloy and neodymium magnet supplies rest on export-restricted jurisdictions, exposing vendors to allocation delays during demand spikes. Distribution runs through processor-owned leasing arms, independent terminal lessors, and direct OEM sales to large banking networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart finance hardware sits in early-cycle expansion as regulatory mandates across India, Brazil, and Southeast Asia compress replacement cycles from seven years to four years, accelerating fleet turnover and opening procurement decisions to non-incumbent vendors.
For Market Incumbents: Build switching-cost moats through integrated service footprints and captive certification pipelines. Diebold Nixdorf and NCR Corporation should deepen backward integration into secure element sourcing to mitigate foundry allocation risks. Defensive consolidation through regional service network acquisitions protects recurring revenue streams against independent software vendors disintermediating hardware procurement.
For New Entrants and Emerging Players: Mid-market transit-retail convergence terminals in Singapore, Hong Kong, and Kuala Lumpur represent the most penetrable entry point for specialized authentication hardware. Brazil's PIX-enabled micro-merchant segment offers white-space demand for low-cost QR-code terminals with simplified compliance pathways. Go-to-market through independent acquiring banks unbundling terminal supply from processing contracts bypasses processor-owned distribution lock-in.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-defined terminal platforms as Android-based operating systems reduce hardware customization requirements. Long-term viability favors vendors with recurring-revenue service contracts displacing pure hardware sales. Acquisition targets should display biometric authentication module expertise or regional certification acceleration capabilities. Watch EMV certification queue lengths as inflection signal for vendor revenue recognition delays.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Authentication Module Acquisition | Captures capability concentration in fingerprint and iris-scanning terminals for transit-banking convergence applications. |
| Regional Service Network Expansion | Builds recurring revenue moats through maintenance contracts with RBI-mandated EMV upgrade fleets across Indian merchant locations. |
| Software-Defined Platform Development | Transforms hardware into Android-based service delivery vehicles with application marketplace revenue streams. |
| Secure Element Supply Agreement | Mitigates single-source vulnerability through long-term offtake contracts with Common Criteria EAL4+ certified foundries. |
| Transit-Retail Terminal Certification | Unlocks dual-purpose deployment in Singapore and Hong Kong metro systems with open-loop contactless acceptance mandates. |
Research Approach
Findings reconcile primary fieldwork against secondary review of PCI SSC certification databases, central bank regulatory filings from RBI and Brazil's central bank, and semiconductor foundry capacity disclosures. Primary interviews engaged terminal procurement managers at Southeast Asian banking networks, merchant acquiring executives in India and Brazil, and secure element supply chain directors. Secondary validation drew from EMVCo compliance bulletins, NIST hardware security guidelines, and EU CSRD sustainability disclosure frameworks. Bottom-up terminal shipment estimates triangulate against top-down payment transaction volume projections.
Forecast inputs include regulatory deadline schedules for EMV migration and data-localization mandates, secure element foundry capacity expansion announcements, and transit operator procurement timelines for open-loop contactless acceptance. Segmentation modeling spans product type, authentication technology, end-user category, and deployment architecture across the analysis window. CAGRs derive from regression against historical replacement cycle compression patterns and penetration rate assumptions for biometric-enabled terminals. Industry-specific inputs incorporate PCI DSS certification queue dynamics and SoftPOS adoption curves.
Stress conditions across secure element allocation delays, copper and rare earth export restrictions, and cloud data sovereignty enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory deadline adherence and foundry capacity utilization. Quarterly review of EMV certification queue lengths, central bank procurement announcements, and transit operator tender awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Information and Communication Technology
Europe Data Center Construction Market
Information and Communication Technology
Global Online Book Services Market
Information and Communication Technology
Big Data in Automotive Market
Information and Communication Technology
Ipad CRM Market
Information and Communication Technology
Omni Channel Messaging Software Market
Information and Communication Technology
AR Glasses Market
Information and Communication Technology
Network Security Appliance Market
Information and Communication Technology
Europe Mobile Cloud Market
Information and Communication Technology
Machine Learning As a Service (Mlaas) Market
Information and Communication Technology
IP PBX Market
Information and Communication Technology
Robotics and Automation Actuators Market
Information and Communication Technology
Smart Industries Market
Information and Communication Technology
Incubator Analyzer Market
Information and Communication Technology
Cannabis POS System Market
Information and Communication Technology
AI in Robotics Market
Information and Communication Technology
Yacht Management Software Market