
 Shortening Powder Market | 2026-2036
Shortening Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Shortening Powder Market Analytics
Malaysian oleochemical processors is recalibrating capacity toward powderized fat formats as bakery automation spreads across Asia. Cargill, Incorporated leverages its integrated oilseed processing network to secure feedstock cost advantages in shortening powder production. IOI Corporation Berhad anchors its position through captive palm oil plantations and downstream fractionation capabilities. AAK AB differentiates via specialty emulsifier blends that improve powder dispersibility in industrial mixing systems.
Shortening powder consists of refined vegetable or animal fats spray-dried or plated onto carbohydrate carriers, typically containing percent fat content ranging from percent to percent and achieving powder flow properties measured in Hausner ratio or Carr index values. The format serves industrial bakeries requiring precise fat incorporation without temperature-controlled liquid handling infrastructure. Non-hydrogenated shortening commands expanding volume as trans-fat labeling mandates harden across major markets, while bakery end users generate the dominant revenue pool due to scale procurement and formulation consistency requirements. Powdered form maintains leadership over granulated alternatives where pneumatic conveying and automated dosing systems predominate.
FDA trans-fat regulations and EFSA nutrient profiling standards constrain permissible formulations in North American and European applications, pressuring reformulation toward interesterified or fully hydrogenated alternatives. BIS quality specifications and FSSAI labeling mandates govern product standards in India, where import tariffs on finished shortening powder protect domestic refiners. Stakeholders must monitor evolving WHO trans-fat elimination targets and corresponding national implementation timelines to anticipate reformulation cost impacts and raw material sourcing shifts.
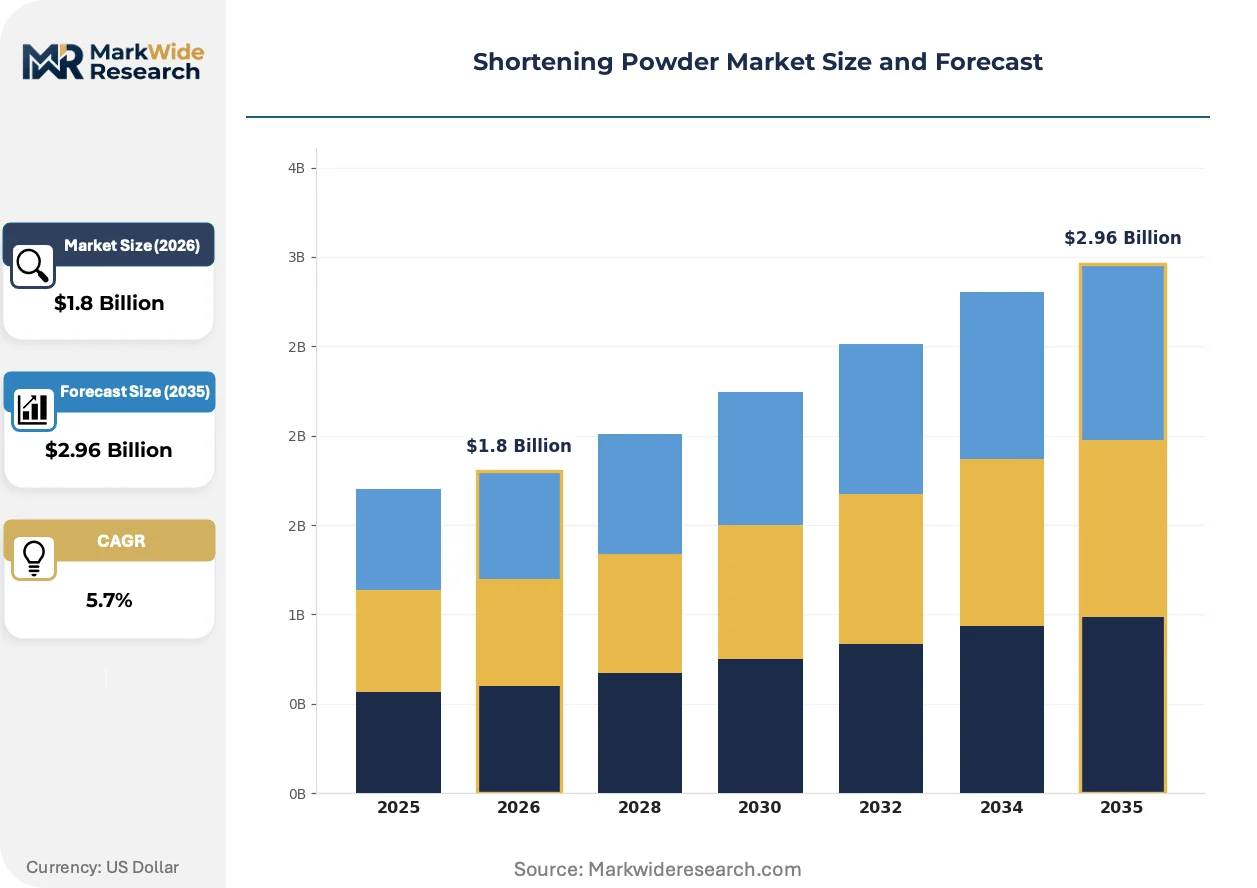
Market Dynamics
WHO trans-fat elimination guidelines are forcing industrial bakeries across Southeast Asia to abandon hydrogenated formulations, triggering a wholesale shift toward interesterified and fractionated palm oil feedstocks that reconfigures raw material sourcing and processing economics simultaneously.
Growth Catalysts
- Non-hydrogenated formulation mandates:FDA trans-fat regulations and EFSA nutrient profiling standards compel reformulation across North American and European industrial bakery operations, creating sustained demand for compliant shortening powder variants.
- Indonesia:Palm oil processing infrastructure concentration enables cost-competitive powder production for regional food service chains, with downstream fractionation capabilities expanding to meet bakery automation requirements.
- High-shear spray drying:Advances in encapsulation technology improve fat loading efficiency and powder flow properties, allowing precise dosing in pneumatic conveying systems without temperature-controlled liquid handling.
Market Restraints
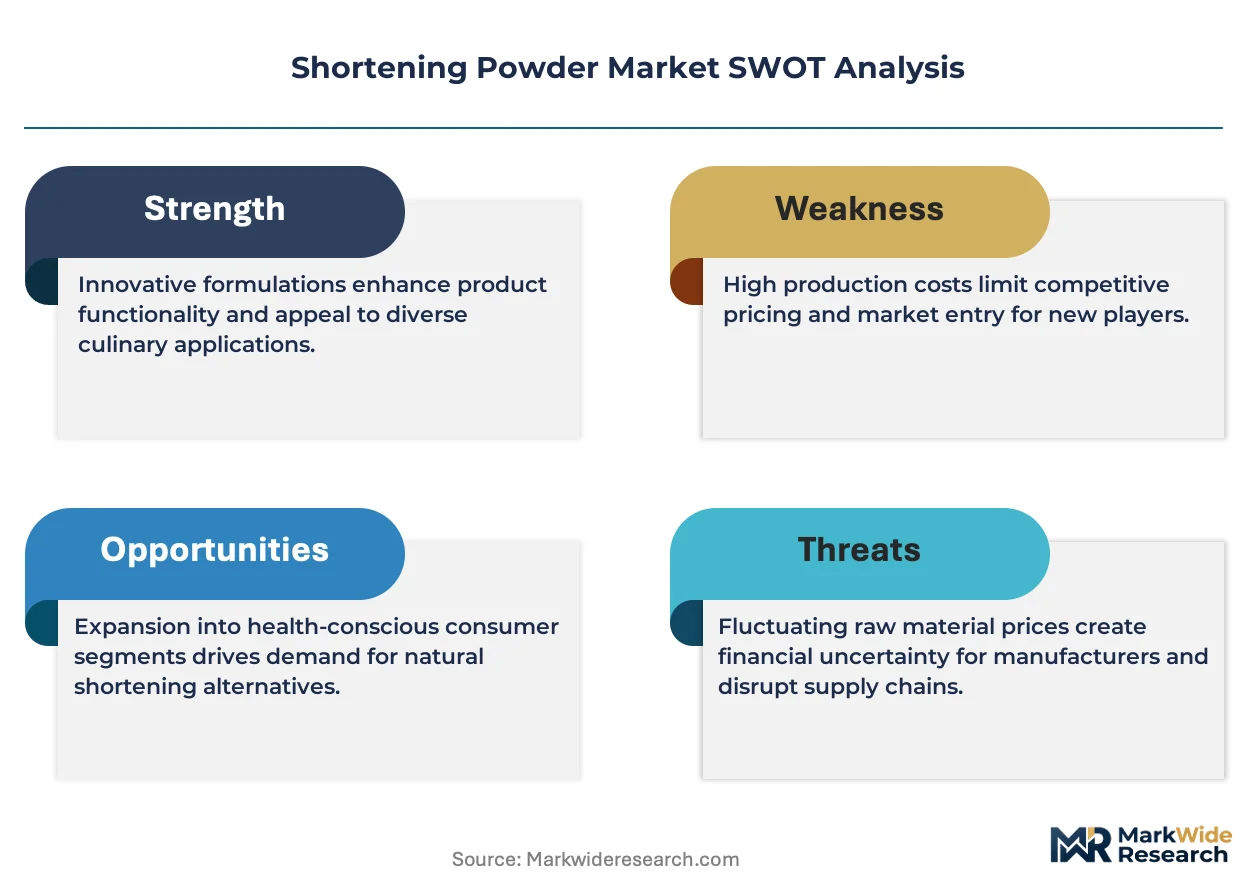
- Crude palm oil price volatility:Feedstock cost fluctuations in Malaysian and Indonesian supply basins compress margin structures for powder manufacturers lacking captive plantation access.
- Technical limitation in cold-water dispersibility:Standard shortening powders exhibit incomplete hydration in ambient-temperature mixing environments, restricting application scope in certain industrial bakery segments.
- Substitution threat from fluid shortenings:Liquid fat systems with improved oxidative stability displace powder formats in facilities with temperature-controlled storage infrastructure.
Strategic Opportunities
- Vietnam:Underpenetrated industrial bakery automation creates whitespace for powder format adoption as foreign direct investment expands frozen dough and par-baked operations.
- Clean-label emulsifier convergence:Integration of enzyme-modified lecithin and natural antioxidant systems opens premium positioning in European artisanal bakery channels.
- PLI scheme incentives:India's production-linked incentive framework for food processing supports domestic shortening powder capacity expansion against import tariff barriers.
Industry Challenges
- Interesterification process scale-up:Capital-intensive enzymatic reactor deployment strains mid-tier processors attempting non-hydrogenated conversion.
- FSSAI compliance timeline compression:Accelerated labeling mandate implementation in India forces rapid reformulation certification without extended validation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shortening Powder Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Shortening, Non-Hydrogenated Shortening, Animal Shortening, Organic Shortening End User: Bakery, Confectionery, Food Service, Households Form: Powdered, Granulated, Liquid, Solid Packaging Type: Bags, Boxes, Tubs, Pouches |
| Companies Covered | Archer Daniels Midland Company (ADM), Cargill, Incorporated, Fuji Oil Holdings Inc, IOI Corporation Berhad, Wilmar International Limited, AAK AB, Bunge Limited, Mewah International Inc., Manildra Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shortening Powder Market Evolving Landscape
Reformulation pressure from trans-fat elimination mandates is accelerating process technology investment across Southeast Asian oleochemical operations, with spray-drying equipment upgrades and emulsifier system innovation dominating capital allocation decisions.
Interesterified palm oil is converging with enzymatic modification processes to produce shortening powders with equivalent functionality to partially hydrogenated predecessors. Industrial bakeries in Malaysia and Thailand are adopting these systems at accelerating rates. This technology convergence is compressing the performance gap between legacy hydrogenated products and clean-label alternatives, enabling full portfolio transition without equipment replacement.
EFSA nutrient profiling standards and FDA trans-fat regulations are tightening permissible saturated fat ratios in finished bakery applications. European industrial users face reformulation deadlines that eliminate time-extended transition periods. Premium positioning strategies now emphasize interesterified base stocks with documented fatty acid profiles exceeding minimum threshold compliance.
Consolidated procurement by multinational food service chains is displacing fragmented distributor networks across Southeast Asian supply channels. Centralized specification setting by regional headquarters in Singapore standardizes shortening powder requirements across national subsidiary operations. This concentration pattern is most visible in Indonesia and the Philippines, where domestic bakery chains adopt identical formulation standards to multinational competitors.
Shortening Powder Market Segmentation
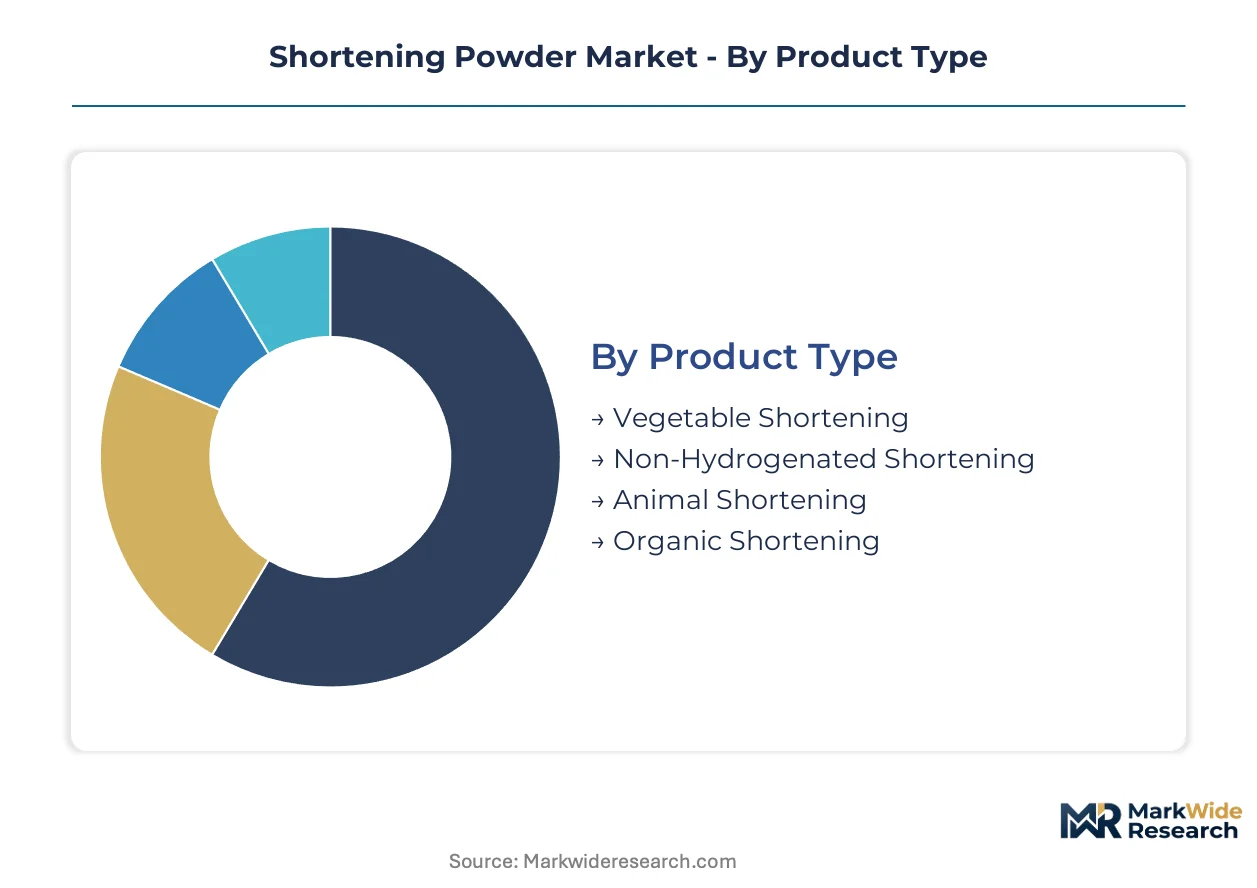
Shortening powder formulation varies sharply by application requirements, with industrial bakeries driving specifications that cascade through supplier portfolios. Procurement patterns cluster around fat content thresholds and dispersibility standards that determine equipment compatibility.
Product Type:
Reformulation cycles are compressing as trans-fat elimination mandates force bakeries to replace hydrogenated bases without sacrificing functionality.
- Vegetable Shortening:Palm oil and soybean oil fractions dominate this category, with spray-dried formats achieving 50-80% fat loading on maltodextrin carriers. Indonesian industrial bakeries account for concentrated procurement volumes due to integrated palm oil processing infrastructure and regional distribution networks.
- Non-Hydrogenated Shortening:Interesterified palm oil or fully hydrogenated alternatives eliminate trans-fat content while maintaining plasticity ranges. FDA and EFSA compliance deadlines are accelerating bakery procurement shifts toward this segment across North American and European manufacturing facilities.
- Animal Shortening:Tallow and lard-based powders serve niche applications requiring specific crystallization behavior.
- Organic Shortening:Certified organic palm or coconut oil bases command premium positioning in European artisanal channels.
Vegetable Shortening sits at the top of the volume ranking, with Non-Hydrogenated Shortening climbing the fastest.
End User:
Customer scale determines specification granularity, with multinational chains imposing centralized standards that reshape supplier priorities.
- Bakery:Industrial bread, pastry, and biscuit manufacturers require precise fat incorporation via pneumatic dosing systems. Malaysian and Thai facilities are automating mixing lines at accelerating rates, generating demand for powders with Hausner ratios below 1.25 and consistent particle size distribution.
- Confectionery:Chocolate compound and coating applications demand narrow melting point ranges and bloom resistance.
- Food Service:Central kitchens and frozen dough operations prioritize shelf stability and ambient storage compatibility.
- Households:Retail-format powders in resealable pouches serve home baking segments with convenience positioning.
Bakery commands the dominant revenue position, while Food Service is expanding most quickly as chain restaurant centralization spreads.
Form:
Material handling infrastructure dictates format selection, with powder flow properties determining equipment compatibility thresholds.
- Powdered:Spray-dried or plated fat systems achieve free-flowing characteristics for automated conveying. Southeast Asian industrial bakeries favor this format where temperature-controlled liquid handling infrastructure is absent or unreliable.
- Granulated:Agglomerated particles improve dissolution rates in high-moisture doughs.
- Liquid:Fluid shortenings with oxidative stability additives compete in facilities with heated storage tanks.
- Solid:Block and flake formats persist in small-scale operations with manual cutting protocols.
Powdered leads volume rankings, though Liquid formats are gaining share fastest in newly automated facilities with climate-controlled infrastructure.
Packaging Type:
Supply chain configuration and end-user scale determine packaging economics, with bulk formats dominating industrial procurement.
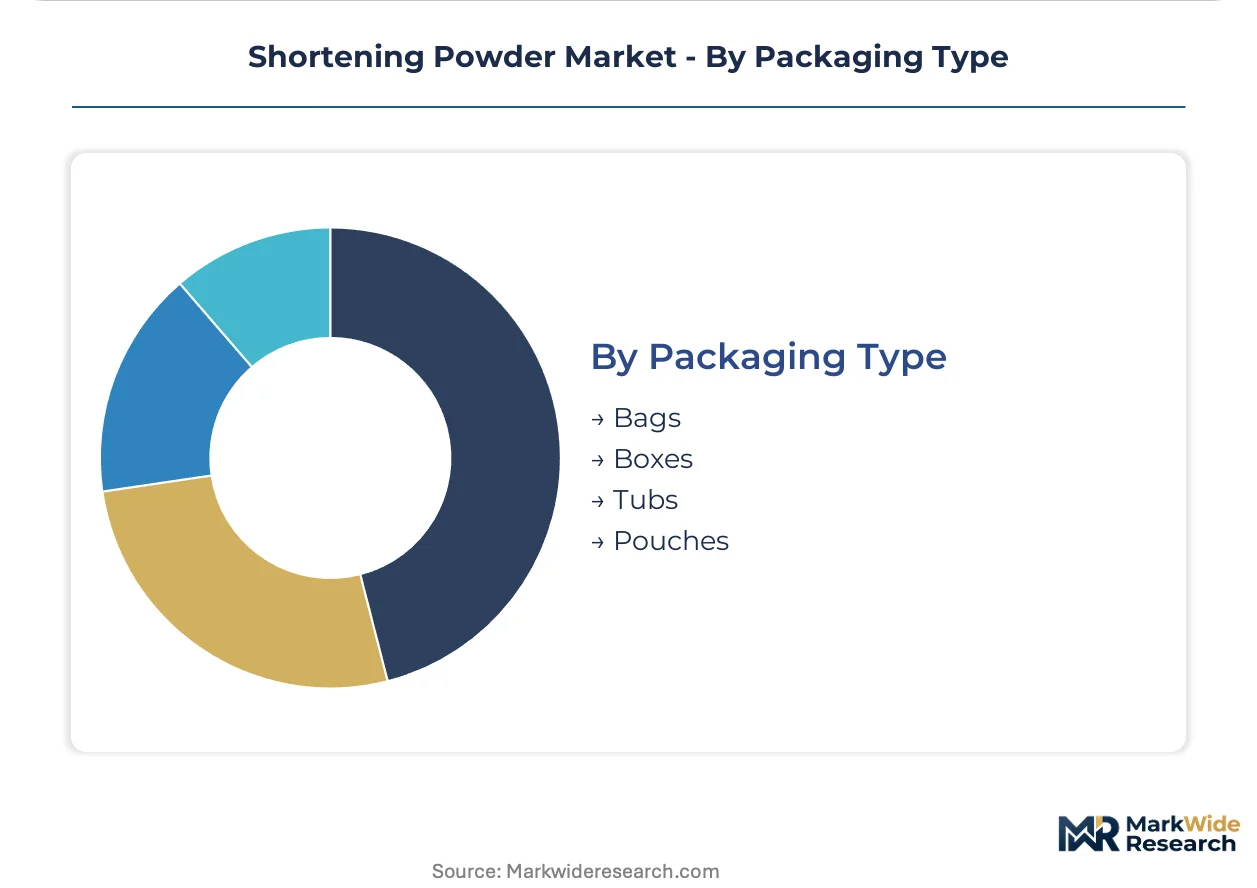
- Bags:Multi-wall paper or woven polypropylene sacks handle 10-25kg industrial shipments. Vietnamese and Indonesian distributors favor bagged formats for bakery consolidation points serving fragmented downstream networks.
- Boxes:Corrugated containers with inner liners protect against moisture ingress in humid climates.
- Tubs:Rigid plastic containers serve food service operators requiring portion-control access.
- Pouches:Flexible laminate structures with reseal features target household and small commercial users.
Bags capture the highest shipment volumes, with Pouches showing the steepest expansion trajectory as retail channel penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting shortening powder production toward jurisdictions with lower compliance costs and integrated feedstock access, as WHO trans-fat mandates reshape manufacturing economics across competing supply basins.
Indonesia
Industrial bakery automation and palm oil processing infrastructure concentration drive procurement volumes. FSSAI-equivalent national standards on trans-fat labeling are tightening formulation requirements for export-bound production. Surabaya and Medan host expanding fractionation facilities serving regional food service chains.
Malaysia
Captive plantation access and downstream oleochemical capabilities anchor cost-competitive powder manufacturing. BIS-aligned quality specifications govern product standards for Indian market exports. Port Klang and Pasir Gudang industrial zones concentrate spray-drying capacity for pneumatic conveying compatibility.
United States
FDA trans-fat regulations compel reformulation across industrial bakery operations toward interesterified alternatives. EPA environmental compliance adds processing cost layers that disadvantage non-integrated producers. Chicago and Minneapolis-St. Paul metropolitan areas cluster automated mixing line deployments demanding precise powder flow properties.
Germany
EFSA nutrient profiling standards constrain permissible saturated fat ratios in finished bakery applications. REACH chemical registration requirements govern emulsifier additive approvals. Hamburg and Frankfurt-Rhine-Main logistics corridors consolidate procurement for pan-European distribution networks.
India
Production-linked incentive schemes for food processing support domestic capacity expansion against import tariff barriers. FSSAI labeling mandates accelerate reformulation certification timelines. Maharashtra and Gujarat industrial corridors attract shortening powder manufacturing investments targeting bakery automation growth.
Shortening Powder Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty emulsifier convergence and clean-label positioning. The vendor base stratifies across integrated plantation holders, toll-processing specialists, and regional distributors with formulation capabilities. Three archetypes dominate: captive feedstock operators leveraging upstream oilseed control, technology licensors monetizing spray-drying equipment expertise, and brand aggregators consolidating fragmented bakery supply channels. Capacity expansion and strategic partnerships represent the primary competitive vectors, with enzymatic interesterification licensing agreements displacing legacy hydrogenation asset bases.
Within the integrated plantation tier, IOI Corporation Berhad and Wilmar International Limited exemplify feedstock-advantaged positioning through Malaysian and Indonesian palm oil infrastructure concentration. AAK AB occupies a specialty emulsifier niche, representing technology-differentiated alternatives to commodity powder formats. These three anchors illustrate the structural divergence between upstream-integrated and formulation-specialized competitive strategies.
| Leading Market Players |
|---|
| Archer Daniels Midland Company (ADM) |
| Cargill, Incorporated |
| Fuji Oil Holdings Inc |
| IOI Corporation Berhad |
| Wilmar International Limited |
| AAK AB |
| Bunge Limited |
| Mewah International Inc. |
| Manildra Group |
| Others |
Value Network & Pricing Analysis
Spray-drying technician concentrations in Malaysia's Port Klang corridor and Indonesia's Surabaya industrial zone generate labor-cost differentials that widen pricing-tier spreads between premium emulsifier-blended powders and economy-grade palm-oil bases.
Pricing Analysis
Distributor margin layers in Southeast Asian shortening powder markets absorb 12-18 percentage points between ex-factory and end-user pricing, with direct-to-OEM contracts commanding steepest discounts for multinational bakery chains. Three-tier pricing structure across premium, standard, and economy levels separates enzyme-interesterified specialty formulations from commodity palm fractions and tallow-based alternatives. Pricing pressure stems from crude palm oil volatility in Malaysian and Indonesian supply basins, compressing margin structures for non-integrated processors. Industrial bakeries with automated dosing systems exhibit lowest price sensitivity due to formulation lock-in costs, while fragmented food service distributors in Vietnam and Philippines face acute margin pressure from substitute fluid shortening competition.
Supply Chain Analysis
Certification gating through FDA trans-fat compliance, EFSA nutrient profiling, and FSSAI labeling mandates restricts market access to processors with validated analytical laboratories and documented fatty acid profiling capabilities. Geographic supply concentration centers on Malaysia, Indonesia, and India, with Malaysian oleochemical corridors feeding Indian export demand through BIS-aligned quality specifications. Raw material dependencies span crude palm oil from Southeast Asian plantations, soybean oil from Argentine and Brazilian crush operations, and specialty emulsifiers from European lecithin processors. Supply chain risk manifests in single-source vulnerability for enzymatic interesterification catalysts, where limited global suppliers constrain non-hydrogenated conversion scale-up. Distribution runs through consolidated multinational food service procurement hubs in Singapore, displacing fragmented national distributor networks across Indonesia and Philippines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortening powder markets function as a geographic-arbitrage play where Malaysian plantation-advantaged producers capture margin premiums against Indian manufacturers facing 15-20% import tariff barriers on finished powder formulations.
For Market Incumbents: Anchor feedstock security through backward integration into Indonesian palm oil fractionation capacity or long-term offtake agreements with Surabaya-based processors, defending against emerging toll-processing specialists with enzymatic reactor licensing. Deepen certification investment in FDA and EFSA compliance documentation to maintain specification-setting authority with multinational bakery chains consolidating procurement through Singapore regional headquarters. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Vietnamese industrial bakery automation creates whitespace for mid-tier powder formats with improved cold-water dispersibility, targeting frozen dough and par-baked operations expanding through foreign direct investment. Enter through clean-label emulsifier convergence positioning, integrating enzyme-modified lecithin systems to capture European artisanal bakery channel premiums without competing directly on plantation scale. For Investors and Strategic Acquirers: Integrated palm oil processors with downstream spray-drying capabilities are the most active acquirer in this space, consolidating toll-processing specialists to secure enzymatic interesterification technology and regional distribution footprints. Target acquisition archetypes include mid-tier Malaysian oleochemical operators with captive plantation access but underutilized powder capacity, monitoring WHO trans-fat elimination implementation timelines as the critical inflection signal for reformulation-driven capacity utilization shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Interesterification Licensing | Enables non-hydrogenated formulation conversion without capital-intensive reactor deployment by mid-tier processors. |
| Backward Integration into Palm Fractionation | Secures cost-competitive feedstock access against crude palm oil price volatility in Malaysian supply basins. |
| Clean-Label Emulsifier Convergence | Opens premium positioning in EFSA-regulated European channels through enzyme-modified lecithin and natural antioxidant systems. |
| Regional Distribution Consolidation | Captures procurement centralization benefits as multinational food service chains standardize specifications through Singapore hubs. |
| Automated Dosing System Compatibility Investment | Aligns powder flow properties with pneumatic conveying requirements in Malaysian and Thai industrial bakery automation. |
Research Methodology
Multiple input streams — technical discussions with spray-drying equipment manufacturers, procurement interviews at Indonesian and Malaysian industrial bakeries, and regulatory filings with FDA, EFSA, and FSSAI — were reconciled through bottom-up capacity modeling and top-down demand validation. Primary interviews engaged plant managers at oleochemical processing facilities, procurement leads at multinational food service chains, distribution channel partners in Vietnam and Philippines, and technical R&D directors at emulsifier suppliers. Secondary sources included customs and trade data from ASEAN and Indian customs authorities, BIS and FSSAI quality specification documents, SEC 10-K filings from listed plantation operators, and industry association reports from Malaysian Palm Oil Council and Indonesian Palm Oil Association.
Historical capacity utilization and procurement volume patterns were cross-referenced against panel input from industry participants to construct segment-level projections across the analysis window. Segmentation dimensions modeled include formulation type (vegetable, non-hydrogenated, animal, organic), end-user scale (industrial bakery, confectionery, food service, household), and physical form (powdered, granulated, liquid, solid). CAGRs were derived from elasticity-adjusted demand curves incorporating bakery automation penetration rates and regulatory compliance deadline clustering. Industry-specific forecast inputs encompassed palm oil fractionation capacity expansion timelines and enzymatic interesterification technology licensing trajectories.
The model assumes a particular technology adoption path for enzymatic interesterification; alternative pathways for chemical interesterification or fully hydrogenated alternatives would alter the outlook for non-hydrogenated shortening powder penetration rates. Forecasts reflect assumptions regarding WHO trans-fat elimination implementation timelines, crude palm oil price band stability, and Southeast Asian industrial bakery automation investment continuity. A model refresh is warranted upon material change in FDA or EFSA regulatory stringency, major plantation consolidation events, or breakthrough dispersibility technology enabling cold-water hydration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Almond Flour Market
Ingredients
Asia-Pacific Bakery Ingredients Market
Ingredients
Carrot Fiber Market
Ingredients
Protein Hydrolysate Market
Ingredients
Seaweed Derivatives Market
Ingredients
Passion Fruit Powder Market
Ingredients
Omega Ingredients Market
Ingredients
France Protein Market
Ingredients
Mexico Sodium Reduction Ingredients Market
Ingredients
Freeze-Dried Vegetable Powder Market
Ingredients
Wheat Gluten Market
Ingredients
Campesterol Market
Ingredients
Philippines Edible Oils & Fats Market
Ingredients
Licorice Root Market
Ingredients
North America Corn Starch Market
Ingredients
Africa Sodium Reduction Ingredients Market