
 Short Sea Shipping Market | 2026-2036
Short Sea Shipping Market Size, Share, and Industry Trends Forecast 2026-2036
Short Sea Shipping Market Insights
ISO 14001 environmental management certification is collapsing as a baseline qualifier for short sea operators bidding on European Union public procurement contracts. Maersk leverages its integrated logistics platform to control feeder vessel deployment across North European hubs. CMA CGM anchors its short sea portfolio through dedicated Mediterranean services linking Spanish, Italian, and Greek terminals.
Short sea shipping denotes maritime cargo and passenger transport over relatively limited distances, typically operating within a single continent or between proximate coastlines using vessels under 15,000 TEU capacity with draft restrictions suited to secondary ports. Its primary commercial purpose centers on extending port hinterlands, relieving landside infrastructure congestion, and offering lower per-ton-kilometer emissions than road or rail alternatives for suitable cargo categories. Containerships dominate the vessel type segment due to standardized intermodal compatibility and high schedule reliability on dense coastal routes. Ferries represent the fastest-expanding category as operators retrofit ro-pax vessels for battery-hybrid propulsion to meet coastal emissions controls.
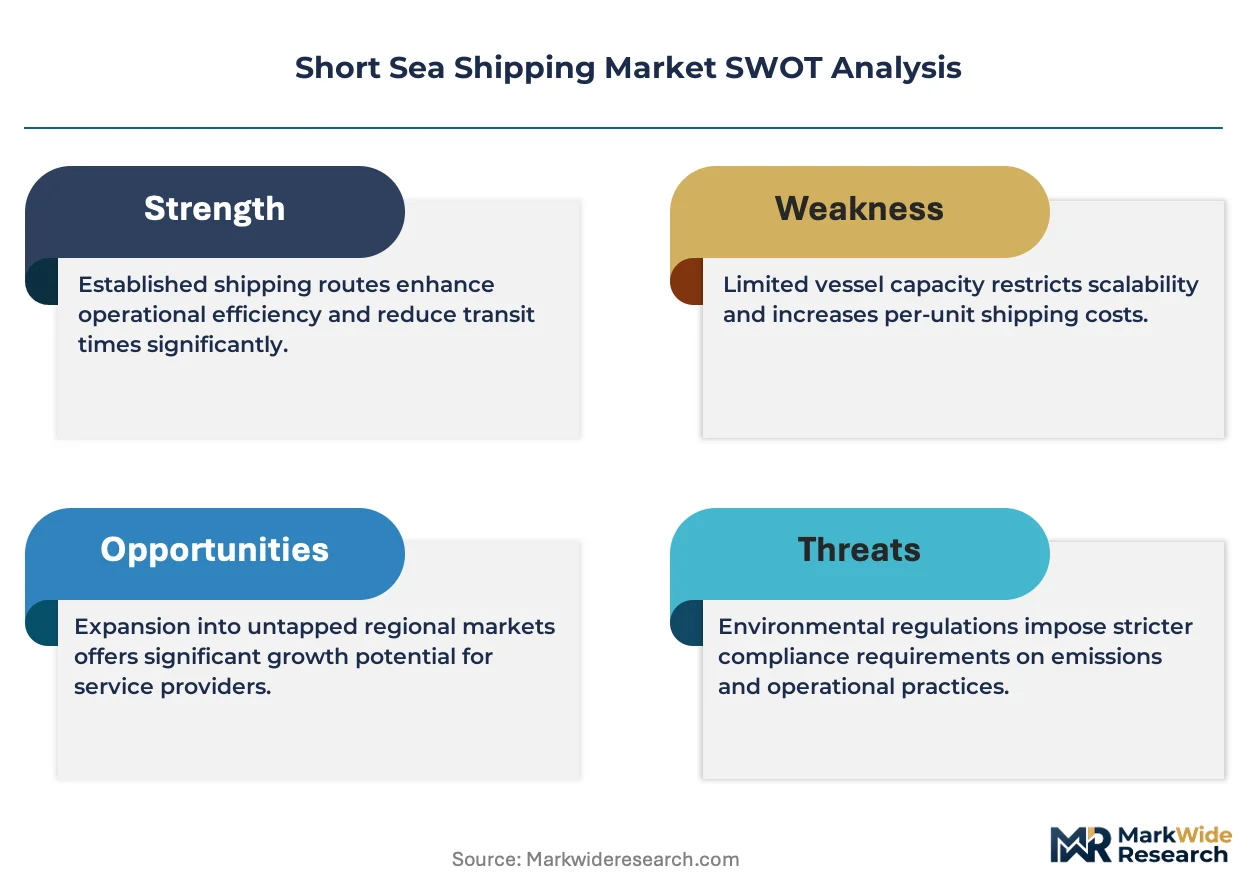
The European Maritime Safety Agency enforces sulfur emission control area standards that dictate fuel quality and scrubber investments for vessels calling EU ports. The International Maritime Organization's Energy Efficiency Existing Ship Index is forcing retrofit decisions on older short sea fleets operating intra-European routes. China's Maritime Safety Administration applies parallel domestic emissions standards for coastal shipping zones. Stakeholders must weigh accelerated fleet renewal costs against the regulatory risk of trading restrictions on non-compliant vessels.
Market Dynamics
The EU Green Deal maritime amendments are compressing fleet renewal timelines while Baltic Sea corridor congestion forces modal shift toward coastal feeders. Operators face simultaneous pressure to decarbonize vessel portfolios and maintain schedule reliability on dense intra-European routes.
Growth Catalysts
- Baltic Sea corridor demand:German, Polish, and Swedish port clusters are channeling automotive and containerized cargo onto feeder networks to bypass saturated road infrastructure.
- EU sulfur emission control areas:The European Maritime Safety Agency's fuel quality mandates are accelerating scrubber retrofits and LNG conversions among compliant operators.
- Battery-hybrid propulsion:Ro-pax ferry operators are retrofitting vessels for electric-diesel hybrid systems to satisfy coastal emissions controls and access port incentive schemes.
Market Restraints
- Marine fuel price volatility:Low-sulfur fuel oil and LNG bunker costs swing with crude benchmarks, compressing margin visibility on fixed-rate contracts.
- Secondary port draft limitations:Vessels over 15,000 TEU face physical exclusion from shallow-hinterland terminals, fragmenting deployment economics.
- Road freight substitution resilience:Trucking retains door-to-door flexibility for time-sensitive cargo, limiting short sea's addressable share in sub-300km corridors.
Strategic Opportunities
- Polish port expansion:Gdansk and Gdynia terminal investments are creating new feeder relay capacity for Asia-Europe mainline connections.
- IMO Energy Efficiency Existing Ship Index retrofit incentives:Compliant vessels gain preferential berthing and reduced port dues at EU terminals.
- Digital freight platform integration:Real-time cargo matching and dynamic scheduling are collapsing empty-leg ratios on irregular routes.
Industry Challenges
- Marine engineering talent scarcity:Dual-fuel and battery system technicians are concentrated among Northern European shipyards, constraining fleet expansion timelines.
- ISO 14001 certification escalation:Environmental management documentation requirements for EU public procurement now demand third-party verification cycles exceeding 18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Short Sea Shipping Market |
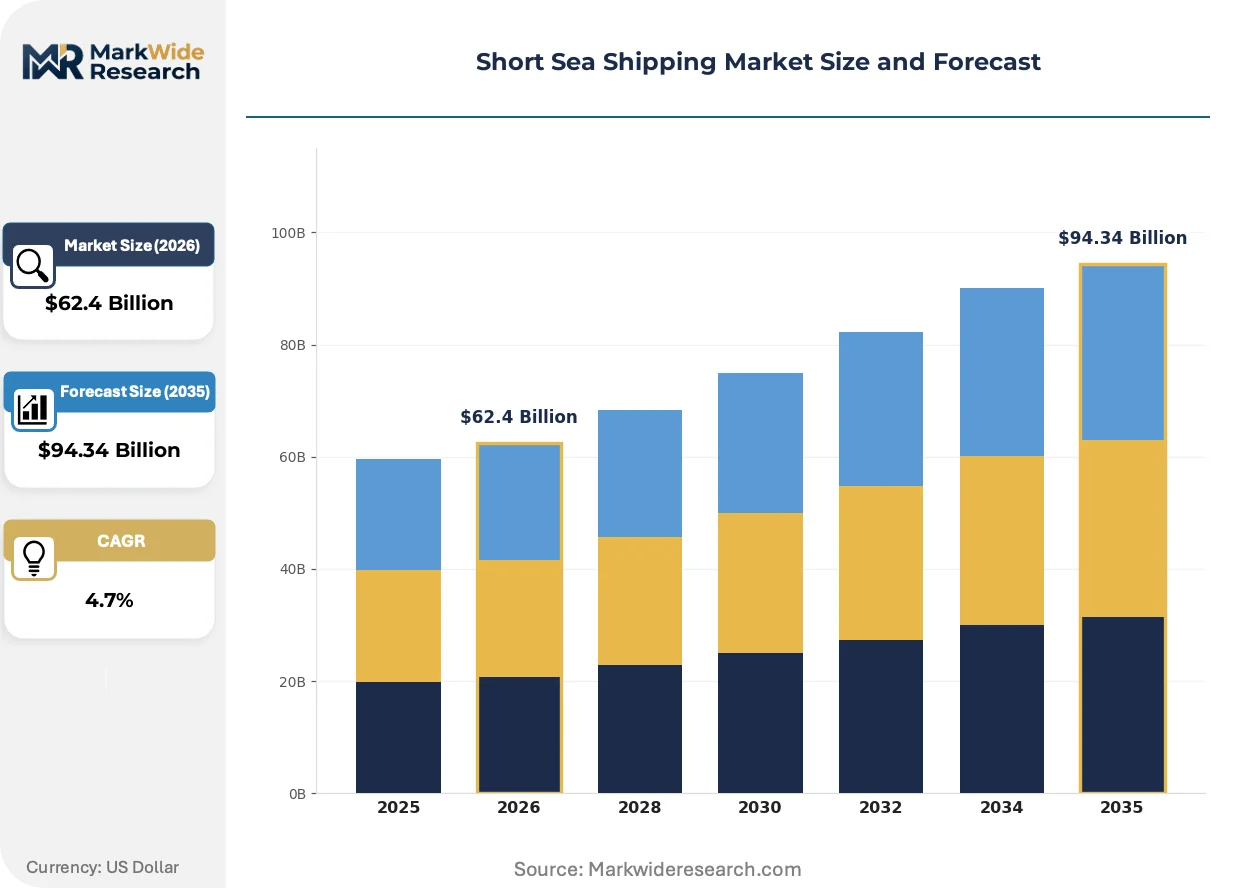
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $94.34 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transport Services, Freight Forwarding, Warehousing, Logistics Vessel Type: Containerships, Ferries, Bulk Carriers, General Cargo Trade Route: Inland Waterways, Coastal Routes, Transnational Connections, Short Haul Customer Segment: Manufacturers, Retailers, Importers, Exporters |
| Companies Covered | Mediterranean Shipping Company (MSC), Maersk, CMA CGM, COSCO Shipping Lines, Hapag-Lloyd, Evergreen Marine Corporation, Ocean Network Express (ONE), SITC International, Regional Container Lines (RCL), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Short Sea Shipping Market Trends and Innovations
Propulsion technology divergence and regulatory compliance automation are fragmenting competitive advantage sources across European short sea networks. Vessel operators must now integrate hardware retrofit decisions with software-enabled operational optimization.
Modular battery container systems are decomposing traditional shipyard retrofit timelines for ro-pax fleets. Stena Line and Color Line are slotting containerized lithium-ion packs into existing deck structures during routine maintenance windows. This plug-in architecture is decomposing the capex barrier that previously gated electrification to newbuild programs.
EU Green Deal maritime amendments are tightening emissions standards for vessels operating within member-state waters. The European Maritime Safety Agency now mandates real-time emissions monitoring and verified fuel chain-of-custody documentation. Short sea operators serving Spanish, Italian, and Greek terminals are prioritizing scrubber installations over LNG conversions to meet interim compliance deadlines.
Shippers are consolidating procurement around integrated logistics platforms that bundle feeder vessel slots with terminal handling and landside distribution. Automotive manufacturers in the German hinterland are abandoning fragmented carrier relationships for single-contract coastal network access. This concentration is most visible along the Hamburg-Rotterdam-Antwerp corridor where volume commitments now lock in multi-year slot agreements.
Short Sea Shipping Market Segmentation
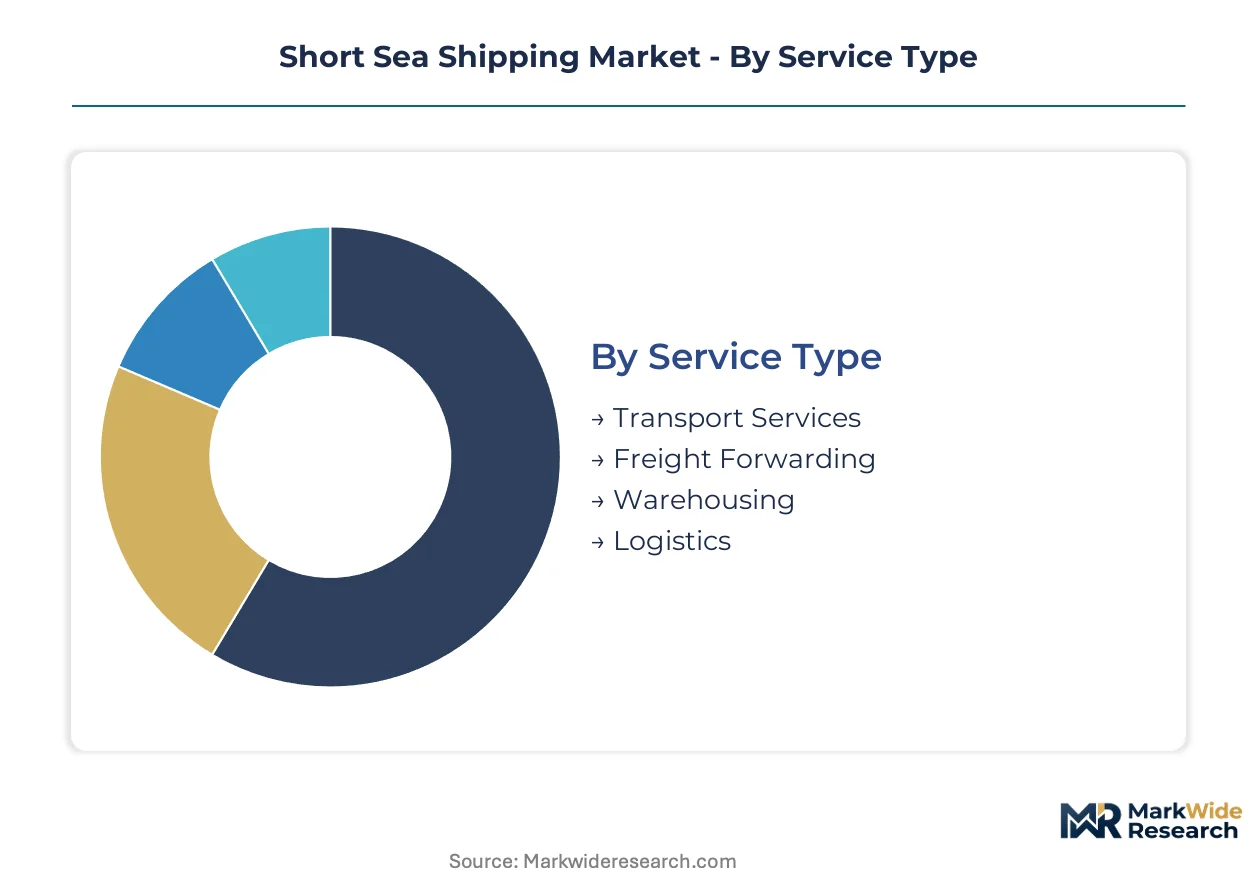
Short sea shipping operators configure service portfolios around vessel economics, route density, and cargo handling capabilities. Segmentation reveals where capital deployment yields differential returns across service tiers and asset categories.
Service Type:
Margins concentrate in integrated logistics bundles that capture value across multiple touchpoints rather than pure transport plays.
- Transport Services:Core vessel operations moving cargo between ports on fixed schedules or voyage charters. Automotive manufacturers along the Hamburg-Rotterdam corridor are locking into multi-year slot agreements to secure feeder capacity.
- Freight Forwarding:Documentation, customs clearance, and cargo consolidation services that bridge maritime and landside legs. Demand is concentrating among shippers seeking single-contract coastal network access rather than fragmented carrier relationships.
- Warehousing:Short-term storage and inventory positioning at port-adjacent facilities. Polish terminal investments at Gdansk and Gdynia are expanding bonded warehouse capacity for Asia-Europe relay cargo.
- Logistics:End-to-end supply chain orchestration bundling feeder slots with terminal handling and distribution. EU Green Deal compliance documentation requirements are pushing procurement toward integrated platforms with verified environmental credentials.
The dominant share belongs to Transport Services, while Logistics is closing the gap fastest as shippers consolidate procurement around bundled offerings.
Vessel Type:
Asset deployment economics hinge on draft restrictions, fuel flexibility, and intermodal compatibility across secondary port networks.
- Containerships:Standardized box vessels under 15,000 TEU optimized for dense coastal routes and crane-equipped terminals. German, Polish, and Swedish port clusters are channeling containerized cargo onto these feeder networks to bypass saturated road infrastructure.
- Ferries:Ro-pax vessels carrying both passengers and wheeled freight, now retrofitting for battery-hybrid propulsion. Stena Line and Color Line are slotting containerized lithium-ion packs into existing deck structures to satisfy coastal emissions controls.
- Bulk Carriers:Single-deck vessels for unpackaged dry cargo like grain, coal, and aggregates. Draft limitations at shallow-hinterland terminals constrain deployment economics for larger hulls.
- General Cargo:Multi-purpose vessels with flexible loading configurations for breakbulk and project cargo. Secondary port access and irregular scheduling produce fragmented utilization rates.
Containerships command the largest fleet investment, though Ferries are expanding most quickly through electrification retrofit programs.
Trade Route:
Route selection determines regulatory exposure, with EU sulfur emission control areas dictating fuel technology choices.
- Inland Waterways:Barge and small-vessel operations on rivers and canals connecting to coastal hubs. The European Maritime Safety Agency's fuel quality mandates are accelerating scrubber retrofits among compliant operators.
- Coastal Routes:Maritime corridors linking ports within the same member state or adjacent territories. Battery-hybrid propulsion retrofits are concentrating here to access port incentive schemes.
- Transnational Connections:Cross-border short sea links between EU member states. Real-time emissions monitoring and verified fuel chain-of-custody documentation are now mandatory requirements.
- Short Haul:Sub-300km maritime legs competing directly with trucking for time-sensitive cargo. Road freight substitution resilience limits addressable share despite lower per-ton-kilometer emissions.
Coastal Routes generate the densest traffic volumes, while Transnational Connections are gaining regulatory attention fastest under EU Green Deal maritime amendments.
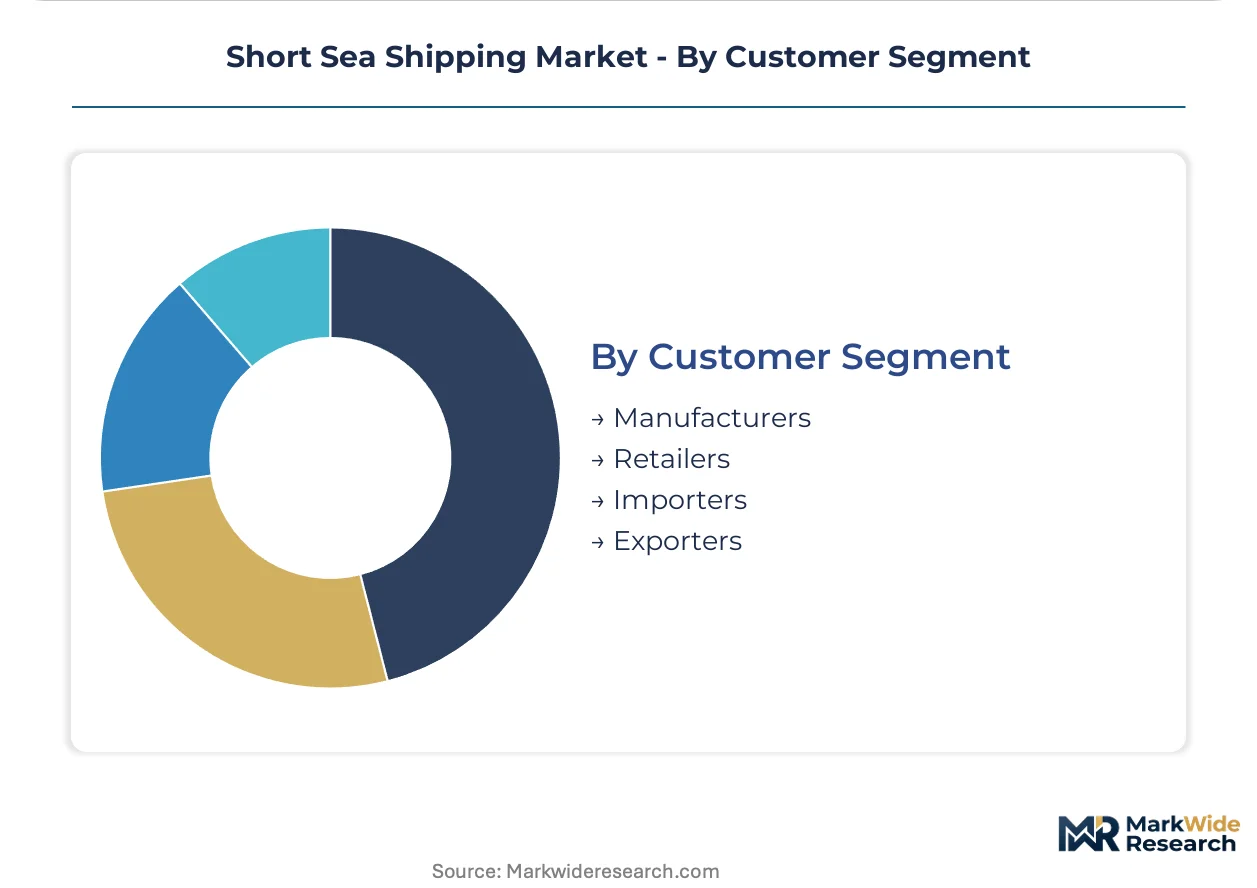
Customer Segment:
Procurement sophistication varies sharply, with automotive OEMs driving standardization of environmental compliance documentation.
- Manufacturers:Industrial producers moving raw materials and finished goods through coastal networks. ISO 14001 certification escalation is forcing third-party verification cycles exceeding 18 months for EU public procurement eligibility.
- Retailers:Consumer goods distributors requiring schedule reliability for inventory replenishment. Digital freight platform integration is collapsing empty-leg ratios on their irregular route patterns.
- Importers:Entities receiving goods from overseas suppliers through feeder relay connections. Polish port expansion is creating new capacity for Asia-Europe mainline handoffs.
- Exporters:Shippers dispatching products to continental European markets via short sea legs. IMO Energy Efficiency Existing Ship Index retrofit incentives are steering carrier selection toward compliant vessel operators.
Manufacturers anchor the revenue base, while Retailers are shifting procurement patterns fastest toward integrated logistics platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and integrated logistics buyers concentrate procurement along coastal corridors where EU Green Deal compliance and feeder network density intersect. Demand clusters around port-adjacent industrial zones in Germany, Poland, and Sweden. Regulatory enforcement from the European Maritime Safety Agency is reshaping carrier deployment decisions across these corridors.
Germany
Automotive manufacturers along the Hamburg-Rotterdam-Antwerp corridor are locking into multi-year slot agreements to secure feeder capacity. The EU Green Deal maritime amendments mandate real-time emissions monitoring for vessels calling German ports. The Port of Hamburg anchors North European relay traffic, with terminal operators expanding crane-equipped berths for sub-15,000 TEU vessels.
Poland
Asia-Europe mainline connections are channeling containerized cargo through Gdansk and Gdynia to bypass saturated road infrastructure. The European Maritime Safety Agency's fuel quality mandates are accelerating scrubber retrofits among Polish-flagged operators. Terminal investments at Gdansk are creating new bonded warehouse capacity for relay cargo destined for German and Czech hinterlands.
Sweden
Battery-hybrid propulsion retrofits are concentrating among ro-pax operators serving Stockholm and Gothenburg corridors to access port incentive schemes. The EU sulfur emission control area standards dictate fuel technology choices for vessels operating Swedish coastal routes. Stena Line's deployment decisions from Gothenburg exemplify the shift toward plug-in electrification architectures.
Netherlands
Rotterdam's position as a North European hub is compressing feeder vessel turnaround times to maintain schedule reliability on dense intra-European routes. The European Maritime Safety Agency enforces chain-of-custody documentation requirements that favor integrated logistics platforms with verified environmental credentials. Maersk leverages its integrated logistics platform to control feeder deployment across Rotterdam-adjacent terminals.
Italy
CMA CGM anchors its short sea portfolio through dedicated Mediterranean services linking Spanish, Italian, and Greek terminals. The EU Green Deal maritime amendments are tightening emissions standards for vessels operating within Italian coastal waters. Port authorities at Genoa and La Spezia are prioritizing scrubber-compliant vessels for preferential berthing allocations.
Short Sea Shipping Market Competitive Landscape
Player mix skews toward diversified container line operators with integrated logistics capabilities rather than pure-play short sea specialists. Consolidation pressure from EU environmental compliance costs is squeezing mid-tier carriers without captive cargo bases. Two strategic archetypes dominate: global container lines leveraging feeder networks as hinterland extensions, and regional ro-pax operators retrofitting for coastal emissions controls. Capacity expansion and scrubber retrofit partnerships represent the dominant competitive moves across both archetypes.
Within the diversified container line tier, Mediterranean Shipping Company and Maersk exemplify operators controlling feeder deployment through integrated logistics platforms. CMA CGM occupies a distinct position through dedicated Mediterranean short sea services linking peninsular terminals. These three companies represent how global scale and regional specialization are converging under EU regulatory pressure.
| Leading Market Players |
|---|
| Mediterranean Shipping Company (MSC) |
| Maersk |
| CMA CGM |
| COSCO Shipping Lines |
| Hapag-Lloyd |
| Evergreen Marine Corporation |
| Ocean Network Express (ONE) |
| SITC International |
| Regional Container Lines (RCL) |
| Others |
Pricing and Supply Chain Analysis
Ninety-day scrubber installation lead times at Northern European shipyards concentrate pricing power among compliant operators while compressing margin visibility for carriers locked into fixed-rate contracts. This inventory-cycle observation shapes how vessel operators index fuel costs and how charterers negotiate slot agreements across Baltic and Mediterranean corridors.
Pricing Analysis
Cost-plus contracts with low-sulfur fuel oil indexation dominate short sea procurement, with premium-mid-economy pricing differentiation separating ISO 14001-certified operators from baseline-compliant carriers. Price differentiation rests on verified emissions documentation and scrubber installation status, with automotive OEMs showing least price sensitivity due to multi-year volume commitments. Pricing pressure stems from marine fuel volatility, while fragmented freight forwarders face greatest margin compression on spot-market exposure.
Supply Chain Analysis
Inventory buffers for dual-fuel engine components stretch 45-60 days at German and South Korean shipyards, constraining fleet expansion timelines for operators seeking LNG conversion slots. Supply concentrates in Germany, South Korea, and China for marine propulsion systems, with specialized battery pack assembly feeding from Japanese and South Korean cell manufacturers. Single-source vulnerability runs through concentrated marine engineering talent pools, while distribution flows through integrated logistics platforms controlling feeder vessel deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Short sea shipping traces a cyclical recovery anchored to EU Green Deal fleet renewal mandates, with vessel replacement cycles compressing as emissions deadlines approach.
For Market Incumbents: Shield market position through scrubber retrofit partnerships with Northern European shipyards and backward integration into terminal handling assets. The ISO 14001 certification escalation threatens mid-tier carriers lacking documentation resources, while captive berth access at Rotterdam and Hamburg anchors schedule reliability.
For New Entrants and Emerging Players: Differentiate on battery-hybrid retrofit speed for ro-pax corridors serving Stockholm and Gothenburg, where port incentive schemes reward early electrification. Polish port expansion at Gdansk offers the most penetrable geography, with Asia-Europe relay cargo seeking alternative feeders to saturated Hamburg-Rotterdam lanes.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because EU sulfur emission control area standards will permanently restructure fleet economics toward scrubber and LNG-equipped vessels. Acquisition targets cluster around regional ro-pax operators with electrification-ready architectures and established coastal route licenses. The signal to watch is IMO Energy Efficiency Existing Ship Index enforcement intensity at Mediterranean terminals.
| Strategic Initiative | Industry Significance |
|---|---|
| Scrubber Retrofit Partnership | Secures shipyard capacity ahead of EU Green Deal compliance deadlines for Baltic operators. |
| Terminal Handling Integration | Captures value across vessel and landside touchpoints along Hamburg-Rotterdam corridor. |
| Battery-Hybrid Conversion Program | Unlocks port incentive schemes at Stockholm and Gothenburg for ro-pax fleets. |
| Digital Freight Platform Development | Collapses empty-leg ratios through real-time cargo matching on irregular coastal routes. |
| Polish Port Capacity Investment | Creates relay infrastructure for Asia-Europe mainline connections bypassing congested hubs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across vessel chartering, terminal operations, and automotive logistics functions. Primary interviews captured fleet managers at German and Swedish ro-pax operators, procurement leads at Polish terminal developments, and sustainability officers at integrated logistics platforms. Secondary validation drew from European Maritime Safety Agency enforcement notices, EU Green Deal amendment texts, and port authority berth allocation records. Bottom-up capacity deployment models were triangulated against top-down trade flow estimates.
Across the analysis window, projections incorporated vessel type segmentation by propulsion architecture, service tier by integration depth, and trade route by regulatory exposure. CAGRs were derived from fleet renewal schedules indexed to IMO Energy Efficiency Existing Ship Index thresholds and EU sulfur emission control area expansion timelines. Modeling incorporated scrubber retrofit cost curves, LNG bunkering infrastructure buildout rates, and battery-hybrid technology cost-down trajectories.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or alternative fuel infrastructure delays would require recalibration. Forecasts reflect documented assumptions around compliance deadlines and carrier capital allocation priorities. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive & Transportation
China Cold Chain Logistics Market
Automotive & Transportation
Automotive Clear Coat Paint Market
Automotive & Transportation
Automotive and Transportation Connector Market
Automotive & Transportation
Europe Bus Market
Automotive & Transportation
Automotive Coolant Aftermarket Market
Automotive & Transportation
Automotive Connecting Rod Market
Automotive & Transportation
Automotive OE Bumper Cover Market
Automotive & Transportation
North America Traffic Signal Recognition Market
Automotive & Transportation
GCC Automotive Connectors Market
Automotive & Transportation
Automotive Solar Film Market
Automotive & Transportation
Vehicle Analytics Market
Automotive & Transportation
North America Ceramic Ball Bearings Market
Automotive & Transportation
Germany Automotive Camera Market
Automotive & Transportation
Marine Outboard Engine Market
Automotive & Transportation
Zonal Vehicle Control Unit Architectures Market
Automotive & Transportation
Windshield Repair Kit Market