
 Shapewear Market | 2026-2036
Shapewear Market Size, Share, and Industry Trends Forecast 2026-2036
Shapewear Market Intelligence
Fragmentation of the customer base across direct-to-consumer online channels is hardening the competitive environment for legacy retail brands. Spanx sustains its market position through established brand equity and broad distribution. In contrast, SKIMS leverages a powerful social media-driven model to capture a digitally native audience. Wacoal specializes in premium offerings through department stores and specialty boutiques, targeting a different consumer demographic.
Shapewear comprises undergarments engineered to temporarily alter the wearer's body shape for aesthetic purposes. These garments utilize high-compression fabrics, typically blends of spandex and nylon, to smooth and contour specific areas like the abdomen, hips, and thighs. Bodysuits and control briefs represent mature product categories, while the plus-size end-user segment is experiencing significant expansion. E-commerce has become the dominant distribution channel, displacing traditional retail stores in volume.
Regulatory oversight primarily concerns material safety and marketing claims, governed by bodies like the US Federal Trade Commission (FTC) and the EU's REACH regulation. These frameworks mandate accurate fiber content labeling and restrict unsubstantiated performance assertions. Future success for brands will depend on balancing the technical demands for compression and shaping with consumer preferences for comfort and sustainable materials.
Market Dynamics
The central force shaping the shapewear market is the convergence of body-positive social movements and material science. This dynamic compels brands to expand sizing inclusivity while simultaneously engineering higher-performance, breathable fabrics for everyday use.
Growth Catalysts
- E-commerce Expansion:Direct-to-consumer channels, amplified by social media, give brands access to a fragmented global customer base and reduce barriers to market entry.
- Fabric Innovation:Advances in spandex and nylon blends are creating lighter, breathable textiles, expanding shapewear's application from formal events to daily wear.
- Plus-Size Demand:A cultural shift toward body positivity creates significant demand for inclusive sizing, opening a large, previously underserved consumer segment.
Market Restraints
- Raw Material Volatility:Price fluctuations in petroleum-derived inputs like spandex and nylon directly impact production costs, compressing manufacturer margins without sufficient hedging.
- Activewear Substitution:Athleisure garments with built-in light compression features present a significant substitution threat, eroding the market for lower-compression shapewear products.
- Marketing Claim Scrutiny:Regulators like the US FTC are increasing oversight of performance assertions, restricting unsubstantiated claims about body modification or health benefits.
Strategic Opportunities
- Sustainable Materials:Developing shapewear from recycled nylon or bio-based spandex can capture environmentally conscious consumers and align with emerging sustainability mandates.
- Medical Applications:A market exists for medical-grade compression garments for post-surgical recovery or lymphatic support, moving beyond purely aesthetic functions.
- Emerging Market Penetration:Rising disposable incomes in Latin America and Southeast Asia present growth opportunities for brands adapting to local sizing and preferences.
Industry Challenges
- Channel Management Complexity:Managing inventory and fulfillment across fragmented direct-to-consumer e-commerce channels requires sophisticated logistics and increases operational costs compared to traditional wholesale.
- Global Compliance Burden:Adhering to disparate chemical safety regulations, such as the EU's REACH and California's Proposition 65, increases testing costs and supply chain complexity for brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shapewear Market |
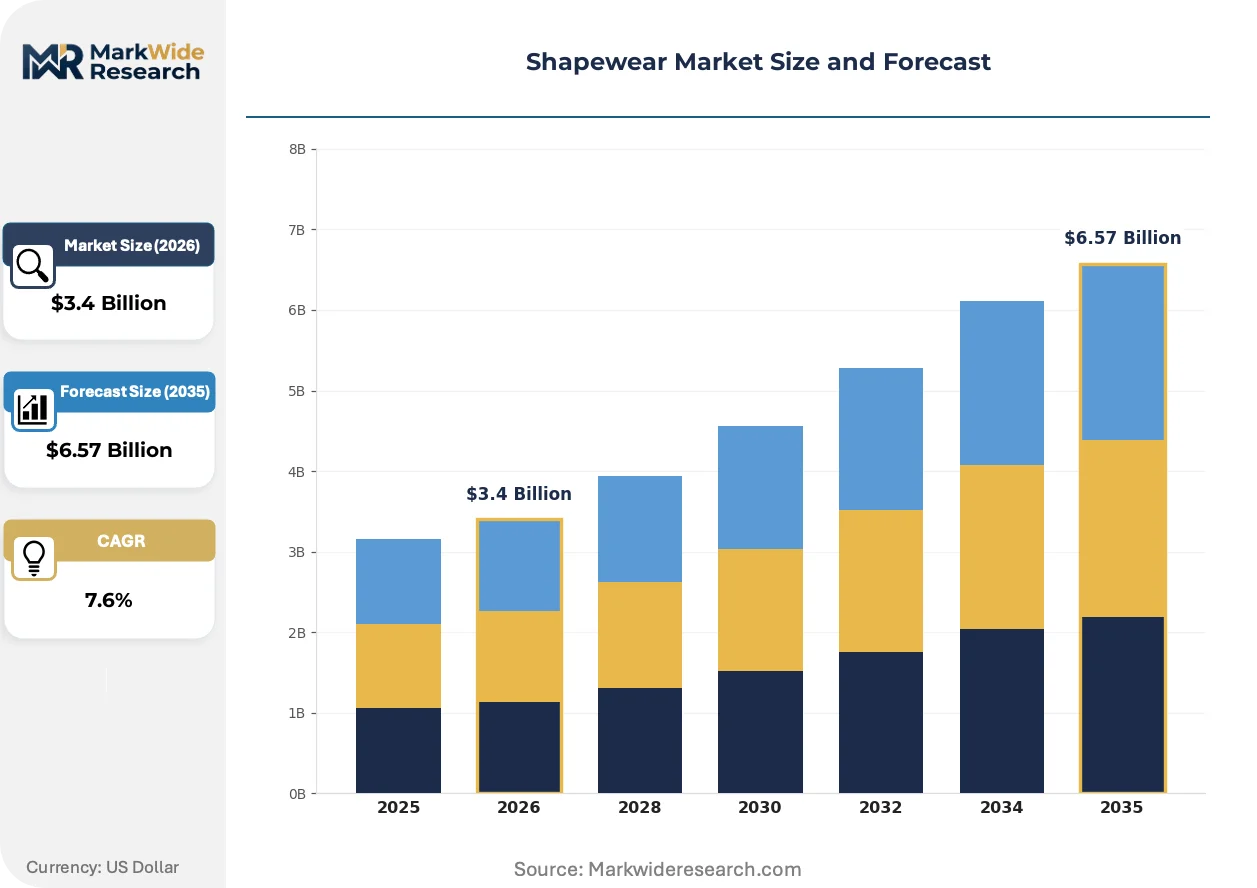
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.57 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bodysuits, Control Briefs, Shaping Camis, Tights End User: Women, Athletes, Maternity, Plus Size Material: Spandex, Nylon, Cotton, Polyester Distribution Channel: E-commerce, Retail Stores, Specialty Shops, Catalogs |
| Companies Covered | Wacoal, Commando, SKIMS, Leonisa, Maidenform, Spanx, Yitty, Triumph International, Honeylove, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shapewear Market Strategic Shifts & Innovations
Product evolution in the shapewear industry is driven by the fusion of aesthetic function with all-day comfort and personal wellness. This shift is redefining consumer expectations and pushing manufacturers toward multifunctional textiles and more inclusive design philosophies.
Micro-encapsulation technology embeds active ingredients like moisturizers or CBD directly into shapewear fabrics. Premium and wellness-focused consumer segments are the primary adopters of this nascent innovation. This development is unifying the separate concepts of aesthetic shaping and active skincare, creating a new 'wearable beauty' product category with higher value propositions.
The EU’s Corporate Sustainability Reporting Directive (CSRD) is forcing greater supply chain transparency. This policy compels manufacturers to disclose the environmental impact of their textile choices, from raw material sourcing to chemical processing. The performance fabric segment, reliant on petroleum-based nylon, faces the most pressure to document its footprint and explore bio-based alternatives.
Consumer behavior is shifting from viewing shapewear as special-occasion attire to integrating it as everyday functional wear. This trend disrupts the traditional, event-based retail sales model in favor of subscription or repeat-purchase cycles common in direct-to-consumer e-commerce. This pattern is most visible in the United States market, amplified by social media.
Shapewear Market Segmentation
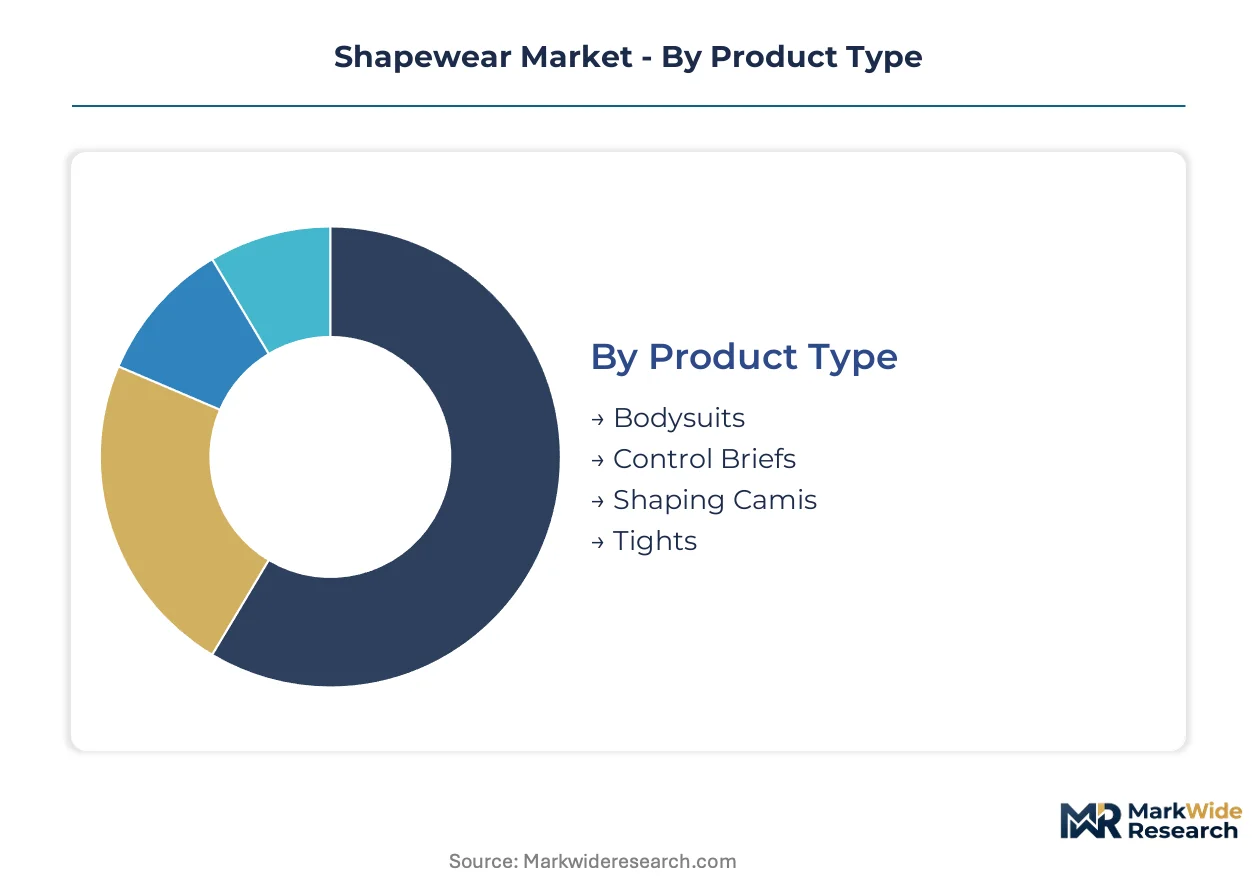
The shapewear market's segmentation provides a critical lens for understanding consumer needs and competitive dynamics. Each category reflects distinct demand patterns and material science applications. Analyzing these segments helps brands tailor product development and distribution strategies effectively.
Product Type:
The upgrade cycle for shapewear often involves consumers seeking more comfortable or versatile garments for daily wear, moving beyond traditional special-occasion pieces.
- Bodysuits:These garments offer full torso compression and smoothing, integrating bra support with lower body shaping. Demand in the United States concentrates on seamless designs that can be layered discreetly under various outfits.
- Control Briefs:Designed to target the abdomen and hips, control briefs utilize high-compression panels to smooth and contour. The plus-size consumer segment drives significant volume for these foundational pieces, prioritizing comfort and effective shaping.
- Shaping Camis:Shaping camisoles provide light to medium compression for the midsection, often worn as a layering piece.
- Tights:Compression tights offer leg and lower body shaping, frequently incorporating features for circulation support or athletic performance.
Bodysuits sits at the top of the volume ranking, with Control Briefs climbing the fastest.
End User:
Customer type differentiation profoundly influences product design and marketing efforts within the shapewear industry, requiring tailored approaches for each demographic.
- Women:This broad category represents the primary consumer base for aesthetic body contouring and smoothing garments. Demand for comfortable, everyday shapewear is particularly strong across various age groups.
- Athletes:Athletes utilize compression garments for muscle support and recovery, often integrating moisture-wicking properties.
- Maternity:Maternity shapewear supports the growing belly and provides back relief for pregnant individuals, emphasizing comfort and adjustability.
- Plus Size:This segment focuses on inclusive sizing and designs that provide effective shaping and support for larger body types. The body positivity movement in Europe and North America significantly drives product innovation here.
The Women segment commands the largest share, while Plus Size is gaining share fastest.
Material:
Material choices dictate the functional performance and comfort profile of shapewear, with manufacturers continually innovating to meet evolving consumer demands for breathability and durability.
- Spandex:Known for its exceptional elasticity and recovery properties, spandex (also known as elastane or Lycra) provides the core compression in most shapewear products. Innovations in fabric blends with high spandex content are expanding its application in performance-focused garments.
- Nylon:Often blended with spandex, nylon offers a smooth texture, durability, and moisture-wicking capabilities, contributing to the garment's overall comfort and longevity. The European market shows a growing preference for recycled nylon options.
- Cotton:Cotton blends offer breathability and softness, often used in less compressive or inner lining layers for comfort.
- Polyester:Polyester provides good moisture management and durability, frequently incorporated into activewear-inspired shapewear.
Spandex remains the dominant material, with Nylon exhibiting the steepest expansion trajectory.
Distribution Channel:
Supply chain configuration directly determines accessibility and market reach, with significant shifts occurring in how consumers acquire shapewear products.
- E-commerce:Online platforms, including brand-specific websites and large retailers, offer extensive product selections and direct-to-consumer convenience. This channel dominates sales volume in the United States and is expanding rapidly in Latin America.
- Retail Stores:Traditional brick-and-mortar stores, including department stores and intimate apparel boutiques, provide a physical shopping experience and personal fitting services. These stores maintain a loyal customer base in established markets like France and Germany.
- Specialty Shops:These stores focus on niche offerings or premium brands, providing expert advice and a curated selection.
- Catalogs:Mail-order catalogs offer a traditional purchasing method, appealing to specific demographics seeking convenience without online interaction.
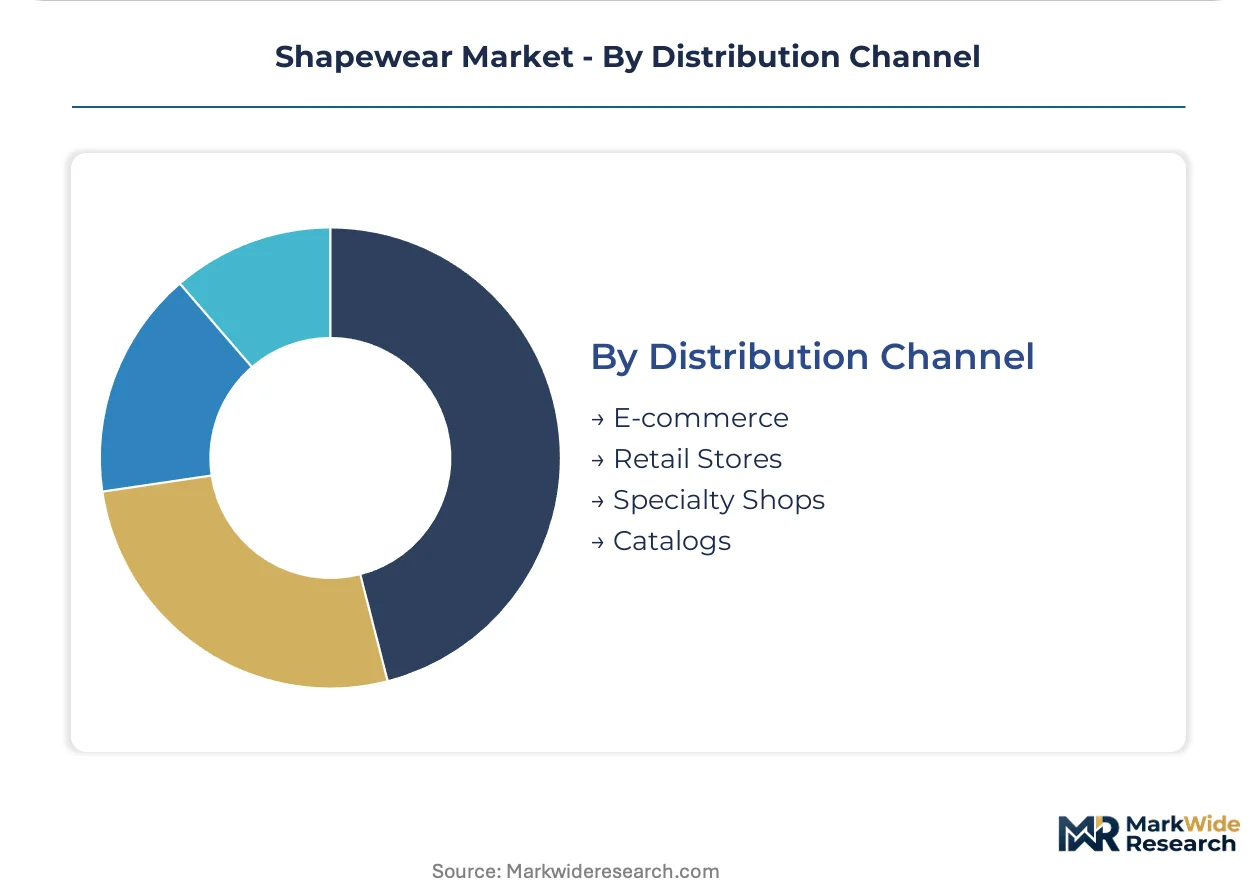
E-commerce represents the largest distribution channel, and it continues to grow most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States market demonstrates a strong preference for e-commerce distribution, amplified by social media influence. In contrast, European markets like Germany retain a significant customer base for traditional retail stores. This divergence in consumer acquisition strategies shapes regional brand investments and logistical infrastructure.
United States
United States consumers prioritize convenience and product variety, fueling e-commerce growth and social media-driven purchases. The US Federal Trade Commission (FTC) oversees accurate marketing claims for shapewear performance. Major fashion centers like New York City remain hubs for design and trend-setting within the apparel industry.
Germany
German consumers show sustained loyalty to traditional retail stores, valuing personal fitting and product quality. The EU's REACH regulation impacts material sourcing and chemical content for textiles sold across Europe. Textile producers in Baden-Württemberg are increasingly focused on developing sustainable fabric alternatives.
Brazil
Brazil's expanding middle class drives demand for aesthetic body contouring garments, particularly in urban centers. ANVISA, the national health surveillance agency, monitors certain garment classifications for material safety. Fashion designers in São Paulo actively incorporate local sizing and style preferences into new collections.
India
India's burgeoning urban population and increasing disposable income create a fertile ground for shapewear adoption. The Bureau of Indian Standards (BIS) establishes quality and safety benchmarks for textile products in the domestic market. E-commerce platforms in Bangalore facilitate direct-to-consumer strategies for apparel brands.
China
Chinese consumers embrace online shopping for apparel, with social media influencing purchasing decisions for shapewear. The State Administration for Market Regulation (SAMR) ensures product quality and accurate fiber content labeling. Manufacturing centers in Shenzhen are at the forefront of developing advanced textile blends for compression garments.
Shapewear Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a tiered market structure. This environment includes established apparel brands leveraging existing distribution networks alongside agile, digitally native entrants. Strategic archetypes include heritage brands emphasizing broad appeal, luxury providers targeting premium segments, and direct-to-consumer disruptors. These players primarily engage in geographic expansion and portfolio diversification to capture new customer bases.
Within the established brand segment, Spanx exemplifies a heritage player maintaining market position through established brand equity and broad distribution channels, catering to a wide consumer base. In contrast, SKIMS represents a digitally native disruptor model, leveraging powerful social media strategies to engage a new, digitally-savvy consumer demographic. Wacoal occupies a distinct position as a luxury provider, specializing in premium offerings distributed through department stores and specialty boutiques, catering to consumers who prioritize high-end materials and personalized service. These companies illustrate the varied approaches to market penetration and customer engagement.
| Leading Market Players |
|---|
| Wacoal |
| Commando |
| SKIMS |
| Leonisa |
| Maidenform |
| Spanx |
| Yitty |
| Triumph International |
| Honeylove |
| Others |
Cost & Logistics Intelligence
The performance gap between high-compression and light-compression shapewear creates a distinct pricing structure, influencing fabric sourcing and manufacturing locations. This divergence compels brands to optimize for either cost-efficiency or advanced material performance across their supply chains.
Pricing Analysis
Capacity additions in China are reshaping price floors for high-volume control briefs and shaping camis. The market operates on a per-unit transactional model, with clear premium, standard, and economy tiers. Price differentiation stems from fabric innovation, such as micro-encapsulation, and established brand equity. Pricing softness reflects intense competition from athleisure garments. The plus-size consumer segment demonstrates lower price sensitivity, prioritizing comfort and effective shaping over the lowest cost.
Supply Chain Analysis
Material safety certifications, such as the EU's REACH regulation, gate market access for textile suppliers. Geographic supply concentrates in China, Vietnam, and India, major hubs for apparel manufacturing. The industry draws heavily from petroleum-derived inputs like spandex and nylon. Raw material volatility, driven by global energy prices, presents a significant structural risk. Distribution runs through e-commerce platforms, which dominate sales volume in the United States and Latin America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shapewear market is evolving into a late-cycle quality story, driven by consumer demand for sustainable materials and enhanced comfort features. This shift prioritizes premium specifications over basic functionality.
For Market Incumbents:Extend brand equity into adjacent wellness categories to counter activewear substitution. Diversify product portfolios with medical-grade compression garments, leveraging existing material science expertise. Invest in bio-based spandex research to mitigate raw material volatility and align with sustainability mandates. Control distribution through owned direct-to-consumer e-commerce channels to maintain margin integrity against digitally native entrants.
For New Entrants and Emerging Players:Enter via niche product categories like micro-encapsulated shapewear, targeting wellness-focused consumers. Prioritize the plus-size segment in Latin America with inclusive sizing and localized marketing. Leverage social media-driven direct-to-consumer models for rapid market penetration. Focus on transparent supply chains and sustainable material claims to capture environmentally conscious buyers.
For Investors and Strategic Acquirers:Consolidation pressure builds where brands lack differentiated material science or strong digital channel presence. Long-term viability favors vertically integrated players controlling fabric innovation and consumer data. Acquisition targets should possess robust e-commerce infrastructure or unique intellectual property in advanced textile blends. A signal to watch is the increasing stringency of regulatory mandates for supply chain transparency, such as the EU’s CSRD.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Spandex Development | Captures environmentally conscious consumers and aligns with sustainability mandates. |
| Direct-to-Consumer Channel Expansion | Bypasses traditional retail, reaching fragmented global customer bases efficiently. |
| Micro-encapsulation Technology Integration | Creates a new 'wearable beauty' category, elevating product value propositions. |
| Plus-Size Product Line Extension | Addresses a large, previously underserved consumer segment with significant demand. |
| Medical-Grade Compression Offering | Diversifies revenue streams beyond aesthetic function into healthcare applications. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to ensure comprehensive market understanding. Primary data involved conversations with brand executives, material scientists, retail buyers, and e-commerce platform managers. Secondary validation drew from US Federal Trade Commission reports, EU REACH documentation, company financial filings, and textile industry publications. Both bottom-up and top-down triangulation methods were applied to ensure data accuracy.
Historical performance and market benchmarks anchored the forecast window, providing a robust basis for future projections. The analytical framework modeled segmentation dimensions including product type (bodysuits, control briefs), end-user (women, plus-size), material (spandex, nylon), distribution channel (e-commerce, retail stores), and regional adoption patterns. Compound annual growth rates were derived from historical trends and projected market shifts. Key forecast inputs included raw material price forecasts and consumer disposable income growth.
Inputs from public company reports and regulatory filings were available through the study window; gaps in proprietary brand sales data introduce uncertainty bands. Forecasts reflect current market dynamics and technological trajectories. A model refresh is warranted upon material change in consumer preference or significant regulatory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Body Shaper Market
Apparel & Footwear
Sleepwear Market
Apparel & Footwear
Secondhand Apparel Market
Apparel & Footwear
North America Jeans Market
Apparel & Footwear
Men Shirts Market
Apparel & Footwear
Hats Market
Apparel & Footwear
Thermal Underwear Market
Apparel & Footwear
Plus Size Clothing Market
Apparel & Footwear
Asia-Pacific Jeans Market
Apparel & Footwear
Jeans Market
Apparel & Footwear
Women's T-Shirts Market
Apparel & Footwear
Sports Apparel Market
Apparel & Footwear
Global Luxury Underwear Market
Apparel & Footwear
Ballet Pointe Shoes Market
Apparel & Footwear
Southeast Asia Lingerie Market
Apparel & Footwear
Outdoor Apparel Market