
 Russia OOH and DOOH Market | 2026-2036
Russia OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
Russia OOH and DOOH Market Insights
Programmatic inventory management is repositioning how media owners monetize outdoor assets, shifting from fixed-rate contracts to impression-based trading. Yandex leverages its data infrastructure to target audiences across digital screens in urban transit hubs. SberMarketing anchors its position through integration with the parent bank's customer data ecosystem. Rambler&Co competes by bundling DOOH placements with its digital publisher network.
Out-of-home and digital out-of-home advertising encompasses physical and electronic display surfaces deployed in public spaces to deliver commercial messages to audiences outside their residences. LED boards operate at luminance thresholds between 5,000 and 10,000 nits to maintain visibility under direct sunlight, while static displays rely on vinyl substrate printing with UV-resistant ink formulations for durability. Digital screens capture the fastest expansion as programmatic trading penetrates transit advertising networks, whereas static billboards retain margin strength in highway corridors where electrical infrastructure remains limited. Interactive kiosks remain nascent outside Moscow and Saint Petersburg due to hardware maintenance complexity.
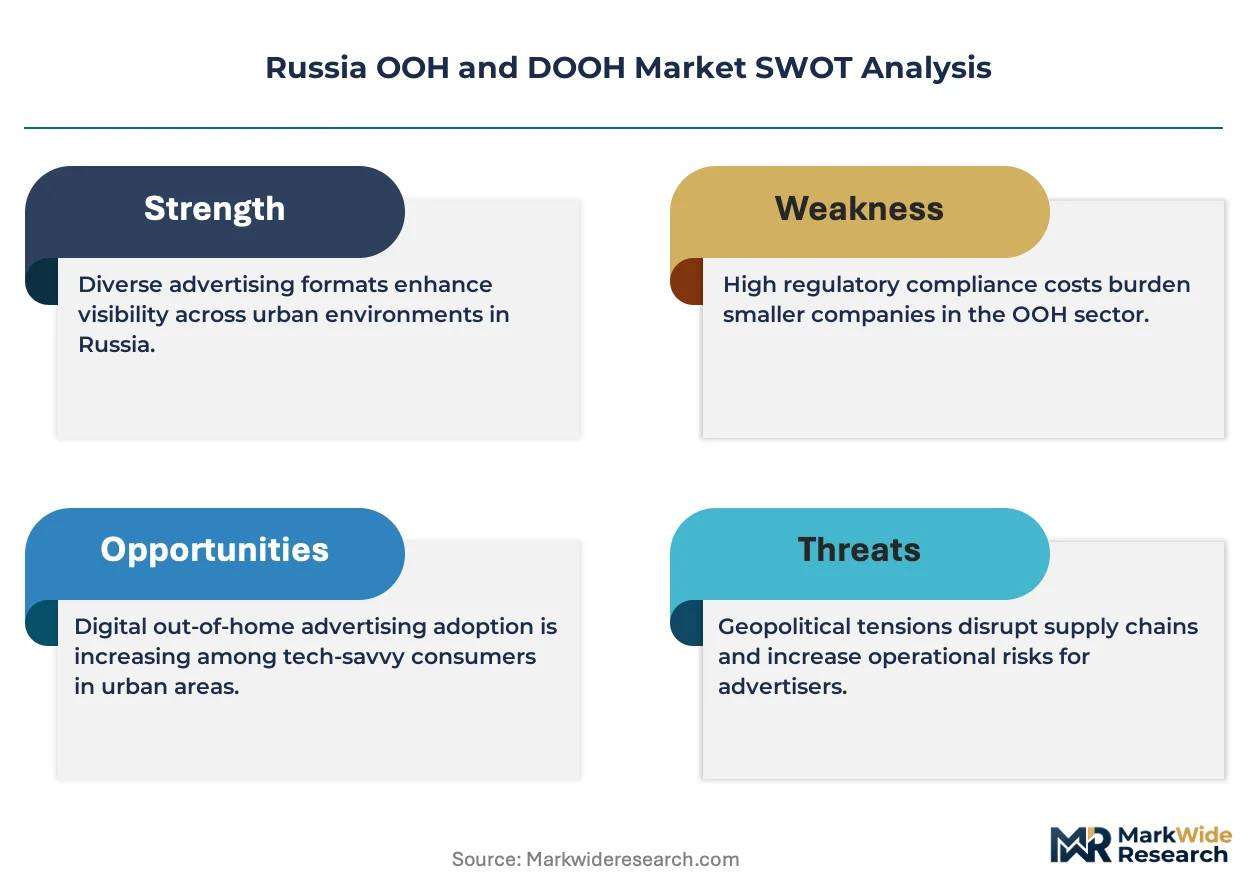
Russia's Federal Antimonopoly Service oversees competitive practices in media placement, while municipal administrations enforce zoning codes that restrict billboard density near historical landmarks and residential zones. The Ministry of Digital Development, Communications and Mass Media sets technical standards for electronic display equipment connected to public networks. Stakeholders must monitor how regional zoning amendments and data localization requirements for audience measurement platforms reshape capital deployment decisions across Russia's federal districts.
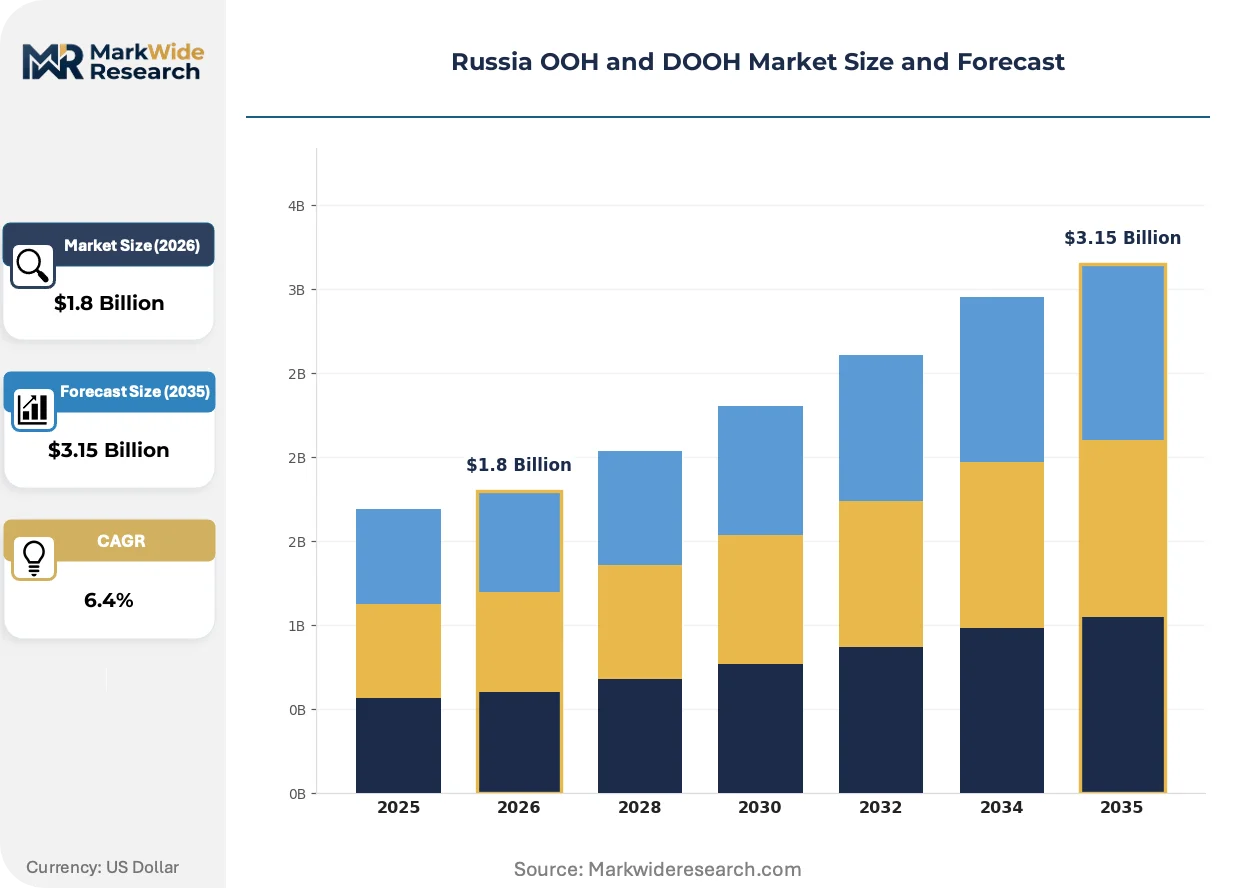
Market Dynamics
Moscow's municipal digitization mandates are forcing a wholesale replacement of static highway inventory with networked LED boards, compressing deployment timelines and rewiring how media owners finance capital cycles across Russia's federal highway system.
Growth Catalysts
- Federal Antimonopoly Service guidelines:These placement rules clarify competitive bidding for premium roadside locations, reducing legal friction for infrastructure investors in high-traffic corridors.
- Real-time audience measurement tools:Transit advertising networks in Saint Petersburg now trade on verified impression data, attracting performance-focused media buyers from retail and FMCG sectors.
- Moscow metropolitan concentration:Premium inventory rates in the capital's transit hubs generate cross-subsidy flows that fund LED expansion into secondary city networks.
Market Restraints
- Electrical infrastructure gaps:Highway corridors in Siberia and the Far East lack grid connectivity sufficient for LED board operation, locking static vinyl substrates as the only viable format.
- Hardware maintenance complexity:Interactive kiosk deployments face recurring field service costs that erode margin structures outside major urban centers.
- Data localization requirements:Russia's audience measurement platforms must store consumer data onshore, adding compliance overhead for international technology vendors.
Strategic Opportunities
- Kazan and Novosibirsk transit networks:These metropolitan areas remain underpenetrated by programmatic DOOH, offering first-mover positioning for platform operators.
- Banking customer data integration:Financial institutions with captive consumer datasets can activate cross-channel campaigns linking mobile banking alerts to screen-based proximity messaging.
- UV-resistant ink formulation advances:Static billboard substrates now achieve extended durability cycles, preserving margin strength in rural highway segments where digital conversion remains uneconomic.
Industry Challenges
- Programmatic trading expertise:Media sales teams lack technical fluency in impression-based auction mechanics, slowing platform adoption among traditional outdoor operators.
- Legacy contract structures:Fixed-rate annual agreements with municipal authorities block dynamic pricing experimentation, constraining revenue optimization for digitized assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia OOH and DOOH Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Media Type: Billboards, Transit Advertising, Street Furniture, Place-Based Media Technology: Digital Screens, Static Displays, LED Boards, Interactive Kiosks End User: Retailers, Automotive Industry, Entertainment, FMCG Application: Brand Promotion, Event Advertising, Local Business Marketing, Public Awareness |
| Companies Covered | Russ, Maer, Sber, Yandex, RMAA Group, VK Advertising, SberMarketing, Rambler&Co, Media Direction Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia OOH and DOOH Market Trends and Innovations
Programmatic infrastructure is penetrating Russia's outdoor advertising stack, collapsing the distinction between digital publisher ad tech and physical screen monetization. Three forces are compressing how inventory is priced, traded, and measured.
Computer vision-based audience analytics is converging with digital screen networks to enable real-time creative rotation based on demographic detection. Retail advertisers in Moscow's metro system are deploying these systems at scale. The technology is converging with demand-side platform architecture to collapse the gap between online and offline attribution models.
Russia's Ministry of Digital Development, Communications and Mass Media has issued technical standards for electronic displays connected to public networks, mandating cybersecurity protocols and data handling procedures. Equipment suppliers must certify compliance before highway deployment. LED board manufacturers serving federal road projects are restructuring firmware architectures to satisfy these connectivity requirements.
Retailers are consolidating media planning authority into centralized procurement functions that specify impression-based guarantees rather than slot-based bookings. This procurement model is displacing the traditional direct-sales relationships between media owners and local brand managers. The shift is most visible among FMCG conglomerates operating national distribution networks across Russia's federal districts.
Russia OOH and DOOH Market Segmentation
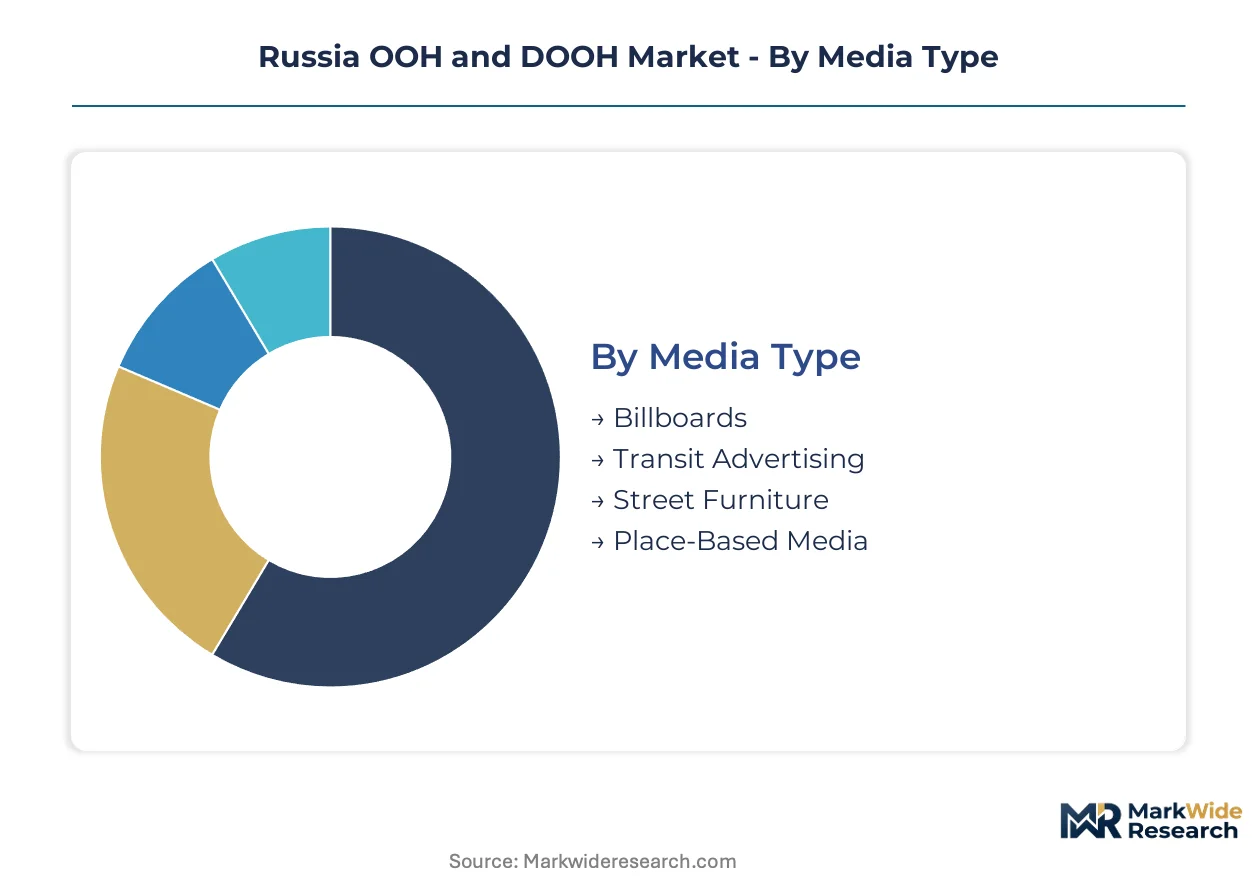
OOH and DOOH segmentation in Russia reveals how capital deployment, technology choices, and advertiser priorities diverge across federal districts. Media owners structure their asset portfolios around electrical infrastructure availability, municipal zoning density, and programmatic trading readiness.
Media Type:
Billboards command the heaviest capital outlays for land lease deposits and structural engineering compliance across Russia's federal highway network.
- Billboards:Steel-framed structures ranging from 3x6 meter roadside panels to 18x6 meter supersites along the M-11 Moscow-Saint Petersburg corridor. Moscow's municipal digitization mandates are forcing wholesale replacement of static highway inventory with networked LED boards, compressing deployment timelines for infrastructure investors.
- Transit Advertising:Interior and exterior placements across metro, bus, and suburban rail networks. Saint Petersburg's metro system now trades on verified impression data from computer vision analytics, attracting performance-focused media buyers from retail and FMCG sectors.
- Street Furniture:Bus shelters, newsstands, and urban wayfinding structures with integrated display surfaces. Municipal authorities in Kazan and Novosibirsk are issuing concession tenders that bundle maintenance obligations with advertising rights.
- Place-Based Media:Screens deployed in retail environments, healthcare facilities, and transit hubs. Shopping mall operators in Moscow are consolidating screen networks under single procurement platforms to enable programmatic trading.
Billboards absorb the bulk of installed capacity; Transit Advertising is expanding most quickly.
Technology:
Technology selection tracks directly to grid connectivity and maintenance infrastructure availability across Russia's federal districts.
- Digital Screens:LCD and LED panels operating at 5,000-10,000 nits luminance for daylight visibility. Retail advertisers in Moscow's metro system deploy these with real-time creative rotation based on demographic detection from computer vision systems.
- Static Displays:Vinyl substrate printing with UV-resistant ink formulations for durability cycles exceeding 36 months. These retain margin strength in Siberian and Far Eastern highway corridors where electrical infrastructure gaps preclude LED conversion.
- LED Boards:High-brightness electronic displays connected to public networks under Ministry of Digital Development technical standards. Federal road projects now mandate cybersecurity-certified firmware architectures before highway deployment authorization.
- Interactive Kiosks:Touch-enabled terminals with integrated payment and information functions. Hardware maintenance complexity limits viable deployment to Moscow and Saint Petersburg metropolitan areas where field service networks can sustain recurring service costs.
Static Displays still dominate unit count; Digital Screens are climbing the fastest as programmatic infrastructure penetrates urban transit networks.
End User:
End user concentration reflects which sectors possess centralized procurement functions capable of impression-based media buying.
- Retailers:Hypermarket chains and specialty store operators with national distribution networks. These advertisers are consolidating media planning authority into centralized procurement functions that specify impression-based guarantees rather than slot-based bookings.
- Automotive Industry:Domestic and international vehicle manufacturers targeting premium positioning. Dealer network density in Moscow and Saint Petersburg concentrates campaign spend in these metropolitan areas.
- Entertainment:Cinema chains, streaming platforms, and event promoters. Seasonal campaign spikes align with holiday release windows and summer festival calendars.
- FMCG:Packaged goods conglomerates with mass-market distribution. Cross-subsidy flows from Moscow metropolitan premium inventory rates fund LED expansion into secondary city networks for these national advertisers.
Retailers command the largest share of programmatic DOOH budgets; FMCG is gaining share fastest as procurement centralization accelerates.
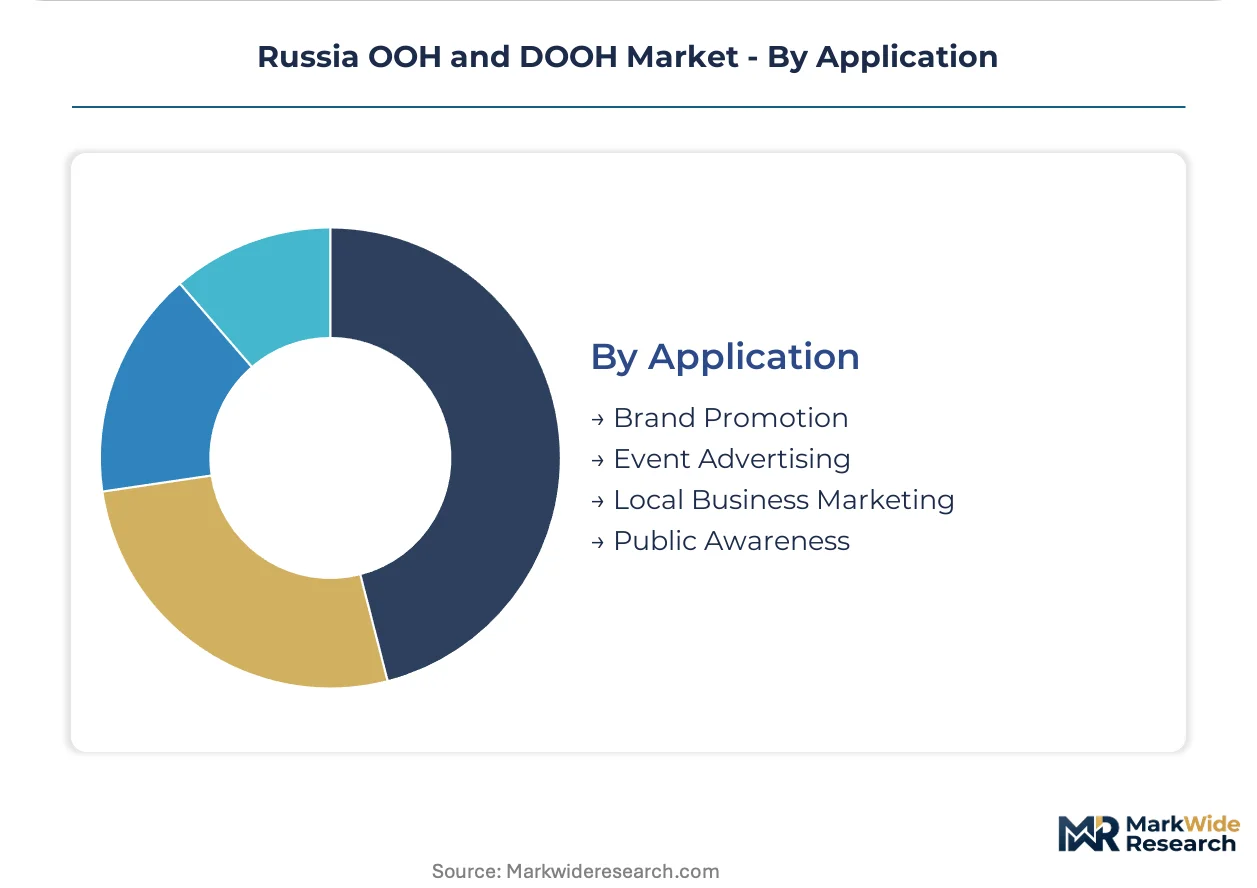
Application:
Application mix varies by advertiser sophistication and attribution requirements.
- Brand Promotion:Sustained awareness campaigns with creative rotation across extended flight dates. Moscow's transit hub premium inventory rates support these long-term commitments from established consumer brands.
- Event Advertising:Time-bound campaigns tied to specific dates or seasonal windows. Saint Petersburg's cultural calendar drives concentrated demand spikes from entertainment and tourism promoters.
- Local Business Marketing:Small and medium enterprise campaigns targeting geographic proximity. Static billboards in secondary cities serve this segment where digital conversion remains uneconomic.
- Public Awareness:Government and non-commercial messaging on health, safety, and civic initiatives. Municipal authorities often mandate minimum inventory allocation for these campaigns in concession agreements.
Brand Promotion accounts for the majority of contracted revenue; Event Advertising shows the steepest expansion trajectory as real-time audience measurement enables performance-based buying.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moscow dominates Russia's OOH and DOOH deployment, with federal highway digitization mandates compressing infrastructure timelines across the Central Federal District.
Moscow and Central Federal District
Moscow's municipal digitization mandates drive wholesale LED board replacement on federal highways. The Federal Antimonopoly Service guidelines clarify competitive bidding for premium roadside locations, reducing legal friction for infrastructure investors. The M-11 Moscow-Saint Petersburg corridor hosts the densest concentration of networked supersites, with media owners financing capital cycles through premium transit hub revenues.
Saint Petersburg and Northwestern Federal District
Saint Petersburg's metro system trades on verified impression data from computer vision analytics, attracting performance-focused retail and FMCG media buyers. The city's cultural calendar generates concentrated demand spikes from entertainment promoters during summer festival windows. Northwestern highway corridors retain static vinyl substrates where electrical infrastructure gaps preclude LED conversion.
Kazan and Volga Federal District
Kazan's transit networks remain underpenetrated by programmatic DOOH, offering first-mover positioning for platform operators. Municipal authorities issue concession tenders bundling maintenance obligations with advertising rights on bus shelters and urban wayfinding structures. The Volga region's secondary cities present expansion opportunities as Moscow-generated cross-subsidy flows fund LED network extension.
Novosibirsk and Siberian Federal District
Novosibirsk's metropolitan area lacks sufficient grid connectivity for highway LED board operation, locking static displays as the dominant format. The Ministry of Digital Development's technical standards for electronic displays connected to public networks add compliance overhead for equipment deployment. Siberian corridors depend on UV-resistant ink formulations achieving durability cycles exceeding 36 months under extreme climate conditions.
Vladivostok and Far Eastern Federal District
Vladivostok's port city status concentrates place-based media demand from logistics and tourism promoters targeting transit hubs. Hardware maintenance complexity limits interactive kiosk deployment to metropolitan cores where field service networks sustain recurring costs. Far Eastern federal highways remain uneconomic for digital conversion due to infrastructure gaps and dispersed population density.
Russia OOH and DOOH Market Competitive Landscape
Capital-heavy media owners with physical screen networks compete with asset-light programmatic platform operators for advertiser budgets across Russia's federal districts. The vendor base separates between infrastructure owners financing LED deployment and technology providers monetizing data-driven audience targeting. Three archetypes dominate: bank-affiliated marketing services leveraging captive customer datasets, search-engine-derived ad tech platforms with urban transit hub penetration, and diversified digital publishers bundling DOOH with online inventory. Consolidation pressure manifests through municipal concession tender requirements and cross-subsidy flows from premium Moscow inventory funding secondary city expansion.
Within the bank-affiliated tier, SberMarketing and Sber occupy positions integrating parent institution customer data ecosystems for cross-channel campaign activation. Yandex anchors the search-derived ad tech archetype, leveraging data infrastructure to target audiences across digital screens in urban transit hubs. Rambler&Co exemplifies the bundled publisher model, competing through combined DOOH and digital publisher network offerings. These three entities represent distinct strategic approaches to collapsing the gap between online attribution models and physical screen monetization across Moscow, Saint Petersburg, and emerging secondary markets.
| Leading Market Players |
|---|
| Russ |
| Maer |
| Sber |
| Yandex |
| RMAA Group |
| VK Advertising |
| SberMarketing |
| Rambler&Co |
| Media Direction Group |
| Others |
Pricing and Supply Chain Analysis
Retail and FMCG procurement centralization into impression-based buying is anchoring value-based pricing models across Moscow's transit advertising networks, compressing slot-based rate cards and forcing media owners to restructure revenue recognition around verified audience throughput.
Pricing Analysis
Outcome-tied impression guarantees now dominate contract structures, with transit hub inventory trading on verified viewership data from computer vision systems. Price differentiation separates premium Moscow metro placements from standard highway LED boards and economy-tier static vinyl in secondary cities. Cost compression in the static billboard segment is intensifying because UV-resistant substrate suppliers face margin pressure from digital conversion mandates. Small and medium enterprises remain most price-sensitive, while national retailers with centralized procurement tolerate premium rates for attribution-ready inventory.
Supply Chain Analysis
Domestic-content requirements for electronic displays connected to public networks are restructuring procurement toward certified Russian firmware architectures and local assembly partnerships. LED module supply draws from China, South Korea, and Taiwan, while steel framing and structural engineering services feed from domestic Russian fabricators. Single-source vulnerability concentrates in high-brightness LED driver components subject to export control friction. Distribution runs through media owner direct sales teams for premium inventory, with programmatic platforms disintermediating traditional broker networks for remnant transit slots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around data-integrated platform operators, with municipal concession tender requirements and cross-subsidy economics forcing smaller static-focused owners toward exit or acquisition.
For Market Incumbents: Hedge against programmatic margin erosion by securing exclusive concession renewals in Kazan and Novosibirsk before platform operators establish beachheads. Backward integration into audience measurement technology preserves pricing power against Yandex's data infrastructure advantages. Prioritize firmware certification under Ministry of Digital Development standards to lock out non-compliant hardware competitors from federal highway projects. For New Entrants and Emerging Players: Computer vision analytics capabilities offer the most penetrable wedge, with Saint Petersburg's impression-verified metro system proving advertiser willingness to pay for demographic detection. Target underpenetrated Volga Federal District transit networks where municipal authorities bundle maintenance obligations with advertising rights. Lead with self-service programmatic interfaces that bypass incumbent sales team bottlenecks. For Investors and Strategic Acquirers: Distressed-cycle entries favor bank-affiliated marketing services with captive customer data ecosystems in Moscow and Saint Petersburg, where cross-channel activation capabilities command strategic premiums. Long-term viability hinges on sustained electrical infrastructure expansion into Siberian and Far Eastern corridors. Watch Federal Antimonopoly Service enforcement intensity as the inflection signal for competitive bidding friction reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Programmatic Platform Integration | Collapses distinction between digital publisher ad tech and physical screen monetization across Moscow transit hubs. |
| Audience Measurement Technology Acquisition | Captures computer vision analytics capabilities that enable real-time creative rotation based on demographic detection. |
| Concession Tender Expansion | Secures bundled maintenance and advertising rights in Kazan and Novosibirsk before first-mover platform operators establish presence. |
| Firmware Certification Investment | Satisfies Ministry of Digital Development cybersecurity protocols for LED board deployment on federal highway networks. |
| Banking Customer Data Partnership | Activates cross-channel campaigns linking mobile banking alerts to screen-based proximity messaging through SberMarketing integration. |
Research Methodology
Multi-period observation of LED deployment timelines, municipal concession award patterns, and programmatic trading penetration anchored the trend analysis, supplemented by interviews with media owners, transit authority procurement officers, platform engineers, and retail media planning directors. Secondary validation drew from Federal Antimonopoly Service placement guidelines, Ministry of Digital Development technical standards, municipal digitization mandates, and customs records for LED module imports. Bottom-up asset-level modeling triangulated against top-down advertiser spend allocation surveys.
Input-output matrices mapped screen inventory expansion, electrical infrastructure availability, and impression-based trading adoption across the projection horizon. Segmentation dimensions included media type, technology format, end-user vertical, and application purpose. CAGRs were derived from fitted growth curves calibrated to observed digitization rates and procurement centralization timelines. Forecast inputs incorporated Federal Antimonopoly Service enforcement patterns and municipal concession renewal schedules.
Several conditions sit outside the modeled scope, including geopolitical disruption to LED component supply chains, abrupt shifts in data localization enforcement, and macroeconomic contraction affecting retail advertising budgets. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
North America Public Relation Services Market
Advertising and Marketing Media
Black Friday Sale Market
Advertising and Marketing Media
Qatar OOH and DOOH Market
Advertising and Marketing Media
Middle East Marketing and Advertising Agency Market
Advertising and Marketing Media
United States OOH and DOOH Market
Advertising and Marketing Media
Nigeria OOH and DOOH Market
Advertising and Marketing Media
Social Video Advertising Market
Advertising and Marketing Media
Outdoor Advertising Market
Advertising and Marketing Media
United States Marketing Agencies Market
Advertising and Marketing Media
Global Social Advertising and Social Media Market
Advertising and Marketing Media
In-Game Advertising Market
Advertising and Marketing Media
Finland OOH and DOOH Market
Advertising and Marketing Media
Europe Public Relation Services Market
Advertising and Marketing Media
Global Programmatic Advertisement Market
Advertising and Marketing Media
North America OOH and DOOH Market
Advertising and Marketing Media
Media Advertising in Southeast Asia Market