
 Russia Drill Pipe Market | 2026-2036
Russia Drill Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Drill Pipe Market Insights
Russia's domestic content mandates for oilfield equipment is decoupling procurement from import-dependent supply chains. TMK Group leverages in-house steelmaking to control alloy specifications across its Volzhsky and Sinarsky pipe plants. Vallourec anchors its position through threaded connection technology developed for high-pressure formations in Eastern Siberia. NOV Inc. competes by sustaining aftermarket repair networks across the Tyumen Oblast.
Russia drill pipe comprises seamless or welded tubular steel products, typically manufactured to API 5DP specifications with outer diameters ranging from 2⅜ to 6⅝ inches, engineered to transmit torque and convey drilling fluid in hydrocarbon extraction operations. Premium product types command margin concentration due to proprietary double-shouldered connections required in extended reach drilling across the Bazhenov Formation. Horizontal drilling applications absorb the fastest equipment replacement cycles as lateral lengths stretch beyond 1,500 meters in the Priobskoye field. Carbon steel grades retain volume dominance in conventional vertical wells where fatigue resistance demands remain moderate.
Russia's Federal Agency on Technical Regulating and Metrology enforces GOST R and GOST standards that supersede API specifications for state-backed exploration projects, while Rosnedra licensing conditions mandate domestic pipe quotas in Arctic offshore concessions. The country's national environmental regulator imposes well integrity rules that accelerate premium connection adoption in permafrost zones. Stakeholders must monitor how sanctions-driven import substitution reshapes alloy sourcing and certification pathways.
Market Dynamics
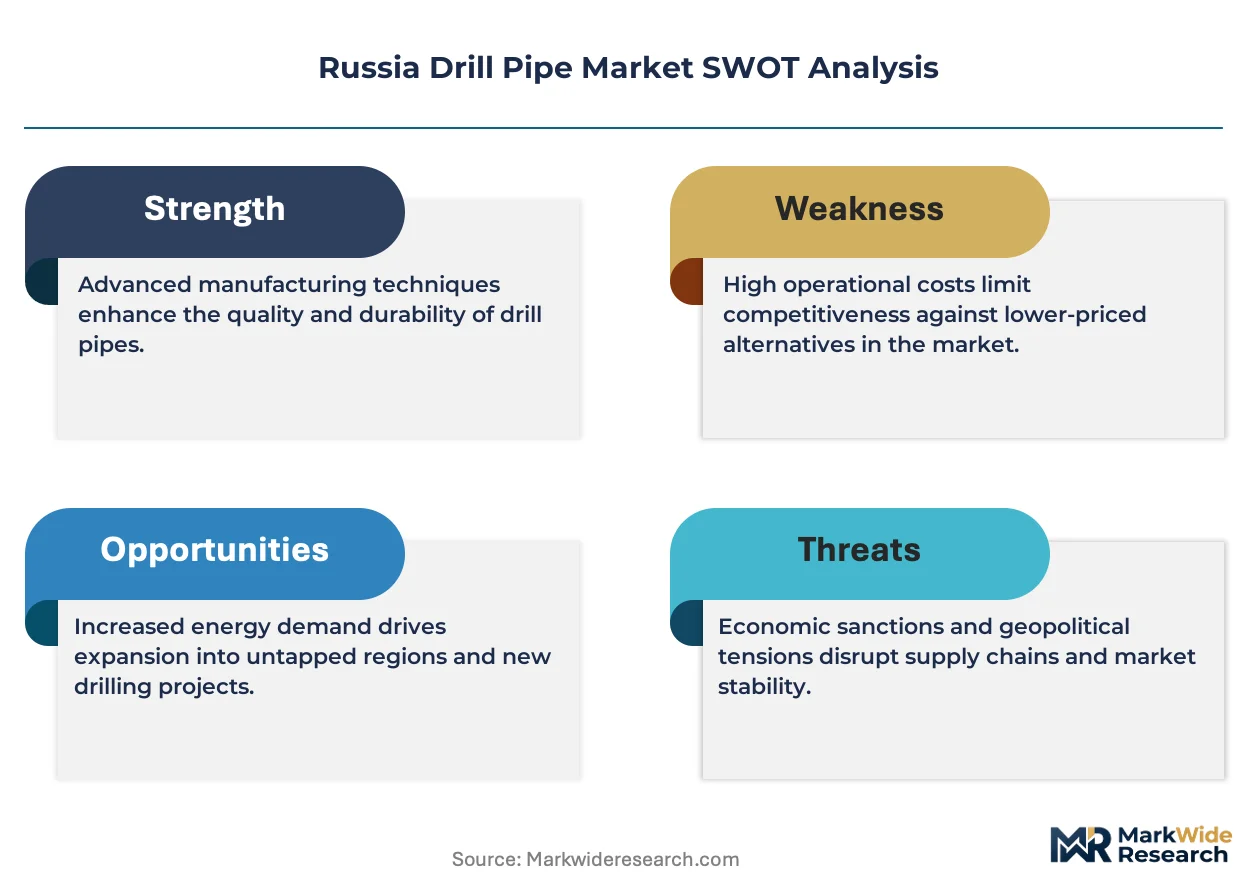
Domestic content mandates from Rosnedra are forcing exploration firms to requalify supply chains around in-country alloy production and GOST-certified threading capabilities, compressing procurement timelines for Arctic offshore projects.
Growth Catalysts
- Bazhenov Formation horizontal drilling:Extended-reach laterals exceeding 1,500 meters in Western Siberia consume premium double-shouldered connections at accelerated replacement cycles.
- Rosnedra Arctic licensing conditions:Domestic pipe quotas in offshore concessions redirect procurement toward Volzhsky and Sinarsky manufacturing clusters.
- Permafrost well integrity rules:The national environmental regulator mandates premium connection specifications that upgrade field equipment standards across the Yamal-Nenets Autonomous Okrug.
Market Restraints
- Specialty alloy import dependency:Chromium-molybdenum billet sourcing concentrates through a narrow corridor of sanctioned supply routes, exposing margin volatility.
- GOST R certification bottlenecks:Rosstandards approval timelines for new connection designs extend qualification periods for state-backed tenders.
- Composite coiled tubing substitution:Lightweight intervention systems displace conventional drill pipe in workover applications across mature Priobskoye field assets.
Strategic Opportunities
- Eastern Siberia greenfield expansion:The Vankor cluster and East Messoyakha developments absorb high-torque pipe specifications for high-pressure formations.
- API-GOST dual certification services:Third-party testing laboratories in Tyumen Oblast capture margin from exporters requiring dual-standard compliance documentation.
- Aftermarket repair network densification:Mobile threading and inspection units embedded at the Ural Federal District's oilfield services cluster reduce rig downtime.
Industry Challenges
- Ultrasonic inspection technician scarcity:GOST-certified NDT specialists command wage premiums that inflate operating costs at regional service centers.
- Legacy API 5DP inventory stranding:Rosnedra's domestic content thresholds devalue non-GOST pipe stockpiles held by distributors in the Khanty-Mansi Autonomous Okrug.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Drill Pipe Market |
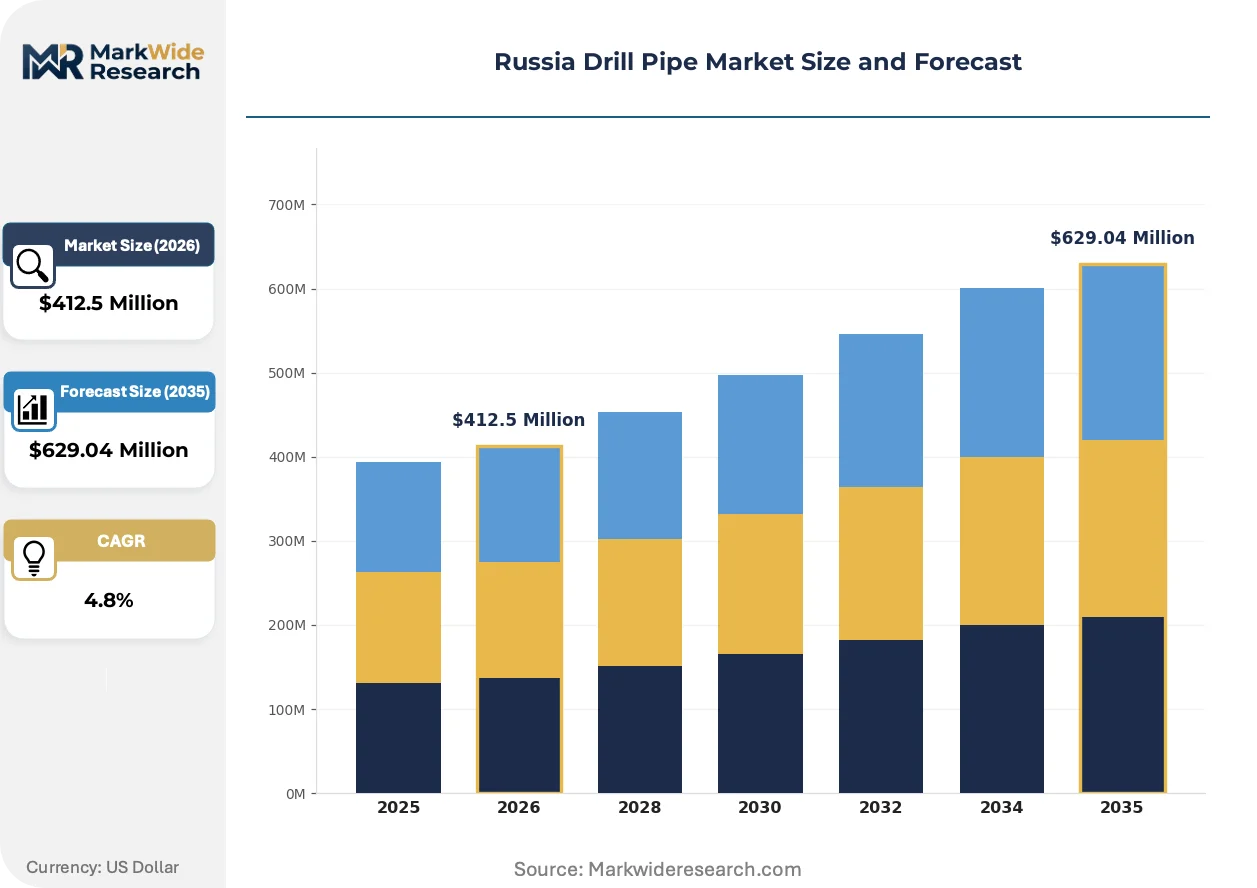
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Premium, Semi-premium, Low Alloy, Stainless Steel, Carbon Steel Material Grade: API 5DP, API 5CT, API 7-1, Inconel, Duplex Steel Application: Onshore Well, Offshore Well, Extended Reach Drilling, Horizontal Drilling, Directional Drilling End User: Exploration Firms, Drilling Contractors, Oil & Gas Operators, Engineering Consultants |
| Companies Covered | Vallourec, Hilong Group, TMK Group, Drill Pipe International LLC, Hunting PLC, EVRAZ North America, NOV Inc., Superior Drillpipe Manufacturing Inc., Tenaris, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Drill Pipe Market Trends and Innovations
Connection metallurgy and inspection protocols are converging around Arctic-specific fatigue requirements, while procurement governance tightens around traceable domestic alloy provenance.
Advanced double-shouldered connection geometries are absorbing torsional loads from rotary steerable systems in extended-reach horizontals. Gazprom Neft and Rosneft drilling divisions specify these designs for Bazhenov Formation laterals where torque transmission exceeds conventional tool joint limits. The technology is absorbing market share from standard API connections in premium-tier procurement categories.
Rosstandards enforcement of GOST R 50278-92 for sour service applications tightens hydrogen sulfide crack resistance testing protocols. State-backed exploration tenders now disqualify pipe lacking domestic certification, redirecting R&D expenditure toward in-country metallurgical qualification. Eastern Siberia operators face the steepest compliance ramps as Rosnedra licensing ties field development rights to certified equipment deployment.
Integrated supply contracting is consolidating procurement decisions at the federal district level rather than individual rig level. Oilfield service majors in the Tyumen Oblast negotiate frame agreements covering pipe, inspection, and threading as bundled units, displacing spot-market purchasing. This concentration is most visible in the Ural Federal District where TMK Group anchors vertically coordinated supply arrangements.
Russia Drill Pipe Market Segmentation
Equipment replacement cycles in Russia's oilfields diverge sharply by application intensity and regulatory compliance tier. Procurement patterns fragment across domestic content mandates, Arctic integrity rules, and horizontal drilling torque requirements that reshape grade specifications.
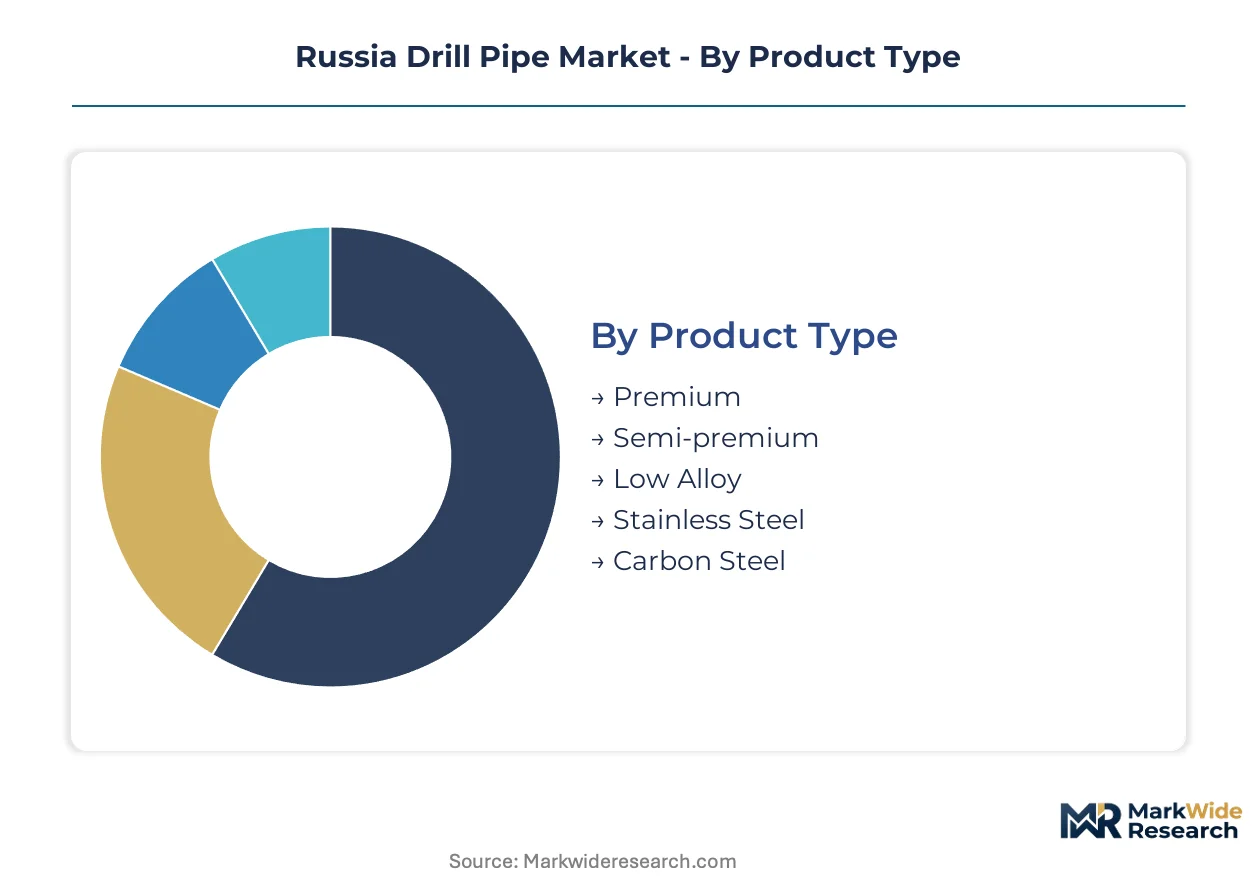
Product Type:
Upgrade cycles accelerate where extended-reach drilling and permafrost integrity rules force connection technology turnover.
- Premium:Double-shouldered connections with proprietary metallurgy handle torque loads exceeding 40,000 ft-lbs in Bazhenov Formation horizontals. Rosnedra licensing ties Arctic offshore concessions to this tier, concentrating demand around Volzhsky manufacturing.
- Semi-premium:Modified API geometries with enhanced fatigue resistance capture transitional demand from operators balancing cost and lateral length. The Ural Federal District's oilfield services cluster stocks this tier for conventional directional work.
- Low Alloy:Cost-optimized specifications serve mature vertical well maintenance programs.
- Stainless Steel:Sour service resistance for hydrogen sulfide-bearing formations in Eastern Siberia.
- Carbon Steel:Volume base for standard API 5DP vertical drilling with moderate fatigue demands.
Carbon Steel sits at the top of the volume ranking, with Premium climbing the fastest.
Material Grade:
Certification pathways split procurement between API standards for export-linked projects and GOST mandates for state-backed exploration.
- API 5DP:Seamless and welded tubular specifications govern torque transmission and fluid conveyance. Western Siberian operators maintain dual-certified inventories to serve both export-oriented joint ventures and domestic Rosneft drilling divisions.
- API 5CT:Casing and tubing specifications overlap with drill pipe in integrated well construction programs. Tyumen Oblast distributors bundle these grades under frame agreements with Ural Federal District service companies.
- API 7-1:Rotary drill stem elements for high-torque rotary steerable applications.
- Inconel:Nickel-based superalloys for extreme temperature gradients in deep Eastern Siberia wells.
- Duplex Steel:Corrosion-resistant grades for chloride-rich formation fluids.
API 5DP holds the dominant procurement position, though GOST-certified alternatives are gaining share fastest.
Application:
Lateral length extension and Arctic deployment conditions drive specification divergence across well types.
- Horizontal Drilling:Laterals stretching beyond 1,500 meters in the Priobskoye field consume premium connections at 1.5-2x replacement frequency versus vertical equivalents. Rotary steerable systems impose torsional loads that accelerate tool joint fatigue.
- Extended Reach Drilling:High-angle trajectories from single surface locations demand fatigue-resistant metallurgy. Gazprom Neft specifications for the Yamal-Nenets Autonomous Okrug prioritize double-shouldered designs.
- Onshore Well:Conventional vertical programs retain carbon steel dominance.
- Offshore Well:Arctic platform drilling ties procurement to GOST R certification and domestic alloy provenance.
- Directional Drilling:Intermediate complexity wells with build-and-hold profiles.
Onshore Well commands the highest volume share, with Horizontal Drilling showing the steepest expansion trajectory.
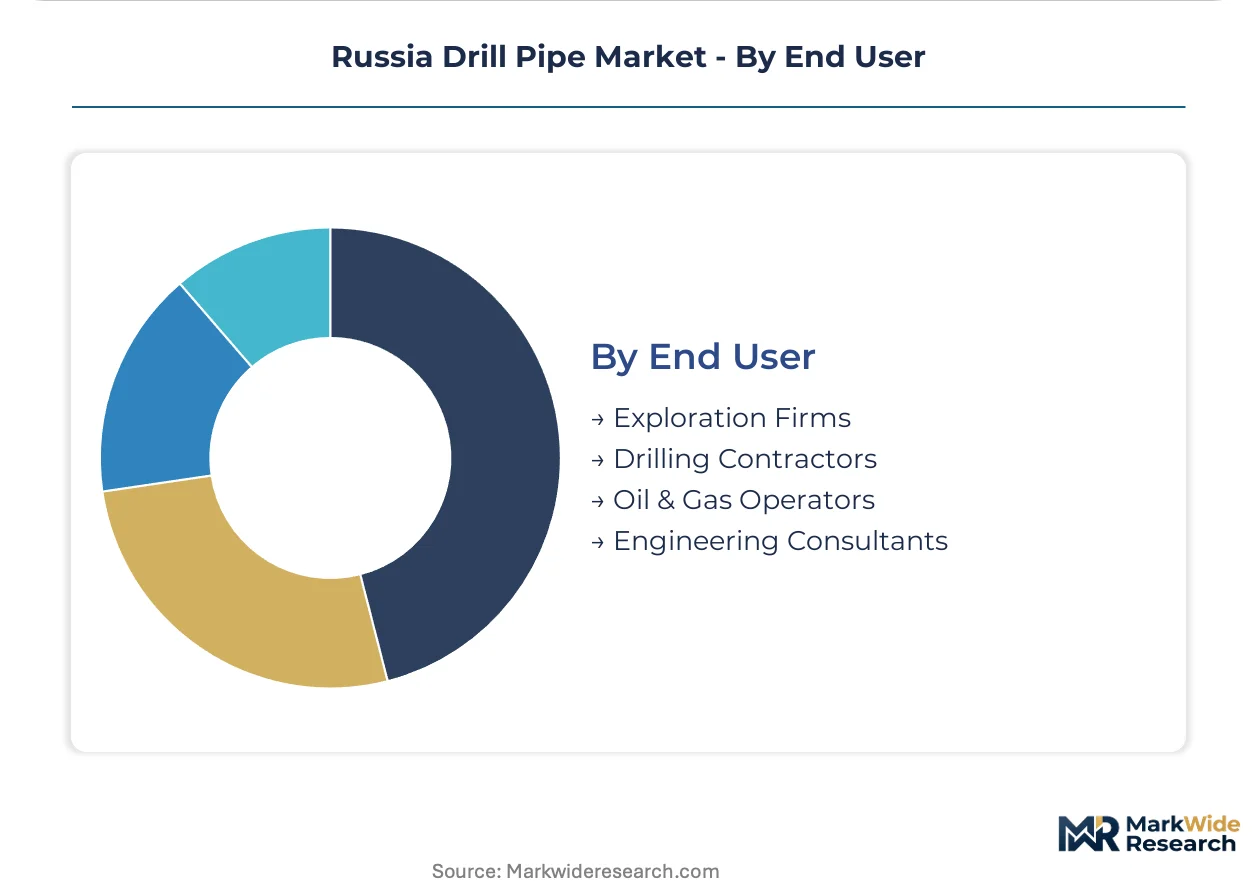
End User:
Procurement centralization varies by entity scale and state ownership structure.
- Oil & Gas Operators:Rosneft and Gazprom Neft drilling divisions consolidate purchasing through federal district-level frame agreements. Integrated supply contracting bundles pipe, inspection, and threading services, displacing spot-market transactions.
- Drilling Contractors:Independent service companies in the Tyumen Oblast operate mobile threading units to reduce rig downtime. Equipment rental models shift capital burden from operators to contractors.
- Exploration Firms:Smaller entities navigating Rosnedra domestic content thresholds.
- Engineering Consultants:Technical specification authorities for complex well designs.
Oil & Gas Operators represent the largest procurement block, with Drilling Contractors expanding their equipment ownership fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's drill pipe industry traces its scale to Soviet-era steelmaking investments in the Volga-Ural region, where integrated metallurgy complexes supplied hydrocarbon extraction across Siberia. State-backed pipeline construction and Arctic exploration mandates have since concentrated manufacturing and procurement decisions around federal district clusters.
Western Siberia
The Priobskoye and Bazhenov formations drive premium connection consumption as laterals exceed 1,500 meters. Rosnedra licensing conditions mandate domestic pipe quotas for Arctic offshore concessions accessible from this region. Tyumen Oblast hosts the densest oilfield services cluster, with mobile threading units reducing rig downtime across the Khanty-Mansi Autonomous Okrug.
Ural Federal District
Volzhsky and Sinarsky manufacturing plants anchor steel-to-pipe vertical coordination for state-backed exploration tenders. The district's metallurgical heritage supports GOST-certified alloy production that satisfies Rosstandards enforcement. Chelyabinsk and Perm clusters specialize in high-torque specifications for extended-reach drilling programs.
Eastern Siberia
The Vankor cluster and East Messoyakha developments absorb high-pressure formation pipe as Gazprom Neft expands greenfield footprints. Permafrost well integrity rules from the national environmental regulator accelerate premium connection adoption across the Yamal-Nenets Autonomous Okrug. Krasnoyarsk Krai distributors manage frame agreements bundling pipe, inspection, and threading services.
North Caucasus Federal District
Mature vertical well maintenance programs retain carbon steel dominance with moderate fatigue resistance requirements. Stavropol and Rostov service centers stock semi-premium inventories for conventional directional work. The district functions as a secondary logistics node for surplus API 5DP inventory redistribution.
Northwestern Federal District
Arctic offshore platform procurement ties to GOST R certification requirements and domestic alloy provenance tracking. Murmansk and Arkhangelsk ports handle import substitution cargo flows reshaped by sanctions-driven supply chain reconfiguration. The region's service infrastructure supports Rosneft drilling divisions operating Barents Sea concessions.
Russia Drill Pipe Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and connection technology specialization. The vendor base concentrates around integrated steelmakers with in-house metallurgy capabilities and threading specialists with GOST-certified inspection networks. Two strategic archetypes dominate: vertically coordinated domestic champions controlling alloy-to-pipe production chains, and technology licensors leveraging proprietary connection geometries. Competitive moves center on federal district-level frame agreement consolidation and mobile repair network densification.
Among the named participants, TMK Group and Vallourec occupy positions at opposite ends of the integration spectrum, with NOV Inc. representing the aftermarket service archetype. TMK Group exemplifies the captive steelmaking model through its Volzhsky and Sinarsky plant control. Vallourec anchors the premium technology tier with threaded connection specialization. NOV Inc. sits within the service-intensive segment, sustaining regional repair networks across Tyumen Oblast. These three patterns—captive metallurgy, proprietary geometry licensing, and distributed aftermarket infrastructure—define the competitive structure.
| Leading Market Players |
|---|
| Vallourec |
| Hilong Group |
| TMK Group |
| Drill Pipe International LLC |
| Hunting PLC |
| EVRAZ North America |
| NOV Inc. |
| Superior Drillpipe Manufacturing Inc. |
| Tenaris |
| Others |
Pricing and Supply Chain Analysis
GOST-certified ultrasonic inspection technician pools in Tyumen Oblast command wage premiums that widen spreads between premium-tier and economy-grade pipe procurement. Labor scarcity at threading and certification facilities concentrates pricing power among vertically integrated domestic producers while compressing margins for import-dependent distributors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Rosnedra-compliant double-shouldered connections from modified API geometries and basic carbon steel grades. Price differentiation hinges on GOST R certification tier and domestic alloy provenance documentation. Cost compression in semi-premium segments intensifies because composite coiled tubing substitutes displace conventional pipe in workover applications. Exploration firms navigating domestic content thresholds exhibit highest price sensitivity, while Arctic offshore operators under Rosnedra licensing show least sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Rosnedra's domestic content mandates are reshaping sourcing corridors toward in-country billet production and GOST-certified threading capabilities. Supply draws from Russia's Volzhsky and Sinarsky manufacturing clusters, with chromium-molybdenum alloy feedstock tethered to sanctioned import routes through narrow logistical corridors. Single-source vulnerability concentrates in specialty alloy billet sourcing. Distribution runs through federal district-level frame agreements bundling pipe, inspection, and threading services rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's drill pipe market functions as a regulatory compounder where Rosnedra licensing conditions and GOST R certification mandates create structural demand for compliant equipment tiers.
For Market Incumbents: Hedge against composite coiled tubing substitution by deepening captive steelmaking control over alloy specifications and accelerating mobile repair network densification in the Ural Federal District. Rosstandards approval bottlenecks for new connection designs threaten to strand R&D investments; prioritize GOST R 50278-92 sour service qualification to defend state-backed tender access. For New Entrants and Emerging Players: Enter via aftermarket repair services in the Khanty-Mansi Autonomous Okrug, where legacy API 5DP inventory stranding creates immediate demand for recertification and threading capabilities. API-GOST dual certification services for export-linked joint ventures represent the most penetrable white-space target, with third-party testing laboratories in Tyumen Oblast capturing margin from documentation requirements. For Investors and Strategic Acquirers: Integrated oilfield service majors are the most active acquirers in this space, consolidating frame agreement coverage across federal districts. Long-term viability rests on regulatory persistence rather than commodity cycle exposure; target mobile threading and inspection unit operators with established Rosstandards relationships. Watch Rosnedra licensing volume for Arctic offshore concessions as the primary inflection signal for premium connection demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| GOST R Certification Investment | Rosstandards approval unlocks state-backed exploration tenders and Arctic offshore procurement channels. |
| Mobile Repair Network Expansion | Embedded threading units in Tyumen Oblast reduce rig downtime and capture recurring service revenue. |
| Backward Integration into Alloy Production | In-house steelmaking at Volzhsky and Sinarsky plants controls specifications and insulates against sanctioned import volatility. |
| Dual Certification Service Launch | API-GOST compliance documentation for Western Siberian export-linked joint ventures captures high-margin testing revenue. |
| Frame Agreement Consolidation | Federal district-level bundling of pipe, inspection, and threading displaces spot-market purchasing and locks in volume. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drilling contractors, oilfield service procurement leads, Rosstandards certification specialists, and metallurgical R&D directors with secondary validation against customs records, Rosnedra licensing disclosures, and GOST standard documentation. Bottom-up field data and top-down trade flow analysis triangulated volume and value estimates.
Historical reference periods anchored the projection horizon across the analysis window, with segmentation modeling across product type tiers, material grade specifications, application intensity levels, and end-user procurement centralization patterns. CAGRs derived from equipment replacement cycle analysis, lateral length extension trajectories in Western Siberia, and regulatory compliance ramp schedules. Forecast inputs incorporated Rosnedra licensing volume for Arctic concessions and composite coiled tubing substitution rates in mature Priobskoye field assets.
The model holds under sustained domestic content enforcement and stable sanctions architecture; deviation in specialty alloy import corridor access or Rosstandards approval timelines would shift premium connection availability and pricing trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
United States Oil and Gas Market
Oil & Gas
GCC and North Africa Coiled Tubing Market
Oil & Gas
United States Onshore Drilling Fluid Market
Oil & Gas
Open Hole Logging Services Market
Oil & Gas
AI in Oil and Gas Market
Oil & Gas
Italy Oil and Gas Downstream Market
Oil & Gas
Enclosed Flares Market
Oil & Gas
Iran Oil and Gas Market
Oil & Gas
Wireline Logging Services Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
GCC Oil and Gas Separation Market
Oil & Gas
Chad Oil and Gas Upstream Market
Oil & Gas
Oilfield Casing Spools Market
Oil & Gas
Drilling and Completion Fluids Market
Oil & Gas
Africa Oil Refining Market
Oil & Gas
North America Artificial Lift Systems Market