
 Road Aggregates Market | 2026-2036
Road Aggregates Market Size, Share, and Industry Trends Forecast 2026-2036
Road Aggregates Market Outlook
Maintenance-service contracts and lifecycle performance guarantees are restructuring how road aggregates get procured, shifting volume risk from public agencies to suppliers. Vulcan Materials Company leverages its quarry network density to anchor regional pricing power across the southeastern United States. CRH competes through integrated asphalt and aggregates positioning in European highway programs. Heidelberg Materials sustains R&D intensity in low-carbon concrete aggregates, differentiating its product line against conventional crushed stone offerings.
Road aggregates consist of granular materials—typically crushed stone, gravel, sand, or slag—graded to specific particle size distributions such as 0-4 mm fines, 4-16 mm base course, and 16-32 mm sub-base layers, produced through mechanical crushing, screening, and washing to meet load-bearing and drainage specifications for pavement structures. Granite and limestone categories dominate volume in high-strength highway applications where abrasion resistance and polished stone value thresholds govern specification compliance. Government agencies and infrastructure developers represent the densest margin pools, as multi-year trunk road and bridge programs aggregate demand into contract bundles that reward scale and logistics coordination over spot-market flexibility.
The US Federal Highway Administration enforces Superpave mix design standards that dictate aggregate angularity and flat-or-elongated particle limits, while the EPA's construction and demolition debris regulations channel recycled concrete into specification-grade feedstock. The EU Green Deal's embodied carbon thresholds for public works are forcing quarries to document lifecycle emissions or forfeit tender eligibility on transnational corridor projects. Stakeholders must monitor how digital material passports and blockchain-tracked provenance requirements reshape supplier qualification criteria before the next procurement cycle locks in multi-year sourcing arrangements.
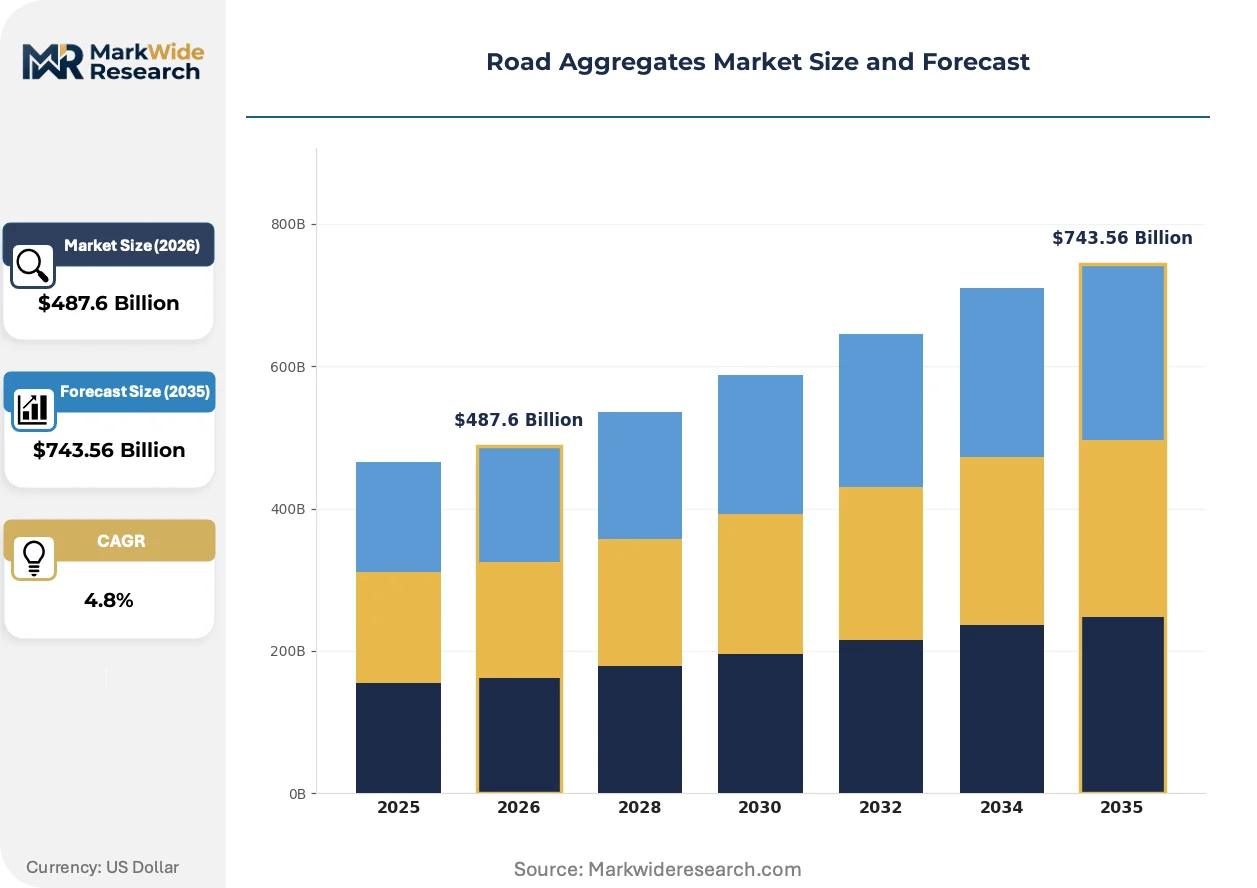
Market Dynamics
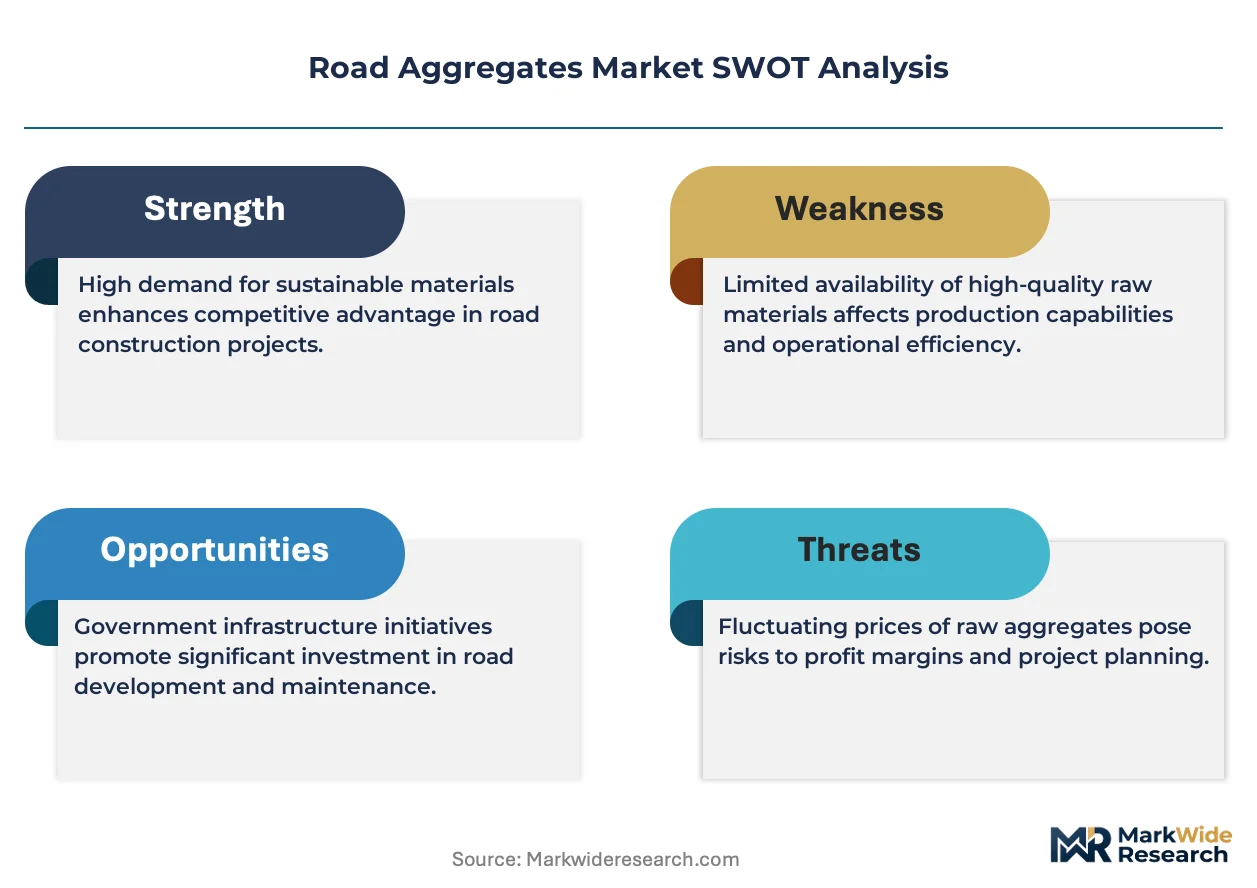
The US Federal Highway Administration's Superpave mix design standards and the EU Green Deal's embodied carbon thresholds are compressing supplier margins while forcing capital reallocation toward certified low-carbon production capacity and digital provenance tracking systems.
Growth Catalysts
- Highway rehabilitation mandates:The US Federal Highway Administration infrastructure spending directives are lifting procurement volumes for crushed stone and recycled concrete aggregates across state transportation departments.
- EU Green Deal construction sustainability requirements:Embodied carbon thresholds for public works are tightening material certification standards and channeling demand toward documented low-carbon feedstock.
- State-led expressway corridors in India:Urban ring road projects and national highway expansion programs are aggregating demand into multi-year contract bundles that reward scale.
Market Restraints
- Quarry permitting delays:Environmental review timelines under the US EPA and state-level air quality regulations are extending greenfield capacity expansion cycles by three to five years.
- Diesel and electricity input volatility:Crushing and screening operations face margin compression from energy price swings that spot-market pricing cannot fully pass through.
- Transportation radius economics:Road aggregates face inherent geographic constraint, with haul costs typically limiting competitive supply zones to fifty-mile radii from production sites.
Strategic Opportunities
- Digital material passports:Blockchain-tracked provenance systems are opening tender eligibility on transnational corridor projects for early-adopting quarries.
- Recycled concrete specification-grade feedstock:The EPA's construction and demolition debris regulations are creating certified channels for reclaimed aggregate into highway base course applications.
- Maintenance-service contract bundling:Lifecycle performance guarantees are shifting volume risk from public agencies to suppliers and locking in multi-year sourcing arrangements.
Industry Challenges
- Superpave angularity compliance:State DOT laboratories are rejecting flat-or-elongated particle shipments that fail automated image analysis thresholds, forcing crusher reconfiguration.
- Geotechnical engineer shortage:Pavement design specialists capable of integrating recycled content into structural layer calculations are concentrated among aging state workforce cohorts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Road Aggregates Market |
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $743.56 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Granite, Limestone, Sandstone, Gravel Application: Road Construction, Pavement Maintenance, Landscaping, Earthworks End User: Construction Companies, Government Agencies, Contractors, Infrastructure Developers Distribution Channel: Direct Sales, Wholesale, Retail, Online |
| Companies Covered | Vulcan Materials Company, CRH, Holcim, CEMEX, Martin Marietta Materials, Heidelberg Materials, Summit Materials, Arcosa, Rogers Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Road Aggregates Market Strategic Shifts
Processing technology and compliance infrastructure are converging to compress production cycles and restructure how material quality gets verified before shipment.
Mobile crushing and screening plants equipped with real-time particle size distribution sensors are modularizing quarry operations. Regional contractors in the southeastern United States and western India are deploying these units directly to demolition sites and borrow pits, eliminating double-handling costs. The technology is modularizing capital deployment by converting fixed-asset intensity into project-based operational expenditure.
The EU Green Deal's embodied carbon documentation requirements are forcing quarries to install continuous emissions monitoring and third-party verification systems. Operations that fail to submit verified lifecycle assessments forfeit eligibility on transnational corridor tenders. German and French highway programs are now requiring digital environmental product declarations as mandatory bid attachments.
Public agencies are consolidating procurement through multi-year performance-based contracts that transfer lifecycle risk to aggregate suppliers. State transportation departments in Texas and Florida are replacing spot-market purchases with five-year maintenance-service agreements bundling material supply and pavement performance guarantees. This restructuring is most visible in North American highway rehabilitation programs where agencies lack in-house materials testing capacity.
Road Aggregates Market Segmentation
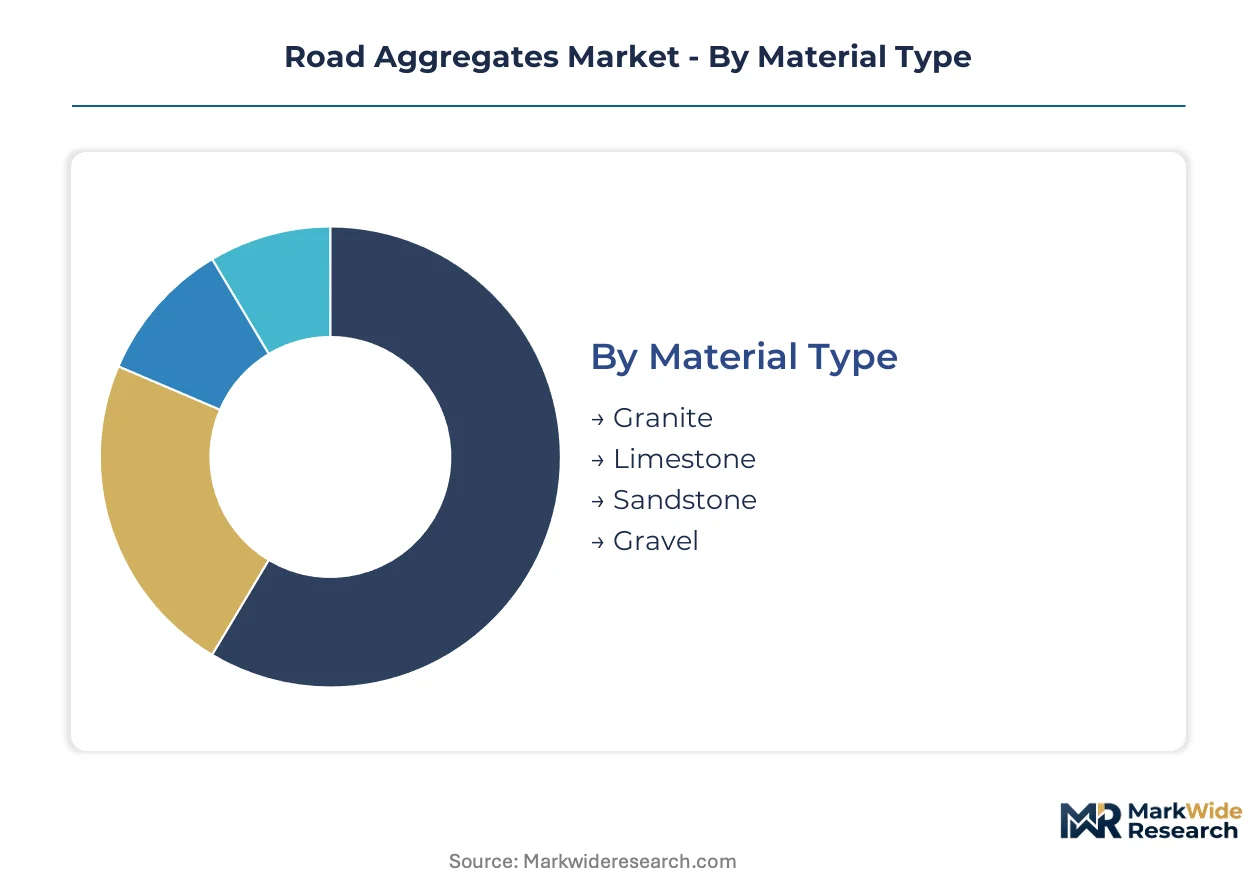
Road aggregates markets fragment across material chemistry, application load-bearing requirements, and procurement channel economics. Specification-grade compliance and logistics radius constraints determine which segments capture margin versus volume.
Material Type:
Granite commands premium pricing in high-strength applications where abrasion resistance thresholds dominate specification sheets, while limestone and gravel compete on cost in base course and fill applications.
- Granite:Igneous rock with superior polished stone value and crushing resistance, specified for surface course layers on heavy-traffic highways. Demand concentrates in Germany's autobahn rehabilitation programs and India's Mumbai-Pune Expressway corridor where axle loads exceed standard design limits. The EU Green Deal's embodied carbon documentation requirements are forcing quarries to certify extraction emissions or forfeit tender eligibility on transnational projects.
- Limestone:Sedimentary carbonate aggregate with lower density and softer abrasion characteristics, dominant in sub-base and drainage layers where cost efficiency outweighs surface performance. Procurement volumes are lifting across Texas and Florida state transportation departments as highway rehabilitation programs accelerate. EPA construction debris regulations are channeling increasing volumes of crushed limestone into recycled concrete feedstock blends.
- Sandstone:Clastic sedimentary material with variable cementation, deployed in decorative and non-structural paving where aesthetic finish specifications apply.
- Gravel:Unconsolidated alluvial deposits requiring minimal processing, supplying rural road maintenance and temporary access routes where haul distance economics favor local borrow pits over crushed stone.
Today's leader: Limestone. Tomorrow's challenger: Granite.
Application:
Road construction absorbs the densest procurement volumes through multi-year trunk highway programs, while maintenance contracts are restructuring how suppliers manage lifecycle performance risk.
- Road Construction:Greenfield highway and bridge projects requiring graded aggregate layers from sub-base through wearing course, governed by Superpave mix design standards in the US and national specification codes in India. State-led expressway corridors in India and urban ring road projects are aggregating demand into contract bundles that reward quarry network density and logistics coordination.
- Pavement Maintenance:Overlay, rehabilitation, and reconstruction work on existing road networks, increasingly procured through performance-based contracts transferring lifecycle risk to suppliers. Texas and Florida transportation departments are replacing spot-market purchases with five-year maintenance-service agreements bundling material supply and pavement performance guarantees.
- Landscaping:Decorative and functional aggregate for commercial and residential hardscaping, governed by aesthetic rather than structural specifications.
- Earthworks:Bulk fill and embankment construction where gradation tolerance loosens and price per ton dominates supplier selection.
Maintenance contracts are climbing fastest as agencies outsource technical risk.
End User:
Government agencies control the deepest margin pools through consolidated procurement of multi-year highway programs, while construction companies compete on operational efficiency in fragmented private development.
- Construction Companies:Private sector builders and civil contractors procuring aggregates for commercial, residential, and industrial development projects. Mobile crushing units are modularizing their capital deployment by converting fixed-asset intensity into project-based operational expenditure.
- Government Agencies:Federal, state, and municipal transportation departments specifying certified materials for public infrastructure. The US Federal Highway Administration's infrastructure spending mandates and the EU Green Deal's sustainability requirements are tightening material certification standards and channeling demand toward documented low-carbon feedstock.
- Contractors:Subcontracted specialists executing specific work packages under prime contractor management.
- Infrastructure Developers:Public-private partnership entities financing and delivering large-scale transport projects with integrated design-build-operate contracts.
Agency procurement is the margin anchor; developer models are expanding fastest.
Distribution Channel:
Direct sales dominate volume through long-term supply agreements with state transportation departments, while wholesale and retail channels serve fragmented private construction demand.
- Direct Sales:Long-term contracts between quarries and major end users, typically government agencies and large infrastructure developers, locking in volume commitments and pricing structures. Blockchain-tracked provenance systems are opening tender eligibility on transnational corridor projects for early-adopting quarries.
- Wholesale:Intermediate distributors aggregating supply from multiple quarries for resale to regional contractors and smaller construction firms.
- Retail:Small-volume sales to residential and light commercial customers through builder supply yards and home improvement channels.
- Online:Digital procurement platforms emerging for standardized aggregate products with transparent pricing and logistics coordination.
Direct sales hold volume leadership; digital channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's state-led expressway corridors are outpacing European rehabilitation programs in procurement velocity, while the United States maintains the deepest contract value pools through multi-year federal infrastructure mandates.
United States
The Federal Highway Administration's infrastructure spending directives are lifting crushed stone and recycled concrete volumes across state transportation departments. EPA construction and demolition debris regulations channel reclaimed material into specification-grade feedstock. Quarry network density in the southeastern states anchors regional pricing power for trunk highway rehabilitation.
Germany
Autobahn rehabilitation programs concentrate demand for granite surface course aggregates where axle loads exceed standard design limits. The EU Green Deal's embodied carbon thresholds force quarries to document lifecycle emissions or forfeit tender eligibility. Operations in the North Rhine-Westphalia industrial corridor are installing continuous emissions monitoring systems to meet digital environmental product declaration requirements.
India
National highway expansion and urban ring road projects are aggregating demand into multi-year contract bundles that reward scale and logistics coordination. State-level expressway corridors in Maharashtra and Gujarat concentrate procurement volumes for base course and sub-base materials. The Mumbai-Pune Expressway corridor specifies granite aggregates where heavy-traffic axle loads demand superior polished stone value performance.
Canada
Provincial transportation departments are consolidating procurement through performance-based contracts that transfer lifecycle risk to aggregate suppliers. Environmental review timelines under federal and provincial regulations extend greenfield quarry expansion cycles. Ontario's highway rehabilitation programs increasingly specify recycled concrete content in structural layer applications.
France
Transnational corridor tenders now require blockchain-tracked provenance systems and verified lifecycle assessments as mandatory bid attachments. French highway programs are tightening material certification standards under EU Green Deal sustainability requirements. Quarries in the Auvergne-Rhône-Alpes region are deploying mobile crushing units equipped with real-time particle size distribution sensors to modularize capital deployment.
Road Aggregates Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated materials groups commanding premium positions in specification-grade highway applications while regional contractors compete on haul distance economics in fragmented rural markets. The vendor base organizes around three strategic archetypes: quarry network density players anchoring regional pricing power, integrated asphalt-aggregates positioned for European highway programs, and R&D-intensive operators differentiating through low-carbon concrete feedstock. Competitive dynamics center on multi-year maintenance-service contract bundling and digital material passport adoption for transnational tender eligibility.
Among North American quarry operators, Vulcan Materials Company and Martin Marietta Materials exemplify network density strategies that lock in volume commitments through direct sales to state transportation departments. European positioning is anchored by CRH and Heidelberg Materials, which occupy positions spanning integrated construction materials and certified low-carbon production capacity. These five entities represent the dominant competitive set across federal and transnational procurement channels where specification compliance and logistics coordination determine contract awards.
| Leading Market Players |
|---|
| Vulcan Materials Company |
| CRH |
| Holcim |
| CEMEX |
| Martin Marietta Materials |
| Heidelberg Materials |
| Summit Materials |
| Arcosa |
| Rogers Group |
| Others |
Value Chain & Pricing Dynamics
Mobile crushing and screening plants equipped with real-time particle size distribution sensors are modularizing quarry operations and simultaneously compressing production costs while fragmenting supply concentration across project-based contractors. This technology shift enables regional operators in the southeastern United States and western India to bypass fixed-asset intensity and compete on haul distance economics against incumbent network density players.
Pricing Analysis
Capacity additions in India are reshaping price floors for base course and sub-base materials as state-led expressway corridors aggregate demand into multi-year contract bundles. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade granite with certified low-carbon documentation from unprocessed gravel borrow pits. Cost compression in limestone sub-base tiers is intensifying because diesel and electricity input volatility cannot be fully passed through spot-market pricing. Government agencies exhibit lowest price sensitivity due to lifecycle performance guarantees, while rural road maintenance contractors face acute pressure from fifty-mile haul radius constraints.
Supply Chain Analysis
Recycled concrete flows from demolition sites through mobile processing units are creating reverse-logistics channels that bypass traditional quarry-to-project distribution. Supply concentrates in the United States, Germany, and India where federal infrastructure mandates and EU Green Deal certification requirements anchor production. Raw material dependencies center on virgin granite and limestone deposits, diesel fuel for crushing operations, and bitumen for integrated asphalt-aggregate positioning. Single-source vulnerability runs through quarry network density in regional markets where permitting delays extend greenfield expansion cycles. Distribution runs through direct sales to state transportation departments with long-term offtake agreements locking in volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The road aggregates market reads as a late-cycle quality story as Superpave angularity compliance and EU embodied carbon thresholds concentrate procurement toward specification-grade certified producers. Demand is shifting toward premium granite surface course materials where polished stone value performance governs heavy-traffic highway awards.
For Market Incumbents: Deepen quarry network density in the southeastern United States to anchor regional pricing power against mobile crushing entrants. Prioritize R&D intensity in low-carbon concrete aggregate certification to defend tender eligibility as EU Green Deal documentation requirements tighten. Lock in five-year maintenance-service contracts with Texas and Florida transportation departments to transfer lifecycle risk and secure volume commitments against spot-market volatility.
For New Entrants and Emerging Players: Capture white-space in recycled concrete specification-grade feedstock where EPA construction debris regulations create certified channels into highway base course applications. Target India's state-led expressway corridors in Maharashtra and Gujarat where logistics coordination gaps reward agile project-based operators. Deploy mobile crushing units equipped with real-time particle size sensors to convert fixed-asset intensity into operational expenditure and compete on haul distance economics.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional contractors with mobile processing capabilities and underutilized permitting assets. Long-term viability centers on quarry network density and integrated asphalt-aggregate positioning across federal procurement channels. Acquisition target archetype: mid-scale operators with certified low-carbon production capacity and established state DOT relationships. Monitor digital material passport adoption rates as the inflection indicator for transnational tender eligibility expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Greenfield quarry development in India aggregates demand from state expressway corridors. |
| Backward Integration | Captive recycled concrete processing secures EPA-compliant feedstock for highway base course. |
| Green Manufacturing Transition | Continuous emissions monitoring systems satisfy EU Green Deal tender documentation requirements. |
| Long-term Supply Agreement | Five-year maintenance-service contracts with Texas DOT lock in volume against spot-market volatility. |
| Joint Venture | Mobile crushing partnerships with demolition contractors eliminate double-handling cost structures. |
Study Parameters
Direct dialogue with quarry operations managers, state transportation department procurement leads, asphalt plant technical directors, and geotechnical pavement engineers grounded this analysis in operational reality. Primary insights were cross-referenced against US Federal Highway Administration infrastructure spending disclosures, EU Green Deal implementation guidance, Indian Ministry of Road Transport project databases, and SEC 10-K filings from listed aggregate producers. Bottom-up and top-down triangulation validated volume estimates across material type and application segments.
Bottom-up modeling built from quarry-level capacity, utilization rates, and contract award pipelines across the analysis window. Segmentation dimensions included material chemistry, application load-bearing requirements, procurement channel economics, and regional regulatory cluster. CAGRs were derived from trend extrapolation of federal and state infrastructure appropriations, EU embodied carbon threshold implementation schedules, and Indian national highway expansion targets. Industry-specific forecast inputs incorporated Superpave mix design standard adoption curves and digital material passport penetration rates.
Permitting delays, diesel price volatility, and geotechnical engineer workforce shortages are the dominant revision risks to production capacity and specification compliance assumptions. Practitioners should monitor state DOT laboratory automation adoption and blockchain-tracked provenance system mandates for early signals of supplier qualification barrier shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
North America Industrial Duct for Dust Collection Market
Construction and Engineering
Ventilation Equipment Market
Construction and Engineering
Carbon Textile Reinforced Concrete Market
Construction and Engineering
Middle East Pipeline Construction Market
Construction and Engineering
Ultra Hard Material Cutting Machines Market
Construction and Engineering
Construction Sustainable Materials Market
Construction and Engineering
Construction Coatings Market
Construction and Engineering
Winch Market
Construction and Engineering
Light Duty Telehandler Market
Construction and Engineering
Europe Cement Market
Construction and Engineering
New Zealand Infrastructure Market
Construction and Engineering
Rivet Gun Market
Construction and Engineering
Austria Prefabricated Houses Market
Construction and Engineering
United States Hand Holes Market
Construction and Engineering
Mobile Elevating Work Platform (MEWP) Market
Construction and Engineering
South Korea HVAC Market