
 Ro-Ro Ocean Freight Transport Market | 2026-2036
Ro-Ro Ocean Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Ro-Ro Ocean Freight Transport Market Insights
Automotive OEMs is rotating toward integrated logistics partnerships that bundle ocean carriage with port processing and inland distribution. Wallenius Wilhelmsen leverages its terminal network to control vehicle-handling infrastructure across major trade lanes. Högh Autoliners anchors its competitive position through specialized pure car/truck carrier design and fuel-efficient vessel architecture. Grimaldi Group dominates Mediterranean-African short-sea routes with multi-purpose Ro-Ro and container vessel combinations.
Ro-Ro ocean freight transport employs vessels with internal ramp systems and adjustable deck configurations to accommodate wheeled cargo ranging from passenger cars to heavy construction equipment, with deck load ratings typically spanning 2 to 20 tons per square meter depending on cargo class. The primary commercial purpose centers on minimizing port dwell time and eliminating crane dependency for cargo handling, thereby reducing terminal costs and damage exposure for high-value automotive and machinery shipments. Vehicle type segmentation shows passenger vehicles commanding the largest volume share while heavy machinery generates premium freight rates due to specialized stowage requirements and lower cargo density. Operating model segmentation reveals deep sea shipping as the value concentration zone where long-haul automotive export contracts deliver extended revenue visibility, while short sea shipping competes on frequency and schedule reliability within regional basins such as the Baltic, Mediterranean, and intra-Asian networks.
The International Maritime Organization's Energy Efficiency Existing Ship Index and Carbon Intensity Indicator regulations are forcing fleet operators to retrofit main engines or retire older tonnage ahead of traditional depreciation cycles. The EU's Fit for 55 package and FuelEU Maritime initiative are reshaping bunker procurement strategies by introducing escalating penalties for fossil fuel consumption on voyages touching European ports. Classification societies including DNV and Lloyd's Register are certifying dual-fuel ammonia and methanol-ready newbuilds that will define capital allocation decisions through the forecast horizon. Stakeholders must monitor fuel pathway clarity and green premium pass-through mechanics to preserve contract competitiveness.
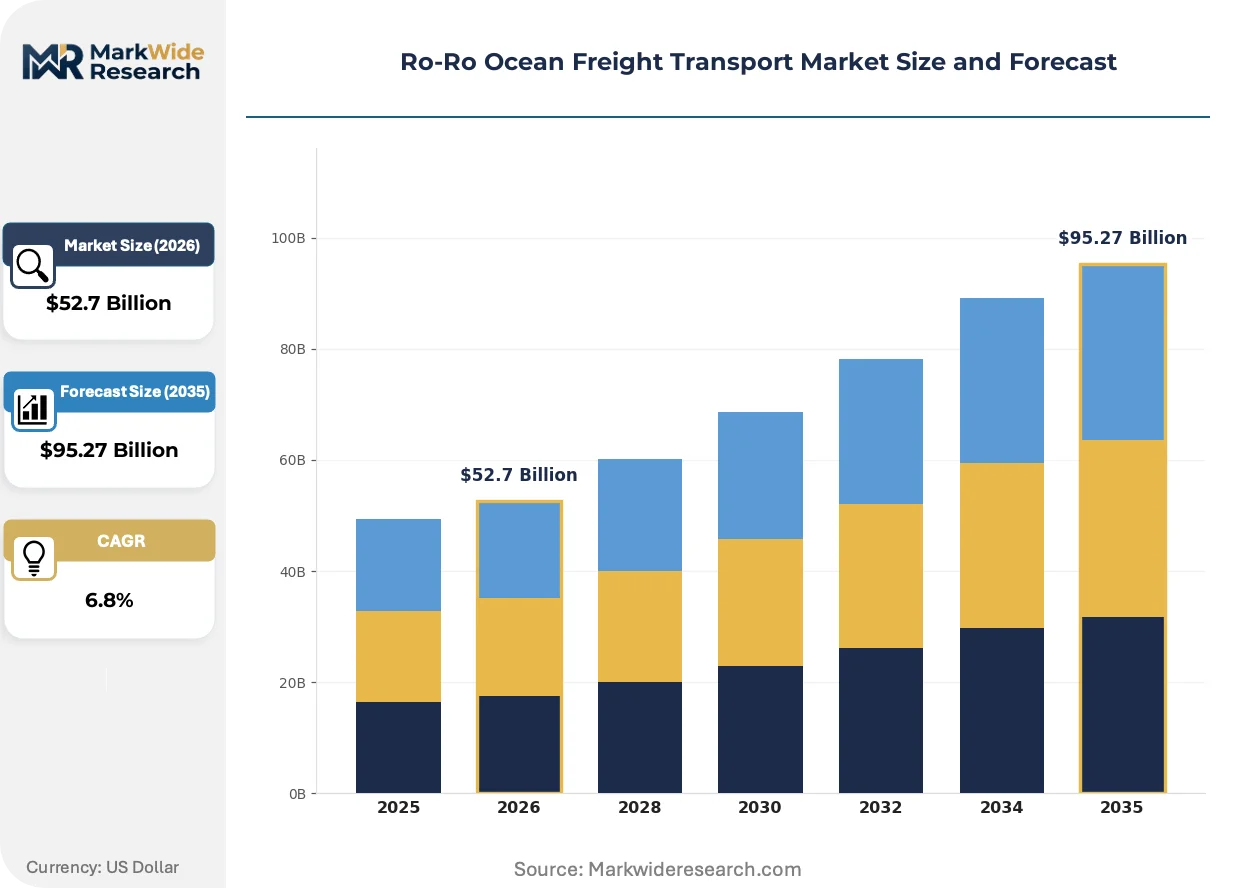
Market Dynamics
The International Maritime Organization's Carbon Intensity Indicator regulations are compressing vessel replacement cycles and forcing capital reallocation toward dual-fuel propulsion systems before traditional asset depreciation timelines expire.
Growth Catalysts
- IMO CII Compliance Deadlines:Fleet operators must retrofit main engines or retire older tonnage ahead of schedule, creating immediate demand for newbuild pure car/truck carriers with ammonia-ready architecture.
- East Asian Export Manufacturing:OEM vehicle production concentration in Japan, South Korea, and China generates sustained long-haul contract volumes toward European and North American destination markets.
- Integrated Logistics Bundling:Automotive manufacturers now contract ocean carriage together with port processing and inland distribution, expanding addressable revenue per vehicle moved.
Market Restraints
- Green Fuel Cost Premium:Ammonia and methanol bunkers trade at multiples of conventional marine fuel, eroding operating margins until carbon penalty pass-through mechanisms mature.
- Asian Shipyard Concentration:Over 80% of pure car/truck carrier newbuild capacity resides in Chinese and South Korean yards, creating single-source vulnerability for fleet renewal programs.
- Port Infrastructure Asymmetry:European and North American terminals lack ammonia bunkering infrastructure, constraining deployment of next-generation vessels on transoceanic routes.
Strategic Opportunities
- Baltic Short-Sea Electrification:Battery-hybrid Ro-Ro vessels can capture frequency-sensitive automotive and trailer traffic between Germany, Poland, and Scandinavian markets with minimal fuel infrastructure investment.
- EU FuelEU Maritime Penalty Avoidance:Operators deploying bio-LNG or e-methanol on voyages touching Rotterdam, Hamburg, or Antwerp can monetize compliance arbitrage against fossil-fuel competitors.
- Heavy Machinery Premium Segment:Construction and agricultural equipment generates freight rates 40-60% above passenger vehicles due to specialized stowage requirements and lower cargo density per deck area.
Industry Challenges
- Dual-Fuel Engineering Talent Scarcity:Ammonia and methanol propulsion systems require specialized marine engineers that classification societies including DNV and Lloyd's Register have certified in insufficient numbers.
- Retrofit Capital Intensity:Main engine conversions for CII compliance demand 15-25% of original vessel construction cost, straining balance sheets of mid-size operators without access to green shipping finance facilities.
- Terminal Automation Integration:Vehicle-handling infrastructure at major load ports operates on legacy control systems that resist real-time data exchange with vessel stowage planning software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ro-Ro Ocean Freight Transport Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Regular Service, Charter Service, Dedicated Service, Ancillary Service Vehicle Type: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, Military Equipment Operating Model: Short Sea Shipping, Deep Sea Shipping, Intermodal Transport, Port-to-Port Cargo Type: Roll-on/Roll-off, Breakbulk, Containers, Others |
| Companies Covered | Wallenius Wilhelmsen, Grimaldi Group, NYK Line, Högh Autoliners, K Line, CMA CGM Group, Mitsui O.S.K. Lines, Stena RoRo, UECC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ro-Ro Ocean Freight Transport Market Trends and Innovations
Propulsion technology pathways are diverging rapidly as regulatory certainty fragments across regional jurisdictions, forcing operators to place speculative bets on ammonia, methanol, or bio-LNG without unified fuel standards.
Wind-assisted propulsion is fragmenting the efficiency technology landscape. Rotor sails and kite systems reduce fuel consumption on long-haul automotive routes. Japanese and European operators are retrofitting existing tonnage with Flettner rotors ahead of newbuild deliveries. This fragmentation is compressing payback period assumptions for conventional hull optimization investments.
The EU's Fit for 55 package and FuelEU Maritime initiative are reshaping contract structures. Escalating penalties for fossil fuel consumption on voyages touching European ports are forcing renegotiation of long-term automotive export agreements. Deep-sea operators serving Rotterdam, Bremerhaven, and Zeebrugge are inserting fuel cost adjustment clauses with accelerated pass-through mechanics.
Automotive OEMs are consolidating logistics procurement under integrated tenders. Manufacturers now bundle ocean carriage, port processing, and inland distribution into single-source contracts rather than fragmenting across specialist providers. This concentration is most visible in German and South Korean export programs where OEMs seek end-to-end liability structures.
Ro-Ro Ocean Freight Transport Market Segmentation
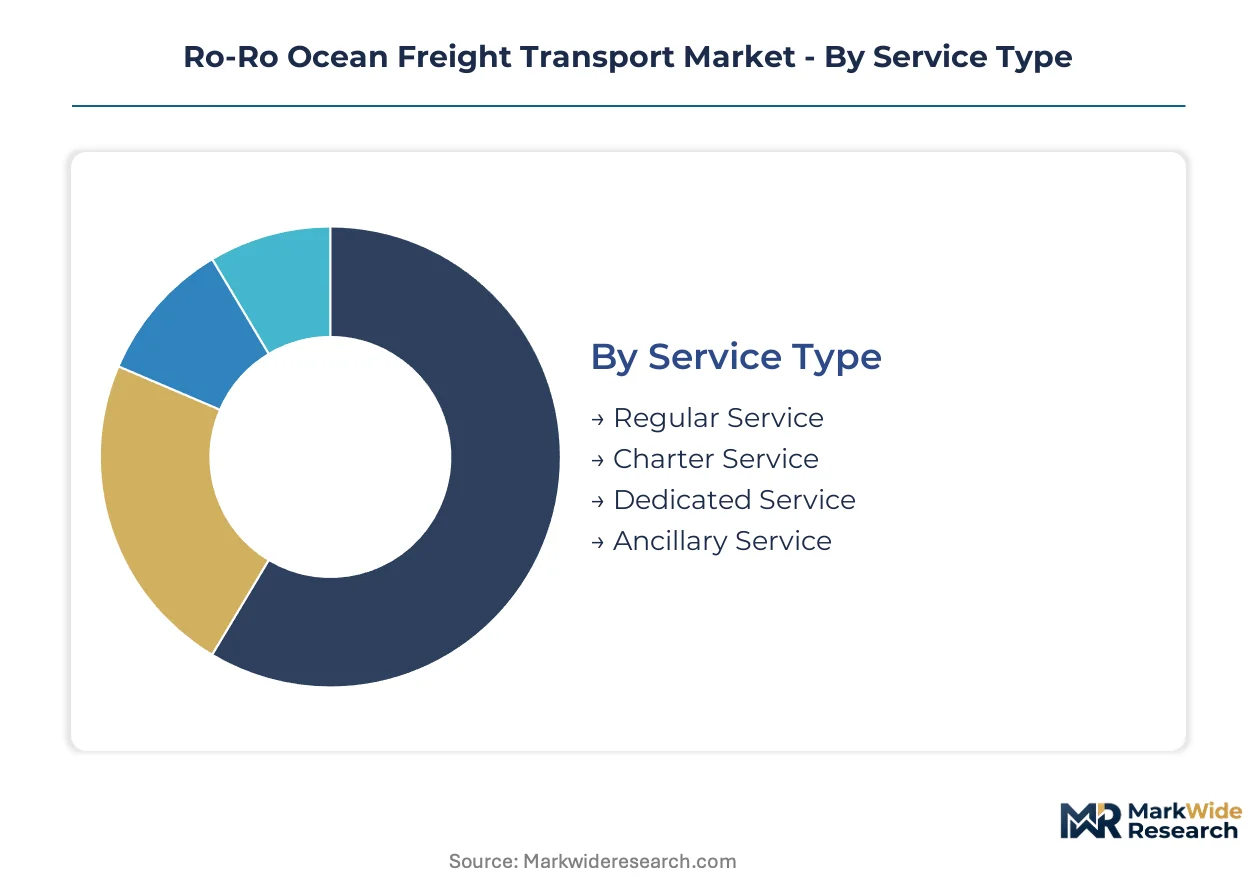
Segmentation in Ro-Ro ocean freight reveals how vessel deployment, cargo handling, and contract structures align with distinct operational economics. Each category isolates variables that determine pricing power, asset utilization, and regulatory exposure across trade lanes.
Service Type:
Regular service dominates intra-regional flows where schedule density matters, while charter and dedicated contracts concentrate on long-haul automotive export corridors from East Asian manufacturing clusters.
- Regular Service:Fixed-schedule operations with published sailing frequencies connecting major load ports. Japanese and South Korean OEMs lock in multi-year capacity commitments on transpacific and Asia-Europe strings to secure export volume visibility.
- Charter Service:Voyage-based contracts for non-recurring cargo movements or peak season overflow. European manufacturers activate spot charter coverage during model changeover periods when pipeline inventory swells beyond contracted liner capacity.
- Dedicated Service:Exclusive vessel allocation for single automotive programs or heavy equipment projects. Mining and construction OEMs deploy dedicated tonnage for outbound machinery from Chinese and German manufacturing hubs.
- Ancillary Service:Complementary offerings including customs brokerage, vehicle pre-delivery inspection, and inland rail connections. Integrated logistics bundling is expanding this segment fastest as OEMs consolidate procurement.
Regular service commands the established base. The steepest expansion runs through dedicated service as manufacturers seek captive capacity for high-value cargo programs.
Vehicle Type:
Volume concentration and freight rate premiums diverge sharply across vehicle categories, with density and handling complexity determining contract economics.
- Passenger Vehicles:High-volume, standardized units with minimal stowage variation. Production concentration in Japan, South Korea, and China generates sustained deep-sea contract demand toward European and North American destination markets.
- Heavy Machinery:Construction and agricultural equipment with irregular dimensions and weight distributions. Specialized lashings and deck reinforcement requirements command freight rate premiums 40-60% above passenger vehicles.
- Commercial Vehicles:Trucks, buses, and vans with intermediate handling complexity. European short-sea routes show strongest frequency for this segment linking manufacturing plants in Germany, Poland, and Turkey.
- Military Equipment:Armored vehicles and tactical transport with security protocols and specialized documentation. Contract structures emphasize confidentiality and government certification over pure commercial optimization.
Passenger vehicles anchor volume throughput. Heavy machinery delivers the strongest margin expansion trajectory per unit moved.
Operating Model:
Route distance and frequency requirements segment operators by asset specialization and capital intensity profiles.
- Deep Sea Shipping:Transoceanic voyages exceeding 3,000 nautical miles with vessel sizes above 7,000 CEU capacity. Long-haul automotive export contracts from East Asia deliver extended revenue visibility through multi-year OEM agreements.
- Short Sea Shipping:Regional routes under 1,500 nautical miles emphasizing schedule reliability over economies of scale. Baltic and Mediterranean operators compete on frequency for just-in-time automotive supply chains.
- Intermodal Transport:Seamless integration of ocean carriage with rail or barge feeder networks. Port congestion at Bremerhaven and Rotterdam is accelerating investment in rail-connected terminal infrastructure.
- Port-to-Port:Pure ocean leg without bundled inland services. Price-sensitive cargo owners fragment procurement across specialist providers to maintain negotiation leverage.
Deep sea shipping locks in the revenue base. Short sea shipping is climbing the fastest as regional automotive supply chains compress inventory cycles.
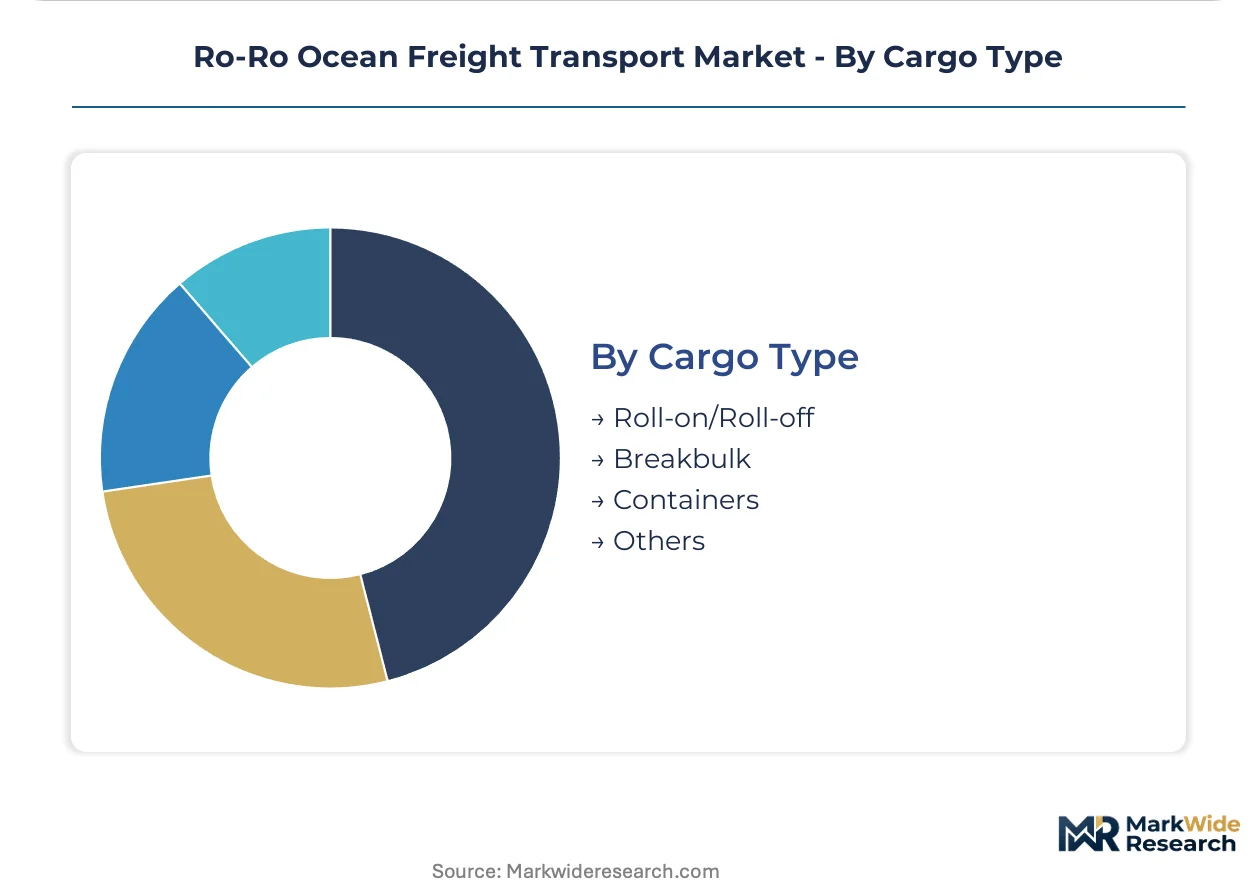
Cargo Type:
Physical handling characteristics determine vessel specification, terminal equipment, and damage liability structures.
- Roll-on/Roll-off:Wheeled cargo loaded via internal vessel ramps without crane dependency. This core segment minimizes port dwell time and eliminates hoist damage exposure for finished vehicles and mobile machinery.
- Breakbulk:Non-containerized project cargo requiring individual lifting and securing. Wind turbine components and industrial modules generate sporadic demand spikes on heavy-lift Ro-Ro vessels.
- Containers:Standardized box units carried on multi-purpose Ro-Ro vessels with cellular guides. Grimaldi Group deploys combined Ro-Ro and container capacity on Mediterranean-African routes to maximize asset utilization.
- Others:Specialized cargo including live animals, refrigerated units, and hazardous materials requiring modified stowage. Regulatory certification complexity limits competition in these niches.
Roll-on/Roll-off underpins fleet design and terminal infrastructure. Breakbulk is gaining share fastest as renewable energy project logistics expand vessel deployment flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Bremerhaven's dedicated vehicle terminals and rail-connected inland network anchor Germany's dominance in European automotive Ro-Ro logistics. Japan's Nagoya Port complex handles the densest concentration of finished vehicle exports to North American and European markets. China's Yangshan deep-water port infrastructure supports the largest pure car/truck carrier deployment base in East Asia.
Germany
Volkswagen, BMW, and Mercedes-Benz export programs drive sustained demand for transatlantic and Asia-Europe Ro-Ro capacity. The EU's FuelEU Maritime initiative imposes escalating penalties on fossil fuel consumption for voyages touching Hamburg and Bremerhaven. The Bremerhaven-Cuxhaven corridor concentrates Europe's largest vehicle-handling terminal infrastructure with direct rail links to industrial plants in Bavaria and Baden-Württemberg.
Japan
Toyota, Honda, and Nissan maintain captive ocean freight arrangements for North American and European distribution. The International Maritime Organization's Carbon Intensity Indicator regulations are accelerating fleet renewal investments by Japanese operators. The Nagoya-Osaka manufacturing belt generates the highest per-capita pure car/truck carrier deployment density globally.
China
BYD, SAIC, and Geely export expansion is reshaping long-haul automotive contract structures toward multi-year volume commitments. The Ministry of Ecology and Environment enforces dual carbon goals that constrain bunker procurement for domestic fleet operators. The Yangtze River Delta ports of Shanghai and Ningbo-Zhoushan anchor the world's largest newbuild pure car/truck carrier orderbook concentration.
United States
Detroit Three and Tesla import volumes sustain inbound Ro-Ro demand from Asian manufacturing clusters. The Environmental Protection Agency's marine diesel engine standards influence retrofit decisions for vessels calling Baltimore and Jacksonville. The Georgia Ports Authority's Brunswick terminal complex processes the highest vehicle throughput on the US East Coast with dedicated processing facilities for electric vehicle battery transport protocols.
South Korea
Hyundai, Kia, and Genesis export programs generate predictable long-haul contract volumes toward European and North American markets. The Ministry of Trade, Industry and Energy coordinates fleet modernization subsidies aligned with national carbon neutrality targets. The Busan-Ulsan industrial corridor concentrates shipyard capacity for pure car/truck carrier newbuild construction alongside automotive manufacturing plants.
Ro-Ro Ocean Freight Transport Market Competitive Landscape
Listed leaders compete with private specialists across fleet scale and terminal network control dimensions. The market structure concentrates around three to five integrated operators commanding multi-vessel fleets above 5,000 CEU average capacity, while regional specialists capture frequency-sensitive short-sea routes. Strategic archetypes include integrated logistics bundlers, pure fleet scale operators, and regional short-sea frequency players. Competitive moves center on terminal infrastructure acquisition and dual-fuel newbuild ordering programs.
Among Nordic-based integrated operators, Wallenius Wilhelmsen and Högh Autoliners exemplify the terminal-network archetype through vehicle-handling infrastructure control across major trade lanes. Grimaldi Group occupies a position within the regional diversification archetype, deploying multi-purpose vessel configurations on Mediterranean-African routes. These three operators represent distinct strategic postures: integrated logistics bundling, specialized pure car/truck carrier design, and regional route density optimization.
| Leading Market Players |
|---|
| Wallenius Wilhelmsen |
| Grimaldi Group |
| NYK Line |
| Högh Autoliners |
| K Line |
| CMA CGM Group |
| Mitsui O.S.K. Lines |
| Stena RoRo |
| UECC |
| Others |
Pricing and Supply Chain Analysis
Multi-year capacity reservation agreements with Japanese and South Korean OEMs lock in vessel utilization visibility while insulating fleet operators from spot-market volatility on transoceanic automotive export corridors. These contractual structures concentrate pricing power with carriers commanding terminal infrastructure at Bremerhaven and Nagoya, yet expose margins to fuel cost pass-through negotiations under EU FuelEU Maritime and IMO CII compliance deadlines.
Pricing Analysis
Volume-discount tiering structures separate long-term automotive OEM contracts from spot charter arrangements and project-based heavy machinery commitments. Freight rates for passenger vehicles stratify across premium, standard, and economy tiers based on vessel age, fuel technology, and bundled inland service inclusion. Cost compression in the spot charter segment is intensifying because surplus tonnage from delayed newbuild deliveries is flooding regional short-sea markets. European manufacturers demonstrate highest price sensitivity due to fragmented procurement across multiple specialist providers, while East Asian OEMs accept premium pricing for captive capacity guarantees.
Supply Chain Analysis
Just-in-time inventory strategies dominate automotive supply chains, forcing Ro-Ro operators to maintain schedule reliability above 95% on transoceanic strings linking Japan, South Korea, and China to European destination markets. Vessel construction draws from Chinese and South Korean shipyards, marine engine manufacturing rests on German and Japanese suppliers, and specialized vehicle-handling equipment feeds from Italian and Finnish producers. Single-source vulnerability concentrates in Asian shipyard capacity, where over 80% of pure car/truck carrier newbuilds originate. Distribution runs through terminal-operating divisions of integrated carriers rather than independent port operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Ro-Ro ocean freight transport market sits in early-cycle expansion as automotive OEM consolidation of logistics procurement accelerates integrated service bundling beyond traditional ocean carriage boundaries.
For Market Incumbents: Consolidate terminal infrastructure control at European load ports to defend against emerging pure fleet-scale operators lacking vehicle-handling capabilities. Deepen backward integration into port processing and inland rail distribution to capture revenue per vehicle moved under integrated tender structures. Priority investment targets ammonia-ready vessel architecture before IMO CII retrofit deadlines compress asset values. For New Entrants and Emerging Players: Differentiate on battery-hybrid propulsion technology for Baltic short-sea routes where electrification infrastructure requires minimal capital deployment against deep-sea ammonia bunkering gaps. Target frequency-sensitive automotive supply chains between Germany, Poland, and Scandinavian markets underserved by incumbent schedule density. Go-to-market positioning should emphasize carbon-neutral service tiers monetizing EU FuelEU Maritime compliance arbitrage. For Investors and Strategic Acquirers: Fleet operators with captive terminal networks at Nagoya, Bremerhaven, and Brunswick represent the most defensible acquisition archetype given infrastructure scarcity and regulatory barriers to greenfield port development. Long-term viability hinges on successful navigation of dual-fuel transition costs and green premium pass-through mechanics across the next decade. Watch for inflection when ammonia bunkering infrastructure deployment at Rotterdam and Singapore crosses commercial viability thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Vessel Newbuild Program | Ammonia-ready architecture at South Korean and Chinese yards secures IMO CII compliance ahead of retrofit cost inflation. |
| Terminal Infrastructure Acquisition | Vehicle-handling control at Bremerhaven and Brunswick locks in automotive OEM integrated logistics bundling demand. |
| Short-Sea Electrification Deployment | Battery-hybrid vessels on Baltic routes capture frequency premiums without awaiting transoceanic green fuel infrastructure. |
| Heavy Machinery Segment Expansion | Construction and agricultural equipment freight rates 40-60% above passenger vehicles improve fleet margin mix. |
| Integrated Logistics Partnership | Ocean-port-rail bundling with German and South Korean OEMs extends contract duration and revenue visibility. |
Research Methodology
A standing panel of fleet operations directors, automotive logistics procurement managers, shipyard commercial executives, and port terminal operators provided ongoing calibration across the primary research phase. Secondary validation drew from Lloyd's Register vessel databases, IMO regulatory filings, customs trade statistics, and SEC disclosures by listed shipping operators. Bottom-up capacity deployment modeling triangulated against top-down trade flow projections from vehicle production and registration data.
Consistency checks validated volume and value outputs against external benchmarks including Lloyd's List intelligence, Clarksons Research vessel orderbook tracking, and automotive OEM export volume disclosures. Segmentation dimensions modeled across the projection horizon encompassed service type, vehicle category, operating model, and cargo handling characteristics alongside regional trade lane concentration. CAGRs were derived from vessel supply-demand balance projections and contract rate escalation assumptions tied to fuel cost pass-through mechanics.
Material uncertainties — green fuel pathway commercialization delays, shipyard delivery slippage, and regulatory enforcement variance across flag states — sit outside the modeled envelope. Forecasts reflect assumptions regarding IMO CII implementation stringency and EU FuelEU Maritime penalty levels. Revision becomes warranted when ammonia or methanol bunker cost premiums compress below 150% of conventional marine fuel parity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive & Transportation
North America MUV Rental Market
Automotive & Transportation
ASEAN Cold Chain Logistics Market
Automotive & Transportation
Asia-Pacific Electric Vehicle (EV) Fluids Market
Automotive & Transportation
Europe Logistics Automation Market
Automotive & Transportation
Automotive Radiator Grille Market
Automotive & Transportation
Automotive Glove Compartment Market
Automotive & Transportation
Automotive 48V System Market
Automotive & Transportation
Automotive Speedometer Market
Automotive & Transportation
United Arab Emirates Used Car Market
Automotive & Transportation
Truck Bedliner Market
Automotive & Transportation
Engine Braking System Market
Automotive & Transportation
Germany Solar E-Bike Market
Automotive & Transportation
Smart Automotive Headlight Market
Automotive & Transportation
Transfer Case Market
Automotive & Transportation
Trailer Surge Brake Market
Automotive & Transportation
North America Passenger Information System Market