
 Revenue Assurance Market | 2026-2036
Revenue Assurance Market Size, Share, and Industry Trends Forecast 2026-2036
Revenue Assurance Market Intelligence
Real-time data streaming architectures is reconfiguring how revenue assurance platforms ingest and validate transaction records across distributed networks. Amdocs leverages its BSS/OSS heritage to anchor large telecom deployments in North America and Europe. Subex specializes in cloud-native fraud and revenue assurance suites, differentiating through AI-driven anomaly detection. TEOCO competes on network cost optimization adjacent to revenue integrity, extending its footprint among tier-one mobile operators.
Revenue assurance encompasses the systematic verification that all billable network events translate correctly into recognized revenue, employing mediation engines, call detail record reconciliation, and tariff-rating validation to close leakage points in order-to-cash workflows. The software segment dominates current spending as carriers replace legacy rule-based engines with machine-learning platforms. Cloud-based deployment is expanding fastest where operators seek elastic capacity during billing-cycle peaks without capital-heavy infrastructure commitments.
The FCC enforces billing accuracy and transparency mandates for US telecommunications providers, while GDPR shapes how European operators handle subscriber data within assurance analytics. India's TRAI imposes revenue reporting standards that drive demand for certified audit trails among mobile carriers. Stakeholders must weigh interoperability investments against vendor lock-in as hybrid deployment models span on-premises mediation and cloud-native analytics layers.
Market Dynamics
Real-time data streaming architectures are compressing the latency window between network event capture and revenue recognition, forcing carriers to rebuild mediation stacks around cloud-native ingestion pipelines rather than batch-oriented legacy frameworks.
Growth Catalysts
- 5G Service Monetization Complexity:Network slicing and dynamic QoS pricing create billions of billable micro-events requiring automated validation, expanding the addressable scope for assurance platforms across tier-one mobile operators.
- FCC Billing Accuracy Mandates:Enforcement actions against US carriers for tariff misapplication drive replacement of rule-based reconciliation engines with machine-learning anomaly detection systems.
- Cloud-Native Mediation Migration:Elastic Kubernetes-orchestrated platforms allow operators to scale compute resources during monthly billing peaks without permanent infrastructure overprovisioning.
Market Restraints
- Legacy System Integration Friction:Decades-old BSS/OSS stacks in established carriers resist API-based connectivity, extending deployment timelines and inflating professional services costs for assurance vendors.
- Specialized Talent Scarcity:Shortage of engineers fluent in both telecommunications protocols and modern data engineering creates bottlenecks in platform customization and operational handoff.
- GDPR Data Handling Constraints:European subscriber privacy requirements limit retention periods for call detail records used in reconciliation algorithms, complicating longitudinal leakage pattern analysis.
Strategic Opportunities
- India TRAI Audit Trail Certification:Mandatory revenue reporting standards for mobile carriers create demand for assured compliance platforms among Reliance Jio and Bharti Airtel as they expand 5G coverage.
- AI/ML Convergence with Streaming Analytics:Real-time federated learning across distributed network probes enables predictive leakage detection before billing cycle closure, differentiating next-generation platforms.
- Edge Computing Revenue Assurance:Multi-access edge computing deployments introduce new monetization touchpoints for low-latency enterprise services, requiring novel validation frameworks for distributed transaction chains.
Industry Challenges
- Hybrid Deployment Orchestration:Operators struggle to synchronize on-premises mediation engines with cloud-native analytics layers, creating data consistency gaps during assurance workflows.
- Interoperability Certification Delays:Vendor-specific data models impede plug-and-play integration with existing billing systems, extending proof-of-concept phases and complicating multi-vendor procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Revenue Assurance Market |
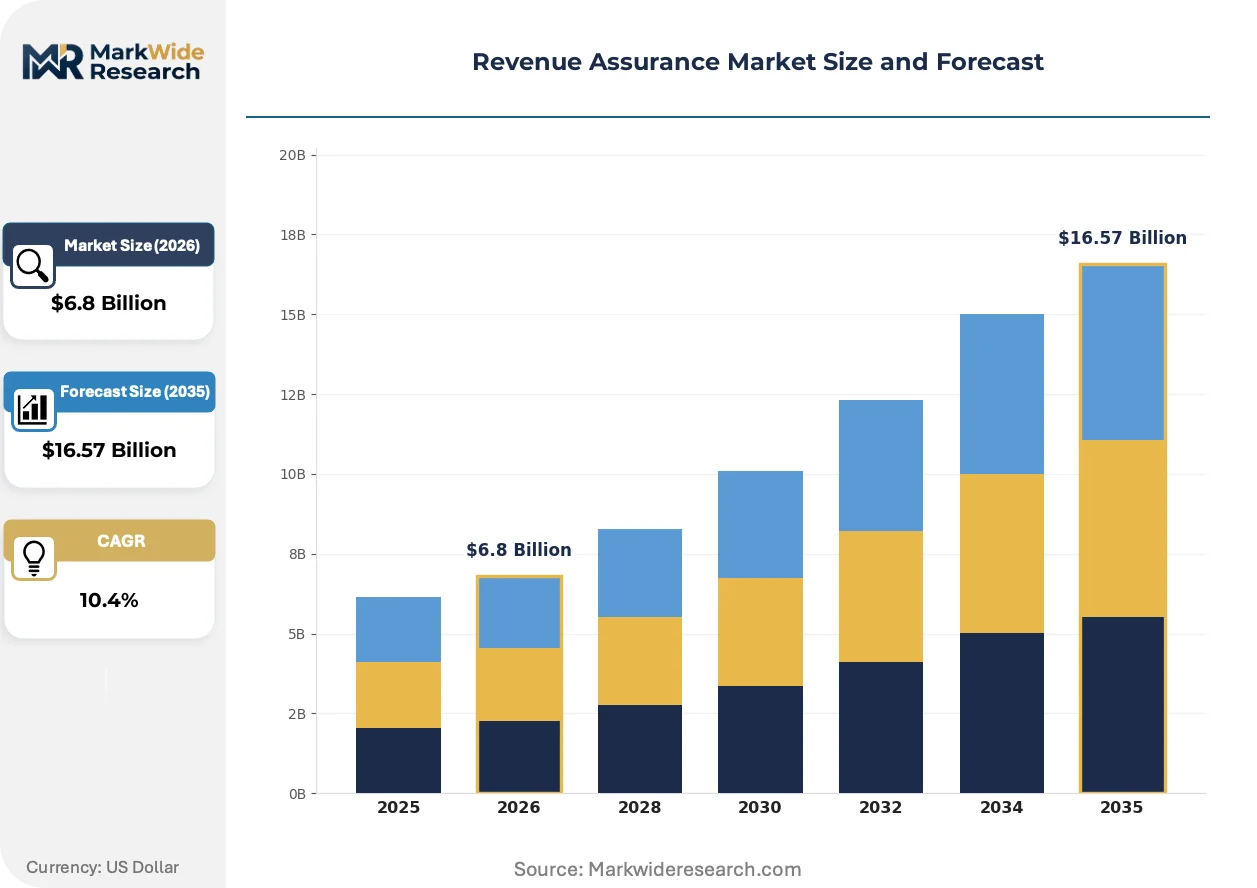
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $16.57 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Services, Consulting, Systems Integration End User: Telecommunications, Utilities, Media, Transportation Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services Solution: Fraud Management, Billing Integrity, Data Analysis, Compliance Monitoring |
| Companies Covered | Hewlett Packard Enterprise, Adapt IT, Amdocs, TEOCO, Cartesian, Subex, Digital Route, Synthesis Systems, Araxxe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Revenue Assurance Market Strategic Shifts & Innovations
Event-driven architectures are reconfiguring how assurance platforms process transaction streams, compressing detection latency from batch-cycle hours to sub-second intervals and enabling preemptive revenue protection.
Apache Kafka and Flink-based streaming pipelines are collapsing the traditional ETL bottleneck that separated mediation from analytics. Tier-one carriers in Germany and South Korea deploy these engines to validate 5G network slicing charges in real time. The structural separation between data ingestion and business intelligence layers is dissolving as unified stream processing handles both functions within milliseconds of event capture.
GDPR's data minimization requirements are reshaping how European operators architect subscriber record retention. Assurance platforms must now apply differential privacy techniques and federated learning to detect anomalies without centralizing raw call detail records. French and Italian carriers invest most heavily in privacy-preserving analytics to maintain reconciliation accuracy under stricter national interpretations of the framework.
Outcome-based assurance contracts are displacing traditional seat-license pricing among North American operators. Procurement teams at Verizon and T-Mobile now demand vendor compensation tied to measured leakage reduction rather than software subscription fees. This shift concentrates vendor risk on performance outcomes and accelerates platform replacement cycles where incumbent solutions fail to demonstrate quantifiable revenue recovery.
Revenue Assurance Market Segmentation
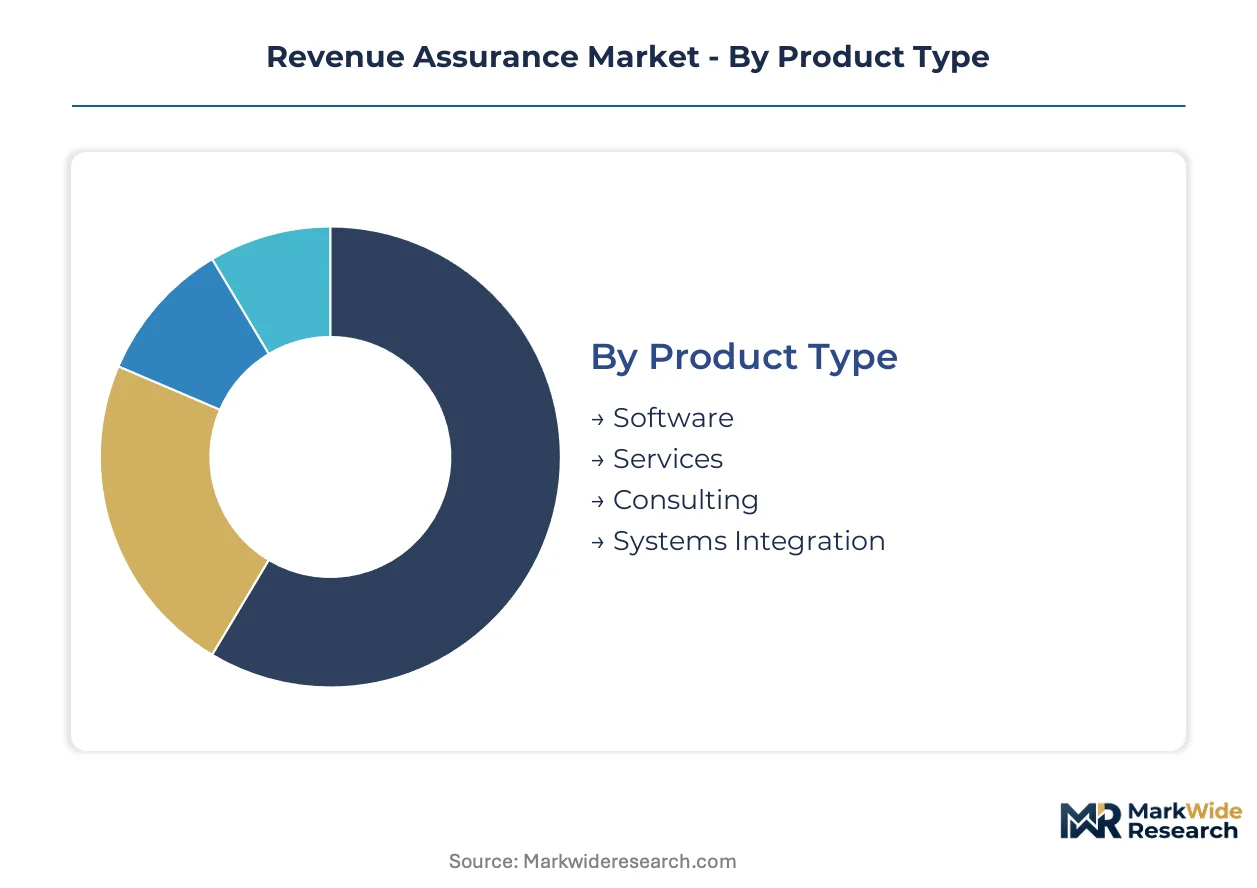
Revenue assurance platforms serve heterogeneous operational environments where deployment complexity, regulatory exposure, and data velocity vary dramatically across buyer profiles. Segmentation reveals where platform vendors must architect for elastic scale versus deep legacy integration.
Product Type:
After-sales service intensity varies sharply across product categories, with software platforms demanding continuous model retraining while consulting engagements concentrate expertise transfer risk.
- Software:Cloud-native assurance engines with embedded machine-learning pipelines for real-time anomaly detection. Tier-one mobile operators in Germany and South Korea deploy these platforms to validate 5G network slicing charges within milliseconds of event capture.
- Services:Managed assurance operations where vendors assume operational responsibility for leakage monitoring and reconciliation workflows. North American carriers increasingly outsource platform administration to address specialized talent scarcity in telecommunications protocol engineering.
- Consulting:Advisory engagements for BSS/OSS transformation and revenue leakage assessment. Projects concentrate among established carriers modernizing decades-old mediation stacks.
- Systems Integration:Deployment services bridging API-resistant legacy infrastructure with modern analytics layers. Professional services costs inflate where decades-old billing systems resist connectivity.
Software holds the largest share; momentum sits with Services as outcome-based contracting concentrates vendor risk on measurable leakage reduction.
End User:
Application context determines functional requirements, with telecommunications demanding sub-second validation latency while utilities prioritize tariff-rating accuracy across smart meter networks.
- Telecommunications:Mobile and fixed-line carriers processing billions of billable events through complex order-to-cash chains. FCC billing accuracy mandates drive replacement of rule-based engines with machine-learning platforms among US operators.
- Utilities:Electric, gas, and water providers reconciling smart meter data against tariff structures. European utilities face GDPR constraints on subscriber record retention that complicate longitudinal consumption pattern analysis.
- Media:Streaming and broadcast operators verifying content licensing revenue shares and advertising insertion metrics.
- Transportation:Logistics and transit authorities auditing toll collection, fare compliance, and usage-based service charges.
Telecommunications dominates absolute spending; Utilities exhibit the steepest expansion trajectory as smart grid investments multiply billable touchpoints.
Deployment Model:
Customer type stratification separates capital-constrained challengers seeking elastic consumption from established operators defending sunk infrastructure investments.
- On-Premises:Perpetual-license platforms deployed within carrier data centers. Established operators with decades-old BSS/OSS stacks maintain these deployments despite higher total cost of ownership.
- Cloud-Based:Kubernetes-orchestrated SaaS platforms scaling compute resources during monthly billing peaks. Elastic capacity attracts challengers avoiding capital-heavy infrastructure commitments.
- Hybrid:Architectures spanning on-premises mediation engines and cloud-native analytics layers. Synchronization challenges create data consistency gaps during assurance workflows.
- Managed Services:Fully outsourced platform operation with vendor responsibility for infrastructure, tuning, and leakage response. Procurement teams at Verizon and T-Mobile now demand compensation tied to measured revenue recovery.
On-Premises retains the largest installed base; Cloud-Based deployments are gaining share fastest where operators prioritize operational flexibility over capital control.
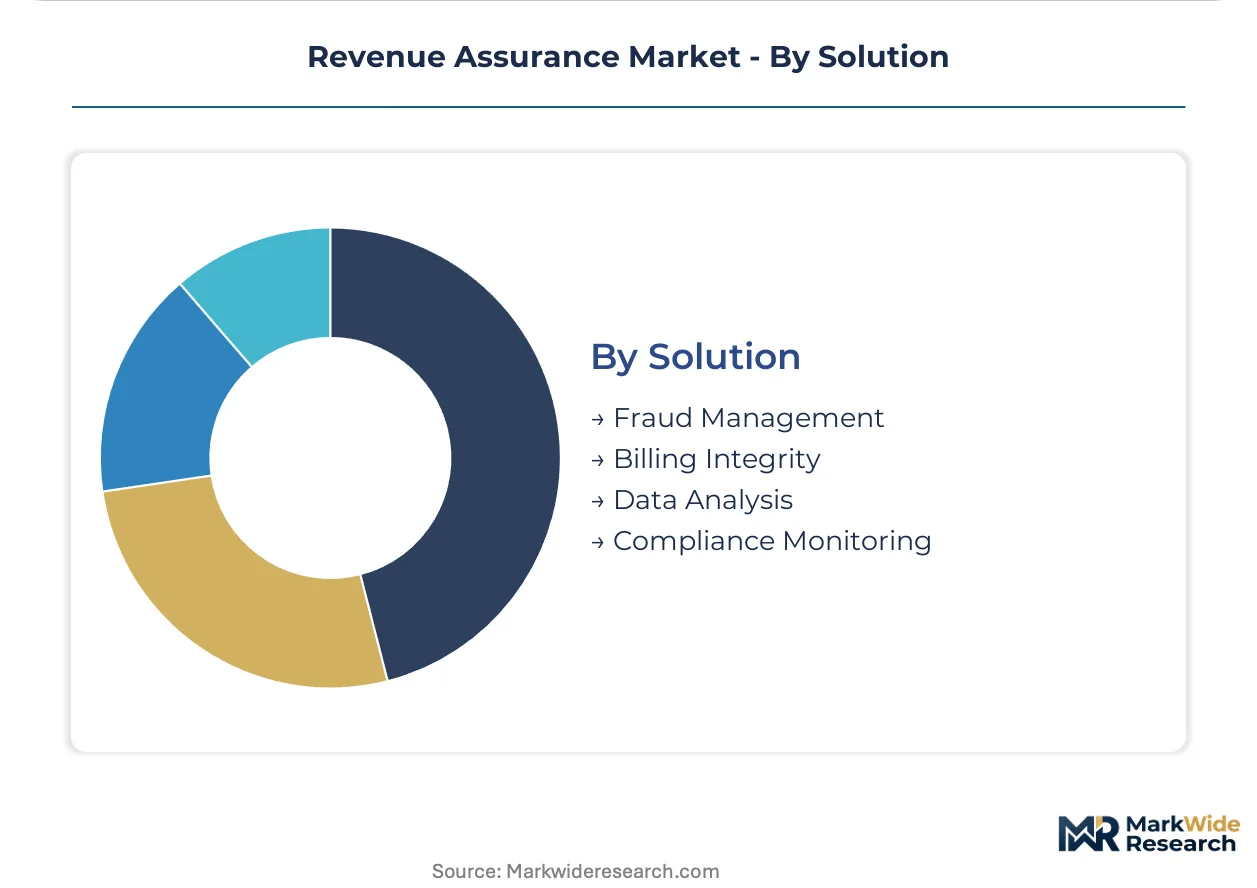
Solution:
Maturity gradients separate commoditized reconciliation functions from emerging AI-driven predictive capabilities that command premium positioning.
- Fraud Management:Real-time detection of subscription fraud, bypass schemes, and revenue diversion through network probes and behavioral analytics. Federated learning across distributed probes enables predictive detection before billing cycle closure.
- Billing Integrity:Mediation engine validation ensuring call detail records translate correctly through rating and invoicing workflows. India's TRAI mandates certified audit trails that drive demand among Reliance Jio and Bharti Airtel.
- Data Analysis:Pattern recognition across transaction streams to identify leakage root causes and tariff misapplication trends.
- Compliance Monitoring:Automated assurance that revenue recognition practices satisfy regulatory mandates across multiple jurisdictions.
Billing Integrity captures the largest share; Fraud Management shows strongest momentum as network slicing and dynamic QoS pricing multiply attack surfaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecommunications operators in the United States, Germany, India, South Korea, and the United Kingdom concentrate the highest revenue assurance platform deployments as carriers modernize billing infrastructure and expand 5G monetization.
United States
Verizon and T-Mobile drive demand for machine-learning anomaly detection as they replace legacy mediation engines. FCC billing accuracy mandates enforce strict tariff-rating validation standards. Seattle hosts a cluster of cloud-native assurance vendors developing Kubernetes-orchestrated platforms for elastic billing-cycle scaling.
Germany
Deutsche Telekom and Vodafone Germany process billions of 5G network slicing events requiring sub-second validation latency. GDPR data minimization rules limit call detail record retention periods for reconciliation algorithms. Munich and Berlin concentrate privacy-preserving analytics development for federated learning deployments.
India
Reliance Jio and Bharti Airtel expand 5G coverage across urban centers, multiplying billable touchpoints. TRAI mandates certified audit trails for revenue reporting among mobile carriers. Bangalore and Hyderabad host systems integration specialists bridging legacy BSS stacks with modern analytics layers.
South Korea
SK Telecom and KT Corporation deploy real-time streaming architectures to validate dynamic QoS pricing events. The country's national telecommunications regulator enforces billing transparency standards for converged services. Seoul anchors a cluster of edge computing assurance development for multi-access enterprise monetization.
United Kingdom
BT Group and Virgin Media O2 modernize order-to-cash workflows amid complex multi-service bundling. GDPR shapes subscriber data handling within assurance analytics platforms. London concentrates managed services providers offering outcome-based contracts tied to measured leakage reduction.
Revenue Assurance Market Key Industry Players
Channel-controlling players compete with product-specialist players across a moderately consolidated vendor landscape. Tier-one mobile operators favor established BSS/OSS heritage vendors with proven mediation engine integration. Strategic archetypes include cloud-native platform specialists, legacy system modernizers, and adjacent network optimization extenders. Dominant competitive moves encompass strategic partnerships for hybrid deployment orchestration and portfolio diversification into fraud management convergence.
Among the named vendors, Amdocs anchors the legacy-heritage tier with deep BSS/OSS integration capabilities. Subex exemplifies the cloud-native specialist archetype through AI-driven anomaly detection suites. TEOCO occupies a position at the network-cost-optimization intersection, extending revenue integrity into adjacent operational domains.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise |
| Adapt IT |
| Amdocs |
| TEOCO |
| Cartesian |
| Subex |
| Digital Route |
| Synthesis Systems |
| Araxxe |
| Others |
Cost & Logistics Intelligence
The Singapore-Dubai cable corridor carries cloud-native software licenses and specialized telecommunications engineering talent between Asia-Pacific deployment centers and Middle Eastern carrier headquarters, with freight cost volatility amplifying price spreads between on-premises perpetual licenses and elastic SaaS tiers while concentrating vendor margin pressure on systems integration services.
Pricing Analysis
Cost-plus contracts indexed to cloud infrastructure consumption dominate outcome-based assurance engagements, with North American operators at Verizon and T-Mobile tying vendor compensation to measured leakage reduction rather than fixed subscriptions. Price differentiation separates premium AI-driven anomaly detection platforms from standard rule-based reconciliation engines and economy-tier managed service bundles. Pricing pressure stems from outcome-based contracting transferring performance risk to vendors. Tier-two challengers exhibit highest price sensitivity as they prioritize elastic consumption over capital control.
Supply Chain Analysis
Export controls on GPU-accelerated analytics hardware and federated learning frameworks limit technology flows between the United States, China, and select European jurisdictions. Software development concentrates in the United States, India, and Israel, with cloud infrastructure provisioning anchored in Ireland, Singapore, and Germany. Raw material dependencies include specialized telecommunications protocol engineering talent, Kubernetes orchestration expertise, and real-time streaming compute capacity. Single-source vulnerability sits with concentrated hyperscaler cloud regions. Distribution runs through direct enterprise sales teams and systems integration partners serving tier-one mobile operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Revenue assurance market fragmentation creates entry niches as 5G network slicing multiplies validation touchpoints beyond legacy platform capabilities, splintering demand across specialized fraud management, billing integrity, and edge computing assurance domains.
For Market Incumbents: Insulate core BSS/OSS integration relationships by embedding machine-learning pipelines deeper into carrier mediation stacks, countering cloud-native challengers. Prioritize certification investments for India's TRAI audit trail mandates to defend position against Subex and emerging specialists. Extend vertical integration into managed services operations to capture outcome-based contract value.
For New Entrants and Emerging Players: Pursue white-space opportunities in multi-access edge computing assurance for South Korean and German enterprise 5G deployments, where distributed transaction validation frameworks remain underdeveloped. Target India's systems integration market bridging legacy stacks with modern analytics layers. Lead with Kubernetes-native deployment speed as primary go-to-market angle against incumbent professional services timelines.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified IT services conglomerates with undermonetized telecommunications assurance divisions, particularly those possessing dormant TRAI or GDPR compliance certifications. Long-term viability centers on AI/ML convergence with streaming analytics capabilities. Monitor 5G standalone network rollouts as inflection signal for platform replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| AI/ML Platform Integration | Embedding federated learning into Subex and Amdocs architectures enables predictive leakage detection before billing closure. |
| Strategic Partnership | Hybrid deployment orchestration agreements between cloud-native vendors and legacy system integrators resolve data consistency gaps. |
| Geographic Expansion | India certification investments capture TRAI-mandated audit trail demand among Reliance Jio and Bharti Airtel. |
| Product Launch | Edge computing assurance modules address distributed transaction validation for SK Telecom and KT Corporation enterprise services. |
| Acquisition of Specialist Firm | Purchasing Kubernetes-orchestration talent accelerates elastic billing-cycle scaling capabilities against TEOCO network optimization positioning. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with revenue assurance directors at tier-one mobile operators, BSS/OSS transformation leads, procurement officers managing outcome-based contracts, and cloud platform engineering specialists. Secondary validation drew from FCC enforcement action databases, TRAI regulatory circulars, GDPR implementation guidance from European data protection authorities, and hyperscaler capex disclosures. Bottom-up sizing of software, services, consulting, and systems integration segments triangulated against top-down telecommunications carrier IT spending benchmarks.
Calibration anchored volume and value outputs to historical platform replacement cycles, with segmentation modeling across deployment models, solution types, and end-user verticals throughout the forecast period. CAGRs derived from elasticity-adjusted adoption curves for cloud-native migration and 5G monetization complexity. Industry-specific forecast inputs included network slicing event volume projections and regulatory compliance deadline clustering across United States, German, Indian, and South Korean jurisdictions.
Sensitivities concentrate around 5G standalone deployment pace, GDPR enforcement variance across member states, and cloud infrastructure cost trajectories. Forecasts reflect documented assumptions on carrier modernization timelines and vendor consolidation patterns. Material shifts in FCC billing accuracy mandate enforcement intensity or TRAI certification requirement scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
BFSI Crisis Management Market
Risk Management and Compliance
Risk-Based Monitoring Software Market
Risk Management and Compliance
Medical Device Cyber Risk Quantification Market
Risk Management and Compliance
Travel Risk Management Services Market
Risk Management and Compliance
Sustainable Finance Market
Risk Management and Compliance
China Enterprise Risk Management Market
Risk Management and Compliance
Global Credit Risk Rating Software Market
Risk Management and Compliance
Stress Testing Services Market
Risk Management and Compliance
Global Risk and Compliance Consulting Services Market
Risk Management and Compliance
Risk Assessment Software Market
Risk Management and Compliance
Risk Analytics Market
Risk Management and Compliance
Compliance As a Service Market
Risk Management and Compliance
Financial Risk Management Software Market
Risk Management and Compliance
Clinical Risk Grouping Solutions Market
Risk Management and Compliance
Loan Compliance Management Software Market
Risk Management and Compliance
Stress Testing Solutions Market