
 Recliner Sofas Market | 2026-2036
Recliner Sofas Market Size, Share, and Industry Trends Forecast 2026-2036
Recliner Sofas Market Outlook
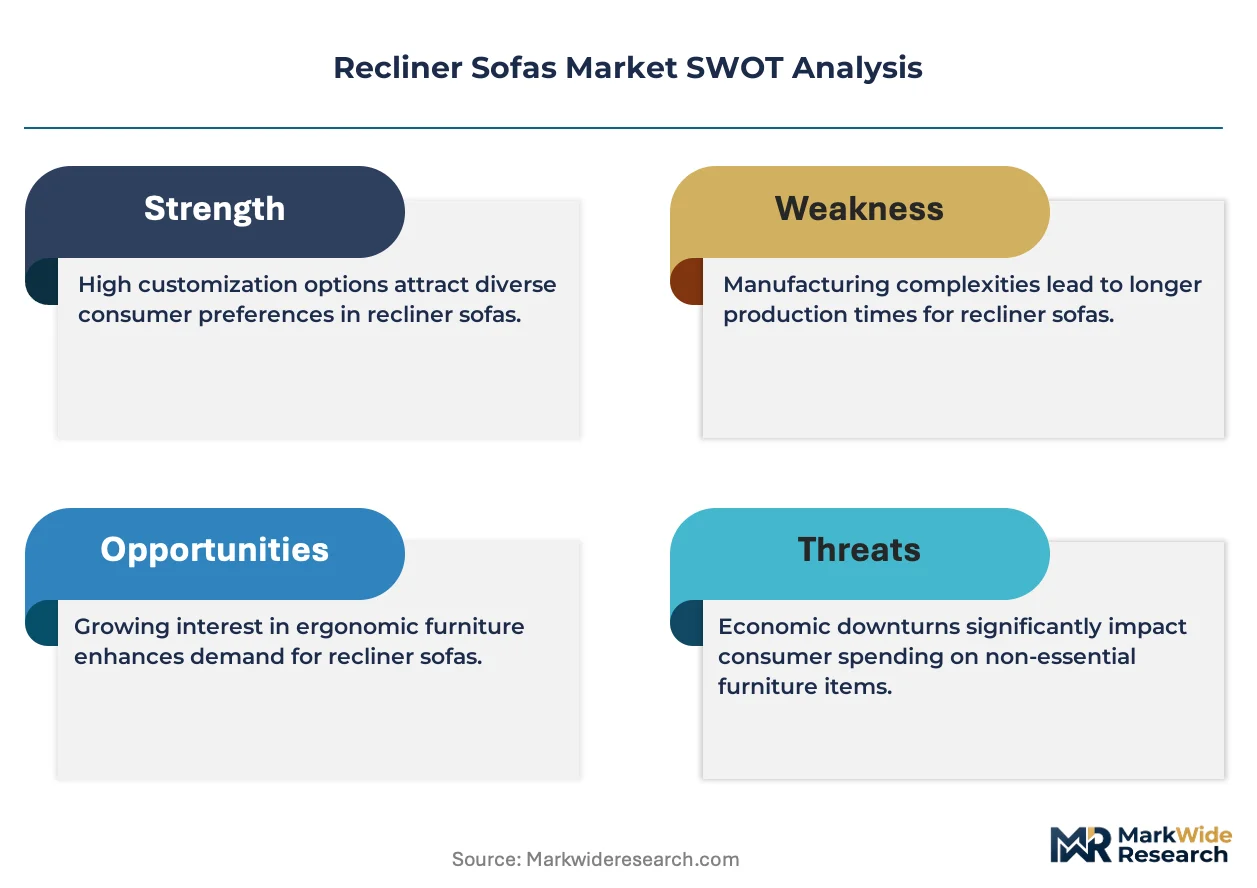
Polyurethane foam is pivoting toward bio-based and recycled-content formulations as resin cost volatility and sustainability mandates reshape bill-of-materials economics. La-Z-Boy leverages its vertically integrated North American manufacturing footprint to control foam-to-upholstery lead times. Man Wah Holdings anchors its cost position through captive production in Asia with direct distribution into Western retail channels. Natuzzi differentiates via Italian design heritage and premium leather sourcing that commands higher average selling prices in European and North American showrooms.
A recliner sofa is an upholstered seating unit incorporating an adjustable backrest and extendable footrest mechanism, typically actuated manually through a lever system or electrically via motorized linear drives with load ratings between 300 and 600 pounds; the assembly integrates hardwood or engineered plywood frames, steel reclining hardware, cushioning layers of varying density foam, and exterior upholstery materials to provide ergonomic positioning for residential relaxation, commercial lounge environments, and healthcare patient seating. Power recliners capture expanding share as dual-motor and zero-wall configurations address aging demographics and smaller urban floor plans, while leather upholstery commands the highest margin pool despite fabric and microfiber options serving broader price-accessible segments. Wall-hugger recliners represent the fastest-growing product configuration where space constraints dominate purchase criteria in dense metropolitan housing.
The EPA enforces formaldehyde emission limits through TSCA Title VI certification requirements for composite wood components, compelling frame suppliers to shift toward CARB Phase 2-compliant or NAF-rated substrates. The EU REACH regulation restricts certain flame retardant chemistries in upholstered furniture, redirecting R&D investment toward halogen-free barrier fabrics and inherent fiber fire resistance. California's TB 117-2013 smolder-resistant standard continues to influence national upholstery testing protocols beyond state borders. Stakeholders must monitor evolving chemical compliance frameworks alongside electrification reliability standards as warranty exposure on motorized mechanisms expands with unit volume.
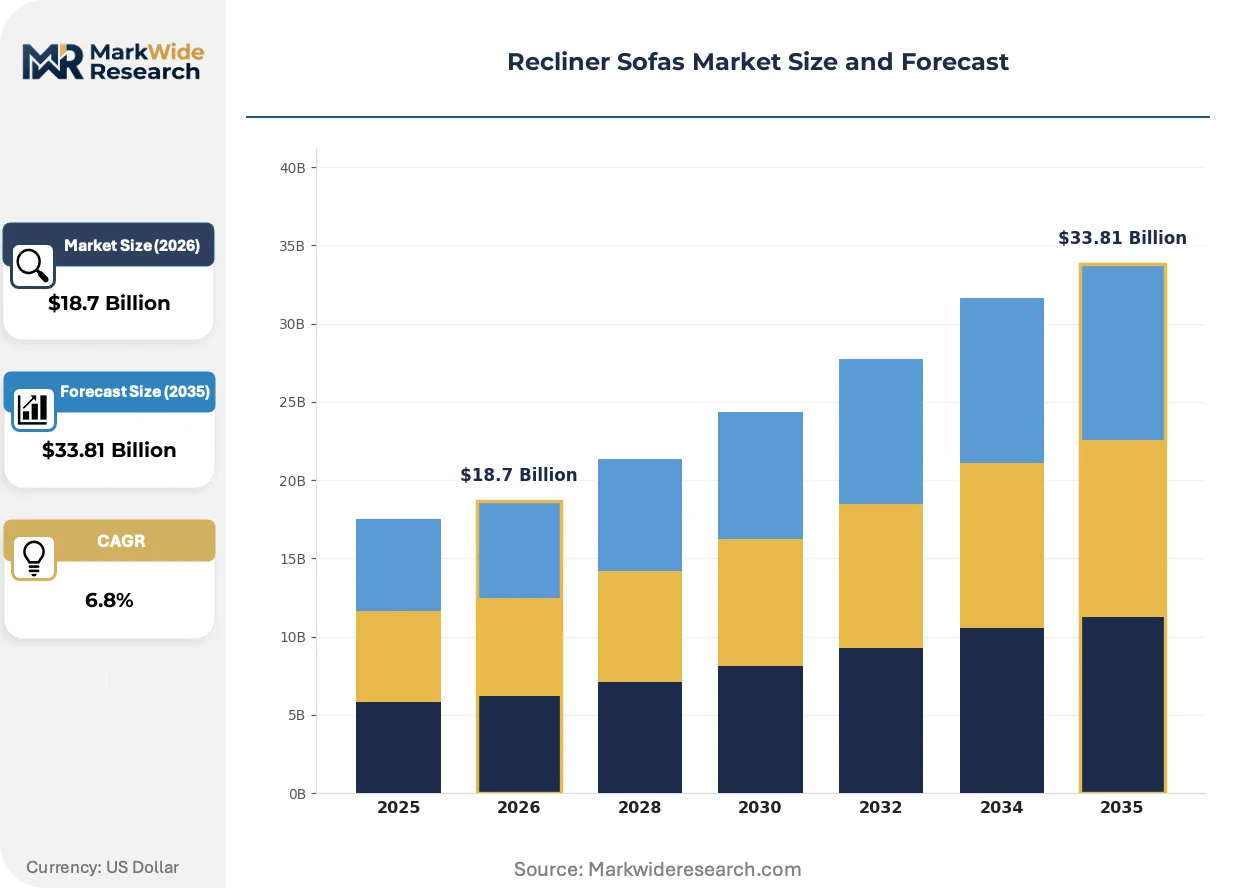
Market Dynamics
Power-adjustable seating mechanisms are displacing manual lever systems as aging-in-place residential communities and urban density constraints reshape specification priorities across residential and healthcare channels.
Growth Catalysts
- EPA TSCA Title VI formaldehyde standards:Low-VOC engineered wood mandates accelerate frame supplier consolidation toward CARB Phase 2-certified substrate producers.
- Zero-wall recliner configurations:Space-constrained metropolitan housing in Sun Belt metros drives specification of dual-motor mechanisms requiring minimal rear clearance.
- Bio-based polyurethane formulations:Resin cost volatility and sustainability procurement criteria push foam suppliers toward recycled-content and plant-derived polyol blends.
Market Restraints
- Steel reclining hardware concentration:Mechanism fabrication clusters in specific Asian manufacturing basins expose lead time vulnerability to logistics disruptions.
- Leather upholstery input cost volatility:Premium hide sourcing faces tannery capacity constraints and livestock cycle fluctuations that compress margin pools.
- EU REACH flame retardant restrictions:Halogen-free barrier fabric R&D timelines extend product certification cycles for European-bound shipments.
Strategic Opportunities
- Healthcare patient seating vertical:Acute care and long-term care facilities present untapped specification channels for pressure-relief recliner configurations.
- Direct-to-consumer distribution:Bypassing traditional furniture retail showrooms enables margin capture and consumer data accumulation.
- Water-based adhesive transition:EPA enforcement patterns create first-mover advantage for manufacturers completing VOC-free assembly process conversions.
Industry Challenges
- Motorized mechanism warranty exposure:Linear drive reliability testing protocols lag behind unit volume expansion, creating service liability concentration.
- Cross-functional compliance expertise:Simultaneous chemical, electrical, and upholstery certification requirements strain quality engineering staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recliner Sofas Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Recliners, Power Recliners, Sectional Recliners, Wall-Hugger Recliners Material: Leather, Fabric, Microfiber, Faux Leather End User: Residential, Commercial, Hospitality, Healthcare Style: Modern, Traditional, Contemporary, Vintage |
| Companies Covered | Kuka Home, Palliser Furniture, Man Wah Holdings, Stressless, Bernhardt, La-Z-Boy, Natuzzi, Pottery Barn, Ashley Furniture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recliner Sofas Market Strategic Shifts
Electrification, material science advances, and channel restructuring are compressing traditional product lifecycles while opening specification pathways outside conventional furniture retail.
Smart home connectivity is converging with power recliner actuation systems. Residential buyers in connected-home ecosystems now expect app-based position memory and voice control integration. This technology convergence is compressing differentiation timelines for mechanism suppliers and forcing upholstery brands to develop electronics partnership capabilities.
California's TB 117-2013 smolder-resistant standard continues propagating beyond state borders into national upholstery testing protocols. Manufacturers serving multi-state distribution networks must maintain dual inventory streams or universal compliance specifications. Fabric suppliers with inherent fiber fire resistance capabilities capture preference share from chemically treated alternatives.
After-sales service unbundling is disrupting traditional furniture retail channel economics. Direct-to-consumer brands now separate white-glove delivery, assembly, and extended mechanism warranties into configurable purchase tiers. This consumption-pattern shift concentrates in Sun Belt metropolitan markets where new single-family construction favors dedicated media room specifications and buyers accept self-assembly trade-offs for price accessibility.
Recliner Sofas Market Segmentation
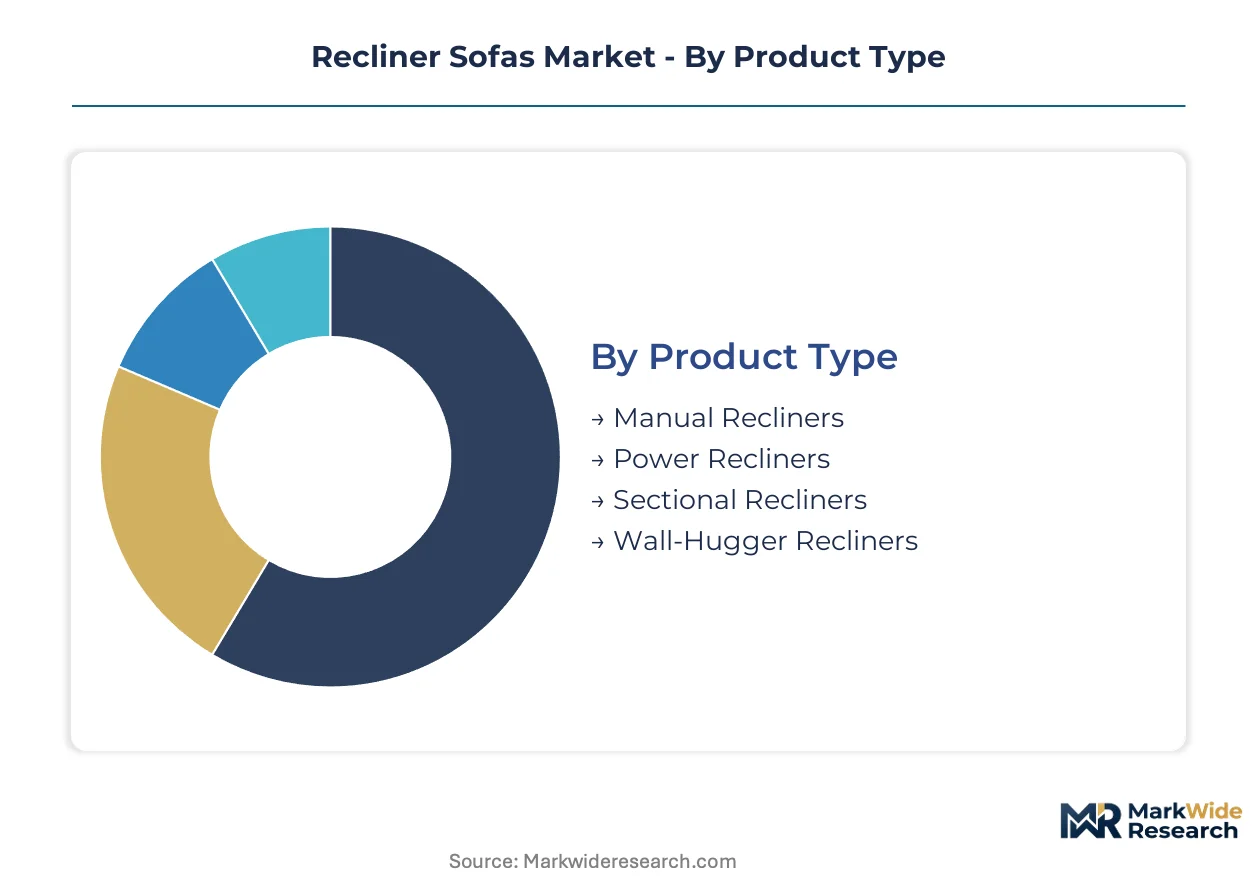
Recliner sofa purchasing cycles vary sharply across mechanism types and use environments, with electrification upgrades shortening replacement intervals in residential settings while commercial installations extend amortization periods. Material selection and end-user application create distinct margin profiles that reshape manufacturer portfolio priorities.
Product Type:
Upgrade cycles differ dramatically between manual and powered mechanisms, with electrification driving accelerated replacement demand as consumers seek connectivity features and improved ergonomics.
- Power Recliners:Dual-motor and zero-wall configurations integrate linear actuators with load ratings between 300-600 pounds, enabling precise position control. Demand concentrates in Sun Belt metropolitan housing where aging-in-place communities prioritize accessibility features; EPA compliance costs for low-VOC assembly processes compress margins for mid-tier suppliers.
- Wall-Hugger Recliners:Space-efficient mechanisms require minimal rear clearance through forward-gliding seat translation, addressing urban density constraints. Specification concentrates in dense metropolitan markets where floor-plan limitations dominate purchase criteria; dual-motor variants command premium positioning against manual alternatives.
- Manual Recliners:Lever-actuated reclining hardware with spring-return mechanisms serves price-accessible segments through simplified assembly and reduced warranty exposure.
- Sectional Recliners:Modular configurations integrate multiple reclining positions within L-shaped or U-shaped footprints, serving dedicated media room installations in new single-family construction.
Volume placements concentrate in Power Recliners; the faster expansion belongs to Wall-Hugger Recliners.
Material:
Input cost volatility and sustainability procurement criteria reshape material selection economics, with bio-based alternatives gaining specification share in premium residential channels.
- Leather:Full-grain and top-grain hides sourced from Italian and Brazilian tanneries deliver durability and aesthetic premium. Specification concentrates in North American and European showrooms where higher average selling prices absorb livestock cycle cost fluctuations; REACH-compliant tanning processes extend European certification timelines.
- Fabric:Woven polyester and cotton blends serve broad price-accessible segments through diverse pattern availability and lower maintenance requirements. Demand concentrates in family-oriented residential applications where stain resistance and washability outweigh premium aesthetics; California TB 117-2013 compliance propagates inherent fiber fire resistance specifications.
- Microfiber:Synthetic suede alternatives offer leather-like tactile properties at reduced price points, capturing specification in rental property and commercial lounge environments.
- Faux Leather:Polyurethane-coated substrates deliver consistent color matching and simplified cleaning protocols for healthcare and hospitality high-turnover installations.
Leather commands the highest margin pool; Fabric captures the broadest volume base.
End User:
Application environment dictates durability specifications, warranty terms, and distribution channel structure across residential and institutional segments.
- Residential:Single-family and multifamily housing drives specification of connected-home integration and position memory features. Demand concentrates in new construction Sun Belt metros where dedicated media rooms favor sectional configurations; direct-to-consumer distribution disrupts traditional furniture retail economics.
- Healthcare:Acute care and long-term care facilities require pressure-relief cushioning and infection-control upholstery protocols. Specification concentrates in aging-in-place communities and rehabilitation centers where motorized positioning aids patient transfer; EPA TSCA Title VI compliance mandates low-VOC frame substrates.
- Commercial:Corporate lounge and waiting area installations prioritize durability and simplified maintenance over feature complexity.
- Hospitality:Hotel suite and resort specifications balance aesthetic differentiation with commercial-grade construction standards for high-turnover environments.
Residential channels dominate absolute unit volume; Healthcare presents the steepest expansion trajectory.
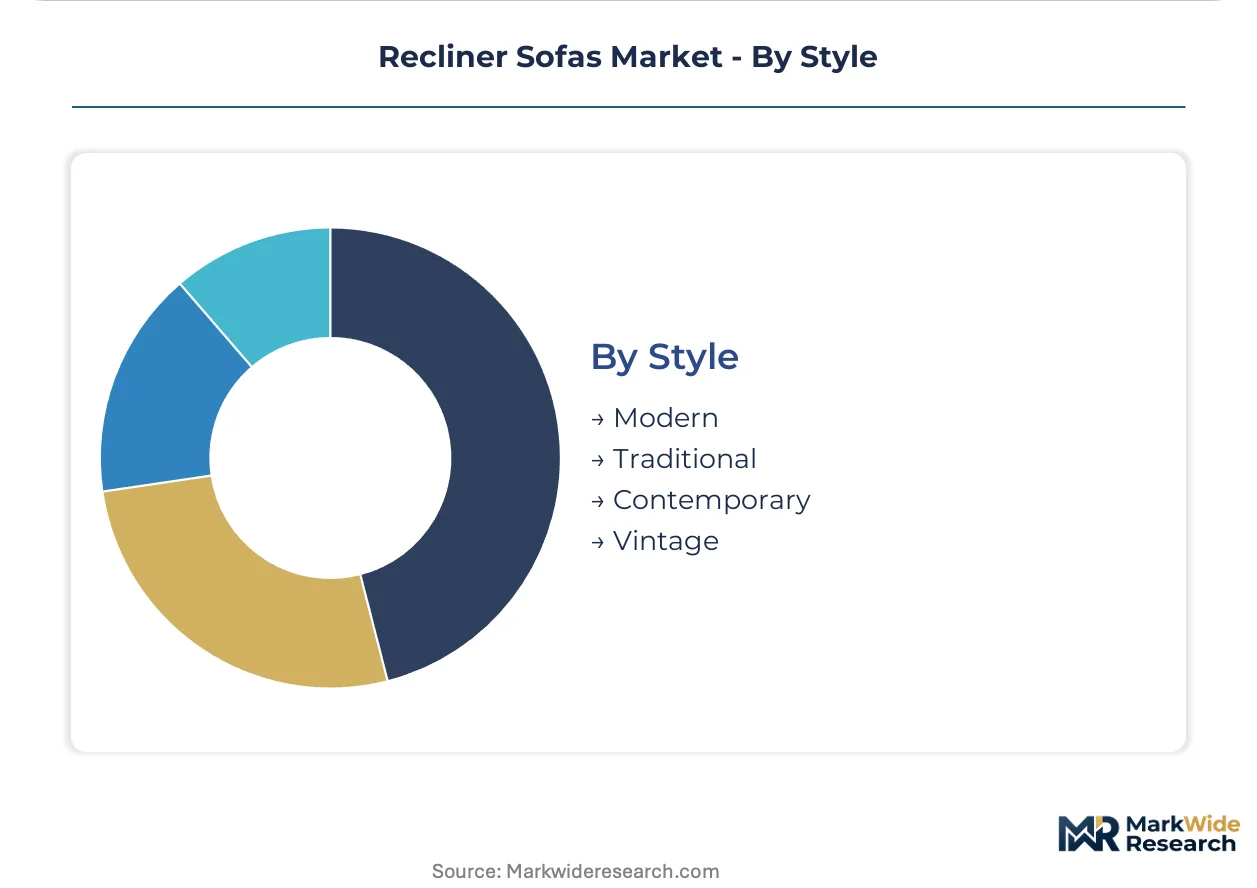
Style:
Design heritage and regional aesthetic preferences create fragmented demand patterns that complicate inventory planning for multi-market distribution networks.
- Modern:Clean lines and minimal ornamentation align with contemporary interior design trends in urban coastal markets. Specification concentrates in metropolitan areas where space constraints favor streamlined silhouettes; Italian design heritage commands premium positioning in North American showrooms.
- Traditional:Rolled arms, nailhead trim, and button-tufted detailing serve established suburban demographics and secondary market preferences. Demand concentrates in Midwest and Southeast residential markets where classic styling retains specification share against contemporary alternatives.
- Contemporary:Transitional styling bridges modern and traditional elements for flexible interior coordination.
- Vintage:Distressed leather and reclaimed aesthetic finishes capture niche specification in boutique hospitality and design-forward residential segments.
Traditional styling maintains volume leadership in suburban markets; Modern designs are gaining share fastest in metropolitan coastal channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for power-adjustable recliner sofas concentrates in the United States, where Sun Belt metropolitan construction and aging-in-place residential communities drive specification of dual-motor mechanisms with connectivity features.
United States
Single-family construction across Phoenix, Dallas, and Atlanta metros favors dedicated media room configurations with sectional recliners. The EPA enforces TSCA Title VI formaldehyde emission limits on composite wood frames, pushing suppliers toward CARB Phase 2-certified substrates. Manufacturing clusters in North Carolina and Mississippi anchor upholstered furniture production with integrated foam-to-finish capabilities.
Germany
Precision-engineered power mechanisms from Baden-Württemberg suppliers serve premium residential and healthcare seating specifications across Europe. The EU REACH regulation restricts halogenated flame retardants in upholstery, redirecting R&D toward inherent fiber fire resistance. Stuttgart-area component fabricators specialize in linear actuator integration for zero-wall configurations.
China
Guangdong and Zhejiang provinces concentrate upholstered furniture manufacturing with captive steel reclining hardware production and direct distribution into Western retail channels. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate water-based adhesive adoption in assembly processes. Dongguan industrial clusters integrate foam formulation with frame fabrication for export-oriented supply chains.
Italy
Full-grain leather upholstery from Tuscan tanneries commands premium positioning in North American and European showrooms. The EU Green Deal procurement criteria push tanneries toward REACH-compliant chrome-free tanning processes. Milan design studios anchor contemporary styling trends that propagate into global residential specifications.
India
Rising middle-class residential construction in Mumbai and Delhi-NCR metros drives demand for price-accessible fabric-upholstered recliners. The Bureau of Indian Standards mandates furniture safety testing that extends product certification timelines for motorized mechanisms. Gujarat-based textile clusters supply woven polyester blends for domestic and export upholstery applications.
Recliner Sofas Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers balance electrification R&D with material compliance investments. The vendor base separates into three tiers: integrated North American producers controlling foam-to-upholstery lead times, Asia-based fabricators leveraging captive hardware production, and European design houses commanding premium leather positioning. Strategic archetypes include vertically integrated specialists, direct-to-consumer disruptors, and healthcare-focused specification players. Competitive intensity centers on mechanism reliability warranties and low-VOC assembly process certification.
Among integrated North American producers, La-Z-Boy and Natuzzi exemplify contrasting geographic anchoring strategies. La-Z-Boy represents the domestic manufacturing archetype with in-house production of upholstered frames and cushioning systems. Natuzzi occupies a position within the European design heritage tier, leveraging Italian leather sourcing for premium showroom placement. Man Wah Holdings anchors the Asia-based cost-positioning archetype through captive production and direct distribution into Western retail channels.
| Leading Market Players |
|---|
| Kuka Home |
| Palliser Furniture |
| Man Wah Holdings |
| Stressless |
| Bernhardt |
| La-Z-Boy |
| Natuzzi |
| Pottery Barn |
| Ashley Furniture |
| Others |
Value Chain & Pricing Dynamics
Leather-upholstered premium configurations versus fabric-covered accessible tiers bifurcate the recliner sofa market, with that divergence manifesting in both margin structures and geographic sourcing footprints. EPA TSCA Title VI compliance costs for low-VOC engineered wood frames concentrate in North American assembly operations, while Asian manufacturing clusters absorb price competition through captive steel hardware production.
Pricing Analysis
Volume placements concentrate in fabric-upholstered manual recliners serving price-accessible residential channels, while leather power recliners with dual-motor mechanisms capture the highest margin pool. Price differentiation hinges on upholstery grade and EPA CARB Phase 2 certification status for frame substrates. Cost compression in mid-tier power recliners is intensifying because resin volatility in polyurethane foam formulations erodes supplier margins. First-time buyers in Sun Belt metropolitan markets exhibit the highest price sensitivity, whereas aging-in-place healthcare facility procurement shows lowest sensitivity due to specification durability requirements.
Supply Chain Analysis
Direct-to-retail and direct-to-consumer channels handle hyperscale demand from Sun Belt residential construction, while traditional furniture showrooms serve specification-heavy healthcare and hospitality segments. Manufacturing gravity centers on China for steel reclining hardware and frame fabrication, the United States for integrated foam-to-upholstery assembly, and Italy for premium leather tanning. Raw material dependencies include Brazilian and Italian hide supplies, petroleum-derived polyols for cushioning, and engineered plywood certified to CARB Phase 2 standards. Single-source vulnerability concentrates in Guangdong province mechanism fabrication clusters. Distribution runs through big-box retail partnerships, dedicated furniture chains, and emerging direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into foam formulation and motorized mechanism supply is accelerating as manufacturers seek insulation from resin cost volatility and linear actuator lead time exposure.
For Market Incumbents: Hedge against Asian hardware supply concentration by qualifying secondary mechanism suppliers in Eastern European manufacturing basins. Deepen backward integration into water-based adhesive assembly processes to capture EPA enforcement first-mover advantages and preempt compliance-driven margin compression from frame substrate suppliers. For New Entrants and Emerging Players: Launch via direct-to-consumer distribution targeting Sun Belt metropolitan markets where self-assembly acceptance enables price accessibility without showroom overhead. Target healthcare patient seating specifications where pressure-relief configurations remain underpenetrated by traditional residential-focused incumbents, leveraging zero-wall mechanism expertise for acute care facility space constraints. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated North American producers given EPA TSCA Title VI enforcement acceleration and carbon-border adjustment exposure on Asian imports. Long-term viability favors manufacturers controlling foam-to-upholstery lead times with demonstrated REACH-compliant tanning partnerships for European market access. Watch EPA enforcement patterns on formaldehyde certification as inflection indicator for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Adhesive Transition | EPA TSCA Title VI enforcement creates compliance-driven competitive moats for early converters. |
| Healthcare Vertical Expansion | Pressure-relief recliner specifications open acute care and long-term care procurement channels. |
| Direct-to-Consumer Channel Buildout | Sun Belt metro self-assembly acceptance enables margin capture and consumer data accumulation. |
| Dual-Motor Mechanism R&D | Zero-wall configurations address aging demographics and urban density constraints simultaneously. |
| Bio-Based Polyurethane Sourcing | Plant-derived polyol blends reduce resin cost volatility exposure and satisfy sustainability procurement criteria. |
Study Parameters
Independent corroboration across upholstery manufacturer executives, furniture retail category managers, healthcare facility procurement directors, and foam supplier technical leads underwrites the qualitative findings. Primary interviews with EPA compliance officers and CARB-certified substrate producers were validated against secondary sources including EPA TSCA Title VI certification databases, customs records for steel reclining hardware imports, and REACH registration dossiers for flame retardant chemistries. Bottom-up channel volume estimates triangulate with top-down construction permit data from Sun Belt metropolitan statistical areas.
Rate-of-change decomposition across mechanism type, upholstery material, end-use application, and regional regulatory cluster informs the analytical framework. Segment-level growth trajectories were derived from housing construction permits, healthcare facility bed counts, and furniture retail point-of-sale data across the projection horizon. Modeled inputs include polyurethane resin pricing indices, livestock cycle fluctuations affecting hide costs, and electrification penetration rates in aging-in-place residential communities.
Supply chain disruption, regulatory enforcement timing shifts, and raw material cost volatility are the dominant revision risks. Forecasts reflect documented assumptions regarding EPA compliance phase-in schedules and REACH flame retardant restriction implementation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture & Home Decor
North America Mattress Market
Furniture & Home Decor
India Sustainable Home Decor Market
Furniture & Home Decor
Resilient Flooring Market
Furniture & Home Decor
Mexico Home Furniture Market
Furniture & Home Decor
Luxury Vinyl Plank (LVP) Market
Furniture & Home Decor
Hospital Bedsheet and Pillow Cover Market
Furniture & Home Decor
Metal Furniture Market
Furniture & Home Decor
North America Home Furniture Market
Furniture & Home Decor
North America Residential Outdoor Gas Fire Pits Market
Furniture & Home Decor
Resilient Floor Covering Market
Furniture & Home Decor
Wall Bed Market
Furniture & Home Decor
Global OFF-THE-SHELF Second Hand Furniture Market
Furniture & Home Decor
North America Tabletop Kitchen Products Market
Furniture & Home Decor
Mattress and Mattress Component Market
Furniture & Home Decor
Saudi Arabia Vinyl Flooring Market
Furniture & Home Decor
Saudi Arabia Modular Kitchen Market