
 Publishing Consulting Services Market | 2026-2036
Publishing Consulting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Publishing Consulting Services Market Insights
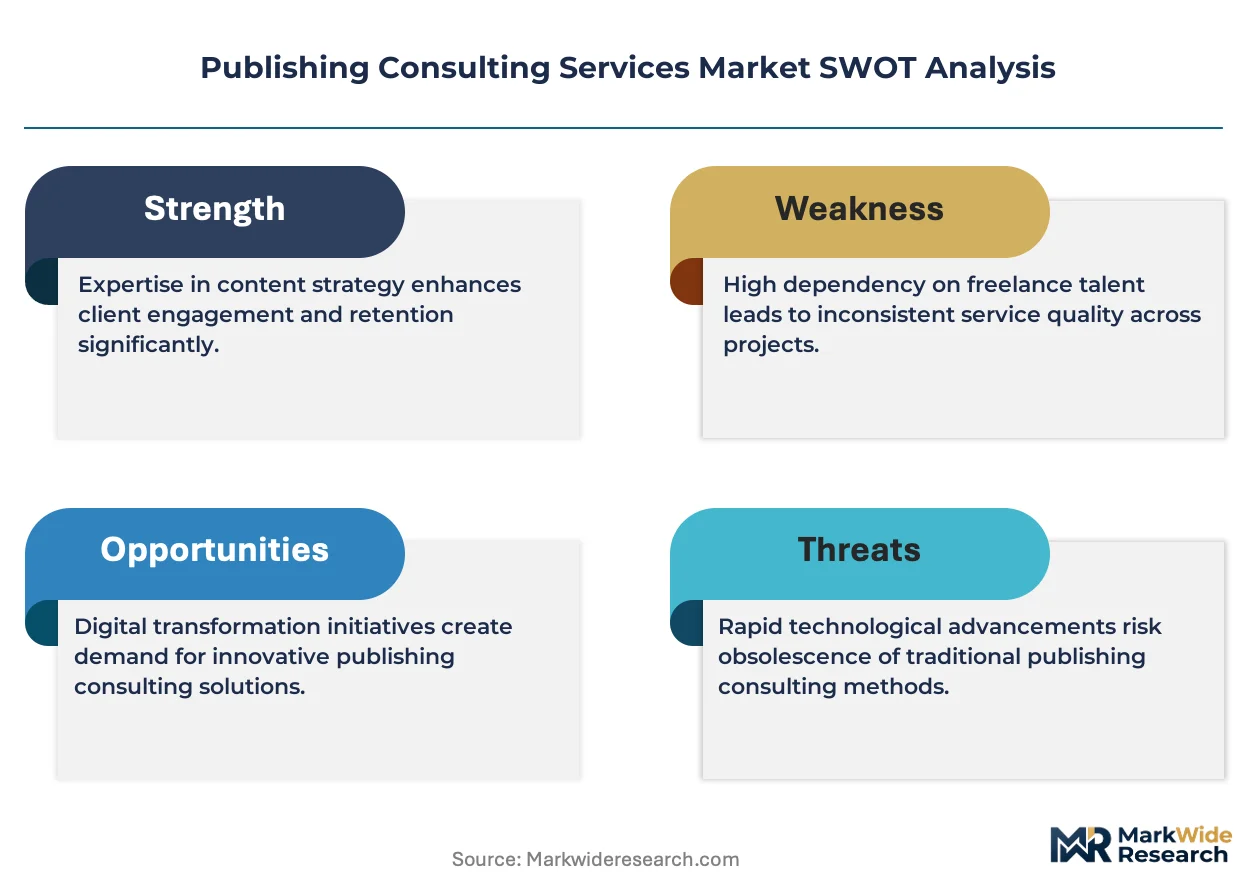
ISO 20700 certification for management consultancy services is reorganizing competitive tiers in publishing advisory, separating credentialed practitioners from unqualified competitors. Deloitte leverages its cross-industry methodology to anchor enterprise publisher transformations across multiple continents. PwC sustains deep relationships with multinational media conglomerates through integrated audit and advisory bundling. Accenture competes on technology-led publishing modernization, embedding artificial intelligence tools into editorial workflow redesigns.
Publishing consulting services encompass strategic advisory, operational restructuring, and digital transformation support delivered to content producers, distributors, and rights holders, typically spanning editorial process optimization, supply chain rationalization, and platform monetization architecture. The primary commercial purpose centers on improving margin structures and audience reach for organizations navigating print-to-digital transitions. Strategic Planning engagements command premium pricing due to C-suite access and long-term contract structures, while Content Development services face margin compression from freelance marketplace competition. Distribution Strategy work accelerates fastest as streaming, direct-to-consumer, and library licensing models proliferate across client segments. Retainer-based Delivery Models generate the most predictable revenue streams, though Workshop formats yield higher per-hour realization rates.
The EU AI Act and GDPR compliance requirements now shape how European publishers deploy automated content tools and manage subscriber data, creating specialized advisory demand. In the United States, the SEC's climate disclosure rules and FTC advertising guidance jointly determine how publicly traded publishers structure sustainability reporting and native advertising practices. Stakeholders must monitor evolving copyright frameworks and platform liability legislation as these regulatory domains increasingly determine which consulting capabilities publishers prioritize and pay for.
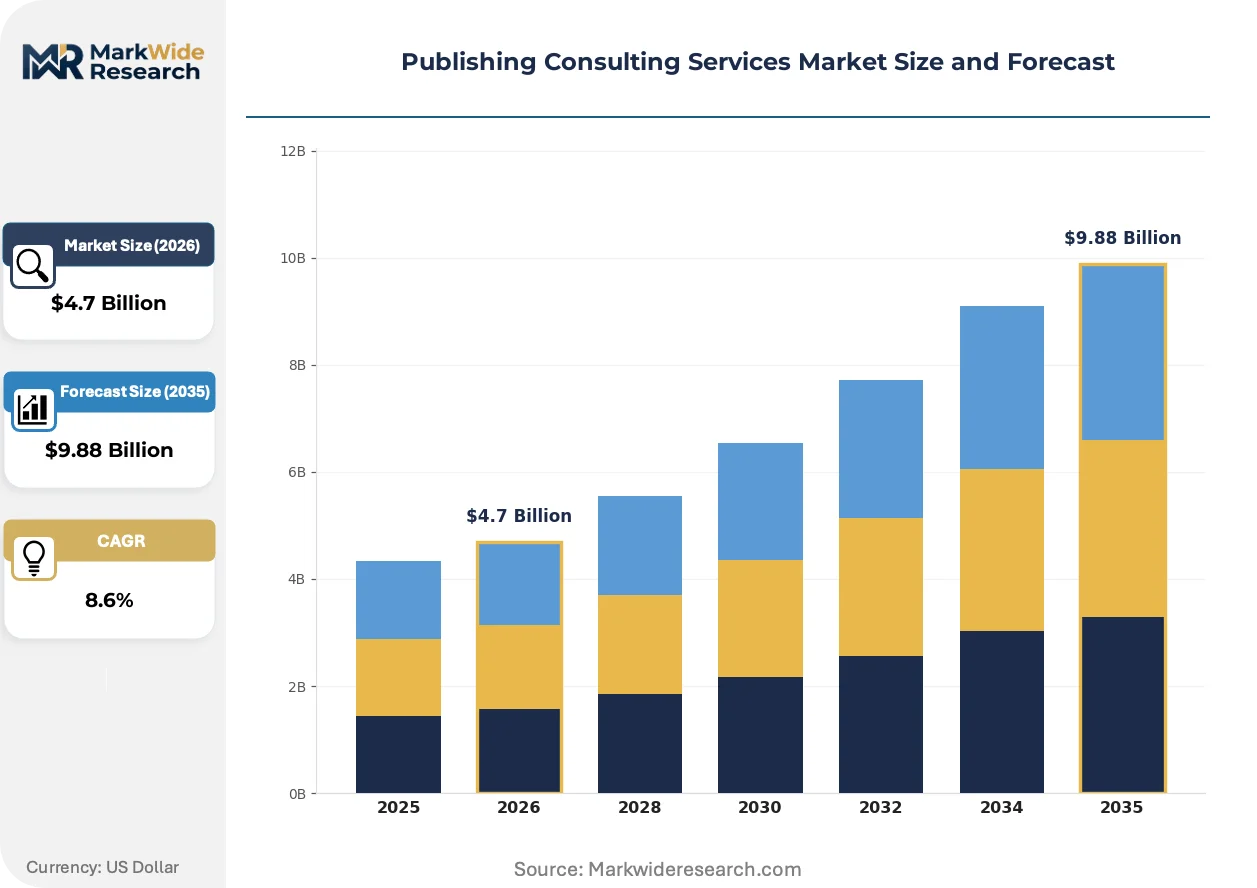
Market Dynamics
Open-access mandates from funding agencies and institutional consortia are forcing academic and trade publishers to rebuild revenue architectures, creating sustained demand for consulting engagements that restructure editorial workflows, rights frameworks, and platform economics simultaneously.
Growth Catalysts
- EU CSRD disclosure rules:Large publishers must now report sustainability metrics, generating compliance-oriented advisory contracts across carbon accounting, supply chain transparency, and ESG data infrastructure.
- Generative AI integration:Automated content tools are reshaping editorial production, requiring consultants who can architect human-AI workflow hybrids and retrain creative teams.
- Consolidation of US trade publishing:Headquarters concentration in New York and Boston maintains procurement budgets for strategic transformation programs.
Market Restraints
- Freelance marketplace saturation:Content Development services face margin compression as platforms like Upwork and Fiverr commoditize editorial and design labor.
- ISO 20700 certification scarcity:Limited pools of credentialed management consultants create supply bottlenecks for publishers seeking verified advisory standards.
- GDPR-EU AI Act compliance stacking:European publishers face overlapping data governance and algorithmic transparency requirements that extend project timelines and inflate consulting costs.
Strategic Opportunities
- Direct-to-consumer subscription architecture:Streaming and membership models for niche content verticals remain underdeveloped outside major metropolitan markets.
- Library licensing platform optimization:Institutional access negotiations and usage analytics represent white-space advisory services with recurring revenue potential.
- AI-assisted rights management convergence:Machine learning for contract extraction and royalty tracking merges with blockchain provenance verification in emerging service bundles.
Industry Challenges
- Editorial-AI workflow integration:Legacy CMS architectures resist seamless API connections with generative tools, requiring costly middleware development.
- Cross-border copyright harmonization:Territorial licensing fragmentation complicates global platform rollouts and demands specialized legal-technical consulting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Publishing Consulting Services Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Strategic Planning, Market Analysis, Content Development, Distribution Strategy Client Type: Independent Authors, Traditional Publishers, Educational Institutions, Digital Platforms Delivery Model: Consultation, Workshop, Online Training, Retainer Services Pricing Model: Hourly Rate, Fixed Fee, Value-Based, Subscription |
| Companies Covered | Deloitte, PwC, Accenture, LEK Consulting, FTI Consulting, KWF Consulting, Maverick Publishing Specialists, Publisher Production Solutions, The Editing Company Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Publishing Consulting Services Market Trends and Innovations
Advisory delivery models are fragmenting as publishers demand specialized capabilities that bridge regulatory compliance, technology implementation, and creative industry economics in integrated engagements rather than siloed projects.
Generative AI content tools are supplanting traditional editorial staffing models in mid-tier publishing houses. Academic presses and educational platforms are adopting these systems fastest, driven by production cost pressures. The technology is supplanting freelance copyediting and fact-checking roles while creating demand for consultants who can design human oversight protocols and restructure editorial department budgets.
The EU AI Act's risk classification system for automated content generation is reshaping how European publishers deploy algorithmic tools. Systems producing journalistic or educational material face transparency obligations and human-in-the-loop mandates. German and French publishers are responding by segregating AI-assisted workflows into distinct legal entities to isolate liability exposure.
Retainer-based advisory relationships are displacing project-based consulting contracts among multinational media conglomerates. Publishers now prioritize consultants who embed staff within editorial operations for 12-24 month terms. This shift concentrates most visibly in the United States, where major trade houses seek continuity through digital transformation programs rather than discrete strategy documents.
Publishing Consulting Services Market Segmentation
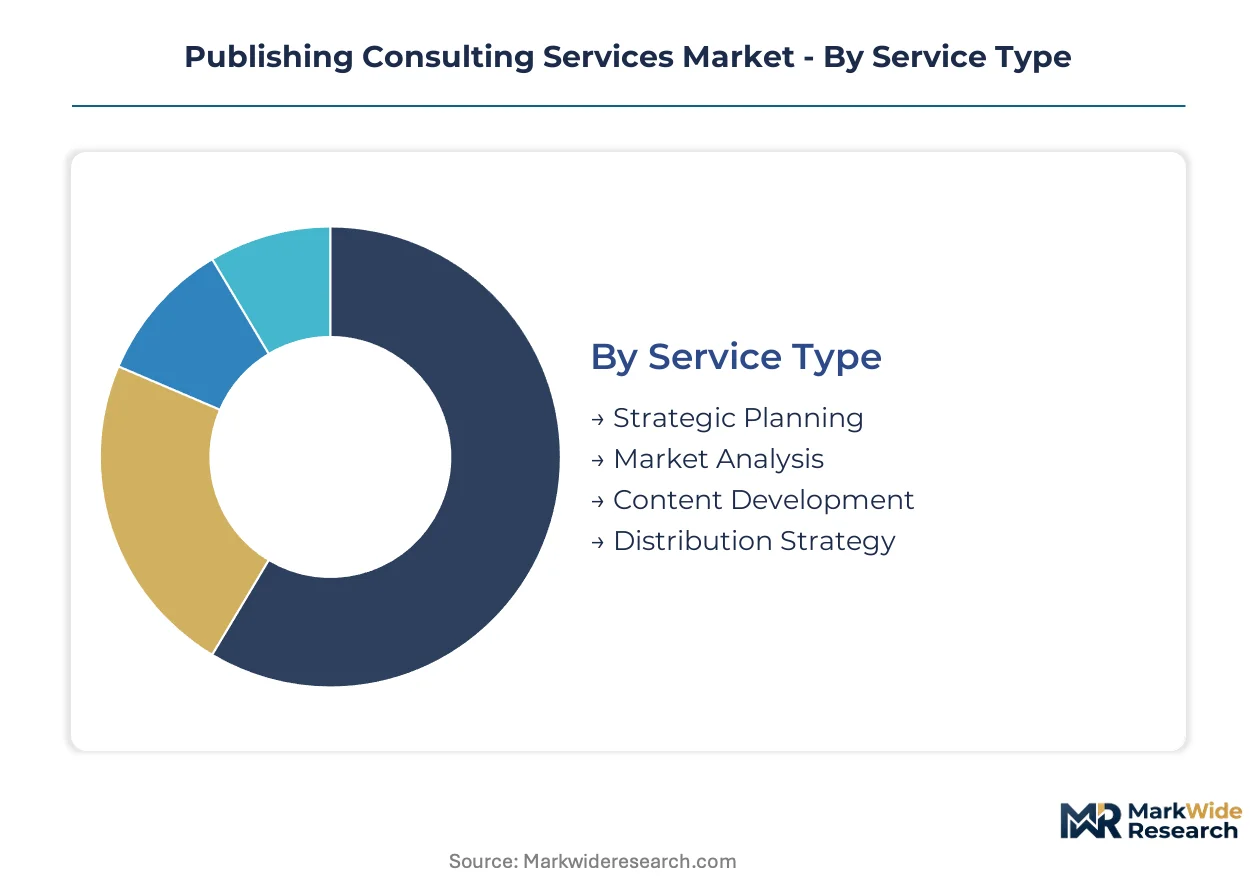
Segmentation reveals how consulting value migrates across service tiers and client sophistication levels in publishing advisory. Margin concentration varies sharply by engagement structure and buyer type, with enterprise retainers commanding multiples of project-based fees.
Service Type:
Margin pools concentrate in strategic advisory engagements that secure C-suite access and multi-year contract structures, while commoditized services face rate compression from freelance competition.
- Strategic Planning:Enterprise-grade advisory encompassing market positioning, M&A support, and organizational redesign for multinational publishers. Demand clusters in New York and Boston headquarters markets where procurement budgets sustain premium pricing.
- Market Analysis:Competitive intelligence and audience segmentation studies leveraging proprietary data assets. Academic presses in Germany and France drive specialized demand as open-access mandates force revenue model reconstruction.
- Content Development:Editorial workflow design and creative team restructuring. Freelance marketplace saturation from Upwork and Fiverr has compressed margins on standalone engagements.
- Distribution Strategy:Platform monetization architecture for streaming, direct-to-consumer, and library licensing models. This segment is climbing the fastest as digital channels proliferate across client segments.
Strategic Planning holds installed capacity. Distribution Strategy is rotating up the share rankings.
Client Type:
Volume concentrates with institutional buyers maintaining dedicated procurement functions, though independent segments show steepest expansion trajectory in platform-enabled advisory access.
- Traditional Publishers:Trade houses and academic presses requiring end-to-end transformation support across print-to-digital transitions. US-based conglomerates anchor global advisory spend through integrated audit and consulting bundles.
- Digital Platforms:Streaming services, subscription aggregators, and self-publishing infrastructure providers. These buyers prioritize technology-led modernization and AI workflow integration, expanding most quickly as new market entrants proliferate.
- Educational Institutions:University presses and learning platforms navigating funding model disruptions. EU open-access mandates and CSRD disclosure rules shape specialized compliance demand.
- Independent Authors:Individual creators accessing advisory through marketplace platforms and micro-consulting arrangements. Lowest absolute spend per engagement but highest volume growth in automated service delivery.
Traditional Publishers anchor revenue concentration. Digital Platforms are gaining share fastest in new contract originations.
Delivery Model:
Revenue predictability varies inversely with per-hour realization rates, creating strategic trade-offs between portfolio stability and margin maximization.
- Retainer Services:Embedded advisory relationships spanning 12-24 month terms with dedicated consulting staff. Multinational media conglomerates in the United States prioritize this structure for digital transformation continuity.
- Workshop:Intensive multi-day engagements delivering accelerated strategic alignment. Commands highest per-hour rates but requires senior practitioner deployment and faces scheduling constraints.
- Consultation:Project-based advisory on discrete strategic or operational questions. Subject to procurement compression and competitive bidding dynamics.
- Online Training:Scalable knowledge transfer through digital modules and virtual facilitation. Expanding access to mid-tier publishers previously priced out of traditional consulting.
Retainer Services hold installed capacity. Workshop formats are rotating up the share rankings in premium segment penetration.
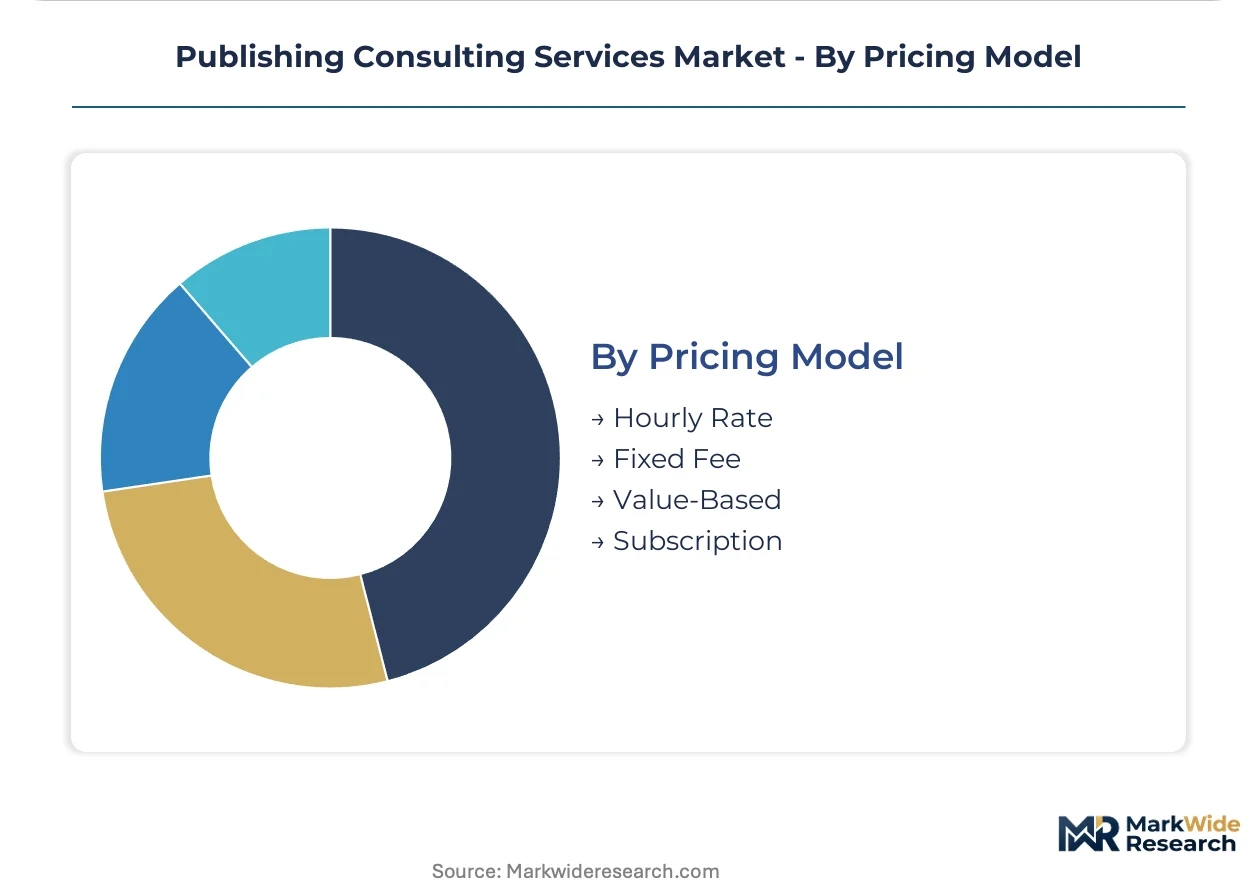
Pricing Model:
Buyer sophistication and engagement risk allocation determine pricing structure selection, with outcome-linked models capturing value from measurable transformation results.
- Value-Based:Fees tied to specific performance metrics including revenue uplift, cost reduction, or market share gains. Requires robust measurement infrastructure and aligns consultant incentives with publisher outcomes.
- Fixed Fee:Predefined scope pricing for discrete deliverables with defined timelines. Preferred by procurement functions seeking budget certainty.
- Hourly Rate:Time-and-materials billing with rate cards stratified by practitioner seniority. Faces downward pressure from freelance marketplace alternatives.
- Subscription:Recurring access fees for advisory platforms, tool licenses, and ongoing support. Emerging model for technology-embedded consulting services.
Value-Based holds installed capacity in transformation engagements. Subscription models are rotating up the share rankings as platform delivery matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU CSRD disclosure rules and SEC climate reporting mandates are reshaping procurement patterns for advisory services across major publishing markets. Publishers in jurisdictions with stringent sustainability and algorithmic transparency requirements now prioritize consultants with cross-border compliance expertise.
United States
Major trade publishing houses in New York and Boston sustain the largest advisory procurement budgets worldwide. SEC climate disclosure rules and FTC advertising guidance jointly determine how publicly traded publishers structure sustainability reporting and native advertising practices. The New York metropolitan area concentrates headquarters functions for multinational media conglomerates seeking integrated audit and consulting bundles.
Germany
Academic presses and educational platforms drive specialized demand as open-access mandates force revenue model reconstruction. The EU AI Act's risk classification system for automated content generation imposes transparency obligations on journalistic and educational material production. Frankfurt and Munich host dense clusters of publishing technology vendors and compliance advisory specialists serving Central European markets.
United Kingdom
London anchors advisory demand from multinational media conglomerates and educational platforms navigating post-Brexit regulatory divergence. GDPR compliance requirements continue shaping how UK publishers deploy automated content tools and manage subscriber data. The Greater London area maintains Europe's deepest concentration of publishing M&A advisory and rights management consulting capabilities.
France
French publishers are responding to EU AI Act mandates by segregating AI-assisted workflows into distinct legal entities to isolate liability exposure. CNIL data governance enforcement and algorithmic transparency requirements extend project timelines for consulting engagements. Paris hosts specialized advisory practices bridging regulatory compliance, technology implementation, and creative industry economics.
India
Educational platforms and self-publishing infrastructure providers represent the fastest-expanding client segment as digital penetration accelerates. The country's national information technology regulator shapes data localization requirements for platform monetization architecture. Bangalore and Mumbai concentrate technology-led publishing modernization advisory serving domestic and export-oriented content producers.
Publishing Consulting Services Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and delivery model sophistication. The market structures around three distinct layers: Big Four accounting networks with cross-industry methodology, technology-focused consultancies embedding AI tools, and boutique specialists with deep publishing sector expertise. Tier separation intensifies as ISO 20700 certification reorganizes competitive positioning between credentialed and unqualified practitioners. Consolidation pressures favor integrated audit-advisory bundling and long-term retainer relationships over project-based engagements.
Within the Big Four tier, Deloitte and PwC exemplify multinational network advantages in enterprise publisher transformations. Accenture occupies a position at the technology-led modernization vector, embedding artificial intelligence into editorial workflow redesigns. Among publishing-specialist boutiques, Maverick Publishing Specialists and Publisher Production Solutions represent the segment-focused advisory archetype with concentrated sector expertise.
| Leading Market Players |
|---|
| Deloitte |
| PwC |
| Accenture |
| LEK Consulting |
| FTI Consulting |
| KWF Consulting |
| Maverick Publishing Specialists |
| Publisher Production Solutions |
| The Editing Company Inc |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Big Four advisory networks in New York and London generates scale economies that compress price floors for mid-tier competitors while elevating premium realization for ISO 20700-certified practitioners serving enterprise publishers.
Pricing Analysis
Certification level creates the primary spread between engagement tiers, with ISO 20700-credentialed consultants commanding premium retainers from multinational media conglomerates while uncertified freelancers compete on hourly rates through Upwork and Fiverr. Value-based pricing dominates transformation engagements, linking fees to measurable revenue uplift or cost reduction outcomes. Pricing pressure intensifies in Content Development services as marketplace platforms commoditize editorial labor. Academic presses in Germany and France show highest price sensitivity due to open-access funding constraints, whereas US trade houses in New York demonstrate lowest sensitivity for strategic advisory retainers.
Supply Chain Analysis
Talent inventory lead times extend 6-12 months for consultants combining publishing sector expertise with CSRD compliance and AI Act technical knowledge, creating bottlenecks that concentrate supply in London, New York, and Frankfurt advisory clusters. The consulting supply chain draws from three primary inputs: credentialed management consultants, publishing industry veterans, and technology implementation specialists. Single-source vulnerability concentrates in EU regulatory expertise pools, where GDPR-EU AI Act compliance stacking exceeds available qualified practitioners. Distribution runs through direct partner networks and platform-enabled marketplace access for independent authors and mid-tier publishers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multinational media conglomerates that demand 12-24 month embedded advisory relationships, fragmenting procurement access for project-based specialists and favoring integrated audit-consulting bundles.
For Market Incumbents: Fortify retainer-based delivery models by embedding dedicated staff within editorial operations for multi-year terms, insulating against freelance marketplace commoditization. Deepen ISO 20700 certification pipelines to maintain tier separation from unqualified competitors. Prioritize backward integration into AI workflow tooling to capture technology-embedded consulting margins. For New Entrants and Emerging Players: White-space advisory for library licensing platform optimization remains underdeveloped outside major metropolitan markets, offering penetrable entry points for specialized practitioners. Direct-to-consumer subscription architecture for niche content verticals presents second target, particularly among academic presses navigating open-access transitions. Lead with technology-implementation credentials rather than generalist strategy positioning to differentiate from Big Four bundling. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among boutique specialists with embedded 12-24 month publisher relationships and proprietary AI workflow tooling. Long-term viability favors acquisition targets combining CSRD compliance expertise with publishing sector relationships in EU markets. Monitor EU AI Act enforcement patterns as inflection indicator for algorithmic transparency advisory demand.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20700 Certification Investment | Separates credentialed practitioners from freelance competitors in procurement evaluations. |
| AI Workflow Tooling Acquisition | Captures technology-embedded margins as generative AI reshapes editorial production. |
| CSRD Compliance Practice Buildout | Addresses mandatory sustainability disclosure requirements for large EU publishers. |
| Retainer Relationship Conversion | Replaces project-based volatility with predictable 12-24 month revenue streams. |
| EU Regulatory Expertise Expansion | Positions for GDPR-EU AI Act compliance stacking driving specialized advisory demand. |
Research Methodology
The analysis maps strategic planning, distribution strategy, content development, and market analysis service tiers, each validated through managing directors at Big Four networks, publishing house CFOs, university press procurement leads, and educational platform strategy officers. Primary interview data triangulates against secondary sources including SEC 10-K filings, EU CSRD disclosure submissions, ISO certification registries, and trade association revenue surveys. Bottom-up service-line builds reconcile with top-down market sizing across geographic clusters.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models service type, client sophistication tier, delivery model structure, and pricing mechanism as core segmentation dimensions, with regulatory compliance intensity as a publishing-specific overlay. CAGRs derive from trend-line extrapolation adjusted for mandate-driven step changes in EU disclosure rules and US climate reporting. Forecast inputs include open-access adoption curves and generative AI penetration rates in editorial workflows.
Forecasts assume regulatory continuity in EU CSRD and AI Act implementation, US SEC climate disclosure enforcement, and FTC advertising guidance; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Global Mobile Learning Market
Education & Training
US Life Coaching Market
Education & Training
Executive Education Program Market
Education & Training
Virtual Schools Market
Education & Training
Saudi Arabia E-Learning Market
Education & Training
Global Social and Emotional Learning (SEL) Market
Education & Training
Corporate eLearning Market
Education & Training
Homeschooling Market
Education & Training
Massive Open Online Courses Market
Education & Training
Child Care Services Market
Education & Training
Global K-12 Software Market
Education & Training
AI in K-12 Education Market
Education & Training
Candidate Skills Assessment Market
Education & Training
English Language Testing Market
Education & Training
M-Education Market
Education & Training
United States HR Professional Service Market