
 Private Equity Market | 2026-2036
Private Equity Market Size, Share, and Industry Trends Forecast 2026-2036
Private Equity Market Analysis
Multi-source capital deployment is decoupling from traditional bank-led syndication as direct lenders and private credit funds capture share in leveraged finance. Blackstone sustains scale advantages through its credit platform's integration with buyout origination. KKR leverages operational value creation teams embedded inside portfolio companies. Carlyle Group anchors geographic diversification through energy transition assets in Europe and Asia.
Private equity denotes pooled investment vehicles that acquire ownership stakes in privately held or de-listed companies, typically employing financial leverage and active operational governance to generate returns over holding periods. The asset class functions as an alternative investment channel designed to deliver illiquidity premiums and portfolio diversification beyond public market correlations. Buyout strategies command the largest capital commitment pools, while infrastructure allocations are expanding fastest as pension funds seek inflation-linked cash flows. Venture capital segments remain mature in North America but face margin compression from founder-friendly terms and valuation resets.
SEC oversight of private fund advisers intensified through Form PF amendments and quarterly fee disclosure mandates, reshaping how general partners report performance to limited partners. EU AIFMD II revisions extend depositary liability and liquidity management tools across cross-border fund structures, altering European fundraising mechanics. Stakeholders must monitor how regulatory fragmentation between Washington and Brussels influences fund domicile selection and investor access channels.
Market Dynamics
Dry powder accumulation exceeding $2.5 trillion is compressing holding periods and intensifying competition for quality assets across developed markets. General partners now deploy operational value creation teams earlier in the investment cycle to justify premium entry multiples.
Growth Catalysts
- SEC Fee Transparency Mandates:Quarterly disclosure requirements under amended Form PF rules are standardizing LP-GP reporting and reducing due diligence friction for institutional allocators.
- Direct Lending Expansion:Private credit funds now originate senior secured loans outside traditional bank syndication, enabling faster execution on mid-market buyouts.
- Pension Fund Reallocation:Public sector retirement systems in Canada and Australia are increasing target allocations to infrastructure and private equity sleeves.
Market Restraints
- Interest Rate Volatility:Central bank policy shifts in the United States and Eurozone are repricing leveraged finance structures and compressing debt-dependent returns.
- Valuation Multiple Compression:Public market comparables for technology and healthcare assets have declined, creating bid-ask spreads in secondary transactions.
- Regulatory Fragmentation:Divergent AIFMD II implementation across EU member states is complicating cross-border fund marketing and depositary arrangements.
Strategic Opportunities
- Energy Transition Assets:European Union Green Deal funding mechanisms and national carbon border adjustments are creating dedicated capital pools for renewable infrastructure sponsors.
- GP-Led Secondaries:Continuation vehicles and single-asset restructurings offer liquidity solutions outside traditional exit windows.
- Healthcare Services Rollups:Demographic aging in Japan and Germany is generating platform opportunities in outpatient care and eldercare facilities.
Industry Challenges
- Talent Competition for Operating Partners:Firms struggle to recruit executives with sector-specific transformation experience at portfolio company level.
- Integration Complexity with ESG Data Systems:Limited partners now require granular emissions tracking and SASB-aligned reporting that legacy portfolio company infrastructure cannot support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Private Equity Market |
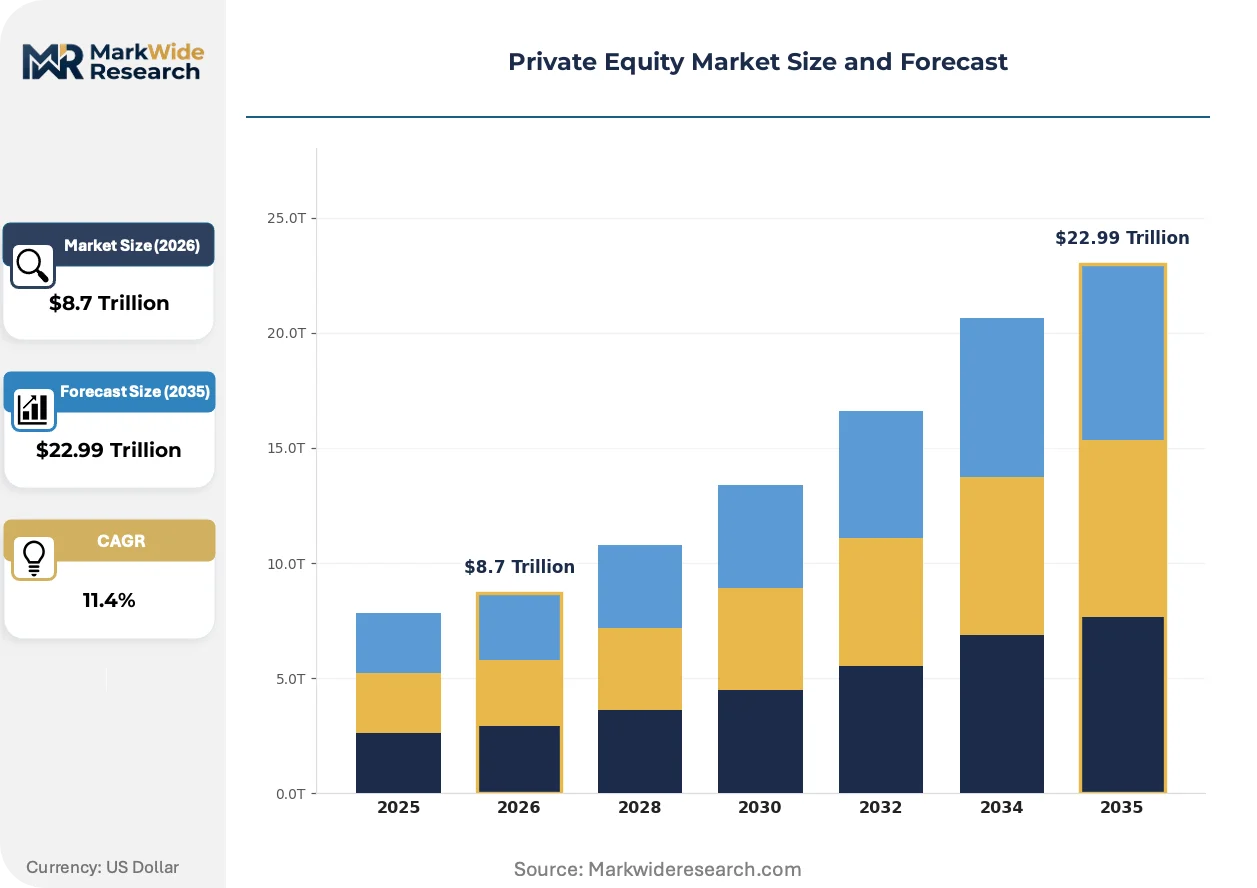
| Market Size in 2026 | $8.7 Trillion |
| Market Size in 2035 | $22.99 Trillion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Stage: Seed, Growth, Buyout, Expansion Asset Class: Venture Capital, Real Estate, Infrastructure, Distressed Investor Type: Institutional Investors, High Net Worth Individuals, Family Offices, Funds of Funds Strategy: Leveraged Buyout, Mezzanine, Secondary, Co-Investment |
| Companies Covered | Blackstone, KKR, EQT, TPG, CVC Capital Partners, Apollo Global Management, Carlyle Group, Thoma Bravo, Hellman & Friedman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Private Equity Market Emerging Trajectories
Artificial intelligence tools are embedding into due diligence workflows and portfolio monitoring, compressing analysis timelines while raising data governance requirements. Three developments are restructuring how capital deploys and returns crystallize.
Machine learning platforms for target screening and operational benchmarking are decentralizing sourcing advantages previously concentrated among largest-scale sponsors. Mid-market firms now access comparable predictive analytics through vendor partnerships. The technology is compressing information asymmetries between generalists and sector specialists.
EU AIFMD II revisions extending depositary liability and liquidity management tools are reshaping European fundraising mechanics. Cross-border fund structures now require enhanced substance in domicile jurisdictions. Small-cap buyout segments face disproportionate compliance cost burdens relative to management fee economics.
Institutional procurement of private market exposure is fragmenting away from long-dated commingled fund commitments. Separate accounts and co-investment vehicles now capture 40% of new capital flows in North America. Sovereign wealth funds in Singapore and Abu Dhabi are leading this structural renegotiation of fee and control terms.
Private Equity Market Segmentation
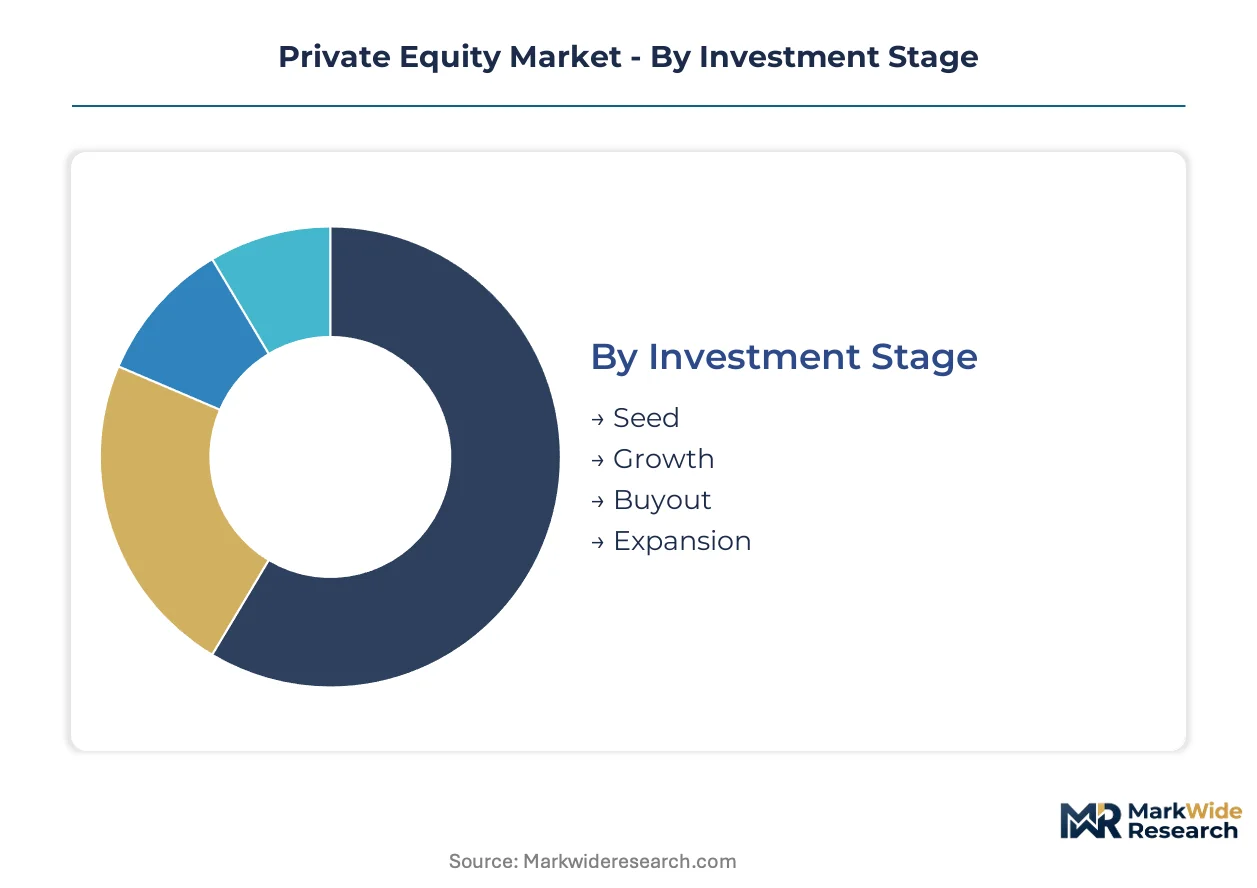
Segmentation in private equity reveals how capital flows diverge across risk-return profiles, regulatory treatment, and liquidity horizons. Each dimension shapes fund structure, fee economics, and the operational capabilities required of general partners.
Investment Stage:
Certification burdens intensify with portfolio company maturity, as SEC Form PF amendments impose quarterly disclosure thresholds that scale with asset complexity.
- Buyout:Majority-stake acquisitions of established enterprises employing financial leverage and operational restructuring. Demand concentrates in United States sponsor-to-sponsor transactions as record dry powder chases de-risked platforms with proven cash flows.
- Growth:Minority or structured equity in revenue-stage companies scaling commercial operations. European technology and healthcare assets attract capital as founder-friendly terms compress in North America.
- Seed:Early-stage equity in pre-revenue ventures with high technical risk and extended liquidity horizons.
- Expansion:Capital for geographic or product-line scaling in proven business models, often bridging toward buyout or public market exits.
Leading the category by volume: Buyout. Growing fastest: Growth.
Asset Class:
Cost tiers separate institutional-quality vehicles from retail-accessible structures, with minimum commitments and liquidity terms scaling inversely to fee compression.
- Infrastructure:Long-duration assets generating inflation-linked cash flows through regulated or contracted revenue streams. Canadian and Australian pension systems anchor demand as liability-driven investment frameworks mature.
- Venture Capital:Early-stage equity in technology and life science ventures with binary outcome distributions. Valuation resets in software and fintech are widening bid-ask spreads in secondary transactions.
- Real Estate:Direct property ownership and development platforms spanning commercial, residential, and logistics segments.
- Distressed:Opportunistic capital deployed during restructuring, bankruptcy, or special situations with event-driven return profiles.
Dominating by committed capital: Infrastructure. Expanding most quickly: Infrastructure.
Investor Type:
Margin profiles vary sharply across limited partner categories, with sovereign wealth funds commanding fee discounts and governance rights unavailable to smaller allocators.
- Institutional Investors:Public and corporate pension funds, endowments, and insurance companies with long-dated liabilities. United States public retirement systems are rebalancing toward private credit sleeves as fixed-income yields reset.
- Family Offices:Single and multi-family investment vehicles with flexible mandates and direct co-investment capabilities. Singapore and Dubai entities lead direct deal sourcing outside traditional fund structures.
- High Net Worth Individuals:Retail investors accessing private markets through feeder funds and registered vehicles with reduced minimums.
- Funds of Funds:Intermediaries providing diversified exposure and due diligence leverage for smaller capital bases.
Controlling the largest capital pools: Institutional Investors. Gaining share fastest: Family Offices.
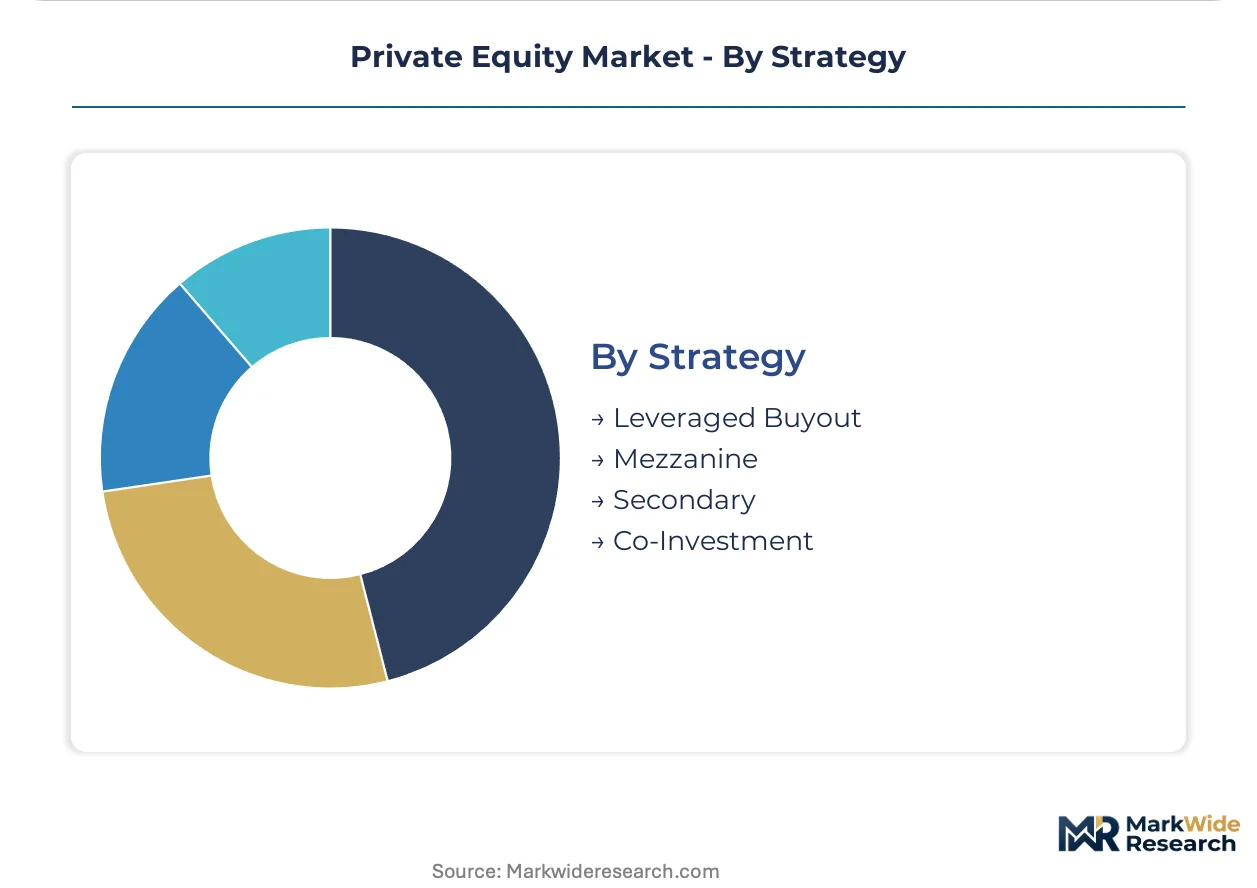
Strategy:
Supply concentration in direct lending is displacing traditional bank syndication, with private credit funds capturing mid-market leverage finance origination.
- Leveraged Buyout:Debt-financed acquisitions with operational value creation mandates. Sponsor-to-sponsor transactions in United States healthcare and technology absorb the largest transaction volumes.
- Secondary:Purchases of existing limited partner interests or portfolio company stakes, providing liquidity outside primary fundraising cycles. GP-led continuation vehicles are restructuring holding periods for trophy assets.
- Mezzanine:Subordinated debt with equity participation features, filling capital structure gaps between senior secured and common equity.
- Co-Investment:Direct stakes alongside lead sponsors, enabling fee avoidance and enhanced control for large limited partners.
Deploying the most capital: Leveraged Buyout. Climbing the fastest: Secondary.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional capital deployment concentrates in jurisdictions offering regulatory certainty and deep secondary liquidity pools. Fundraising velocity diverges sharply between established financial centers and emerging alternatives.
United States
Sponsor-to-sponsor transactions and take-private deals absorb record dry powder levels as public market valuations reset. SEC quarterly fee disclosure mandates under amended Form PF rules standardize LP-GP reporting friction. New York and Boston anchor the largest concentration of buyout origination teams.
Germany
Demographic aging generates platform opportunities in outpatient care and eldercare facilities across industrial regions. EU AIFMD II revisions extend depositary liability across cross-border fund structures. Frankfurt's fund administration cluster absorbs compliance cost burdens through specialized service providers.
United Kingdom
Secondary market liquidity and GP-led continuation vehicles attract capital seeking shorter holding periods. FCA oversight of private fund marketing maintains alignment with EU regulatory frameworks post-Brexit. London's Mayfair district retains concentration of European headquarters for global sponsors.
Japan
Corporate carve-outs and cross-border M&A provide deal flow as conglomerates streamline non-core holdings. METI guidelines on stewardship codes pressure institutional investors toward active ownership models. Tokyo's Marunouchi financial district hosts the regional headquarters for infrastructure-focused funds.
Singapore
Sovereign wealth fund co-investment vehicles renegotiate fee and control terms outside traditional commingled structures. MAS regulatory sandbox frameworks accommodate novel fund structures for family office capital. The city-state's wealth management corridor attracts Singapore and Dubai-based family offices for direct deal sourcing.
Private Equity Market Vendor Landscape
Scale-driven consolidation dominates the current landscape as operational value creation capabilities separate tier-one sponsors from mid-market competitors. The vendor base organizes around three archetypes: integrated credit-buyout platforms, sector-specialist operational firms, and diversified geographic allocators. Strategic differentiation hinges on proprietary deal origination networks and embedded portfolio company transformation teams. M&A and portfolio diversification represent the dominant competitive vectors as firms acquire specialist capabilities and expand across asset classes.
Among integrated platform operators, Blackstone and KKR exemplify the credit-buyout convergence archetype, each sustaining scale advantages through origination-syndication integration. Apollo Global Management occupies a position within the yield-focused specialist tier, while Carlyle Group anchors geographic diversification capabilities across European and Asian energy transition assets.
| Leading Market Players |
|---|
| Blackstone |
| KKR |
| EQT |
| TPG |
| CVC Capital Partners |
| Apollo Global Management |
| Carlyle Group |
| Thoma Bravo |
| Hellman & Friedman |
| Others |
Supply Flow & Price Mechanics
SOFR spreads and base rate movements cascade through private fund fee structures, compressing management fee margins at mid-market sponsors while carry multiples reset across buyout tiers. The transmission from central bank policy into LP-GP negotiations reshapes how operational value creation justifies premium pricing.
Pricing Analysis
Volume concentration at mega-funds splits pricing power from mid-market competitors, with Blackstone and KKR commanding premium carry structures through scale-driven origination advantages. Fee differentiation hinges on fund size thresholds and track record vintage, with first-time sponsors facing pressure to accept reduced management fees. Pricing compression intensifies in European fundraising as AIFMD II compliance costs erode net returns. Sovereign wealth funds exhibit lowest price sensitivity through direct co-investment rights, while smaller pension systems negotiate hardest on fee terms.
Supply Chain Analysis
Deal flow origination rests on sponsor relationships with corporate executives, investment bankers, and intermediary networks concentrated in New York, London, and Singapore. Capital deployment feeds from limited partner commitments through fund administrators, depositaries, and compliance infrastructure. Single-source vulnerability sits with top-tier legal counsel and audit firms serving concentrated sponsor rosters. Distribution runs through placement agents, consultant gatekeepers, and direct sovereign wealth fund relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry powder accumulation exceeding deployable quality assets creates a supply-constrained dynamic, with operational transformation capabilities propping pricing power for sponsors with embedded value creation teams.
For Market Incumbents: To counter direct lending encroachment on traditional leverage finance, mega-funds should deepen credit platform integration with buyout origination and anchor depositary relationships in Luxembourg and Ireland ahead of AIFMD II implementation. Capacity addition in operational partner headcount across healthcare and technology verticals preserves premium multiple justification. For New Entrants and Emerging Players: Enter via GP-led secondaries and single-asset continuation vehicles, where established sponsors seek liquidity solutions outside traditional exit windows. The most penetrable segment sits in mid-market healthcare services rollups across Germany and Japan, with demographic aging generating platform opportunities. A go-to-market angle anchored in sector-specific operating partner credentials bypasses scale disadvantages in primary fundraising. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-market sponsors with concentrated healthcare and energy transition portfolios in European jurisdictions, where regulatory fragmentation has compressed valuations. Long-term viability over the coming decade rests on operational value creation infrastructure rather than financial engineering alone. The signal to watch is LP commitment pacing to direct lending vehicles as interest rate volatility persists.| Strategic Initiative | Industry Significance |
|---|---|
| Operational Value Creation Team Expansion | Embedded transformation capabilities at portfolio companies justify premium entry multiples in competitive auctions. |
| Credit Platform Integration | Direct lending origination synergies with buyout deal flow accelerate execution timelines outside bank syndication. |
| GP-Led Secondary Vehicle Launch | Continuation funds restructure holding periods for trophy assets while crystallizing returns for legacy LP bases. |
| Energy Transition Asset Buildout | EU Green Deal funding mechanisms create dedicated capital pools for renewable infrastructure deployment. |
| Regulatory Substance Investment | Enhanced Luxembourg and Ireland depositary arrangements secure cross-border fundraising access under AIFMD II. |
Methodological Framework
SEC Form PF filings, EU regulatory registers, and pension fund annual reports formed the secondary backbone, cross-referenced with primary interviews across general partners, limited partner allocators, fund administrators, and placement agents. Bottom-up triangulation against top-down macroeconomic indicators validated capital flow estimates across the analysis window.
Historical trendline analysis of fundraising velocity and deployment pacing informed the projection framework, with segmentation modeling across investment stage, asset class, investor type, and geographic domicile. CAGRs derived from regression analysis of committed capital growth and dry powder accumulation trajectories. Forecast inputs incorporated regulatory implementation timelines for SEC and EU disclosure mandates alongside pension fund reallocation patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained interest rate volatility or abrupt LP liquidity withdrawals. The analysis reflects assumptions on regulatory implementation pacing and institutional commitment durability. A small set of named triggers—central bank policy pivots, AIFMD II enforcement variance, and sovereign wealth fund pacing shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Investment Analysis and Financial Strategies
India AMC Industry Market
Investment Analysis and Financial Strategies
Europe Online Insurance Market
Investment Analysis and Financial Strategies
Uganda Mobile Money Market
Investment Analysis and Financial Strategies
Digital Money Transfer Market
Investment Analysis and Financial Strategies
Germany Mobile Payments Market
Investment Analysis and Financial Strategies
India Health and Medical Insurance Market
Investment Analysis and Financial Strategies
Australia Education Student Loans Market
Investment Analysis and Financial Strategies
Fixed Income Asset Management Market
Investment Analysis and Financial Strategies
Cyber Insurance Market
Investment Analysis and Financial Strategies
Global Liquidity Asset Liability Management Solutions Market
Investment Analysis and Financial Strategies
P and C Insurance Software Market
Investment Analysis and Financial Strategies
South Korea Mobile Payment Market
Investment Analysis and Financial Strategies
Third-Party Banking Software Market
Investment Analysis and Financial Strategies
United States Payments Market
Investment Analysis and Financial Strategies
Hong Kong Payments Market
Investment Analysis and Financial Strategies
Online Insurance Market