
 Phytogenic Feed Additives Market | 2026-2036
Phytogenic Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Phytogenic Feed Additives Market Outlook
The capital-intensity divergence between integrated extract processors and formulation-assemblers is bifurcating competitive returns in phytogenic feed additives. Kemin Industries, LLC leverages captive botanical sourcing from South American supply bases to control raw material consistency. BIOMIN Holding GmbH anchors its position through fermentation-linked phytogenic platforms that sustain higher R&D recovery rates. Cargill, Incorporated dominates volume channels by extending its existing premix distribution infrastructure into phytogenic blends.
Phytogenic feed additives comprise bioactive compounds derived from essential oils, herbs, spices, and plant extracts, standardized for minimum concentrations of phenolics, terpenoids, or alkaloids to ensure batch-to-batch efficacy in animal diets. These compounds function primarily as antimicrobial growth promoters, gut health modulators, and antioxidant stress reducers in commercial livestock operations. Essential oils command the widest formulation penetration due to their concentrated bioactivity and established dosing protocols, while plant extracts represent the fastest-expanding category as extraction technologies improve yield economics. The poultry application segment leads absolute consumption volumes, though aquaculture emerges as the highest-margin growth vector where residue regulations are most stringent.
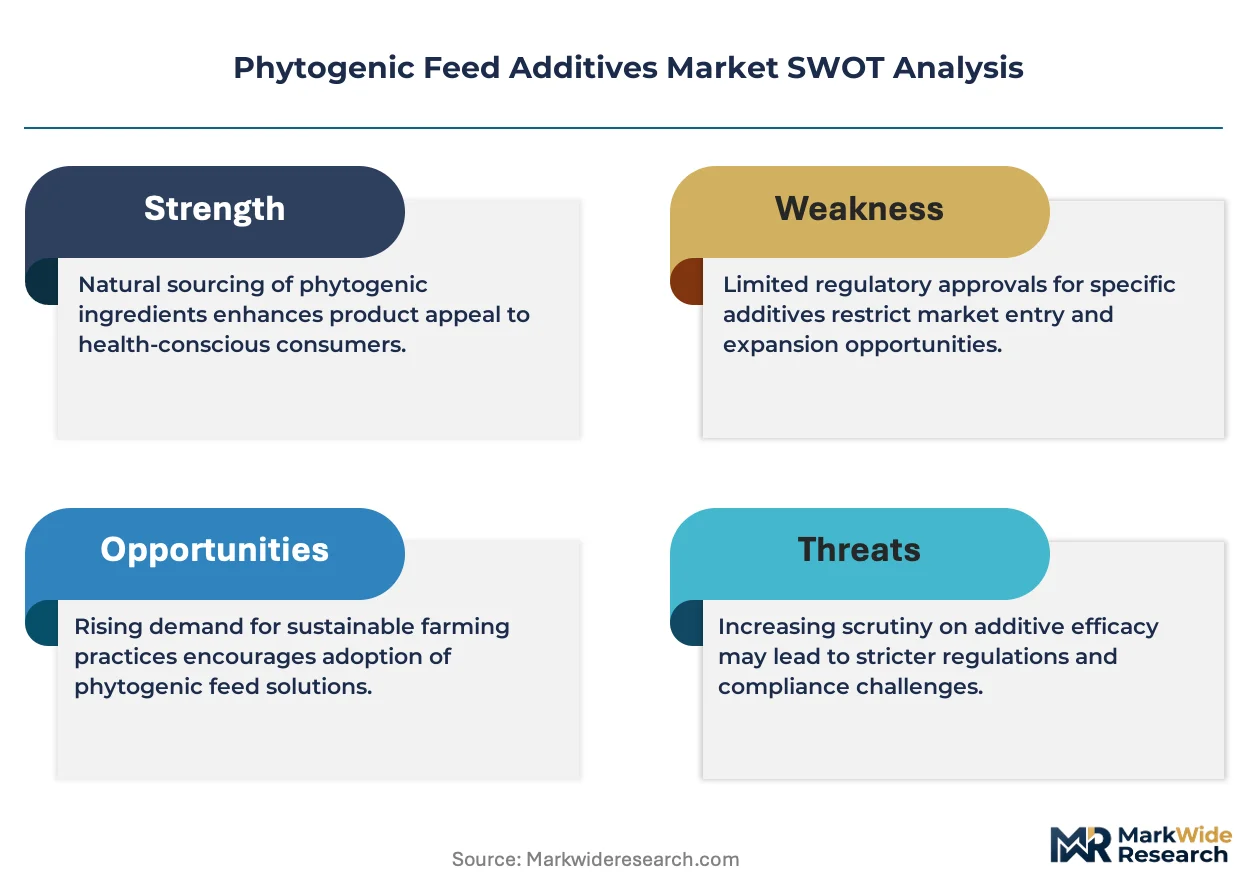
The EU Green Deal and F-Gas Regulation tighten antimicrobial residue ceilings across member states, directly elevating phytogenic alternatives in regulated protein supply chains. FDA guidance on veterinary feed directives in the United States restricts medically important antibiotic use, creating parallel demand pull for botanical performance enhancers. Stakeholders must monitor evolving maximum residue limits from EFSA and national regulators to align product registration pipelines with jurisdiction-specific compliance windows.
Market Dynamics
EU Green Deal residue thresholds and FDA veterinary feed directives are compressing synthetic growth promoter margins while elevating botanical alternatives across regulated protein supply chains. This regulatory compression is fragmenting competitive returns between integrated extract processors and formulation-assemblers.
Growth Catalysts
- EU F-Gas Regulation:Tightening antimicrobial residue ceilings across member states directly elevates phytogenic alternatives in regulated poultry and aquaculture operations.
- Poultry integrators in Brazil:Expanding phytogenic inclusion rates in antibiotic-free programs creates sustained demand pull for standardized essential oil formulations.
- Supercritical CO2 extraction:Advancing yield economics for plant extracts is displacing solvent-based methods and improving batch-to-batch phenolic consistency.
Market Restraints
- Raw material volatility:Essential oil feedstocks from South American botanical supply bases face climate-driven harvest inconsistency and price swings.
- Regulatory fragmentation:Divergent maximum residue limits between EFSA, FDA, and national regulators create multi-jurisdiction registration friction and compliance cost stacking.
- Synthetic alternative cost pressure:Conventional acidifiers and medium-chain fatty acids retain price advantages in unregulated or price-sensitive channels.
Strategic Opportunities
- Aquaculture in Southeast Asia:Residue-sensitive shrimp and finfish operations present highest-margin growth vector for phytogenic gut health modulators.
- Precision fermentation:Convergence of microbial cultivation with botanical extraction enables novel bioactive compound libraries beyond traditional plant sourcing.
- EU Green Deal incentives:Carbon border adjustments and sustainable protein mandates create preferential procurement pathways for certified-sustainable phytogenic suppliers.
Industry Challenges
- Phytochemist talent scarcity:Standardization of phenolic, terpenoid, and alkaloid concentrations requires specialized analytical chemistry expertise that outpaces current training pipelines.
- Certification timeline compression:EFSA novel food and feed additive approvals demand 18-36 month toxicology dossiers that delay product commercialization.
- Legacy premix integration:Formulating phytogenics into existing mineral-vitamin matrices without bioactive degradation requires process reengineering and capital retooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phytogenic Feed Additives Market |
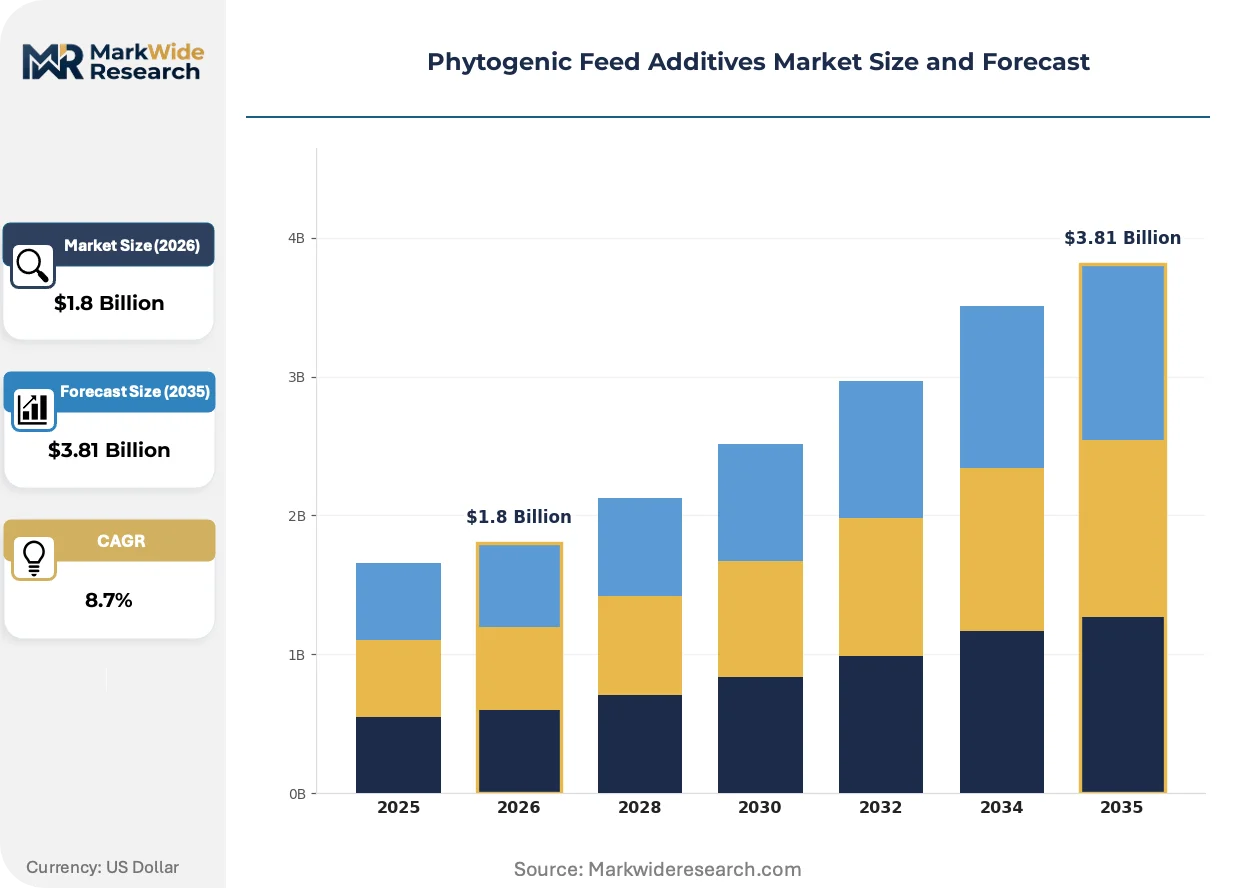
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Herbs, Spices, Plant Extracts Application: Poultry, Ruminants, Swine, Aquaculture Form: Liquid, Powder, Granules, Capsules Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Kemin Industries, LLC, BIOMIN Holding GmbH, Cargill, Incorporated, Phytobiotics Futterzusatzstoffe GmbH, Delacon Biotechnik GmbH, Archer Daniels Midland Company, Alltech, Inc., Novus International, Inc., Koninklijke DSM N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phytogenic Feed Additives Market Strategic Shifts
Extraction technology maturation and regulatory chemistry are fragmenting traditional competitive moats while creating new entry points for specialized processors. Three developments are compressing incumbent advantages.
Encapsulation technologies for essential oil stabilization are fragmenting formulation value chains. Liposome and cyclodextrin shell systems protect volatile terpenoids from feed processing heat and rumen degradation. Poultry integrators in Germany and Brazil are adopting these protected forms at accelerating rates. The technology is fragmenting margins between raw extract suppliers and finished premix formulators by shifting value capture downstream.
REACH and EU Green Deal alignment is tightening substance authorization pathways for feed additives. The F-Gas Regulation's extension to processing emissions is elevating botanical alternatives over synthetic manufacturing routes. Aquaculture operators in Mediterranean member states face the strictest residue enforcement and are responding with accelerated phytogenic substitution timelines.
Buyer consolidation among protein multinationals is compressing supplier negotiation cycles. Direct procurement relationships between integrators and extract processors are displacing traditional distribution intermediaries. This channel restructuring is most visible in German and Austrian production clusters where Delacon and BIOMIN anchor vertically integrated supply relationships.
Phytogenic Feed Additives Market Segmentation
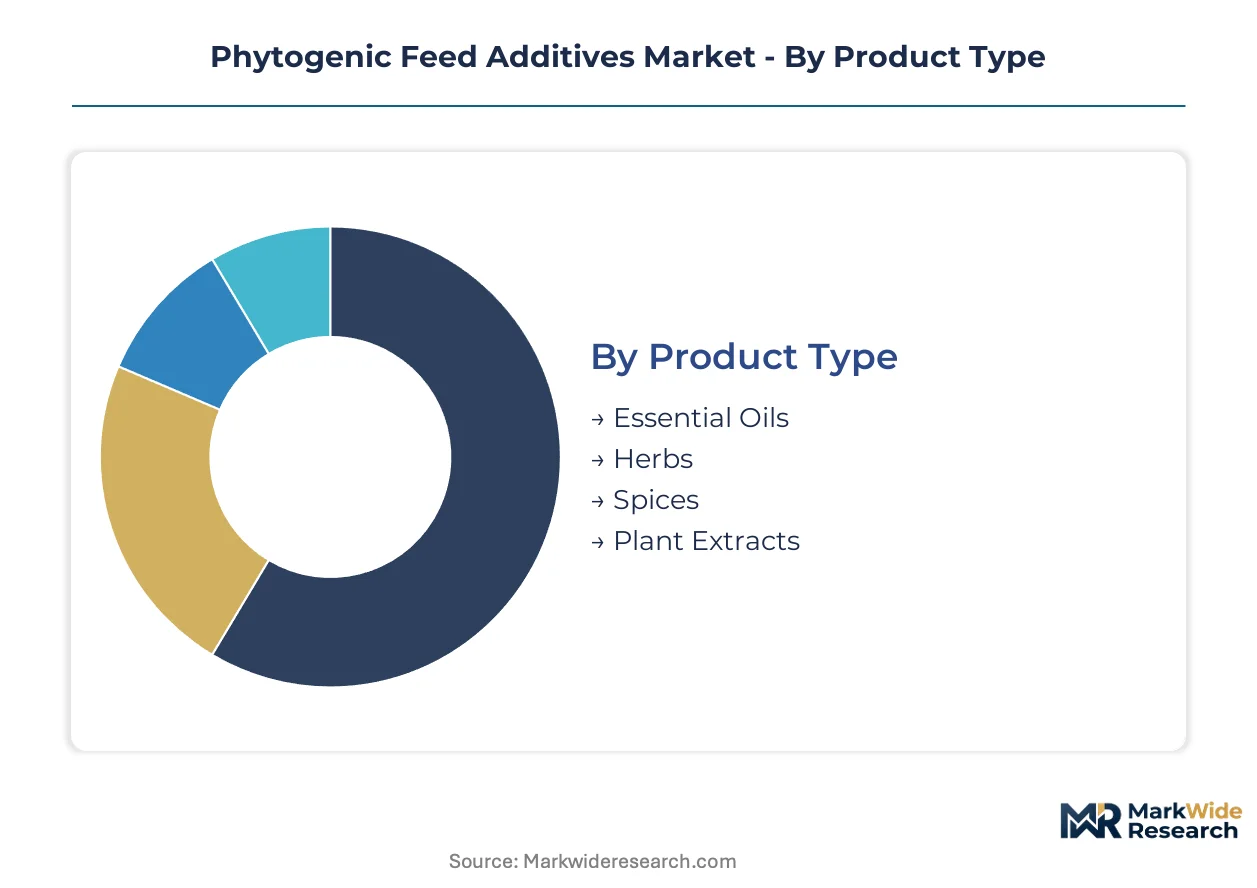
Segmentation in phytogenic feed additives reveals how substitution pressure varies by bioactive concentration, species-specific metabolism, and formulation stability requirements. Understanding these fault lines helps suppliers align R&D pipelines with the segments where synthetic growth promoters face the steepest displacement.
Product Type:
Substitution pressure from synthetic acidifiers and medium-chain fatty acids concentrates in lower-concentration botanical categories, while high-bioactivity segments command premium positioning.
- Essential Oils:Concentrated terpenoid and phenolic compounds from oregano, thyme, and cinnamon deliver standardized antimicrobial activity at low inclusion rates. Poultry integrators in Brazil and Germany are expanding essential oil programs as EFSA residue thresholds tighten against synthetic alternatives.
- Plant Extracts:Polyphenol-rich fractions from grape seed, green tea, and maritime pine require advanced supercritical CO2 extraction to achieve batch-to-batch consistency. Aquaculture operations in Vietnam and Indonesia are driving demand for these extracts as residue-sensitive shrimp exporters face EU import scrutiny.
- Herbs:Dried and ground botanicals including garlic, turmeric, and ginger provide cost-accessible entry points for price-sensitive ruminant operations.
- Spices:Capsicum and black pepper derivatives function primarily as palatability enhancers and gut motility stimulants in swine starter diets.
Essential oils retain volume leadership; plant extracts hold the steepest expansion curve.
Application:
Margin tiering across species tracks regulatory stringency, with residue-sensitive channels commanding price premiums over commodity protein segments.
- Poultry:Broiler and layer operations consume the largest absolute volumes, driven by antibiotic-free program expansion across Brazilian integrators and Southeast Asian export-oriented farms. Heat-stable encapsulated formulations are displacing unprotected essential oils in pelleted feed.
- Aquaculture:Shrimp and finfish producers face the strictest maximum residue limits from EU and Japanese importers, creating highest-margin demand for standardized phytogenic gut health modulators. Vietnamese and Indonesian operators are accelerating substitution timelines ahead of anticipated regulatory tightening.
- Swine:Post-weaning diarrhea control in nursery diets represents the primary application, though price pressure from zinc oxide alternatives limits premium capture.
- Ruminants:Methane inhibition and rumen modulation applications remain nascent, constrained by bioactive degradation in the rumen environment and higher cost-per-head economics.
Poultry dominates absolute consumption; aquaculture delivers the highest margin expansion.
Form:
Supply concentration in extraction and encapsulation technologies is fragmenting competitive returns between raw material processors and finished formulation suppliers.
- Liquid:Unencapsulated oil blends offer lowest unit cost but suffer from volatility losses during feed processing and storage. Direct sales to integrated poultry operations in Brazil favor tanker-delivered liquid formulations for on-farm inclusion.
- Powder:Spray-dried and adsorbed forms provide handling convenience for premix manufacturers, though heat exposure during pelleting degrades unprotected bioactives.
- Granules:Extruded matrix systems protect terpenoids from rumen degradation and feed mill thermal stress, commanding premium pricing in ruminant and poultry applications.
- Capsules:Precision-dosed gelatin or polymer shells enable targeted release in specific gut segments, finding niche adoption in high-value aquaculture and breeder stock programs.
Powder forms retain manufacturing scale leadership; granules are climbing the fastest as encapsulation technology matures.
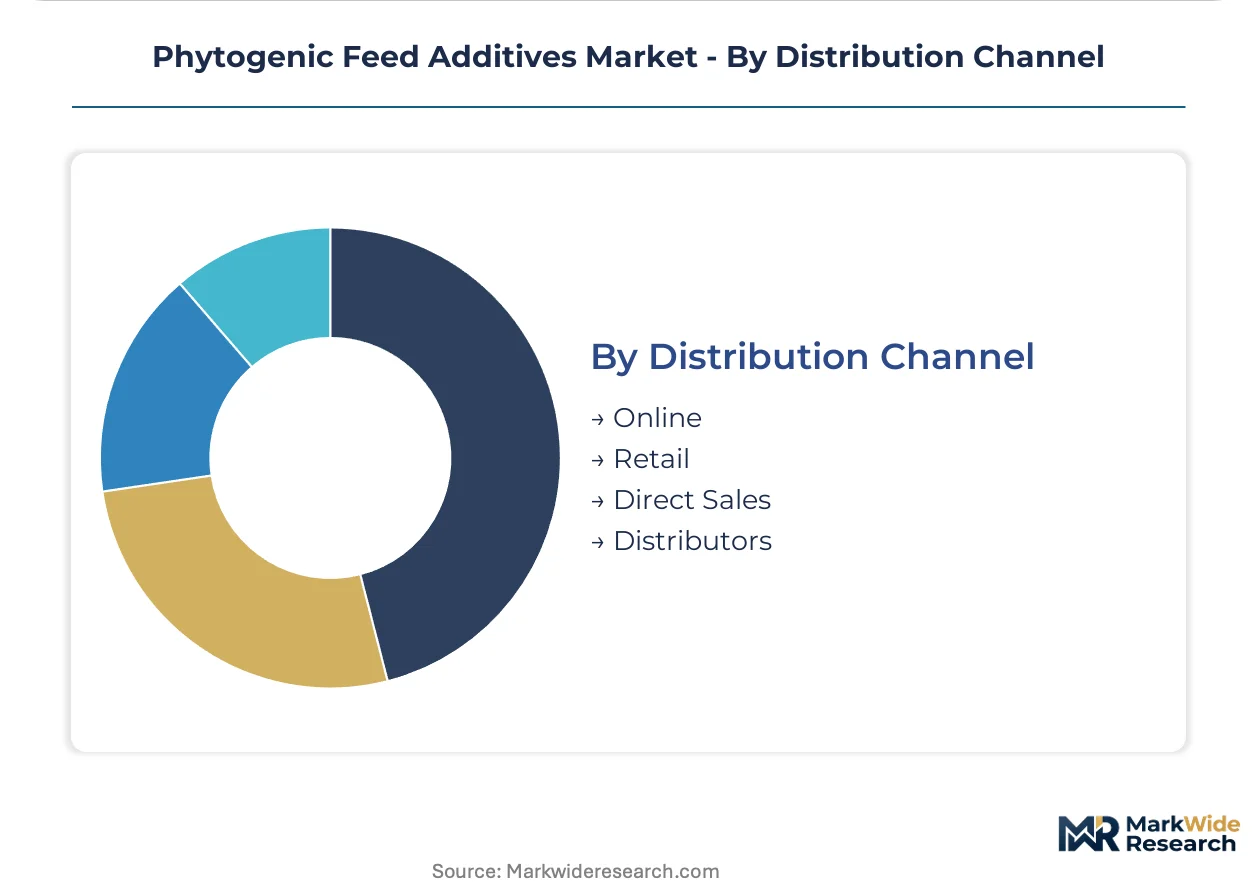
Distribution Channel:
Customer type concentration is forcing channel restructuring, with direct procurement relationships displacing traditional distribution intermediaries in large-account segments.
- Direct Sales:Long-term supply agreements between extract processors and protein multinationals eliminate margin stacking from distribution layers. German and Austrian production clusters anchor these relationships through captive technical service capabilities.
- Distributors:Regional feed additive distributors retain relevance in fragmented poultry and swine markets across Eastern Europe and Latin America, though SKU proliferation strains inventory economics.
- Online:E-procurement platforms are emerging for standardized essential oil formulations in smaller-scale poultry operations, particularly in Brazil's independent producer segment.
- Retail:Farm supply stores and cooperatives serve hobby farms and smallholders with pre-packaged phytogenic supplements, representing minimal revenue concentration.
Direct sales capture the largest account relationships; online channels are expanding most quickly in price-transparent commodity formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies, with Brazilian poultry integrators absorbing premium pricing for antibiotic-free programs while Southeast Asian shrimp producers face acute cost pressure from EU residue enforcement.
Germany
Poultry and aquaculture operators drive phytogenic uptake as EFSA residue thresholds tighten against synthetic growth promoters. The EU Green Deal's carbon border adjustments favor certified-sustainable botanical suppliers in regulated protein chains. Frankfurt and Innsbruck production clusters anchor captive supply relationships between extract processors and protein multinationals.
Brazil
Integrated poultry producers expand essential oil inclusion rates in antibiotic-free broiler programs, creating sustained volume demand. ANVISA alignment with Codex Alimentarius standards accelerates registration timelines for standardized phytogenic formulations. São Paulo state concentrators dominate domestic formulation capacity while southern regions supply oregano and thyme feedstocks.
Vietnam
Shrimp exporters facing EU and Japanese maximum residue limits drive fastest-margin expansion for gut health modulators. The country's national feed regulator tightens import scrutiny on synthetic alternatives ahead of anticipated regulatory convergence. Mekong Delta processing zones concentrate aquaculture phytogenic demand.
United States
Feedlot and poultry operations respond to FDA veterinary feed directives restricting medically important antibiotic use. USDA-FSIS residue monitoring programs elevate documentation requirements for botanical performance enhancers. Midwest premix manufacturing hubs integrate encapsulated essential oils into mineral-vitamin matrices.
Indonesia
Export-oriented shrimp and finfish producers accelerate phytogenic substitution timelines under EU import pressure. The national food and drug regulator harmonizes feed additive standards with ASEAN MRL frameworks. Java-based aquaculture clusters drive technical service demand for heat-stable granule formulations.
Phytogenic Feed Additives Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated extract processors commanding premium positioning while formulation-assemblers compete on volume scale. The vendor base clusters around three strategic profiles: captive botanical sourcers with South American supply control, fermentation-linked platform developers sustaining higher R&D recovery, and premix distributors extending existing infrastructure into phytogenic blends. M&A activity concentrates on extraction technology acquisition, while capacity expansion targets supercritical CO2 processing capabilities.
Among European specialists with fermentation and biotechnology roots, BIOMIN Holding GmbH and Delacon Biotechnik GmbH exemplify the integrated platform archetype, anchoring production relationships near Frankfurt and Innsbruck. Kemin Industries, LLC represents the captive sourcing model with South American botanical supply control. Cargill, Incorporated occupies the scale-driven distribution position, leveraging premix infrastructure for volume channel penetration.
| Leading Market Players |
|---|
| Kemin Industries, LLC |
| BIOMIN Holding GmbH |
| Cargill, Incorporated |
| Phytobiotics Futterzusatzstoffe GmbH |
| Delacon Biotechnik GmbH |
| Archer Daniels Midland Company |
| Alltech, Inc. |
| Novus International, Inc. |
| Koninklijke DSM N.V. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between South American botanical suppliers and German extraction processors lock in multi-year feedstock access while stabilizing phenolic concentrate pricing against harvest volatility. These arrangements concentrate pricing power with integrated processors who control captive oregano and thyme supply bases, while formulation-assemblers absorb spot-market volatility in essential oil feedstocks.
Pricing Analysis
Technical service bundling drives lifetime value capture beyond base product margins. Three-tier pricing structure across premium, standard, and economy levels stratifies by extraction method and EFSA registration status. Premium supercritical CO2 extracts command sustained margins from aquaculture exporters facing Japanese and EU residue scrutiny. Price erosion runs through unencapsulated liquid formulations as Brazilian poultry integrators consolidate procurement volumes. Smallholder cooperatives in Southeast Asia exhibit highest price sensitivity, while German protein multinationals prioritize batch-to-batch consistency over unit cost.
Supply Chain Analysis
Andean highland harvest windows create seasonal chokepoints for oregano and thyme terpenoid concentration. Supply draws from Peru, Brazil, and southern Germany for botanical feedstocks, with supercritical CO2 extraction equipment concentrated in Austrian and Italian manufacturing hubs. Raw material dependencies include steam-distilled essential oils, spray-dried polyphenol fractions, and liposome encapsulation substrates. Single-source vulnerability persists in certified-organic botanical streams where conversion timelines stretch 24-36 months. Distribution runs through direct technical service relationships for large integrators, with regional distributors serving fragmented Latin American poultry operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive returns as fermentation-linked bioactive production converges with traditional botanical extraction, creating interoperability between microbial cultivation and plant-derived compound libraries.
For Market Incumbents: Consolidate extraction technology acquisition targets to defend against precision fermentation entrants disrupting terpenoid supply economics. Prioritize captive supply agreements with Peruvian and Brazilian botanical cooperatives before climate-driven harvest compression intensifies. EFSA novel food approval timelines represent the critical regulatory moat requiring sustained toxicology investment. For New Entrants and Emerging Players: Lead with encapsulated granule formulations targeting Vietnamese and Indonesian shrimp exporters facing imminent EU carbon border adjustment pressure. Aquaculture gut health modulators present the most penetrable white space where residue regulations outpace incumbent capacity expansion. Establish direct technical service presence in Mekong Delta processing zones before distribution relationships crystallize. For Investors and Strategic Acquirers: Fermentation-platform developers with existing GRAS dossiers present the most defensible acquisition archetype for sustained value creation. Supercritical CO2 processing capabilities anchor margin expansion as solvent-based extraction faces REACH authorization pressure. Watch EFSA maximum residue limit revisions for poultry and aquaculture as the signal indicating acceleration or compression in botanical substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Delivers batch-to-batch phenolic consistency demanded by German poultry integrators under EFSA scrutiny. |
| Precision Fermentation Platform Development | Enables novel bioactive libraries beyond climate-constrained botanical harvesting in Andean supply zones. |
| Direct Procurement Relationship Formation | Eliminates margin stacking for Brazilian integrators consolidating antibiotic-free program supply chains. |
| Encapsulation Technology Licensing | Protects volatile terpenoids from pelleting heat degradation in Southeast Asian aquaculture feed mills. |
| EFSA Novel Feed Additive Registration | Secures 18-36 month regulatory moat against synthetic growth promoter re-entry in EU protein supply chains. |
Study Parameters
Cross-validation between regulatory filing analysis and extraction technology patent mapping anchors the qualitative findings on competitive positioning. Primary interviews with phytogenic formulation directors, poultry integrator procurement leads, aquaculture technical service managers, and EFSA regulatory affairs consultants combined with secondary validation from ANVISA registration databases, EFSA novel food opinions, South American customs export records, and supercritical CO2 equipment shipment data. Bottom-up demand modeling across species-specific inclusion rates triangulates against top-down market sizing from premix manufacturer capacity disclosures.
Sensitivity analysis on harvest yield volatility and regulatory approval timelines shapes the projection framework. Segmentation dimensions span bioactive concentration tier, species application, formulation stability technology, and regional regulatory cluster. CAGRs derive from compound growth trajectory fitting across the modeling period, with inputs including EFSA residue threshold revision schedules, Brazilian antibiotic-free program expansion rates, and Vietnamese shrimp export volume forecasts to EU markets.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or accelerated FDA veterinary feed directive implementation would require recalibration. Forecasts assume continued divergence between regulated and unregulated protein supply chain standards. Practitioners should keep alternative scenarios live as ANVISA-Codex alignment timelines and ASEAN maximum residue limit harmonization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Australia Food Colorants Market
Food Additives and Ingredients
Fish Tank Water Additives Market
Food Additives and Ingredients
Europe Feed Anti-Caking Agents Market
Food Additives and Ingredients
Russia Feed Additives Market
Food Additives and Ingredients
Emulsifiers Market
Food Additives and Ingredients
Food Grade Carrageenan Market
Food Additives and Ingredients
South America Brewing Enzymes Market
Food Additives and Ingredients
Casamino Acids Market
Food Additives and Ingredients
Japan Feed Additives Market
Food Additives and Ingredients
Food Grade Calcium Lactate Market
Food Additives and Ingredients
Brazil Food Ingredient Market
Food Additives and Ingredients
Fat Replacers Salt Reducers and Replacers Market
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
Acidity Regulators Market
Food Additives and Ingredients
Meat Stabilizers Blends Market
Food Additives and Ingredients
Food and Beverages Color Fixing Agents Market