
 Pet Services Market | 2026-2036
Pet Services Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Services Market Intelligence
Veterinary technician shortages is bifurcating market access between premium full-service chains and budget digital platforms. Mars Petcare anchors its position through captive veterinary networks spanning specialty and general practice. PetSmart leverages its retail footprint to integrate grooming with in-store veterinary clinics. Rover competes through a gig-based model that reduces fixed labor costs in pet sitting and dog walking.
Pet services encompass non-medical and medical care activities delivered to companion animals, including grooming, behavioral conditioning, temporary housing, and wellness monitoring through scheduled protocols and facility-based interventions. The sector serves commercial and residential end-users seeking outsourced animal management, hygiene maintenance, and socialization support. Grooming and boarding command mature revenue pools with established pricing benchmarks, while subscription payment models are capturing recurring revenue from digitally native pet owners. Dog services dominate volume across all segments, though exotic pet boarding represents a margin-rich niche with limited specialist supply.
FDA Center for Veterinary Medicine oversight of telehealth prescribing rules shapes how Banfield Pet Hospital and National Veterinary Associates deploy remote diagnostics. State-level veterinary practice acts and USDA animal welfare standards govern facility licensing, staffing ratios, and transport conditions for boarding operators. Stakeholders must weigh capital intensity against regulatory compliance costs when selecting between asset-light platforms and integrated service networks.
Market Dynamics
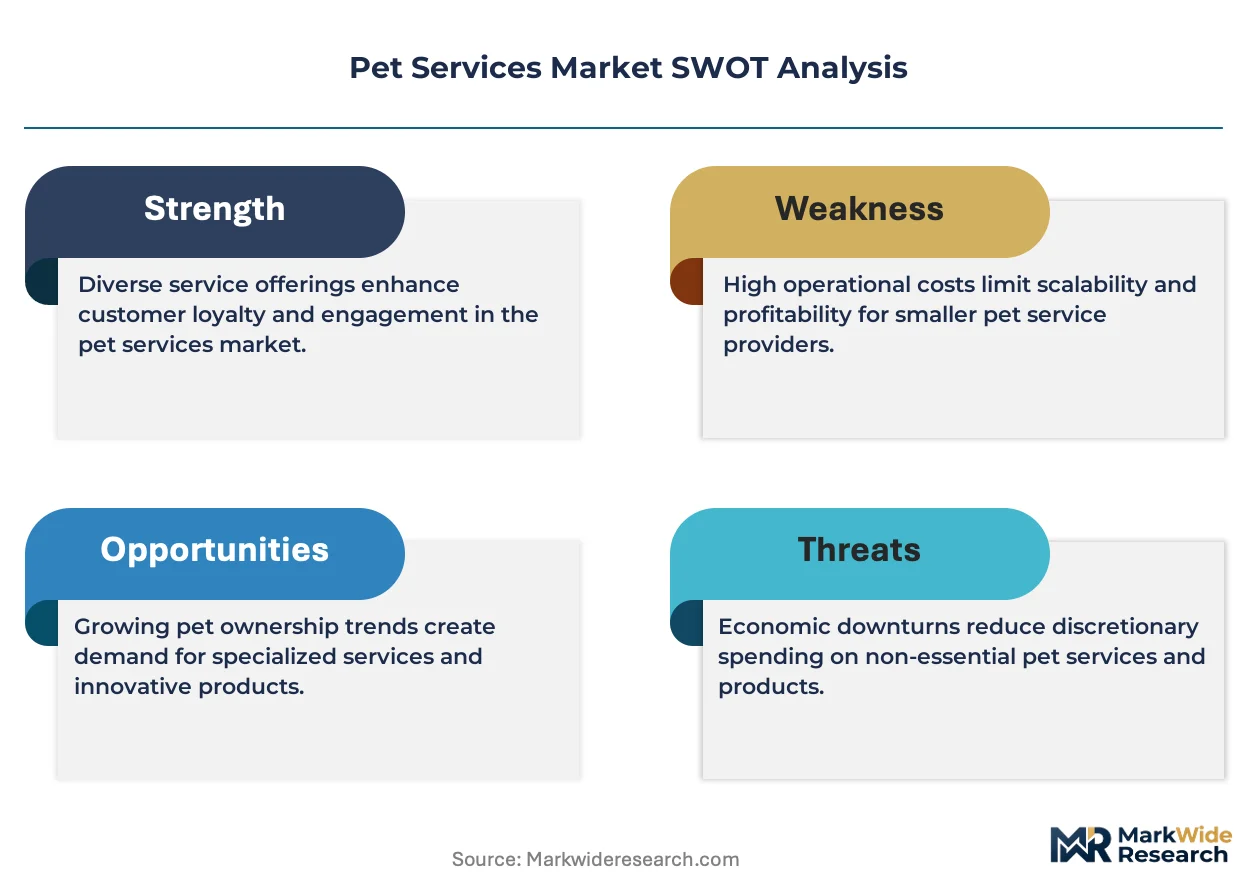
Veterinary technician shortages are bifurcating market access between premium full-service chains and budget digital platforms, forcing capital allocation decisions that reshape competitive positioning across service tiers.
Growth Catalysts
- Urban pet density:Metropolitan corridors with high companion animal populations generate concentrated demand for outsourced care, grooming, and behavioral services.
- FDA Center for Veterinary Medicine telehealth guidance:Clarified prescribing rules enable remote diagnostic platforms to expand service reach into underserved exurban markets.
- Subscription payment models:Digitally native pet owners prefer recurring billing structures for wellness monitoring and preventive care protocols.
Market Restraints
- Veterinary labor supply constraints:Accredited technician training program capacity limits service expansion regardless of capital availability.
- State veterinary practice act fragmentation:Inconsistent cross-border licensing rules prevent mobile clinic operators from achieving route density economics.
- Commercial real estate cost inflation:Facility-based boarding and grooming operations face margin compression in prime urban locations.
Strategic Opportunities
- Exotic pet boarding specialization:Reptile and avian housing commands premium pricing due to limited specialist supply and specialized habitat requirements.
- USDA animal welfare standards certification:Compliance differentiation enables operators to access institutional contracts with municipal shelters and rescue networks.
- AI-powered behavioral analytics:Integration of machine learning with wearable monitoring devices creates predictive wellness subscription tiers.
Industry Challenges
- Telehealth-platform integration with legacy practice management systems:Data interoperability gaps force manual workflow workarounds that degrade clinician productivity.
- Multi-jurisdiction compliance for mobile veterinary units:Transport condition standards vary by state, complicating fleet deployment scheduling and equipment configuration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Services Market |
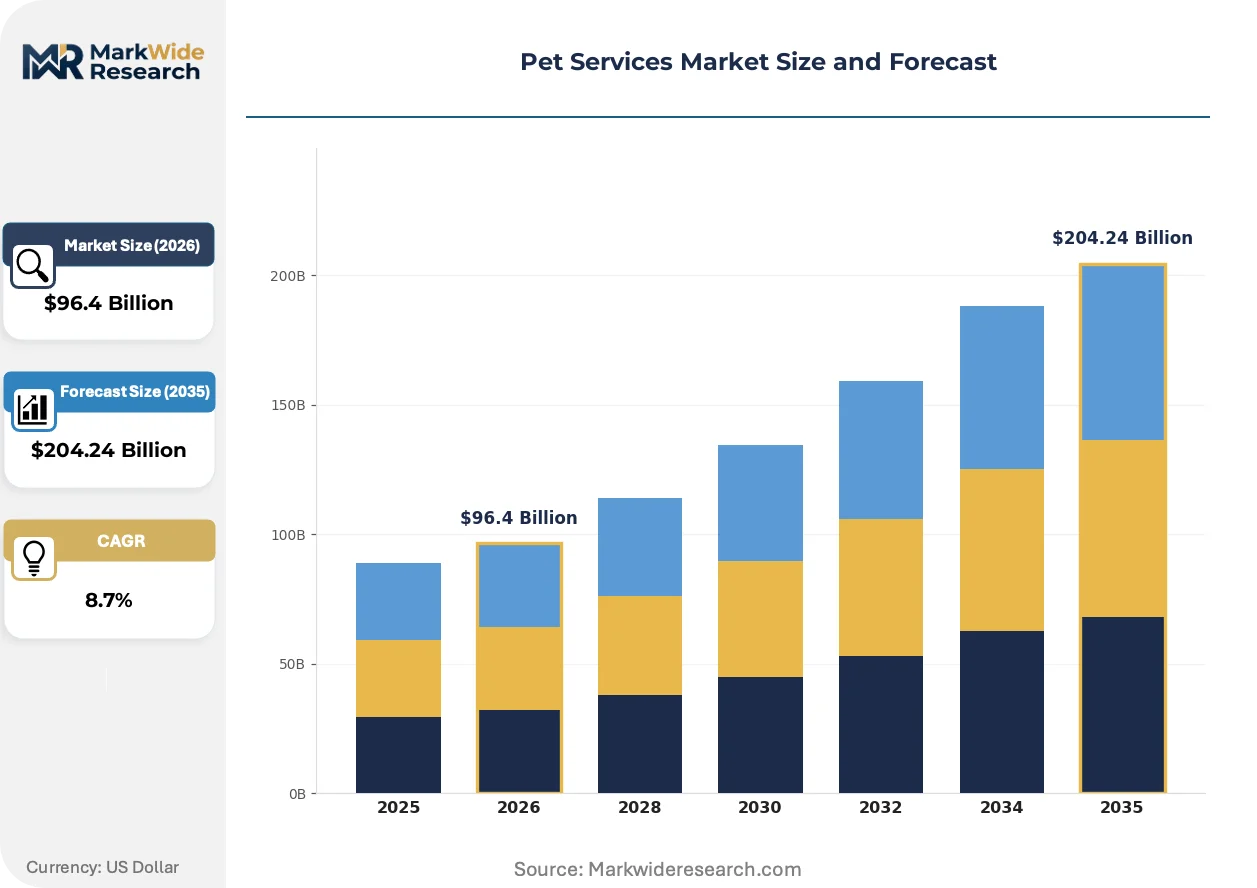
| Market Size in 2026 | $96.4 Billion |
| Market Size in 2035 | $204.24 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Grooming, Training, Boarding, Pet Sitting Customer Type: Pet Owners, Pet Breeders, Shelters, Veterinarians Animal Type: Dog, Cat, Bird, Exotic Pets Payment Model: Subscription, Pay-per-Visit, Package Deals, Membership |
| Companies Covered | PetSmart, Rover, Mars Petcare, Banfield Pet Hospital, Petco, National Veterinary Associates, IVC Evidensia, AniCura, CVS Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Services Market Strategic Shifts & Innovations
Digital infrastructure is compressing service delivery timelines while regulatory clarity around remote care reshapes competitive entry requirements. Three developments merit particular attention.
Wearable biometric sensors for companion animals are miniaturizing. Continuous glucose monitors and activity trackers now integrate with smartphone applications used by urban millennial pet owners. This hardware convergence is miniaturizing the gap between professional veterinary monitoring and owner-managed preventive care, compressing visit frequency for stable chronic conditions.
State veterinary board oversight of mobile clinic staffing ratios is tightening. New requirements for on-site licensed veterinarian presence during all operating hours increase labor costs for asset-light operators. Boarding and grooming chains with captive veterinary networks absorb this friction more easily than independent mobile platforms.
Millennial and Gen Z pet owners now prioritize subscription-based wellness bundles over transactional service purchases. Traditional per-visit pricing at independent clinics faces displacement by integrated monthly plans offered through retail-anchored networks. This preference shift concentrates in coastal metropolitan markets with higher digital service adoption rates.
Pet Services Market Segmentation
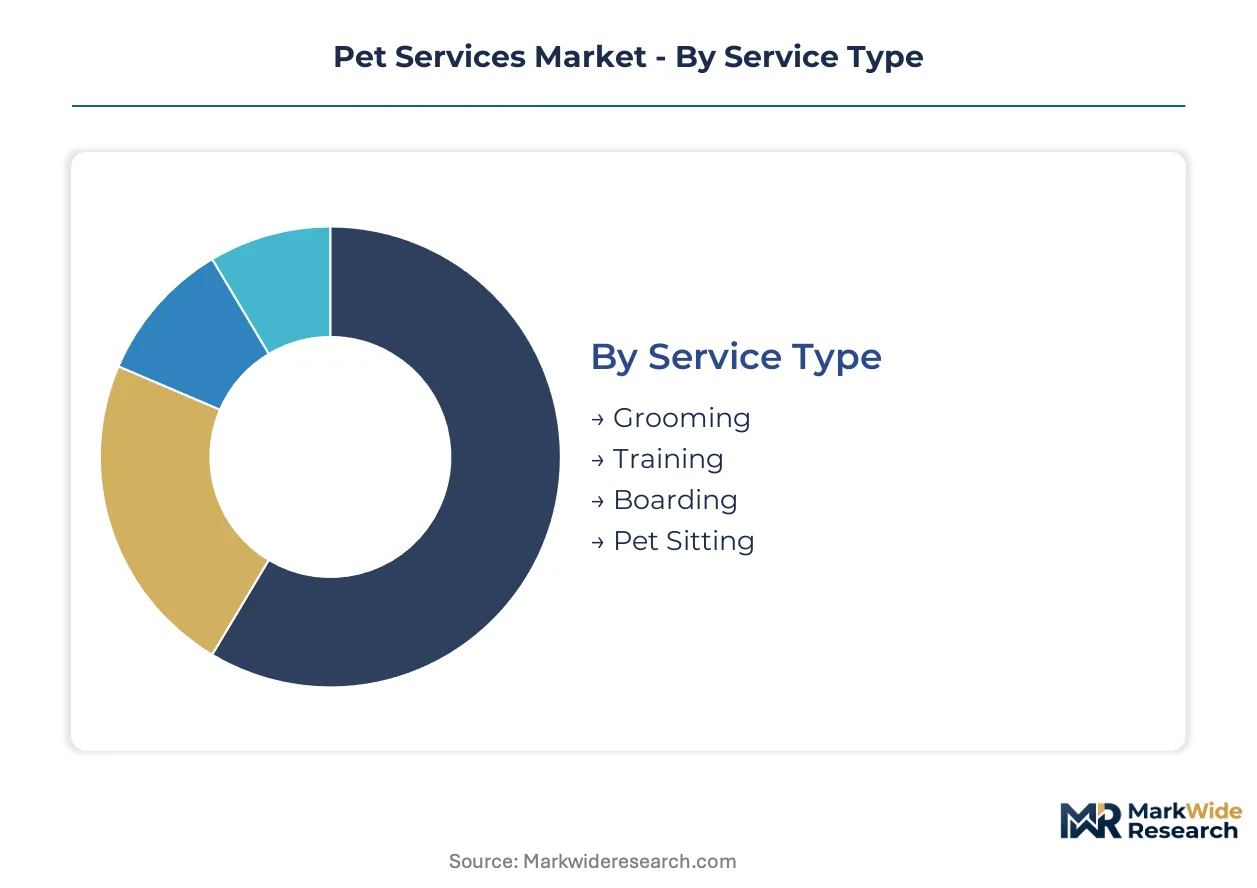
Segmentation in pet services reveals divergent margin structures across service modalities and customer archetypes. Payment model innovation and species-specific care requirements create distinct operational footprints that reward specialized positioning over undifferentiated scale.
Service Type:
Grooming and boarding concentrate in domestic metropolitan corridors with established facility infrastructure, while training and pet sitting services exhibit stronger export-led characteristics through digital platform scalability.
- Grooming:Hygiene maintenance encompassing bathing, coat trimming, nail care, and dental cleaning delivered through fixed-location salons or mobile units. Demand clusters in high-income urban zip codes where owners prioritize breed-standard presentation and coat health; labor intensity limits margin expansion despite premium pricing power.
- Training:Behavioral conditioning protocols addressing obedience, socialization, anxiety management, and specialized task instruction. Metropolitan pet density in cities like New York and Los Angeles sustains brick-and-mortar academies, while virtual coaching modules enable cross-border revenue capture with minimal incremental cost.
- Boarding:Temporary residential care in kennel or home-stay formats providing feeding, exercise, and monitoring during owner absence.
- Pet Sitting:In-home visitation and overnight care preserving animals in familiar environments; gig-platform intermediation reduces customer acquisition costs.
Grooming holds the largest share; momentum sits with pet sitting as platform intermediation compresses pricing friction.
Customer Type:
Cost tier stratification separates transactional retail consumers from institutional buyers negotiating volume-based service agreements.
- Pet Owners:Individual residential consumers purchasing services for companion animals under direct custody. Subscription payment models capture recurring revenue from digitally native millennial and Gen Z demographics in coastal metropolitan markets.
- Pet Breeders:Commercial breeding operations requiring standardized grooming, behavioral conditioning, and temporary housing for inventory management. Breeders in USDA-licensed facilities demand documentation rigor that elevates compliance costs for service providers.
- Shelters:Municipal and nonprofit animal control operations outsourcing intake grooming, behavioral rehabilitation, and pre-adoption socialization.
- Veterinarians:Clinical practices referring or co-locating non-medical services to extend patient touchpoints and ancillary revenue streams.
Pet owners dominate volume; breeders deliver the steepest expansion trajectory as commercial breeding consolidation elevates professional service standards.
Animal Type:
Species-specific physiological requirements fragment service standardization, with margin concentration in categories demanding specialized habitat or handling expertise.
- Dog:Canine-specific services spanning size-stratified grooming, breed-appropriate training protocols, and exercise-intensive boarding. Volume concentration in suburban corridors with yard access constraints drives dog walking and daycare demand.
- Cat:Feline grooming emphasizing low-stress handling techniques and medical-grade sanitary trims; boarding requires species-separated facilities with vertical space configuration.
- Bird:Avian grooming encompassing wing clipping, nail trimming, and beak maintenance; behavioral services address screaming and feather-destruction disorders.
- Exotic Pets:Reptile, amphibian, and small mammal care demanding temperature-controlled habitats, specialized nutrition, and veterinary-adjacent handling protocols.
Dog services command the largest share; exotic pets are climbing the fastest as specialist scarcity sustains premium pricing.
Payment Model:
Revenue predictability varies sharply across billing structures, with subscription architectures reducing customer lifetime value volatility relative to transactional models.
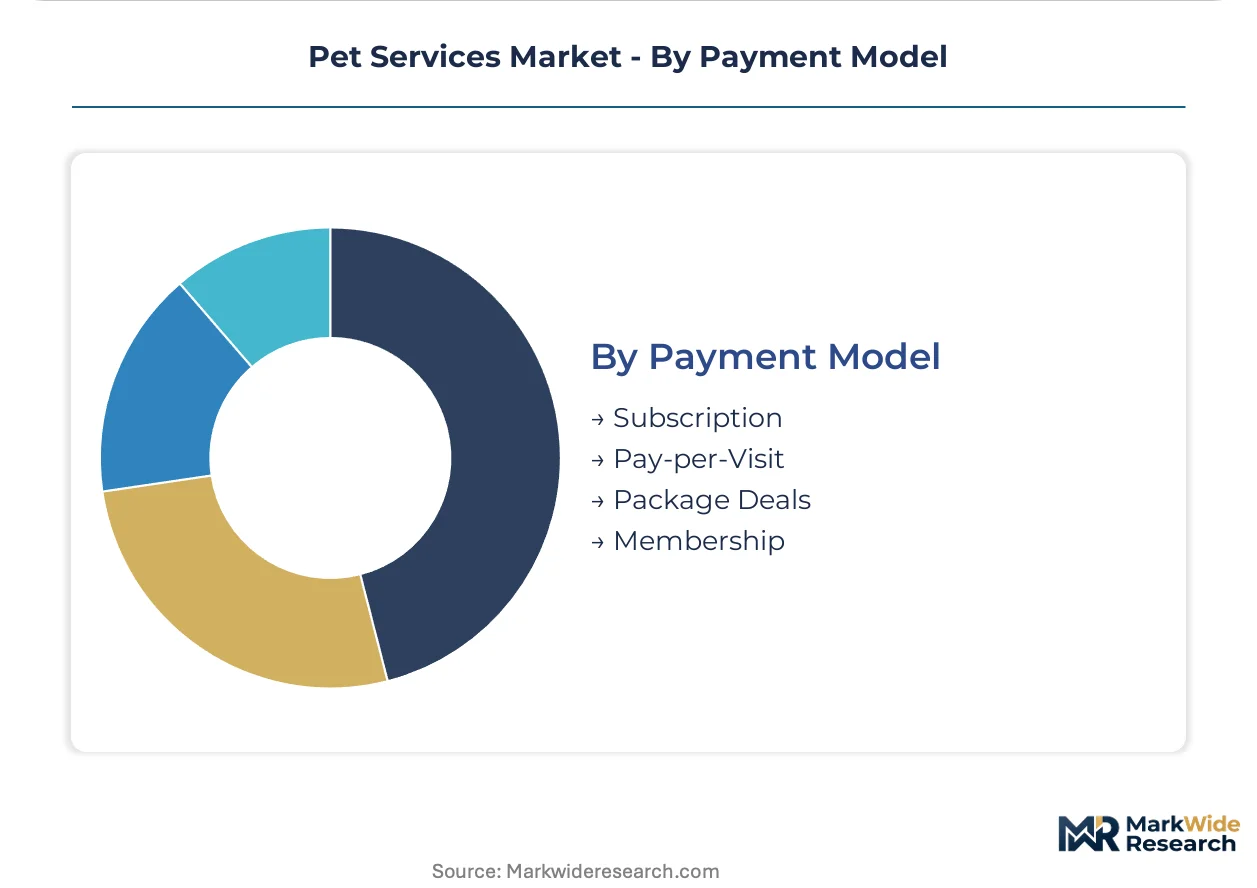
- Subscription:Recurring monthly or annual fees covering bundled wellness monitoring, preventive grooming, and priority booking privileges. Digital-native pet owners in metropolitan markets exhibit strongest adoption.
- Pay-per-Visit:Single-transaction pricing for discrete service events; legacy independent clinics and mobile groomers rely on this structure.
- Package Deals:Prepaid multi-service bundles offering modest per-unit discounts; common in training academies and boarding facilities.
- Membership:Annual enrollment fees conferring service discounts and exclusive access without true subscription bundling; retail-anchored networks deploy this hybrid.
Pay-per-visit retains the largest share; subscription models are gaining share fastest as platform intermediation reduces enrollment friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine telehealth guidance anchors the United States as the dominant geography, with metropolitan corridors generating concentrated demand for premium wellness services. Urban pet density and disposable income differentials create stark regional performance variations across national markets.
United States
Metropolitan corridors in New York, Los Angeles, and Chicago concentrate demand for outsourced grooming, boarding, and behavioral services. FDA telehealth prescribing rules enable Banfield Pet Hospital and National Veterinary Associates to deploy remote diagnostics into exurban markets. The Northeast Corridor exhibits strongest subscription payment model adoption among digitally native millennial pet owners.
Germany
Urban centers in Berlin, Munich, and Hamburg sustain premium pet service demand through high companion animal ownership rates. EMA-aligned veterinary standards govern cross-border service provision, complicating mobile clinic operations into neighboring jurisdictions. The North Rhine-Westphalia industrial cluster supports specialized pet food and equipment supply chains feeding service providers.
United Kingdom
London and Southeast England concentrate volume for premium grooming and daycare services among high-income professionals. The Royal College of Veterinary Surgeons maintains stringent telehealth supervision requirements that shape competitive entry for remote care platforms. Manchester and Birmingham emerging as secondary hubs for boarding chain expansion.
Japan
Tokyo and Osaka metropolitan areas exhibit highest per-capita spending on pet grooming and behavioral conditioning services. METI guidelines on animal welfare standards influence facility licensing requirements for boarding operators. Aging demographics in rural prefectures drive demand for in-home pet sitting as family-based care availability declines.
Australia
Sydney and Melbourne coastal metropolitan markets sustain premium pricing for wellness monitoring and preventive care subscriptions. TGA oversight of veterinary pharmaceuticals indirectly shapes service protocols through prescribing limitation impacts. Queensland emerging as growth corridor for exotic pet boarding specialization due to climate-advantaged facility economics.
Pet Services Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with captive veterinary networks and retail-anchored service chains commanding premium positioning. Mars Petcare anchors the integrated tier through specialty and general practice consolidation. Three strategic archetypes dominate: retail-anchored networks integrating grooming with veterinary clinics, gig-platform intermediaries reducing fixed labor costs, and captive veterinary chains absorbing regulatory compliance friction. Competitive moves concentrate on M&A for network density and subscription model deployment for recurring revenue capture.
Within the integrated veterinary tier, Mars Petcare and Banfield Pet Hospital exemplify captive network strategies that absorb regulatory compliance costs more efficiently than independent operators. PetSmart occupies a retail-anchored position leveraging physical footprint for service integration, while Rover represents the asset-light platform archetype competing through variable cost structures in pet sitting and dog walking segments.
| Leading Market Players |
|---|
| PetSmart |
| Rover |
| Mars Petcare |
| Banfield Pet Hospital |
| Petco |
| National Veterinary Associates |
| IVC Evidensia |
| AniCura |
| CVS Group |
| Others |
Cost & Logistics Intelligence
Platform intermediation replacing traditional facility-based booking systems simultaneously redistributes service supply toward asset-light operators and compresses pricing power for fixed-location incumbents. This substitution dynamic concentrates margin capture with digital-native networks while eroding the geographic premium historically commanded by urban facility operators.
Pricing Analysis
Long-term subscription contracts dominate premium wellness segments, while spot-market transactional pricing persists in grooming and boarding. Price differentiation separates USDA-certified operators from standard-tier competitors, with certification commanding measurable premiums in institutional procurement. Cost compression in urban facility operations intensifies as commercial real estate inflation outpaces service pricing elasticity. Budget-conscious residential consumers exhibit highest price sensitivity, whereas institutional buyers negotiating volume agreements demonstrate lowest sensitivity.
Supply Chain Analysis
Inbound logistics costs for specialized pet nutrition and pharmaceutical inputs fluctuate with container availability on Asia-Pacific trade lanes serving US and European markets. Manufacturing concentration for companion animal diagnostics and therapeutic products centers on the United States, Germany, and China. Raw material dependencies include active pharmaceutical ingredients, specialized feed additives, and precision-machined veterinary equipment. Single-source vulnerability in accredited veterinary technician training programs constrains service expansion regardless of capital deployment. Distribution runs through retail-anchored networks, digital platforms, and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent operators face substitution pressure from AI-powered behavioral monitoring and telehealth platforms that disintermediate traditional clinic relationships. Defense requires strategic repositioning around irreplaceable in-person care modalities.
For Market Incumbents: Shield captive veterinary networks through backward integration into technician training pipelines, addressing the labor scarcity that constrains competitor expansion. Deepen certification investment in USDA animal welfare standards to differentiate from unlicensed platform competitors. Prioritize subscription model deployment in coastal metropolitan markets where digitally native owners concentrate.
For New Entrants and Emerging Players: Lead with exotic pet boarding specialization in climate-advantaged geographies where specialist scarcity sustains premium pricing. Target underserved exurban corridors where FDA telehealth guidance enables remote diagnostic reach without facility investment. Deploy mobile clinic formats with route-optimized scheduling to circumvent state licensing fragmentation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed veterinary consolidators seeking platform integration capabilities. Long-term viability hinges on recurring revenue capture through wellness subscriptions rather than transactional service dependence. Watch telehealth-platform integration milestones as inflection indicators for legacy practice management displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Network Consolidation | Captive technician pipelines address labor scarcity constraining competitor expansion. |
| Subscription Model Deployment | Recurring billing structures reduce customer lifetime value volatility in metropolitan markets. |
| Exotic Pet Specialization | Limited specialist supply in reptile and avian care sustains premium pricing power. |
| Telehealth Platform Integration | FDA prescribing rules enable remote diagnostic reach into underserved exurban corridors. |
| USDA Certification Investment | Compliance differentiation unlocks institutional contracts with municipal shelter networks. |
Research Approach
Cross-validation between executive interviews and regulatory filing analysis anchors the qualitative findings in documented operational constraints. Primary fieldwork encompassed veterinary practice owners, platform operations executives, state veterinary board administrators, and municipal shelter procurement officers. Secondary validation drew from FDA Center for Veterinary Medicine guidance documents, state practice act compilations, USDA facility licensing records, and trade association membership data. Bottom-up service volume estimates triangulated against top-down expenditure benchmarks.
Sensitivity analysis tested forecast robustness across alternative labor supply scenarios and regulatory implementation timelines. Segmentation modeling incorporated service type, payment structure, animal species, and customer archetype dimensions. CAGRs derived from trend extrapolation adjusted for identified inflection drivers including telehealth adoption curves and subscription penetration rates. Veterinary technician training program capacity and commercial real estate cost trajectories served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained urban pet density growth or clarified telehealth prescribing rules would require recalibration. Forecasts reflect documented assumptions regarding labor supply constraints and regulatory enforcement intensity. Recalibration cycles align with material shifts in FDA guidance, state veterinary board staffing requirements, or platform intermediation penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare
Global Histone Deacetylase Inhibitors Market
Healthcare
Computer-Aided Oral and Maxillofacial Surgery Market
Healthcare
Europe Esoteric Testing Market
Healthcare
Defibrillator Pads Market
Healthcare
Athletic Knee Treatment Market
Healthcare
NPWT Canisters Market
Healthcare
Occupational Therapy Software Market
Healthcare
Electrocardiograph (ECG) Market
Healthcare
Global Legionella Testing Market
Healthcare
India Urology Market
Healthcare
Gonorrhea Therapeutics Market
Healthcare
China Computed Tomography Market
Healthcare
China Medical Tourism Market
Healthcare
Global Ligation Devices Market
Healthcare
Global Lithotripsy Device Market
Healthcare
Germany Aesthetic Devices Market