
 Pet Insurance Market | 2026-2036
Pet Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Insurance Market Analysis
North American veterinary infrastructure expansion is rewriting competitive dynamics for pet insurance distribution. Trupanion leverages direct-to-consumer veterinary partnerships to sustain premium growth without broker intermediation. Nationwide Mutual Insurance Company anchors its position through employer-sponsored group policies embedded in Fortune 500 benefits packages. Healthy Paws differentiates through unlimited lifetime coverage terms that eliminate per-incident or annual caps.
Pet insurance constitutes a risk-transfer contract indemnifying policyholders against veterinary medical expenditures through premium pooling and actuarial underwriting; policies specify reimbursement percentages, annual deductibles, and waiting periods before coverage activation. Lifetime policies dominate premium pools in mature markets while accident-only coverage occupies price-sensitive entry segments. Online platforms represent the fastest-growing sales channel as digital-native pet owners bypass traditional broker relationships for instant quote comparison and policy binding.
The National Association of Insurance Commissioners (NAIC) coordinates state-level rate filings and consumer protection standards that shape product design across the United States. The UK's Financial Conduct Authority (FCA) mandates transparency in policy terms and claims handling that influences disclosure practices adopted by multinational carriers. Stakeholders must monitor evolving veterinary cost inflation indices and telemedicine reimbursement rulings that will determine future policy pricing structures and coverage scope.
Market Dynamics
Veterinary cost inflation is compressing policy margins while digital distribution platforms dismantle traditional broker intermediation. Insurers must reconcile actuarial precision with consumer price sensitivity as claim frequencies rise alongside advanced diagnostic adoption.
Growth Catalysts
- Telemedicine reimbursement expansion:State veterinary boards in the US and the RCVS in the UK are clarifying remote consultation billing codes. This regulatory clarity enables insurers to bundle virtual triage into base policies without reserve uncertainty.
- Corporate wellness bundling:Large employers across Germany and the United States are adding pet insurance to voluntary benefits portals. This channel bypasses individual customer acquisition costs while embedding premiums in payroll deduction systems.
- Genetic testing integration:Breed-specific health profiles from laboratories in the Netherlands and California allow predictive underwriting. Carriers price policies by hereditary risk rather than age-band averages alone.
Market Restraints
- Veterinary labor scarcity:Accredited veterinary schools in Australia and the United Kingdom produce insufficient graduates to match specialty clinic expansion. This supply bottleneck drives wage inflation that transfers directly to claim costs.
- Reinsurance capacity tightening:Catastrophe bond markets and specialty reinsurers in Bermuda and Zurich are reducing pet health exposure limits. Primary carriers face higher retrocession costs that compress underwriting margins.
- Policy switching friction:Pre-existing condition exclusions create lock-in effects that reduce competitive pressure on incumbent pricing. Consumers cannot port coverage seamlessly when changing employment or relocating across state lines.
Strategic Opportunities
- Wellness subscription layering:Preventive care packages covering dental cleanings and parasite prevention in France and Japan generate recurring revenue beyond indemnity risk transfer. These services reduce long-term claim severity through early intervention.
- AI-assisted claims adjudication:Machine learning models trained on veterinary invoice databases in Canada and Sweden accelerate payment processing. Automation reduces loss adjustment expense ratios while improving customer retention through speed.
- Exotic pet coverage white space:Reptile and avian veterinary networks in metropolitan Texas and Florida remain underserved by standard canine-feline products. Specialized actuarial pools for these species command premium pricing with limited competition.
Industry Challenges
- Veterinary data interoperability:Electronic medical record systems in private practices across Italy and Spain use proprietary formats that resist standardized claims extraction. Insurers must maintain multiple API integrations that increase IT overhead.
- Fraud detection sophistication:Inflated invoice schemes and staged accident documentation require continuous algorithmic monitoring. Detection systems must balance false-positive reduction with genuine claim payment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Insurance Market |
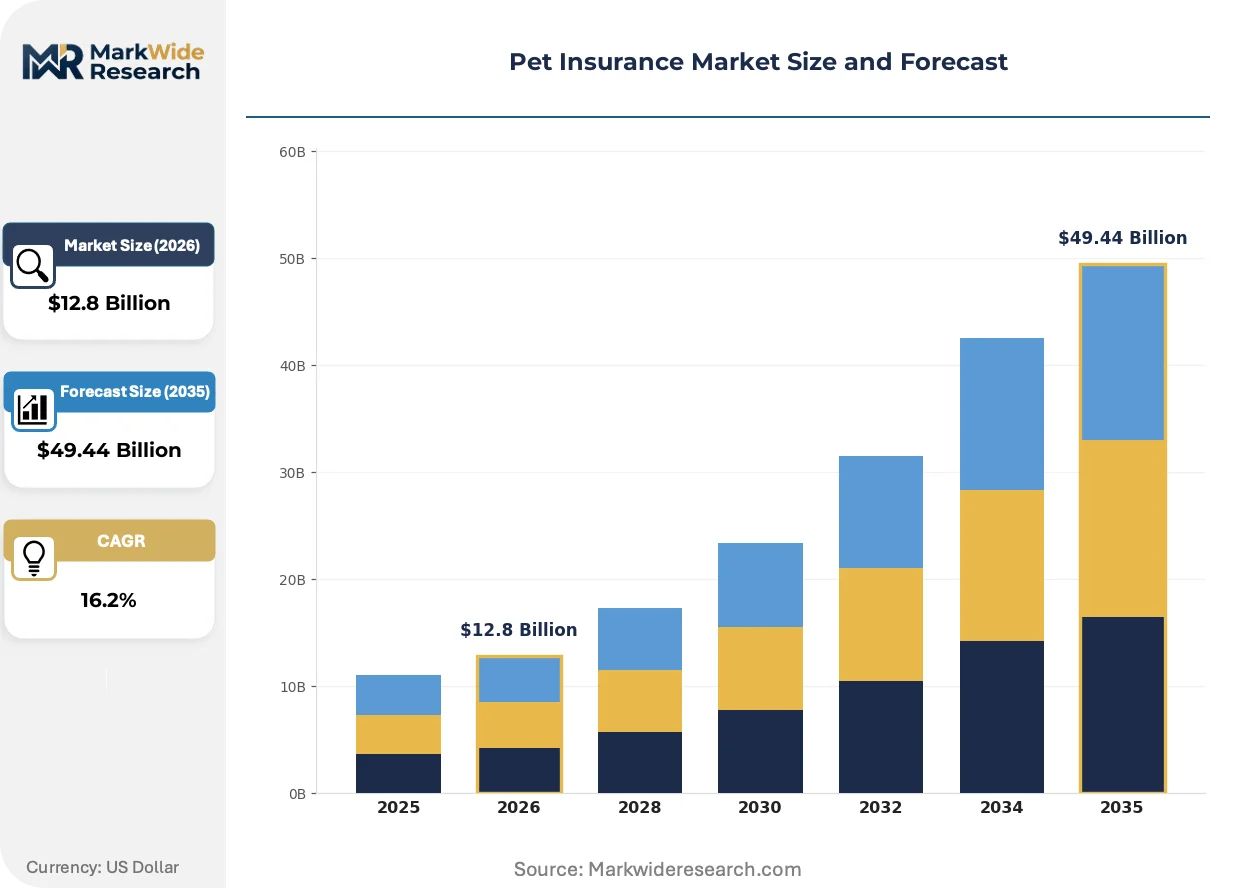
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $49.44 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Lifetime, Time-limited, Maximum benefit, Accident-only Animal Type: Dogs, Cats, Birds, Exotic Pets Sales Channel: Direct, Brokers, Pet Stores, Online Platforms Coverage Level: Basic, Comprehensive, Value, Optional Add-ons |
| Companies Covered | Trupanion, Nationwide Mutual Insurance Company, Embrace Pet Insurance Agency, Fetch Pet Insurance, Pets Best Insurance Services, Healthy Paws, ASPCA Pet Insurance, Figo Pet Insurance, Spot Pet Insurance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Insurance Market Emerging Trajectories
Digital-native distribution models are dismantling decades-old broker relationships while artificial intelligence reconfigures underwriting and claims operations. Three structural shifts define the current innovation cycle.
Machine learning risk scoring is migrating from experimental pilot programs to core underwriting infrastructure. European insurtech platforms deploy neural networks trained on multi-year claims histories to predict individual pet health trajectories. These models compress quote-to-bind timelines from days to minutes while reducing adverse selection through granular risk segmentation.
The EU Green Deal's sustainability disclosure mandates are pressuring insurers to quantify environmental footprints of claims processing operations. Carriers operating in Germany and France must now report paperless policy administration rates and data center carbon intensity. This regulatory layer adds compliance overhead but creates competitive differentiation for carriers with cloud-native architectures.
Employer-sponsored enrollment is displacing direct-to-consumer marketing as the dominant acquisition channel for working-age pet owners. Human resources platforms in the United States and United Kingdom embed pet insurance alongside dental and vision selections during annual benefits elections. This channel shift reduces customer acquisition costs while increasing policy persistency through payroll deduction convenience.
Pet Insurance Market Segmentation
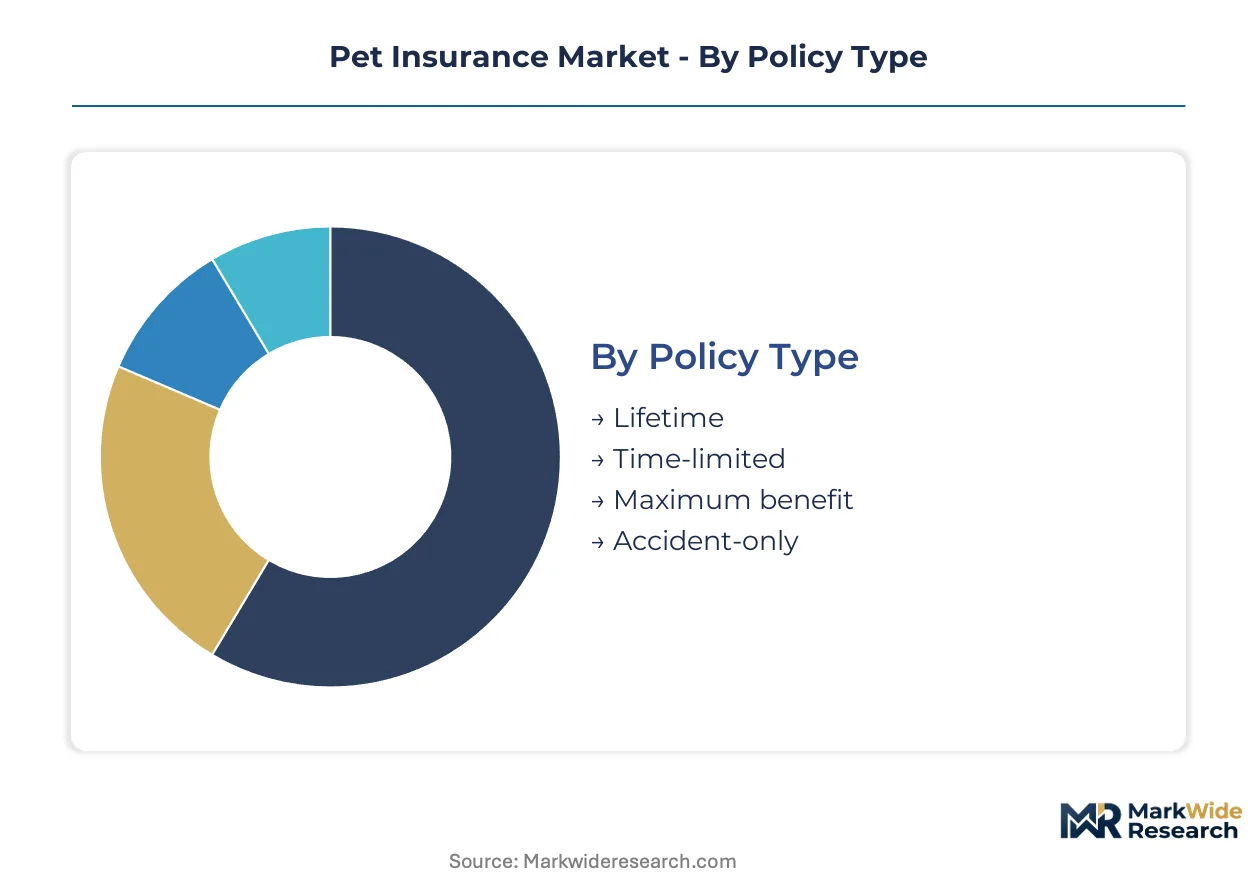
Pet insurance segmentation reveals divergent risk pools and distribution economics across policy structures and species categories. Insurers must calibrate actuarial models and channel investments to match segment-specific claim frequencies and customer acquisition costs.
Policy Type:
Lifetime policies renew annually with continuous coverage for chronic conditions, creating sticky premium streams. Accident-only contracts turn over faster as price-sensitive customers churn between providers seeking lower entry points.
- Lifetime:Indemnity contracts cover recurring conditions across policy years without re-underwriting for diagnosed illnesses. Demand concentrates in the United Kingdom where regulatory precedent from the FCA mandates clear renewal terms. Chronic condition prevalence among aging pet populations locks in premium persistence.
- Accident-only:Coverage excludes illness claims entirely, limiting payouts to trauma and injury events. Price-conscious households in Germany and France select this tier for entry-level protection against emergency veterinary costs. Lower premiums attract younger pet owners with limited disposable income.
- Time-limited:Coverage expires for each condition after 12 months regardless of renewal status.
- Maximum benefit:Per-condition financial caps create defined exposure for insurers and predictable out-of-pocket costs for policyholders.
Lifetime policies dominate installed base. Accident-only is where expansion concentrates.
Animal Type:
Canine and feline segments generate predictable actuarial data from decades of claims history. Avian and exotic species present thin data sets requiring conservative reserve assumptions.
- Dogs:Larger animals incur higher surgical and pharmaceutical costs across all life stages. Demand clusters in the United States where employer-sponsored enrollment channels reach working-age households with Labrador and Golden Retriever ownership concentration. Breed-specific hereditary conditions drive premium differentiation.
- Cats:Lower average claim severity and indoor lifestyle risk profiles compress premiums below canine equivalents. Urban apartment dwellers in Japan and the United Kingdom favor feline companionship, concentrating policy density in metropolitan postal codes. Longer lifespans extend policy duration.
- Birds:Avian veterinary specialists remain scarce outside metropolitan Texas and Florida corridors.
- Exotic Pets:Reptile and small mammal coverage requires specialized actuarial pools with limited historical data.
Dogs dominate installed base. Cats are climbing the fastest.
Sales Channel:
Digital platforms compress quote-to-bind timelines from days to minutes. Traditional broker relationships retain value for complex multi-pet household configurations requiring customized coverage stacking.
- Online Platforms:Instant comparison engines and automated underwriting algorithms eliminate human intermediation. Digital-native pet owners in Sweden and Canada bypass agent relationships entirely, selecting policies through mobile-optimized interfaces. Customer acquisition costs fall below traditional channels.
- Direct:Carrier-owned sales forces and veterinary clinic partnerships embed enrollment at point of care. Trupanion's direct-to-veterinary model in the United States captures customers during initial puppy and kitten wellness visits. First-mover advantage in clinic relationships creates defensive moats.
- Brokers:Independent agents serve multi-pet households requiring policy customization across species.
- Pet Stores:Retail partnerships capture impulse enrollment during initial pet acquisition.
Direct channels dominate installed base. Online platforms are gaining share fastest.
Coverage Level:
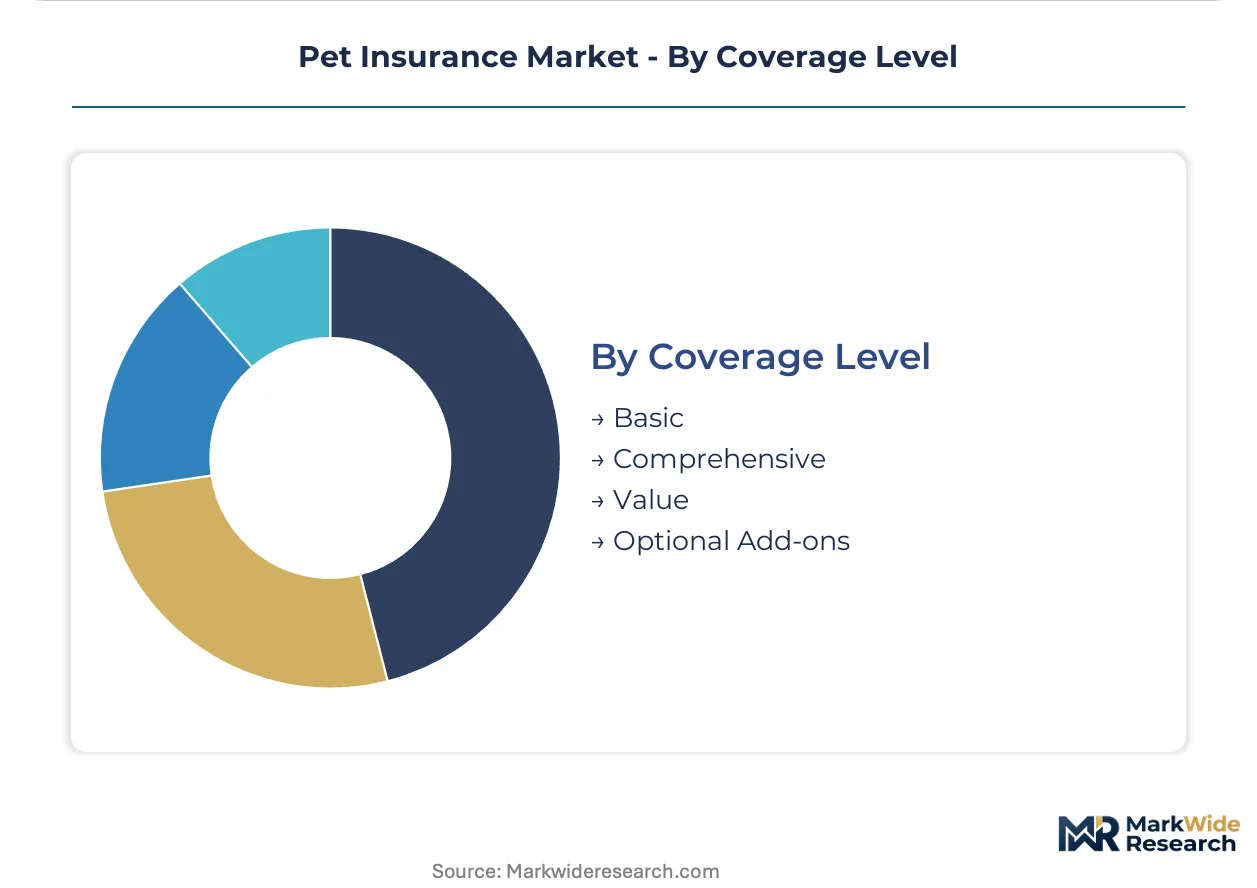
Premium tiers separate risk-averse households seeking comprehensive protection from price-sensitive buyers accepting higher deductibles. Optional add-ons generate incremental revenue beyond base indemnity contracts.
- Comprehensive:Full illness and accident coverage with wellness rider eligibility creates maximum protection profiles. Affluent households in Switzerland and the United Kingdom select this tier for peace of mind against catastrophic veterinary expenditures. Higher premiums support lower loss ratios through adverse selection mitigation.
- Basic:Stripped-down coverage with elevated deductibles and co-payment percentages targets budget-constrained segments. Young professionals in Germany and the Netherlands accept higher out-of-pocket exposure for affordable monthly premiums. Churn rates exceed comprehensive tier benchmarks.
- Value:Mid-tier positioning balances premium affordability with meaningful claim protection.
- Optional Add-ons:Dental, behavioral therapy, and alternative medicine riders attach to base policies.
Comprehensive coverage dominates installed base. Optional add-ons are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Veterinary service chains and insurtech platforms cluster in markets with mature pet ownership demographics and favorable regulatory treatment of alternative distribution channels. Premium growth rates diverge sharply between established markets with legacy provider saturation and emerging markets where first-time penetration drives expansion.
United States
Employer-sponsored enrollment through Fortune 500 benefits portals accelerates policy acquisition among working-age households. The NAIC coordinates state-level rate filings that standardize consumer protection across jurisdictions. Veterinary clinic partnerships in metropolitan Texas and Florida concentrate direct-to-consumer distribution capacity for specialty and exotic pet coverage.
United Kingdom
Legacy providers and digital entrants compete for share of a mature pet-owning population with high lifetime policy penetration. The FCA mandates transparency in policy terms and claims handling that shapes disclosure practices adopted across European operations. London-based insurtech clusters leverage machine learning models trained on multi-year claims histories for granular risk segmentation.
Germany
Corporate wellness bundling through voluntary benefits portals reduces customer acquisition costs for mid-market carriers. The EU Green Deal's sustainability reporting requirements pressure insurers to quantify environmental footprints of paperless operations. Munich and Frankfurt insurance hubs develop predictive underwriting tools using breed-specific health profiles from Dutch and Californian laboratories.
Japan
Urban apartment dwellers favor feline companionship, concentrating policy density in metropolitan postal codes with compressed premiums below canine equivalents. METI guidelines influence product standardization across domestic carriers. Tokyo and Osaka veterinary networks expand telemedicine reimbursement capabilities following regulatory clarity on remote consultation billing codes.
Canada
Digital-native pet owners bypass traditional broker relationships through mobile-optimized comparison platforms with instant quote-to-bind functionality. Health Canada oversight aligns with provincial insurance regulations governing policy terms. Toronto and Vancouver insurtech clusters deploy AI-assisted claims adjudication trained on veterinary invoice databases to accelerate payment processing.
Pet Insurance Market Vendor Landscape
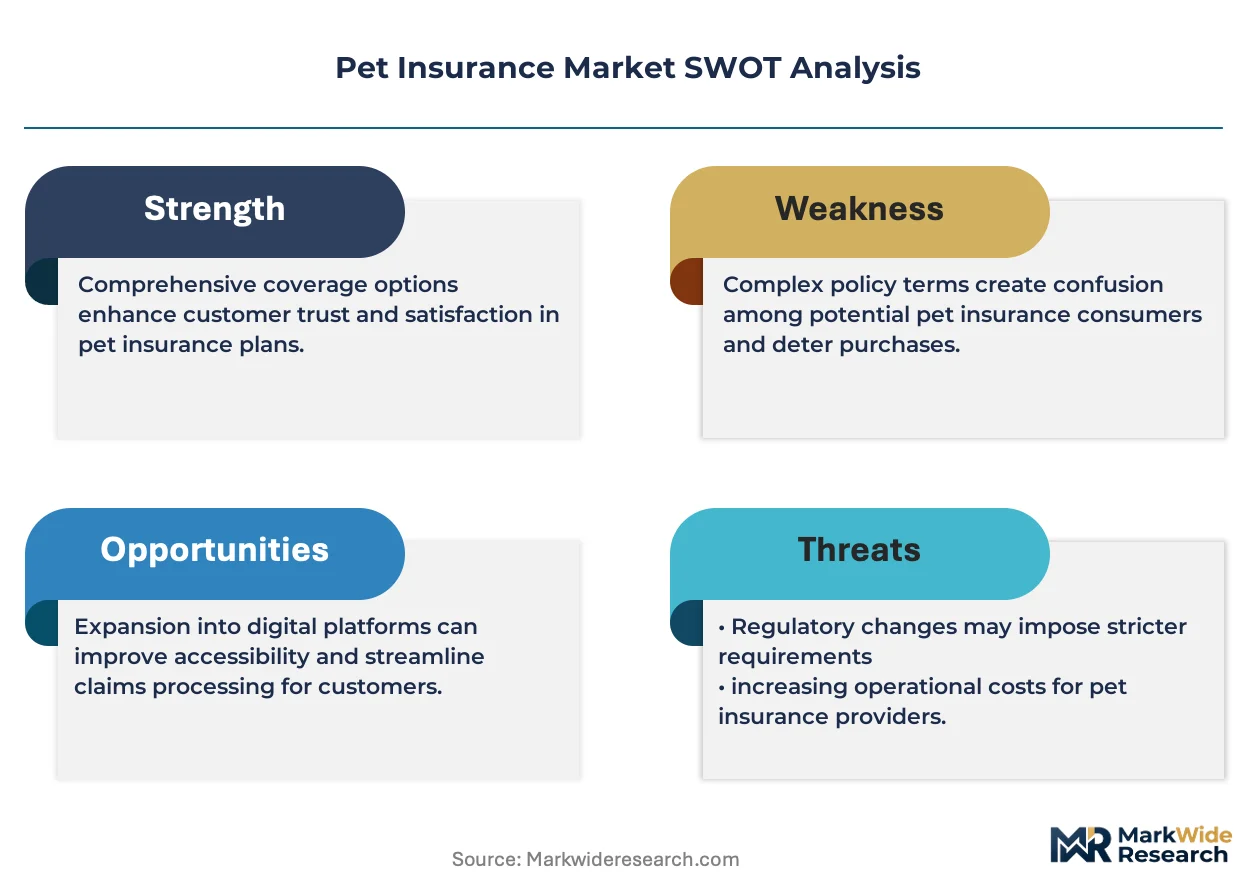
Platform integrators command the system tier; component specialists sit upstream in risk assessment and distribution technology. The market structure consolidates around vertically integrated carriers with captive veterinary networks, while insurtech platforms fragment the direct-to-consumer segment through algorithmic underwriting. Three archetypes dominate: legacy mutual insurers with employer channel dominance, digital-native platforms with AI-driven pricing, and veterinary-embedded direct enrollment specialists. Competitive intensity centers on M&A activity targeting telemedicine capabilities and strategic partnerships bundling preventive care with indemnity contracts.
Among North American carriers, Trupanion and Nationwide Mutual Insurance Company exemplify divergent channel strategies. Trupanion anchors the veterinary-embedded tier through clinic partnership networks that capture customers at point of care. Nationwide occupies the employer-sponsored tier, leveraging group policy structures within Fortune 500 benefits ecosystems. Healthy Paws represents the unlimited coverage archetype, eliminating per-incident and annual caps to differentiate in a market segment sensitive to long-term chronic condition exposure.
| Leading Market Players |
|---|
| Trupanion |
| Nationwide Mutual Insurance Company |
| Embrace Pet Insurance Agency |
| Fetch Pet Insurance |
| Pets Best Insurance Services |
| Healthy Paws |
| ASPCA Pet Insurance |
| Figo Pet Insurance |
| Spot Pet Insurance |
| Others |
Supply Flow & Price Mechanics
Munich and Frankfurt insurance hubs concentrate predictive underwriting capacity that feeds premium pricing power across European operations. Their machine learning infrastructure compresses quote-to-bind timelines while elevating actuarial precision that supports tiered rate structures.
Pricing Analysis
The EU Green Deal's sustainability disclosure mandates dictate the pricing tier structure across German and French operations. Three-tier pricing structure across premium, standard, and economy levels separates comprehensive lifetime coverage from accident-only entry products. Cost compression in the accident-only tier is intensifying because digital-native platforms bypass broker commissions entirely. Young professionals in the Netherlands and Germany exhibit highest price sensitivity, while affluent households in Switzerland accept premium positioning for unlimited coverage terms.
Supply Chain Analysis
Extended payment terms from reinsurance partners in Bermuda and Zurich shape working capital requirements for primary carriers. Veterinary service chains in the United States, United Kingdom, and Canada provide the downstream distribution infrastructure that embeds enrollment at point of care. Predictive underwriting draws from genetic testing laboratories in the Netherlands and California, creating dependencies on specialized diagnostic inputs. Single-source vulnerability concentrates in reinsurance capacity from Bermuda-based catastrophe bond markets. Distribution runs through employer-sponsored benefits portals and direct-to-consumer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Self-funded veterinary savings accounts present a substitution threat that incumbent insurers must neutralize through embedded preventive care bundling.
For Market Incumbents: Insulate premium persistency by embedding wellness subscriptions that reduce claim severity through early intervention. Capture exclusive veterinary clinic partnerships in metropolitan Texas and Florida before insurtech platforms replicate Trupanion's direct-to-consumer model. Vertical integration into telemedicine capabilities defends against digital-native entrants offering virtual triage as a loss-leader acquisition tool. For New Entrants and Emerging Players: Establish a beachhead in exotic pet coverage for reptile and avian species across metropolitan Texas and Florida corridors. Target corporate wellness bundling through voluntary benefits portals in Germany and the United States to bypass individual customer acquisition costs. White-label AI-assisted claims adjudication to mid-tier carriers seeking automation without internal development overhead. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because employer-sponsored enrollment channels embed premiums in payroll deduction systems that sustain persistency. Acquisition targets should display captive veterinary network relationships or proprietary machine learning underwriting models trained on multi-year claims histories. Monitor telemedicine reimbursement rulings from state veterinary boards and the RCVS as inflection indicators for virtual care integration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Clinic Partnership Expansion | Trupanion's direct-to-veterinary model demonstrates defensive moat creation through exclusive point-of-care enrollment. |
| AI-Assisted Claims Adjudication | Machine learning models trained on Canadian and Swedish veterinary invoice databases accelerate payment velocity. |
| Corporate Wellness Bundling | Employer-sponsored channels through Fortune 500 benefits portals reduce customer acquisition costs sustainably. |
| Telemedicine Capability Integration | Regulatory clarity from state veterinary boards and RCVS enables virtual triage bundling without reserve uncertainty. |
| Exotic Pet Coverage Development | Specialized actuarial pools for reptile and avian species in Texas and Florida command premium pricing with limited competition. |
Methodological Framework
A standing panel of actuarial directors, veterinary clinic operators, employer benefits administrators, and insurtech platform engineers provided ongoing calibration across primary research phases. Secondary validation drew from NAIC rate filings, FCA disclosure mandates, EU Green Deal sustainability reporting guidelines, and veterinary cost inflation indices maintained by industry associations. Bottom-up policy enrollment data triangulated against top-down premium pool estimates from regulatory disclosures.
Scenario-bracketing framed the analytical framework across the projection horizon, with CAGRs derived from regression analysis of historical premium growth correlated with veterinary service expansion and pet ownership demographics. Segmentation dimensions modeled include policy type, animal species, sales channel, and coverage level alongside regional regulatory cluster differentiation. Forecast inputs incorporated telemedicine reimbursement rulings and reinsurance capacity trends from Bermuda and Zurich markets.
Stress conditions across veterinary labor scarcity, reinsurance pricing volatility, and digital platform competitive intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory stability in NAIC and FCA jurisdictions and continued employer benefits channel expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Investment Analysis and Financial Strategies
Asia-Pacific Private Equity Market
Investment Analysis and Financial Strategies
Spain Accounting Software Market
Investment Analysis and Financial Strategies
Canada Motor Insurance Market
Investment Analysis and Financial Strategies
Mobile Notary Service Market
Investment Analysis and Financial Strategies
IoT Insurance Market
Investment Analysis and Financial Strategies
Credit Rating Software Market
Investment Analysis and Financial Strategies
Europe Accounts Payable Automation Market
Investment Analysis and Financial Strategies
North America Used Car Financing Market
Investment Analysis and Financial Strategies
Financial Technology Fintech Market
Investment Analysis and Financial Strategies
Spain Mobile Payment Market
Investment Analysis and Financial Strategies
Asia-Pacific Life and Annuity Insurance Market
Investment Analysis and Financial Strategies
Italy Forensic Accounting Market
Investment Analysis and Financial Strategies
Singapore Motor Insurance Market
Investment Analysis and Financial Strategies
P and C Insurance Software Market
Investment Analysis and Financial Strategies
Fund Management Software Market
Investment Analysis and Financial Strategies
Germany E-Brokerage Market