
 Pet Boarding Services Market | 2026-2036
Pet Boarding Services Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Boarding Services Market Analytics
Franchise networks is rewriting competitive access across the Pet Boarding Services landscape. Dogtopia Enterprises leverages its membership-based model to secure recurring revenue streams in suburban corridors. PetSmart LLC anchors market presence through co-located boarding within retail supercenters, blending convenience with scale. Camp Bow Wow competes via its play-centered daycare-to-overnight service ladder, building customer lifetime value through activity-based differentiation.
Pet boarding services encompass supervised overnight care, exercise programming, and health monitoring for companion animals in licensed commercial or residential facilities, typically requiring climate-controlled kennels, staff-to-pet ratios, and vaccination verification as core operational parameters. The primary commercial purpose centers on replacing informal care arrangements with standardized, insured alternatives for traveling or working pet owners. Luxury kennels and home-based boarding now capture the most attractive margin pools, as pet owners trade up from standard kennels toward personalized, lower-density environments. Daycare services represent the fastest-expanding service type, driven by weekday drop-off routines that convert into extended-stay bookings.
USDA Animal Welfare Act licensing, state-level Department of Agriculture facility inspections, and local zoning boards collectively govern market entry and operating standards across American jurisdictions. FDA guidelines on pet food safety and state veterinary practice acts further shape ancillary service bundling and staff credentialing requirements. Stakeholders must monitor evolving municipal short-term rental ordinances that increasingly classify home-based boarding as commercial lodging subject to new permitting layers.
Market Dynamics
Dual-income household expansion is compressing informal care networks and forcing pet owners toward licensed commercial boarding facilities with standardized operational protocols.
Growth Catalysts
- USDA Animal Welfare Act licensing:Federal facility standards elevate consumer trust and accelerate conversion from informal neighbor arrangements to insured commercial alternatives.
- Smartphone-enabled booking platforms:Real-time availability visibility and digital payment integration reduce friction in reservation workflows for time-constrained professionals.
- Suburban corridor density:Clustered dual-income households in exurban zones generate sufficient demand concentration to support dedicated facility economics.
Market Restraints
- Veterinary labor scarcity:Licensed technician availability constraints limit facility expansion in markets with concentrated demand.
- Municipal zoning friction:Local land-use boards classify kennel operations as commercial lodging, triggering multi-layer permitting delays in residential-adjacent zones.
- Home-based boarding substitution:Unlicensed residential operators capture price-sensitive demand through peer-to-peer platforms, eroding formal market capture rates.
Strategic Opportunities
- Veterinary clinic co-location:Adjacent boarding capacity within animal hospital campuses captures medical-adjacent demand and enables premium health-monitoring service tiers.
- Corporate employer partnerships:Workplace pet-benefit programs create B2B subscription channels for weekday daycare conversion to overnight stays.
- Aging pet demographic specialization:Geriatric companion animals require medication administration and mobility assistance, opening differentiated service verticals.
Industry Challenges
- Staff credentialing pipelines:State veterinary practice acts mandate supervised hours for animal handling certification, constraining rapid workforce scaling.
- Climate control capex:HVAC redundancy requirements for kennel licensing impose upfront infrastructure investments that strain independent operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Boarding Services Market |
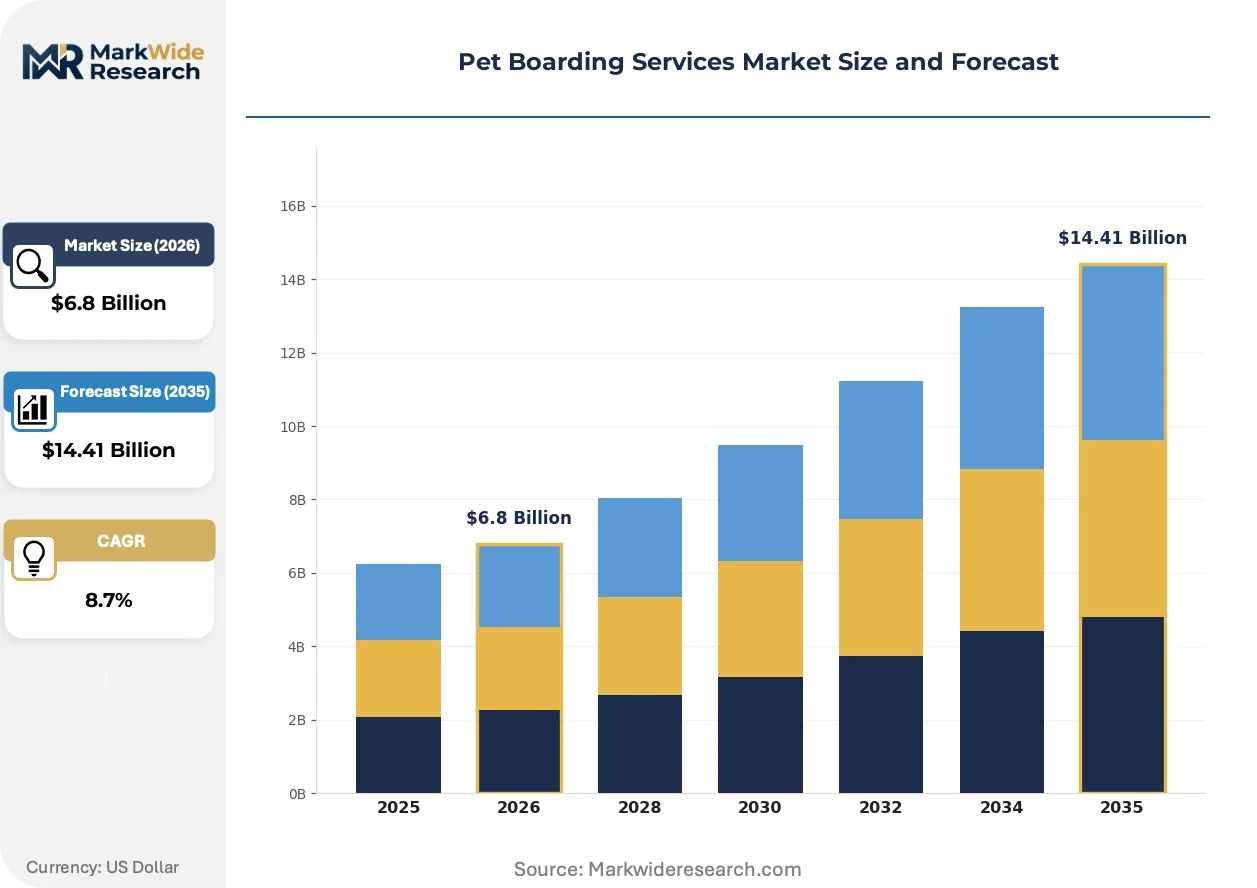
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dog Boarding, Cat Boarding, Exotic Pet Boarding, Daycare Services Facility Type: Luxury Kennels, Standard Kennels, Home-Based Boarding, Veterinary Clinics Payment Model: Daily Rate, Weekly Packages, Membership Plans, Pay-as-You-Go Additional Services: Grooming, Training, Feeding, Playtime Activities |
| Companies Covered | Dogtopia Enterprises, Fetch! Pet Care, PetSmart LLC, PetBacker, We Love Pets, Camp Bow Wow, A Place for Rover, Inc., Urban Tails Pet Resort, Rover, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Boarding Services Market Evolving Landscape
Facility operators are deploying sensor networks and predictive analytics to replace manual welfare checks with continuous environmental monitoring and behavioral pattern recognition.
Internet-of-Things collar systems is digitizing pet location tracking, activity logging, and biometric alerting across premium boarding facilities. Millennial pet owners adopting these transparency features expect real-time mobile dashboard access during travel absences. This visibility compression is collapsing information asymmetry between operators and clients, forcing standard kennels toward technology parity or margin erosion.
State-level Department of Agriculture inspection protocols are tightening ventilation, sanitation, and staff-to-pet ratio mandates. Facilities must document continuous temperature logging and isolation capacity for infectious disease containment. Luxury and home-based segments absorb compliance costs through pricing power, while budget operators face consolidation pressure from capital requirements.
Subscription-based membership models are displacing transactional nightly bookings among frequent travelers. Corporate road warriors and consulting professionals pre-commit to monthly daycare-to-boarding tiers, locking capacity and smoothing revenue volatility for facility operators. This preference shift concentrates most visibly in United States metropolitan corridors with high business travel density.
Pet Boarding Services Market Segmentation
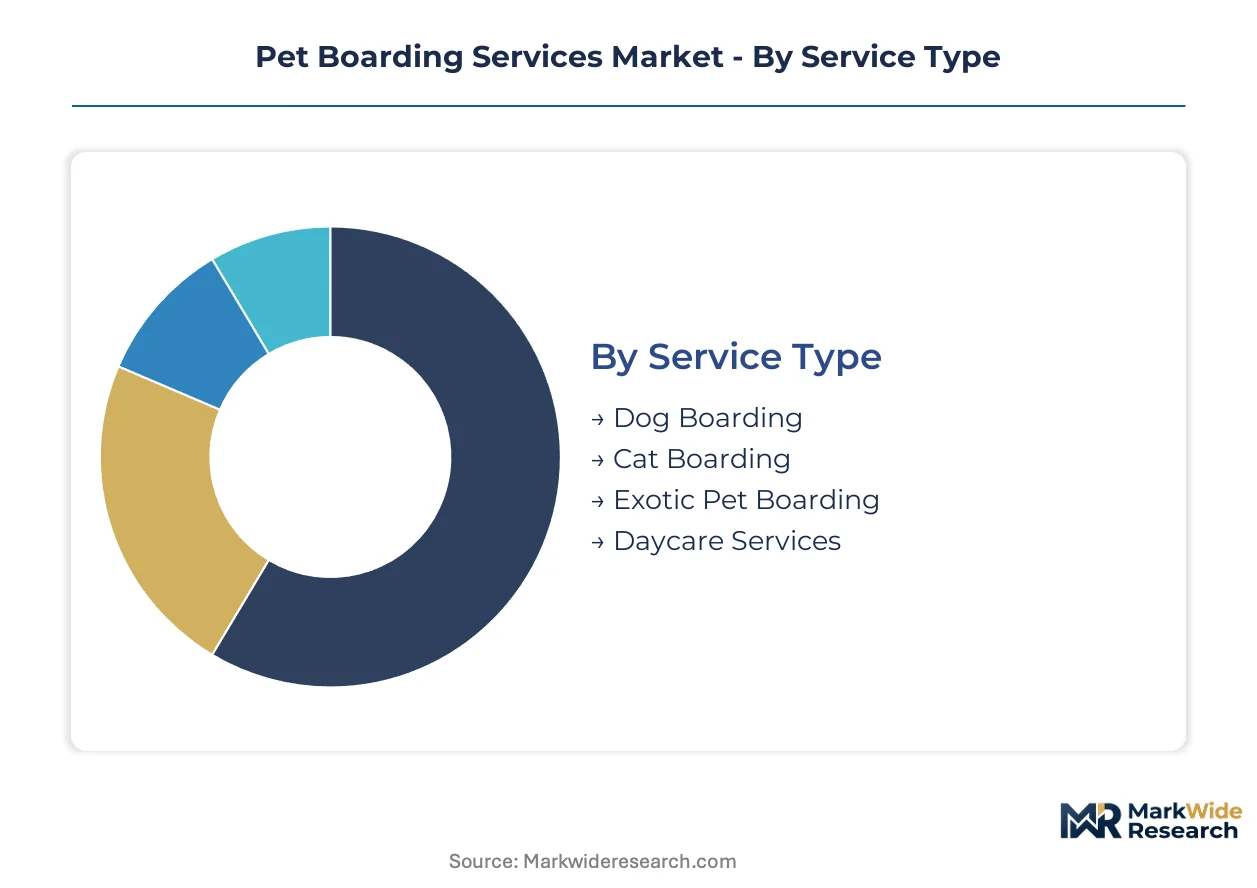
Pet boarding services fragment across service delivery models, facility configurations, and pricing architectures that reshape customer acquisition costs and lifetime value calculations. Understanding these segment boundaries clarifies where capital deployment yields margin expansion versus commodity competition.
Service Type:
Mature overnight care segments coexist with emerging daycare formats that convert frequency into loyalty.
- Dog Boarding:Climate-controlled kennel environments with supervised exercise protocols dominate facility design standards. Demand concentrates in United States suburban corridors where dual-income households lack informal care networks, with USDA licensing requirements elevating operational compliance costs.
- Cat Boarding:Separate ventilation systems and vertical climbing structures distinguish feline-specific facilities from multi-species operations. Urban clusters in Texas and California generate sufficient density to support dedicated cat-only boarding economics.
- Exotic Pet Boarding:Specialized habitat replication for reptiles, birds, and small mammals requires species-specific temperature and humidity controls.
- Daycare Services:Weekday drop-off routines convert into extended-stay bookings through activity-based differentiation and staff relationship continuity.
Dog boarding retains volume leadership; daycare services hold the steepest expansion curve.
Facility Type:
Cost tier stratification separates capital-intensive premium operations from asset-light residential alternatives.
- Luxury Kennels:Private suites with webcam access, custom feeding protocols, and spa service bundling command pricing premiums through experience differentiation. Affluent ZIP codes in New York, Florida, and Illinois sustain dedicated luxury facility economics.
- Home-Based Boarding:Lower-density residential environments capture pet owners seeking personalized attention over institutional scale. Municipal short-term rental ordinances increasingly subject these operators to commercial lodging permits.
- Standard Kennels:Functional kennel row configurations with basic exercise yards serve price-sensitive demand through operational efficiency.
- Veterinary Clinics:Co-located boarding within animal hospital campuses enables medical-adjacent demand capture and premium health-monitoring tiers.
Standard kennels retain volume leadership; veterinary clinic boarding holds the steepest expansion curve.
Payment Model:
Customer type preferences are shifting from transactional nightly bookings toward pre-committed subscription relationships.
- Membership Plans:Monthly daycare-to-boarding tiers lock capacity and smooth revenue volatility for operators serving corporate road warriors. Business travel density in metropolitan corridors drives subscription adoption.
- Weekly Packages:Bundled multi-night discounts reduce per-night price sensitivity for vacation travelers.
- Daily Rate:Single-night transactional pricing remains prevalent for infrequent users and emergency boarding situations.
- Pay-as-You-Go:Digital wallet integration and smartphone-enabled booking platforms reduce friction for spontaneous reservations.
Daily rate structures retain volume leadership; membership plans hold the steepest expansion curve.
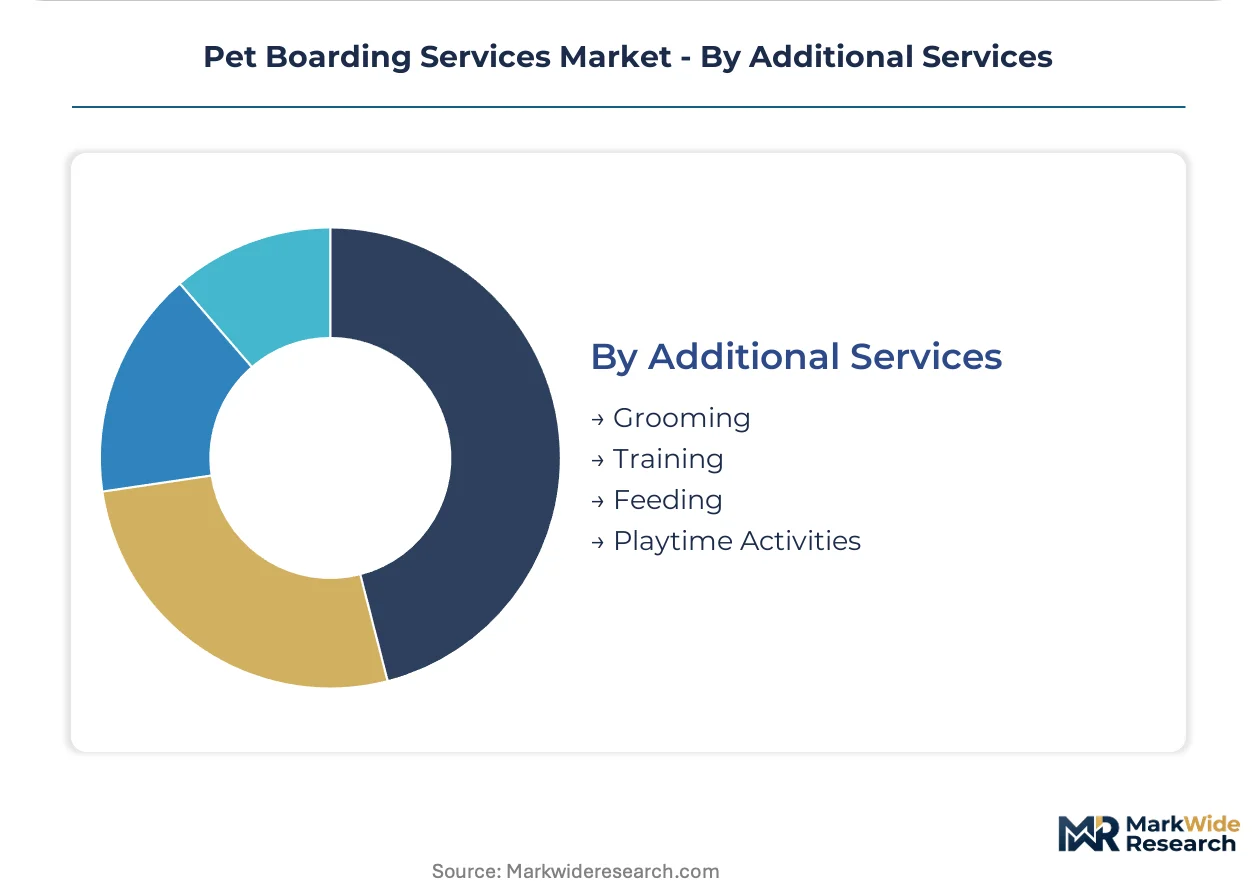
Additional Services:
Margin contribution from ancillary offerings varies by labor intensity and equipment specialization.
- Grooming:Bathing, coat maintenance, and nail trimming generate incremental revenue with dedicated hydrotherapy and drying infrastructure.
- Training:Obedience sessions and behavioral modification programs extend customer engagement duration.
- Feeding:Medication administration and prescription diet management serve geriatric pet demographics with specialized care requirements.
- Playtime Activities:Supervised group socialization and individual enrichment sessions differentiate daycare-to-boarding conversion funnels.
Feeding services retain volume leadership; playtime activities hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate highway network and dense suburban corridor development across the United States underwrite the geography's dominance in facility-based pet care infrastructure. Dual-income household concentration and premium pet spending norms sustain facility economics at scale unmatched elsewhere.
United States
Suburban corridor density in Texas, Florida, and Illinois generates sufficient demand concentration to support dedicated facility economics. USDA Animal Welfare Act licensing elevates operational compliance costs while accelerating conversion from informal neighbor arrangements to insured commercial alternatives. Dallas-Fort Worth and Houston metropolitan clusters anchor multi-location franchise expansion for membership-based operators.
Canada
Urban pet ownership rates in Toronto and Vancouver sustain premium facility economics despite smaller market scale. Provincial Department of Agriculture facility inspections govern operating standards alongside municipal zoning boards that classify kennel operations as commercial lodging. Calgary and Montreal emerge as secondary hubs where veterinary clinic co-location strategies capture medical-adjacent demand.
United Kingdom
London commuter belt density and weekday daycare routines drive conversion to extended-stay bookings among consulting professionals. DEFRA licensing requirements and local authority animal welfare inspections tighten facility standards beyond baseline EU norms. Home counties surrounding Greater London concentrate home-based boarding substitution that municipal short-term rental ordinances increasingly subject to commercial permitting.
Germany
Affluent metropolitan corridors in Bavaria and North Rhine-Westphalia sustain luxury kennel economics through experience differentiation. Federal animal welfare regulations and state-level veterinary practice acts mandate supervised handling certification that constrains rapid workforce scaling. Munich and Frankfurt clusters anchor subscription-based membership models displacing transactional nightly bookings among corporate road warriors.
Australia
Eastern seaboard urbanization in New South Wales and Victoria generates demand concentration for climate-controlled kennel infrastructure. State-level Department of Agriculture inspection protocols tighten ventilation and sanitation mandates that strain independent operator balance sheets. Sydney and Melbourne metropolitan zones absorb compliance costs through pricing power while budget operators face consolidation pressure.
Pet Boarding Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in facility operations and ancillary service delivery. The vendor base clusters around three strategic archetypes: membership-based franchise networks, retail-anchored supercenter operators, and peer-to-peer marketplace platforms. Consolidation pressure concentrates among standard kennel operators unable to absorb climate control capex requirements. Dominant competitive moves include veterinary clinic co-location partnerships and smartphone-enabled booking platform deployment.
Within the franchise network tier, Dogtopia Enterprises and Camp Bow Wow exemplify membership-based models that lock recurring revenue through suburban corridor density. PetSmart LLC anchors retail-anchored positioning through co-located boarding within supercenter footprints. Among peer-to-peer facilitators, Rover, Inc. and A Place for Rover, Inc. occupy positions that aggregate unlicensed residential supply against formal facility alternatives. These three archetypes—franchise membership, retail integration, and marketplace aggregation—capture distinct customer lifetime value profiles across the pricing spectrum.
| Leading Market Players |
|---|
| Dogtopia Enterprises |
| Fetch! Pet Care |
| PetSmart LLC |
| PetBacker |
| We Love Pets |
| Camp Bow Wow |
| A Place for Rover, Inc. |
| Urban Tails Pet Resort |
| Rover, Inc. |
| Others |
Value Network & Pricing Analysis
Municipal zoning friction as a regulatory chokepoint determines both pricing tier spreads and supply chain shape across the pet boarding services landscape. Local land-use boards classify kennel operations as commercial lodging, triggering multi-layer permitting delays that concentrate facility development in suburban corridors with compliant zoning inventory.
Pricing Analysis
Volume-discount tiering structures dominate the payment architecture, with membership plans locking recurring revenue against transactional nightly rates. Pricing stratifies across premium, standard, and economy tiers based on facility amenity density and staff-to-pet ratios, with luxury kennels commanding premiums through webcam access and custom feeding protocols. Cost compression in the standard kennel tier is intensifying because climate control capex requirements strain independent operator balance sheets. Price-sensitive demand concentrates among infrequent users selecting daily rate structures, while corporate road warriors exhibit lowest sensitivity through pre-committed subscription relationships.
Supply Chain Analysis
Extended payment terms from HVAC and kennel equipment suppliers have become critical financing mechanisms for independent operators facing upfront infrastructure investments. Manufacturing concentration for climate control systems draws from the United States, China, and Germany, while specialized veterinary equipment sources from the Netherlands and Switzerland. Supply chain risk centers on single-source vulnerability for IoT-enabled collar systems and sensor networks. Distribution runs through regional facility supply distributors serving franchise networks and independent operators across metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive positioning in pet boarding services, with smartphone-enabled booking platforms collapsing information asymmetry between operators and clients. Interoperability between membership systems and corporate HR benefit portals is reshaping customer acquisition economics.
For Market Incumbents: Entrench suburban corridor density through exclusive veterinary clinic co-location partnerships that capture medical-adjacent demand. Lock capacity through corporate employer subscription channels before emerging aggregators consolidate weekday daycare conversion. Climate control capex requirements and USDA licensing standards create defensive moats against unlicensed residential substitution.
For New Entrants and Emerging Players: Pursue home-based boarding segments in municipalities where short-term rental ordinances remain unenforced, capturing price-sensitive demand through personalized attention value propositions. Target geriatric pet specialization with medication administration capabilities, as aging companion animal demographics open differentiated service verticals. Deploy peer-to-peer marketplace aggregation as the primary go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors membership-based franchise networks with recurring revenue visibility. Long-term viability hinges on technology parity for transparency features and sensor network deployment. Watch municipal short-term rental enforcement patterns as the signal indicating formal market capture rate inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Clinic Co-location | Adjacent boarding capacity within animal hospital campuses captures medical-adjacent demand and enables premium health-monitoring tiers. |
| Membership Model Deployment | Monthly daycare-to-boarding subscriptions lock capacity and smooth revenue volatility for operators serving corporate road warriors. |
| IoT Sensor Network Integration | Continuous environmental monitoring and behavioral pattern recognition replace manual welfare checks across premium facilities. |
| Corporate Employer Partnership | Workplace pet-benefit programs create B2B subscription channels for weekday daycare conversion to overnight stays. |
| Geriatric Pet Specialization | Medication administration and mobility assistance capabilities serve aging companion animals with differentiated care requirements. |
Research Methodology
A standing panel of facility operators, veterinary practice managers, municipal zoning officials, and franchise development executives provided ongoing calibration throughout the research process. Primary interviews with these stakeholders combined with secondary validation from USDA Animal Welfare Act licensing records, state Department of Agriculture inspection protocols, municipal zoning board filings, and franchise disclosure documents. Bottom-up facility count modeling and top-down pet ownership demographic analysis enabled triangulation across data sources.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions including service type, facility configuration, payment model, and regional regulatory cluster. CAGRs derived from facility expansion trajectories, dual-income household formation rates, and premium pet spending elasticity. Forecast inputs incorporated municipal zoning pipeline data and veterinary technician workforce pipeline constraints.
Sensitivities concentrate around municipal short-term rental ordinance enforcement intensity and veterinary labor scarcity resolution. Forecasts reflect assumptions regarding smartphone-enabled booking platform penetration and corporate pet-benefit program adoption. Macroeconomic deviation in dual-income household formation, regulatory shifts in facility licensing standards, or technological disruption in remote pet monitoring would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare
South America Body Temperature Monitoring Market
Healthcare
US Integrated Delivery Network Market
Healthcare
Intratumoral Cancer Therapies Market
Healthcare
Teledentistry Market
Healthcare
Global DNA Test Kit Market
Healthcare
Computed Tomography (CT) Scanners Market
Healthcare
Diabetic Assays Market
Healthcare
Alpha Emitter Market
Healthcare
Wrist Replacement Orthopedic Devices Market
Healthcare
Enterprise Medical Image Viewers Market
Healthcare
Sweden Respiratory Devices Market
Healthcare
Global Autoimmune Disease Therapeutics Market
Healthcare
Monkeypox Vaccine and Treatment Market
Healthcare
Italy OTC Drugs Market
Healthcare
Dermal Allograft Market
Healthcare
Cardiovascular Ultrasound Market