
 Personal Protective Gloves Market | 2026-2036
Personal Protective Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Protective Gloves Market Analysis
Asset-light leasing models for automated glove production lines is reconfiguring competitive entry barriers for mid-tier manufacturers. Hartalega Holdings Berhad anchors its position through proprietary nitrile formulation technology and high-speed production infrastructure. Top Glove Corporation Bhd leverages integrated rubber sourcing across plantation networks to sustain margin control. Ansell Ltd differentiates through specialized chemical-resistant portfolios serving laboratory and industrial channels.
Personal protective gloves are barrier garments engineered from elastomeric compounds—nitrile butadiene rubber, natural latex, or synthetic polyisoprene—with thickness specifications typically ranging from 3 to 15 mils depending on hazard exposure levels, manufactured through coagulant dipping or chlorination finishing processes to achieve tactile sensitivity and chemical permeation resistance. Nitrile formulations now lead procurement volumes across healthcare and chemical handling applications due to latex allergy prevalence and superior puncture resistance. The medical application segment concentrates margin pools in sterilized surgical grades, while food processing demand standardizes around powder-free vinyl and nitrile disposables with FDA compliance documentation.
OSHA mandates govern industrial hand protection requirements in the United States, while the EU MDR and REACH frameworks constrain chemical composition and biocompatibility standards for European market access. FDA enforcement of Quality System Regulation for medical-grade gloves shapes manufacturer audit burdens and import documentation. Stakeholders must monitor evolving nitrile raw material pricing volatility and regulatory harmonization pressures between major economies to calibrate capacity planning and certification investments.
Market Dynamics
Malaysia's dominance in nitrile butadiene rubber processing has created a supply-side chokepoint where raw material pricing volatility now transmits directly into manufacturer margin compression across all tiers.
Growth Catalysts
- OSHA Bloodborne Pathogen Standard:United States healthcare facilities must maintain universal precautions requiring disposable glove inventories, institutionalizing replacement demand cycles regardless of economic conditions.
- Chemical handling protocols:Semiconductor fabrication and battery manufacturing facilities are expanding nitrile glove consumption for cleanroom compatibility and solvent resistance.
- Coagulant dipping automation:High-speed production lines achieving 35,000 pieces per hour are lowering unit economics for powder-free formulations.
Market Restraints
- Acrylonitrile monomer concentration:Butadiene and acrylonitrile feedstock pricing tracks crude oil and petrochemical indices, exposing margin structures to energy market volatility.
- Single-geometry supply clustering:Over 60% of nitrile glove capacity sits within 200 kilometers of Kuala Lumpur, creating geographic concentration risk for procurement continuity.
- Latex protein residue limitations:Type I hypersensitivity prevalence restricts natural rubber latex to niche applications despite superior elasticity.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO-mandated quality upgrades in active pharmaceutical ingredient facilities are accelerating medical-grade glove specification.
- EU MDR compliance gap:European medical device regulation recertification timelines are displacing non-compliant suppliers and creating share capture potential for certified manufacturers.
- Chlorination finishing + antimicrobial additive convergence:Surface modification technologies enabling extended-wear surgical applications are opening premium pricing tiers.
Industry Challenges
- Polymer compounding expertise scarcity:Formulation chemists capable of balancing tensile strength against tactile sensitivity command premium compensation and limited availability.
- FDA 510(k) clearance timelines:Medical-grade glove certification requires 12-18 month validation cycles that delay revenue recognition for new product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Protective Gloves Market |
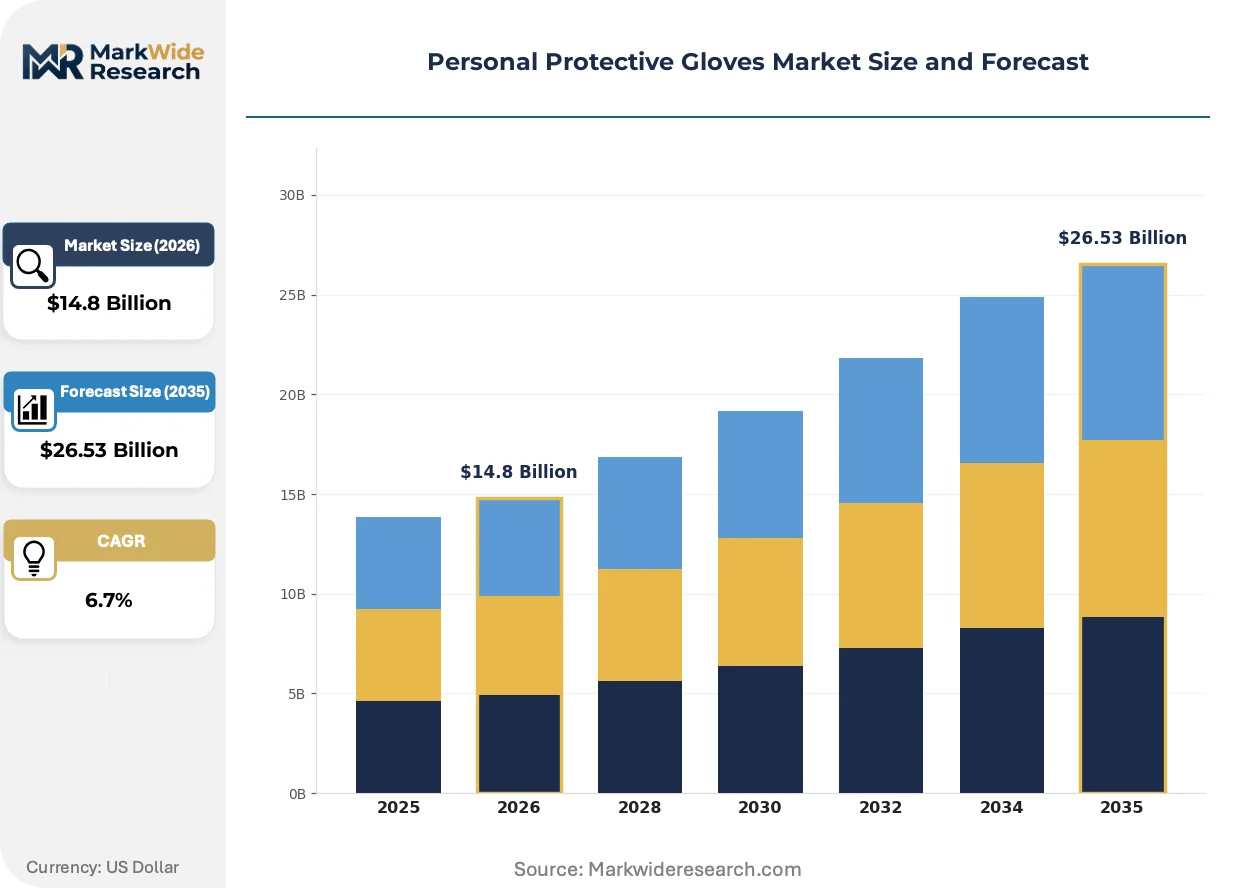
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrile, Latex, Vinyl, Neoprene End User: Healthcare, Industrial, Food Service, Construction Application: Medical, Laboratory, Chemical Handling, Food Processing Size: Small, Medium, Large, Extra Large |
| Companies Covered | Top Glove Corporation Bhd, Kossan Rubber Industries Bhd, Hartalega Holdings Berhad, Ansell Ltd, 3M, Honeywell International Inc., DuPont, Lakeland Industries, Supermax Corporation Berhad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Protective Gloves Market Emerging Trajectories
Automation is compressing production economics while regulatory fragmentation is forcing parallel certification strategies. Material science advances are enabling thinner barriers without sacrificing puncture resistance.
Digital twin simulation of coagulant dipping lines is virtualizing process optimization, allowing manufacturers to model thickness distribution and defect rates before physical line commissioning. Tier-one producers in Malaysia and Thailand are deploying these tools to reduce startup waste by half. The technology is virtualizing capital deployment decisions and shortening time-to-volume for capacity expansions.
REACH Annex XVII restrictions on chemical substances are forcing reformulation of plasticizers and accelerators used in nitrile vulcanization. Manufacturers serving European Union markets must maintain dual inventory streams—REACH-compliant and standard formulations. Medical-grade suppliers with EU MDR technical documentation are absorbing compliance costs into premium pricing while industrial channels face margin pressure.
Hospital procurement consortiums are consolidating glove purchasing through standardized specification contracts that displace distributor intermediaries. Integrated delivery networks in the United States are negotiating direct manufacturer relationships with multi-year volume commitments. The shift is most visible in acute care settings where GPOs command 70% of purchasing volume.
Personal Protective Gloves Market Segmentation
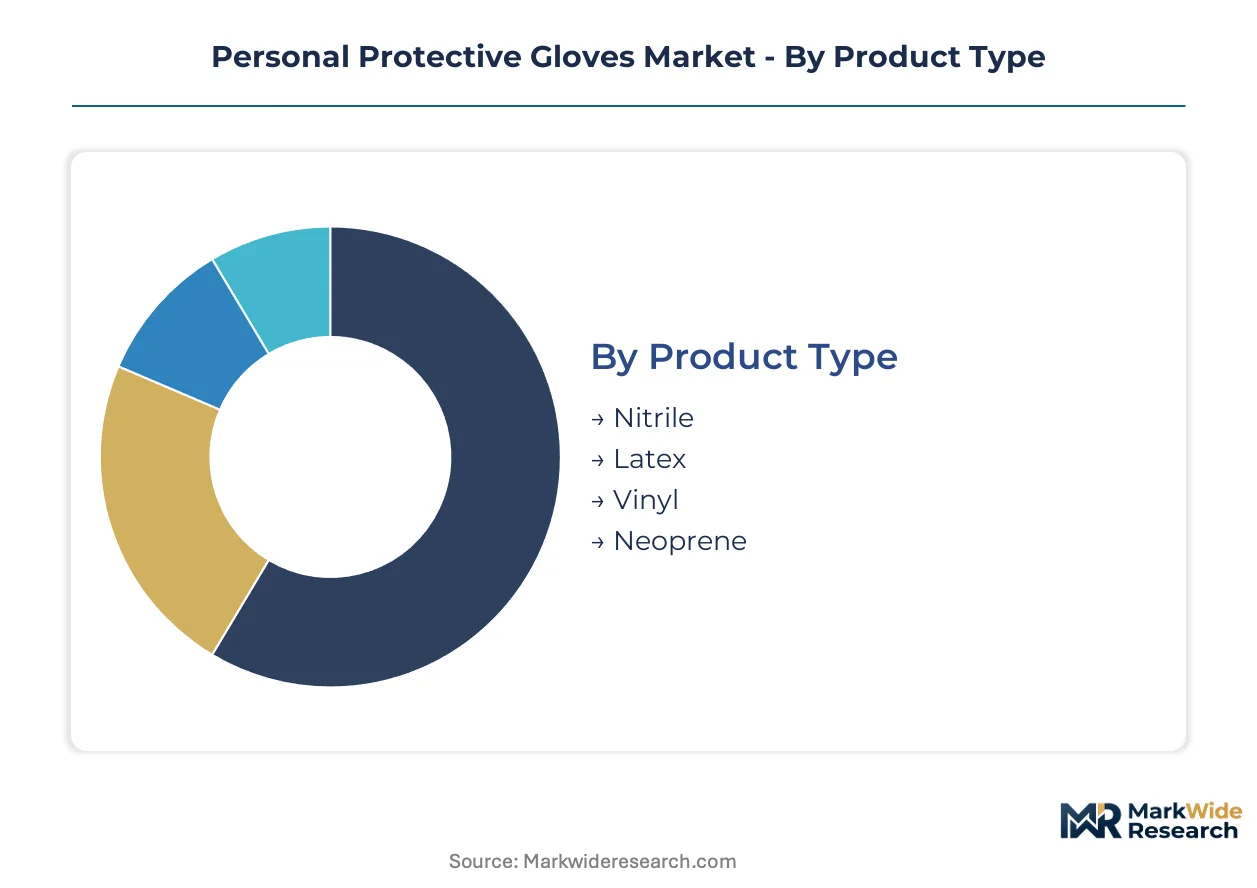
Protective glove procurement varies sharply by hazard exposure, regulatory environment, and replacement frequency. Manufacturers configure production lines around specific polymer formulations and thickness profiles to match end-use certification requirements rather than pursuing universal coverage.
Product Type:
Mature nitrile formulations dominate hospital procurement, while emerging alternatives target allergy-sensitive and specialty chemical markets.
- Nitrile:Nitrile butadiene rubber compounds deliver puncture resistance three times higher than latex with zero protein allergen content. Acute care facilities in the United States specify nitrile for universal precautions under OSHA mandates, with semiconductor cleanrooms adding solvent-resistant grades for wafer handling protocols.
- Latex:Natural rubber latex maintains superior elasticity and tactile sensitivity for surgical precision tasks. Malaysia's integrated plantation-to-glove supply chains concentrate latex production, though Type I hypersensitivity prevalence restricts deployment to double-gloving scenarios and specialized dental applications.
- Vinyl:Polyvinyl chloride formulations serve cost-sensitive food service and janitorial segments where puncture risk remains minimal.
- Neoprene:Chloroprene rubber withstands petroleum-based solvents and caustic chemicals in industrial maintenance and laboratory settings.
Nitrile handles the majority of throughput; neoprene is gaining share fastest in chemical-process industries.
End User:
Customer procurement scale ranges from institutional volume contracts to fragmented small-lot purchasing.
- Healthcare:Hospital systems negotiate multi-year supply agreements through group purchasing organizations, with FDA 510(k) clearance mandatory for sterile surgical grades. Infection control protocols mandate single-use disposal after every patient contact.
- Industrial:Manufacturing facilities specify chemical permeation ratings and abrasion resistance per ANSI/ISEA hand protection standards. Automotive assembly and metal fabrication drive bulk purchasing of cut-resistant and impact-protection variants.
- Food Service:Restaurants and processing plants require powder-free formulations with FDA food contact substance compliance for direct food handling.
- Construction:General contractors source leather-palm work gloves and coated knit varieties for masonry and framing crews through distributor channels.
Healthcare commands the steepest pricing tiers; food service shows the most rapid volume expansion as safety culture penetrates smaller operators.
Application:
Certification burden separates medical-grade from general-purpose segments.
- Medical:Sterilized surgical gloves undergo biocompatibility testing per ISO 10993 standards with lot-level traceability. EU MDR technical documentation requirements are displacing non-compliant suppliers from European hospital tenders.
- Laboratory:Research facilities specify extended-cuff designs and chemical permeation data for reagent handling. Academic and pharmaceutical R&D labs drive demand for low-particulate cleanroom-compatible formulations.
- Chemical Handling:Industrial laundries and battery manufacturing require breakthrough-time documentation against specific solvent classes.
- Food Processing:USDA-inspected facilities mandate blue-colored detectable gloves for foreign material control in meat and poultry operations.
Medical applications absorb the highest certification overhead; laboratory demand is climbing fastest as biopharma R&D spending accelerates.
Size:
Fit standardization enables inventory pooling across large user populations.
- Small:Precision assembly tasks and dental hygienist procedures require snug fit for tactile instrument control.
- Medium:The most commonly stocked size across healthcare and food service operations, supporting bulk procurement economies.
- Large:Industrial maintenance and construction trades specify larger dimensions for comfort during extended wear periods.
- Extra Large:Heavy-duty chemical handling and specialized protective equipment integration accommodate broader hand geometry.
Medium size rotates through inventory fastest; extra large shows tightest supply availability due to production line calibration constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA mandates in the United States institutionalize replacement demand cycles for disposable gloves regardless of economic conditions. Malaysia's manufacturing corridor attracts capacity investment for nitrile production. Germany's EU MDR compliance requirements reshape supplier qualification for European hospital procurement.
United States
Hospital systems negotiate multi-year supply agreements through group purchasing organizations. FDA enforces Quality System Regulation for medical-grade glove import documentation. The Southeast industrial corridor hosts distribution hubs serving acute care networks with sterilized surgical inventory.
Germany
Chemical handling protocols in semiconductor fabrication expand nitrile consumption for cleanroom compatibility. REACH Annex XVII restricts plasticizers in vulcanization processes. The Rhine-Ruhr industrial zone concentrates laboratory and pharmaceutical R&D glove procurement.
Malaysia
Integrated plantation-to-glove supply chains sustain natural rubber latex production for surgical precision applications. The country's national standards body enforces quality benchmarks for export certification. The Klang Valley corridor hosts high-speed automated dipping lines achieving 35,000 pieces per hour.
China
Battery manufacturing facilities expand nitrile glove consumption for solvent resistance in electrode processing. NMPA regulates medical device registration for sterile surgical grades. The Yangtze River Delta clusters electronics cleanroom suppliers specifying low-particulate formulations.
India
Pharmaceutical manufacturing expansion accelerates medical-grade glove specification for active ingredient facilities. CDSCO mandates quality upgrades in sterile production environments. Maharashtra's API manufacturing belt drives procurement volume for powder-free nitrile disposables.
Personal Protective Gloves Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Malaysian manufacturers anchor supply through integrated raw material sourcing and high-volume automated production. Three archetypes dominate: plantation-integrated latex producers, petrochemical-linked nitrile specialists, and diversified industrial safety conglomerates. Capacity expansion and formulation licensing represent the dominant competitive moves as firms defend margin structures against feedstock volatility.
Within the plantation-integrated tier, Top Glove Corporation Bhd and Hartalega Holdings Berhad occupy positions exemplifying backward control over rubber sourcing. Kossan Rubber Industries Bhd represents the nitrile-specialist archetype with petrochemical-linked formulation capabilities. Ansell Ltd anchors the diversified safety portfolio segment serving laboratory and industrial channels with chemical-resistant product lines.
| Leading Market Players |
|---|
| Top Glove Corporation Bhd |
| Kossan Rubber Industries Bhd |
| Hartalega Holdings Berhad |
| Ansell Ltd |
| 3M |
| Honeywell International Inc. |
| DuPont |
| Lakeland Industries |
| Supermax Corporation Berhad |
| Others |
Supply Flow & Price Mechanics
Overcapacity signals from Malaysia's Klang Valley dipping lines are pressuring spot pricing for standard nitrile grades while tightening availability for FDA-cleared surgical inventories, forcing buyers to choose between volume discounts and certification premiums.
Pricing Analysis
Certification level creates the primary spread across personal protective gloves, with FDA 510(k)-cleared surgical grades commanding substantial premiums over industrial nitrile disposables. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10993 biocompatibility testing burdens, volume scale commitments from GPOs, and geographic delivery cost differentials. Cost compression in standard nitrile is intensifying because Malaysian producers are absorbing acrylonitrile feedstock volatility to maintain utilization rates. Hospital systems through GPO contracts show lowest price sensitivity, while food service distributors and janitorial procurement teams exhibit highest elasticity to per-unit movements.
Supply Chain Analysis
Extended payment terms now stretch to 90-120 days for distributor relationships as Malaysian manufacturers deploy supply-chain finance facilities to preserve working capital amid feedstock margin squeeze. Production gravity centers on Malaysia, Thailand, and China, with the Klang Valley corridor hosting over sixty percent of nitrile capacity. Raw material sourcing draws from butadiene crackers in Singapore and Rotterdam, acrylonitrile monomer from Korean petrochemical complexes, and coagulant chemicals from German specialty suppliers. Single-geometry clustering within 200 kilometers of Kuala Lumpur creates geographic concentration risk for procurement continuity. Distribution runs through integrated delivery networks and medical-surgical distributors serving acute care facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where FDA and EU MDR certification entrenchment creates substantial switching costs for hospital procurement committees, defending incumbent positions against price-only competition.
For Market Incumbents: Harden certification portfolios through accelerated EU MDR technical documentation submissions before recertification deadlines displace non-compliant rivals. Deepen backward integration into nitrile butadiene rubber compounding capabilities to insulate margin structures from acrylonitrile monomer volatility. Anchor capacity expansion in Thai industrial zones to diversify geographic risk beyond Malaysia's Klang Valley chokepoint.
For New Entrants and Emerging Players: Establish a beachhead in India's pharmaceutical manufacturing belt where CDSCO-mandated quality upgrades are accelerating medical-grade glove specification ahead of domestic capacity buildout. Target chlorination finishing with antimicrobial additive convergence for extended-wear surgical applications where premium pricing tiers remain underdeveloped. Pursue asset-light leasing models for automated production lines to compress competitive entry barriers without capital-intensive greenfield commitments.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among plantation-integrated latex producers with captive rubber sourcing and long-term hospital system contracts. Five-to-ten year viability favors manufacturers with dual REACH-compliant and standard formulation inventory streams serving European laboratory channels. Monitor FDA 510(k) clearance timeline acceleration as signal of regulatory pathway efficiency that would compress revenue recognition delays for new product lines.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Recertification timelines displace non-compliant suppliers from European hospital tenders. |
| Backward Integration into Nitrile Compounding | Captive formulation expertise insulates margin structures from petrochemical feedstock volatility. |
| Chlorination Finishing Capability Expansion | Surface modification technologies enable premium pricing tiers in extended-wear surgical segments. |
| Direct Manufacturer Contracting with IDNs | Integrated delivery networks negotiate multi-year volume commitments displacing distributor intermediaries. |
| Digital Twin Line Commissioning | Virtual process optimization reduces startup waste and shortens time-to-volume for capacity expansions. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital GPO contracts managers, biomedical engineers at acute care networks, glove manufacturing plant managers in Malaysia and Thailand, and chemical handling procurement leads at semiconductor fabrication facilities. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation registries, OSHA enforcement records, customs and trade flow data for nitrile butadiene rubber compounds, and SEC filings from publicly traded glove manufacturers. Bottom-up volume modeling triangulated against top-down macroeconomic drivers across the analysis window.
Calibration anchored volume and value outputs to segment-level replacement rates, regulatory compliance burdens, and raw material cost pass-through elasticity. Segmentation dimensions modeled encompassed polymer formulation, end-use certification tier, thickness specification, and regional regulatory cluster. CAGRs were derived from regression analysis against healthcare expenditure trajectories and industrial safety mandate expansion. Forecast inputs included acrylonitrile monomer pricing volatility indices and cleanroom construction activity in battery manufacturing corridors.
Sensitivities concentrate around nitrile feedstock cost shocks, EU MDR recertification timeline delays, and geographic concentration disruptions from Malaysia's supply corridor. Forecasts reflect documented assumptions regarding OSHA mandate continuity and hospital procurement consolidation trajectories. Macroeconomic contraction, regulatory harmonization failure between major economies, or breakthrough synthetic elastomer alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Explosion Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety IO Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Firefighter Tape Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above-The-Neck PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Traffic Baton Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Monitoring and Dosimeter Badges Market
Safety Equipment and Personal Protective Equipment (PPE)
Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Pest Control Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Radiation Protection Aprons Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Eye Wash Stations Market
Safety Equipment and Personal Protective Equipment (PPE)
Emergency Showers Market
Safety Equipment and Personal Protective Equipment (PPE)
Latin America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Electronic Siren Systems Market