
 Performance and Goal Management Market | 2026-2036
Performance and Goal Management Market Size, Share, and Industry Trends Forecast 2026-2036
Performance and Goal Management Market Analytics
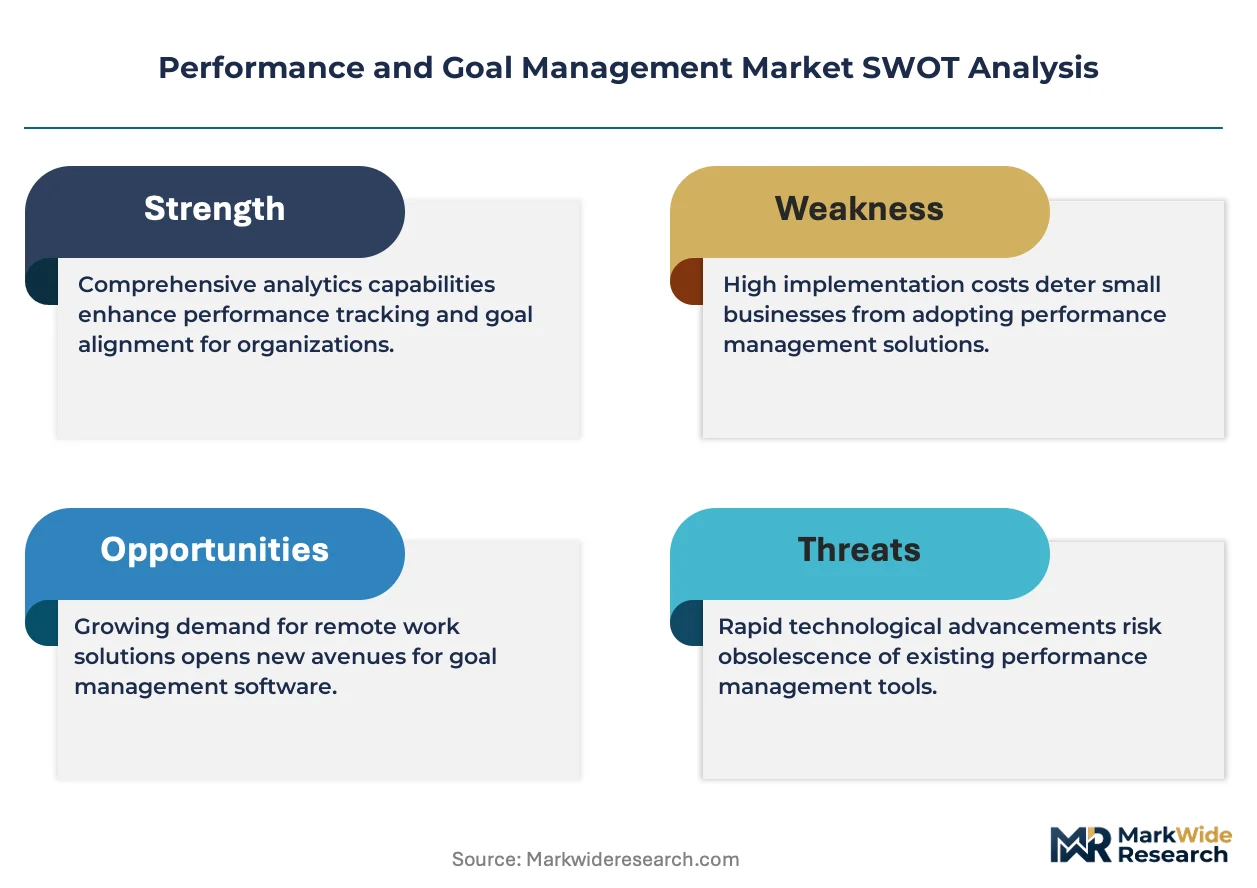
Talent scarcity among data-literate HR practitioners is redrawing competitive boundaries for platform vendors. SAP leverages its embedded ERP footprint to sustain cross-sell momentum into workforce analytics. Workday anchors cloud HCM deployments among large enterprises with unified payroll-to-performance data models. Oracle competes through database-layer integration that positions its goal-management modules inside existing infrastructure spend.
Performance and Goal Management encompasses software systems that operationalize objective-setting, continuous feedback loops, and competency-aligned evaluation protocols through configurable workflow engines and real-time dashboarding. These platforms serve commercial and institutional employers seeking to replace episodic appraisal rituals with dynamic talent optimization. Cloud-based deployment leads segment momentum as SaaS architectures reduce implementation friction and enable mobile-first manager experiences. Platform offerings capture expanding margin pools by bundling AI-driven sentiment analysis and predictive flight-risk scoring. On-premise installations retain footholds in government agencies and regulated financial institutions where data sovereignty requirements constrain off-premises processing.
ISO 30414 workforce reporting standards, the EU AI Act's risk-classification rules for automated employment decision systems, and SEC human capital disclosure mandates collectively elevate audit-grade traceability requirements for goal-management data. OSHA whistleblower protections and GDPR Article 22 provisions on automated profiling further shape feature roadmaps around explainability and consent documentation. Stakeholders must weigh interoperability investments against the accelerating regulatory fragmentation between algorithmic accountability regimes in Brussels, Washington, and Beijing.
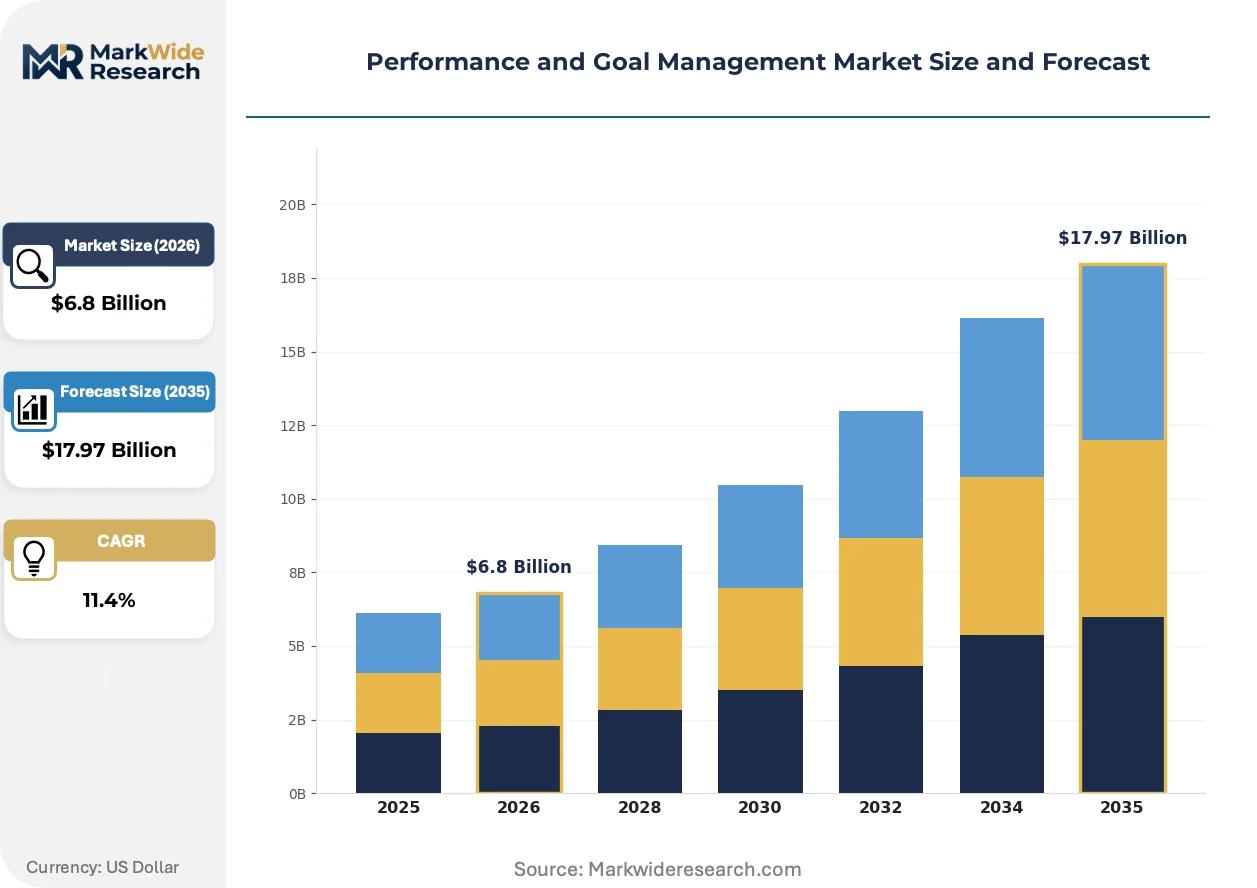
Market Dynamics
AI-driven predictive analytics is compressing performance feedback cycles from annual rituals into continuous calibration loops, forcing platform vendors to rearchitect data pipelines around real-time sentiment signals and flight-risk scoring.
Growth Catalysts
- ISO 30414 workforce reporting standards:Mandatory human capital disclosure requirements in the United States and European Union are creating audit-grade demand for traceable goal-management data architectures.
- Cloud-native SaaS deployment:Mobile-first manager experiences and reduced implementation friction are accelerating replacement of on-premise HR systems among mid-market employers.
- EU AI Act risk classification:Automated employment decision systems face new algorithmic accountability mandates that elevate explainability features to competitive differentiators.
Market Restraints
- Data sovereignty compliance costs:GDPR Article 22 automated profiling restrictions and China's data localization requirements fragment platform development roadmaps across incompatible jurisdictions.
- Talent scarcity in HR analytics:Shortages of data-literate workforce practitioners constrain implementation velocity and extend customer success timelines for complex deployments.
- Legacy system integration friction:Deeply embedded on-premise ERP footprints in regulated financial institutions create switching costs that delay cloud migration decisions.
Strategic Opportunities
- Japan's digital HR transformation:METI-led workplace innovation initiatives and aging workforce pressures are expanding budgets for predictive retention and succession planning tools.
- Skills-based credentialing convergence:Integration of performance data with digital badge and micro-credential platforms creates new revenue streams in talent mobility marketplaces.
- OSHA whistleblower protection alignment:Anonymous feedback channel requirements are driving demand for sentiment analysis modules that preserve investigatory traceability.
Industry Challenges
- Algorithmic bias audit complexity:Platform vendors must document model training data provenance and decision logic to satisfy divergent explainability standards across Brussels, Washington, and Beijing.
- Cross-functional implementation coordination:Successful deployments require alignment between HR business partners, IT security teams, and line managers with competing priority hierarchies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Performance and Goal Management Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Platform, Tool, Service Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Corporations, Educational Institutions, Nonprofits, Government Agencies Solution: Performance Tracking, Employee Engagement, Feedback Management, Goal Setting |
| Companies Covered | Workhuman, O.C. Tanner, Qualtrics, SAP, Cornerstone OnDemand, Workday, ServiceNow, UKG, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Performance and Goal Management Market Evolving Landscape
Continuous performance management architectures are replacing episodic appraisal rituals through real-time feedback loops, predictive analytics, and mobile-native user experiences that compress managerial decision cycles.
Natural language processing engines analyzing manager-employee conversation patterns are displacing static competency checklists in Fortune 500 performance evaluations. CHROs at technology and professional services firms are piloting these tools to identify coaching intervention moments before engagement decay accelerates. The shift is compressing vendor competitive differentiation from feature breadth to predictive accuracy benchmarks.
SEC human capital disclosure mandates now require quantitative workforce metrics in 10-K filings, elevating audit-grade data lineage to a procurement prerequisite. Platform vendors are embedding SOX-compliant change logs and immutable timestamp architectures to capture board-level compliance attention. Financial services and publicly traded industrials represent the most affected buyer segments, with procurement teams demanding third-party attestation of data handling protocols.
Subscription pricing for workforce analytics is fragmenting traditional perpetual-license structures as buyers demand consumption-scaled access to AI modules. Mid-market employers in Germany and the United States are leading this shift, preferring per-employee-per-month arrangements that align vendor incentives with measured outcome improvements. Channel partners are restructuring implementation services around activation milestones rather than upfront configuration fees.
Performance and Goal Management Market Segmentation
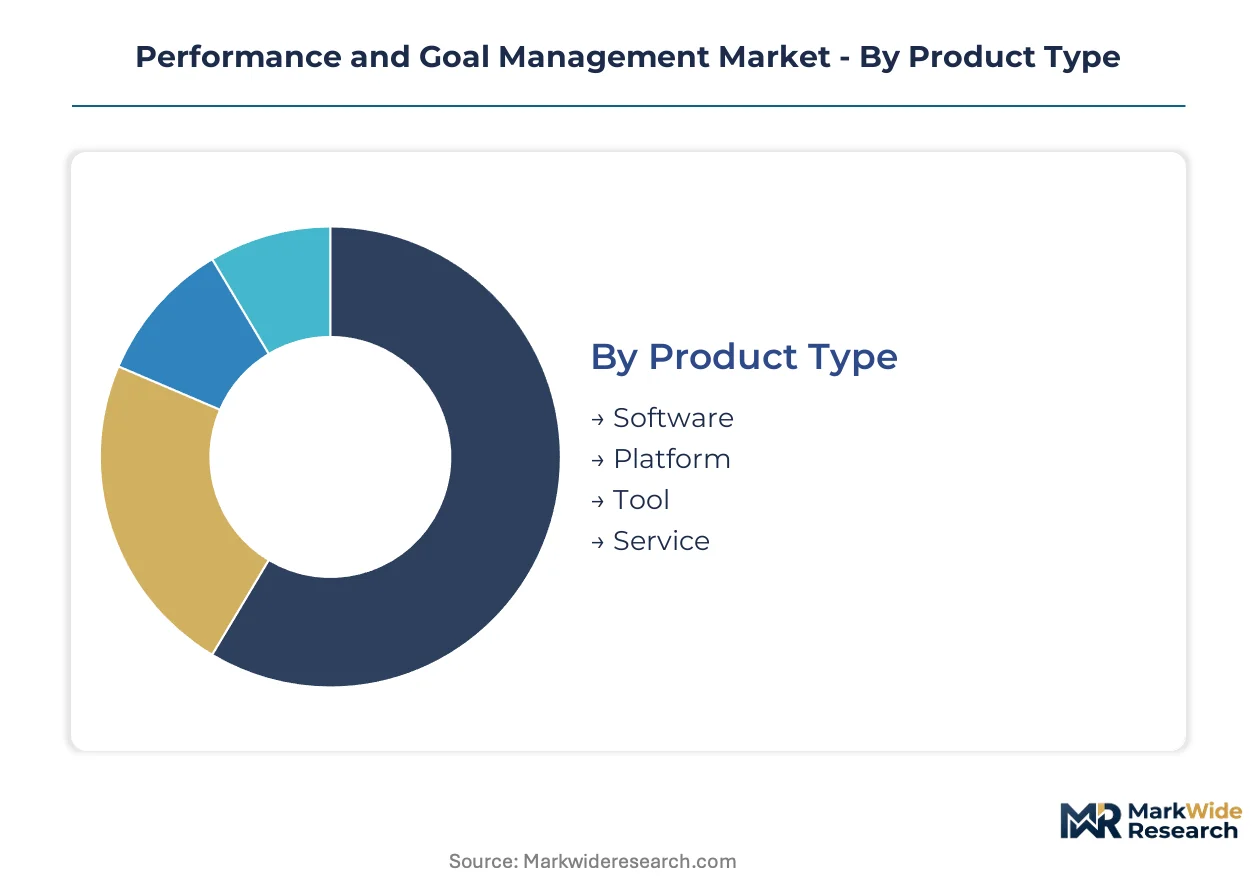
Segmentation in the Performance and Goal Management market reveals distinct margin architectures across deployment models and solution types. Buyers prioritize predictive capabilities and compliance-grade audit trails when allocating software budgets across enterprise tiers.
Product Type:
Margin pools concentrate in recurring-revenue platforms that bundle AI modules with core workflow engines, while perpetual-license software faces compression from SaaS substitution.
- Software:Traditional on-premise and early cloud applications deliver objective-setting and evaluation workflows through configurable rule engines. Demand persists among government agencies in Germany and Japan where procurement cycles favor established vendors with security clearances.
- Platform:Unified architectures integrating payroll, talent acquisition, and performance data through single data models command premium pricing. Workday and SAP anchor enterprise deployments in the United States with embedded predictive analytics that reduce flight-risk false positives.
- Tool:Point solutions addressing narrow use cases such as 360-degree feedback or competency mapping occupy mid-market price tiers. These offerings face consolidation pressure as buyers prefer integrated suites.
- Service:Implementation, change management, and ongoing optimization consulting capture value from deployment complexity. Skills scarcity among data-literate HR practitioners extends professional services attach rates.
Platform holds installed capacity. Software is rotating up the share rankings as buyers seek unified data models over fragmented point solutions.
Deployment:
Cloud-native architectures dominate new bookings, though data sovereignty requirements sustain hybrid configurations in regulated European and Asian markets.
- On-Premise:Legacy installations in financial services and defense contractors maintain air-gapped performance data to satisfy SEC and national security audit requirements. These deployments carry high maintenance burdens and limited AI feature access.
- Cloud-Based:Multi-tenant architectures with regional data residency options address GDPR Article 22 automated profiling constraints while enabling real-time sentiment analysis. German mid-market employers favor these configurations for METI-aligned workplace innovation budgets.
- Hybrid:Sensitive performance data remains on-premise while analytics workloads process in cloud environments. Japanese manufacturers adopt this model to balance aging workforce analytics with intellectual property protection.
- SaaS:Per-employee-per-month pricing aligns vendor incentives with measured outcome improvements. United States technology and professional services firms drive adoption of consumption-scaled AI module access.
SaaS commands new booking velocity. Hybrid is climbing the fastest as regulated industries seek sovereignty-compliant cloud pathways.
End User:
Corporations generate the majority of revenue, though public sector procurement is accelerating as ISO 30414 disclosure mandates expand audit-grade platform requirements.
- Corporations:Fortune 500 technology, financial services, and industrial employers deploy continuous feedback architectures to compress managerial decision cycles. These buyers demand predictive accuracy benchmarks and third-party algorithmic bias attestation.
- Educational Institutions:Universities and research hospitals adapt performance frameworks for faculty and administrative staff evaluation. Procurement emphasizes interoperability with existing learning management and grant administration systems.
- Nonprofits:Mission-driven organizations prioritize cost efficiency and donor reporting transparency over advanced analytics. These deployments rarely exceed core goal-setting and basic feedback modules.
- Government Agencies:Federal and state entities in the United States, prefectural governments in Japan, and EU institutions face whistleblower protection and human capital disclosure mandates. OSHA-aligned anonymous feedback channels drive feature requirements.
Corporations anchor revenue concentration. Government Agencies are gaining share fastest as regulatory compliance elevates procurement priority.
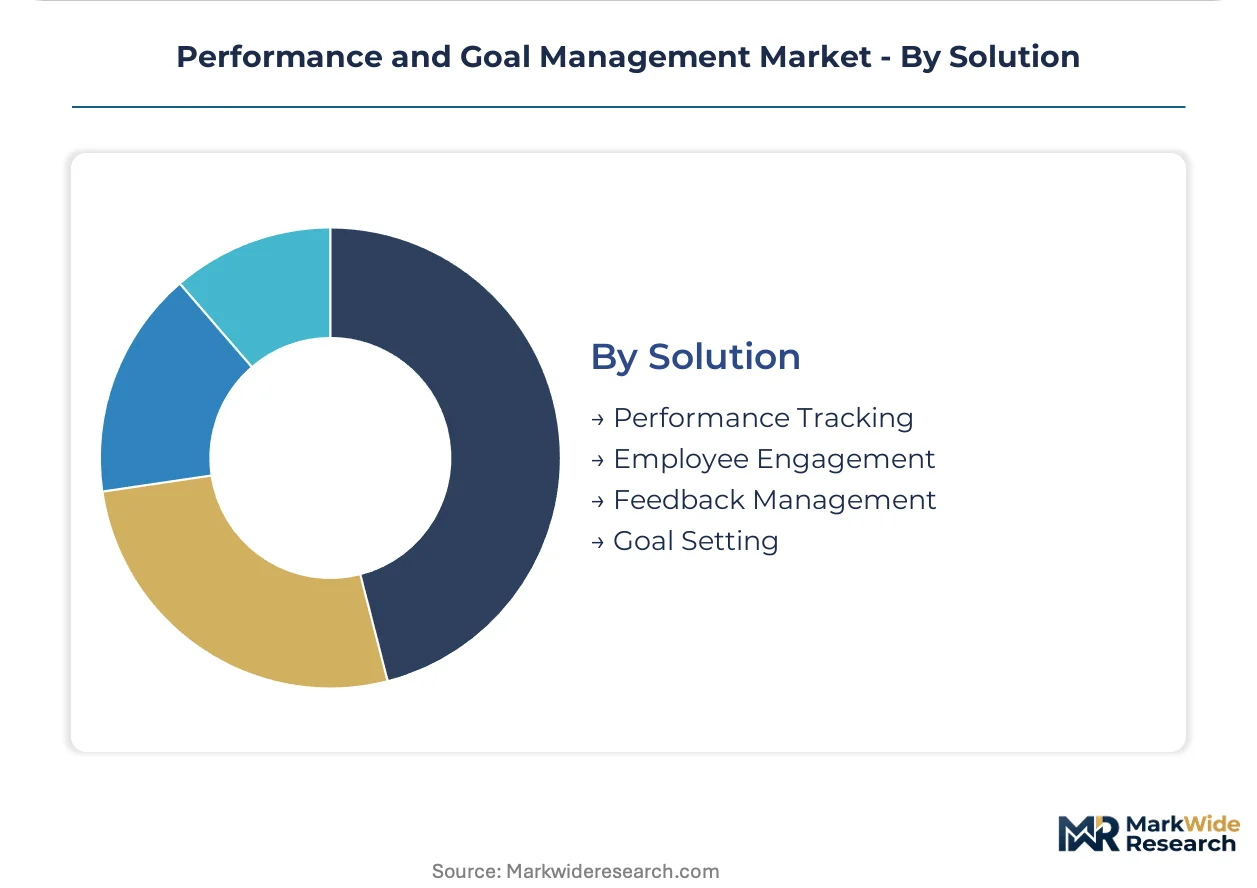
Solution:
Performance Tracking and Goal Setting capture foundational spend, while Employee Engagement modules with NLP-driven sentiment analysis command expansion premiums.
- Performance Tracking:Real-time dashboarding of objective progress, competency ratings, and calibration analytics replaces annual review documentation. Financial services firms in New York and London prioritize SOX-compliant change logs for board reporting.
- Employee Engagement:Pulse surveys, sentiment analysis, and predictive flight-risk scoring identify coaching intervention moments. CHROs at United States technology firms pilot NLP engines analyzing manager-employee conversation patterns.
- Feedback Management:Continuous 360-degree and peer feedback workflows with mobile-native interfaces compress feedback cycles. These tools face integration complexity with legacy HR information systems.
- Goal Setting:OKR and SMART objective frameworks with cascading alignment visualization remain table stakes. Differentiation shifts toward AI-suggested goal calibration based on historical performance patterns and peer benchmarks.
Performance Tracking holds installed capacity. Employee Engagement is rotating up the share rankings as predictive accuracy becomes the primary vendor selection criterion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC human capital disclosure mandates in the United States anchor regulatory momentum for audit-grade performance management platforms across major economies.
United States
Fortune 500 technology and financial services employers drive cloud-native platform adoption to compress managerial decision cycles. OSHA whistleblower protection requirements elevate anonymous feedback channel specifications in procurement evaluations. New York and San Francisco metropolitan clusters concentrate pilot deployments of NLP-driven sentiment analysis engines.
Germany
Mid-market employers favor SaaS configurations with regional data residency to satisfy GDPR Article 22 automated profiling constraints. METI-aligned workplace innovation budgets channel investment into predictive retention tools for aging workforce challenges. Industrial employers in Bavaria and Baden-Württemberg prioritize hybrid deployments balancing analytics workloads with intellectual property protection.
Japan
Prefectural governments and manufacturers expand budgets for succession planning and flight-risk scoring capabilities. The country's national labor standards framework shapes feature roadmaps around explainability documentation. Automotive and electronics clusters in Nagoya and Osaka anchor enterprise platform deployments with METI-led digital transformation incentives.
United Kingdom
Professional services firms and publicly traded industrials demand SOX-compliant change logs for board-level workforce reporting. The country's financial conduct regulator influences algorithmic accountability specifications for automated employment decisions. London's financial services corridor concentrates procurement of audit-grade data lineage architectures.
India
Technology services exporters and multinational captive centers adopt continuous feedback architectures to align with parent-company compliance frameworks. The country's central bank guidelines on data localization shape hybrid deployment preferences. Bengaluru and Hyderabad technology corridors drive mid-market SaaS adoption for mobile-first manager experiences.
Performance and Goal Management Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in a market structure defined by ERP-embedded cross-sell momentum versus point-solution agility. Cloud-native platform vendors with unified data models command premium pricing against legacy on-premise incumbents. Two archetypes dominate: enterprise suite extenders leveraging existing infrastructure spend, and agile specialists delivering predictive analytics modules. Competitive moves center on AI feature bundling and regional data residency certifications to satisfy fragmented sovereignty requirements.
Among enterprise suite extenders, SAP and Oracle occupy positions anchored by database-layer integration and embedded ERP footprints. Workday sits within the cloud-native tier, exemplifying unified payroll-to-performance data models that reduce implementation friction for large employers. These three companies represent the competitive fault line between infrastructure-anchored incumbents and agile challengers.
| Leading Market Players |
|---|
| Workhuman |
| O.C. Tanner |
| Qualtrics |
| SAP |
| Cornerstone OnDemand |
| Workday |
| ServiceNow |
| UKG |
| Oracle |
| Others |
Value Network & Pricing Analysis
Ninety-day implementation cycles for enterprise performance platforms concentrate vendor pricing power among SAP, Workday, and Oracle, while compressed delivery timelines force mid-market buyers toward SaaS tiers with reduced customization scope. This lead-time compression shapes procurement patterns across United States and German employers, where METI and SEC disclosure mandates accelerate replacement decisions.
Pricing Analysis
Per-employee-per-month spreads between United States and German deployments reflect GDPR Article 22 compliance overhead and regional data residency requirements. Pricing stratifies across premium, standard, and economy tiers, with premium differentiation anchored by AI module bundling and third-party algorithmic bias attestation. Cost compression in standard tiers intensifies because Workday and SAP cross-sell momentum narrows standalone vendor viability. Mid-market employers in Germany exhibit highest price sensitivity, while Fortune 500 technology firms in New York and San Francisco prioritize predictive accuracy over per-seat economics.
Supply Chain Analysis
United States and Germany anchor cloud infrastructure provisioning for performance management platforms, with Ireland and Singapore serving regional data residency nodes for GDPR and PDPA compliance. Development talent pools draw from Bengaluru and Hyderabad for NLP engineering, while customer success functions center on Dallas and Frankfurt. Single-source vulnerability concentrates in hyperscaler compute contracts, where AWS, Azure, and Google Cloud pricing power constrains vendor margin flexibility. Distribution runs through direct enterprise sales teams with systems integrator augmentation for complex ERP integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise software procurement cycles are recovering from pandemic-era budget freezes, with ISO 30414 disclosure mandates and EU AI Act implementation deadlines creating replacement urgency among Fortune 500 employers.
For Market Incumbents: Compound embedded ERP footprint advantages by accelerating AI feature bundling into existing maintenance contracts before cloud-native challengers achieve parity. Defend against Qualtrics and ServiceNow encroachment by embedding predictive flight-risk scoring into payroll-to-performance data models. Prioritize certification investment in EU AI Act explainability documentation to maintain procurement eligibility across Brussels-regulated buyers.
For New Entrants and Emerging Players: ISO 30414 fast-track implementation services create immediate revenue traction among publicly traded industrials facing SEC human capital disclosure deadlines. White-space concentrates in Japan's prefectural governments and mid-market German manufacturers, where METI workplace innovation budgets exceed incumbent sales coverage. Go-to-market positioning should emphasize per-employee-per-month pricing with activation-milestone guarantees rather than upfront configuration fees.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy on-premise HR software divisions of diversified enterprise technology parents, where cloud migration investment requirements strain capital allocation priorities. Long-term viability favors vendors with unified data models spanning payroll, talent acquisition, and performance analytics. Monitor OSHA whistleblower protection enforcement intensity as inflection indicator for anonymous feedback channel demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified payroll-to-performance data models reduce flight-risk false positives for Workday and SAP enterprise deployments. |
| AI Module Bundling | Predictive sentiment analysis and flight-risk scoring command premium pricing in United States technology sector procurement. |
| Regional Data Residency Certification | GDPR Article 22 compliance enables German mid-market SaaS penetration against United States-hosted competitors. |
| Strategic Partnership | Systems integrator alliances accelerate ERP replacement timelines for Oracle database-layer integration plays. |
| Acquisition of Specialist Firm | NLP engine specialists enhance continuous feedback architectures for Qualtrics and ServiceNow competitive positioning. |
Research Methodology
A standing panel of CHROs, IT procurement officers, HRIS implementation specialists, and workforce analytics directors provided ongoing calibration across primary interview programs and secondary validation sources. Primary fieldwork encompassed structured conversations with platform vendors, systems integrators, and end-user employers across United States, German, and Japanese markets. Secondary sources included SEC 10-K human capital disclosures, EU AI Act regulatory filings, ISO 30414 implementation guidance, and METI workplace innovation program documentation. Bottom-up deployment estimates triangulated against top-down software spend projections from hyperscaler and ERP vendor disclosures.
Consistency checks validated volume and value outputs against external benchmarks including cloud HCM adoption surveys, HR technology procurement databases, and regional digital transformation budget allocations. Segmentation modeling spanned deployment architecture, organization size tier, vertical industry, integration complexity, and regulatory jurisdiction cluster. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns, with cross-validation against vendor-reported booking growth and channel partner pipeline data. Industry-specific inputs incorporated ISO 30414 compliance timeline assumptions and EU AI Act risk classification implementation schedules.
Decision-makers should treat outputs as directional under sustained regulatory enforcement intensity and stable enterprise IT budget trajectories; material deviation in either assumption would warrant model refresh. Forecasts incorporate assumptions regarding cloud migration velocity, AI feature adoption curves, and data sovereignty requirement proliferation. Recalibration cycles align with material shifts in SEC disclosure enforcement, EU AI Act delegated act publication, and METI workplace innovation budget allocations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness
Spain Sports Tourism Market
Sports & Fitness
Brazil Sports Nutrition Market
Sports & Fitness
USA Sports Team and Club Market
Sports & Fitness
Ski Vacation Market
Sports & Fitness
Balance Bike Market
Sports & Fitness
Outdoor Living Product Market
Sports & Fitness
Asia-Pacific Fantasy Sports Market
Sports & Fitness
Baseball Equipment Market
Sports & Fitness
Europe Climbing Gym Market
Sports & Fitness
Global Rock Climbing Equipment Market
Sports & Fitness
Smart Bike Trainers Market
Sports & Fitness
Rubber Fitness Flooring Market
Sports & Fitness
Playground Sets and Equipment Market
Sports & Fitness
Kiteboarding Equipment Market
Sports & Fitness
Sports Training Market
Sports & Fitness
Weight Management Market