
 Paint Process Automation Market | 2026-2036
Paint Process Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Paint Process Automation Market Intelligence
Software-defined maintenance contracts is hardening into the dominant revenue layer as paint line operators shift from capital expenditure to operational expenditure models. Dürr AG leverages its integrated digital service platform to lock in long-term aftermarket relationships with European automotive plants. FANUC Corporation anchors its position through dense installed bases in Japan and North America that generate recurring service revenue streams. Graco Inc. differentiates by specializing in precision fluid management technologies that reduce material waste during automated coating operations.
Paint process automation encompasses the integrated use of robotic systems, programmable controllers, and sensor networks to execute surface coating with repeatable film thickness tolerances of ±5 micrometers across complex geometries. The primary industrial purpose centers on eliminating human variability from high-volume finishing while reducing solvent exposure and material over-spray in regulated manufacturing environments. Robotic arms command the largest installed base as six-axis articulation remains essential for automotive body-in-white coverage, yet vision systems represent the fastest-expanding segment as AI-enabled defect detection replaces manual quality gates. Automated spray systems concentrate margin pools at the premium tier where electrostatic rotary bell technologies achieve transfer efficiency above 85 percent.
The EPA enforces National Emission Standards for Hazardous Air Pollutants that mandate maximum achievable control technology for paint operations, directly shaping equipment procurement specifications across US manufacturing. REACH compliance in Europe restricts chromate and lead-based pretreatment chemistries, forcing automation vendors to validate process compatibility with substitute formulations. China's MEE administers dual carbon goals that tighten energy intensity benchmarks for industrial coating lines, accelerating retrofits in Shanghai and Guangzhou automotive clusters. Stakeholders must monitor how evolving VOC thresholds across these jurisdictions reshape the technical specifications that define competitive product roadmaps.
Market Dynamics
EU F-Gas Regulation enforcement is compressing paint line upgrade cycles across automotive OEMs, forcing capital allocation toward robotic systems that eliminate solvent-based coating processes before compliance deadlines arrive.
Growth Catalysts
- REACH chromate restrictions:European pretreatment chemistry bans accelerate automation retrofits as manufacturers validate substitute formulations through robotic process control.
- Automotive OEM consolidation:Tier-one suppliers in Germany and the United States standardize on electrostatic rotary bell technologies to achieve transfer efficiency above 85 percent.
- China's dual carbon goals:MEE energy intensity benchmarks tighten for industrial coating clusters in Shanghai and Guangzhou, driving automation procurement.
Market Restraints
- Specialized integrator concentration:Six-axis robotic programming expertise concentrates among German and Japanese system houses, creating bottleneck risk for new market entrants.
- Copper and rare earth input volatility:Servo motor and magnetic component costs fluctuate with commodity markets, compressing margin visibility on long-delivery equipment contracts.
- Legacy solvent compatibility:Waterborne coating chemistries require humidity-controlled booth environments that conflict with existing plant infrastructure in older US Midwest facilities.
Strategic Opportunities
- India PLI scheme alignment:Domestic vehicle production scale-up creates first-mover positioning for precision fluid management vendors serving emerging paint shops in Pune and Chennai.
- AI-enabled vision convergence:Machine learning defect detection integration with six-axis arms opens aftermarket service contracts beyond hardware installation.
- Software-defined maintenance channels:Subscription-based predictive analytics replace traditional break-fix service models, locking recurring revenue with European automotive plants.
Industry Challenges
- Robotic programming talent scarcity:Shortage of technicians proficient in both spray dynamics and PLC ladder logic extends commissioning timelines for complex body-in-white lines.
- ISO 9001 certification delays:Quality management system audits for automated coating processes add six to nine months to supplier qualification cycles.
- Multi-vendor integration complexity:Proprietary communication protocols between paint robots, conveyors, and curing ovens require custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paint Process Automation Market |
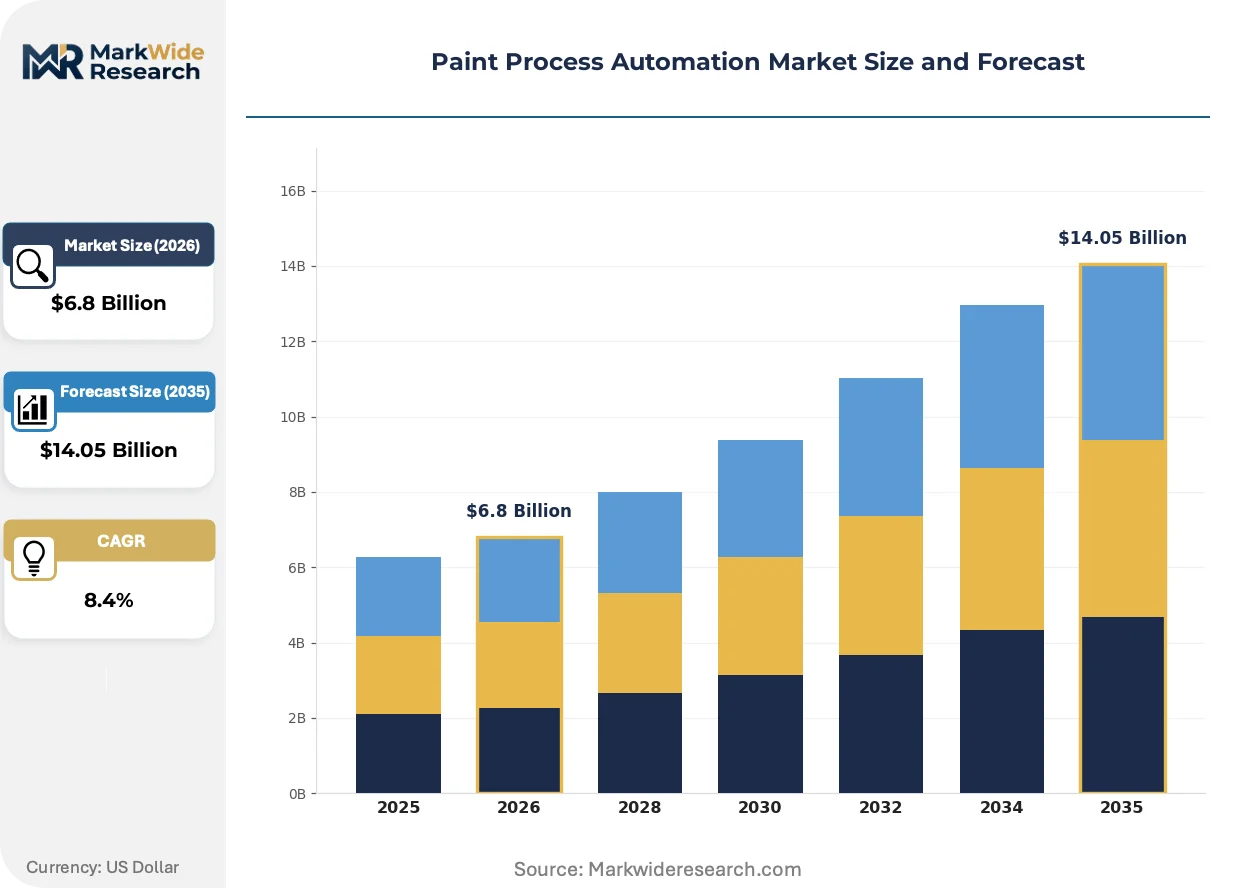
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Robotic Arms, Automated Spray Systems, Conveyor Systems, Vision Systems Application: Automotive Painting, Furniture Coating, Industrial Equipment Finishing, Aerospace Surfaces End User: Manufacturers, Contractors, Distributors, Original Equipment Manufacturers Installation: Onshore, Offshore, Permanent, Mobile |
| Companies Covered | ABB, FANUC Corporation, KUKA AG, Yaskawa Electric Corporation, Dürr AG, CMA Robotics, Graco Inc., Kawasaki Heavy Industries, Staubli International AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paint Process Automation Market Strategic Shifts & Innovations
Digital thread architectures are threading sensor data from spray guns through MES layers to cloud analytics platforms, compressing the feedback loop between coating application and quality verification.
AI-enabled vision systems is overtaking manual defect inspection stations in automotive paint shops. These systems classify orange peel, dirt inclusions, and color match deviations at line speed. European luxury OEMs in Stuttgart and Munich deploy them at final inspection gates. The technology is overtaking traditional quality labor pools while generating training datasets that improve detection accuracy without production stoppage.
REACH authorization timelines now classify certain corrosion inhibitors as substances of very high concern, forcing pretreatment chemical suppliers to reformulate phosphate-free conversion coatings. Automotive OEMs in Wolfsburg and Rüsselsheim accelerate validation of zirconium-based alternatives. The regulation compresses process window tolerances, demanding tighter automation control over bath chemistry monitoring and replenishment cycles.
Buyer consolidation among tier-one automotive suppliers concentrates procurement leverage, squeezing equipment vendors into multi-year framework agreements with price-down clauses. Japanese and German OEMs now bundle paint line automation into turnkey facility contracts awarded to single-source integrators. The shift is most visible in greenfield EV manufacturing plants where coating process design precedes equipment vendor selection.
Paint Process Automation Market Segmentation
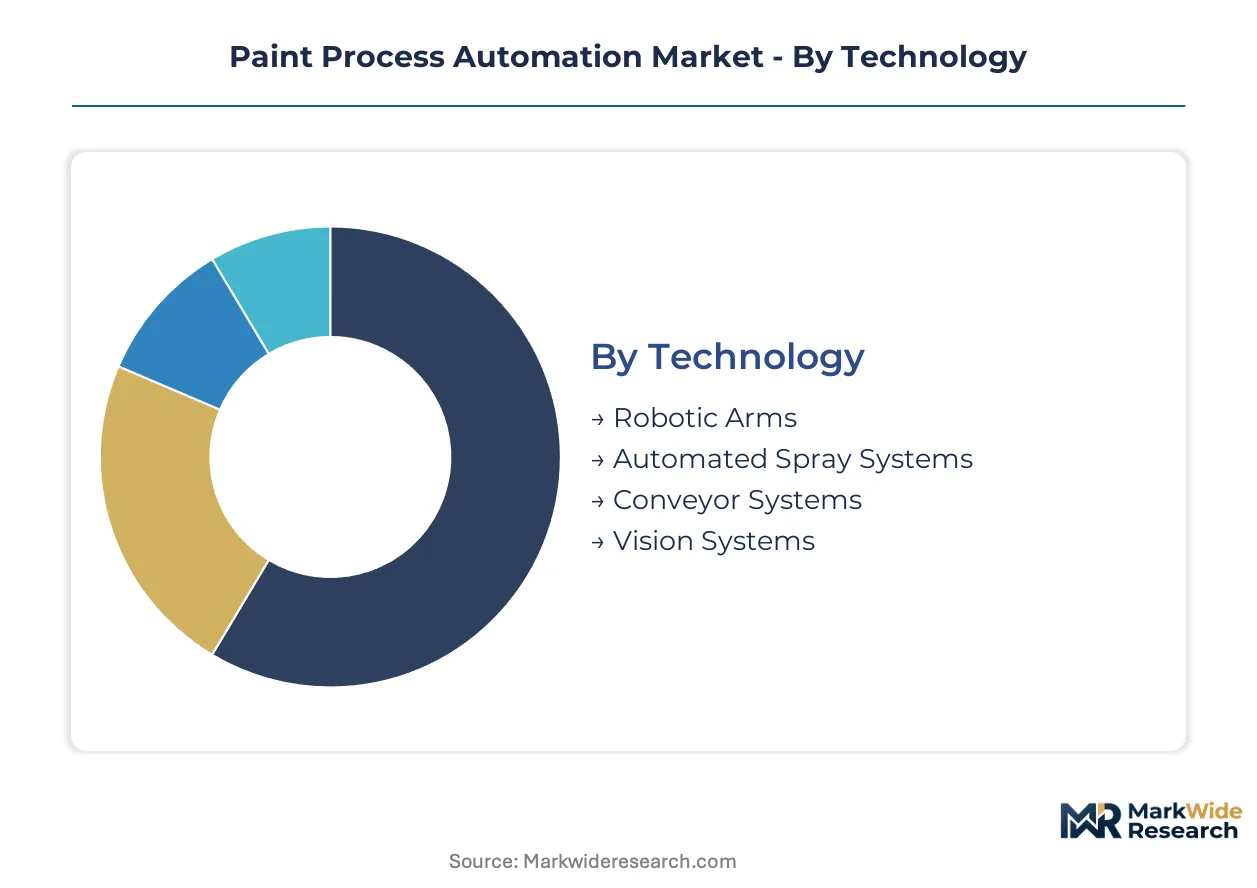
Segmentation in paint process automation reveals how certification burdens, application complexity, and installation constraints reshape procurement patterns across equipment categories. Technical specifications vary sharply by end-use environment, with automotive OEMs demanding ISO 9001-validated systems while furniture coaters prioritize flexible reconfiguration.
Technology:
ISO 10218 safety certification governs robotic arm deployments, while vision systems face emerging EU AI Act conformity requirements for automated defect classification algorithms.
- Robotic Arms:Six-axis articulated systems execute complex body-in-white trajectories with repeatable positioning accuracy. Automotive OEMs in Germany and the United States concentrate procurement here, driven by EU F-Gas Regulation deadlines eliminating manual spray operations.
- Vision Systems:AI-enabled cameras classify coating defects at line speed using machine learning models trained on historical quality data. These systems are expanding most quickly across European luxury automotive plants in Stuttgart and Munich as labor costs for manual inspection escalate.
- Automated Spray Systems:Electrostatic rotary bell technologies achieve transfer efficiency above 85 percent in tier-one supplier installations.
- Conveyor Systems:Overhead and floor-mounted transport infrastructure synchronizes workpiece flow with robotic cycle times.
Leading the category by volume: Robotic Arms. Growing fastest: Vision Systems.
Application:
Cost tier differentiation separates premium automotive specifications from economy-grade furniture operations, with certification depth scaling proportionally.
- Automotive Painting:Multi-layer coating sequences demand humidity-controlled booths and electrostatic application for basecoat, clearcoat, and primer systems. OEM consolidation in Wolfsburg and Rüsselsheim drives standardization on integrated paint shop automation.
- Aerospace Surfaces:Low-VOC polyurethane and epoxy formulations require precision film thickness control for fuel efficiency and corrosion protection. Boeing and Airbus tier suppliers in Wichita and Toulouse validate systems against NADCAP accreditation standards.
- Furniture Coating:Flat-line and three-dimensional spray systems handle wood, metal, and synthetic substrates with rapid color change capability.
- Industrial Equipment Finishing:Heavy machinery and agricultural equipment lines prioritize durability coatings with extended weathering resistance.
Margin concentration peaks in Automotive Painting. Fastest expansion trajectory belongs to Aerospace Surfaces.
End User:
Customer type determines whether procurement flows through capital expenditure committees or operational expenditure service contracts.
- Original Equipment Manufacturers:Vertically integrated producers specify turnkey paint shop designs during facility planning, locking multi-year framework agreements with single-source integrators.
- Manufacturers:Independent production facilities purchase discrete automation modules for line upgrades and capacity expansion.
- Contractors:Third-party finishing service providers prioritize mobile and reconfigurable systems for multi-site deployment flexibility.
- Distributors:Channel intermediaries stock spare components and consumables for aftermarket maintenance revenue.
Highest procurement authority: Original Equipment Manufacturers. Fastest contract velocity: Contractors.
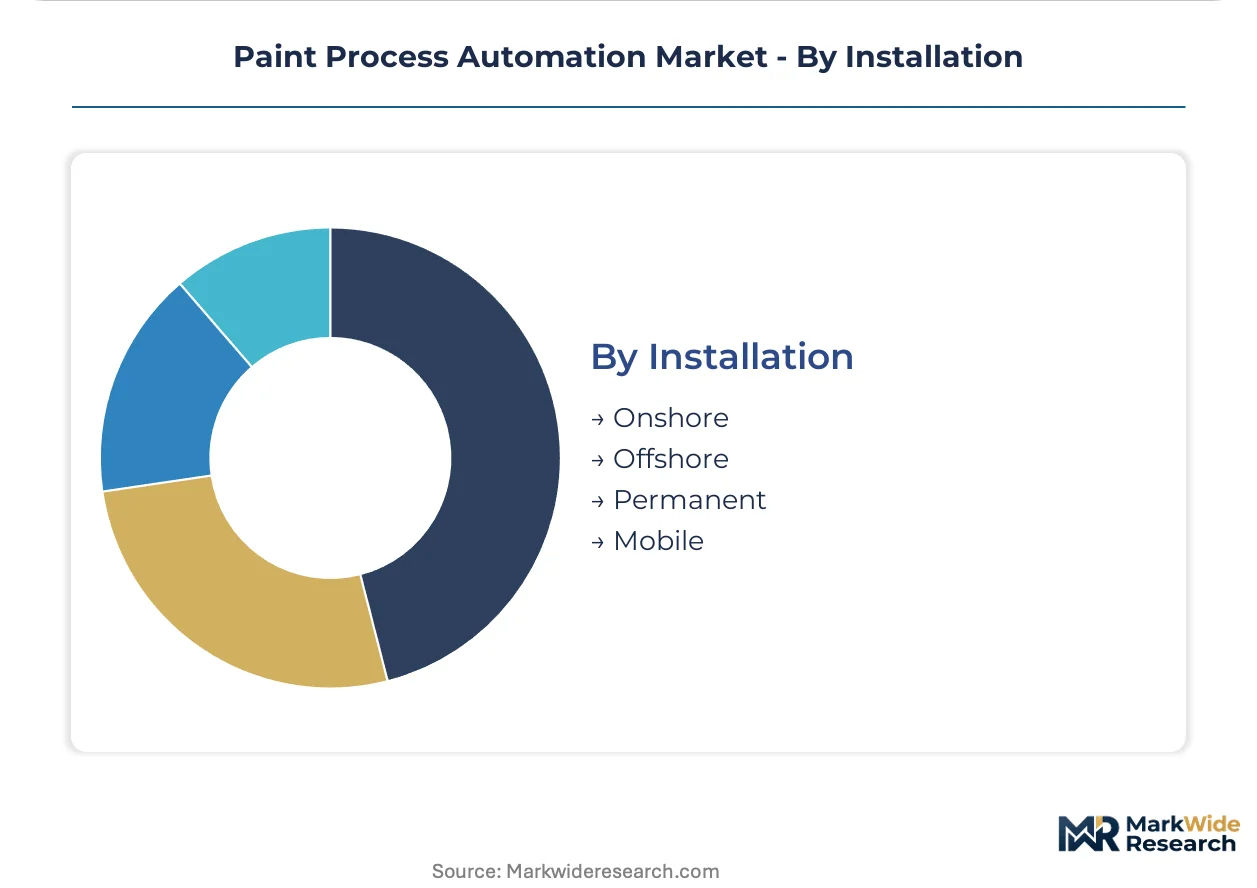
Installation:
Geography and mobility requirements dictate infrastructure investment intensity and regulatory compliance scope.
- Permanent:Fixed installations anchor greenfield automotive plants and major facility expansions with 15-20 year depreciation horizons.
- Onshore:Domestic deployment within national boundaries simplifies certification and service access for mid-size manufacturers.
- Offshore:International installations face extended commissioning timelines due to specialized integrator travel requirements and import documentation.
- Mobile:Containerized and trailer-mounted systems serve temporary production surges and remote industrial sites.
Dominant deployment mode: Permanent. Gaining share fastest: Mobile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany, China, and the United States where automotive OEMs deploy capital-intensive paint lines, while consumption spreads across manufacturing clusters in India and Japan as domestic vehicle assembly scales.
United States
Automotive OEMs in Michigan and Ohio accelerate robotic paint shop retrofits to meet EPA National Emission Standards for Hazardous Air Pollutants. The IRA manufacturing incentives support greenfield EV facility construction in Tennessee and Kentucky. Detroit-area suppliers standardize on electrostatic application systems for multi-layer coating sequences.
Germany
Wolfsburg and Rüsselsheim automotive clusters drive demand for integrated paint shop automation as EU F-Gas Regulation deadlines approach. REACH authorization timelines force reformulation of pretreatment chemistries, compressing process validation cycles. Stuttgart luxury OEMs deploy AI-enabled vision systems at final inspection gates.
China
Shanghai and Guangzhou automotive manufacturing hubs face tightening MEE energy intensity benchmarks under dual carbon goals. Domestic EV producers scale paint line capacity to match battery electric vehicle output growth. Local manufacturers upgrade finishing operations with automated spray systems.
India
Pune and Chennai emerging paint shops benefit from PLI scheme alignment as domestic vehicle production scales. Tier-one suppliers validate robotic process control for substitute pretreatment formulations. Contract finishing service providers prioritize mobile system deployment for multi-site flexibility.
Japan
Nagoya and Tokyo industrial corridors maintain dense installed bases of six-axis robotic arms generating recurring service revenue. METI industrial efficiency guidelines accelerate humidity-controlled booth installations for waterborne coating compatibility. Precision fluid management specialists anchor aftermarket relationships with automotive plants.
Paint Process Automation Market Key Industry Players
Top-tier vendors anchor integrated paint shop design, while mid-tier specialists concentrate on discrete automation modules and regional service networks. The vendor base stratifies across three layers: turnkey facility contractors, precision component suppliers, and software-defined maintenance platforms. Two dominant competitive moves reshape positioning: backward integration into proprietary control systems and geographic expansion through local integrator partnerships.
Within the robotics fabrication tier, ABB and FANUC Corporation exemplify scale-driven archetypes with dense installed bases generating recurring aftermarket revenue. Dürr AG occupies a position representing the integrated facility contractor model, locking multi-year framework agreements through digital service platforms. KUKA AG and Yaskawa Electric Corporation sit within the precision motion control specialist category, anchoring supply relationships with tier-one automotive suppliers.
| Leading Market Players |
|---|
| ABB |
| FANUC Corporation |
| KUKA AG |
| Yaskawa Electric Corporation |
| Dürr AG |
| CMA Robotics |
| Graco Inc. |
| Kawasaki Heavy Industries |
| Staubli International AG |
| Others |
Cost & Logistics Intelligence
Six-axis robotic programming expertise concentration in German and Japanese system houses feeds directly into pricing-tier spreads, with labor-cost differentials between Stuttgart integrators and emerging Pune contractors widening the premium-to-economy equipment gap by certification depth and commissioning timeline.
Pricing Analysis
Margin tightening in mid-tier equipment reflects buyer consolidation among tier-one automotive suppliers bundling paint line automation into turnkey facility contracts. Pricing stratifies across ISO 10218-certified premium systems, standard robotic modules, and economy-grade fluid management components. Cost-down pressure accelerates as Japanese and German OEMs impose multi-year framework agreements with price-down clauses. Contract finishing service providers exhibit highest price sensitivity, while vertically integrated automotive OEMs prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Workforce scarcity for PLC ladder logic technicians in Stuttgart and Nagoya constrains output expansion from established fabrication hubs. Supply concentrates in Germany, Japan, and China for six-axis articulated arms, vision system processors, and electrostatic rotary bell components. Rare earth magnet and copper winding dependencies tether motor production to commodity market volatility. Single-source vulnerability concentrates at precision servo drive suppliers. Distribution runs through authorized integrator networks with regional service commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paint process automation operates as a supply-constrained market where six-axis robotic programming talent scarcity props pricing power for qualified system integrators.
For Market Incumbents: Lock in long-term aftermarket relationships through software-defined maintenance platforms that generate recurring revenue streams beyond hardware installation. Deepen backward integration into proprietary control systems to defend against emerging AI-enabled vision specialists. Prioritize certification investment in EU AI Act conformity for automated defect classification algorithms to maintain premium positioning. For New Entrants and Emerging Players: The premium-to-economy price-point gap in automotive painting creates white-space opportunity for precision fluid management vendors serving India's emerging Pune and Chennai paint shops. Target mobile system deployment for contract finishing service providers seeking multi-site flexibility. Pursue PLI scheme alignment as the primary go-to-market angle for first-mover positioning in domestic vehicle production scale-up. For Investors and Strategic Acquirers: Re-rating potential sits with precision motion control specialists given AI-enabled vision convergence opening aftermarket service contracts. Long-term viability hinges on installed base density generating recurring maintenance revenue. Monitor commissioning timeline extensions as the inflection signal indicating talent scarcity threshold breach.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Proprietary Control Systems | Captures margin pools at the premium tier where Dürr AG and FANUC Corporation anchor positioning. |
| Software-Defined Maintenance Platform Launch | Locks recurring revenue with European automotive plants shifting from capital expenditure to operational expenditure models. |
| AI-Enabled Vision System Integration | Opens aftermarket service contracts beyond hardware installation as Stuttgart luxury OEMs deploy at final inspection gates. |
| Geographic Expansion through Local Integrator Partnerships | Addresses bottleneck risk from German and Japanese system house concentration for new market entrants. |
| REACH-Compliant Pretreatment Chemistry Validation | Accelerates automation retrofits as Wolfsburg and Rüsselsheim OEMs reformulate phosphate-free conversion coatings. |
Research Approach
Document review covered SEC filings, customs and trade data, automotive production databases, and regulatory agency submissions, complemented by interviews with paint shop engineers, Tier 1 supplier procurement leads, OEM platform engineers, and aftermarket service heads. Secondary validation drew from EPA enforcement records, ECHA REACH authorization timelines, and MEE energy intensity benchmark disclosures. Bottom-up equipment shipment analysis and top-down automotive production capacity modeling were triangulated to cross-verify segment sizing.
Historical robotic arm deployment patterns were cross-referenced against expert panel input on F-Gas Regulation compliance timelines. The analytical framework modeled technology, application, end user, and installation type segments across the projection horizon. CAGRs were derived from regression analysis of capital expenditure cycles and regulatory deadline clustering. Forecast inputs included EV manufacturing facility announcements and pretreatment chemistry reformulation schedules.
Inputs from primary interviews were available through the study window; gaps in long-delivery equipment contract visibility introduce uncertainty bands around margin compression estimates. Forecasts reflect assumptions on regulatory enforcement consistency and commodity price stability. Material deviation in EU F-Gas Regulation deadline adherence or rare earth supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Global Wheel Trenchers Market
Construction and Engineering
Fastening Power Tools Market
Construction and Engineering
GCC Construction Market
Construction and Engineering
Zinc Polycarboxylate Cement Market
Construction and Engineering
Bamboo Engineered Wood Market
Construction and Engineering
Sanding Machine Market
Construction and Engineering
Excavating Contractor Market
Construction and Engineering
Hot Water Circulator Pump Market
Construction and Engineering
Automated Material Handling Systems Market
Construction and Engineering
North America Concrete Conditioner Market
Construction and Engineering
Moisture Resistant Plaster Boards Market
Construction and Engineering
Italy Infrastructure Investment Market
Construction and Engineering
Asia-Pacific Shotcrete Market
Construction and Engineering
Asia-Pacific Heating Equipment Market
Construction and Engineering
Pile Cage Welding Machine Market
Construction and Engineering
Thermostatic Faucet Market