
 Packaging Design and Simulation Technology Market | 2026-2036
Packaging Design and Simulation Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Design and Simulation Technology Market Outlook
High-fidelity finite element analysis is redrawing competitive benchmarks for drop-test simulation and shelf-life prediction. Dassault Systèmes leverages its 3DEXPERIENCE platform to anchor digital twin workflows across European pharmaceutical packaging lines. ANSYS sustains technology leadership in multiphysics coupling for aseptic container integrity modeling. Altair competes through cloud-native solver architectures that reduce compute costs for mid-tier converters.
Packaging design and simulation technology encompasses computational tools that model structural behavior, thermal transfer, and fluid interaction across primary and secondary packaging formats using mesh densities typically ranging from 10^5 to 10^7 elements. These systems enable engineers to validate drop resistance, seal integrity, and temperature excursion performance without physical prototypes, compressing qualification timelines from months to weeks. Virtual prototyping commands the fastest expansion among technology categories as pharmaceutical cold-chain requirements intensify validation rigor. Flexible packaging simulation occupies the deepest margin pool due to nonlinear material characterization complexity and the specialized expertise required for polymer viscoelastic modeling. Food and beverage end users dominate volume adoption, though electronics represents the steepest growth trajectory driven by electrostatic discharge and shock sensitivity protocols.
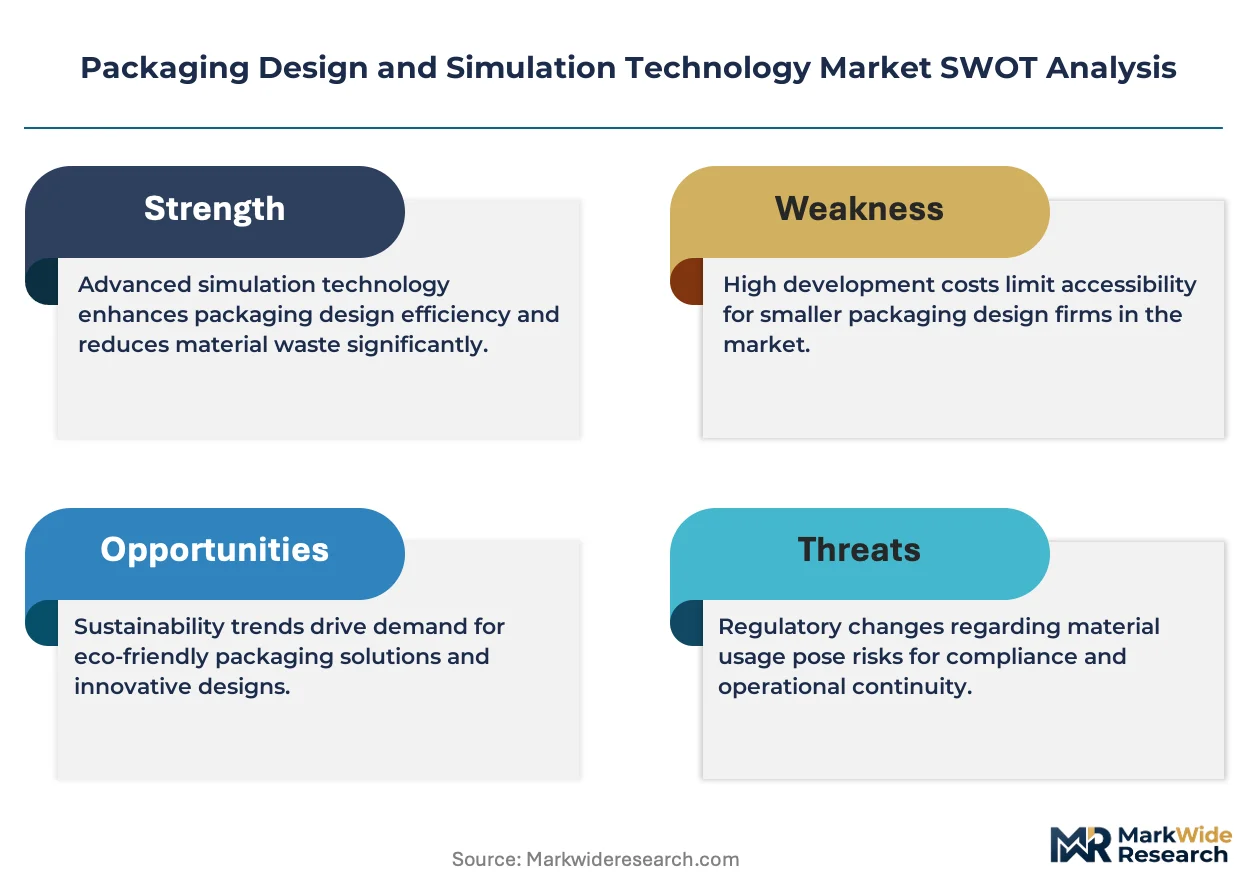
FDA 21 CFR Part 11 compliance requirements shape software validation protocols for pharmaceutical simulation workflows, while EU MDR technical documentation standards extend traceability obligations to packaging performance claims. ISO 11607 sterilization validation standards further constrain acceptable modeling tolerances for medical device primary packaging. REACH substance restrictions on certain plasticizers are forcing recalibration of material property databases embedded in simulation libraries. Stakeholders must weigh cloud solver accessibility against data sovereignty requirements as regulatory scrutiny of packaging sustainability claims intensifies.
Market Dynamics
Virtual prototyping workflows are compressing pharmaceutical packaging qualification timelines from months to weeks, forcing incumbent simulation vendors to recalibrate pricing architectures and solver accessibility for mid-tier converters.
Growth Catalysts
- Cold-chain pharmaceutical protocols:Temperature excursion validation requirements from FDA 21 CFR Part 11 are mandating digital twin deployment across sterile container development pipelines.
- EU Packaging and Packaging Waste Regulation:Material efficiency mandates are accelerating finite element analysis adoption for lightweighting optimization in automotive and industrial packaging clusters.
- Polymer viscoelastic modeling advances:Nonlinear characterization breakthroughs are unlocking simulation accuracy for flexible packaging formats previously resistant to computational validation.
Market Restraints
- High-performance computing costs:Mesh densities exceeding 10^6 elements require specialized GPU clusters that exclude smaller converter operations from competitive simulation depth.
- Material property database gaps:REACH substance restrictions on legacy plasticizers have invalidated established polymer models, forcing costly recalibration cycles.
- Cloud solver data sovereignty:Pharmaceutical manufacturers face jurisdictional compliance conflicts when deploying EU-regulated packaging data on non-European cloud infrastructure.
Strategic Opportunities
- Electronics electrostatic discharge protocols:Shock sensitivity modeling for semiconductor transport packaging represents an underpenetrated vertical with steep margin potential.
- ISO 11607 sterilization validation:Medical device primary packaging tolerance requirements are creating certified simulation service niches for specialized consultancies.
- Cloud-native solver architectures:Browser-based multiphysics platforms are democratizing access for tier-two food and beverage converters previously locked out of enterprise licensing.
Industry Challenges
- Multiphysics coupling expertise scarcity:Engineers capable of integrating thermal, structural, and fluid interaction models command premium compensation that strains mid-market hiring budgets.
- Legacy CAD integration friction:Established automotive packaging workflows built on proprietary formats resist seamless data handoff to modern simulation environments.
- FDA software validation timelines:21 CFR Part 11 compliance documentation for new simulation modules extends commercialization cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Design and Simulation Technology Market |
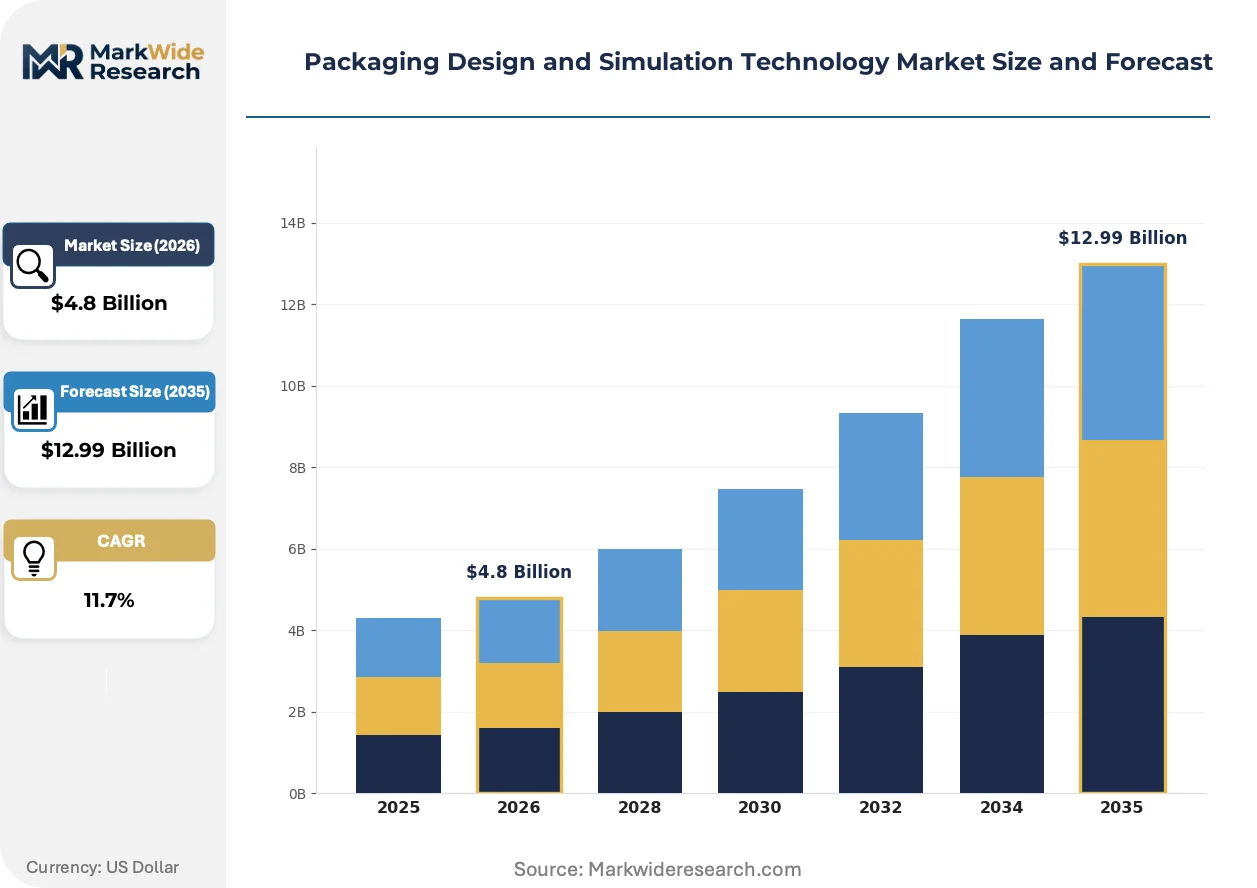
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Labels, Containers Technology: 3D Visualization, Finite Element Analysis, CAD, Virtual Prototyping End User: Food & Beverage, Personal Care, Pharmaceuticals, Electronics Application: Design Improvement, Cost Reduction, Sustainability Practices, Market Testing |
| Companies Covered | ANSYS, Dassault Systèmes, Esko, Siemens Digital Industries, Autodesk, Altair, ESI Group, MSC Software, AVID Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Design and Simulation Technology Market Strategic Shifts
Artificial intelligence is embedding itself across the simulation stack, from generative design exploration to automated mesh refinement, compressing the expertise barrier that previously gated advanced packaging analysis.
Physics-informed neural networks are displacing traditional finite element solvers for preliminary drop-test screening. Pharmaceutical cold-chain engineers at mid-tier contract manufacturers are adopting these tools within six-month evaluation cycles. The technology is displacing month-long physical prototyping phases with hour-long computational iterations, collapsing supplier qualification timelines.
EU MDR technical documentation standards now extend traceability obligations to packaging performance claims, mandating simulation audit trails for sterile barrier systems. Medical device manufacturers must reconstruct modeling assumptions for notified body review. German automotive packaging clusters are responding by embedding ISO 13485 quality management protocols into simulation workflows preemptively.
Subscription-based solver access is eroding perpetual licensing dominance among European converter networks. Tier-two food and beverage packaging engineers now procure simulation capacity by the hour rather than committing to five-year enterprise agreements. This procurement rotation is most visible in Benelux and Nordics markets where converter consolidation has concentrated buying power.
Packaging Design and Simulation Technology Market Segmentation
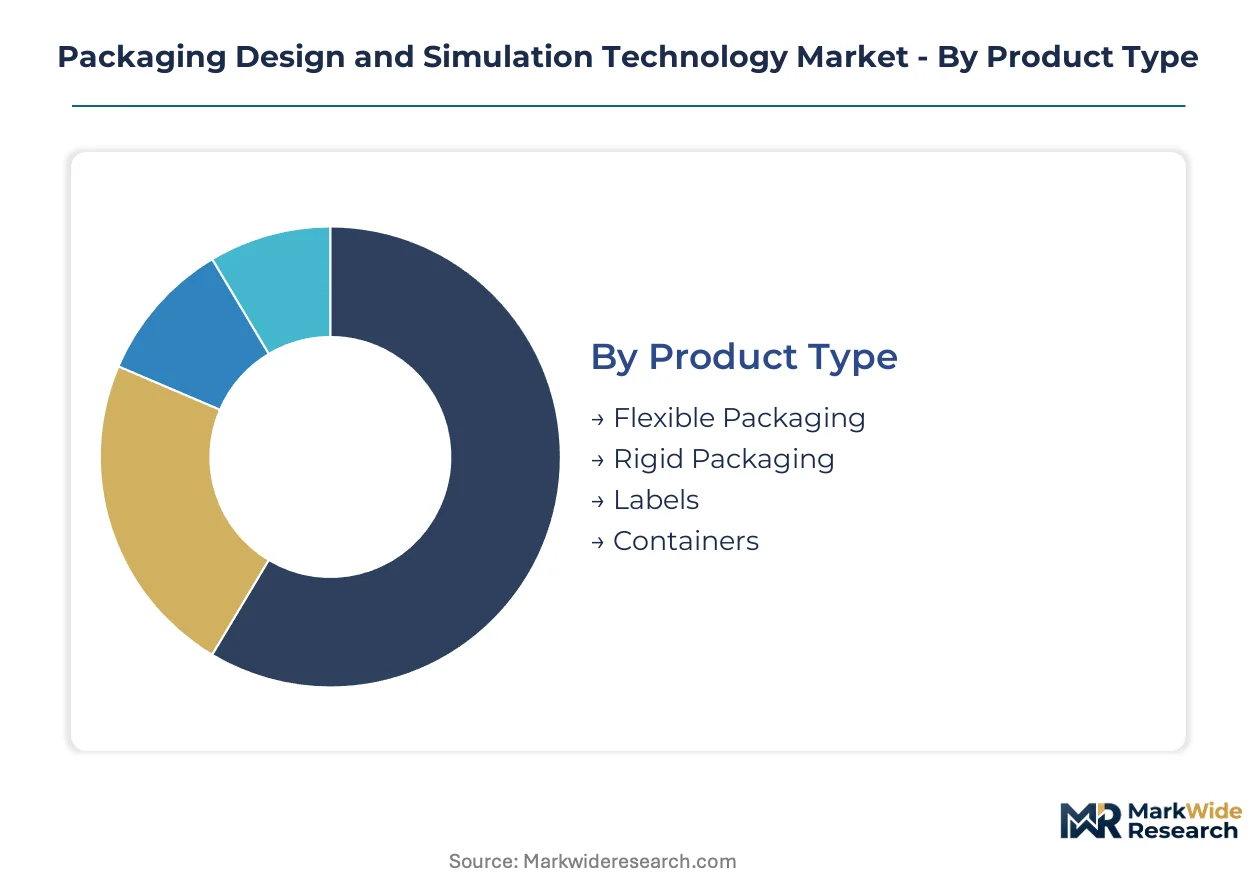
Segmentation in packaging design and simulation technology reveals how computational investment flows through distinct material formats, solver methodologies, and regulatory environments. Channel mix varies sharply across these dimensions, with pharmaceutical workflows demanding validated digital twins while food converters prioritize accessible cloud solvers.
Product Type:
Channel distribution for simulation tools diverges sharply by packaging format, with flexible packaging solutions flowing through polymer specialist consultancies and rigid formats dominating direct enterprise licensing.
- Flexible Packaging:Nonlinear viscoelastic modeling for films, pouches, and laminates requires specialized polymer characterization expertise. German automotive packaging clusters and Dutch food converters drive the deepest simulation investment here, constrained by REACH substance restrictions forcing material database recalibration.
- Rigid Packaging:Structural finite element analysis for bottles, trays, and clamshells leverages established CAD-native workflows. Pharmaceutical sterile container development in Switzerland and France concentrates demand, accelerated by EU MDR traceability mandates for barrier system validation.
- Labels:Adhesive performance and print registration simulation occupies a narrow tooling niche with limited standalone solver demand.
- Containers:Aseptic integrity and drop-resistance modeling for primary packaging formats serves medical device and pharmaceutical end users with intensive regulatory documentation requirements.
Rigid packaging dominates installed base. Flexible packaging is where expansion concentrates.
Technology:
Cost tiering separates enterprise-grade multiphysics platforms from browser-accessible screening tools, with procurement patterns shifting toward subscription access for mid-market converters.
- 3D Visualization:Real-time rendering engines for design review and stakeholder communication reduce physical mockup cycles. Electronics packaging teams in Japan and South Korea adopt these tools fastest for electrostatic discharge visualization protocols.
- Finite Element Analysis:Mesh-based structural solvers for stress, strain, and thermal transfer represent the core simulation stack. German automotive suppliers and Swiss pharmaceutical manufacturers maintain the densest installed base, though GPU cluster costs exclude smaller operations.
- CAD:Native design environments with embedded simulation modules anchor legacy workflows in established packaging engineering departments.
- Virtual Prototyping:Integrated digital twin workflows compress qualification timelines from months to weeks. FDA 21 CFR Part 11 compliance requirements shape validation protocols for pharmaceutical deployments, while cloud-native architectures democratize access for tier-two converters.
Finite element analysis commands the largest installed base. Virtual prototyping is climbing the fastest.
End User:
Application maturity varies by sector compliance burden, with pharmaceutical and electronics end users accepting premium pricing for validated workflows while food and beverage procurement prioritizes cost efficiency.
- Food & Beverage:Shelf-life prediction and lightweighting optimization drive simulation adoption across converter networks. Benelux and Nordic markets show the steepest subscription solver uptake as consolidated buying power shifts procurement toward hourly capacity models.
- Personal Care:Aesthetic and ergonomic packaging validation occupies a mid-tier spending position with moderate regulatory documentation requirements.
- Pharmaceuticals:Cold-chain temperature excursion modeling and sterile barrier validation demand the highest simulation fidelity. EU MDR technical documentation standards and FDA 21 CFR Part 11 compliance create substantial vendor qualification barriers.
- Electronics:Shock sensitivity and electrostatic discharge protocols for semiconductor transport packaging represent an underpenetrated vertical with steep margin potential. Japanese and South Korean electronics manufacturers are accelerating adoption fastest.
Food and beverage dominates installed base. Electronics is gaining share fastest.
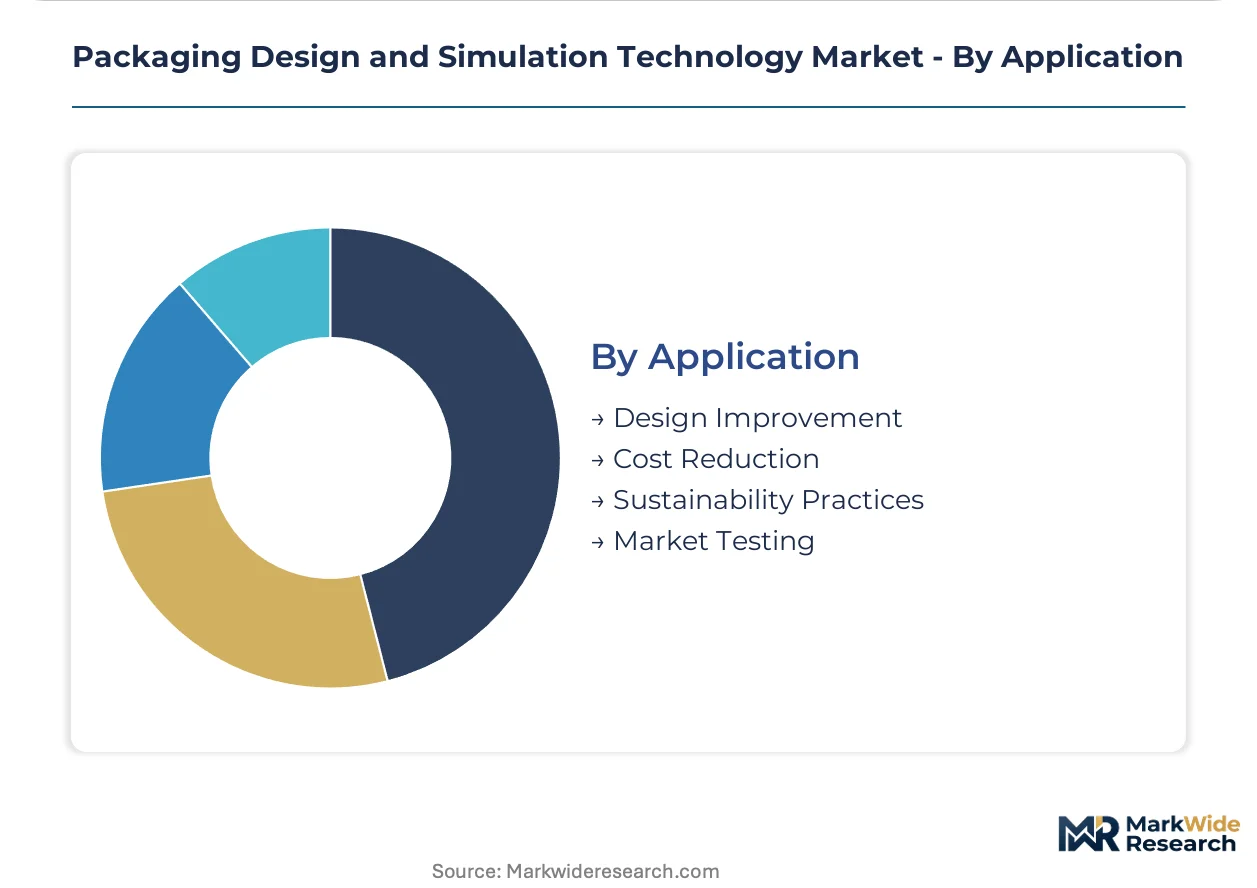
Application:
Customer type segmentation separates engineering-led design improvement from procurement-driven cost reduction, with sustainability practices increasingly bridging both constituencies.
- Design Improvement:Structural optimization and aesthetic refinement workflows serve brand-owner engineering teams with direct solver licensing. German automotive packaging clusters embed ISO 13485 quality protocols preemptively.
- Cost Reduction:Lightweighting and material minimization analysis responds to EU Packaging and Packaging Waste Regulation efficiency mandates across member states.
- Sustainability Practices:Lifecycle assessment integration and circularity modeling address tightening regulatory scrutiny of packaging environmental claims. ECHA substance database integration constrains acceptable material specifications.
- Market Testing:Consumer response simulation and virtual shelf placement occupy an emerging niche with limited current solver penetration.
Design improvement dominates installed base. Sustainability practices is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in packaging simulation technology favor established European and North American vendors supplying Asian manufacturing hubs. Germany and the United States maintain substantial trade surpluses in high-fidelity solver licenses and digital twin platforms. Chinese and Indian converters increasingly source cloud-native simulation capacity from Western providers while building indigenous alternatives.
Germany
Automotive packaging clusters in Stuttgart and Munich drive advanced finite element analysis adoption for lightweighting optimization. REACH substance restrictions under ECHA jurisdiction force continuous recalibration of polymer material databases embedded in simulation libraries. The Baden-Württemberg industrial corridor anchors Europe's densest concentration of packaging engineering consultancies specializing in multiphysics coupling.
United States
FDA 21 CFR Part 11 compliance requirements shape software validation protocols across pharmaceutical packaging workflows in New Jersey and Massachusetts. The EPA's evolving sustainability disclosure frameworks pressure material lifecycle assessment integration into simulation platforms. Greater Boston's medical device cluster demands ISO 11607-certified digital twin deployments for sterile barrier validation.
China
SAMR standardization initiatives accelerate domestic solver development for food and beverage packaging optimization across Yangtze River Delta manufacturing zones. Dual carbon goals under MEE jurisdiction mandate energy-efficient packaging simulation for export-oriented electronics manufacturers. Shenzhen semiconductor packaging facilities adopt electrostatic discharge modeling protocols fastest among Asia-Pacific markets.
Japan
METI industrial digitalization programs subsidize virtual prototyping adoption for precision electronics transport packaging in Nagoya and Osaka corridors. PMDA technical documentation standards extend traceability requirements to pharmaceutical primary packaging simulation workflows. Kyushu's semiconductor materials cluster drives regional demand for shock sensitivity and thermal excursion modeling.
India
CDSCO pharmaceutical packaging regulations tighten validation documentation for contract manufacturers in Maharashtra and Gujarat. The PLI scheme for specialty chemicals supports domestic polymer characterization laboratory expansion. Bangalore's medical device startup ecosystem sources cloud-native simulation tools to compress sterile container qualification timelines.
Packaging Design and Simulation Technology Market Competitive Environment
Concentration sits with diversified engineering software conglomerates anchoring enterprise-grade multiphysics platforms. The vendor landscape organizes into three functional tiers: full-suite platform providers with CAD-native integration, specialized finite element analysis houses with polymer expertise, and cloud-native challengers democratizing solver access. Consolidation pressure intensifies as pharmaceutical and automotive end users demand validated digital twin workflows spanning structural, thermal, and fluid interaction domains. Strategic moves center on subscription pricing architecture migration and preemptive ISO 13485 quality protocol embedding for medical device packaging verticals.
Among diversified platform providers, ANSYS and Dassault Systèmes occupy positions exemplifying the enterprise-tier archetype with regulatory-validated workflow depth. Altair represents the cloud-native challenger model reducing compute cost barriers for mid-tier converter operations. These three entities anchor competitive positioning across pharmaceutical cold-chain, automotive lightweighting, and electronics electrostatic discharge application vectors without exclusive segment lock-in.
| Leading Market Players |
|---|
| ANSYS |
| Dassault Systèmes |
| Esko |
| Siemens Digital Industries |
| Autodesk |
| Altair |
| ESI Group |
| MSC Software |
| AVID Technologies |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day solver licensing lead times concentrate pricing power with German and US platform providers, while cloud-native alternatives compress procurement cycles for tier-two converters seeking hourly capacity models. Pharmaceutical manufacturers absorbing FDA 21 CFR Part 11 validation costs accept premium perpetual licenses, whereas food and beverage buyers in Benelux and Nordic markets rotate toward subscription architectures that reduce capital commitment.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with pharmaceutical sterile container developers occupying the premium tier and automotive lightweighting engineers clustering in standard. Certification-grade differentiation separates FDA-validated digital twin workflows from browser-accessible screening tools lacking audit trail documentation. Pricing pressure stems from GPU cluster cost compression as mid-tier converters demand accessible multiphysics without enterprise infrastructure investment. Food and beverage procurement teams exhibit highest price sensitivity, while medical device manufacturers prioritize validation depth over licensing expenditure.
Supply Chain Analysis
Just-in-time solver deployment dominates pharmaceutical and automotive packaging clusters, whereas strategic stockpiling of polymer characterization data persists among flexible packaging specialists confronting REACH substance restriction volatility. Software development concentrates in Germany, the United States, and France, with cloud infrastructure drawing from Irish and Dutch data center hubs. Raw material dependencies include GPU semiconductor supply from Taiwan, polymer test data from German laboratories, and regulatory documentation templates from Swiss consultancies. Single-source vulnerability sits with NVIDIA GPU allocation for high-fidelity finite element mesh processing. Distribution runs through direct enterprise licensing for tier-one manufacturers and hourly marketplace access for tier-two converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated pharmaceutical and automotive packaging clusters that command volume-based solver pricing, while fragmentation among mid-tier food and beverage converters erodes individual negotiation leverage.
For Market Incumbents: Consolidate multiphysics coupling expertise through targeted acquisition of polymer characterization consultancies in Germany and Switzerland, defending against cloud-native challengers democratizing solver access. Deepen backward integration into GPU cluster infrastructure to reduce dependency on external compute pricing volatility. Preemptively embed ISO 13485 quality protocols into medical device packaging workflows before EU MDR traceability mandates harden competitive moats.
For New Entrants and Emerging Players: Anchor in electronics electrostatic discharge modeling for semiconductor transport packaging, the most penetrable vertical with steep margin potential and limited incumbent specialization. Target tier-two food and beverage converters in Benelux and Nordic markets through browser-based subscription solvers that bypass enterprise procurement friction. Pursue partnership-led go-to-market with polymer testing laboratories to accelerate material database credibility.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified engineering software conglomerates seeking to divest non-core packaging simulation modules. Long-term viability hinges on regulatory validation depth rather than raw computational performance, favoring assets with FDA 21 CFR Part 11 documentation infrastructure. Monitor cloud-native solver penetration rates among mid-tier converters as inflection indicator for pricing architecture disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Solver Architecture Migration | Browser-based multiphysics platforms democratize access for tier-two Benelux and Nordic converters previously excluded from enterprise licensing. |
| ISO 13485 Quality Protocol Preemption | German automotive packaging clusters embed medical device standards before EU MDR traceability mandates extend to sterile barrier systems. |
| Polymer Characterization Laboratory Acquisition | Specialized consultancies in Baden-Württemberg corridor anchor nonlinear viscoelastic modeling expertise for flexible packaging formats. |
| GPU Cluster Infrastructure Expansion | In-house compute capacity reduces dependency on external NVIDIA allocation for mesh densities exceeding 10^6 elements. |
| Electronics ESD Modeling Specialist Partnership | Japanese and South Korean semiconductor packaging facilities demand shock sensitivity simulation protocols with limited incumbent coverage. |
Study Parameters
Cross-validation between primary interviews with packaging engineering directors and secondary validation through FDA 510(k) filings anchors the qualitative findings. The research team conducted structured conversations with pharmaceutical simulation validation leads, automotive lightweighting engineers, polymer characterization specialists, cloud solver procurement officers, and regulatory affairs consultants at notified bodies. Secondary sources include ECHA substance restriction updates, EU MDR technical documentation guidance, SEC filings from listed engineering software providers, and customs data on solver license trade flows. Bottom-up demand modeling triangulates against top-down market sizing across technology categories.
Sensitivity analysis around GPU cost trajectories and REACH substance restriction timelines shapes the projection framework. The analytical model segments by packaging format, solver methodology, end-use vertical, and regulatory compliance tier across the analysis window. CAGRs derive from weighted average of historical adoption curves and technology substitution rates. Industry-specific forecast inputs include pharmaceutical cold-chain validation pipeline depth and automotive lightweighting regulatory mandate implementation schedules.
Decision-makers should treat outputs as directional under stable GPU supply and continued ECHA polymer database expansion assumptions; material deviation would warrant model refresh. Specific risks that could revise projections include export control restrictions on GPU semiconductor supply, accelerated EU Packaging and Packaging Waste Regulation enforcement, or breakthrough displacement of finite element methods by physics-informed neural networks. Revision becomes warranted when cloud-native solver penetration among mid-tier converters crosses threshold adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
Biodegradable Cups Market
Packaging
High-Density Packaging Market
Packaging
Metal Aerosol Can Market
Packaging
Canada Plastic Packaging Films Market
Packaging
Canada Disposable Tableware Market
Packaging
Gas-Flushing Band Sealing Systems Market
Packaging
Metallic Static Shielding Bags Market
Packaging
Collapsible Crate Market
Packaging
Sliding Blister Packaging Market
Packaging
Rigid Sleeve Boxes Market
Packaging
Global Molded Pulp Packaging Market
Packaging
Construction Films Market
Packaging
Ethiopia Container Glass Market
Packaging
Food Wrapping Paper Market
Packaging
Electrical Shielding Tape Market
Packaging
Middle East and Africa Aerosol Cans Market