
 Organic Textile Market | 2026-2036
Organic Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Textile Market Analytics
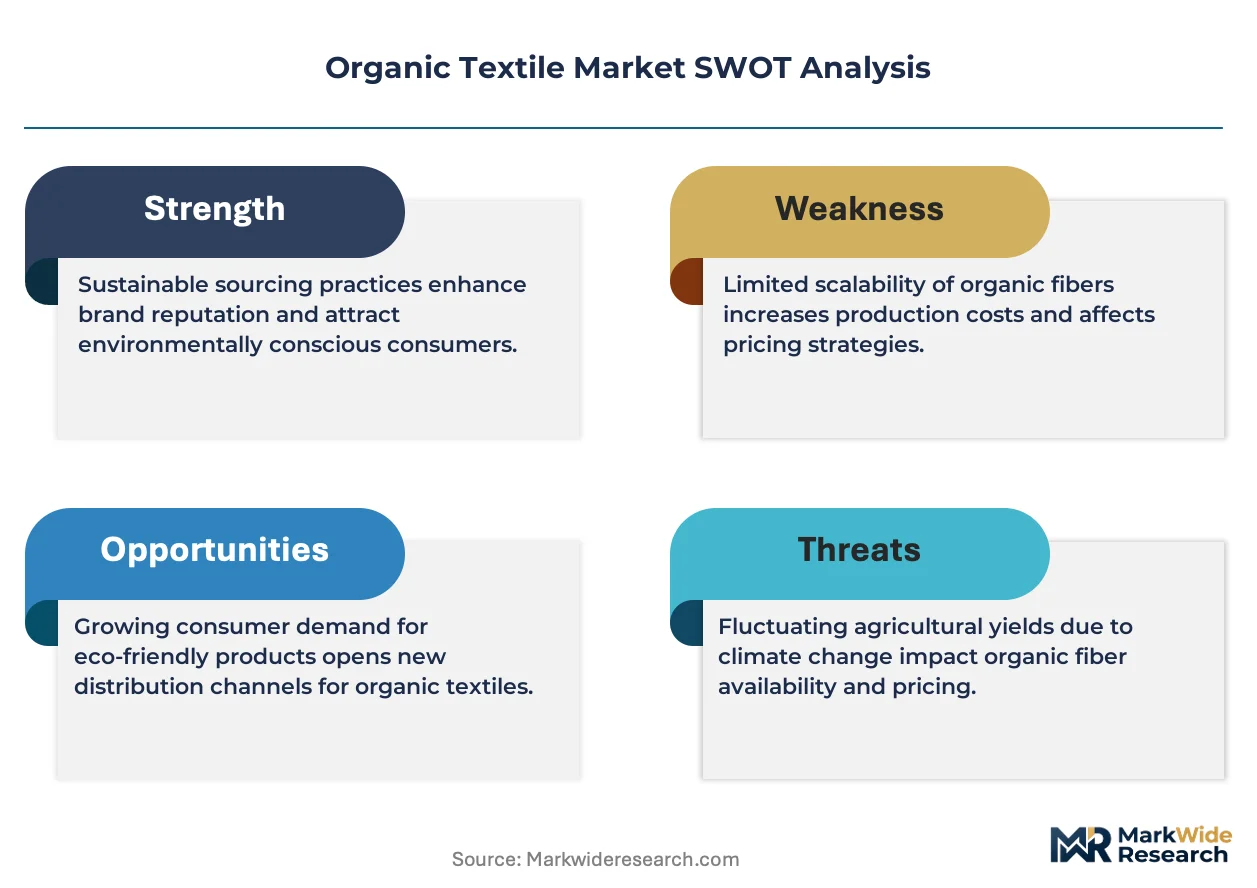
The EU Green Deal's textile sustainability requirements is rebalancing procurement priorities across European retail chains. Esquel Group leverages its vertically integrated organic cotton operations from Xinjiang to Vietnam to sustain long-term buyer contracts with brands seeking supply chain transparency. Patagonia anchors its market position through rigorous in-house sourcing standards that exceed baseline certification requirements. Vardhman Textiles competes on manufacturing scale, operating one of India's largest certified organic yarn production facilities.
Organic textiles comprise fibers cultivated without synthetic pesticides, genetically modified organisms, or petroleum-based fertilizers, typically processed under restricted chemical protocols such as GOTS-certified dyeing and finishing. These materials serve apparel, home furnishing, and technical applications where skin-contact safety and biodegradability carry premium value. Cotton dominates product type volume due to established ginning infrastructure and consumer familiarity, though hemp is gaining fastest as fiber decortication technology improves yield economics. Application segmentation tilts toward apparel and home textiles where eco-brand positioning commands price premiums, while industrial and non-woven segments remain nascent but hold margin expansion potential as automotive and medical sectors adopt biodegradable substrates.
GOTS certification, the EU's REACH chemicals framework, and India's BIS textile labeling standards collectively define market access thresholds for organic textile producers seeking cross-border sales. REACH restricts azo dyes and heavy metal finishes common in conventional processing, pushing dyehouses toward GOTS-approved chemical lists that add compliance cost but unlock European retail channels. Stakeholders must monitor divergence between national organic labeling rules and private certification schemes, as misalignment creates customs delays and duplicate audit burdens for multi-market suppliers.
Market Dynamics
EU Green Deal chemical disclosure mandates are forcing dyehouses to abandon azo dyes and heavy metal finishes, triggering a wholesale reconfiguration of sourcing relationships between European retailers and GOTS-certified spinners in South Asia.
Growth Catalysts
- EU REACH framework:Restrictions on hazardous processing chemicals push conventional textile mills toward GOTS-approved inputs, creating certified capacity shortages that premium buyers must secure through long-term contracts.
- Automotive interior applications:Biodegradable non-woven substrates for seat padding and insulation panels attract procurement teams from manufacturers seeking landfill diversion credits.
- Xinjiang-to-Vietnam migration:Vertically integrated cotton operations relocate spinning capacity to escape trade documentation scrutiny while preserving quality control standards.
Market Restraints
- Organic cotton fiber premiums:Farmgate prices for certified lint run 20-40% above conventional grades, compressing margins for mid-market apparel brands unable to pass full costs to consumers.
- Ginning infrastructure concentration:India and Turkey control the majority of mechanical processing equipment suitable for organic fiber separation, creating bottleneck risks during harvest windows.
- Hemp decortication yields:Bast fiber recovery rates remain below cotton-equivalent economics despite processing improvements, limiting near-term substitution at scale.
Strategic Opportunities
- Medical non-woven segment:Surgical gowns and wound dressings requiring skin-contact biocompatibility certification represent an underserved channel with margin structures above apparel.
- EU CSRD alignment:Corporate sustainability reporting mandates create procurement preference for suppliers with blockchain-tracked organic credentials.
- Enzymatic scouring:Convergence of biotechnology with textile preparation reduces water intensity in organic fiber processing, opening capacity expansion in water-stressed regions.
Industry Challenges
- GOTS auditor scarcity:Certification bodies face backlogs exceeding six months for facility inspections, delaying market entry for new spinning operations.
- Dyehouse retooling:Conversion to GOTS-approved chemical lists requires capital expenditure on effluent treatment and input storage systems that smaller processors cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Textile Market |
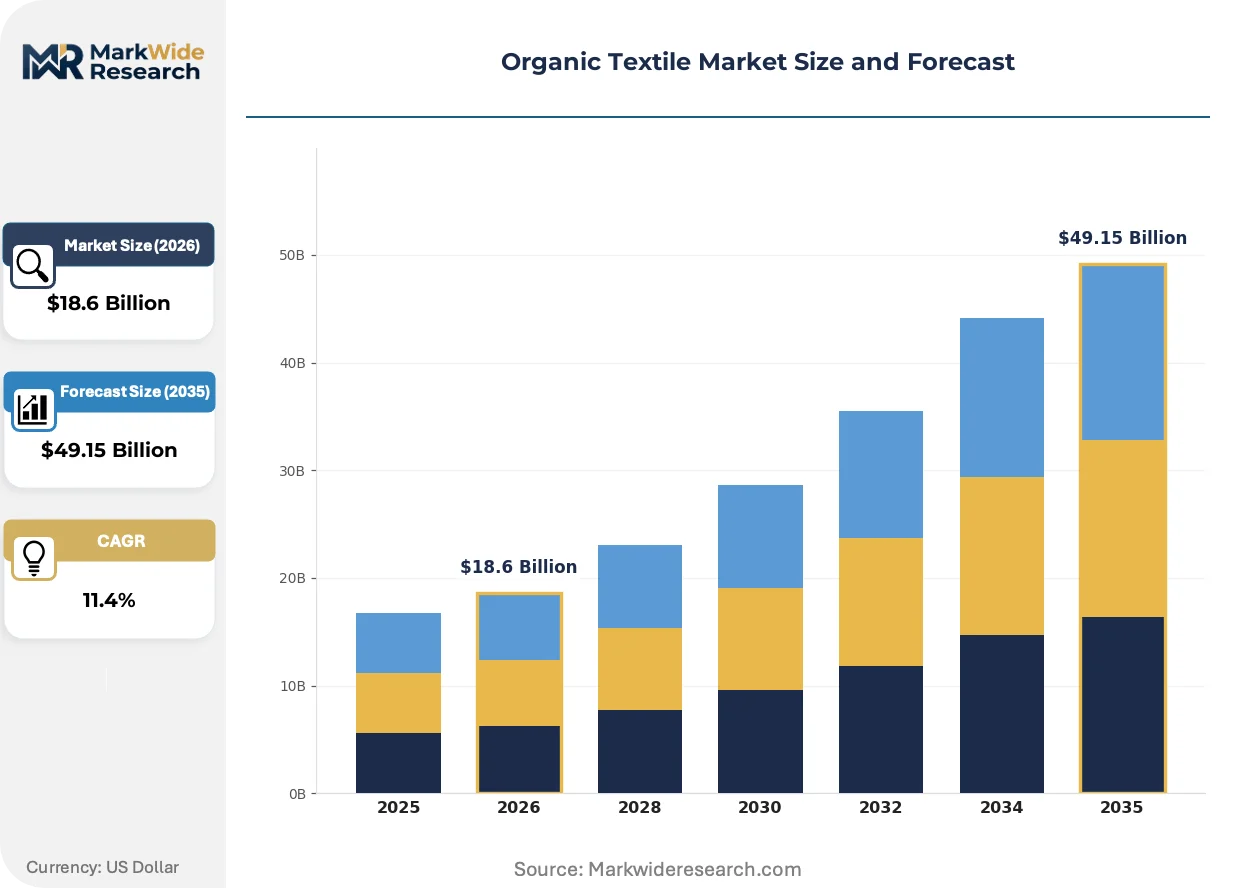
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $49.15 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton, Hemp, Linen, Bamboo Application: Apparel, Home Textiles, Industrial, Non-Woven End User: Retail, Manufacturers, Wholesalers, Eco-Brands Certification: GOTS, OEKO-TEX, USDA Organic, Global Organic Textile Standard |
| Companies Covered | Esquel Group, Welspun, Toray Industries, Billoomi Fashion, Arvind Ltd, Vardhman Textiles, Crystal International Group, Thygesen Textile Vietnam, Patagonia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Textile Market Evolving Landscape
Processing technology advances and regulatory disclosure requirements are compressing the gap between certified organic and conventional textile economics while fragmenting procurement authority across sustainability, quality, and finance functions.
Mechanical hemp fiber decortication is expanding into apparel supply chains as European technical textile engineers refine roller-mill configurations that reduce bast damage during separation. Denim brands in the Netherlands and Germany are trialing hemp-cotton blends at 20-30% fiber content, with spinning mills reporting acceptable yarn tenacity for twill constructions. This penetration is expanding into home textile categories previously reserved for all-cotton specifications.
REACH authorization procedures for disperse dyes and flame retardants are eliminating processing options for conventional mills serving EU export markets. ECHA's 2024 updates to restricted substance lists forced Turkish finishing houses to discard inventory and reformulate recipes using GOTS-compliant alternatives. The burden falls heaviest on mid-volume apparel suppliers lacking in-house chemical compliance teams.
Blockchain-enabled fiber provenance tracking is displacing paper-based certification for European luxury houses seeking litigation protection against greenwashing claims. Procurement directors now require QR-linked batch records from ginning through garment assembly, with verification costs absorbed by suppliers or passed through as line-item surcharges. France and Germany exhibit the strictest documentation expectations, with Dutch retailers following at narrower tolerance bands.
Organic Textile Market Segmentation
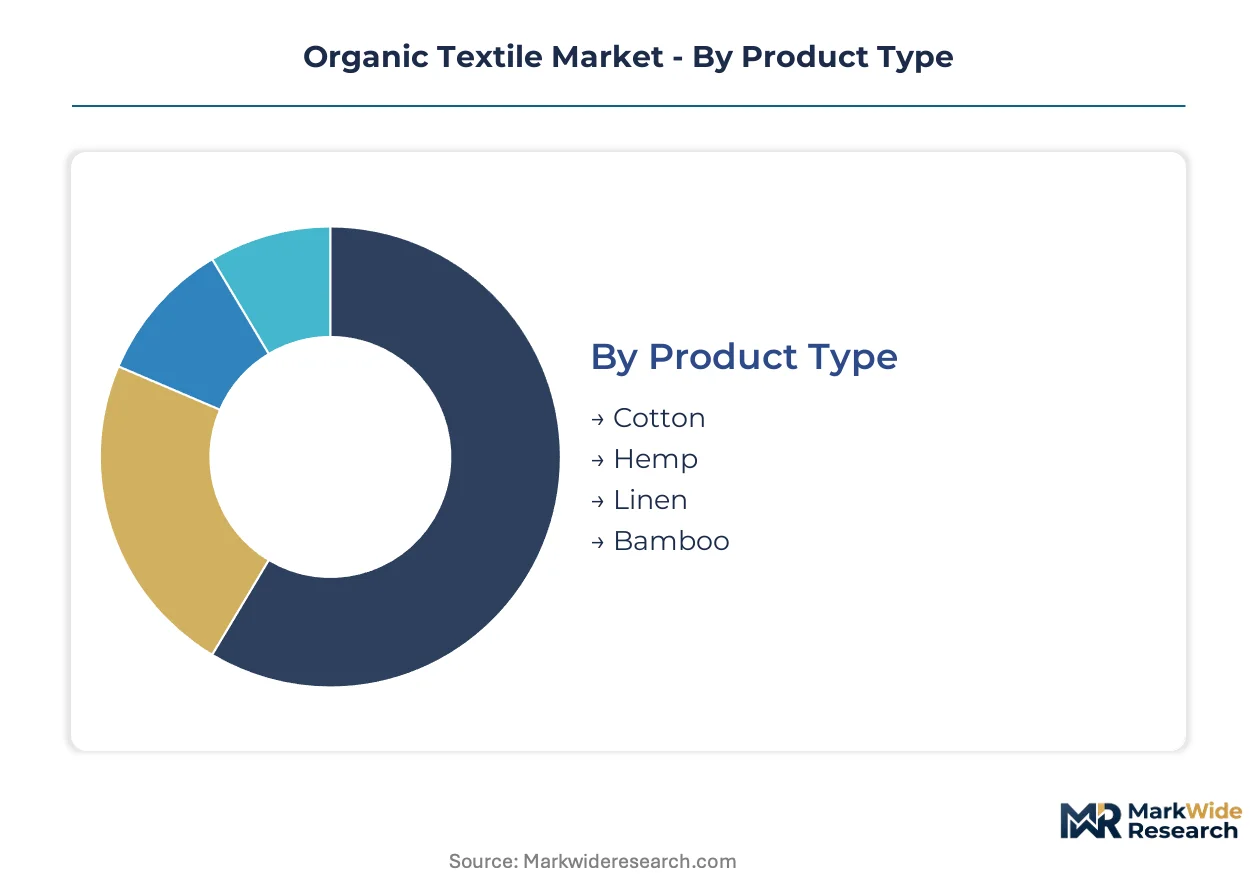
Segmentation in organic textiles reveals how certification tiers, fiber economics, and end-use specifications fragment procurement authority across sustainability, quality, and finance functions. Buyers optimize for traceability depth, chemical compliance, and volume scalability depending on their channel position.
Product Type:
Fiber selection hinges on ginning infrastructure maturity, decortication yield economics, and dye affinity for restricted-chemical processing protocols.
- Cotton:Long-staple varieties dominate certified volume through established mechanical separation infrastructure and consumer familiarity with natural fiber care. Apparel brands in Germany and France anchor procurement contracts on GOTS-certified lint from Indian ginning cooperatives, though farmgate premiums compress mid-market margins.
- Hemp:Bast fiber recovery rates are climbing as European roller-mill configurations reduce damage during decortication. Dutch and German denim mills now trial 20-30% hemp-cotton blends with acceptable yarn tenacity, expanding fastest into home textiles previously reserved for all-cotton specifications.
- Linen:Flax cultivation concentrates in France and Belgium, where dew-retting traditions align with EU organic labeling requirements. Linen commands niche positioning in premium shirting and bedding where slub texture carries aesthetic value.
- Bamboo:Viscose-processed bamboo faces scrutiny under REACH chemical disclosure rules, constraining European market access. Mechanical bamboo linen variants gain traction in Asian domestic markets where processing cost advantages offset certification complexity.
Cotton leads on scale; hemp leads on momentum.
Application:
End-use segmentation tracks biodegradability requirements, skin-contact safety standards, and price premium capture potential across consumer and industrial channels.
- Apparel:Direct skin-contact applications drive GOTS certification adoption, with EU retailers requiring blockchain-tracked batch records from ginning through garment assembly. Esquel Group and similar vertically integrated operators sustain long-term contracts through transparency documentation that exceeds baseline requirements.
- Home Textiles:Bedding and towel categories leverage organic positioning for margin expansion in European specialty retail, where eco-brand credentials justify price architecture. Hemp-cotton blends are penetrating this segment as fiber technology improves hand-feel equivalence.
- Industrial:Technical textile applications remain nascent but hold margin expansion potential as automotive manufacturers seek biodegradable substrates for interior components. Seat padding and insulation panels attract procurement teams pursuing landfill diversion credits.
- Non-Woven:Medical applications including surgical gowns and wound dressings represent underserved channels with biocompatibility certification requirements. This segment climbs fastest as healthcare procurement prioritizes skin-contact safety alongside disposability.
Apparel dominates current revenue; non-woven applications are climbing fastest.
End User:
Channel position determines certification stringency, volume commitment scale, and documentation depth requirements.
- Retail:European fashion houses and specialty chains drive GOTS demand through procurement policies that mandate chemical disclosure compliance. France and Germany exhibit strictest documentation expectations, with Dutch retailers following at narrower tolerance bands.
- Manufacturers:Tier-1 suppliers to automotive and medical sectors prioritize batch-level traceability for litigation protection against greenwashing claims. Blockchain-enabled provenance tracking is displacing paper-based certification for these buyers.
- Wholesalers:Volume distributors in India and Turkey manage certified inventory pools that bridge ginning concentration and fragmented retail demand, absorbing auditor backlog delays through pre-certified stock positions.
- Eco-Brands:Purpose-driven labels such as Patagonia anchor market position through in-house sourcing standards that exceed baseline certification requirements, creating specification tiers above commodity GOTS.
Retail commands procurement volume; eco-brands set specification ceilings.
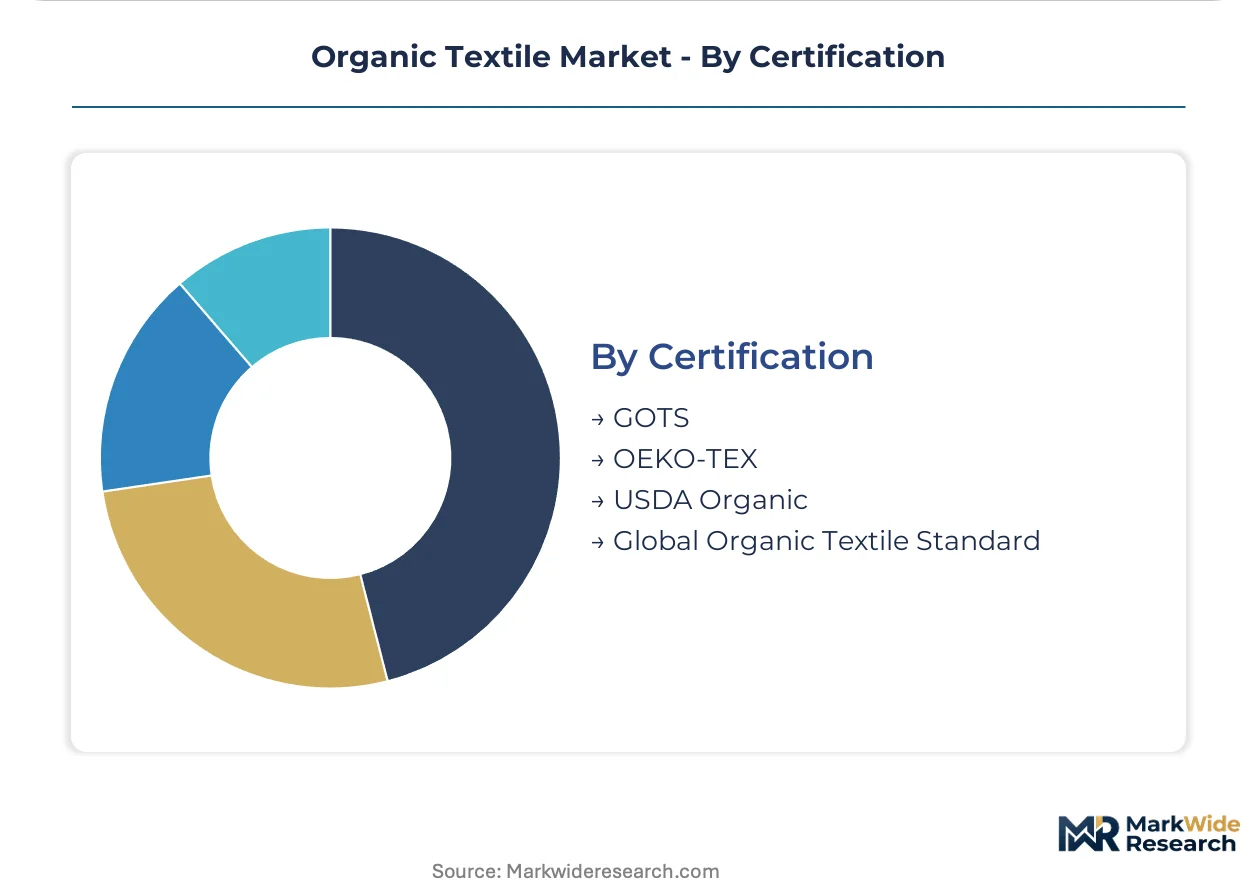
Certification:
Regulatory alignment and private scheme divergence create compliance cost layers that filter market access by processor scale and export destination.
- GOTS:The Global Organic Textile Standard integrates fiber cultivation, processing, and labeling requirements into a single audit framework. ECHA's REACH restrictions on azo dyes and heavy metal finishes push conventional mills toward GOTS-approved chemical lists, creating certified capacity shortages.
- OEKO-TEX:The Standard 100 framework addresses harmful substance testing without organic cultivation requirements, serving as a stepping-stone certification for processors transitioning toward full GOTS compliance. Mid-volume apparel suppliers lacking in-house chemical teams face heaviest burden from dual scheme maintenance.
- USDA Organic:United States Department of Agriculture labeling applies to raw fiber production, with downstream processing falling outside federal organic jurisdiction. This creates gap coverage that US-based brands supplement with private certification.
- Global Organic Textile Standard:This duplicates GOTS nomenclature in raw data and should be consolidated with the GOTS entry above; where distinct, it refers to the same integrated framework covering mechanical processing, wet processing, and trading operations under unified chain-of-custody documentation.
GOTS anchors cross-border trade; OEKO-TEX bridges transition economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organic textile manufacturing traces its industrial-scale origins to European dyehouse traditions, with mechanical processing expertise later migrating to South Asian spinning clusters. Today, certification requirements and chemical compliance frameworks redistribute competitive advantage across four distinct national production bases.
Germany
Denim brands in North Rhine-Westphalia and Baden-Württemberg trial hemp-cotton blends at 20-30% fiber content, with spinning mills reporting acceptable yarn tenacity for twill constructions. The EU Green Deal's REACH framework restricts azo dyes and heavy metal finishes, pushing domestic finishing houses toward GOTS-approved chemical lists. Stuttgart-based technical textile engineers refine roller-mill configurations that reduce bast damage during hemp decortication.
India
Ginning cooperatives in Gujarat and Maharashtra supply GOTS-certified lint to European apparel brands, though farmgate premiums compress mid-market margins. The Bureau of Indian Standards textile labeling requirements create baseline compliance thresholds for domestic producers. Tiruppur's dyehouse cluster retools effluent treatment systems to meet GOTS chemical storage protocols, absorbing auditor backlog delays through pre-certified stock positions.
Vietnam
Vertically integrated cotton operations relocate spinning capacity from Xinjiang to escape trade documentation scrutiny while preserving quality control standards. The country's national textile regulator aligns with ASEAN harmonization protocols for organic fiber import documentation. Ho Chi Minh City and Binh Duong Province concentrate the fastest capacity additions for GOTS-certified weaving operations serving EU retail contracts.
United States
USDA Organic labeling applies to raw fiber production, with downstream processing falling outside federal organic jurisdiction, creating gap coverage that domestic brands supplement with private certification. The EPA and FTC enforce greenwashing litigation protections that drive blockchain-enabled provenance adoption. California's eco-brand clusters anchor market position through in-house sourcing standards that exceed baseline GOTS requirements.
Netherlands
Dutch retailers follow German and French documentation expectations at narrower tolerance bands, creating procurement preference for suppliers with blockchain-tracked organic credentials. The country's national consumer protection authority enforces strict chemical disclosure mandates aligned with ECHA updates. Amsterdam's specialty retail chains leverage hemp-cotton blend penetration into home textile categories previously reserved for all-cotton specifications.
Organic Textile Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and traceability documentation tiers. The vendor base separates into three distinct strata: vertically integrated operators controlling cultivation through garment assembly, specialist spinners concentrating on certified yarn scale, and purpose-driven labels embedding sustainability specifications above baseline compliance. Competitive moves center on long-term contract lock-in with GOTS-certified capacity and enzymatic processing technology licensing for water-stressed region expansion.
Among Asia-Pacific-based fabricators, Esquel Group and Vardhman Textiles occupy positions at opposite ends of the integration spectrum. Esquel exemplifies the vertically integrated archetype with operations spanning Xinjiang cultivation through Vietnam garment assembly. Vardhman represents manufacturing-scale specialization, operating certified organic yarn production facilities that supply downstream cut-make-trim operators. Patagonia anchors the premium-tier vector as a purpose-driven label whose in-house sourcing standards create specification ceilings above commodity GOTS certification.
| Leading Market Players |
|---|
| Esquel Group |
| Welspun |
| Toray Industries |
| Billoomi Fashion |
| Arvind Ltd |
| Vardhman Textiles |
| Crystal International Group |
| Thygesen Textile Vietnam |
| Patagonia |
| Others |
Value Network & Pricing Analysis
European fashion house procurement teams concentrate purchasing authority for GOTS-certified organic textiles, imposing contract-based long-term offtake structures that lock in volume commitments against farmgate premium volatility. This buyer archetype dominance forces suppliers to absorb certification audit costs and chemical compliance investments upfront, compressing working capital cycles for mid-tier spinners serving secondary retail channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates blockchain-tracked luxury contracts from commodity GOTS certification and transitional OEKO-TEX positioning. Price differentiation hinges on certification depth and volume scale, with full provenance documentation commanding substantial premiums over baseline compliance. Cost compression in the standard tier is intensifying because farmgate organic cotton premiums run persistently above conventional grades. Mid-market apparel brands exhibit highest price sensitivity, while European luxury houses demonstrate lowest elasticity due to litigation exposure from greenwashing claims.
Supply Chain Analysis
Dual-sourcing requirements from EU retailers mandate multi-supplier qualification across Indian ginning cooperatives and Vietnamese spinning operations to mitigate single-source vulnerability. Geographic supply concentration centers on India, Vietnam, and Turkey, with mechanical processing infrastructure for organic fiber separation drawing from established equipment bases in Gujarat and Ho Chi Minh City. Raw material dependencies rest on certified cotton lint, GOTS-approved dyestuffs, and enzymatic scouring agents. Tariff exposure stalks Xinjiang-origin fiber documentation. Distribution runs through certified inventory pools managed by Turkish and Indian wholesalers bridging ginning concentration and fragmented retail demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic textile market compounds steadily as regulatory disclosure mandates harden procurement specifications across European retail chains. EU Green Deal chemical compliance requirements create durable demand for certified capacity that outpaces supply expansion.
For Market Incumbents: Acquire GOTS-certified spinning capacity in South Asia to preempt auditor backlog constraints and secure long-term buyer contracts. Esquel Group's vertically integrated model from cultivation through garment assembly demonstrates how upstream control over fiber provenance defends margin position against emerging regional competitors. Investment in enzymatic scouring technology licensing opens capacity expansion in water-stressed regions where conventional wet processing faces regulatory restriction. For New Entrants and Emerging Players: Launch via medical non-woven distribution partnerships targeting surgical gown and wound dressing procurement teams seeking biocompatibility certification. The medical segment remains underpenetrated relative to apparel saturation, with margin structures exceeding commodity textile economics. Direct-to-technical-textile-manufacturer positioning bypasses crowded retail channel competition and leverages faster certification pathways for single-use disposables. For Investors and Strategic Acquirers: Specialty chemical houses pursuing textile sustainability portfolios are the most active acquirer in this space, seeking dyehouses with GOTS-approved formulation libraries. The five-to-ten year viability window favors targets with pre-certified stock positions absorbing auditor scarcity delays. Acquisition target archetype: mid-cap spinners with established European retail relationships and excess certified capacity. Watch GOTS inspector training program expansion as the signal indicating certification bottleneck resolution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cotton Cultivation | Captures farmgate premiums and secures fiber provenance documentation for EU retail contracts. |
| Enzymatic Processing Technology Licensing | Reduces water intensity in scouring operations, enabling capacity expansion in drought-prone regions. |
| Blockchain-Enabled Provenance Tracking | Provides litigation protection against greenwashing claims for European luxury fashion houses. |
| Medical Non-Woven Segment Entry | Accesses biocompatibility-certified channels with margin structures above commodity apparel. |
| Long-Term GOTS-Certified Capacity Contracts | Locks in spinning and weaving output ahead of EU REACH chemical disclosure mandate enforcement. |
Research Methodology
Multiple input streams — primary interviews with spinning mill directors, dyehouse compliance officers, and European retail procurement leads; secondary validation through GOTS certification databases, ECHA restricted substance registry updates, and Indian Bureau of Standards textile labeling records; plus customs trade flow documentation — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged ginning cooperative managers, technical textile engineers, and sustainability certification auditors. Secondary sources incorporated EU Green Deal implementation guidance, ASEAN harmonization protocols, and EPA greenwashing litigation filings.
Data-stream reconciliation across the projection horizon modeled segmentation dimensions including fiber type, end-use application, certification tier, and geographic production cluster. The analytical framework derived CAGRs through supply-side capacity buildout trajectories and demand-side procurement policy elasticity. Industry-specific forecast inputs incorporated GOTS auditor training pipeline expansion rates and REACH authorization procedure timelines for restricted dyestuffs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA substance list acceleration or abrupt Xinjiang trade documentation enforcement. Projections reflect assumptions regarding certification body capacity scaling and enzymatic processing technology adoption curves. Deviation in EU Green Deal implementation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textiles
Global Maternity Innerwear Market
Textiles
Aramid Conveyor Belt Market
Textiles
Sustainable Fabrics Market
Textiles
IMO Fiber Market
Textiles
Medical Non-Woven Disposables Market
Textiles
Ceramic Textiles Market
Textiles
US Textile Market
Textiles
Fiberglass Coated Fabric Market
Textiles
Nonwoven Cleanroom Apparel Market
Textiles
Europe Textile Dyes Market
Textiles
Antimicrobial Textiles Market
Textiles
Multifunctional Clothes Folding Machine Market
Textiles
Nonwoven Floor Covers Market
Textiles
Italy Textile Manufacturing Market
Textiles
TIC for Apparel Market
Textiles
Canvas Bags Market