
 Organic Fruit Powder Market | 2026-2036
Organic Fruit Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Fruit Powder Market Analytics
Market Context with Strategic Players
Single-serve sachet bundling is rebalancing buyer choice toward trial-sized organic fruit powder assortments in direct-to-consumer channels. NutraDry leverages captive spray-drying capacity in the Pacific Northwest to sustain bulk supply contracts with beverage co-packers. FutureCeuticals anchors its position through backward integration into blueberry cultivar development, while Fruit d'Or Nutraceuticals differentiates via certified organic cranberry and blueberry powder lines for supplement brands.
Technical Definition and Structural Segments
Organic fruit powder consists of dehydrated, pulverized fruit tissue processed under certified organic protocols, typically retaining moisture below five percent and preserving native polyphenol profiles through controlled thermal or cryogenic drying. The primary commercial purpose centers on delivering concentrated flavor, color, and phytonutrient density to formulated foods, supplements, and functional beverages without synthetic additives. Freeze-dried powders command premium positioning in nutritional supplements due to superior aromatic retention and structural integrity, while spray-dried variants dominate food processing volumes where cost efficiency outweighs sensory fidelity. Bakery applications represent the fastest-growing demand pool as clean-label formulators replace artificial flavor systems with standardized fruit powders.
Regulatory Frame and Forward-Looking Close
The USDA National Organic Program, EU Organic Regulation 2018/848, and FDA food facility registration requirements collectively shape market access through supply chain traceability mandates and residue testing protocols. EFSA novel food evaluations and USDA organic certification audits constrain ingredient sourcing flexibility while creating compliance barriers for uncertified entrants. Stakeholders must monitor evolving EU Green Deal agricultural targets and potential alignment shifts in USDA enforcement priorities that could reroute procurement toward regenerative-certified orchards.
Market Dynamics
EU Organic Regulation 2018/848 residue limits are compressing ingredient sourcing flexibility for functional beverage formulators, forcing procurement teams to validate orchard-level traceability before contract execution. This regulatory tightening is redrawing competitive advantage toward suppliers with captive organic cultivation and certified drying infrastructure.
Growth Catalysts
- EU Green Deal agricultural targets:Regenerative orchard certification requirements are accelerating grower conversion to organic protocols, expanding certified raw material availability for powder processors.
- Clean-label bakery reformulation:Industrial bakers in Germany and France are replacing synthetic flavor systems with standardized blueberry and mango powders to meet retailer clean-label mandates.
- Freeze-drying technology diffusion:Cryogenic drying capacity expansion in the Pacific Northwest is improving aromatic retention for nutraceutical-grade powders, opening premium supplement applications.
Market Restraints
- Organic input cost volatility:Certified fresh fruit prices fluctuate with weather-driven yield variation, compressing processor margins during poor harvest seasons.
- Supply concentration in Pacific Northwest:Blueberry powder production clusters in Oregon and Washington, creating geographic risk exposure for buyers without multi-source contracts.
- USDA organic certification audit timelines:Facility certification delays of 12-18 months constrain new entrant capacity expansion and contract qualification.
Strategic Opportunities
- Underpenetrated clinical nutrition:Hospital and eldercare foodservice channels in Japan represent untapped demand for polyphenol-dense fruit powders with documented antioxidant profiles.
- Regenerative organic certification:USDA pilot programs for soil health verification create premium tier differentiation beyond baseline organic compliance.
- Direct-to-consumer sachet bundling:Single-serve trial formats are displacing bulk canister sales in online supplement channels, lowering customer acquisition costs for emerging brands.
Industry Challenges
- Polyphenol stability expertise gap:Formulation chemists with cryogenic drying process knowledge command premium compensation, constraining R&D team scaling.
- Multi-jurisdiction certification complexity:Simultaneous USDA NOP, EU 2018/848, and JAS organic compliance requires dedicated regulatory affairs headcount.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Fruit Powder Market |
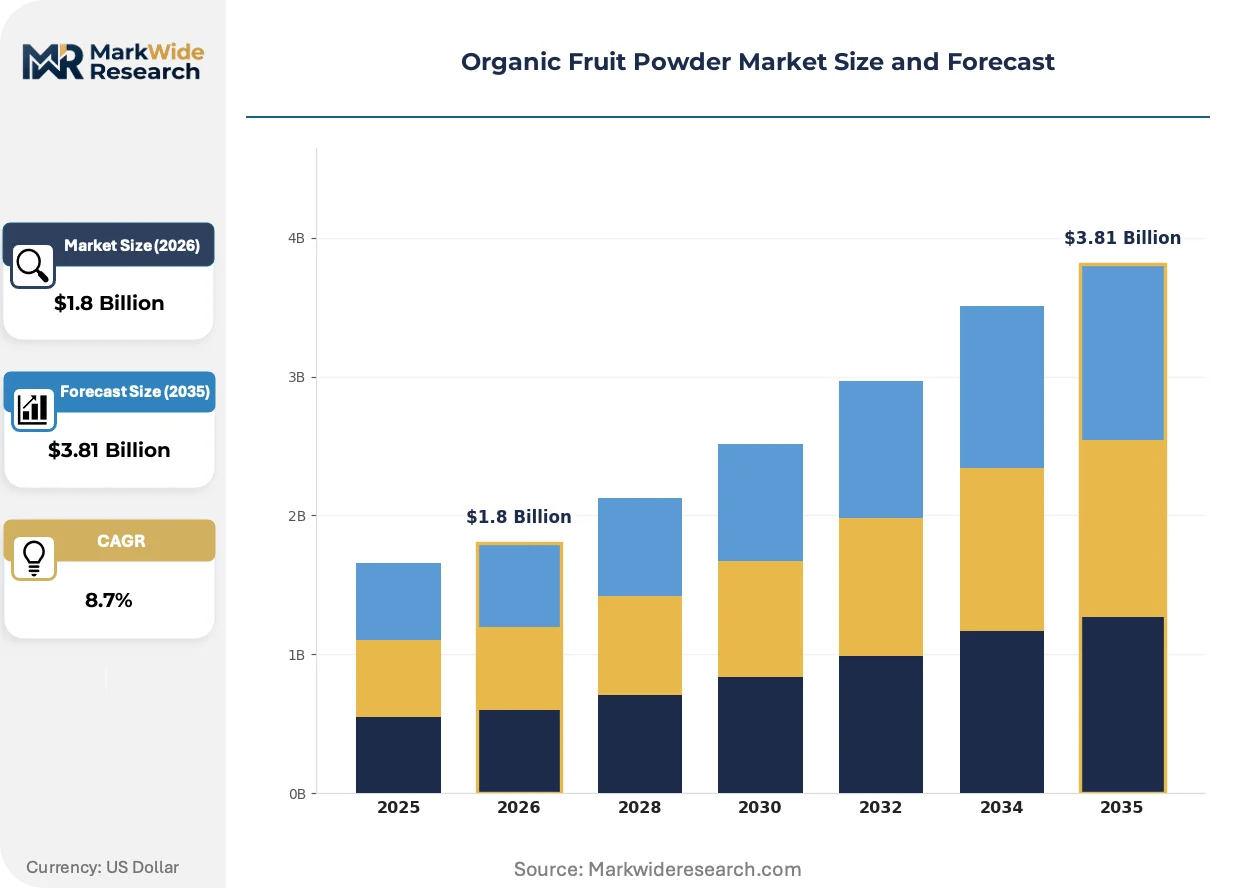
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
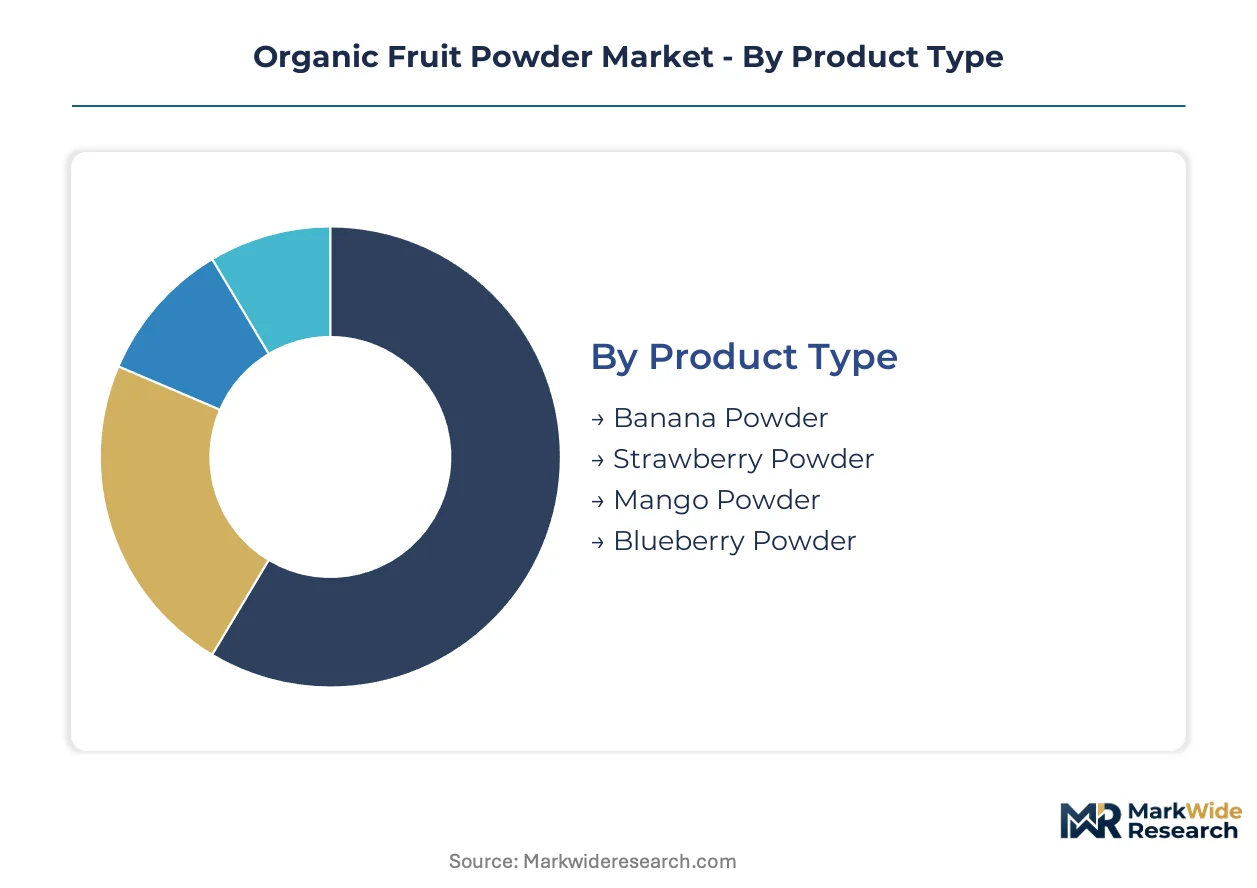
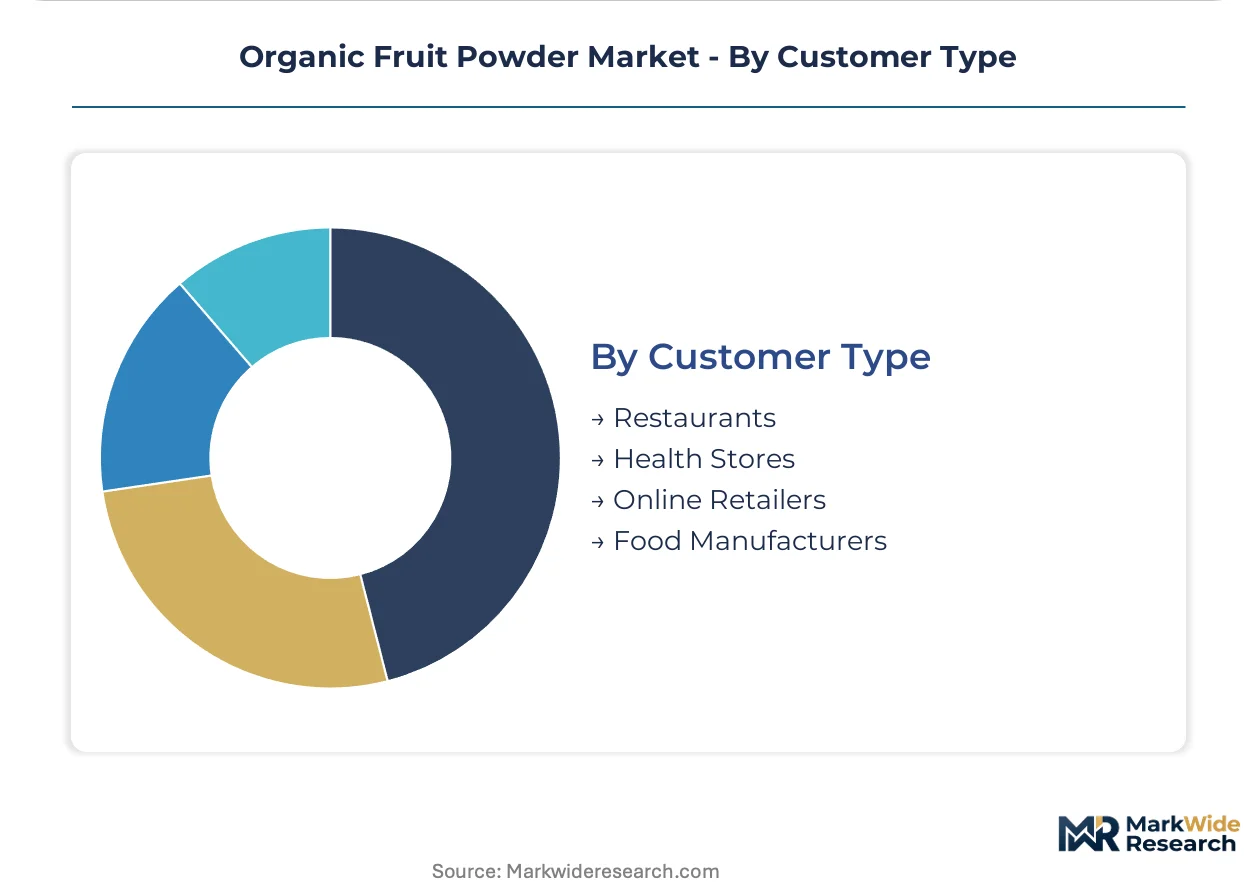
| Segmentation | Product Type: Banana Powder, Strawberry Powder, Mango Powder, Blueberry Powder Form: Freeze-Dried, Spray-Dried, Air-Dried, Dehydrated Application: Food Processing, Nutritional Supplements, Bakery Products, Beverages Customer Type: Restaurants, Health Stores, Online Retailers, Food Manufacturers |
| Companies Covered | Saipro Biotech Pvt Ltd, NutraDry, Northwest Wild Foods, Wildly Organic, KAREN'S NATURALS, Mevive International Food Ingredients, Fruit d’Or Nutraceuticals, FutureCeuticals, Baobab Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Fruit Powder Market Evolving Landscape
Controlled-atmosphere drying technologies are compressing the sensory quality gap between freeze-dried and spray-dried powders, enabling cost-sensitive food processors to access previously premium-only flavor profiles. This technological convergence is redrawing segment boundaries across beverage, bakery, and supplement applications.
Cryogenic grinding coupled with nitrogen-flush packaging is integrating into high-throughput processing lines, preserving volatile aromatic compounds through temperature-controlled pulverization and immediate oxygen exclusion. Nutraceutical contract manufacturers in California and Bavaria are adopting these integrated systems to meet supplement brands' stability specifications. The technology is integrating formerly separate drying, milling, and packaging stages into continuous operations, reducing handling losses and labor intensity.
EFSA novel food evaluations for emerging tropical fruit powders are extending market access timelines, requiring comprehensive toxicological dossiers for non-traditional species like camu camu and açai. This regulatory friction favors established berry powders with grandfathered safety status while constraining innovation pipelines for exotic alternatives. Supplement brands are responding by concentrating R&D investment on polyphenol enhancement of already-approved blueberry and cranberry matrices rather than pursuing novel species qualification.
Certification-driven preference shifts are compressing buyer evaluation cycles, with procurement teams now requiring organic and regenerative credentials before technical specification review. This behavioral change elevates compliance documentation to primary selection criteria, displacing historical price-tonnage negotiation sequences. The shift is most visible in German and Dutch beverage co-packer channels, where retailer sustainability scorecards mandate verified organic supply chain documentation upstream to orchard level.
Organic Fruit Powder Market Segmentation
Segmentation in organic fruit powder markets reveals how drying technology and end-use specifications create distinct procurement patterns. Buyers upgrade from spray-dried to freeze-dried formats as clean-label requirements intensify, while application-driven sourcing separates commodity food processors from premium nutraceutical formulators.
Product Type:
Reformulation cycles in functional foods and supplements are accelerating replacement demand for specific fruit matrices with documented polyphenol profiles.
- Blueberry Powder:Anthocyanin-rich matrices from Vaccinium cultivars deliver standardized antioxidant content for cognitive health supplements. Demand concentrates in Pacific Northwest processing clusters supplying German and United States nutraceutical contract manufacturers facing EU Green Deal residue compliance deadlines.
- Mango Powder:Carotenoid-dense powders from Mangifera indica pulp retain tropical flavor intensity through controlled thermal processing. United States beverage co-packers in California and Florida are expanding procurement for clean-label smoothie base formulations.
- Strawberry Powder:Ellagic acid-bearing powders from Fragaria species support antioxidant positioning in women's health supplements.
- Banana Powder:Resistant starch-rich green banana matrices serve prebiotic fiber applications in clinical nutrition and infant formula.
Volume placements concentrate in Blueberry Powder; the faster expansion belongs to Mango Powder.
Form:
Cost-tier differentiation separates mass-market food processors from premium supplement brands based on aromatic retention requirements and per-kilogram procurement budgets.
- Freeze-Dried:Sublimation-based dehydration preserves cellular structure and volatile aromatic compounds at sub-zero temperatures. Nutraceutical-grade specifications command 3-4x price multiples over thermal alternatives, with demand clustering in United States and German supplement manufacturing corridors.
- Spray-Dried:Atomized pulp exposure to heated air streams delivers cost-efficient powders for high-volume bakery and beverage applications. Industrial bakers in France and Germany leverage this format for clean-label flavor replacement at scale.
- Air-Dried:Convective dehydration at moderate temperatures balances cost and quality for private-label foodservice applications.
- Dehydrated:Traditional thermal methods serve commodity ingredient channels with minimal processing investment.
Procurement volumes skew toward Spray-Dried; premium positioning gains share fastest in Freeze-Dried.
Application:
Customer maturity stages dictate specification stringency, with early-adopter supplement brands driving cryogenic drying adoption while mainstream food processors optimize for cost-per-kilogram.
- Nutritional Supplements:Polyphenol-standardized powders with certificate of analysis documentation for antioxidant activity. United States and German brands require batch-level traceability to certified organic orchards under USDA NOP and EU 2018/848 protocols.
- Bakery Products:Flavor-intense powders replacing synthetic color and taste systems in clean-label reformulations. French and German industrial bakers face retailer sustainability scorecards mandating verified organic supply chains.
- Beverages:Soluble formats for functional drink bases and smoothie concentrates.
- Food Processing:Commodity-grade powders for mass-market confectionery and dairy applications.
Contract volumes concentrate in Food Processing; Nutritional Supplements climbs fastest on premium pricing.
Customer Type:
Supply concentration in Pacific Northwest blueberry production shapes procurement geography, with multi-source strategies becoming essential for risk mitigation.
- Food Manufacturers:High-volume buyers with specification-driven procurement teams validating organic certification and residue testing. Oregon and Washington processors dominate contract fulfillment for United States-based CPG brands.
- Online Retailers:Direct-to-consumer channels driving single-serve sachet bundling and trial-size formats. German and United States supplement brands leverage this channel for customer acquisition cost optimization.
- Health Stores:Specialty retail requiring branded, story-driven organic positioning.
- Restaurants:Foodservice operators incorporating fruit powders into beverage and dessert applications.
Order volumes concentrate in Food Manufacturers; Online Retailers expands most quickly on format innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Oregon and Washington draw freeze-drying capacity investments through state-level clean energy tax credits and proximity to certified organic blueberry cultivation. Processing clusters concentrate near raw material sources to minimize polyphenol degradation during transport.
United States
Pacific Northwest beverage co-packers expand procurement of certified organic mango and blueberry powders as USDA National Organic Program audits intensify supply chain documentation requirements. Oregon's Business Energy Tax Credit accelerates cryogenic drying facility construction. Washington State processors dominate contract fulfillment for domestic nutraceutical brands requiring batch-level orchard traceability.
Germany
Industrial bakers in Bavaria and Baden-Württemberg replace synthetic flavor systems with standardized fruit powders to meet retailer sustainability scorecards under EU Green Deal agricultural targets. EU Organic Regulation 2018/848 residue limits compress ingredient sourcing flexibility. The Munich-Stuttgart corridor anchors reformulation demand for clean-label bakery applications.
Canada
British Columbia's organic blueberry growers supply raw material to cross-border processors as CFIA and USDA organic certification alignment simplifies North American trade. The Okanagan Valley concentration of certified organic cultivation supports powder processing investments. Vancouver-area facilities handle Pacific Rim export logistics for Asian nutraceutical distributors.
France
Île-de-France supplement brands drive demand for polyphenol-standardized cranberry powders as ANSM enforcement of novel food guidelines tightens ingredient qualification. The country's national food safety regulator coordinates with EFSA on organic residue testing protocols. Lyon-based foodservice distributors expand fruit powder portfolios for hospital and eldercare nutrition channels.
India
Maharashtra and Karnataka processing facilities export spray-dried mango powders to European beverage manufacturers seeking cost-efficient clean-label inputs. FSSAI organic certification alignment with EU 2018/848 streamlines market access. Mumbai-Pune industrial corridors concentrate drying capacity serving Middle East and Southeast Asian contract buyers.
Organic Fruit Powder Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification tiers, creating a bifurcated structure where captive organic cultivation separates premium-positioned suppliers from commodity processors. The vendor base clusters around three strategic archetypes: backward-integrated cultivator-processors, toll-drying service operators, and branded ingredient marketers. Capacity expansion and regenerative organic certification acquisition constitute the dominant competitive moves as procurement teams elevate compliance documentation above price negotiation.
Within the cultivator-processor archetype, Fruit d'Or Nutraceuticals and FutureCeuticals exemplify positions anchored in certified organic berry supply chains. Saipro Biotech Pvt Ltd represents Indian processing capacity serving export markets. NutraDry occupies a position among North American toll-drying specialists leveraging Pacific Northwest geographic concentration.
| Leading Market Players |
|---|
| Saipro Biotech Pvt Ltd |
| NutraDry |
| Northwest Wild Foods |
| Wildly Organic |
| KAREN'S NATURALS |
| Mevive International Food Ingredients |
| Fruit d'Or Nutraceuticals |
| FutureCeuticals |
| Baobab Foods Inc. |
| Others |
Value Network & Pricing Analysis
Freeze-drying technology diffusion in the Pacific Northwest is simultaneously elevating production costs and concentrating supply among certified processors, compressing margin structures for commodity-grade spray-dried alternatives while amplifying pricing power for aroma-retentive formats. This technological bifurcation rewards backward-integrated cultivator-processors with captive organic orchards, as EU 2018/848 residue mandates force buyers to absorb traceability premiums.
Pricing Analysis
Short lead-time procurement commands substantial premiums in contract negotiations, with German beverage co-packers paying elevated rates for certified organic blueberry powder with validated orchard documentation under compressed EU Green Deal compliance deadlines. Three-tier pricing structure across premium freeze-dried, standard spray-dried, and economy air-dried levels separates nutraceutical-grade specifications from industrial bakery inputs. Pricing pressure stems from weather-driven yield volatility in certified organic fruit, compressing processor margins during poor harvest seasons. Industrial bakers exhibit highest price sensitivity, while supplement brands prioritize polyphenol standardization over per-kilogram cost.
Supply Chain Analysis
Reverse-logistics infrastructure for organic certification documentation flows upstream from powder processors to orchard-level auditors, with batch-level traceability records circulating back through supply chains to satisfy EU 2018/848 and USDA NOP verification requirements. Raw material supply concentrates in Oregon and Washington for blueberry, Maharashtra and Karnataka for mango, and British Columbia for cross-border organic cultivation. Processing capacity draws from certified fresh fruit, cryogenic drying equipment, and nitrogen-flush packaging systems. Single-source vulnerability in Pacific Northwest blueberry production creates geographic risk exposure for buyers lacking multi-contract coverage. Distribution runs through beverage co-packers, supplement contract manufacturers, and direct-to-consumer online channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as EU 2018/848 residue limits and USDA certification audit timelines force uncertified processors into distressed exit scenarios, elevating acquisition opportunities for compliant operators with captive organic supply chains.
For Market Incumbents: Hedge geographic concentration risk by diversifying procurement contracts across British Columbia and Indian processing clusters, insulating against Pacific Northwest weather-driven supply disruptions. Deepen backward integration into regenerative organic orchard certification to capture premium tier pricing beyond baseline USDA NOP compliance, as German retailer sustainability scorecards elevate soil health verification to mandatory selection criteria. For New Entrants and Emerging Players: Enter via clinical nutrition channels in Japanese hospital and eldercare foodservice, where polyphenol-dense fruit powders with documented antioxidant profiles remain underpenetrated relative to North American and Western European supplement markets. Leverage single-serve sachet bundling formats to displace bulk canister sales in direct-to-consumer online channels, lowering customer acquisition costs through trial-sized assortments. For Investors and Strategic Acquirers: Exit pathways concentrate in cultivator-processor archetypes with certified organic berry supply chains and captive cryogenic drying infrastructure, as procurement teams elevate compliance documentation above price negotiation in vendor selection. Long-term viability favors operators with multi-jurisdiction certification capability spanning USDA NOP, EU 2018/848, and JAS organic protocols. Monitor EFSA novel food evaluation timelines for exotic tropical powders as inflection indicator for innovation pipeline constraints favoring established berry matrices.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Organic Certification | USDA pilot programs for soil health verification create premium tier differentiation beyond baseline organic compliance. |
| Multi-Source Procurement Contracts | British Columbia and Indian processing diversification reduces Pacific Northwest geographic risk exposure for buyers. |
| Cryogenic Drying Capacity Expansion | Oregon's Business Energy Tax Credit accelerates facility construction serving domestic nutraceutical brands. |
| Direct-to-Consumer Sachet Bundling | Single-serve trial formats displace bulk canister sales in online supplement channels, optimizing customer acquisition economics. |
| Clinical Nutrition Channel Development | Japanese hospital and eldercare foodservice represents untapped demand for polyphenol-standardized fruit powders. |
Research Methodology
Document review covered EU 2018/848 regulatory filings, USDA NOP certification databases, and EFSA novel food evaluation records, complemented by interviews with organic fruit powder processors, nutraceutical contract manufacturers, beverage co-packer procurement leads, and German industrial bakery reformulation teams. Secondary validation drew from customs trade data, organic certification audit reports, and state-level clean energy tax credit disclosures. Bottom-up volume modeling triangulated against top-down demand aggregation across application segments.
Historical shipment data cross-referenced against expert panel input on EU Green Deal implementation timelines and freeze-drying technology diffusion rates. Segmentation dimensions modeled included drying technology tier, fruit matrix type, end-use application, and customer channel archetype across the projection horizon. CAGRs derived from slope-consistency checks against organic input cost trajectories and certified cultivation expansion patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA novel food evaluation delays or abrupt EU residue limit tightening. Practitioners should monitor regenerative organic certification pilot program expansion and Pacific Northwest weather patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Organic Soy Products Market
Organic Food and Beverages
Australia Organic Food Market
Organic Food and Beverages
Organic Acai Juice Market
Organic Food and Beverages
United States Organic Skin Care Market
Organic Food and Beverages
Non-GMO Food Market
Organic Food and Beverages
UK Organic Food Market
Organic Food and Beverages
Japan Organic Food Market
Organic Food and Beverages
Global Natural and Organic Food Market
Organic Food and Beverages
Organic Coconut Syrup Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
Organic Yeast Market
Organic Food and Beverages
Scandinavia Organic Packaged Food and Beverages Market
Organic Food and Beverages
Organic Goji Berry Market
Organic Food and Beverages
Organic Coconut Sugar Market
Organic Food and Beverages
Global Organic Dried Fruit Market
Organic Food and Beverages
Spain Organic Food Market