
 Online Music Streaming Market | 2026-2036
Online Music Streaming Market Size, Share, and Industry Trends Forecast 2026-2036
Online Music Streaming Market Intelligence
The gap between premium subscription tiers and ad-supported free tiers is hardening around audio quality, offline access, and exclusive content libraries. Spotify leverages its algorithmic recommendation engine to sustain listener engagement across both tiers. Apple Music anchors its position through tight integration with proprietary hardware ecosystems and lossless audio streaming.
Online music streaming is the digital distribution of audio content via internet protocols, typically encoded at bit rates ranging from 128 kbps for standard streams to 9216 kbps for hi-res lossless formats, enabling on-demand playback without permanent local file storage. The subscription model segment splits into ad-supported, freemium, premium, and student plans, with premium tiers capturing the dominant share of revenue per user while ad-supported volumes drive platform scale. Content type segmentation spans original content, user-generated uploads, licensed tracks, and podcasts, with podcast investments expanding addressable listening hours and advertiser inventory.
The US Copyright Royalty Board sets mechanical royalty rates that directly impact platform cost structures and artist payout frameworks. The EU Digital Services Act imposes transparency obligations on recommendation algorithms and content moderation practices that affect user experience design. China's SAMR enforces antitrust scrutiny on exclusive licensing deals that once concentrated catalog control among single platforms. Stakeholders must weigh the trade-off between subscriber growth in price-sensitive markets and the margin compression from elevated content acquisition costs.
Market Dynamics
Platform economics now pivot on algorithmic personalization density and exclusive content acquisition costs, with royalty rate arbitrage between jurisdictions compressing margins faster than subscriber growth can offset.
Growth Catalysts
- Smartphone penetration clusters:India, Brazil, and Indonesia deliver mass-market access through sub-$200 Android devices and sub-$2 monthly data plans. Young demographics in these markets stream 3-4 hours daily.
- EU Digital Services Act transparency mandates:Algorithmic disclosure requirements reduce regulatory uncertainty for platforms operating across 27 member states. Compliance investments unlock standardized European expansion.
- Podcast format diversification:True crime, sports wagering, and regional language content extend daily active listening hours. Advertiser CPMs for spoken-word inventory exceed music streaming rates by 40-60%.
Market Restraints
- Mechanical royalty rate volatility:US Copyright Royalty Board proceedings reset statutory rates every five years. Platform cost structures face unpredictable step-function increases.
- Content licensing concentration:Major label catalogs concentrate among three global rights holders. Negotiating leverage tilts toward content owners in renewal cycles.
- Lossless bandwidth requirements:Hi-res audio streams at 9216 kbps strain mobile data caps. Infrastructure gaps in emerging markets throttle premium tier adoption.
Strategic Opportunities
- Underpenetrated African markets:Nigeria, Kenya, and South Africa exhibit 60%+ smartphone penetration with minimal paid music subscription penetration. Local artist aggregation strategies unlock first-mover positioning.
- AI-generated voice licensing frameworks:Synthetic artist vocals and automated mastering tools reduce production costs. Rights-clearance protocols for generative audio remain undefined.
- Automotive embedded streaming:Native dashboard integration replaces Bluetooth phone tethering. OEM pre-installation contracts secure captive listener bases.
Industry Challenges
- Recommendation algorithm audit complexity:EU Digital Services Act requires explainability documentation for content ranking systems. Engineering teams lack standardized methodologies for bias detection.
- Cross-border royalty accounting:Performing rights organizations in 180+ jurisdictions maintain incompatible reporting standards. Reconciliation latency stretches 12-18 months.
- Legacy hardware codec fragmentation:Proprietary spatial audio formats from Apple, Sony, and Dolby force multi-format encoding pipelines. Storage and delivery costs multiply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Music Streaming Market |
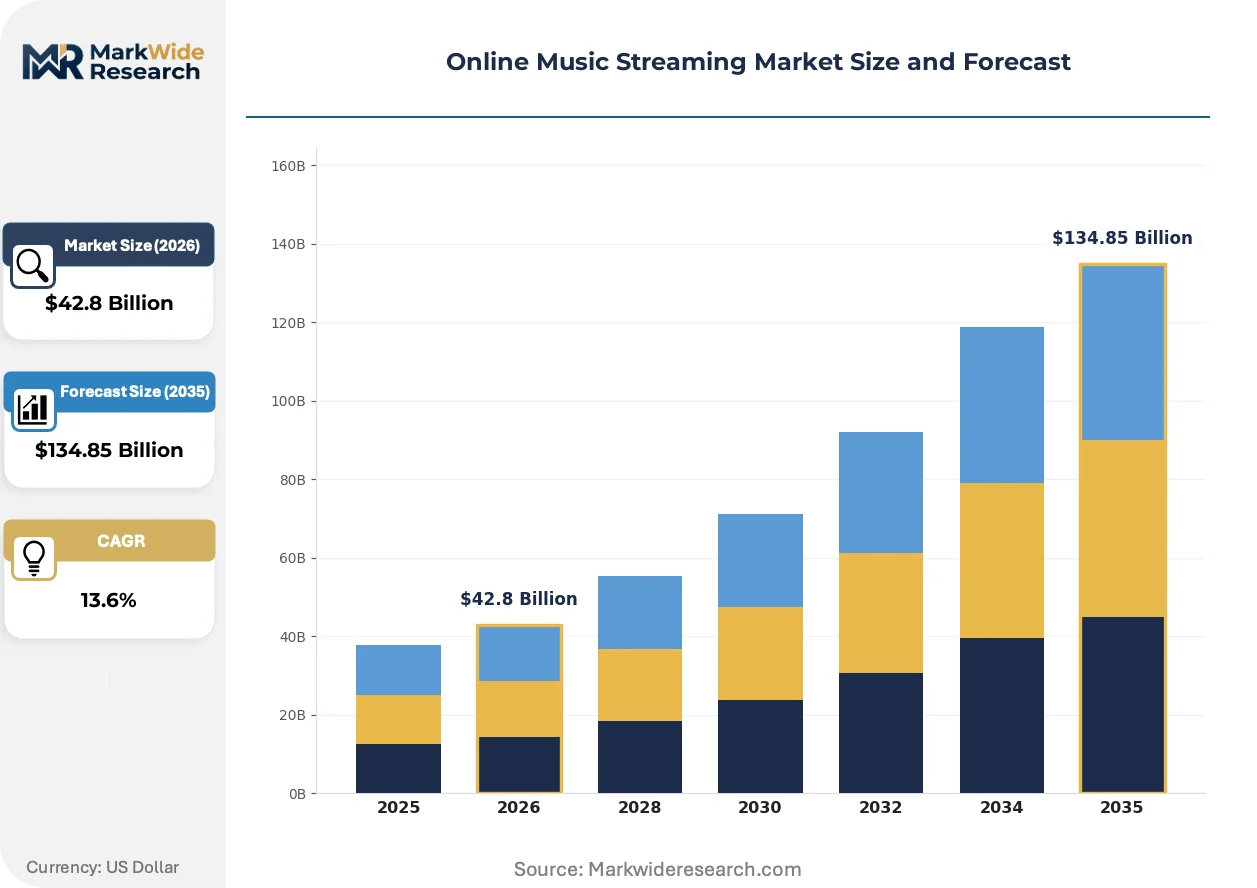
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $134.85 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Subscription Model: Ad-Supported, Freemium, Premium, Student Plans Content Type: Original Content, User-Generated, Licensed Tracks, Podcasts Device Type: Smartphones, Desktop PCs, Smart Speakers, Tablets End User: Individuals, Families, Educational Institutions, Businesses |
| Companies Covered | Spotify, Apple Music, Amazon Music, YouTube Music, Tencent Music, NetEase, Deezer, Tidal, Yandex Music, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Music Streaming Market Strategic Shifts & Innovations
Audio streaming infrastructure is bifurcating between lossless fidelity arms races and algorithmic engagement optimization, with regulatory transparency mandates forcing architectural redesigns of recommendation engines.
Spatial audio rendering is converging with head-tracking sensors in premium earbuds. Audiophile subscribers in Japan, Germany, and South Korea adopt Dolby Atmos and Sony 360 Reality Audio formats at 3x the rate of standard lossless tiers. Hardware-software bundling is compressing standalone streaming margins while elevating ecosystem lock-in.
The EU Digital Services Act mandates algorithmic audit trails and user control over recommendation parameters. Platforms must document content ranking logic and provide chronological feed alternatives. European user experience teams are stripping behavioral signals from ranking models to reduce regulatory surface area.
Listener attention is fragmenting across short-form audio clips, full albums, and background instrumental streams. Gen Z subscribers in Southeast Asia toggle between TikTok music discovery and platform full-track playback within single sessions. Discovery-to-conversion funnels compress from days to minutes.
Online Music Streaming Market Segmentation
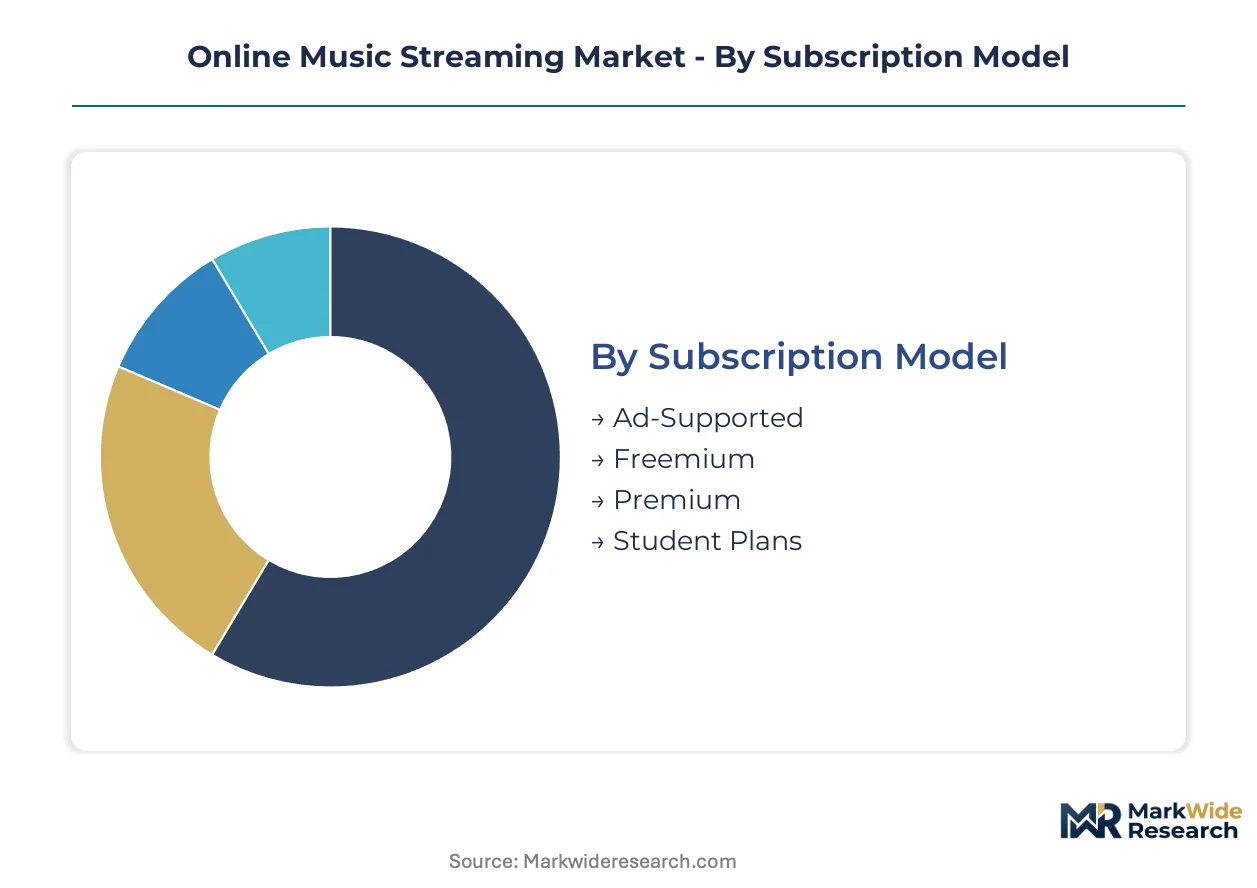
Streaming platforms architect pricing and content strategies around distinct listener clusters. Each segmentation dimension reveals where subscriber lifetime value concentrates and which infrastructure investments yield platform scale.
Subscription Model:
Standalone subscription tiers operate independently of hardware bundles, while embedded plans integrate with carrier billing and OEM pre-installs.
- Premium:Lossless audio up to 9216 kbps, offline downloads, and ad-free playback define this tier. Demand clusters in Japan, Germany, and South Korea where audiophile subscribers pay 2-3x standard rates for spatial audio rendering.
- Ad-Supported:Compressed streams at 128-256 kbps with interstitial advertising fund free access. Volume concentrates in India, Brazil, and Indonesia where price-sensitive users accept audio commercials for zero direct cost.
- Freemium:Hybrid access with skip-limited mobile playback and unlimited desktop streaming. This tier bridges conversion funnels between free and paid experiences.
- Student Plans:Discounted verification-based subscriptions tied to academic email domains. Campus networks in North America and Western Europe drive seasonal enrollment spikes.
Volume placements concentrate in Ad-Supported; the faster expansion belongs to Premium.
Content Type:
Cost structures diverge sharply between licensed third-party catalogs and owned intellectual property.
- Licensed Tracks:Major label agreements command 70% of platform revenue share in mechanical royalties. Renewal negotiations with Universal, Sony, and Warner determine margin sustainability.
- Podcasts:Spoken-word content attracts 40-60% higher advertiser CPMs than music inventory. True crime and sports wagering formats extend daily listening hours in English-speaking markets.
- Original Content:Platform-commissioned exclusives reduce per-stream royalty burdens. Production costs amortize across global subscriber bases.
- User-Generated:Independent artist uploads and remix culture expand catalog depth. Content moderation costs scale with upload volume.
Revenue concentrates in Licensed Tracks; podcast investments are climbing the fastest.
Device Type:
Mobile-first consumption patterns dominate emerging economies while multi-device households characterize mature markets.
- Smartphones:Sub-$200 Android devices in India, Indonesia, and Nigeria account for 75% of new subscriber additions. Mobile data plans under $2 monthly unlock mass-market access.
- Smart Speakers:Voice-activated playback in kitchen and living room environments drives background listening. Amazon Echo and Google Nest ecosystems capture household-level subscription sharing.
- Desktop PCs:Workplace and home office streaming sustains higher average session durations. Lossless tier adoption runs 2x higher on wired broadband connections.
- Tablets:Video-centric music consumption and lyric display features differentiate this form factor. Family plan multi-user scenarios favor tablet secondary devices.
Subscriber additions concentrate in Smartphones; smart speaker integration shows the steepest expansion trajectory.
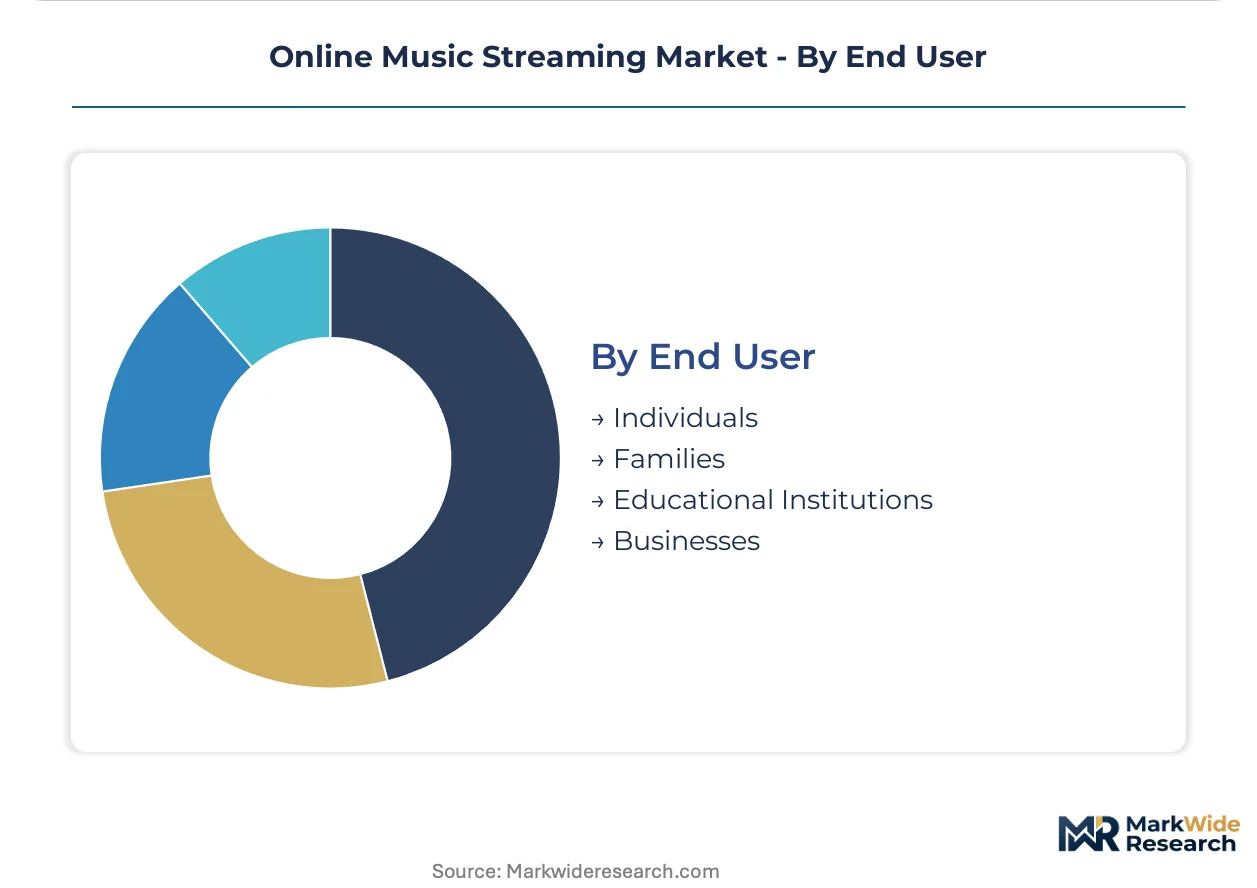
End User:
Account structures range from single-user individual plans to multi-profile household bundles and B2B licensing arrangements.
- Individuals:Single-profile subscriptions with personalized recommendation engines. Churn rates run highest in this segment due to price sensitivity and competitive switching.
- Families:Up to six-profile bundles with parental controls and explicit content filters. Shared payment methods reduce per-user acquisition costs for platforms.
- Businesses:Commercial licensing for retail, hospitality, and workplace background music. Performing rights organization fees add 30-50% premium over consumer tiers.
- Educational Institutions:Campus-wide access agreements with bulk pricing and curriculum integration. Library science and musicology departments drive specialized database subscriptions.
Revenue per account concentrates in Families; commercial licensing is gaining share fastest among B2B verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangalore anchors streaming platform engineering operations across emerging markets, while São Paulo and Lagos drive subscriber acquisition through localized content strategies and mobile-first distribution partnerships.
United States
Los Angeles-based major label headquarters and Nashville's music publishing corridors concentrate licensing negotiations that determine platform cost structures. The US Copyright Royalty Board's five-year rate proceedings create statutory uncertainty for mechanical royalty obligations. Seattle and San Francisco technology clusters host algorithmic recommendation development and cloud infrastructure scaling.
India
Mumbai's Bollywood production ecosystem and Chennai's independent music scenes generate regional language content that drives 3-4 hour daily streaming sessions among 18-34 year-olds. TRAI's affordable data pricing mandates enable sub-$2 monthly mobile plans that unlock mass-market access. Bangalore's technology parks host platform localization engineering for Hindi, Tamil, Telugu, and Punjabi catalog expansion.
Brazil
São Paulo's funk carioca and sertanejo music production clusters supply localized content that converts ad-supported users to premium tiers. ANVISA's digital platform transparency frameworks intersect with consumer protection oversight on subscription billing practices. Rio de Janeiro's creative industries drive podcast investments in Portuguese-language sports wagering and true crime formats.
Germany
Berlin's electronic music production studios and Hamburg's audio engineering facilities anchor lossless audio adoption at 2-3x standard tier pricing. The EU Digital Services Act's algorithmic audit requirements impose documentation burdens on recommendation engine architectures. Munich's automotive OEM headquarters negotiate embedded streaming pre-installation contracts for native dashboard integration.
Indonesia
Jakarta's dangdut and pop music production houses feed localized content pipelines for smartphone-first subscribers on sub-$200 Android devices. The Ministry of Communication and Informatics enforces content moderation standards that shape platform moderation cost structures. Bandung's creative technology sector experiments with AI-generated voice licensing for synthetic artist vocal production.
Online Music Streaming Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the streaming value chain, with major label catalog owners wielding negotiating leverage over platform operators. The market structures around three tiers: global scale platforms with algorithmic density, hardware-integrated services with ecosystem lock-in, and regional specialists with localized content depth. Strategic moves concentrate on exclusive content acquisition and automotive OEM pre-installation contracting.
Within the global scale tier, Spotify and Apple Music exemplify divergent archetypes—one algorithm-driven and cross-platform, the other hardware-anchored with lossless audio integration. Tencent Music occupies a position representing regional platform consolidation, leveraging social entertainment features and karaoke functionality that diverge from Western subscription models. These three entities collectively illustrate how competitive positioning fragments across personalization technology, proprietary device ecosystems, and market-specific feature adaptation.
| Leading Market Players |
|---|
| Spotify |
| Apple Music |
| Amazon Music |
| YouTube Music |
| Tencent Music |
| NetEase |
| Deezer |
| Tidal |
| Yandex Music |
| Others |
Cost & Logistics Intelligence
Mechanical royalty rate indices set by the US Copyright Royalty Board cascade through platform cost structures into three distinct subscriber tiers, compressing margins for ad-supported offerings while sustaining premium pricing power in audiophile segments.
Pricing Analysis
Per-stream royalty obligations anchor value-based pricing across subscription tiers, with lossless audio quality and offline download privileges commanding 2-3x multiples over standard compressed streams. Price differentiation rests on bandwidth allocation and exclusive catalog access rather than pure audio fidelity alone. Cost compression in ad-supported tiers is intensifying because major label renewal negotiations concentrate negotiating leverage among three global rights holders. Price sensitivity clusters in India, Brazil, and Indonesia where sub-$2 monthly data plans set consumer willingness-to-pay ceilings; Japan, Germany, and South Korea exhibit the lowest sensitivity with spatial audio premiums.
Supply Chain Analysis
Direct-to-OEM automotive channels handle embedded dashboard integration demand, while carrier-billing partnerships manage smartphone-first subscriber acquisition in emerging markets. Content licensing concentrates in the United States, Sweden, and China where platform headquarters and major label negotiations anchor rights acquisition. Raw material dependencies span server infrastructure, CDN bandwidth, and proprietary spatial audio codec licensing from Dolby, Sony, and Apple. Supply chain risk centers on single-source vulnerability for exclusive catalog rights that concentrate among Universal, Sony, and Warner. Distribution runs through app store ecosystems and automotive pre-installation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where exclusive content production and algorithmic recommendation technology represent the critical upstream levers separating margin-sustainable platforms from commodity intermediaries.
For Market Incumbents: Deepen original content commissioning to reduce per-stream royalty burdens while consolidating recommendation algorithm audit capabilities ahead of EU Digital Services Act enforcement. Defend against emerging regional specialists in Nigeria and Indonesia by accelerating localized artist aggregation. Prioritize automotive OEM pre-installation contracts to secure captive listener bases before dashboard integration standardizes. For New Entrants and Emerging Players: Launch via carrier-billing partnerships in underpenetrated African markets where smartphone penetration exceeds 60% yet paid subscription adoption remains minimal. Target Nigeria, Kenya, and South Africa with local artist aggregation strategies that bypass major label concentration. Exploit white-space in AI-generated voice licensing frameworks before rights-clearance protocols formalize. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap platforms with regional content depth and algorithmic personalization density in Southeast Asia. Long-term viability hinges on exclusive catalog control and automotive integration contracts rather than pure subscriber scale. Monitor US Copyright Royalty Board proceedings as the inflection signal for platform cost structure resets.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Content Acquisition | Platform-commissioned originals reduce mechanical royalty exposure to major label concentration. |
| Automotive OEM Pre-installation | Native dashboard integration secures captive listener bases ahead of Bluetooth displacement. |
| Algorithmic Transparency Investment | EU Digital Services Act compliance unlocks standardized expansion across 27 member states. |
| Regional Language Catalog Expansion | Hindi, Tamil, and Punjabi content drives 3-4 hour daily sessions in India's mobile-first market. |
| Podcast Format Diversification | Spoken-word inventory attracts 40-60% advertiser CPM premiums over music streaming rates. |
Research Approach
Document review covered SEC filings from streaming platforms, major label financial disclosures, and regulatory proceedings from the US Copyright Royalty Board, complemented by interviews with platform licensing executives, major label royalty administration directors, and automotive OEM infotainment procurement leads. Secondary validation drew from TRAI data pricing reports, EU Digital Services Act implementation guidance, and smartphone penetration statistics from national telecommunications regulators. Bottom-up subscriber modeling and top-down market sizing triangulated volume and value estimates.
Cross-referencing historical growth patterns against panel input from industry stakeholders anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include subscription tier, content type, device category, and end-user structure alongside regional regulatory cluster variations. CAGRs were derived from trend extrapolation adjusted for smartphone penetration curves and data pricing trajectories. Forecast inputs incorporated mechanical royalty rate proceedings and exclusive licensing deal renewal cycles.
Regulatory rate resets, exclusive catalog renewal failures, and automotive integration contract losses are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions around subscriber conversion funnels and content cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Media and Entertainment
Latin America OTT Platform Market
Media and Entertainment
Subscription Video on Demand (Svod) Market
Media and Entertainment
Adaptive Content Publishing Market
Media and Entertainment
Global E-Book Market
Media and Entertainment
Africa Animation Market
Media and Entertainment
Independent Music Publishing Market
Media and Entertainment
Smart Advertising Market
Media and Entertainment
US Webtoons Market
Media and Entertainment
Content Creation Market
Media and Entertainment
India Gaming Market
Media and Entertainment
Photographic Services Market
Media and Entertainment
Pro AV Market
Media and Entertainment
Global Programmatic Advertisement Market
Media and Entertainment
Japan Webtoons Market
Media and Entertainment
North America Gaming Market
Media and Entertainment
Global Blogging Platforms Market