
 Norway Used Car Market | 2026-2036
Norway Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Used Car Market Insights
The capital-intensity divergence between digital-first platforms and legacy dealer networks is collapsing as both models require comparable technology investments. Bilia leverages its established showroom footprint to sustain physical-digital hybrid operations across southern Norway. Bertel O. Steen anchors its competitive position through certified pre-owned programs tied to manufacturer service standards. MøllerGruppen competes by extending its new-car customer relationships into structured trade-in and resale cycles.
Used cars in Norway comprise previously registered passenger vehicles traded through secondary ownership channels, typically evaluated by odometer reading, service history documentation, and residual battery state-of-health for electric units. These assets serve consumers priced out of new-vehicle markets and commercial operators managing total cost of ownership. Electric drivetrain vehicles command structural premiums due to battery certification requirements and constrained original supply. SUV body styles lead transaction volumes as family buyers prioritize cabin flexibility and all-wheel capability for Nordic road conditions. Online platforms represent the fastest-growing sales channel, displacing traditional auction formats as consumers demand price transparency and remote vehicle history access.
Norwegian regulators enforce strict roadworthiness inspections through the Norwegian Public Roads Administration, while the Norwegian Consumer Authority mandates disclosure standards for digital vehicle listings. Battery health reporting requirements for pre-owned electric vehicles shape inspection protocols and pricing methodologies. Stakeholders must monitor how forthcoming EU battery passport regulations integrate with national type-approval frameworks for cross-border used-vehicle flows.
Market Dynamics
Norway's zero-emission vehicle mandate is compressing new-car supply and redirecting commercial demand toward certified pre-owned electric vehicles, particularly in Oslo and Bergen where fleet electrification deadlines are tightest.
Growth Catalysts
- Oslo municipal fleet procurement:Urban operators face binding electrification targets that outstrip new EV availability, forcing systematic sourcing from secondary channels with verified battery health documentation.
- EU battery passport regulations:Cross-border traceability requirements for battery state-of-health are standardizing inspection protocols and reducing information asymmetry in electric vehicle transactions.
- Charging infrastructure density:Greater Oslo's network coverage eliminates range anxiety barriers that previously suppressed used EV demand in secondary ownership cycles.
Market Restraints
- Battery replacement cost volatility:Lithium-ion cell pricing fluctuations create residual value uncertainty that complicates financing structures for pre-owned electric units.
- Original supply concentration:Norway's new vehicle market depends on limited OEM allocation of right-hand-drive electric models, constraining downstream used inventory formation.
- Roadworthiness inspection stringency:Norwegian Public Roads Administration protocols for electric drivetrain certification add processing time and compliance overhead to dealer operations.
Strategic Opportunities
- Trøndelag regional expansion:Secondary cities including Trondheim show charging infrastructure catch-up and underdeveloped dealer network coverage relative to Oslo-Akershus corridor.
- Battery health certification services:Independent diagnostic platforms can capture margin from OEM-agnostic verification demand as trade-in volumes rise.
- Subscription-to-ownership conversion:Fleet operators with short-cycle electric leases create structured off-lease channels for retail remarketing with complete maintenance records.
Industry Challenges
- Technician certification gaps:High-voltage battery diagnostics and repair require specialized training that outpaces vocational program output in Norwegian technical colleges.
- Legacy auction format displacement:Physical wholesale channels struggle to integrate real-time battery health data feeds that digital platforms now deliver as standard.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Used Car Market |
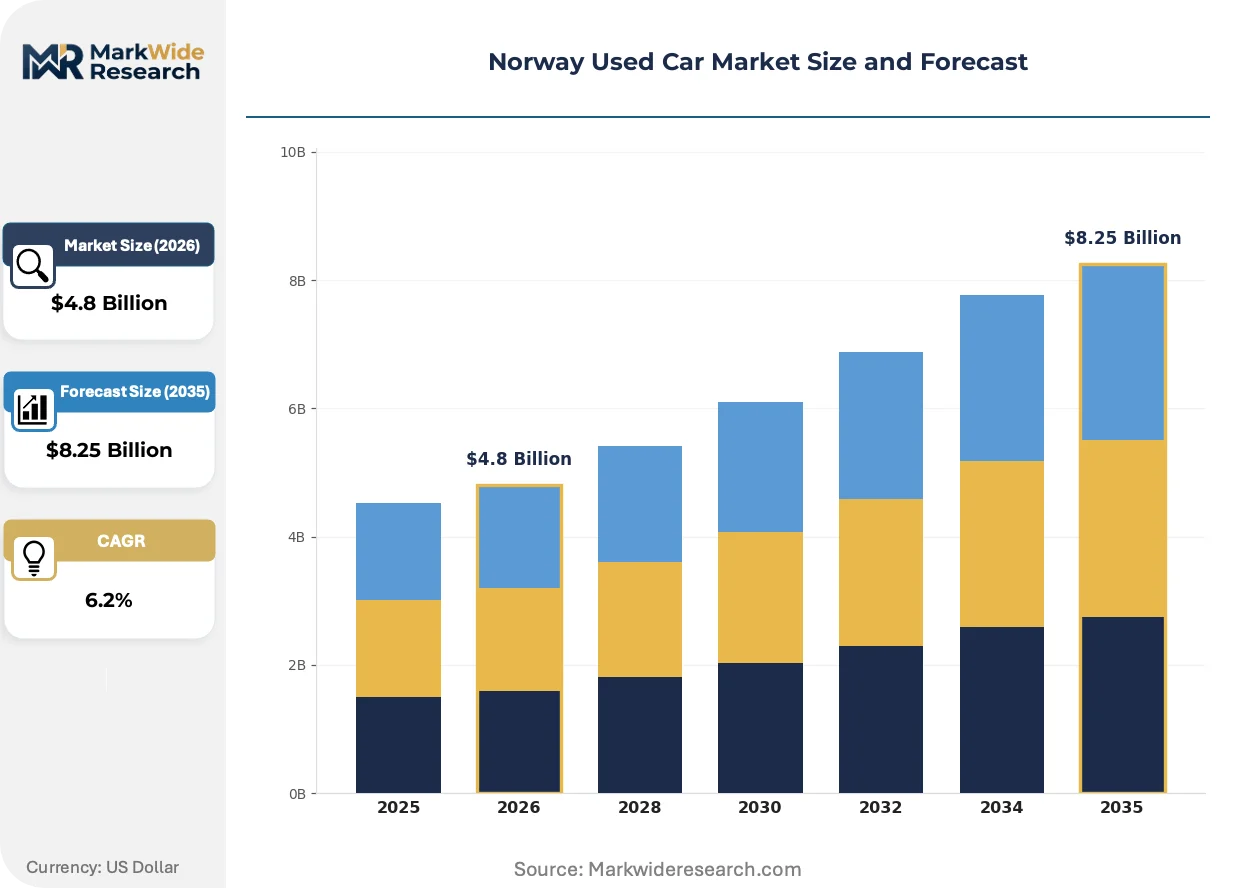
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedans, SUVs, Hatchbacks, Station Wagons Fuel Type: Petrol, Diesel, Electric, Hybrid Age Group: Newer Models, Mid-Age Vehicles, Older Models, Classic Cars Sales Channel: Dealerships, Private Sellers, Auctions, Online Platforms |
| Companies Covered | TrueCar, Inc., Trucar Inc., Bilia, Bertel O. Steen, MøllerGruppen, RSA BIL, Lee Auto Malls, Auksjonen.no, Birger N. Haug, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Used Car Market Trends and Innovations
Digital vehicle history platforms are compressing transaction friction and enabling remote price discovery, while regulatory pressure on battery traceability reshapes inspection standards across the value chain.
Blockchain-based provenance verification is supplanting paper service records as the trust anchor in secondary electric vehicle transactions. Fleet buyers in Bergen now mandate cryptographically signed maintenance logs before procurement authorization. This shift is compressing due diligence timelines from weeks to hours and marginalizing dealers unable to integrate API-connected history feeds.
The Norwegian Consumer Authority's disclosure mandate for battery state-of-health in digital listings is forcing inspection infrastructure investment. Dealer networks must now deploy standardized diagnostic hardware or forfeit platform visibility. Electric drivetrain vehicles face the steepest compliance burden, with Greater Oslo listings rejected for incomplete health certification.
Fleet procurement departments are consolidating vendor relationships around full-lifecycle service providers. Single-source contracts covering acquisition, maintenance, and remarketing are displacing fragmented spot-market purchasing. This concentration is most visible among municipal operators in Oslo-Akershus, where total cost of ownership frameworks dominate evaluation criteria.
Norway Used Car Market Segmentation
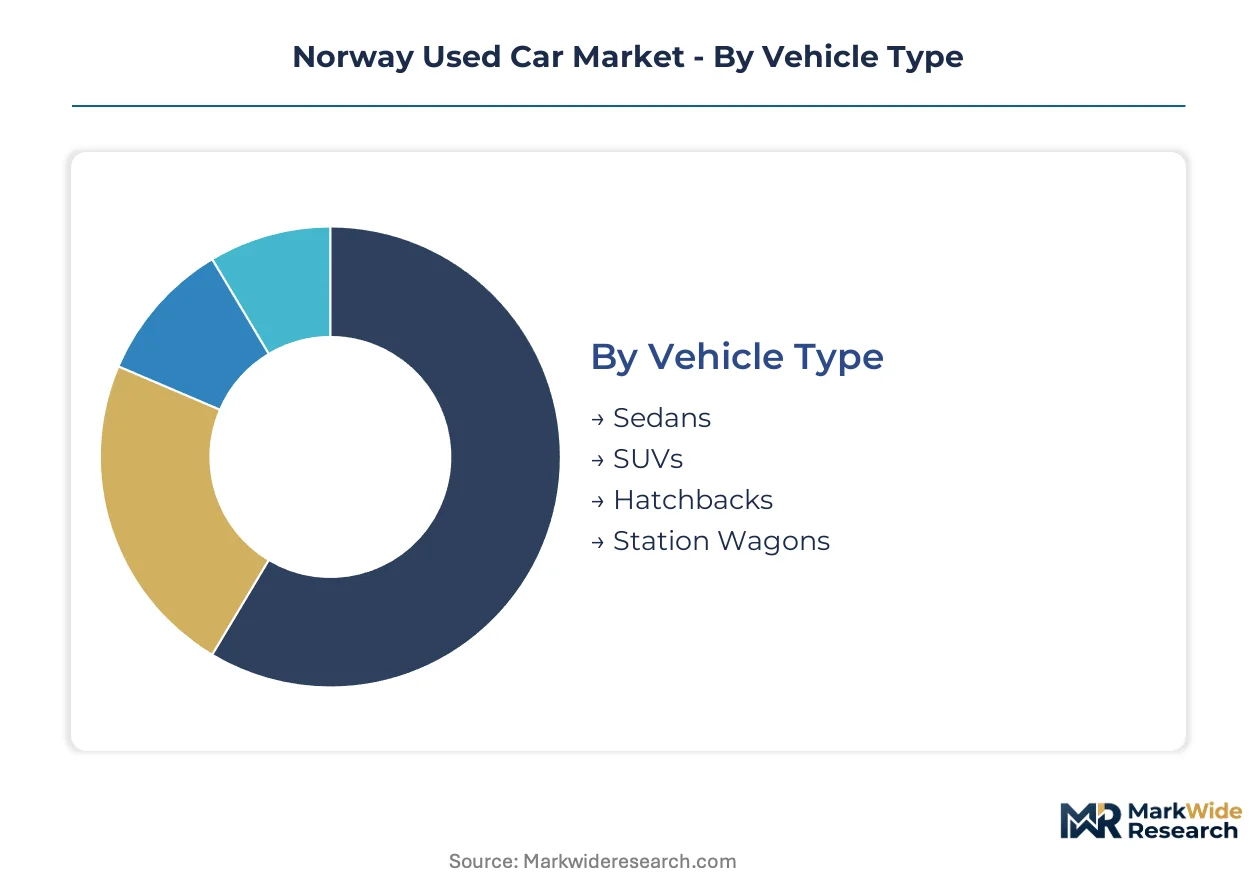
Norway's used car market segments reflect structural pressures from electrification mandates and digital channel migration. Understanding substitution dynamics across vehicle categories reveals where incumbent formats face displacement from emerging alternatives.
Vehicle Type:
Substitution pressure runs strongest against body styles poorly suited to electric drivetrain packaging and Nordic climate demands.
- Sedans:Three-box passenger vehicles with dedicated trunk compartments. Demand concentrates among corporate fleet operators in Oslo-Akershus seeking cost-efficient electrification pathways, constrained by declining new-model availability as OEMs prioritize SUV platforms.
- SUVs:High-riding body styles with all-wheel capability and expanded cabin volume. Family buyers across Greater Oslo drive transaction volumes, prioritizing ground clearance and cargo flexibility for winter road conditions and recreational access.
- Hatchbacks:Compact two-box designs with integrated cargo areas. Urban single-vehicle households in Bergen favor maneuverability and parking efficiency.
- Station Wagons:Extended roofline variants combining sedan platforms with expanded load capacity. Rural municipalities maintain procurement interest for service fleet applications.
SUVs anchor the volume base while electric-adapted hatchbacks gain share at the steepest rate.
Fuel Type:
Cost tier stratification separates powertrains by total ownership economics and regulatory treatment intensity.
- Electric:Battery-electric vehicles with zero tailpipe emissions. Municipal fleet operators in Oslo face binding procurement deadlines that outstrip new-vehicle allocation, forcing systematic secondary market sourcing with mandatory battery health documentation.
- Hybrid:Dual-powertrain systems combining combustion engines with electric assist. Bergen commercial operators value transitional technology during charging infrastructure buildout phases.
- Petrol:Conventional spark-ignition internal combustion engines. Price-sensitive private buyers in secondary cities maintain demand where charging density remains limited.
- Diesel:Compression-ignition engines with higher thermal efficiency. Declining residual values reflect municipal access restrictions and taxation disadvantages in urban zones.
Electric powertrains command structural premiums while hybrid configurations show the most volatile demand patterns across regulatory transition periods.
Age Group:
Application intensity varies sharply between depreciation-curve positioning and collector-market scarcity value.
- Newer Models:Vehicles under three years from initial registration. Fleet remarketing channels in Trøndelag supply complete maintenance records and manufacturer warranty transfers.
- Mid-Age Vehicles:Three-to-seven-year-old units exiting initial ownership cycles. Oslo dealer networks concentrate refurbishment capacity and certified pre-owned programs here.
- Older Models:Eight-to-fifteen-year vehicles entering tertiary ownership. Price transparency platforms reduce information asymmetry for budget-constrained rural buyers.
- Classic Cars:Vehicles exceeding twenty-five years with historical or collector significance. Niche specialist dealers in southern Norway manage provenance verification and restoration sourcing.
Mid-age vehicles generate the transaction volume foundation while newer models show the tightest supply-demand imbalance.
Sales Channel:
Customer type fragmentation separates institutional procurement from individual consumer behavior patterns.
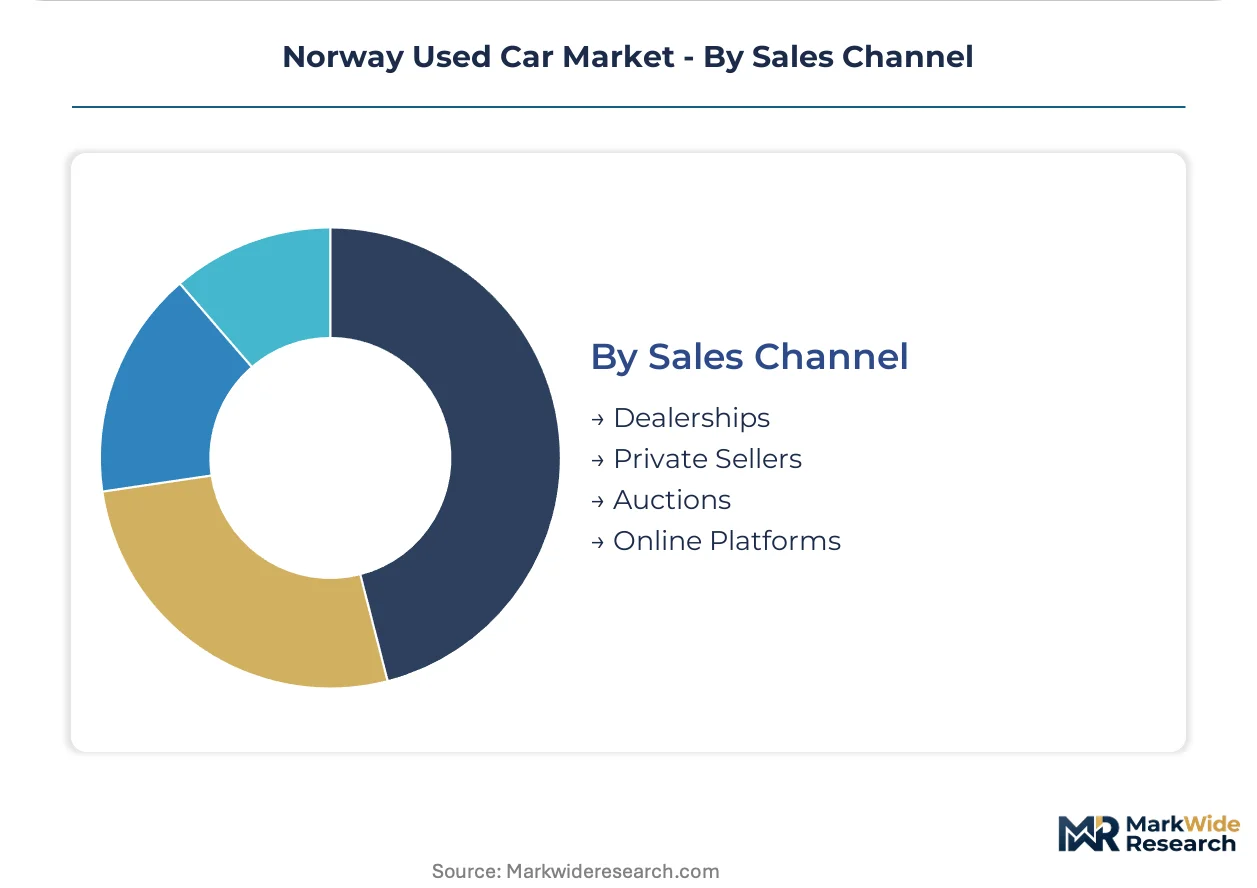
- Online Platforms:Digital marketplaces with remote vehicle history access and price benchmarking tools. Greater Oslo consumers demand real-time battery health data feeds unavailable through physical channels.
- Dealerships:Branded retail networks with certified pre-owned programs and financing integration. MøllerGruppen and Bertel O. Steen anchor southern Norway coverage with manufacturer service standard compliance.
- Private Sellers:Direct owner-to-buyer transactions without intermediary markup. Norwegian Consumer Authority disclosure mandates now require standardized battery state-of-health reporting for electric listings.
- Auctions:Wholesale trading venues for dealer inventory acquisition. Physical formats struggle to integrate diagnostic data streams that digital platforms deliver as standard.
Dealerships retain the volume anchor position while online platforms expand most quickly across all consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price premiums in Greater Oslo exceed those in Trøndelag by substantial margins, reflecting charging infrastructure density and municipal fleet procurement intensity. This asymmetry redirects trade flows and inventory positioning across Norway's secondary automotive channels.
Oslo-Akershus
Municipal fleet operators face binding electrification deadlines that outstrip new-vehicle allocation. The Norwegian Public Roads Administration enforces strict roadworthiness protocols for electric drivetrain certification. Urban dealers concentrate refurbishment capacity and certified pre-owned programs in this corridor.
Bergen
Commercial operators value hybrid configurations during charging infrastructure buildout phases. Norwegian Consumer Authority disclosure mandates require standardized battery state-of-health reporting for all electric listings. Port-city logistics clusters facilitate cross-border inventory flows from continental Europe.
Trøndelag
Fleet remarketing channels supply complete maintenance records and manufacturer warranty transfers for newer models. National type-approval frameworks govern cross-border used-vehicle documentation requirements. Trondheim's charging infrastructure catch-up creates underdeveloped dealer network coverage relative to southern corridors.
Stavanger-Rogaland
Energy sector employment sustains demand for mid-age premium SUVs with all-wheel capability. Municipal access restrictions and taxation disadvantages suppress residual values for diesel configurations. Suburban dealer networks compete with digital platforms for price-transparent transactions.
Troms og Finnmark
Rural municipalities maintain procurement interest for station wagon body styles in service fleet applications. Range anxiety barriers previously suppressed used EV demand where charging density remains limited. Specialist dealers manage provenance verification for classic vehicle restoration sourcing.
Norway Used Car Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Norway's used car channels. Established dealer networks with manufacturer service standard compliance occupy premium-tier positioning, while digital-first platforms capture volume through price transparency and remote vehicle history access. Two strategic archetypes dominate: physical-digital hybrid operators leveraging showroom footprints, and API-connected marketplace specialists compressing transaction friction. Competitive moves concentrate on certified pre-owned program expansion and battery health certification infrastructure deployment.
Among Norway-based dealer groups, Bilia, Bertel O. Steen, and MøllerGruppen exemplify the physical-digital hybrid archetype. Bilia occupies a position anchored in southern Norway showroom coverage. Bertel O. Steen represents manufacturer-tied service standard compliance. MøllerGruppen sits within structured trade-in and resale cycle extension. These entities compete with digital platforms including TrueCar and Trucar on remote price discovery and battery health data integration.
| Leading Market Players |
|---|
| TrueCar, Inc. |
| Trucar Inc. |
| Bilia |
| Bertel O. Steen |
| MøllerGruppen |
| RSA BIL |
| Lee Auto Malls |
| Auksjonen.no |
| Birger N. Haug |
| Others |
Pricing and Supply Chain Analysis
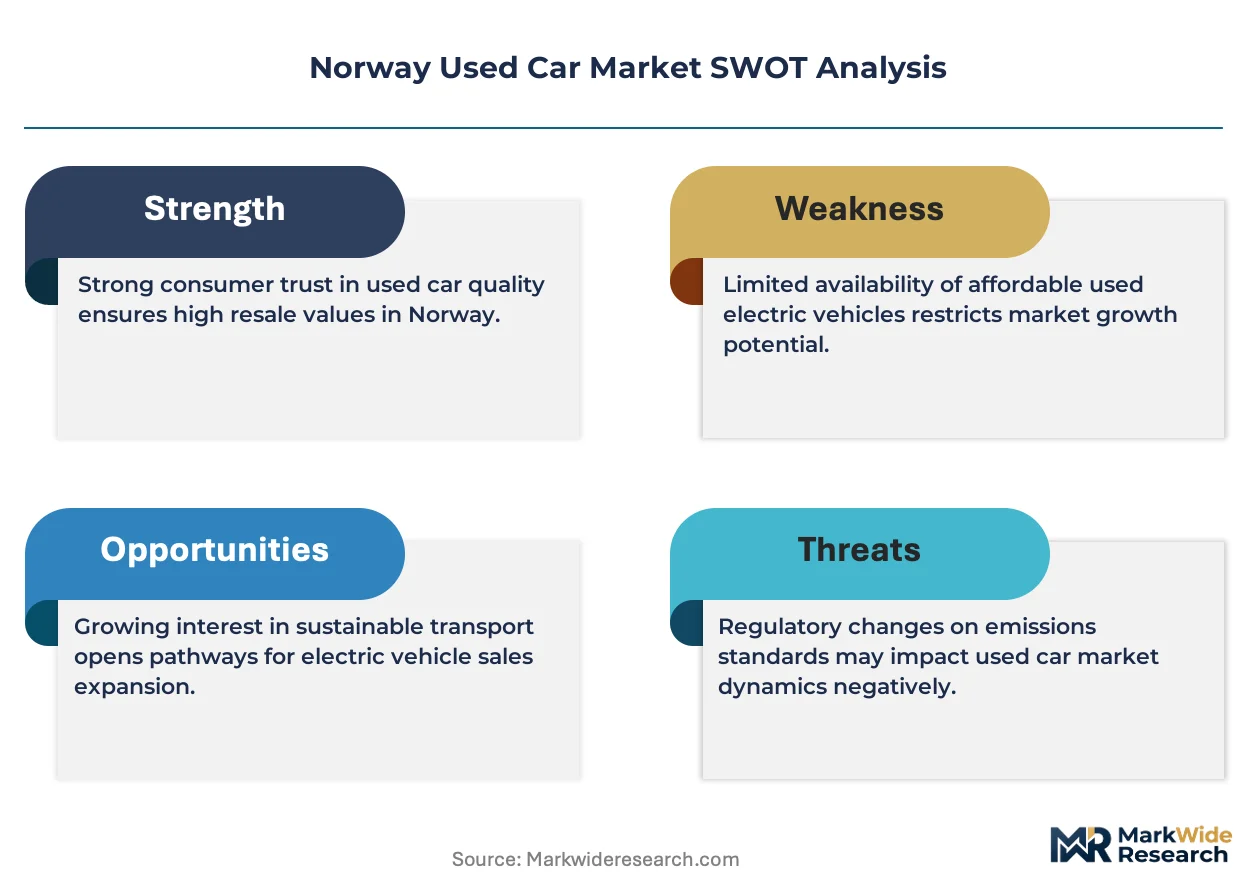
The Norwegian Public Roads Administration's electric drivetrain certification protocol gates both dealer qualification and price differentiation simultaneously. Battery health documentation standards separate certified pre-owned inventory from unverified secondary market units, compressing margin structures for non-compliant operators while elevating premiums for verified assets.
Pricing Analysis
The customization-premium spread between configured-to-order certified pre-owned programs and standard auction-sourced inventory defines transaction economics. Three-tier pricing structure across certified pre-owned, dealer-refurbished, and private-sale economy levels stratifies by battery state-of-health certification and warranty transferability. Cost compression in economy-tier petrol vehicles is intensifying because diesel residual value collapse redirects budget buyers toward undifferentiated combustion inventory. Municipal fleet procurement departments show least price sensitivity due to total cost of ownership frameworks, while rural private buyers exhibit highest sensitivity to upfront acquisition costs.
Supply Chain Analysis
Inventory-strategy preferences favor just-in-time sourcing from fleet remarketing channels over strategic stockpiling given battery degradation risk and model-year obsolescence. Supply concentrates in Germany, Sweden, and the Netherlands as primary sources for right-hand-drive electric vehicle allocation feeding Norwegian secondary channels. Raw material dependencies span lithium-ion cell supply, diagnostic hardware components, and high-voltage technician training capacity. Single-source vulnerability in OEM-certified battery diagnostic tooling creates procurement bottlenecks for independent dealers. Distribution runs through physical-digital hybrid networks anchored in Greater Oslo, with digital platforms capturing incremental volume through API-connected inventory feeds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norway's used car market operates as a substitution defense against digital platform disintermediation of traditional dealer economics. Incumbents must navigate remote price discovery tools that commoditize physical showroom advantages.
For Market Incumbents: Compound certified pre-owned program density in Greater Oslo-Akershus corridor to anchor manufacturer-tied service relationships against pure-play digital entrants. Deepen backward integration into battery health certification infrastructure, deploying standardized diagnostic hardware before Norwegian Consumer Authority disclosure mandates harden compliance barriers. Channel control through exclusive fleet remarketing contracts protects volume access as subscription-to-ownership conversion accelerates.
For New Entrants and Emerging Players: Battery health verification as a service-layer gap offers white-space penetration where legacy dealer networks under-invest in independent diagnostic platforms. Trøndelag regional expansion presents the most penetrable geography given charging infrastructure catch-up and underdeveloped incumbent coverage relative to southern corridors. API-first marketplace architecture with real-time Norwegian Public Roads Administration inspection data integration provides the decisive go-to-market angle against physical-format auction displacement.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across battery health certification infrastructure as regulatory disclosure mandates harden compliance thresholds. Long-term viability over the next decade favors acquisition targets combining physical showroom footprint with digital platform integration capabilities. The signal to watch as inflection indicator is consolidation velocity among mid-size dealer groups unable to sustain parallel technology and certification infrastructure investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Health Certification Infrastructure | Norwegian Consumer Authority disclosure mandates force standardized diagnostic hardware deployment across dealer networks. |
| Fleet Remarketing Channel Control | Exclusive municipal procurement contracts in Oslo-Akershus secure structured off-lease inventory with complete maintenance records. |
| Physical-Digital Hybrid Platform Integration | Showroom footprint leverage sustains customer acquisition against pure-play digital price transparency competitors. |
| Trøndelag Regional Network Expansion | Charging infrastructure catch-up in secondary cities creates first-mover advantage before incumbent dealer saturation. |
| Technician Training Program Investment | High-voltage battery diagnostics capability scarcity in Norwegian technical colleges creates captive service capacity moats. |
Research Methodology
A spread of perspectives from fleet procurement managers, dealer operations directors, digital platform engineers, and Norwegian Public Roads Administration certification officers converged on the working assumptions shaping this analysis. Primary interview data combined with secondary validation from vehicle registration databases, charging infrastructure deployment records, and Norwegian Consumer Authority enforcement disclosures. Bottom-up transaction volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled span vehicle type, fuel architecture, age cohort, and sales channel, with additional granularity on battery state-of-health certification tiers unique to electric drivetrain transactions. CAGRs were derived through regression analysis of historical transaction flows and projected electrification mandate compliance requirements. Forecast inputs incorporated municipal fleet procurement deadlines, EU battery passport regulatory integration timelines, and charging infrastructure density trajectories.
Underlying assumptions cover stable lithium-ion cell pricing, consistent Norwegian Public Roads Administration inspection protocol enforcement, and gradual EU regulatory harmonization, with deviation risk concentrated in battery replacement cost volatility and OEM right-hand-drive allocation shifts. Revision becomes warranted when cross-border used vehicle flow documentation requirements cross implementation thresholds that reshape inventory sourcing economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Singapore Used Car Market
Used Vehicles
France Used Car Market
Used Vehicles
Russia Used Car Market
Used Vehicles
Malaysia Used Car Market
Used Vehicles
South Africa Used Car Market
Used Vehicles
North America Used Truck Market
Used Vehicles
Used Semi Truck Market
Used Vehicles
Kenya Used Car Market
Used Vehicles
Indonesia Used Car Market
Used Vehicles
Thailand Used Car Market
Used Vehicles
Europe Used Car Market
Used Vehicles
Australia Used Car Market
Used Vehicles
China Used Car Market
Used Vehicles
South Korea Used Car Market
Used Vehicles
Used E-Scooter Market
Used Vehicles
Indonesia Used Car Financing Market