
 North America Used Truck Market | 2026-2036
North America Used Truck Market Size, Share, and Industry Trends Forecast 2026-2036
North America Used Truck Market Analytics
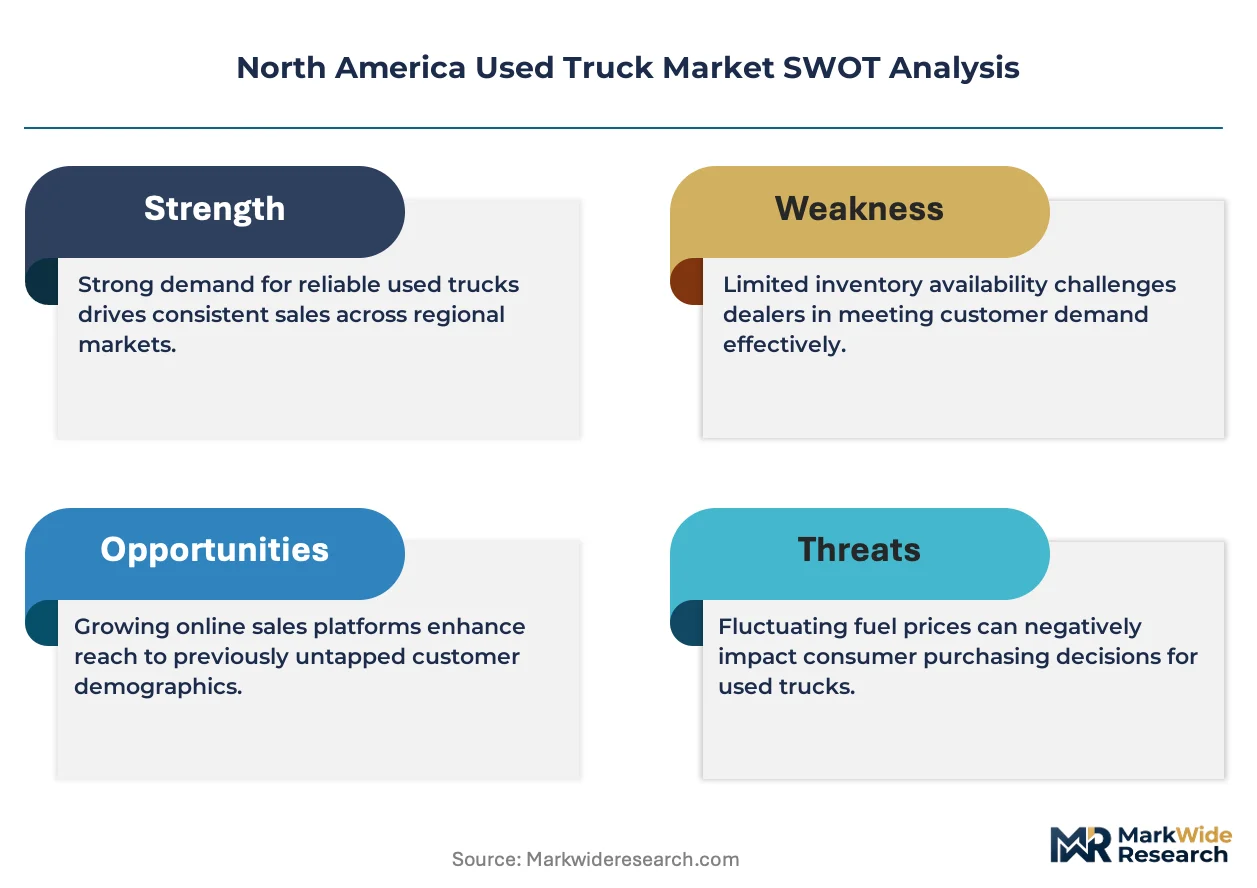
Lease-to-own and third-party fleet financing is rewriting competitive access across the North America Used Truck Market, enabling mid-size carriers to acquire late-model Class 8 units without traditional balance-sheet leverage. Paccar Inc leverages its captive finance arm to move high-mileage Kenworth and Peterbilt trade-ins through certified remarketing channels. Ryder System, Inc. anchors its position through full-service lease returns that feed a controlled pipeline of uniformly maintained medium-duty inventory. Volvo Trucks differentiates by extending powertrain warranties on used VNL tractors, reducing residual risk for second owners.
A used truck denotes a previously registered commercial vehicle with a gross vehicle weight rating exceeding 10,000 pounds, typically retaining diesel or gasoline internal combustion architectures with odometer readings between 100,000 and 700,000 miles, acquired for freight hauling, construction, or utility fleet applications after initial depreciation. Heavy Duty units dominate transaction volume owing to sustained replacement demand from long-haul operators seeking proven engine durability without new-equipment premiums. Electric fuel type represents the fastest-growing structural category as early-adopter fleet operators cycle initial battery-electric prototypes into secondary markets ahead of wider zero-emission mandates.
EPA emission certification tiers and CARB heavy-duty vehicle rules shape engine eligibility for interstate registration, while NHTSA safety recall compliance determines remarketability of specific model years. The Federal Motor Carrier Safety Administration's inspection protocols further filter salvage and non-certified units from premium resale channels. Stakeholders must monitor how state-level zero-emission vehicle sales mandates reshape residual values for diesel-dominant inventory in California-adjacent markets.
Market Dynamics
EPA Phase 3 greenhouse gas standards and CARB Advanced Clean Trucks rules are compressing resale eligibility for older diesel inventory while accelerating capital rotation toward certified pre-owned units with compliant engine profiles.
Growth Catalysts
- Last-mile fleet expansion:E-commerce fulfillment operators in Texas and California are scaling medium-duty used truck acquisitions to control per-mile operating costs without new-equipment depreciation exposure.
- EPA emission tier compliance:Interstate carriers facing Phase 3 certification deadlines are sourcing 2019-2023 model year used tractors to meet greenhouse gas thresholds without full replacement capex.
- Battery-electric remarketing:Early-adopter fleets in California are cycling initial BEV prototypes into secondary channels, creating certified pre-owned zero-emission inventory ahead of 2035 CARB mandates.
Market Restraints
- Diesel engine residual compression:CARB heavy-duty vehicle rules and state-level ZEV sales mandates are eroding resale premiums for pre-2020 diesel units in California-adjacent markets.
- Parts supply concentration:Specialized aftertreatment component availability for EPA-certified engines concentrates with limited Tier 1 suppliers, creating maintenance cost volatility for second owners.
- Inspection protocol friction:FMCSA safety recall compliance requirements filter non-certified units from premium remarketing channels, compressing eligible inventory pools.
Strategic Opportunities
- Texas-Oklahoma corridor density:Oilfield services and interstate freight operators in this cluster maintain accelerated replacement cycles, creating consistent late-model supply for remarketers.
- Lease-to-own channel innovation:Captive finance arms and third-party fleet lessors are structuring used truck acquisitions with embedded maintenance, expanding mid-size carrier access without balance-sheet leverage.
- Powertrain warranty extension:Extended coverage on used heavy-duty tractors reduces residual risk for second owners, differentiating certified programs from auction-grade transactions.
Industry Challenges
- Technician certification gaps:BEV and hybrid powertrain maintenance requires specialized training that remains scarce in independent service networks across the US Midwest and Mountain states.
- Recall compliance tracking:NHTSA safety recall resolution status must be verified pre-transaction, adding administrative burden to wholesale and retail remarketing workflows.
- Residual value forecasting:Zero-emission mandate timelines vary by state, complicating depreciation modeling for diesel-dominant inventory in California versus Texas markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Used Truck Market |
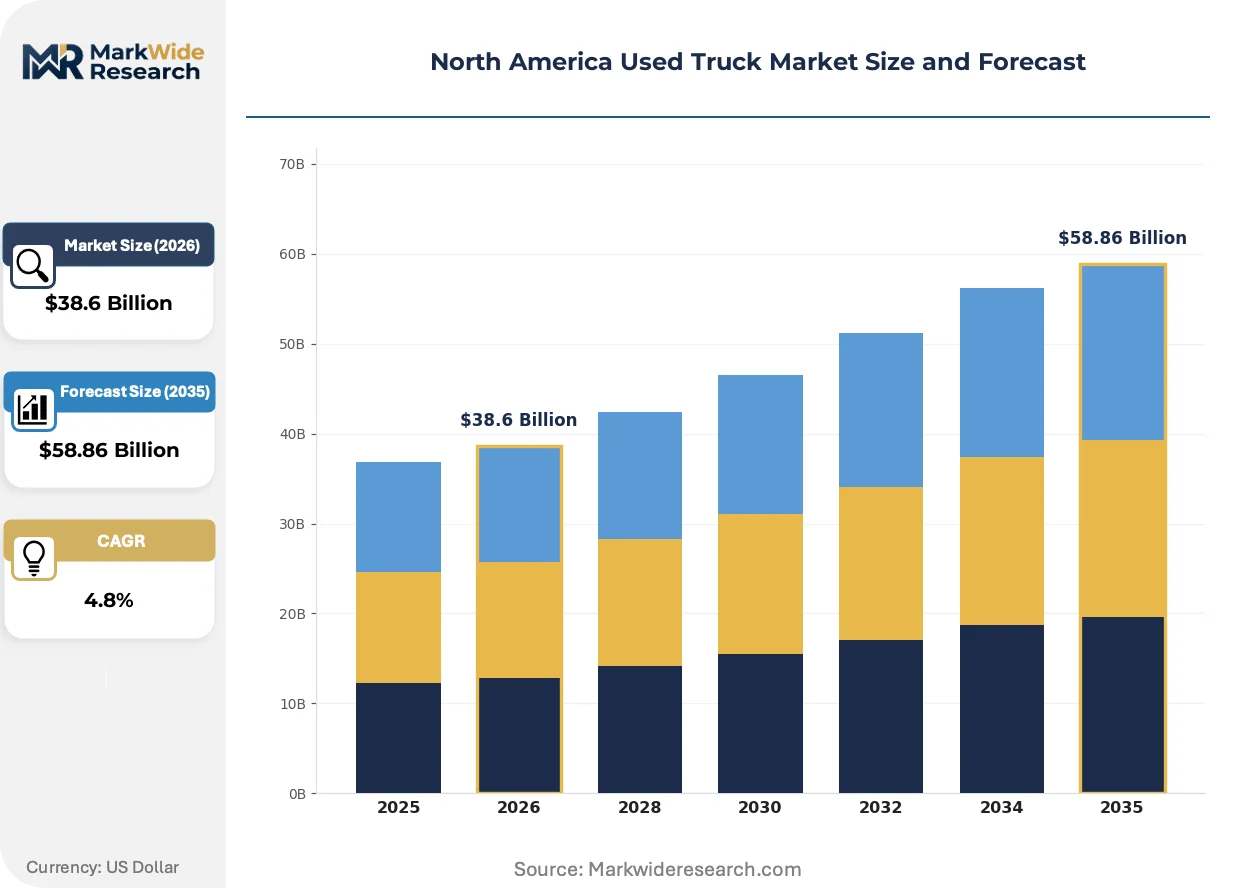
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Truck Type: Light Duty, Medium Duty, Heavy Duty, Super Heavy Duty Fuel Type: Diesel, Gasoline, Electric, Hybrid Sales Channel: Dealerships, Online Auctions, Private Sales, Remarketing Companies Condition: Certified Pre-Owned, Non-Certified, Salvage, Refurbished |
| Companies Covered | Navistar International Corporation, Gordon Truck Centers, Inc, Paccar Inc, General Motors Company, Ford Motor Company, Volvo Trucks, Ryder System, Inc., MAN SE, Daimler AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Used Truck Market Evolving Landscape
Telematics-enabled condition monitoring and powertrain electrification are restructuring how used trucks are certified, priced, and financed across North American remarketing channels.
Prognostic maintenance algorithms are collapsing traditional inspection-based valuation methods. These systems analyze engine stress data, duty-cycle severity, and component wear patterns to generate residual-life scores. Fleet remarketers in the US Southeast are adopting this technology to standardize trade-in valuations. The practice is compressing price dispersion between similarly aged units with divergent maintenance histories.
CARB Advanced Clean Trucks regulation and EPA Phase 3 standards are tightening engine eligibility for interstate registration. Fleets operating across California-state lines must now verify compliance with both federal and state certification tiers before acquisition. Heavy-duty tractor buyers in the Texas-California freight corridor are prioritizing 2021+ model years to ensure dual-jurisdiction operability.
Lease-return aggregation is displacing auction-centric procurement for mid-size carriers. Full-service lessors in the US Midwest are channeling uniformly maintained medium-duty inventory directly to second owners through certified remarketing programs. This pattern concentrates in last-mile logistics verticals where predictable maintenance records outweigh initial acquisition cost minimization.
North America Used Truck Market Segmentation
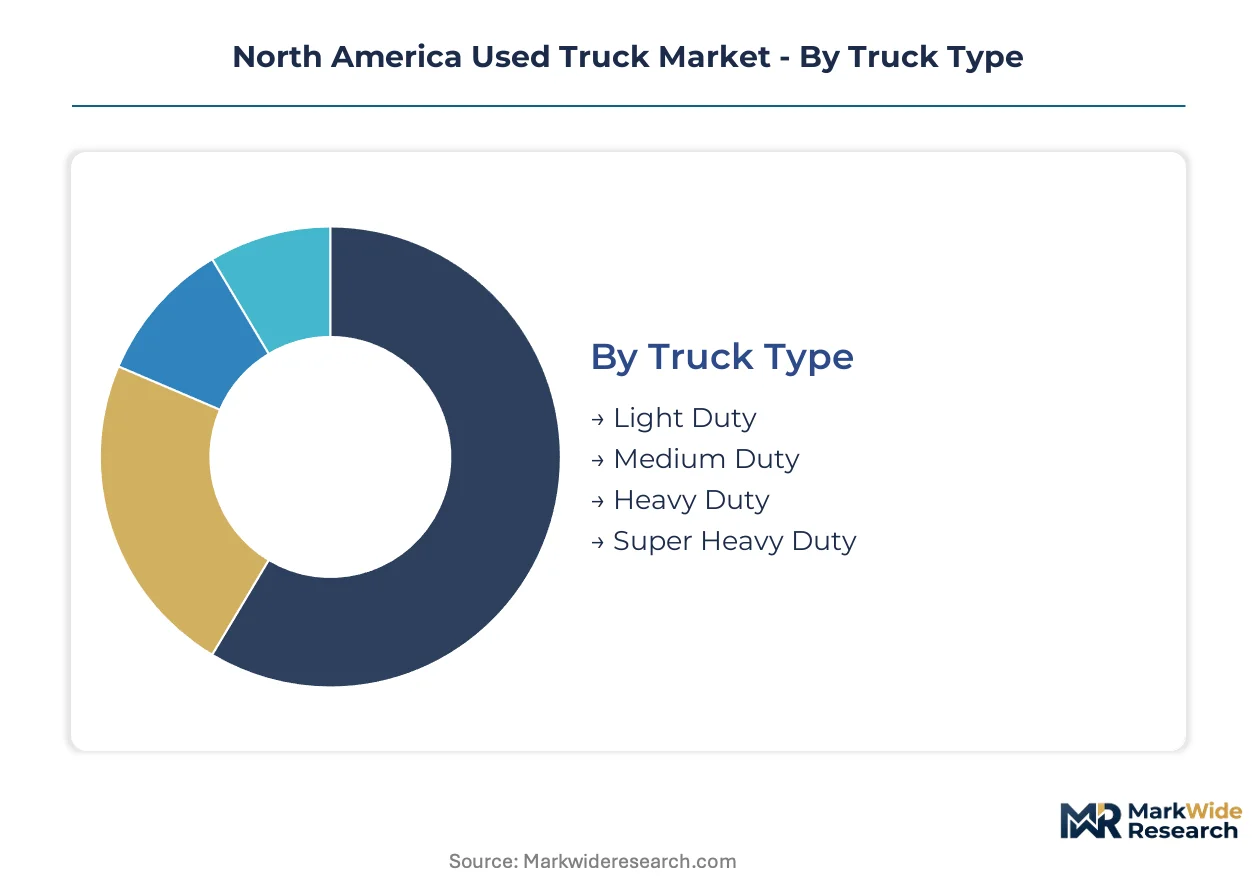
Segmentation in the North America Used Truck Market reflects how fleet operators balance acquisition cost against regulatory compliance and operational risk. Each dimension shapes procurement channels, financing terms, and residual value forecasting across interstate corridors.
Truck Type:
Mature categories dominate transaction volume while emerging segments capture regulatory tailwinds.
- Heavy Duty:Class 8 tractors with diesel powertrains and odometer readings between 400,000 and 700,000 miles form the core resale pool. Long-haul operators along the Texas-California corridor source these units to meet EPA Phase 3 greenhouse gas thresholds without new-equipment capital outlays.
- Medium Duty:Class 4-7 vehicles serve last-mile logistics and urban freight applications with lower per-mile operating costs. E-commerce fulfillment operators in Texas and California are scaling acquisitions of these units to control depreciation exposure while expanding fleet capacity.
- Light Duty:Class 1-3 pickups and vans support contractor and utility fleet applications with gasoline-dominant powertrains.
- Super Heavy Duty:Specialized haulers exceeding 80,000 pounds GVWR serve oilfield services and heavy-haul freight in the Texas-Oklahoma corridor.
Heavy Duty handles the majority of throughput; Electric is the fastest mover on share among powertrain transitions affecting type demand.
Fuel Type:
Cost tier differentiation separates compliance-ready premiums from legacy discount segments.
- Diesel:Compression-ignition engines with EPA-certified aftertreatment systems retain dominant transaction share. Interstate carriers facing CARB Advanced Clean Trucks rules are filtering acquisitions toward 2019-2023 model year diesel units with proven emission tier compliance.
- Electric:Battery-electric powertrains are cycling into secondary markets as early-adopter fleets in California rotate initial prototypes. CARB zero-emission mandates are accelerating remarketing velocity ahead of 2035 deadlines.
- Gasoline:Spark-ignition engines concentrate in light-duty and medium-duty segments with lower upfront acquisition costs.
- Hybrid:Diesel-electric and gasoline-electric architectures remain limited in secondary supply but attract urban freight operators seeking fuel economy gains.
Diesel handles the majority of throughput; Electric is expanding most quickly on regulatory pressure.
Sales Channel:
Customer type preferences diverge between risk-tolerant auction buyers and certainty-seeking direct purchasers.
- Remarketing Companies:Captive finance arms and fleet lessors channel uniformly maintained inventory through certified programs with extended powertrain warranties. Mid-size carriers access late-model Class 8 units through these structures without traditional balance-sheet leverage.
- Dealerships:Authorized outlets provide inspection-verified inventory with recall compliance documentation and financing facilitation.
- Online Auctions:Digital platforms aggregate wholesale supply for price-sensitive buyers willing to absorb condition uncertainty.
- Private Sales:Direct transactions between fleet operators bypass intermediary margins but require independent verification of maintenance history and regulatory compliance.
Remarketing Companies handle the majority of throughput; Online Auctions are gaining share fastest on digital procurement adoption.
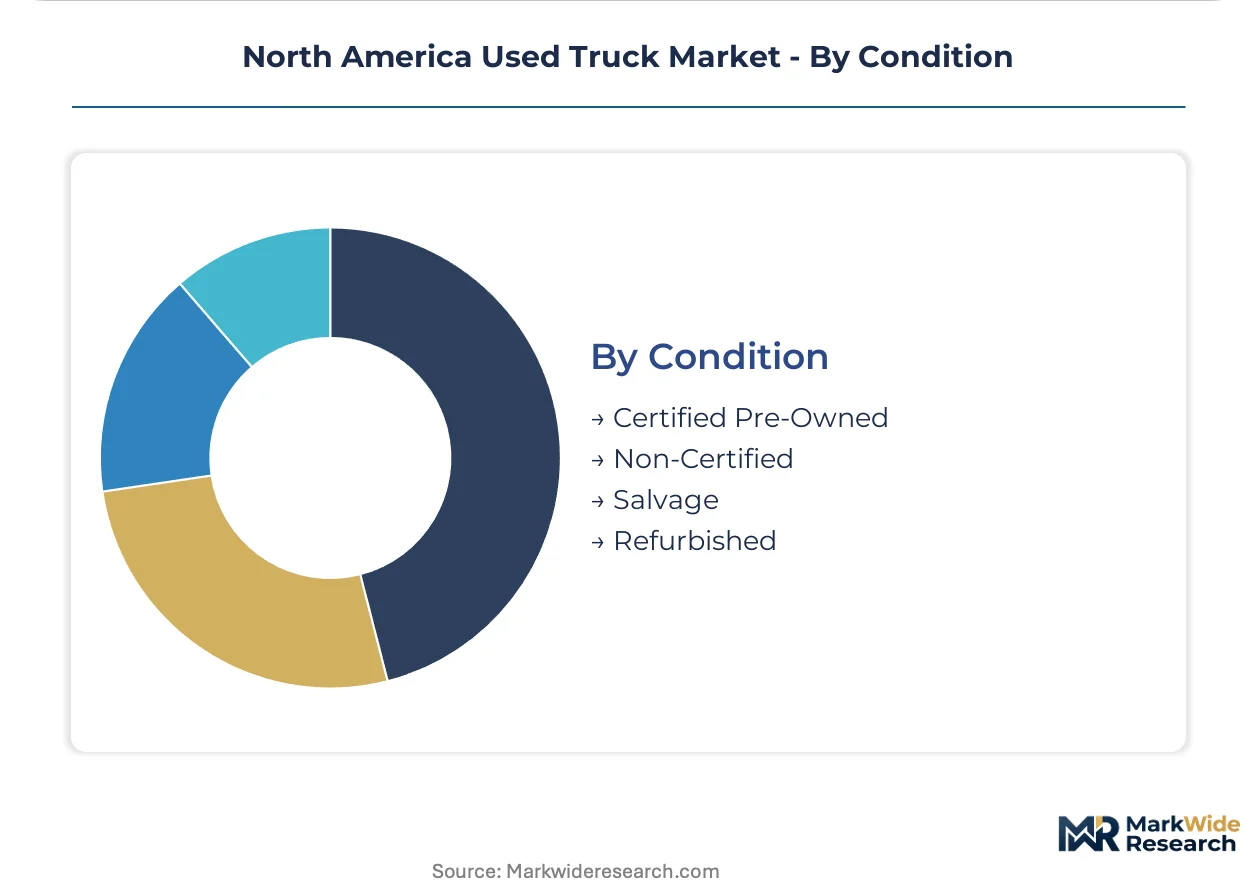
Condition:
Margin structure separates certified premiums from salvage recovery values.
- Certified Pre-Owned:Units passing multi-point inspections with verified maintenance records and extended warranty coverage command price premiums. Paccar and Volvo captive programs differentiate through powertrain guarantees that reduce residual risk for second owners.
- Non-Certified:As-is inventory without warranty coverage attracts cash buyers with in-house maintenance capabilities.
- Refurbished:Reconditioned units with component replacements and cosmetic restoration occupy a mid-tier price position.
- Salvage:Damaged or high-mileage units feed parts recovery and export markets with minimal resale eligibility for interstate operation.
Certified Pre-Owned handles the majority of premium throughput; Refurbished is climbing the fastest as remarketers invest in value-add reconditioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border freight flows between the United States, Canada, and Mexico create divergent supply dynamics for used truck remarketing, with export-oriented inventory gravitating toward border-adjacent corridors while domestic absorption centers on high-mileage agricultural and energy belts.
United States
Interstate carriers along the Texas-California freight corridor dominate procurement of late-model Class 8 tractors to satisfy EPA Phase 3 greenhouse gas thresholds without full fleet replacement. The FMCSA enforces safety recall compliance protocols that filter non-certified units from premium resale channels. Dallas-Fort Worth anchors the highest transaction velocity, where oilfield services operators maintain accelerated replacement cycles for heavy-haul equipment.
Canada
Alberta-based energy contractors source high-mileage Super Heavy Duty units from US auction channels to service oil sands logistics without exposure to new-equipment depreciation. Transport Canada aligns commercial vehicle safety regulations with NHTSA recall standards, streamlining cross-border remarketing eligibility. The Calgary-Edmonton corridor concentrates procurement activity for vocational trucks serving remote extraction sites.
Mexico
Mexican fleet operators in Nuevo León and Jalisco acquire medium-duty used trucks from US lease-return programs to expand last-mile capacity for manufacturing supply chains. The Secretariat of Economy maintains import age restrictions that favor 2015+ model year units with verifiable EPA emission tier certification. Monterrey industrial parks drive concentrated demand for uniformly maintained Class 4-7 inventory with documented maintenance histories.
North America Used Truck Market Competitive Landscape
On the supply side, the industry is consolidating around captive finance arms and full-service lessors that control certified remarketing pipelines, while independent auction platforms fragment the non-certified segment. Strategic archetypes include OEM-affiliated remarketers with extended warranty programs, fleet lessors monetizing lease-return inventory, and digital auction platforms aggregating wholesale supply. Dominant competitive moves encompass powertrain warranty extension to reduce residual risk and telematics-enabled condition certification to standardize valuations.
Within the OEM-affiliated tier, Paccar Inc and Volvo Trucks exemplify archetypes that leverage captive finance structures to channel high-mileage trade-ins through controlled remarketing programs. Ryder System, Inc. occupies a distinct position among full-service lessors, feeding uniformly maintained medium-duty inventory directly to second owners. These three entities anchor the premium certified-pre-owned segment through differentiated warranty and maintenance bundling.
| Leading Market Players |
|---|
| Navistar International Corporation |
| Gordon Truck Centers, Inc |
| Paccar Inc |
| General Motors Company |
| Ford Motor Company |
| Volvo Trucks |
| Ryder System, Inc. |
| MAN SE |
| Daimler AG |
| Others |
Value Network & Pricing Analysis
EPA Phase 3 emission certification chokepoints determine both tier spreads between certified and non-certified used trucks and the geographic shape of inventory flows across North American remarketing channels. Diesel engine aftertreatment component scarcity compresses margins on pre-2020 units while concentrating pricing power with remarketers controlling late-model certified pipelines.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the North America Used Truck Market. Pricing stratifies across certified pre-owned units with extended powertrain warranties, non-certified auction-grade inventory, and refurbished units with component replacements. Cost compression in the non-certified tier intensifies because CARB heavy-duty vehicle rules erode resale eligibility for pre-2020 diesel tractors in California-adjacent markets. Small fleet operators and independent owner-operators exhibit highest price sensitivity, while mid-size carriers with lease-to-own access absorb premium pricing for warranty-backed inventory.
Supply Chain Analysis
Export-control restrictions on heavy-duty diesel engine technology limit cross-border component flows from the United States into Mexican refurbishment facilities. Manufacturing concentration for EPA-certified aftertreatment systems rests on suppliers in the United States, Germany, and Japan. Raw material dependencies span platinum group metals for catalytic converters, high-grade steel for chassis components, and specialized electronics for telematics systems. Single-source vulnerability concentrates in Tier 1 aftertreatment suppliers, creating maintenance cost volatility for second owners. Distribution runs through captive finance remarketing channels, authorized dealerships, and digital auction platforms serving price-sensitive wholesale buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Used Truck Market is entering a cyclical recovery phase as fleet replacement cycles normalize following emission-regulation compression. EPA Phase 3 compliance deadlines and CARB Advanced Clean Trucks implementation create predictable demand waves for certified pre-owned inventory.
For Market Incumbents: Harden remarketing channel control by deepening captive finance integration and securing exclusive lease-return pipelines from major fleet lessors. Invest in telematics-enabled condition certification to standardize valuations and compress price dispersion. Battery-electric powertrain service capabilities represent a critical defensive lever as zero-emission mandates reshape residual value forecasting.
For New Entrants and Emerging Players: Pursue white-space opportunities in BEV and hybrid powertrain refurbishment, where technician certification gaps create supply scarcity across the US Midwest and Mountain states. Target medium-duty last-mile logistics verticals in Texas and California, where e-commerce fulfillment operators prioritize predictable maintenance records over acquisition cost minimization. Structure lease-to-own offerings with embedded maintenance to bypass balance-sheet constraints limiting mid-size carrier access.
For Investors and Strategic Acquirers: Fleet lessors with controlled remarketing pipelines and uniform maintenance documentation represent the most defensible acquisition archetype in this market. Long-term viability hinges on positioning for zero-emission transition trajectories that vary materially between California and Texas regulatory environments. Watch CARB zero-emission vehicle sales mandate acceleration as the primary inflection signal requiring portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Powertrain Warranty Extension | Volvo Trucks and Paccar differentiate certified programs by reducing residual risk for second owners. |
| Telematics-Enabled Condition Certification | Prognostic maintenance algorithms standardize trade-in valuations across the US Southeast remarketing corridor. |
| Lease-Return Aggregation | Ryder System channels uniformly maintained medium-duty inventory directly to second owners bypassing auction friction. |
| Battery-Electric Remarketing Infrastructure | Early-adopter fleets in California cycle initial BEV prototypes into secondary channels ahead of 2035 mandates. |
| Cross-Border Export Compliance | Mexican import age restrictions favor 2015+ model year units with verifiable EPA emission tier certification. |
Research Methodology
Operator-level perspectives from fleet procurement managers, captive finance executives, independent remarketing specialists, and aftermarket service directors anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against FMCSA inspection protocol documentation, EPA emission certification databases, and NHTSA safety recall records. Trade flow analysis drew from customs records and cross-border commercial vehicle registration data. Bottom-up transaction volume estimates triangulated with top-down fleet replacement cycle modeling.
Scenario-bracketing around EPA Phase 3 implementation timing and CARB mandate acceleration shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include truck type classification, fuel architecture, sales channel structure, and condition grade tier. CAGRs derived from historical replacement cycle patterns and regulatory compliance deadline clustering. Industry-specific forecast inputs encompassed oilfield services activity levels in the Texas-Oklahoma corridor and e-commerce fulfillment fleet expansion rates in California and Texas urban markets.
Macroeconomic conditions sit as an overlay; deviation in freight demand indices, diesel fuel price volatility, or interest rate trajectories would shift the trajectory of used truck residual values. Forecasts reflect assumptions about regulatory implementation timelines and fleet technology adoption curves. Material shifts in zero-emission mandate enforcement intensity or cross-border trade policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Vintage Car Market
Used Vehicles
Brazil Used Car Market
Used Vehicles
Middle East and Africa Used Car Market
Used Vehicles
Used E-Scooter Market
Used Vehicles
South Africa Used Car Market
Used Vehicles
Germany Used Car Market
Used Vehicles
North America Used Car Market
Used Vehicles
India Used Car Market
Used Vehicles
Netherlands Used Car Market
Used Vehicles
Malaysia Used Car Market
Used Vehicles
United States Used Car Market
Used Vehicles
Japan Used Car Market
Used Vehicles
Indonesia Used Car Market
Used Vehicles
Hong Kong Used Car Market
Used Vehicles
Norway Used Car Market
Used Vehicles
Portugal Used Car Market