
 North America Multi-Cloud Networking in Fintech Market | 2026-2036
North America Multi-Cloud Networking in Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
North America Multi-Cloud Networking in Fintech Market Analytics
Buyer concentration among payment processors and digital banks is recalibrating procurement priorities across the North America Multi-Cloud Networking in Fintech Market. Amazon Web Services leverages its extensive edge presence to dominate financial services infrastructure deployments. Microsoft Azure anchors enterprise relationships through deep integration with compliance tooling. Cisco Systems Inc. specializes in secure connectivity layers that bridge heterogeneous cloud environments.
Multi-cloud networking in fintech denotes the architectural practice of interconnecting two or more cloud service providers through software-defined networking, API orchestration, and policy-driven traffic management to deliver sub-50 millisecond latency for real-time payment clearing and settlement. Its primary purpose is eliminating single-cloud dependency while maintaining consistent security posture and regulatory audit trails across distributed financial workloads. Hybrid cloud deployments command the largest addressable base as institutions retain core banking systems on-premises while bursting customer-facing applications to public infrastructure. Network as a Service represents the fastest-expanding service category, driven by fintechs seeking consumption-based WAN alternatives to capital-intensive MPLS contracts.
The SEC, Canada's Office of the Superintendent of Financial Institutions, and Mexico's CNBV impose overlapping cybersecurity and data residency requirements that shape architecture decisions for cross-border fintech operations. FFIEC examination guidelines further tighten network segmentation mandates, pushing institutions toward solution types with embedded compliance management capabilities. Stakeholders must evaluate whether their current vendor portfolios can sustain audit readiness as regulatory jurisdictions continue refining cloud-specific financial rules.
Market Dynamics
Payment processors are forcing architectural consolidation across North American fintech infrastructure as transaction volumes strain single-cloud resilience models. The SEC's cybersecurity disclosure mandates now require demonstrable network governance documentation that spans heterogeneous environments.
Growth Catalysts
- SEC Cybersecurity Disclosure Rules:Public fintechs must file incident reports within four business days, compelling investment in unified multi-cloud observability platforms that maintain continuous audit trails across distributed environments.
- Real-Time Payment Networks:FedNow and RTP clearing systems demand sub-50 millisecond latency thresholds that single-cloud architectures cannot guarantee, driving redundant cloud interconnect deployments.
- California Bay Area Cluster:Digital-native financial services firms headquartered in San Francisco and Silicon Valley operate the continent's most complex multi-cloud topologies, creating concentrated demand for advanced network orchestration tooling.
Market Restraints
- Specialized Engineering Talent Scarcity:Cloud network architects with cross-platform Kubernetes and service mesh expertise command compensation premiums that inflate operational expenditures for mid-market fintechs.
- Cross-Border Data Friction:Canada's Office of the Superintendent of Financial Institutions imposes data residency requirements that complicate seamless workload portability between US and Canadian cloud regions.
- API Orchestration Complexity:Heterogeneous cloud provider control planes create integration overhead that extends deployment timelines and elevates technical debt accumulation rates.
Strategic Opportunities
- Mexico Fintech Expansion:CNBV licensing reforms are attracting neobank entrants that require compliant multi-cloud foundations, creating first-mover advantages for infrastructure vendors with local presence.
- Network-as-a-Service Convergence:Consumption-based WAN alternatives to MPLS contracts enable capital-light scaling for payment processors experiencing volume volatility.
- Zero Trust Architecture Mandates:FFIEC examination guidelines are accelerating demand for identity-centric segmentation that spans on-premises core banking and bursted public cloud workloads.
Industry Challenges
- Legacy Core Banking Integration:Mainframe-dependent institutions face protracted refactoring cycles when extending COBOL-based transaction processing into containerized multi-cloud environments.
- Cross-Cloud Compliance Certification:SOC 2 Type II and PCI-DSS attestation processes must be replicated across multiple cloud provider environments, multiplying audit costs and timeline risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Multi-Cloud Networking in Fintech Market |
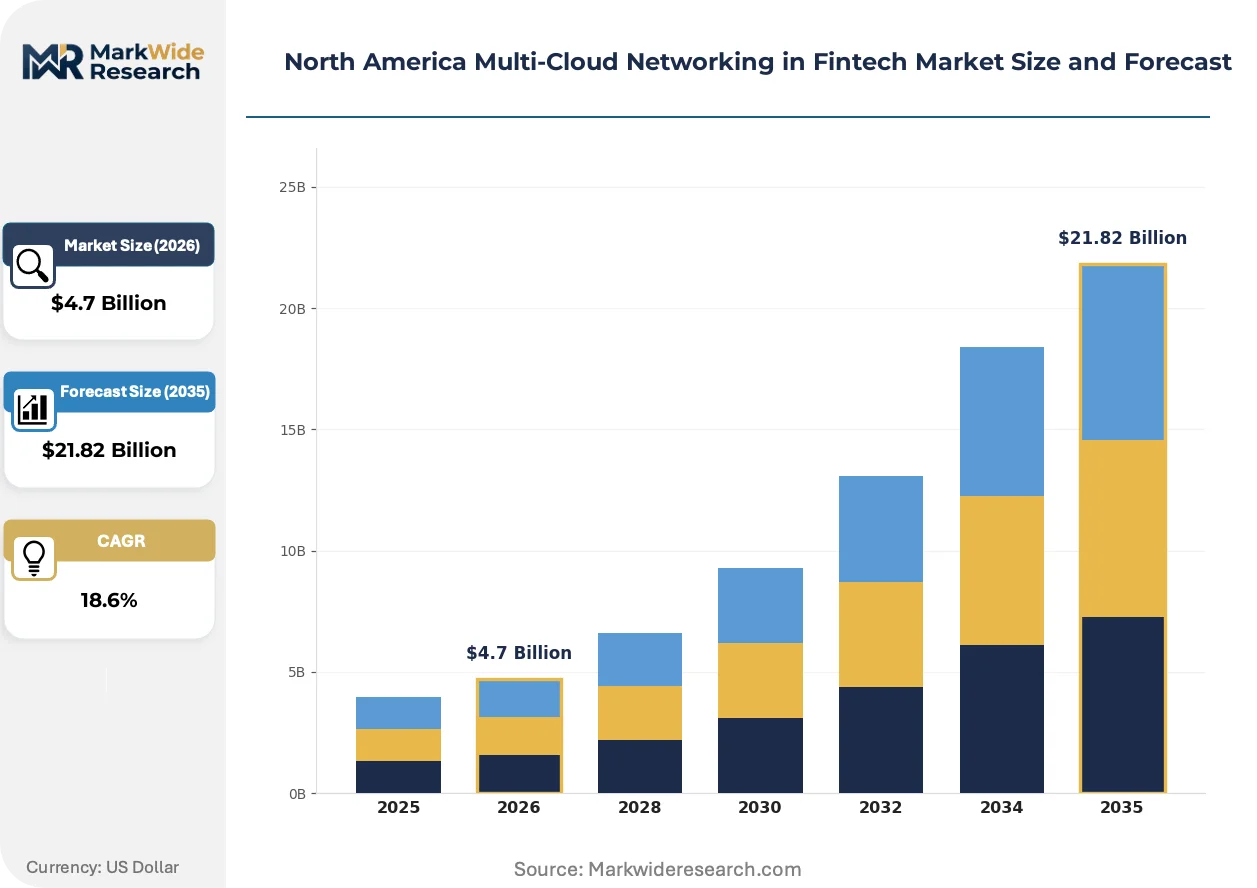
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Network as a Service End User Type: Commercial Banks, Investment Firms, Payment Processors, Insurance Companies Solution Type: Data Management, Security Solutions, Connectivity Services, Compliance Management |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, Oracle Corporation, Cisco Systems Inc., VMware Inc., IBM Cloud, Cloudflare Inc., Aviatrix, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Multi-Cloud Networking in Fintech Market Evolving Landscape
Service mesh architectures are absorbing operational complexity that previously required dedicated network engineering teams. This technological shift is compressing deployment timelines while elevating baseline security postures.
Service mesh technology is absorbing traffic management functions that previously demanded custom load balancer configurations and manual certificate rotation workflows. Mid-market digital banks are adopting Istio and Linkerd implementations at accelerated cadences to reduce operational toil. The technology is absorbing point-solution vendor roles in the connectivity stack, consolidating procurement decisions around platform-native offerings.
FFIEC examination guidelines now mandate explicit network segmentation documentation for institutions with over $10 billion in assets, tightening compliance windows. Examiners are requesting packet-level flow logs that demonstrate consistent policy enforcement across cloud boundaries. Large payment processors are responding by embedding compliance-as-code modules directly into infrastructure deployment pipelines.
Consumption-based procurement models are displacing capital-intensive MPLS commitments among transaction-heavy fintechs. Network-as-a-Service providers are capturing wallet share from traditional telecom carriers by offering elastic bandwidth scaling tied to settlement volume spikes. This behavioral shift is most pronounced among California-based payment processors managing seasonal demand fluctuations.
North America Multi-Cloud Networking in Fintech Market Segmentation
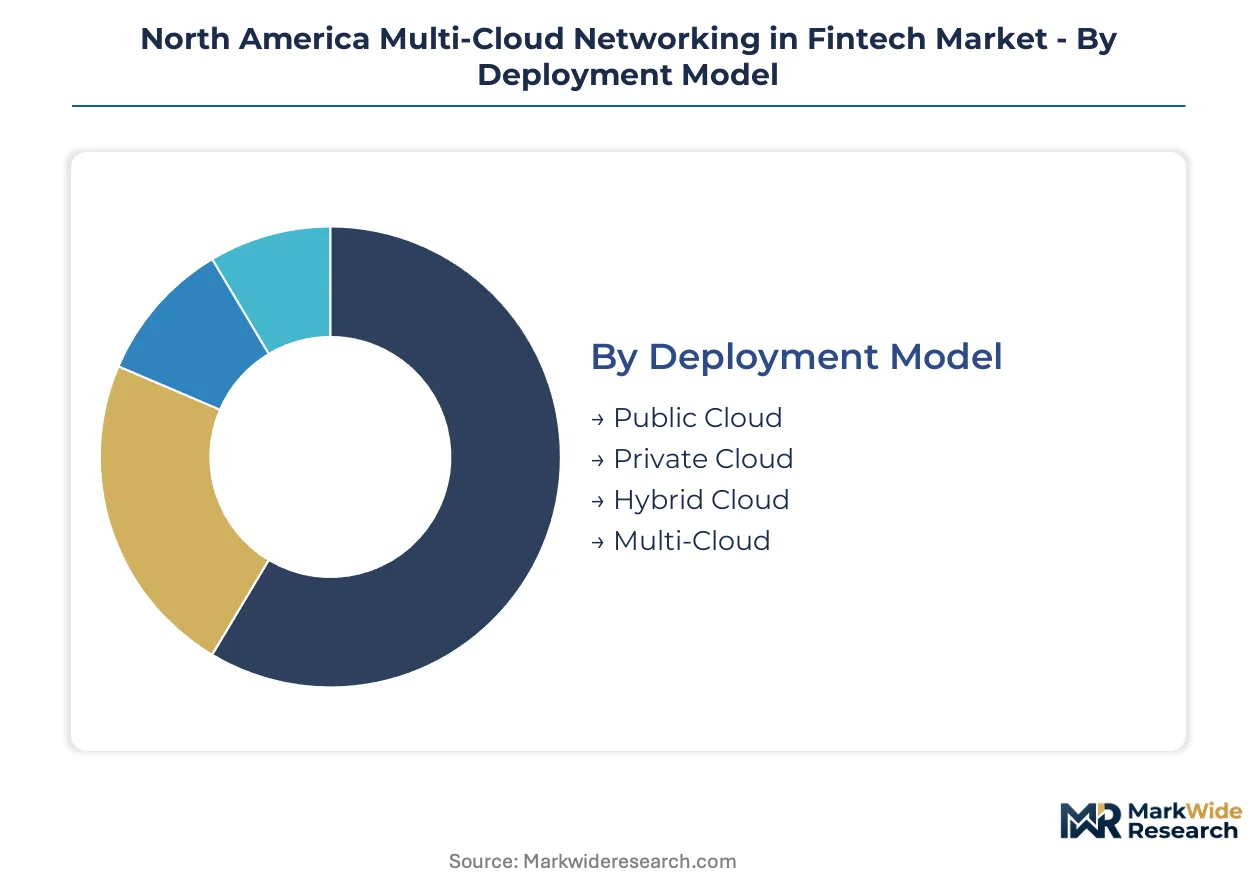
Deployment architecture, service consumption patterns, and regulatory exposure create distinct procurement profiles across North American fintech infrastructure buyers. Segmentation reveals how payment processors prioritize latency guarantees while commercial banks emphasize audit-ready compliance tooling.
Deployment Model:
Buyers differentiate by core system location versus burst capacity needs, with legacy institutions retaining on-premises infrastructure and digital natives pursuing cloud-native elasticity.
- Hybrid Cloud:Institutions maintain COBOL-based core banking systems in private data centers while bursting customer-facing applications to public infrastructure during settlement peaks. Commercial banks across the US Midwest dominate procurement, driven by FFIEC examination mandates requiring demonstrable segmentation between legacy and modern workloads.
- Multi-Cloud:Architectures distribute workloads across two or more hyperscale providers to eliminate single-vendor dependency and satisfy regional data residency requirements. California Bay Area digital banks and payment processors concentrate demand, compelled by FedNow latency thresholds that single-cloud deployments cannot guarantee.
- Public Cloud:Fully outsourced infrastructure serving neobanks and early-stage fintechs without legacy mainframe dependencies.
- Private Cloud:Dedicated environments for institutions with strict data sovereignty requirements under Canada's Office of the Superintendent of Financial Institutions guidelines.
Volume sits with Hybrid Cloud; growth tilts toward Multi-Cloud.
Service Type:
Procurement economics separate capital-constrained growth-stage fintechs from established institutions with multi-year telecom commitments.
- Network as a Service:Consumption-based WAN alternatives replace MPLS contracts with elastic bandwidth scaling tied to transaction volume spikes. Payment processors experiencing seasonal demand fluctuations in California and Texas lead adoption, drawn by opex flexibility and sub-50 millisecond latency SLAs.
- Platform as a Service:Managed Kubernetes and service mesh environments reduce operational toil for mid-market digital banks lacking specialized cloud network engineering talent. Demand concentrates among Bay Area neobanks scaling containerized payment applications.
- Infrastructure as a Service:Raw compute and storage provisioning for institutions with internal platform engineering capabilities.
- Software as a Service:Pre-built observability and compliance dashboards serving smaller investment firms with limited DevOps resources.
Revenue concentrates in Infrastructure as a Service; Network as a Service climbs the fastest.
End User Type:
Transaction velocity and regulatory scrutiny intensity shape divergent networking requirements across financial subsectors.
- Payment Processors:Entities handling real-time clearing demand redundant cloud interconnects with automated failover orchestration. FedNow and RTP network participation requirements drive deployment across the US Southeast and Southwest, where transaction volumes strain single-cloud resilience models.
- Commercial Banks:Deposit-taking institutions with over $10 billion in assets face FFIEC-mandated network segmentation documentation. Procurement prioritizes compliance-as-code modules embedded directly into infrastructure deployment pipelines.
- Investment Firms:Broker-dealers and asset managers requiring low-latency market data feeds across distributed trading infrastructure.
- Insurance Companies:Carriers with less stringent real-time requirements but complex policy administration system integrations.
Investment Firms hold established share; Payment Processors gain share fastest.
Solution Type:
Functional priorities reflect whether buyers confront audit readiness gaps or operational complexity in heterogeneous environments.
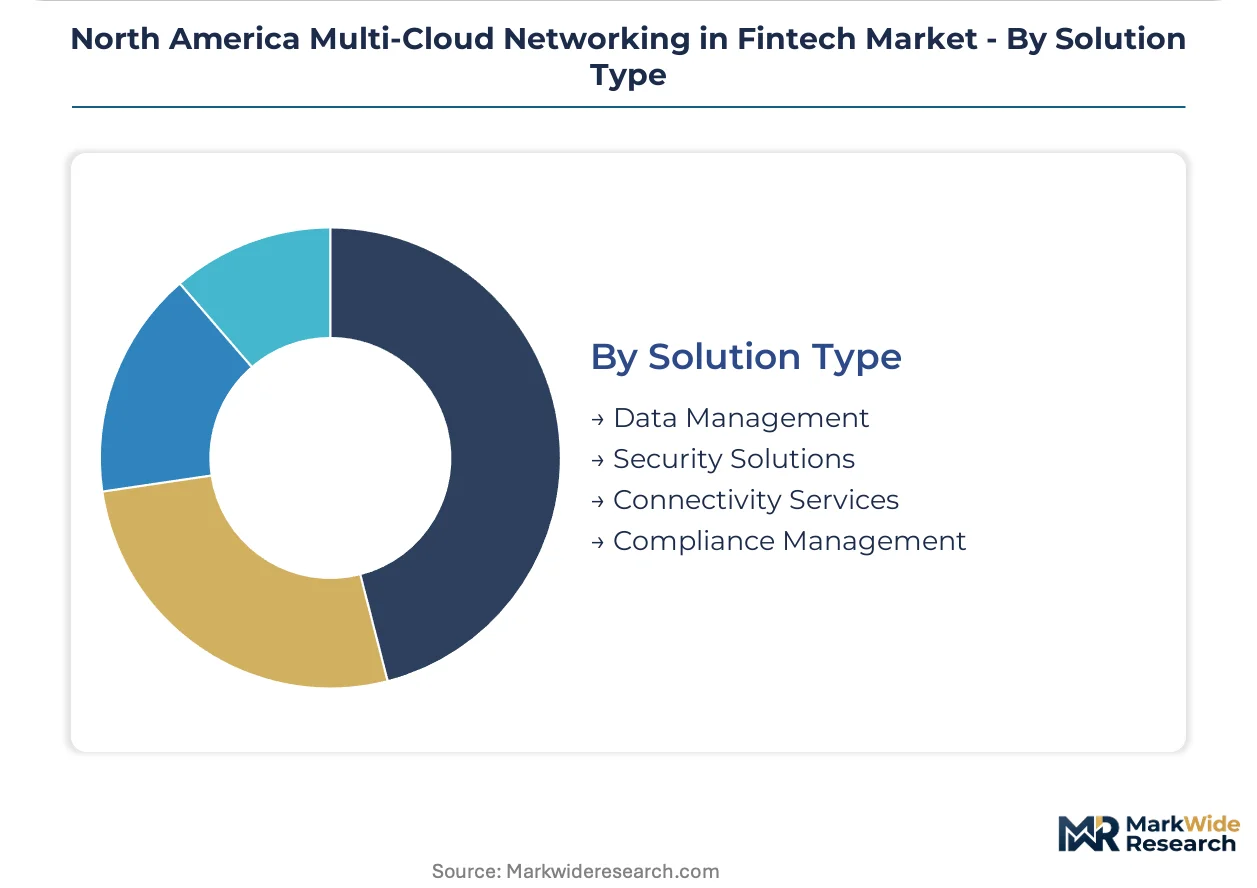
- Compliance Management:Embedded governance tooling automates SOC 2 Type II and PCI-DSS attestation processes across multiple cloud provider environments. Large US payment processors deploy these solutions to satisfy SEC cybersecurity disclosure rules requiring incident reporting within four business days.
- Connectivity Services:Secure transit layers bridging on-premises core banking with bursted public cloud workloads, featuring API orchestration and policy-driven traffic management. Demand surges among Canadian fintechs navigating cross-border data friction under OSFI residency requirements.
- Security Solutions:Zero trust segmentation and identity-centric access controls spanning distributed financial workloads.
- Data Management:Unified observability platforms maintaining continuous audit trails across multi-cloud transaction pipelines.
Connectivity Services anchor current procurement; Compliance Management shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payment processors and digital banks cluster disproportionately in three North American jurisdictions, each imposing distinct compliance architectures on multi-cloud infrastructure procurement.
United States
FedNow and RTP clearing networks drive redundant cloud interconnect deployments among payment processors seeking sub-50 millisecond latency guarantees. The SEC's four-day incident reporting mandate compels public fintechs to maintain continuous audit trails across distributed environments. California's Bay Area hosts the continent's densest concentration of digital-native financial services firms operating complex multi-cloud topologies.
Canada
OSFI data residency requirements complicate seamless workload portability between domestic and US cloud regions for cross-border fintech operations. The federal regulator's cybersecurity guidelines tighten network segmentation mandates for deposit-taking institutions with international footprints. Toronto's financial district anchors procurement demand among established banks modernizing legacy core banking infrastructure.
Mexico
CNBV licensing reforms attract neobank entrants requiring compliant multi-cloud foundations with local presence. The banking regulator's fintech authorization framework shapes architecture decisions for payment institutions serving underbanked populations. Mexico City Metro concentrates demand among digital payment startups scaling containerized transaction processing.
North America Multi-Cloud Networking in Fintech Market Competitive Landscape
US-based hyperscalers anchor one tier; specialized connectivity vendors hold differentiated positions in secure transit layers. The vendor base stratifies between full-stack cloud platforms and point-solution networking specialists. Three archetypes dominate: infrastructure incumbents with financial services compliance depth, cloud-native entrants with consumption-based pricing, and legacy networking vendors with hybrid integration expertise. Competitive moves center on embedded compliance-as-code modules and geographic edge expansion.
Within the infrastructure incumbent tier, Amazon Web Services and Microsoft Azure exemplify platform breadth that absorbs multi-cloud orchestration complexity. Cisco Systems Inc. occupies a distinct position bridging heterogeneous cloud environments through secure connectivity layers. These three anchors represent divergent strategic postures: hyperscale platform consolidation versus specialized transit expertise.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| Oracle Corporation |
| Cisco Systems Inc. |
| VMware Inc. |
| IBM Cloud |
| Cloudflare Inc. |
| Aviatrix |
| Others |
Value Network & Pricing Analysis
Cloud network architects with Kubernetes and service mesh expertise concentrated in California's Bay Area command compensation premiums that inflate operational expenditures for mid-market fintechs, widening pricing-tier spreads between premium managed services and economy self-service tiers. This labor-cost differential forces procurement trade-offs between vendor-managed solutions with embedded compliance tooling and capital-light internal platform builds.
Pricing Analysis
Volume concentrates in Infrastructure as a Service while margins accrue to Network as a Service and Compliance Management tiers. Three-tier pricing structure across premium, standard, and economy levels separates hyperscaler-managed offerings from platform-native alternatives and open-source self-managed deployments. Price differentiation hinges on certification level (SOC 2 Type II, PCI-DSS) and embedded compliance automation depth. Pricing pressure stems from consumption-based WAN alternatives displacing MPLS contracts among payment processors. Early-stage neobanks exhibit highest price sensitivity; large payment processors with FedNow latency requirements show lowest.
Supply Chain Analysis
Dual-sourcing requirements embedded in FFIEC examination guidelines mandate multi-supplier qualification for critical network infrastructure, compelling fintechs to maintain active vendor relationships across at least two hyperscale providers. Geographic supply concentration centers on the United States, Canada, and Mexico for regulatory-compliant data residency. Raw material dependencies include silicon for edge compute appliances, optical fiber for inter-cloud transit, and specialized ASICs for encryption acceleration. Supply chain risk manifests in single-source vulnerability for service mesh control plane software. Distribution runs through direct hyperscaler marketplaces and specialized systems integrators with financial services compliance depth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a vertical-integration race where players are pursuing backward integration into compliance-as-code modules to capture margin from audit-ready infrastructure deployments.
For Market Incumbents: Deepen embedded compliance tooling integration to defend against cloud-native entrants with consumption-based pricing. Invest in Canadian and Mexican edge presence to satisfy OSFI and CNBV data residency mandates before regulatory windows tighten. Acquire specialized Kubernetes networking talent pools in the Bay Area to offset engineering scarcity premiums. For New Entrants and Emerging Players: Enter via Mexico's neobank licensing wave under CNBV reforms, where incumbent presence remains thin and first-mover advantages accrue to compliant multi-cloud foundations. Target payment processors in Texas and the US Southeast experiencing FedNow-driven volume spikes. Pursue service mesh specialization as a wedge against full-stack hyperscaler competition. For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with compliance depth and geographic edge coverage. Long-term viability hinges on sustained audit readiness as SEC, OSFI, and CNBV jurisdictions refine cloud-specific financial rules. Watch CNBV licensing velocity as the inflection indicator for Mexico market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance-as-Code Module Development | Automates SOC 2 Type II and PCI-DSS attestation across AWS, Azure, and Google Cloud environments. |
| Geographic Edge Expansion | Establishes Toronto and Mexico City points of presence to satisfy OSFI and CNBV data residency mandates. |
| Service Mesh Platform Integration | Consolidates Istio and Linkerd procurement decisions around platform-native offerings for mid-market digital banks. |
| Network-as-a-Service Convergence | Captures wallet share from telecom carriers with elastic bandwidth scaling tied to FedNow settlement volume spikes. |
| Zero Trust Architecture Certification | Addresses FFIEC examination mandates for identity-centric segmentation spanning on-premises core banking and public cloud. |
Research Methodology
Document review covered SEC cybersecurity disclosure filings, FFIEC examination guidelines, hyperscaler financial services compliance documentation, and CNBV fintech licensing frameworks, complemented by interviews with cloud network architects, fintech CTOs, compliance officers at payment processors, and procurement leads at commercial banks. Secondary validation drew from hyperscaler capex disclosures, regulatory agency rulemaking dockets, and industry association infrastructure surveys. Bottom-up deployment sizing and top-down market aggregation were triangulated to establish segment boundaries.
Segmentation outputs reflect deployment model splits across hybrid, multi-cloud, public, and private architectures; service type differentiation between Network as a Service, Platform as a Service, Infrastructure as a Service, and Software as a Service; and end-user type disaggregation across payment processors, commercial banks, investment firms, and insurance carriers. CAGRs were derived from elasticity modeling of transaction volume growth against infrastructure capacity expansion patterns, with cross-validation against regulatory compliance cost trajectories and labor market tightness indices for specialized cloud engineering roles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated SEC rulemaking or abrupt CNBV licensing suspension. Deviation in FedNow transaction volume adoption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Information and Communication Technology
Italy Cloud Robotics Market
Information and Communication Technology
Robot Controller, Integrator and Software Market
Information and Communication Technology
Japan ICT Market
Information and Communication Technology
Sweden Data Center Rack Market
Information and Communication Technology
Saudi Arabia Telecom Market
Information and Communication Technology
Beacons Management Software Market
Information and Communication Technology
Global Customer Communications Management (CCM) Software Market
Information and Communication Technology
Global Tracking As a Service Market
Information and Communication Technology
Global Digital Intelligence Platform Market
Information and Communication Technology
North America Healthcare Cloud Computing Market
Information and Communication Technology
Global Enterprise Information Archiving Market
Information and Communication Technology
Bot Services Market
Information and Communication Technology
Online Donation Software Market
Information and Communication Technology
Medical Service Robots Market
Information and Communication Technology
Global Programming Software Market
Information and Communication Technology
RIP Color Management Software Market