
 North America Leather Goods Market | 2026-2036
North America Leather Goods Market Size, Share, and Industry Trends Forecast 2026-2036
North America Leather Goods Market Analytics
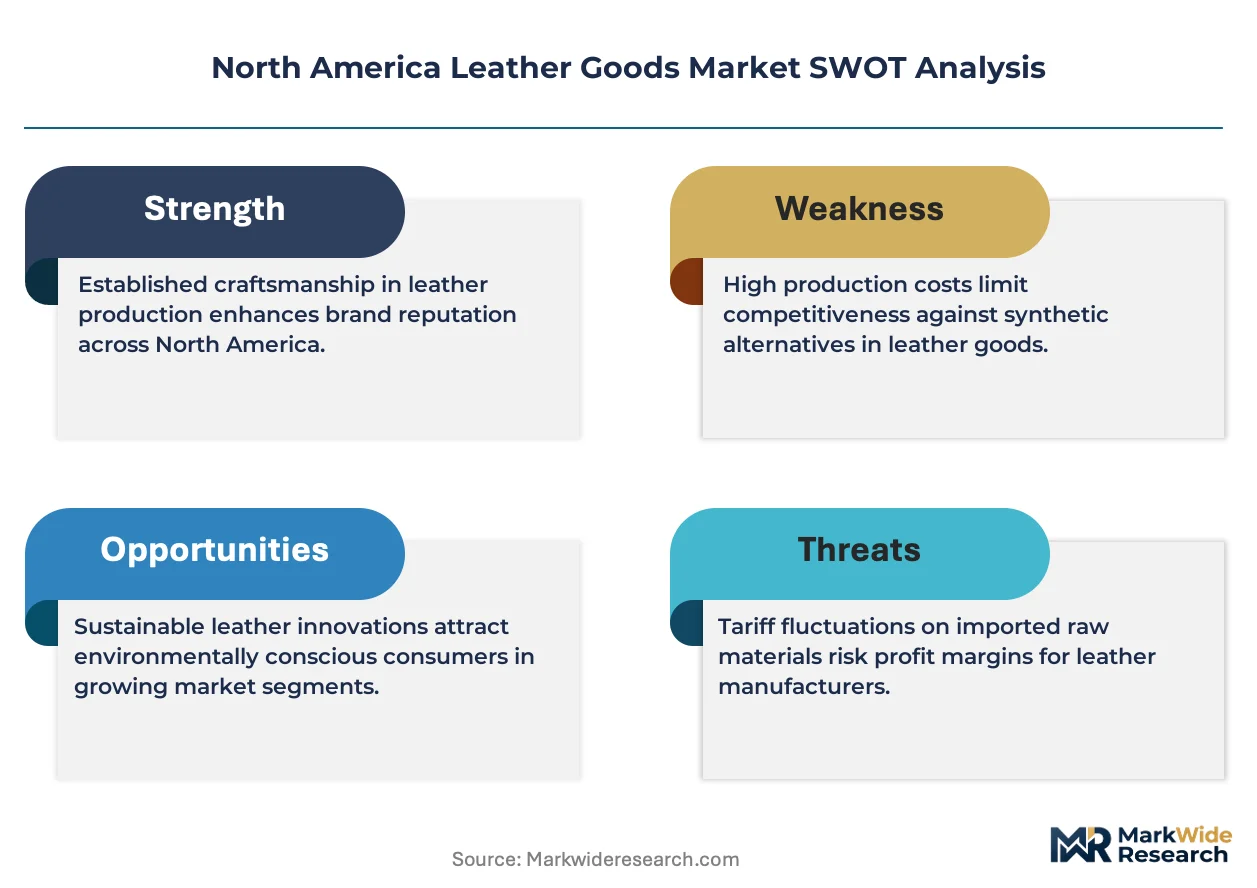
A shift from outsourced tanning to captive finishing operations is rebalancing supply chain economics for premium leather goods producers. Nike, Inc. leverages its scale to secure dedicated hide processing capacity in North American facilities. Kering anchors its regional portfolio through controlled distribution of luxury handbags and small leather goods. Timberland LLC competes by integrating sustainable leather sourcing with its heritage work-boot specialization.
North America leather goods encompass finished articles crafted from bovine, ovine, or exotic hides through chrome, vegetable, or synthetic tanning processes, valued for durability, aesthetic grain structure, and tactile performance in apparel and accessory applications. Footwear commands the largest revenue pool among product types, while wallets and belts sustain steadier replacement-cycle demand. Online retail captures the fastest-growing distribution channel as direct-to-consumer platforms displace department store foot traffic among mass market and eco-conscious buyers.
The EPA enforces effluent limitations under the Clean Water Act for tannery discharge, while California's Proposition 65 mandates chemical labeling that affects formulation choices across the supply chain. Health Canada and the Consumer Product Safety Commission coordinate on lead-content restrictions in accessible leather components. Stakeholders must monitor evolving state-level chemical restrictions and traceability mandates to preserve market access and brand positioning.
Market Dynamics
Captive tanning capacity and traceable hide sourcing are restructuring supply chain economics across North American leather goods, as brands absorb finishing operations to secure quality control and margin protection against volatile raw material costs.
Growth Catalysts
- California Proposition 65 chemical disclosure mandates:Brands investing in compliant formulation gain preferential placement with retailers and liability protection, accelerating certified clean-material adoption.
- Metropolitan fashion corridor concentration:New York, Los Angeles, and Toronto generate concentrated demand density for premium handbags and small leather goods, reducing customer acquisition costs for direct distribution.
- Chrome-free vegetable tanning processes:Tanneries deploying bio-based alternatives capture eco-conscious buyer segments and command price premiums in accessory categories.
Market Restraints
- Bovine hide cost volatility:Feed grain price fluctuations and herd-size cycles transmit directly to raw material input costs, compressing margin predictability for finished goods producers.
- EPA Clean Water Act effluent limitations:Tannery discharge permitting and treatment infrastructure requirements raise capital barriers for new domestic finishing capacity entrants.
- Synthetic leather substitution threat:Polyurethane and plant-based alternatives from Asia-Pacific suppliers capture price-sensitive wallet and belt segments through improved tactile performance.
Strategic Opportunities
- Mexico nearshoring expansion:Untapped cut-and-sew capacity in León and Guadalajara offers tariff-advantaged production for US-bound finished goods with shorter lead times.
- Direct-to-consumer platform penetration:Owned digital channels bypass department store margin extraction and enable first-party data capture for personalization.
- Health Canada traceability coordination:Harmonized lead-content standards with US CPSC rules simplify cross-border compliance and open unified North American product lines.
Industry Challenges
- Artisanal craft skill scarcity:Master leatherworkers capable of hand-finishing and edge-burnishing for luxury tiers retire faster than apprenticeship pipelines replenish.
- Legacy ERP integration friction:Tannery-to-brand data interoperability for lot-level traceability requires expensive middleware development against decades-old production systems.
- Multi-state chemical patchwork compliance:Divergent state-level restricted substance lists beyond federal baselines force SKU proliferation and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Leather Goods Market |
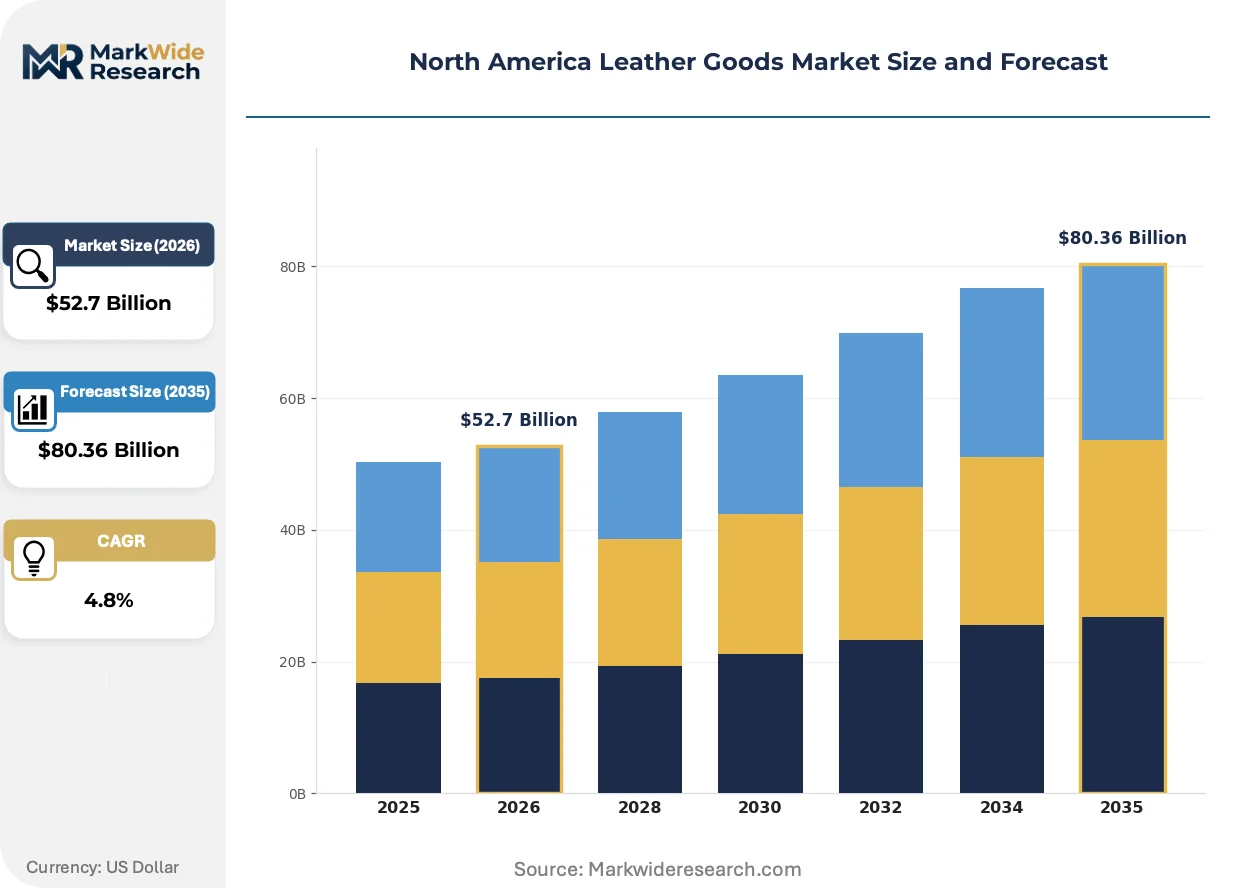
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $80.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handbags, Wallets, Footwear, Belts Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales Customer Type: Luxury Consumers, Mass Market, Eco-Conscious Buyers, Corporate Clients End Use: Fashion Accessories, Functional Goods, Work Products, Gifts |
| Companies Covered | Nike, Inc., New Balance Athletics, Inc., Timberland LLC, Johnston & Murphy, VF Corporation, Capri Holdings Limited, Hermès, Kering, Tapestry Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Leather Goods Market Evolving Landscape
Digital traceability infrastructure and bio-based material science are converging to redefine quality verification and sustainability claims across the North American leather goods value chain.
Blockchain-enabled provenance tracking is decentralizing authentication authority away from traditional certifying bodies toward immutable supply chain records. Premium handbag buyers now verify hide origin and tanning method through QR-linked distributed ledgers rather than paper certificates. This shift compresses trust-building timelines for emerging brands while raising transparency expectations for established players.
The EPA's evolving effluent limitation guidelines under the Clean Water Act are tightening chromium discharge thresholds for domestic tanneries. Facilities must deploy advanced membrane filtration or precipitate recovery systems to maintain operating permits, favoring capital-rich integrated producers over independent finishers. Vegetable-tanned specialty operations in the Northeast and Pacific Northwest gain relative positioning through inherently lower chemical intensity.
Subscription-based accessory refresh models are displacing traditional replacement-cycle purchasing among urban professional segments. Services offering seasonal wallet and belt exchanges with buyout options capture younger demographics in Toronto and Chicago who prioritize variety over permanent ownership. This behavioral pivot pressures wholesale-dependent brands to build direct relationships or risk margin erosion through platform intermediation.
North America Leather Goods Market Segmentation
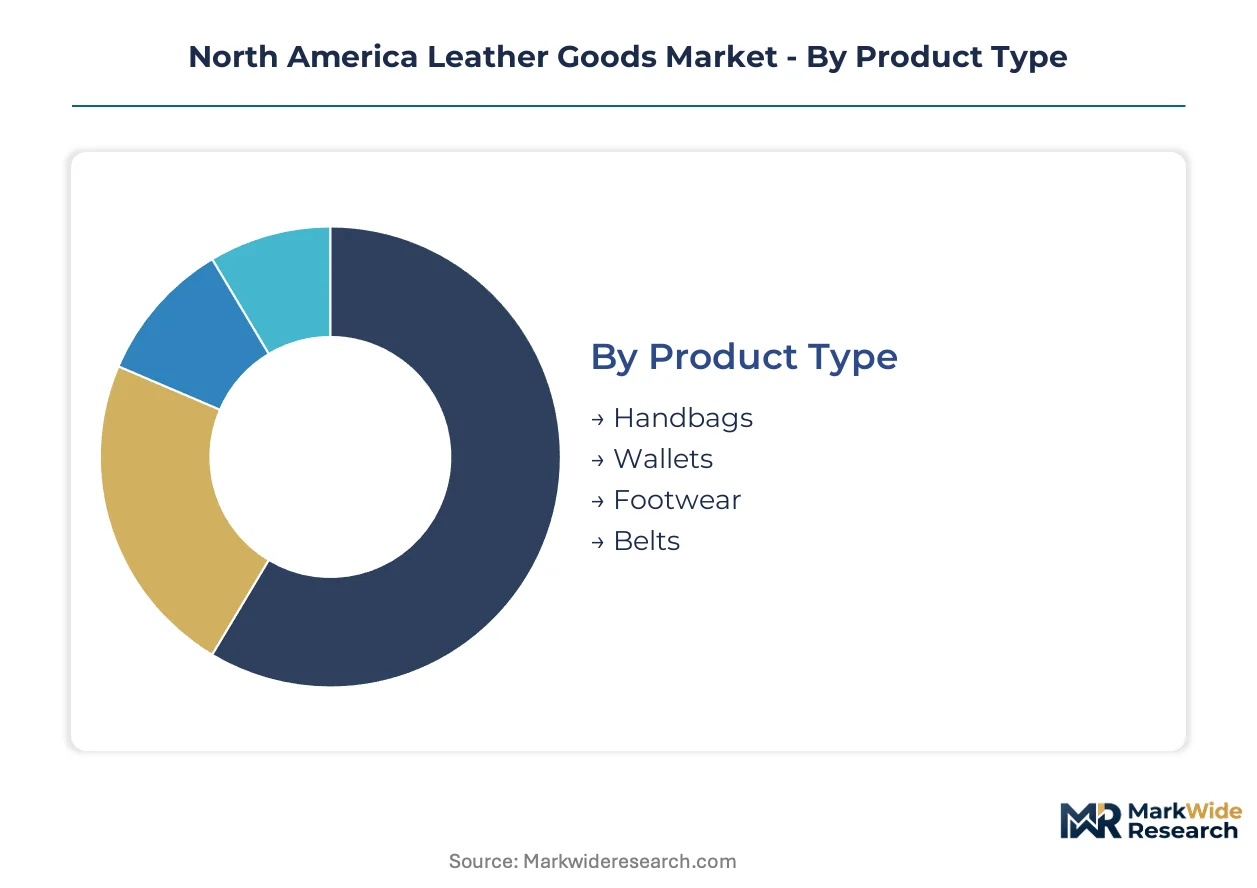
Segmentation reveals how tanning methods, distribution economics, and buyer psychographics partition revenue across the North American leather goods value chain. Distinct margin profiles and compliance burdens attach to each category, shaping where integrated producers concentrate investment versus where specialists defend niche positions.
Product Type:
Customization intensity spans from made-to-measure exotic hides to standardized commodity cuts, with premium tiers commanding dedicated finishing lines and mass volumes flowing through automated cutting.
- Handbags:Full-grain bovine and exotic hides dominate luxury construction, with vegetable-tanned panels preferred for structural integrity. Demand clusters in New York and Los Angeles fashion corridors, where direct-to-consumer platforms now capture share from wholesale-dependent heritage brands. Chrome-free certification drives material specification for California Proposition 65 compliance.
- Footwear:Work-boot heritage specialization and athletic-lifestyle crossover define the largest revenue pool by volume. Captive tanning capacity in domestic facilities secures consistent hide quality for Timberland and Nike production lines. EPA effluent limitations favor capital-rich integrated producers over independent finishers serving this segment.
- Wallets:Compact dimensions and standardized cutting patterns enable efficient small-batch production across León, Mexico cut-and-sew operations.
- Belts:Replacement-cycle stability sustains steadier demand than fashion-driven categories, with price compression from Asia-Pacific synthetic alternatives threatening mid-tier positioning.
Leading the category by volume: Footwear. Growing fastest: Handbags.
Distribution Channel:
Channel economics diverge sharply on customer acquisition cost, margin retention, and data sovereignty, with digital platforms restructuring traditional wholesale hierarchies.
- Online Retail:Direct-to-consumer penetration accelerates fastest among mass market and eco-conscious buyer segments, displacing department store foot traffic. First-party data capture enables personalization engines that reduce customer acquisition costs in metropolitan corridors. Shopify and proprietary platforms bypass traditional retail margin extraction.
- Specialty Stores:Curated assortment and tactile evaluation sustain relevance for premium handbag and small leather goods categories. Toronto and Chicago flagships anchor brand positioning for Kering portfolio labels. Staff expertise on tanning methods and hide provenance justifies price premiums over digital alternatives.
- Department Stores:Consolidating footprint and deteriorating terms pressure wholesale-dependent brands to diversify channel mix.
- Direct Sales:Corporate gifting programs and trunk show models serve B2B volume with customized embossing and volume pricing.
Dominant by transaction volume: Specialty Stores. Expanding most quickly: Online Retail.
Customer Type:
Price elasticity and sustainability sensitivity stratify purchasing behavior, with regulatory tailwinds concentrating demand among disclosure-responsive segments.
- Luxury Consumers:United States buyers drive expanding adoption of premium handbags and wallets, prioritizing traceable hide origin and hand-finishing craftsmanship. Blockchain-enabled provenance verification now substitutes for traditional paper certification. This segment absorbs price premiums for vegetable-tanned and chrome-free construction.
- Eco-Conscious Buyers:Bio-based tanning process preference and circularity expectations reshape material sourcing decisions. Subscription-based accessory refresh models capture younger demographics in Toronto and Chicago who prioritize variety over permanent ownership.
- Mass Market:Price sensitivity exposes this segment to polyurethane substitution from Asia-Pacific suppliers.
- Corporate Clients:Custom embossing and standardized gift sets sustain steady B2B demand with lower margin but higher volume predictability.
Largest revenue concentration: Luxury Consumers. Gaining share fastest: Eco-Conscious Buyers.
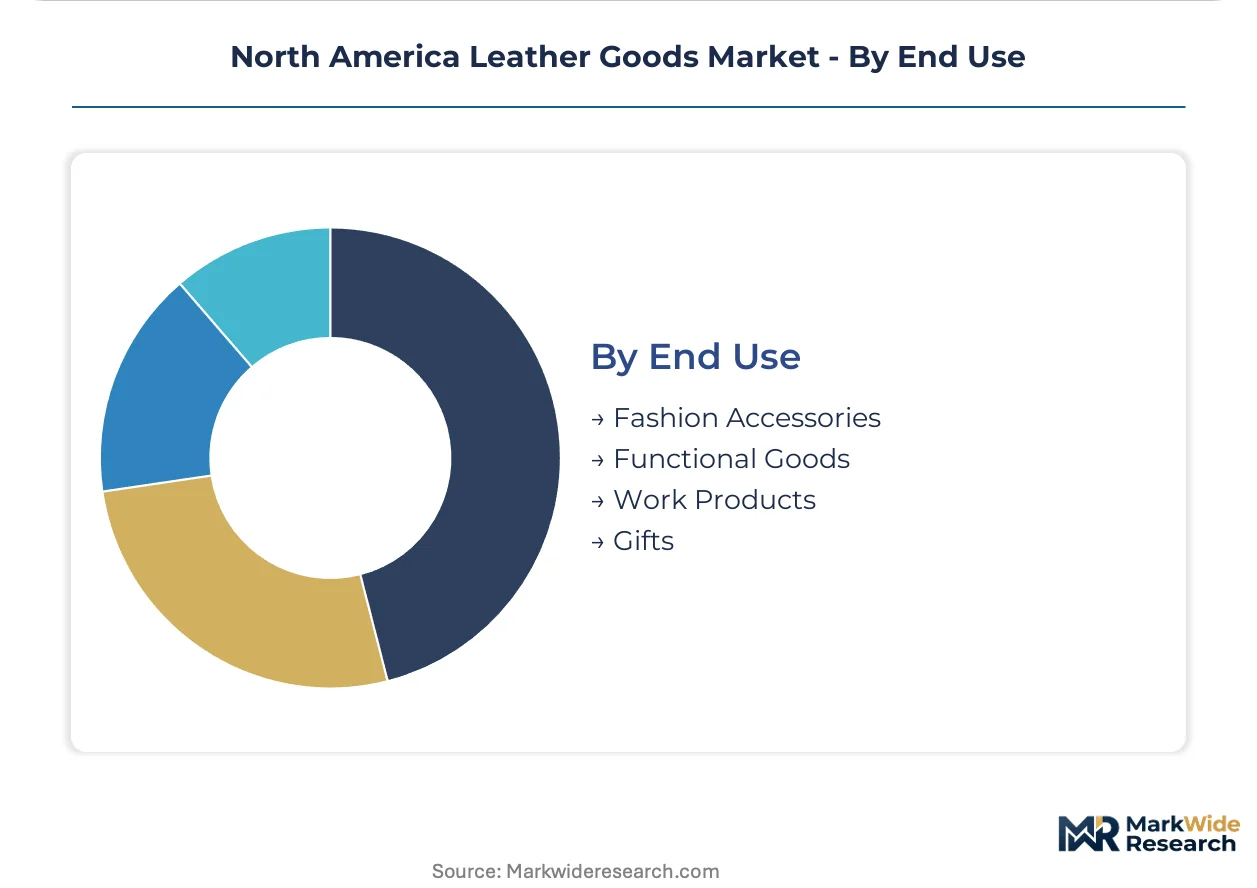
End Use:
Functional durability requirements versus aesthetic obsolescence cycles determine replacement frequency and material specification intensity across application categories.
- Fashion Accessories:Seasonal color and silhouette turnover drives handbag and belt demand in New York and Los Angeles corridors. Rapid style cycling pressures inventory management and markdown risk for wholesale-dependent brands. Direct-to-consumer platforms mitigate this through made-to-order and pre-sale models.
- Work Products:Heritage work-boot specialization and tool-belt construction prioritize abrasion resistance and welted durability over trend responsiveness. Timberland competes through sustainable leather sourcing integration with functional performance guarantees.
- Functional Goods:Everyday carry wallets and travel accessories balance durability with refined aesthetics for professional demographics.
- Gifts:Seasonal concentration and price-point accessibility define this segment, with corporate procurement programs providing baseline volume.
Highest volume endpoint: Fashion Accessories. Steepest expansion trajectory: Work Products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Great Lakes hide auctions and Texas Panhandle feedlot clusters supply the raw material base that anchors North American leather goods production. Regional tanning capacity concentrates near these supply nodes to minimize hide transport spoilage. Metropolitan fashion corridors in New York, Los Angeles, and Toronto generate the demand density that completes the value chain.
United States
Luxury consumers in New York and Los Angeles drive premium handbag and wallet adoption, with direct-to-consumer platforms displacing department store channels. EPA Clean Water Act effluent limitations reshape domestic tanning economics, favoring capital-rich integrated producers. Chicago anchors the Midwest distribution hub for work-boot heritage specialization.
Canada
Toronto generates concentrated demand density for small leather goods, reducing customer acquisition costs for direct distribution entrants. Health Canada coordinates lead-content restrictions with US CPSC rules, simplifying cross-border compliance for unified product lines. Montreal tanneries supply cut-and-sew operations with vegetable-tanned panels for structural accessory construction.
Mexico
Untapped cut-and-sew capacity in León and Guadalajara offers tariff-advantaged production for US-bound finished goods with shorter lead times. Mexican environmental regulators enforce discharge standards aligned with US EPA frameworks, preserving export eligibility. León's leatherworking heritage cluster supports skilled artisan pipelines for hand-finishing operations.
North America Leather Goods Market Competitive Landscape
Global majors compete with regional champions across captive tanning capacity and direct-to-consumer platform penetration. The market structure tiers into integrated luxury houses with controlled distribution, athletic-lifestyle conglomerates with scale advantages, and heritage work-boot specialists with sustainable sourcing integration. Strategic moves concentrate on backward integration into hide processing and owned digital channel buildout to bypass wholesale margin extraction.
Within the integrated luxury tier, Kering and Hermès exemplify controlled distribution archetypes that secure margin protection through captive supply chains. Among athletic-lifestyle conglomerates, Nike, Inc. and VF Corporation occupy positions defined by scale-driven procurement and dedicated finishing capacity. Timberland LLC anchors the heritage specialization vector, integrating sustainable leather sourcing with functional performance positioning.
| Leading Market Players |
|---|
| Nike, Inc. |
| New Balance Athletics, Inc. |
| Timberland LLC |
| Johnston & Murphy |
| VF Corporation |
| Capri Holdings Limited |
| Hermès |
| Kering |
| Tapestry Inc. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap tanneries in the US Northeast and Pacific Northwest anchor supply-side discipline through generational hide-procurement relationships and limited external financing, enabling patient pricing strategies that resist commodity volatility while California Proposition 65 compliance costs concentrate premium-tier markups.
Pricing Analysis
Warranty-bundling separates premium handbag tiers from mass-market alternatives, with vegetable-tanned construction commanding lifetime repair guarantees against chrome-tanned economy tiers sold as-is. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and hide provenance traceability. Cost compression in the mid-tier wallet segment is intensifying because Asia-Pacific polyurethane alternatives match tactile performance at lower price points. Mass-market buyers exhibit highest price sensitivity, while luxury consumers absorb premiums for blockchain-verified origin documentation.
Supply Chain Analysis
Single-source vulnerability sits with Texas Panhandle and Great Lakes hide auction clusters that feed domestic tanning capacity. Raw material flows draw from US cattle operations, Canadian ovine herds, and Mexican exotic hide ranches. Tariff exposure threatens León cut-and-sew operations serving US-bound finished goods. Distribution runs through direct-to-consumer platforms displacing department store wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive tanning capacity determines margin protection against volatile hide costs and regulatory compliance burdens.
For Market Incumbents: Deepen backward integration into hide processing facilities near Texas Panhandle supply nodes to secure quality consistency against bovine cost volatility. Absorb vegetable-tanning specialty operations in the Pacific Northwest to capture eco-conscious buyer premiums and simplify California Proposition 65 compliance documentation. For New Entrants and Emerging Players: The pricing gap between Kering-controlled luxury handbags and mass-market synthetic alternatives offers white-space entry for traceable mid-tier positioning. Target Toronto and Chicago metropolitan corridors with subscription-based accessory refresh models that prioritize variety over ownership. Launch through Shopify-native direct-to-consumer platforms to bypass department store margin extraction. For Investors and Strategic Acquirers: EPA effluent limitation tightening is the leading indicator that capital-rich integrated producers will consolidate independent tannery capacity. Over a multi-year horizon, vertically integrated houses with owned digital channels and captive finishing operations present superior viability against wholesale-dependent competitors. Monitor Health Canada-US CPSC harmonization progress as signal for unified North American product line scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Tanning Capacity Acquisition | Secures EPA-compliant hide processing and insulates margin from raw material volatility. |
| Direct-to-Consumer Platform Buildout | Bypasses department store consolidation and captures first-party data for personalization engines. |
| Vegetable-Tanning Certification Investment | Unlocks California Proposition 65 preferential placement and eco-conscious buyer price premiums. |
| Blockchain Provenance Infrastructure | Substitutes distributed ledger verification for paper certificates in luxury handbag authentication. |
| León Nearshoring Expansion | Captures tariff-advantaged cut-and-sew capacity with shorter lead times for US-bound finished goods. |
Research Methodology
Trade association filings, EPA enforcement databases, and Health Canada regulatory guidance formed the secondary backbone, cross-referenced with primary interviews involving tannery operations managers, luxury brand supply chain directors, retail category buyers, and leather goods artisans. Bottom-up volume modeling triangulated against top-down market sizing from customs records and sectoral economic indicators.
Historical trendline analysis across hide price indices, tanning capacity utilization rates, and channel mix evolution informed projection frameworks. Segmentation dimensions spanned product type, tanning method, distribution channel, and metropolitan demand corridor. CAGRs derived from regression-adjusted growth rates applied to segment-specific baseline values, incorporating EPA regulatory trajectory and synthetic substitution elasticity as leather-specific inputs.
Underlying measurement precision varies by segment; footwear volume estimates carry tighter precision than exotic hide handbag projections given standardized production metrics. Forecasts reflect assumptions around regulatory enforcement intensity and consumer willingness-to-pay for traceability documentation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Massaging Cosmetic Applicators Market
Consumer Goods
China Maternity Goods Market
Consumer Goods
Aromatherapy Diffuser Market
Consumer Goods
On-The-Go Pots Market
Consumer Goods
Driving Footwear Market
Consumer Goods
Germany Washing Machine Market
Consumer Goods
Hand Dryer Market
Consumer Goods
Beauty Salon Market
Consumer Goods
Range Hood Cleaning Service Market
Consumer Goods
Gulf Cooperation Council Fragrance and Perfumes Market
Consumer Goods
Household Sewing Machines Market
Consumer Goods
Handheld Massager Market
Consumer Goods
Slip Resistant Shoes Market
Consumer Goods
Cleaning Trolleys Market
Consumer Goods
Floor-Standing Integrated Smart Toilet Market
Consumer Goods
Pet Hair Care Market