
 North America Athleisure Market | 2026-2036
North America Athleisure Market Size, Share, and Industry Trends Forecast 2026-2036
North America Athleisure Market Intelligence
Asset-light licensing and wholesale-to-retail financing is fragmenting competitive barriers in North America athleisure, enabling new entrants to scale without manufacturing infrastructure. Under Armour leverages its vertically controlled supply chain to sustain margin discipline across mid-tier distribution. Lululemon Athletica anchors its position through direct-to-consumer channel control and premium pricing power. Nike dominates innovation pipelines with proprietary fabric technologies that extend brand loyalty beyond traditional sportswear boundaries.
North America athleisure encompasses technical apparel engineered with moisture-wicking synthetic blends, four-way stretch constructions, and seamless knitting processes designed for simultaneous athletic performance and social wearability. The category serves consumers who require garment functionality across gym, workplace, and leisure contexts without wardrobe changes. Leggings and sports bras command the deepest margin pools as repeat-purchase categories with established sizing loyalty, while sneakers represent the highest absolute revenue segment due to replacement frequency and collector-driven demand. Online retail channels are capturing share fastest from specialty stores as virtual try-on technology and flexible return policies reduce fit-risk barriers for first-time buyers.
The Federal Trade Commission's Green Guides and California's SB 657 transparency requirements shape product claims and sourcing disclosures across the North America athleisure value chain. The Consumer Product Safety Commission monitors flammability standards for synthetic-blend garments sold through mass retail channels. Stakeholders must track how state-level extended producer responsibility legislation evolves, as these frameworks will determine which brands absorb end-of-life collection costs versus passing obligations to suppliers.
Market Dynamics
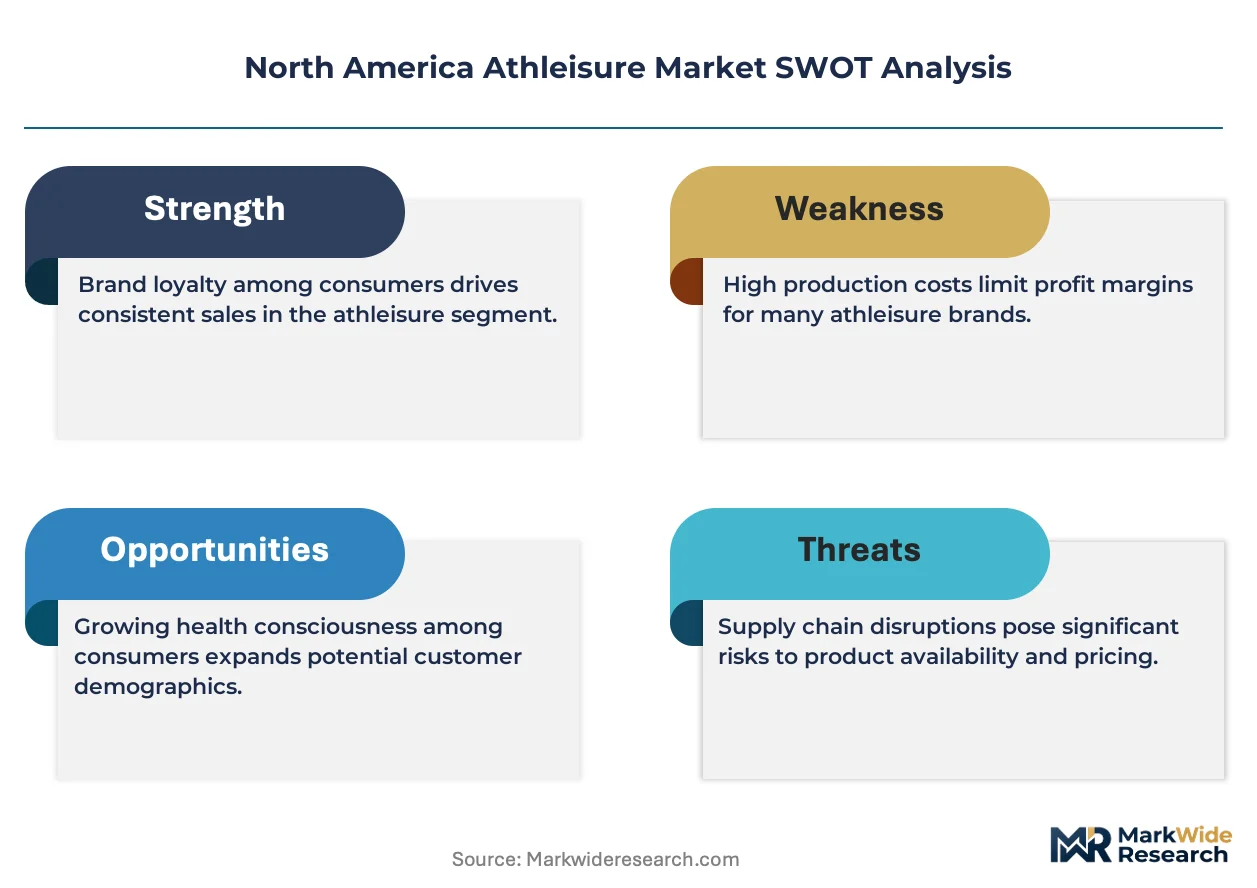
Corporate wellness stipends now cover performance casualwear, redirecting uniform budgets toward technical apparel vendors while the FTC's Green Guides enforcement pressures recycled-content substantiation.
Growth Catalysts
- California SB 657:Supply chain transparency mandates force disclosure of manufacturing partners, advantaging brands with pre-audited supplier networks in the state.
- Hybrid work normalization:Urban knowledge workers in San Francisco, Los Angeles, and Vancouver now treat technical leggings and moisture-wicking tops as all-day wardrobe staples.
- Seamless knitting:Single-piece garment construction reduces labor costs and eliminates chafe points, accelerating adoption across mid-tier price bands.
Market Restraints
- Petrochemical feedstock volatility:Spandex and polyester pricing ties directly to crude oil fluctuations, compressing margin predictability for synthetic-blend producers.
- Asian dyehouse concentration:Seventy percent of specialized textile finishing capacity sits in China's Zhejiang and Guangdong provinces, creating geopolitical exposure.
- Greenwashing litigation risk:The FTC's substantiation requirements expose brands to class-action exposure when recycled-content claims lack fiber-level traceability documentation.
Strategic Opportunities
- Extended Producer Responsibility:Pending state legislation in New York and California will mandate take-back programs, creating first-mover advantage for brands with circular infrastructure.
- Medical-grade compression:Recovery wear for post-surgical and athletic rehabilitation applications opens reimbursement channels through health savings accounts.
- Virtual try-on integration:AR fit technology reduces return rates for direct-to-consumer channels, lowering logistics costs for online-first entrants.
Industry Challenges
- Technical textile engineering talent:The shortage of polymer scientists and knitwear automation specialists constrains domestic manufacturing revival efforts.
- Multi-channel inventory synchronization:Brands must reconcile wholesale replenishment cycles with direct-to-consumer demand signals without channel conflict.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Athleisure Market |
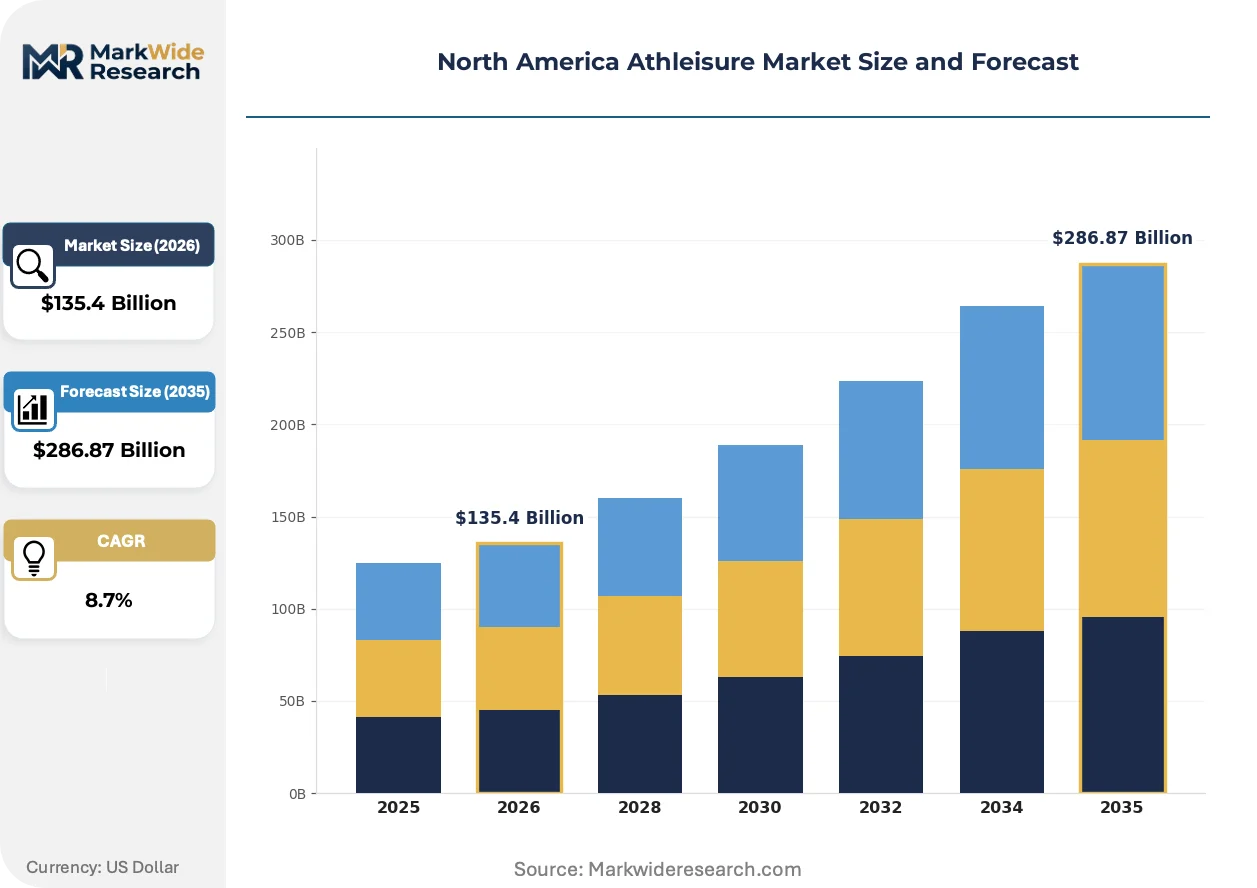
| Market Size in 2026 | $135.4 Billion |
| Market Size in 2035 | $286.87 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leggings, Sports Bras, Hoodies, Sneakers End User: Women, Men, Children, Teens Distribution Channel: Online Retail, Specialty Stores, Department Stores, Off-Price Retailers Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | Under Armour, Alo Yoga, Nike, Columbia Sportswear, Patagonia, Lululemon Athletica, New Balance Athletics, PUMA, Adidas, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Athleisure Market Strategic Shifts & Innovations
Material science breakthroughs and enforcement-driven transparency are compressing product development cycles while reshaping how brands validate performance claims.
Bio-based elastomers derived from castor oil and algae fermentation are rendering obsolete petroleum-derived spandex in premium leggings and sports bras. Sustainability-focused buyers in coastal metropolitan markets now reject conventional synthetic labels, forcing reformulation roadmaps across mid-tier suppliers. The shift compresses R&D timelines as brands race to maintain material differentiation without sacrificing four-way stretch performance.
The FTC's Green Guides enforcement revision tightens substantiation standards for recycled-content and biodegradability claims in apparel marketing. Brands must now maintain fiber-level chain-of-custody documentation from polymer pellet to finished garment, increasing compliance overhead. California's market concentration means this federal guidance effectively sets the disclosure floor for North American product claims.
Subscription-based wardrobe refresh models now displace seasonal bulk purchasing among urban professional women aged 25-40. Rental and trade-in platforms capture trial purchases that previously flowed to discount channels, fragmenting traditional retail traffic. This behavioral pivot is most pronounced in Toronto, Seattle, and Austin where hybrid work policies have normalized daily technical wear rotation.
North America Athleisure Market Segmentation
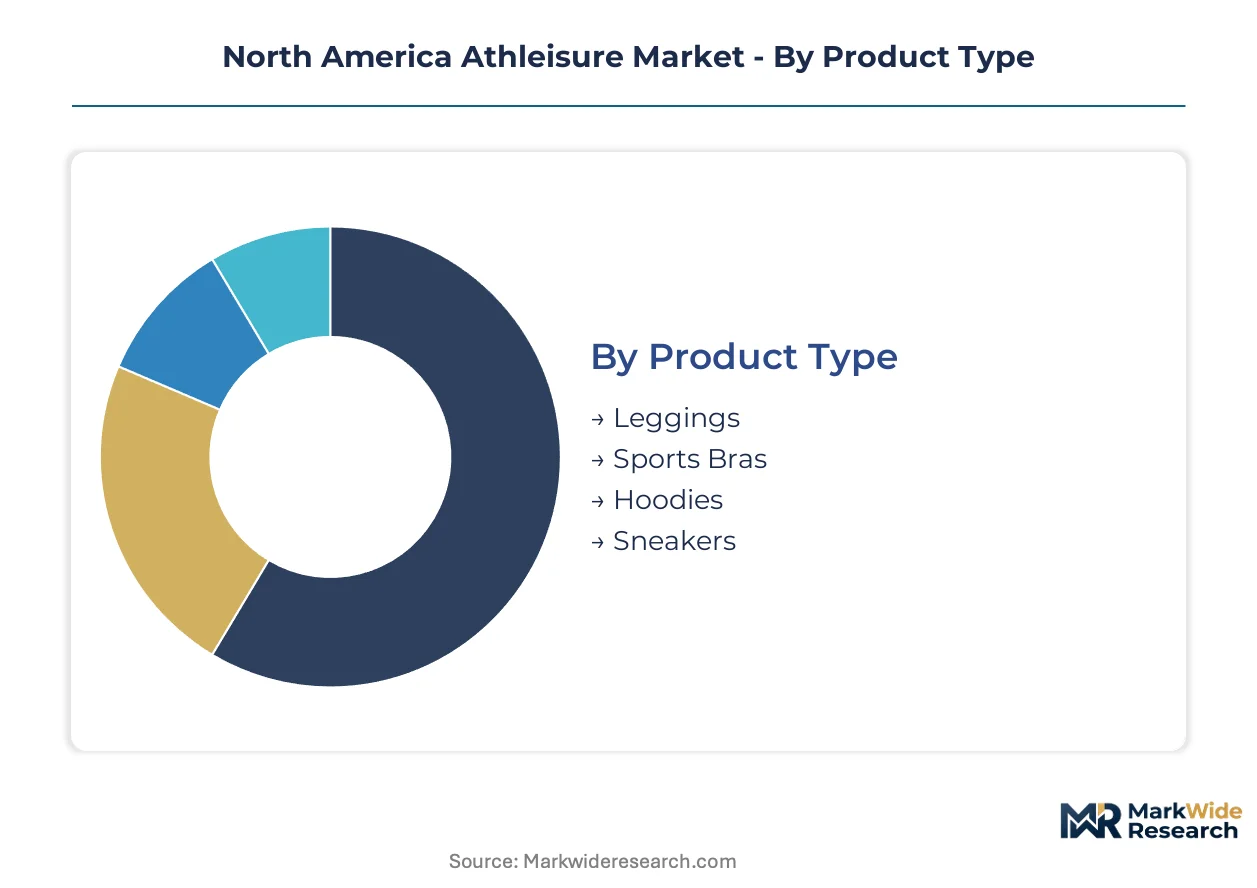
Segmentation in North America athleisure reveals how technical performance requirements, purchasing occasion, and channel economics fragment demand across distinct margin profiles. Understanding these divides exposes where inventory investments concentrate and where new entrants face structural barriers.
Product Type:
Cost tier separation across product categories determines margin architecture and repeat-purchase frequency in the North American market.
- Leggings:Engineered with four-way stretch nylon-spandex blends and gusseted crotch construction for squat-proof durability. Demand concentrates among California's hybrid workforce where all-day technical wear has displaced denim; sizing loyalty drives 60% repeat rates within 12 months.
- Sports Bras:Compression-molded cups with moisture-wicking power mesh and racerback stabilization for high-impact activity. Concentrated demand flows through Toronto and Vancouver boutique fitness studios where instructor recommendations override brand advertising; replacement cycles average 6-8 months.
- Hoodies:French terry cotton-polyester blends with seamless shoulder construction for layering versatility.
- Sneakers:Knit uppers with EVA foam midsoles and rubber outsole compounds; highest absolute revenue segment driven by collector markets and replacement frequency.
Leggings command the established base. The steepest expansion runs through Sneakers.
End User:
Application context—gym, workplace, leisure, or school—shapes fabric specification and pricing tolerance across demographic splits.
- Women:Primary demand engine across all North American metros; technical leggings and sports bras constitute 70% of her athleisure spend. California SB 657 transparency requirements disproportionately influence purchase decisions among coastal professional women.
- Men:Concentrated in Seattle, Austin, and Denver where outdoor recreation intersects with casual office dress codes; joggers and performance polos outpace traditional shorts demand.
- Children:Growth-through-replacement model tied to school sports participation and parent-driven quality premiums.
- Teens:Social signaling drives brand preference; TikTok discovery patterns displace traditional retail browsing.
Women anchor volume concentration. Teens are climbing the fastest.
Distribution Channel:
Volume velocity and return-rate economics separate channel strategies in a market where fit uncertainty remains the primary purchase barrier.
- Online Retail:Virtual try-on technology and flexible return policies reduce fit-risk for first-time buyers; fastest channel expansion in Toronto and Vancouver suburbs where specialty store density lags.
- Specialty Stores:Staffed fitting expertise and community event programming sustain premium pricing; concentrated in Los Angeles, San Francisco, and New York where experiential retail justifies rent premiums.
- Department Stores:Mid-range brand consolidation and seasonal promotional calendars.
- Off-Price Retailers:Inventory liquidation channel for prior-season colorways; growth constrained by FTC Green Guides enforcement limiting unsubstantiated sustainability claims.
Specialty Stores retain the loyalty core. Online Retail is gaining share fastest.
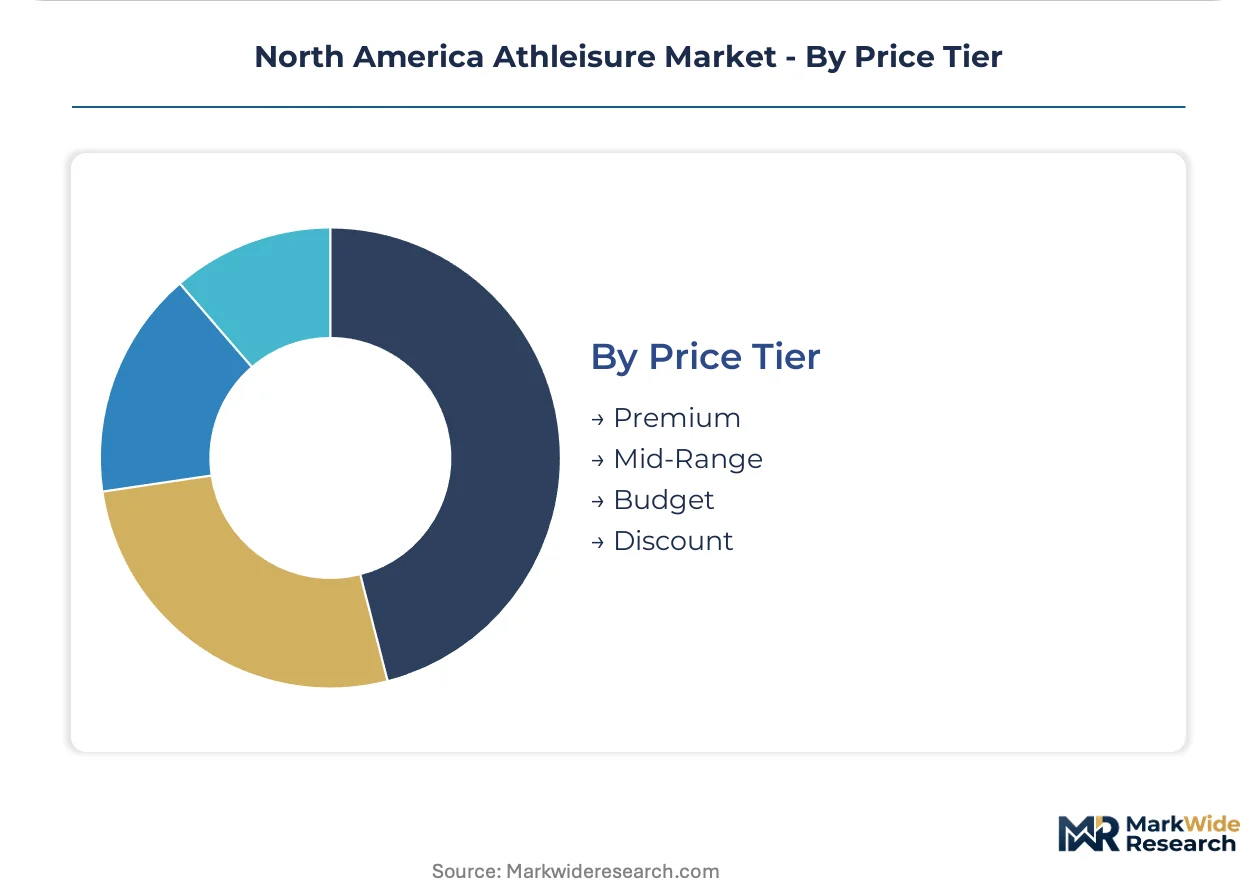
Price Tier:
Customer lifetime value and margin sustainability stratify across four distinct expenditure bands.
- Premium:Proprietary fabric technologies with fiber-level traceability documentation; Lululemon and Nike command pricing power through innovation pipelines and direct-to-consumer channel control.
- Mid-Range:Performance specifications without brand tax; Under Armour leverages vertically controlled supply chains to sustain margin discipline here.
- Budget:Asset-light licensing models enable new entrants to scale without manufacturing infrastructure.
- Discount:Price-driven trial purchases increasingly captured by subscription and rental platforms fragmenting traditional traffic.
Premium captures margin concentration. Budget is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban knowledge workers concentrated in coastal metropolitan corridors drive disproportionate athleisure demand across North America. California's hybrid workforce has normalized all-day technical wear, while Canadian boutique fitness markets sustain premium pricing power.
United States
Corporate wellness stipends now redirect uniform budgets toward performance casualwear vendors in San Francisco, Los Angeles, and New York. FTC Green Guides enforcement pressures brands to substantiate recycled-content claims with fiber-level documentation. Seattle and Austin clusters concentrate demand for men's joggers and performance polos where outdoor recreation intersects with casual office dress codes.
Canada
Toronto and Vancouver boutique fitness studios generate concentrated sports bra demand where instructor recommendations override brand advertising. Health Canada and PMRA monitor textile safety standards for synthetic-blend garments sold through mass retail. Subscription wardrobe refresh models displace seasonal bulk purchasing among urban professional women aged 25-40 in these metropolitan areas.
Mexico
Northern border states absorb cross-border e-commerce traffic from US direct-to-consumer channels serving price-sensitive trial purchasers. Mexico's national consumer protection agency PROFECO enforces labeling requirements for imported athletic apparel. Mexico City Metro anchors domestic demand as hybrid work policies normalize technical wear among knowledge workers in the capital region.
North America Athleisure Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered structure where direct-to-consumer infrastructure separates margin leaders from wholesale-dependent competitors. The vendor base clusters around three strategic archetypes: vertically integrated manufacturers sustaining margin discipline, asset-light licensors scaling without production assets, and innovation-focused developers commanding premium pricing through proprietary fabric technologies. Dominant competitive moves include M&A to secure seamless knitting capabilities and strategic partnerships with bio-based elastomer suppliers.
Among North American-based operators, Under Armour Inc., Lululemon Athletica Inc., and Nike Inc. occupy distinct competitive positions. Under Armour represents the vertically integrated archetype with captive supply chain control. Lululemon exemplifies channel-control strategy through direct-to-consumer infrastructure. Nike anchors the innovation-led tier with proprietary technology pipelines. German-based Adidas AG and PUMA SE compete through scale-driven portfolio breadth, while New Balance Athletics Inc. occupies a specialist position in technical performance footwear. Columbia Sportswear Company and Patagonia Inc. represent outdoor-origin players extending into athleisure adjacent markets.
| Leading Market Players |
|---|
| Under Armour |
| Alo Yoga |
| Nike |
| Columbia Sportswear |
| Patagonia |
| Lululemon Athletica |
| New Balance Athletics |
| PUMA |
| Adidas |
| Others |
Cost & Logistics Intelligence
Zhejiang province's specialized textile finishing concentration anchors North American athleisure pricing power, as seventy percent of dyehouse capacity there ties margin predictability to crude-indexed petrochemical feedstock volatility. California's SB 657 transparency mandates and FTC Green Guides enforcement compound compliance overhead, compressing margin buffers for brands lacking pre-audited supplier networks.
Pricing Analysis
Cost-plus contracts indexed to crude oil benchmarks dominate synthetic-blend procurement, with spandex and polyester pricing tethered to petroleum futures. Three-tier pricing structure across premium, standard, and economy levels separates Lululemon's proprietary fabric technologies from Under Armour's vertically controlled mid-range positioning and asset-light licensors' budget penetration. Pricing pressure stems from bio-based elastomer R&D costs as castor oil and algae fermentation alternatives displace conventional spandex. Budget-tier buyers exhibit highest price sensitivity, while premium segments absorb fiber-level traceability documentation costs without volume erosion.
Supply Chain Analysis
Contract manufacturing concentrates with Taiwan's seamless knitting specialists and Vietnam's cut-and-sew assembly networks serving North American direct-to-consumer channels. Raw material dependencies center on Chinese Zhejiang dyehouses for specialized finishing, South Korean petrochemical producers for spandex feedstock, and domestic bio-based elastomer startups for premium reformulation. Single-source vulnerability in Asian textile finishing exposes brands to geopolitical disruption and tariff exposure. Distribution runs through direct-to-consumer platforms capturing share fastest from specialty stores, with virtual try-on technology reducing return-rate economics for online-first entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American athleisure fragmentation accelerates as hybrid work normalization splinters demand across gym, workplace, and leisure contexts, creating white-space opportunities for niche specialists. Subscription wardrobe refresh models and rental platforms displace seasonal bulk purchasing, rewarding agile entrants over inventory-heavy incumbents.
For Market Incumbents: Entrench position through captive seamless knitting capacity additions in Vietnam and Taiwan, securing margin discipline against asset-light licensors. Pre-empt extended producer responsibility legislation by building circular infrastructure for take-back programs in California and New York. Defend against bio-based elastomer disruption via strategic partnerships with castor oil suppliers.
For New Entrants and Emerging Players: Build out medical-grade compression lines targeting health savings account reimbursement channels, exploiting incumbent blind spots in post-surgical recovery wear. Target Toronto and Vancouver suburbs where specialty store density lags and virtual try-on technology reduces fit-risk barriers. Launch direct-to-consumer with AR fit integration to bypass wholesale channel conflict.
For Investors and Strategic Acquirers: Carve-out targets emerge from outdoor-origin apparel parents extending into athleisure adjacent markets, offering brand equity without technical textile R&D overhead. Long-term viability hinges on circular infrastructure ownership as state-level take-back mandates crystallize. Monitor FTC Green Guides enforcement intensity as inflection signal for compliance-cost winners versus losers.
| Strategic Initiative | Industry Significance |
|---|---|
| Seamless Knitting Capacity Expansion | Taiwanese and Vietnamese CM partnerships reduce labor costs and chafe points for mid-tier price bands. |
| Bio-Based Elastomer Supply Agreement | Castor oil and algae fermentation partnerships render petroleum-derived spandex obsolete in premium lines. |
| Direct-to-Consumer Channel Buildout | AR virtual try-on integration captures Toronto and Vancouver suburban demand without specialty store rent premiums. |
| Circular Infrastructure Investment | Pre-emptive take-back program development secures first-mover advantage under pending California and New York EPR legislation. |
| Medical-Grade Compression Launch | Recovery wear reimbursement through health savings accounts opens defensible niche against lifestyle-brand incumbents. |
Research Approach
A spread of perspectives from brand supply chain directors, boutique fitness studio owners, corporate wellness program administrators, and direct-to-consumer platform operators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, customs and trade data for synthetic textile imports, and California SB 657 disclosure databases. Bottom-up demand modeling across product categories triangulated with top-down market sizing from retail audit data.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeled by product type, end user demographic, distribution channel, and price tier. CAGRs derived from historical volume trajectories adjusted for hybrid work policy diffusion rates and corporate wellness stipend expansion. Forecast inputs incorporated polymer science talent pipeline constraints and state-level extended producer responsibility legislative tracking.
Stress conditions across petrochemical feedstock volatility, geopolitical disruption in Asian dyehouse regions, and FTC Green Guides enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hybrid work permanence and bio-based elastomer cost curves. Quarterly review of state EPR bill progression and virtual try-on technology adoption metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Global Laptop Skins Market
Consumer Goods
Tobacco Products Market
Consumer Goods
Commercial Lawnmower Market
Consumer Goods
Thailand Retail Market
Consumer Goods
Lawn Roller Market
Consumer Goods
Leaf Blower Market
Consumer Goods
Command Hooks Market
Consumer Goods
Anti-Fog Lens Market
Consumer Goods
Children Shoes Market
Consumer Goods
GCC E-Cigarette Market
Consumer Goods
US Cosmetics Market
Consumer Goods
Consumer Electronics Retail Market
Consumer Goods
Dog Hats Market
Consumer Goods
Compound Bow and Crossbows Market
Consumer Goods
Paw Plunger Market
Consumer Goods
New Smart Wardrobe Market