
 North America Affordable Housing Market | 2026-2036
North America Affordable Housing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Affordable Housing Market Insights
Multi-family dwelling development for low-income families is expanding across the southern United States. The NRP Group leverages its vertical integration from land acquisition to property management to control costs in high-growth metros. Alliance Residential Company competes through geographic concentration in Sun Belt states where zoning flexibility supports higher-density projects. Greystar Real Estate Partners dominates the institutional capital channel, anchoring pension fund flows into tax credit partnerships.
Affordable housing denotes residential units priced below area median income thresholds, typically requiring households to spend no more than thirty percent of income on housing costs including utilities. Construction methods span stick-built, modular, and manufactured housing with energy efficiency standards governed by HUD Code for manufactured homes and local building codes for site-built units. Multi-family dwellings command the largest share of new affordable unit production, while modular homes represent the fastest-growing segment as factory fabrication compresses delivery timelines and labor exposure. First-time buyers and low-income families form the deepest customer pools, though senior-focused developments attract higher per-unit subsidy levels through HUD Section 202 and state bond programs.
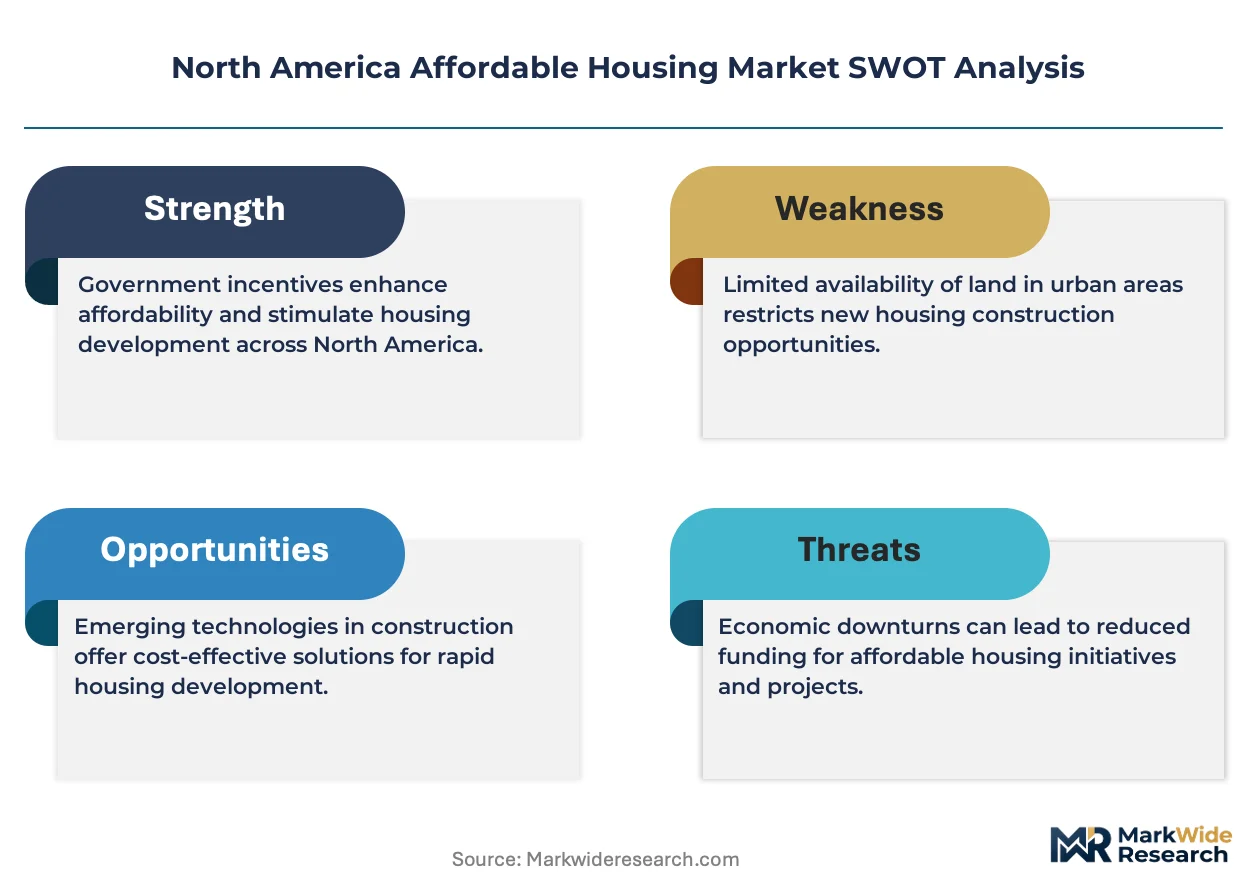
The Department of Housing and Urban Development, state housing finance agencies, and the Internal Revenue Service collectively shape market access through LIHTC allocation, Section 8 voucher administration, and Fair Housing Act enforcement. Local inclusionary ordinances in California and Massachusetts mandate set-asides or in-lieu fees, redirecting market-rate developer capital into below-market production. Stakeholders must monitor interest rate trajectories and municipal zoning liberalization as these forces determine whether projected unit volumes materialize or shift toward market-rate alternatives.
Market Dynamics
The Low-Income Housing Tax Credit program channels institutional capital into below-market units while local inclusionary zoning mandates force market-rate developers to cross-subsidize affordable production, fundamentally restructuring project economics across the United States and Canada.
Growth Catalysts
- LIHTC allocation authority:The Internal Revenue Service allocates tax credits to state housing finance agencies, which award them to developers through competitive qualified allocation plans. This mechanism anchors approximately ninety percent of new affordable rental construction in the United States.
- Modular fabrication methods:Factory-built components compress construction timelines by forty to sixty percent versus stick-built alternatives. Developers in high-cost labor markets deploy this technology to reduce wage exposure and accelerate lease-up.
- Sun Belt population concentration:Texas, Florida, and Arizona absorb domestic migration flows that outpace housing supply. Municipalities in these states exhibit greater zoning flexibility for higher-density multi-family projects than coastal jurisdictions.
Market Restraints
- Lumber and steel price volatility:Commodity input swings compress development margins during the twelve-to-eighteen month construction window. Fixed-rate LIHTC equity cannot absorb material cost spikes without sponsor capital calls.
- Construction labor scarcity:Skilled trades concentration in non-residential sectors leaves affordable housing projects competing for electricians and plumbers. Union jurisdictions in the Northeast and Pacific Coast amplify wage pressure.
- Site control competition:Market-rate developers and industrial warehouse operators bid land prices beyond affordable housing pro formas. Land banking by public entities remains underdeveloped in most metropolitan areas.
Strategic Opportunities
- Conversion of obsolete commercial stock:Vacant office buildings in downtown cores present adaptive reuse candidates for mixed-income housing. Federal and state historic rehabilitation tax credits stack with LIHTC to improve feasibility.
- Native American tribal development:The Indian Housing Block Grant and Title VI loan guarantee programs support tribally designated housing entities. These sovereign jurisdictions operate outside certain local zoning constraints.
- Utility allowance restructuring:HUD's proposed reforms to utility reimbursement methodologies would reward energy-efficient design. Developers incorporating solar thermal and heat pump systems capture operating reserve advantages.
Industry Challenges
- Compliance monitoring capacity:Property managers must verify tenant income eligibility annually across dispersed portfolios. Software systems for income calculation and documentation remain fragmented across state housing finance agency requirements.
- Resyndication timeline compression:Fifteen-year LIHTC compliance periods expire, triggering complex refinancing and rehabilitation decisions. Sponsor teams must coordinate investor exits, new equity placement, and construction sequencing within narrow windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Affordable Housing Market |
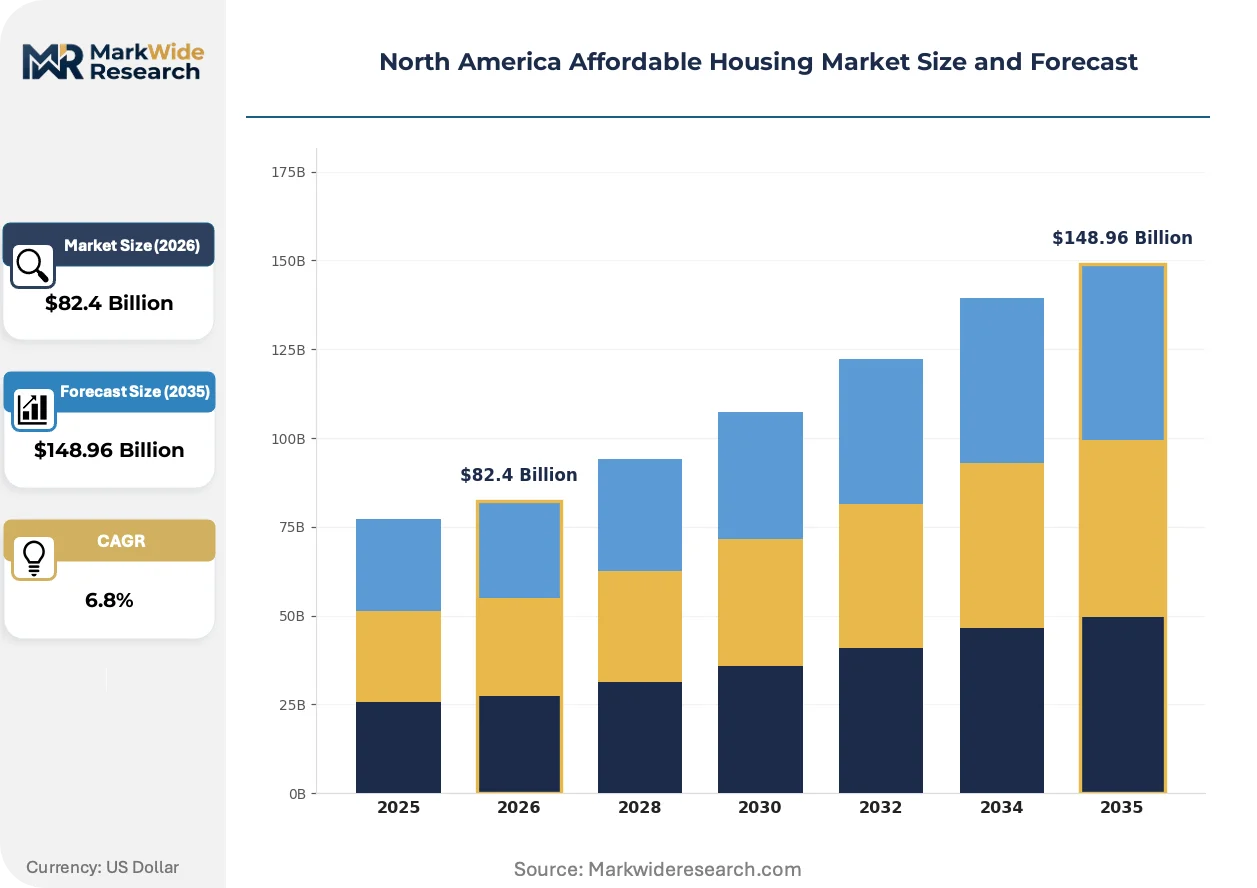
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $148.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Family Homes, Multi-Family Dwellings, Modular Homes, Tiny Houses Customer Type: First-Time Buyers, Low-Income Families, Seniors, Veterans Financing Model: Government Subsidies, Low-Interest Loans, Grants, Non-Profit Funding Development Stage: Pre-Construction, Under Construction, Completed, Renovated |
| Companies Covered | The NRP Group, The Michaels Organization, Lincoln Avenue Communities, Alliance Residential Company, TWG Development, Dominium, Greystar Real Estate Partners, Mercy Housing, The Pacific Companies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Affordable Housing Market Trends and Innovations
Capital deployment patterns and construction methodologies are diverging sharply between jurisdictions with active zoning reform and those preserving exclusionary single-family districts. Three forces dominate this bifurcation.
Modular construction is decentralizing project delivery by enabling factory fabrication far from final sites. Developers in Ontario and the southern United States contract with plants in Indiana and Alabama to supply wall panels and bathroom pods. This geography-agnostic sourcing compresses local labor requirements and permits year-round production regardless of site conditions.
California's Senate Bill 35 mandates ministerial approval for affordable housing projects in jurisdictions failing regional housing needs allocation targets. The law strips local councils of discretionary review authority, cutting entitlement timelines from thirty-six months to under twelve. Developers report accelerated capital commitment from institutional investors previously deterred by political risk.
Renter household formation is fragmenting traditional site selection models. Workforce housing demand now concentrates near logistics hubs and medical districts rather than central business districts. Developers in Dallas-Fort Worth and Phoenix are acquiring industrial-adjacent parcels previously rejected for residential use, capitalizing on commute-time preferences of warehouse and hospital employees.
North America Affordable Housing Market Segmentation
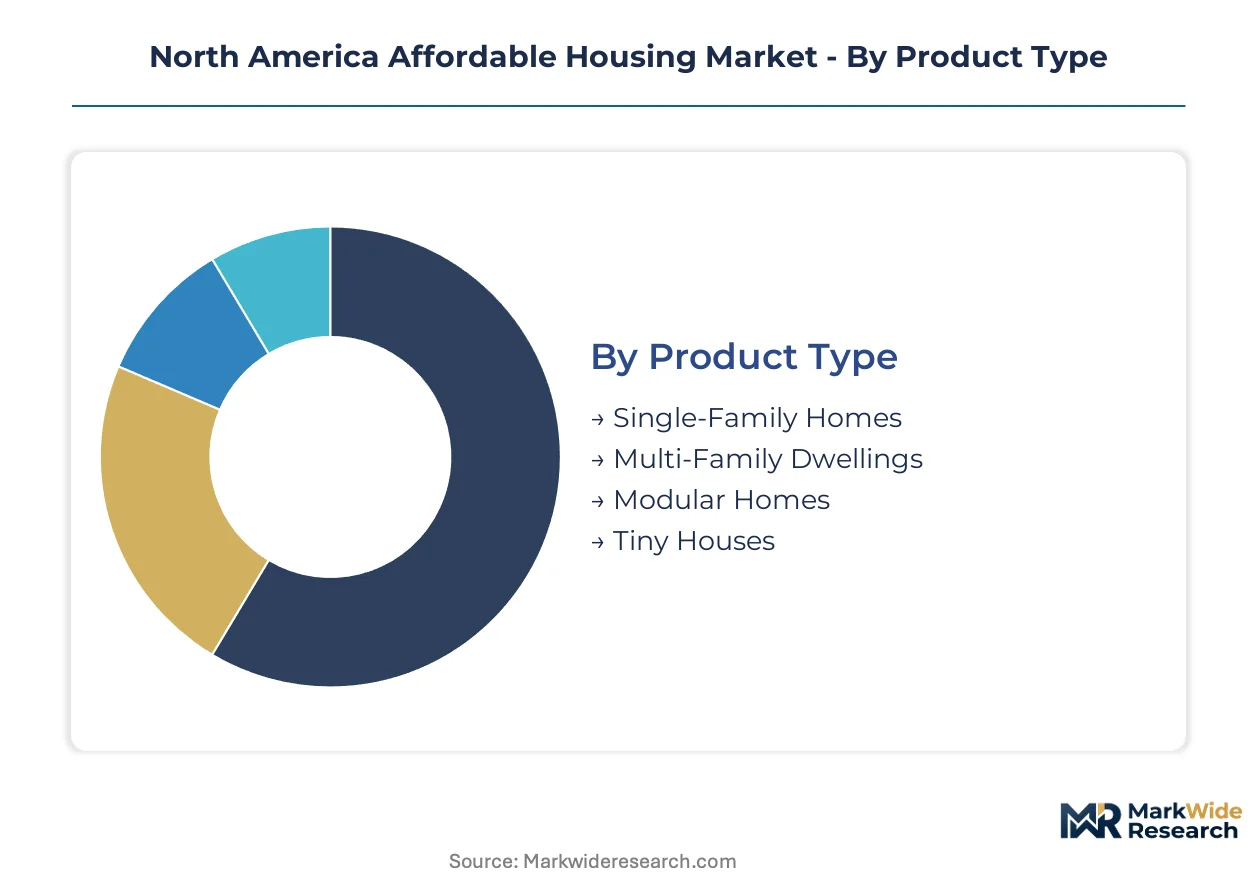
Segmentation in affordable housing reveals how regulatory requirements, subsidy structures, and construction methodologies fragment production economics across distinct customer pools. Developers must match product specifications to financing eligibility rules that vary by income tier and household composition.
Product Type:
HUD Code certification governs manufactured housing, while site-built units fall under local building codes with LIHTC compliance adding layered documentation requirements.
- Multi-Family Dwellings:Structures containing five or more rental units dominate LIHTC-funded production. Texas and California municipalities approve these projects at three times the rate of single-family permits due to density bonuses and parking requirement waivers.
- Modular Homes:Factory-built components assembled on-site compress construction timelines by forty to sixty percent versus stick-built alternatives. Ontario developers source wall panels from Indiana plants to bypass local labor scarcity and accelerate lease-up in Toronto's undersupplied corridors.
- Single-Family Homes:Detached units serve Native American tribal developments and rural scattered-site programs. USDA Section 502 direct loans support acquisition in designated rural service areas.
- Tiny Houses:Units under four hundred square feet face zoning restrictions in most incorporated areas. Oregon and Maine have adopted specialty building codes permitting these structures as accessory dwelling units.
Multi-Family Dwellings sits at the top of the volume ranking, with Modular Homes climbing the fastest.
Customer Type:
Subsidy tiers create four distinct pricing bands based on area median income thresholds and specialized federal program eligibility.
- Low-Income Families:Households earning below fifty percent of area median income qualify for Section 8 vouchers and LIHTC units. Texas Housing Finance Corporation prioritizes this segment in qualified allocation plans, directing tax credits to projects with deeper affordability commitments.
- Seniors:Adults aged sixty-two and above access HUD Section 202 capital advances and state bond programs. These developments command higher per-unit subsidy levels due to accessibility mandates and service coordination requirements.
- First-Time Buyers:FHA-insured mortgages with three percent down payment thresholds serve this segment. State housing finance agencies in California and Massachusetts layer closing cost assistance atop federal programs.
- Veterans:VA direct and guaranteed loans eliminate down payment requirements for eligible service members. Native American veterans access specialized loan programs through tribally designated housing entities.
Low-Income Families captures the largest addressable population, while Seniors shows the steepest expansion trajectory due to demographic aging in Florida and Arizona.
Financing Model:
Capital stack complexity varies from nine percent LIHTC syndications to simple grant-funded tribal developments with no investor exit requirements.
- Government Subsidies:LIHTC allocations from state housing finance agencies anchor ninety percent of new affordable rental construction. Investors purchase tax credits through partnership structures, with compliance periods extending fifteen years.
- Low-Interest Loans:FHA-insured mortgages and USDA Section 502 programs reduce borrowing costs below market rates. State housing finance agencies issue tax-exempt bonds to fund these products.
- Grants:Community Development Block Grants and HOME Investment Partnerships provide gap financing. These sources require no repayment but impose Davis-Bacon prevailing wage requirements on construction.
- Non-Profit Funding:Community development financial institutions and philanthropic capital fill financing gaps in high-cost markets. These sources accept below-market returns to preserve long-term affordability.
Government Subsidies structures the largest capital deployment, with Non-Profit Funding gaining share fastest in coastal markets where conventional yields fail to clear pro forma hurdles.
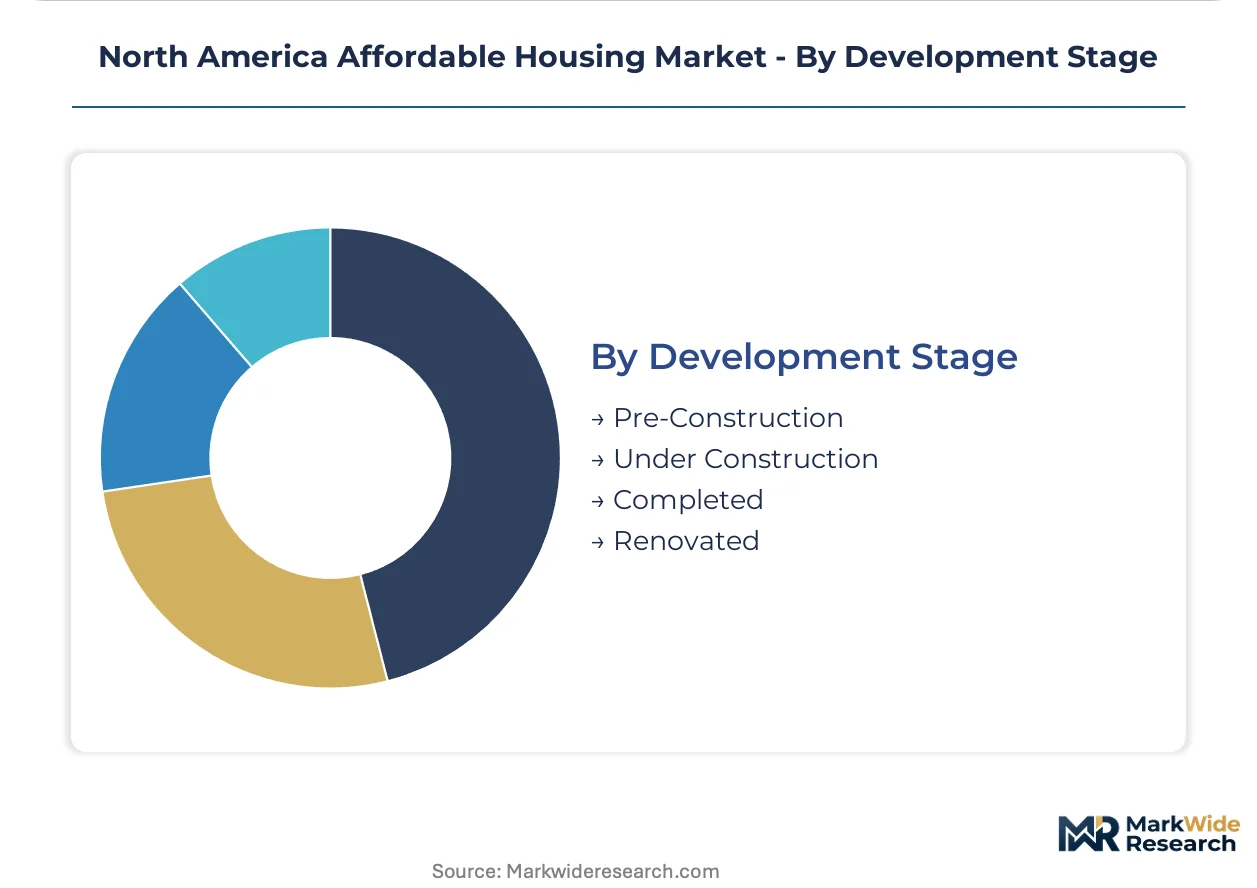
Development Stage:
Risk profiles and investor return expectations shift dramatically from raw land entitlement through stabilized lease-up and eventual resyndication.
- Pre-Construction:Land acquisition and entitlement consume twelve to thirty-six months in jurisdictions with discretionary review. California Senate Bill 35 mandates ministerial approval for affordable projects in non-compliant jurisdictions, compressing timelines.
- Under Construction:Fixed-price contracts with modular fabricators reduce cost overrun exposure. Union jurisdictions in the Northeast and Pacific Coast amplify wage pressure during this phase.
- Completed:Stabilized properties generate tax credit benefits and depreciation shields for institutional investors. Property managers must verify tenant income eligibility annually across dispersed portfolios.
- Renovated:Resyndication of fifteen-year LIHTC compliance period expirations triggers complex refinancing decisions. Federal and state historic rehabilitation tax credits stack with new LIHTC allocations to improve feasibility.
Completed assets hold the largest institutional capital allocation, with Renovated projects expanding most quickly as the LIHTC program matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Developers exploit cost-of-compliance gaps between jurisdictions, shifting capital from high-barrier coastal markets to Sun Belt states with streamlined entitlement procedures and flexible zoning codes. This arbitrage accelerates project velocity and compresses carry costs.
United States
Texas and Florida absorb domestic migration flows that outpace housing supply, with Austin and Miami metros approving multi-family permits at triple the rate of coastal peers. California's Senate Bill 35 mandates ministerial approval for affordable projects in non-compliant jurisdictions, stripping local councils of discretionary review authority. Dallas-Fort Worth developers acquire industrial-adjacent parcels near logistics hubs, capitalizing on commute-time preferences of warehouse employees.
Canada
Ontario's population growth concentrates in Toronto's undersupplied corridors, where developers source modular wall panels from Indiana plants to bypass local labor scarcity. The Canada Mortgage and Housing Corporation administers National Housing Strategy funding, layering low-interest loans atop provincial land assembly programs. Vancouver's inclusionary zoning mandates redirect market-rate developer capital into below-market production through set-aside requirements.
Mexico
Manufacturing corridor expansion near Monterrey and Tijuana generates workforce housing demand from maquiladora employees earning below median income thresholds. INFONAVIT, the federal housing finance agency, channels payroll deductions into mortgage liquidity for formal sector workers. Developers in Nuevo León deploy prefabricated construction methods to accelerate delivery timelines for automotive supplier communities.
North America Affordable Housing Market Competitive Landscape
Geographic concentration dominates the current landscape, with developers staking positions in high-growth metros where zoning flexibility supports higher-density entitlement. The market structures around three tiers: vertically integrated national platforms controlling land-to-lease pipelines, regional specialists exploiting local political relationships, and mission-driven nonprofits prioritizing permanent affordability over yield. Consolidation pressures intensify as institutional capital favors sponsors with multi-state operating platforms and proven LIHTC compliance track records.
Among vertically integrated developers, The NRP Group and Alliance Residential Company exemplify the national-platform archetype, anchoring pension fund flows into tax credit partnerships across Sun Belt states. Greystar Real Estate Partners occupies a distinct position at the institutional capital channel, syndicating equity for large-scale multi-family portfolios. These three entities collectively represent how scale and geographic diversification attract limited partner commitments in a subsidy-dependent asset class.
| Leading Market Players |
|---|
| The NRP Group |
| The Michaels Organization |
| Lincoln Avenue Communities |
| Alliance Residential Company |
| TWG Development |
| Dominium |
| Greystar Real Estate Partners |
| Mercy Housing |
| The Pacific Companies |
| Others |
Pricing and Supply Chain Analysis
Electrician and plumber concentration in Texas and Florida creates labor-cost differentials that widen pricing-tier spreads between Sun Belt developments and Northeast projects. Developers in union jurisdictions face wage premiums that compress margins on LIHTC-financed units, while southern states attract capital seeking lower construction cost bases.
Pricing Analysis
Direct-to-institutional-investor syndication discounts dominate the capital stack, with nine-percent LIHTC equity pricing stratifying across premium, standard, and economy tiers based on sponsor track record and geographic risk. Price differentiation hinges on state housing finance agency allocation competitiveness and local zoning certainty. Cost compression in standard-tier projects is intensifying because lumber and steel volatility erodes fixed-price contract viability. Non-profit developers exhibit highest price sensitivity due to limited sponsor guarantee capacity, while vertically integrated national platforms command lowest capital costs.
Supply Chain Analysis
HUD Code certification and state housing finance agency compliance documentation gate entry for manufactured housing suppliers and modular fabricators. Factory-built component production concentrates in Indiana, Alabama, and Ontario, drawing from Canadian lumber and U.S. steel feedstocks. Supply chain risk centers on single-source vulnerability for bathroom pods and electrical panel assemblies. Distribution runs through developer-procurement teams coordinating just-in-time delivery to construction sites across dispersed metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California's Senate Bill 35 ministerial approval mandates against Texas local discretion requirements frame this market as a geographic-arbitrage play, with entitlement timeline differentials creating twenty-four-month cost advantages for Sun Belt capital deployment.
For Market Incumbents: Deploy modular fabrication partnerships to compress construction timelines and reduce wage exposure in high-cost labor markets. Consolidate land positions in Dallas-Fort Worth and Phoenix logistics corridors before industrial warehouse operators bid parcels beyond residential pro formas. Threat substitution from market-rate developers accessing inclusionary zoning in-lieu fee options demands preemptive site control in jurisdictions with flexible density bonuses. For New Entrants and Emerging Players: Canada's National Housing Strategy low-interest loan programs in Ontario open a window for U.S. modular fabricators to establish cross-border supply relationships. Target tribal development opportunities under Indian Housing Block Grant programs, where sovereign jurisdiction bypasses local zoning constraints. Go-to-market leverage rests on partnering with tribally designated housing entities for Title VI loan guarantee access. For Investors and Strategic Acquirers: Pension fund capital providers are the most active acquirer in this space, seeking yield replacement in fixed-income portfolios through LIHTC equity placements. Long-term viability hinges on resyndication pipeline depth as fifteen-year compliance periods mature. Watch state housing finance agency allocation authority expansions as the inflection indicator for capital deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Fabrication Scale-Up | Factory-built wall panels from Indiana plants bypass Toronto labor scarcity and accelerate Ontario lease-up. |
| LIHTC Resyndication Pipeline | Fifteen-year compliance period expirations create refinancing demand for new equity placement and rehabilitation sequencing. |
| Tribal Development Partnership | Sovereign jurisdiction access through Indian Housing Block Grant programs unlocks land outside municipal zoning constraints. |
| Sun Belt Geographic Expansion | Texas and Florida entitlement flexibility supports triple the multi-family permit velocity of coastal jurisdictions. |
| Commercial Adaptive Reuse | Federal historic rehabilitation tax credits stacking with LIHTC improve feasibility for obsolete downtown office conversions. |
Research Methodology
Bottom-up LIHTC allocation modeling reconciled against top-down construction permit tracking forms the analytical core of this study. Primary interviews with state housing finance agency directors, LIHTC syndication executives, modular fabrication plant managers, and tribal housing entity administrators combine with secondary validation from HUD program data, Canada Mortgage and Housing Corporation funding disclosures, and state qualified allocation plan filings. Triangulation between sponsor-reported development costs and municipal permit records ensures volume estimates align with actual construction activity.
Input-output matrices map tax credit equity flows to geographic production clusters across the projection horizon. Segmentation dimensions modeled include product type, customer income tier, financing model complexity, and development stage risk profile. CAGRs derive from slope analysis of annual unit completion trajectories moderated by interest rate sensitivity and zoning liberalization indices. Forecast inputs incorporate state-level inclusionary ordinance adoption timelines and federal LIHTC allocation authority renewal patterns.
Revisions become necessary when interest rate trajectories shift materially, municipal zoning reforms accelerate or stall, or commodity input volatility exceeds historical bands. Deviation in state housing finance agency competitive scoring criteria would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
United States Commercial Real Estate Market
Real Estate
Hungary Warehousing Sector Market
Real Estate
Global Facility Management Software Market
Real Estate
Smart Building Market
Real Estate
Indonesia Real Estate Market
Real Estate
Egypt Condominiums and Apartments Market
Real Estate
Bahrain Co-Working Office Space Market
Real Estate
Armenia Real Estate Market
Real Estate
Bahrain Luxury Residential Real Estate Market
Real Estate
UAE Commercial Real Estate Market
Real Estate
India Home Mortgage Finance Market
Real Estate
Mortgage Brokerage Services Market
Real Estate
Austria Facility Management Market
Real Estate
India Office Real Estate Market
Real Estate
Egypt Commercial Real Estate Market
Real Estate
US Property Management Software Market