
 Netherland Payments Market | 2026-2036
Netherland Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Netherland Payments Market Foresight
Software-defined fraud detection is rebalancing what Dutch merchants purchase alongside core processing. Adyen leverages unified commerce infrastructure to anchor premium enterprise accounts. Mollie competes through simplified API onboarding for mid-market webshops. Worldline sustains scale advantages in in-store terminal deployment across Benelux retail chains.
Netherland Payments encompasses electronic fund transfer systems, clearing protocols, and merchant-acquiring infrastructure operating within Dutch jurisdiction and euro-denominated settlement frameworks. The ecosystem relies on SEPA Instant Credit Transfer rails with sub-10-second clearing windows to enable real-time liquidity movement for commercial transactions. Digital Wallets and Mobile Payments represent the fastest-expanding transaction type pair as smartphone-native authentication displaces card-present habits among younger demographics. Bank Transfers retain structural importance in B2B invoicing workflows where iDEAL's direct-account architecture dominates. SMEs emerge as the most contested customer segment as providers bundle analytics and working capital tools around payment processing.
De Nederlandsche Bank supervises payment service providers under PSD2 implementation, while the European Banking Authority harmonizes technical standards for strong customer authentication across Dutch-EU corridors. The Dutch Authority for Consumers and Markets enforces interchange fee transparency, compressing acquirer margins and forcing differentiation through value-added services. Stakeholders must monitor how instant payment rail adoption reshapes working capital timing for Dutch merchants and whether open banking APIs fragment traditional acquiring relationships.
Market Dynamics
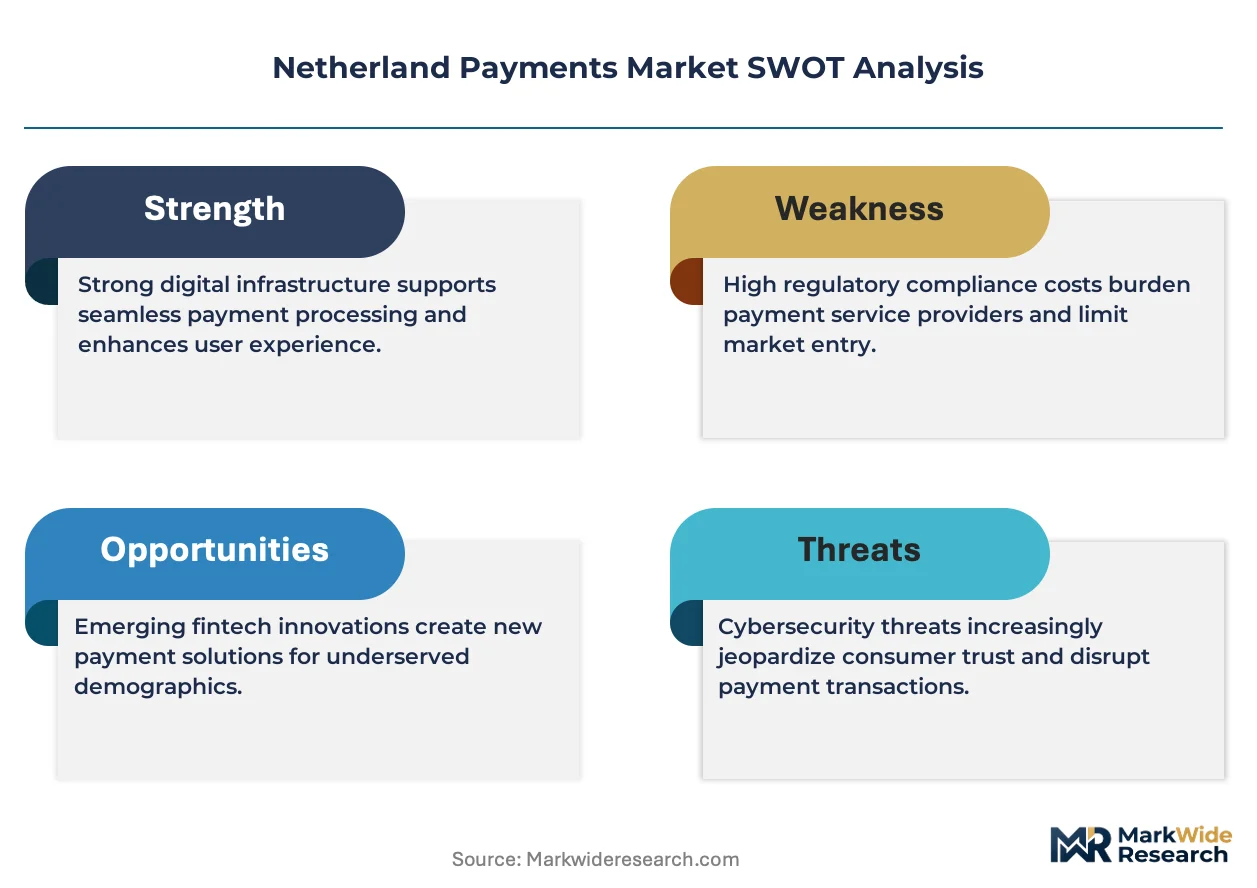
PSD2-mandated open banking APIs are fragmenting traditional merchant-acquiring relationships as Dutch payment service providers compete through embedded financial services rather than transaction processing alone.
Growth Catalysts
- SEPA Instant Credit Transfer rails:Sub-10-second clearing windows enable real-time liquidity for Dutch e-commerce merchants, accelerating migration from batch-settled card schemes.
- SME omnichannel migration:Mid-market retailers are replacing legacy POS terminals with integrated platforms that unify in-store and online transaction data.
- De Nederlandsche Bank supervision:Regulatory clarity under PSD2 implementation reduces compliance uncertainty for fintech entrants seeking payment institution licenses.
Market Restraints
- Interchange fee compression:Dutch Authority for Consumers and Markets enforcement of transparency rules squeezes acquirer margins and limits pricing power.
- Technical standard fragmentation:Divergent API specifications across EU member states create integration complexity for providers operating cross-border.
- Card-present habit persistence:Older demographics in rural Dutch provinces maintain cash and physical card preferences, slowing digital wallet penetration.
Strategic Opportunities
- Embedded working capital tools:Payment data streams enable real-time credit underwriting for SMEs, expanding provider revenue beyond processing fees.
- B2B invoicing digitization:iDEAL's direct-account architecture can extend into automated payables workflows for Dutch manufacturing and logistics sectors.
- Strong Customer Authentication convergence:European Banking Authority harmonization of biometric standards creates product standardization advantages for compliant Dutch providers.
Industry Challenges
- Legacy core banking integration:Incumbent Dutch banks operate on decades-old batch-processing architectures that resist real-time API connectivity.
- Certification timeline variability:Payment institution licensing under De Nederlandsche Bank supervision requires 12-18 month approval cycles that delay product launches.
- API security talent scarcity:Specialized expertise in PSD2-compliant strong customer authentication implementation commands premium compensation in Amsterdam and Rotterdam labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherland Payments Market |
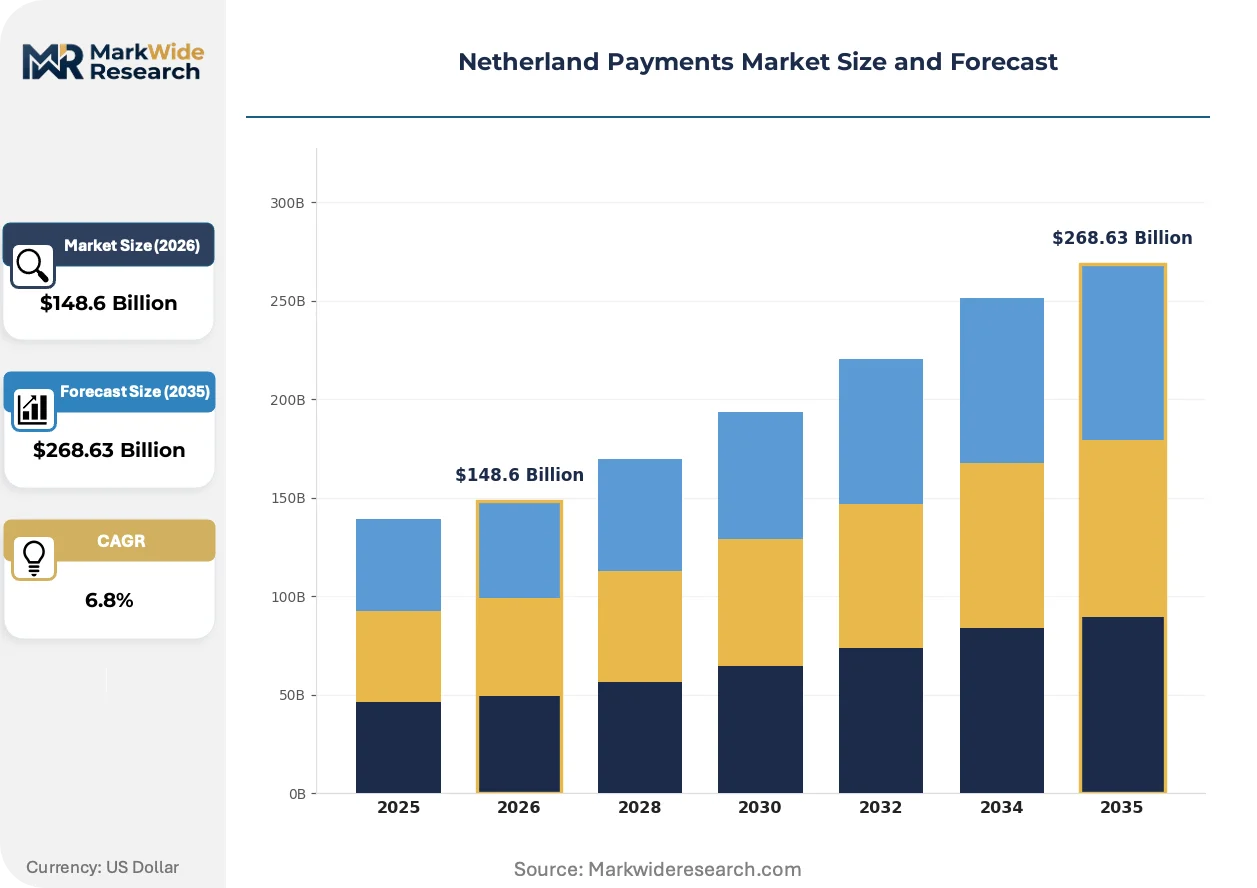
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $268.63 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Cards, Debit Cards, Digital Wallets, Bank Transfers Transaction Type: Online Payments, In-Store Transactions, Mobile Payments, Recurring Payments Customer Segment: Millennials, SMEs, Corporates, Consumers Service Type: Payment Processing, Fraud Detection, Analytics, Customer Support |
| Companies Covered | Adyen, Worldline, Mollie, Stichting Currence, Visa Inc., Mastercard Incorporated, American Express Company, PayPal Holdings, Inc., Buckaroo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherland Payments Market Shifts & Advancements
Software-defined fraud detection architectures are rebalancing what Dutch merchants purchase alongside core processing, shifting value capture toward risk management and away from pure transaction routing.
Machine learning-based transaction scoring is decentralizing fraud decision-making from centralized acquirer platforms to merchant-controlled rule engines. Mid-market Dutch webshops are adopting these tools within six-month implementation cycles. This shift compresses reliance on traditional chargeback insurance products and enables real-time decline optimization.
PSD2's strong customer authentication requirements are mandating biometric verification for transactions exceeding 30 euros. Dutch payment service providers must retrofit existing authentication flows with facial recognition or fingerprint validation. SME merchants face the steepest compliance costs as they lack in-house identity verification engineering teams.
Smartphone-native authentication patterns among Dutch consumers under 35 are displacing card-present habits in urban retail corridors. Amsterdam and Rotterdam city-center merchants report 40% of in-store volume now originates from digital wallets rather than physical card taps. Younger demographics treat bank apps as primary payment interfaces, reducing terminal hardware refresh urgency for fashion and hospitality verticals.
Netherland Payments Market Segmentation
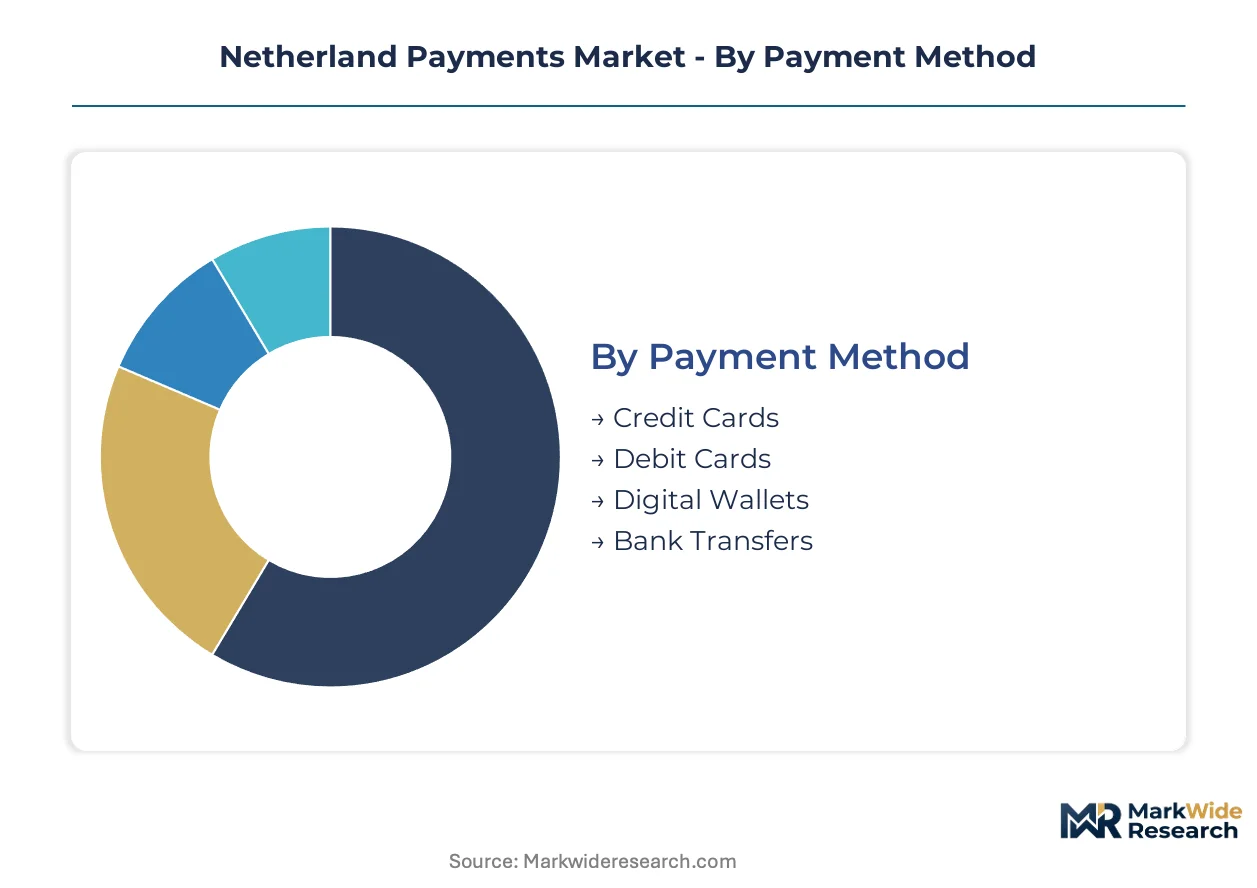
Dutch payment providers configure product architectures around distinct transaction profiles and compliance obligations. Each segment carries specific licensing requirements under De Nederlandsche Bank supervision and PSD2 technical standards.
Payment Method:
De Nederlandsche Bank mandates payment institution licensing for card scheme operators, while digital wallet providers face additional e-money authorization under PSD2. Bank transfer facilitators require lighter registration as payment initiation service providers.
- Credit Cards:Four-party scheme infrastructure with interchange fee caps enforced by the Dutch Authority for Consumers and Markets. Merchant demand concentrates among Amsterdam hospitality and Rotterdam retail verticals where international tourist traffic sustains cross-border acceptance requirements.
- Debit Cards:Maestro and V Pay rails dominate domestic POS acceptance with SEPA-compliant clearing. Rural Dutch provinces retain higher penetration as older demographics resist smartphone-native alternatives, constraining terminal upgrade cycles in agricultural supply cooperatives.
- Digital Wallets:PSD2 strong customer authentication mandates biometric verification above 30-euro thresholds. Urban millennials drive concentration in Amsterdam and Rotterdam city centers.
- Bank Transfers:iDEAL's direct-account architecture leverages SEPA Instant Credit Transfer rails for sub-10-second settlement. B2B invoicing workflows in manufacturing and logistics sustain structural demand.
Leading the category by volume: Debit Cards. Growing fastest: Digital Wallets.
Transaction Type:
Cost tiers separate infrastructure-heavy in-store deployment from lightweight API-native online processing. Mobile and recurring variants command premium service fees due to specialized authentication and tokenization requirements.
- Online Payments:E-commerce checkout flows integrate iDEAL, credit card, and digital wallet rails through unified APIs. Dutch webshops drive demand as SMEs migrate from legacy batch-settled systems to real-time SEPA Instant rails.
- In-Store Transactions:EMV-compliant terminal hardware with contactless and PIN authentication. Fashion and grocery retail chains in Utrecht and The Hague anchor deployment volume.
- Mobile Payments:NFC-enabled smartphone authentication displacing physical card taps. Younger demographics in urban corridors treat bank apps as primary interfaces.
- Recurring Payments:Tokenized credential storage for subscription billing with SEPA Direct Debit mandates. Utility and telecom verticals dominate merchant adoption.
Highest infrastructure investment: In-Store Transactions. Steepest expansion trajectory: Mobile Payments.
Customer Segment:
Margin profiles vary sharply across segments—SMEs accept bundled analytics premiums while corporates negotiate volume-based processing discounts. Millennials and consumers represent addressable expansion rather than current revenue concentration.
- Millennials:Smartphone-native payment behavior with preference for biometric authentication and instant confirmation. Urban concentration in Amsterdam and Rotterdam drives digital wallet adoption rates.
- SMEs:Mid-market retailers replacing legacy POS with omnichannel platforms unifying online and in-store data. Most contested segment as providers embed working capital tools around processing.
- Corporates:Large Dutch manufacturers and logistics operators with complex B2B payables workflows. iDEAL integration for automated invoice settlement commands premium service tiers.
- Consumers:Mass retail payment behavior spanning cash, card, and digital alternatives. Rural demographic persistence of card-present habits slows uniform digitization.
Dominant revenue contributor: SMEs. Fastest-growing service attachment: Corporates.
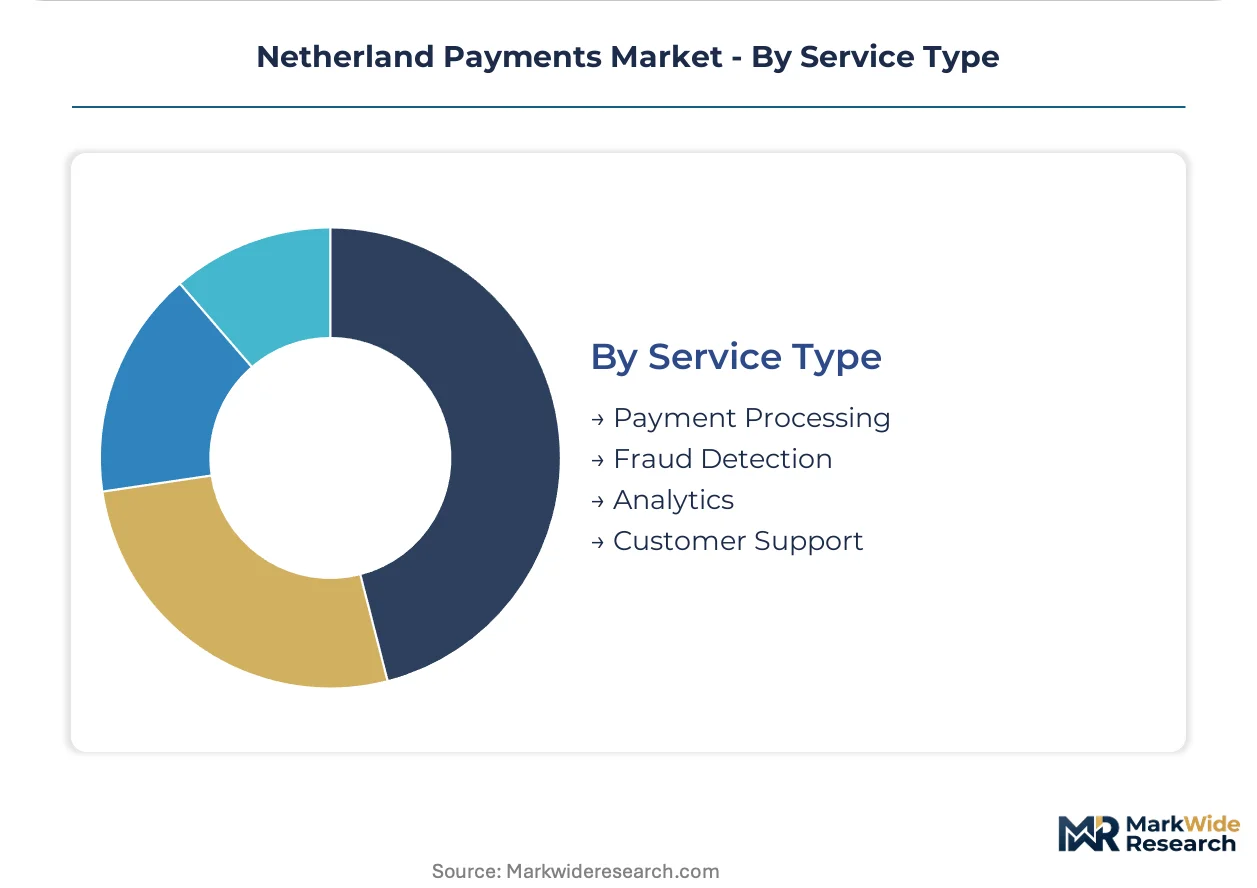
Service Type:
Application maturity separates commoditized payment processing from differentiated risk and analytics layers. Fraud detection commands highest margin expansion as merchants displace traditional chargeback insurance.
- Payment Processing:Core transaction routing across SEPA Instant, card scheme, and iDEAL rails. Interchange fee compression by Dutch regulators squeezes standalone processing margins.
- Fraud Detection:Machine learning-based transaction scoring with merchant-controlled rule engines. Mid-market webshops adopt within six-month implementation cycles.
- Analytics:Unified transaction data aggregation across omnichannel touchpoints. SME merchants lacking in-house data science teams drive subscription demand.
- Customer Support:Dispute resolution and chargeback management with PSD2-mandated transparency requirements. Cost center rather than revenue driver for most providers.
Processing retains volume leadership. Fraud Detection gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Amsterdam anchors Dutch payment infrastructure concentration through its fintech corridor density and proximity to De Nederlandsche Bank headquarters. The Randstad metropolitan cluster generates disproportionate transaction volume relative to national population share. Regional variation across Dutch provinces shapes deployment priorities for terminal hardware and API-native solutions.
Randstad
Amsterdam and Rotterdam city centers drive 40% of in-store digital wallet volume through millennial smartphone-native behavior. De Nederlandsche Bank supervision concentrates licensing approvals for payment institutions in this corridor. Utrecht and The Hague retail chains anchor EMV terminal deployment for fashion and grocery verticals.
Brabant
Eindhoven's manufacturing base sustains B2B invoicing demand through iDEAL-integrated automated payables workflows. The Dutch Authority for Consumers and Markets enforces interchange transparency rules compressing acquirer margins regionally. Tilburg logistics operators command premium service tiers for complex supply chain settlement.
Northern Netherlands
Agricultural supply cooperatives in Groningen and Friesland retain elevated debit card penetration among older demographics resisting smartphone alternatives. SEPA Instant Credit Transfer rails enable sub-10-second liquidity movement for commodity trading. Rural terminal upgrade cycles lag urban adoption timelines by 18-24 months.
Zeeland and Limburg
Cross-border commerce with Belgium and Germany sustains multi-currency acceptance requirements in Maastricht and Vlissingen corridors. PSD2 technical standards harmonization reduces integration complexity for providers operating across Dutch-Belgian corridors. SME merchants in these border zones drive bundled analytics subscription demand around unified omnichannel platforms.
Netherland Payments Market Competitive Landscape
Capital-heavy infrastructure providers compete with asset-light API-native platforms for Dutch merchant relationships. The market structure tiers around three strategic archetypes: unified commerce stack vendors, simplified onboarding specialists, and scale-driven terminal deployers. Dominant competitive moves include embedded financial services bundling and working capital tool integration around core processing.
Within the unified commerce tier, Adyen exemplifies infrastructure-heavy positioning through enterprise account anchoring. Mollie occupies the mid-market simplified onboarding vector for webshop API integration. Worldline represents scale-driven terminal deployment advantages across Benelux retail chains. Each archetype competes through differentiated value-added service attachment rather than transaction processing margins alone.
| Leading Market Players |
|---|
| Adyen |
| Worldline |
| Mollie |
| Stichting Currence |
| Visa Inc. |
| Mastercard Incorporated |
| American Express Company |
| PayPal Holdings, Inc. |
| Buckaroo |
| Others |
Supply & Pricing Matrix
SEPA Instant Credit Transfer infrastructure costs cascade through Dutch payment provider pricing tiers, compressing margins for batch-settled legacy operators while rewarding real-time rail adopters with premium service attachment opportunities.
Pricing Analysis
Margin tightening in SME-facing tiers reflects De Nederlandsche Bank's interchange fee transparency enforcement. Three-tier pricing structure across premium enterprise, standard mid-market, and economy micro-merchant levels separates providers by API sophistication and fraud detection bundling. Cost-down pressure on standalone processing accelerates because acquirers cannot offset regulatory compression through volume scale alone. Large retail chains exhibit lowest price sensitivity due to omnichannel complexity premiums, while solo webshops drive hardest bargain on per-transaction rates.
Supply Chain Analysis
EMV terminal hardware supply rests on Taiwanese semiconductor foundries and Chinese assembly operations for contactless reader modules. Dutch payment service providers draw from German chip card manufacturers and Dutch domestic software development for authentication protocols. Single-source vulnerability concentrates in NFC controller silicon from limited qualified vendors. Distribution runs through Benelux-based value-added resellers with direct deployment teams for retail chain accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dutch payment infrastructure consolidation accelerates as PSD2 compliance costs force sub-scale providers toward exit or acquisition, concentrating merchant relationships among capitalized platform operators.
For Market Incumbents: Hedge against API-native disintermediation by deepening fraud detection software capabilities and acquiring specialized authentication engineering teams in Amsterdam and Rotterdam. Incumbents should anchor enterprise accounts through embedded working capital tools that offset processing margin compression from Dutch Authority for Consumers and Markets enforcement.
For New Entrants and Emerging Players: PSD2 in the Netherlands opens a window for payment initiation service providers targeting B2B manufacturing workflows in Eindhoven and Tilburg corridors. New entrants should prioritize iDEAL-integrated automated payables for logistics operators, using simplified API documentation to compress six-month merchant onboarding cycles against incumbent twelve-month integration timelines.
For Investors and Strategic Acquirers: The window for entry favors mid-market omnichannel platform specialists with proven SEPA Instant rail connectivity. Investors should monitor De Nederlandsche Bank licensing queue depth as inflection indicator for competitive entry velocity, targeting providers with 12-18 month approval track records and existing e-money authorization.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Working Capital Launch | Real-time credit underwriting using SEPA Instant transaction data expands revenue beyond processing fees for SME merchants. |
| Biometric Authentication Integration | PSD2 strong customer authentication compliance above 30-euro thresholds differentiates providers in urban millennial segments. |
| Cross-Border API Harmonization | Belgian-Dutch corridor standardization reduces integration complexity for providers operating across Zeeland and Limburg border zones. |
| Legacy Core Modernization | Real-time API connectivity retrofits enable incumbent banks to compete with fintech-native SEPA Instant rail deployment. |
| Specialized Talent Acquisition | PSD2 security engineering teams in Amsterdam command premium compensation, creating defensive moat through scarce expertise capture. |
Research Methodology
Multi-period observation of SEPA Instant adoption rates and merchant migration patterns anchored the trend analysis, supplemented by interviews with payment platform CTOs, De Nederlandsche Bank supervisory staff, retail chain procurement directors, and fintech API integration specialists. Secondary validation drew from European Banking Authority technical standard publications, Dutch Authority for Consumers and Markets enforcement disclosures, and SEPA scheme participant reports. Bottom-up merchant volume estimates triangulated against top-down euro-denominated settlement flow data from clearing infrastructure operators.
Segment-weighting across payment method, transaction type, customer segment, and service type dimensions informed the analytical framework throughout the projection horizon. CAGRs were derived from S-curve diffusion modeling of instant payment rail penetration and SME omnichannel platform replacement cycles. Forecast inputs incorporated PSD2 licensing timeline distributions and biometric authentication hardware cost trajectories.
Caveats apply where De Nederlandsche Bank supervisory priority shifts or SEPA Instant technical standard revisions could materially shift the outlook. Forecasts reflect assumptions regarding merchant behavior persistence and regulatory enforcement continuity. A small set of triggers—interchange fee cap adjustments, core banking modernization accelerations, and cross-border API fragmentation resolutions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Luxembourg POS Terminals Market
Payments
Biometric Payment Cards Market
Payments
Proximity Mobile Payment Market
Payments
Smart Payment Market
Payments
Latin America Retail Cash Management Market
Payments
Middle East and Africa Real Time Payments Market
Payments
Saudi Arabia Payments Market
Payments
Mexico Payments Market
Payments
Latin America Payment Gateway Market
Payments
Mobile Payment Security Software Market
Payments
Malta POS Terminal Market
Payments
APAC Mobile Payments Market
Payments
Asia Pacific Mobile Wallet Market
Payments
Point-To-Point Encryption (P2PE) Payment Market
Payments
Telecom Cloud Billing Market
Payments
Spain Payment Gateway Market