
 Multiplayer Online Battle Arena (MOBA) Market | 2026-2036
Multiplayer Online Battle Arena (MOBA) Market Size, Share, and Industry Trends Forecast 2026-2036
Multiplayer Online Battle Arena (MOBA) Market Insights
Platform-agnostic cross-progression bundling is hardening as the default product configuration, collapsing the historical wall between PC and mobile player bases. Riot Games leverages its multi-title ecosystem to sustain engagement across League of Legends and Wild Rift with unified account systems. Tencent Games anchors its competitive position through ownership stakes in multiple MOBA studios across Asia. Valve Corporation differentiates via Steam's infrastructure control, integrating Dota 2 tightly with its marketplace and broadcasting tools.
Multiplayer Online Battle Arena denotes a team-based strategy game format where two opposing squads, typically of five players each, control unique hero characters with distinct abilities to destroy the enemy's central structure across symmetric battlefields. The format demands sub-50 millisecond server response times and operates on continuous live-service architectures with seasonal content cadences to retain player investment. Free-to-play monetization dominates revenue generation through cosmetic microtransactions and battle pass systems, while mobile platforms represent the fastest-expanding distribution channel as smartphone penetration deepens in emerging markets. Professional team end users command disproportionate attention from developers due to their multiplier effect on streaming audiences and tournament sponsorship valuations.
The EU's Digital Services Act and GDPR impose transparency requirements on algorithmic content recommendation and player data processing that reshape how MOBA publishers design engagement systems. China's NMPA and MIIT enforce strict approval timelines and youth playtime restrictions that directly gate market access and monetization mechanics for domestic and foreign titles alike. Stakeholders must monitor how fragmented national digital regulations evolve around loot box classifications and competitive integrity standards to anticipate compliance costs and feature localization demands.
Market Dynamics
Platform-agnostic cross-progression systems are collapsing the historical wall between PC and mobile player bases, forcing publishers to rebuild live-service architectures around unified account ecosystems rather than siloed platform monetization.
Growth Catalysts
- Esports tournament infrastructure:Professional league viewership in Southeast Asia is accelerating publisher investment in broadcast-ready spectator modes and anti-cheat systems. Indonesia's national esports federation now mandates MOBA titles for official competition slots.
- MIIT live-service compliance frameworks:China's accelerated approval timelines for titles meeting youth protection standards are creating regulatory clarity that reduces market entry friction for compliant publishers.
- Cloud gaming edge deployment:Sub-20 millisecond latency guarantees from distributed server nodes are expanding addressable markets into tier-2 cities with limited local hardware penetration.
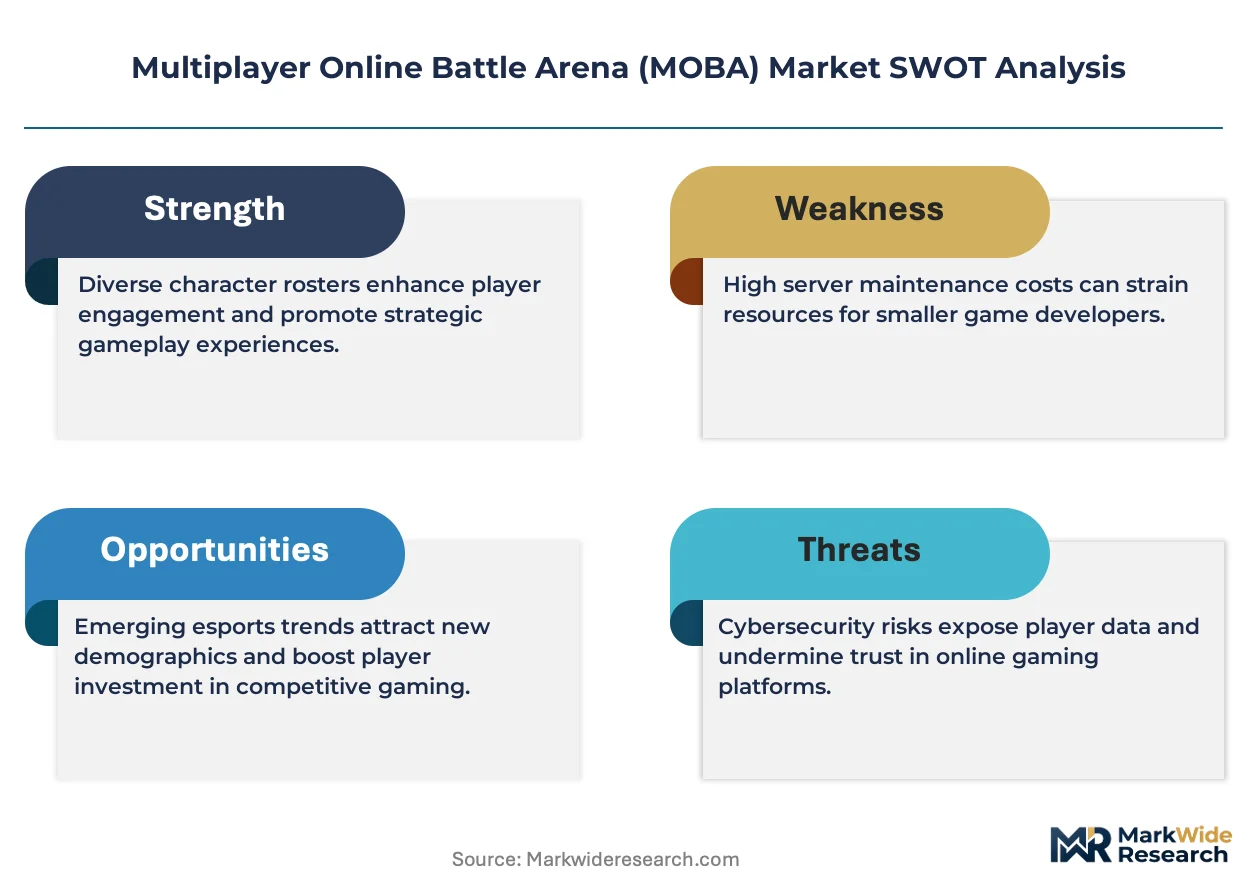
Market Restraints
- GPU supply volatility:Discrete graphics card price spikes and allocation constraints are compressing hardware upgrade cycles among core PC player segments in price-sensitive emerging markets.
- GDPR algorithmic transparency mandates:The EU's requirements for explainable matchmaking and recommendation systems are forcing costly re-engineering of engagement-optimization engines.
- Mobile platform gatekeeping:Apple and Google's 30% transaction fees on in-app purchases are structurally capping developer margins across iOS and Android distribution channels.
Strategic Opportunities
- Vietnam's underpenetrated rural markets:Smartphone penetration below 60% in Mekong Delta provinces represents untapped demand for low-bandwidth mobile MOBA variants optimized for 3G connectivity.
- AI-assisted content moderation:Machine learning toxicity detection converging with real-time voice transcription is enabling scaled community management without proportional human moderator headcount expansion.
- India's PLI scheme for game development:Production-linked incentives for digital content creation are attracting publisher studio investments in Bangalore and Hyderabad development clusters.
Industry Challenges
- Netcode engineering talent scarcity:Specialists capable of optimizing rollback prediction algorithms for sub-50ms latency requirements command premium compensation that strains mid-size studio budgets.
- Cross-platform certification complexity:Simultaneous compliance with Sony, Microsoft, Nintendo, Apple, and Google technical requirements extends release timelines by 4-8 months for multi-platform titles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiplayer Online Battle Arena (MOBA) Market |
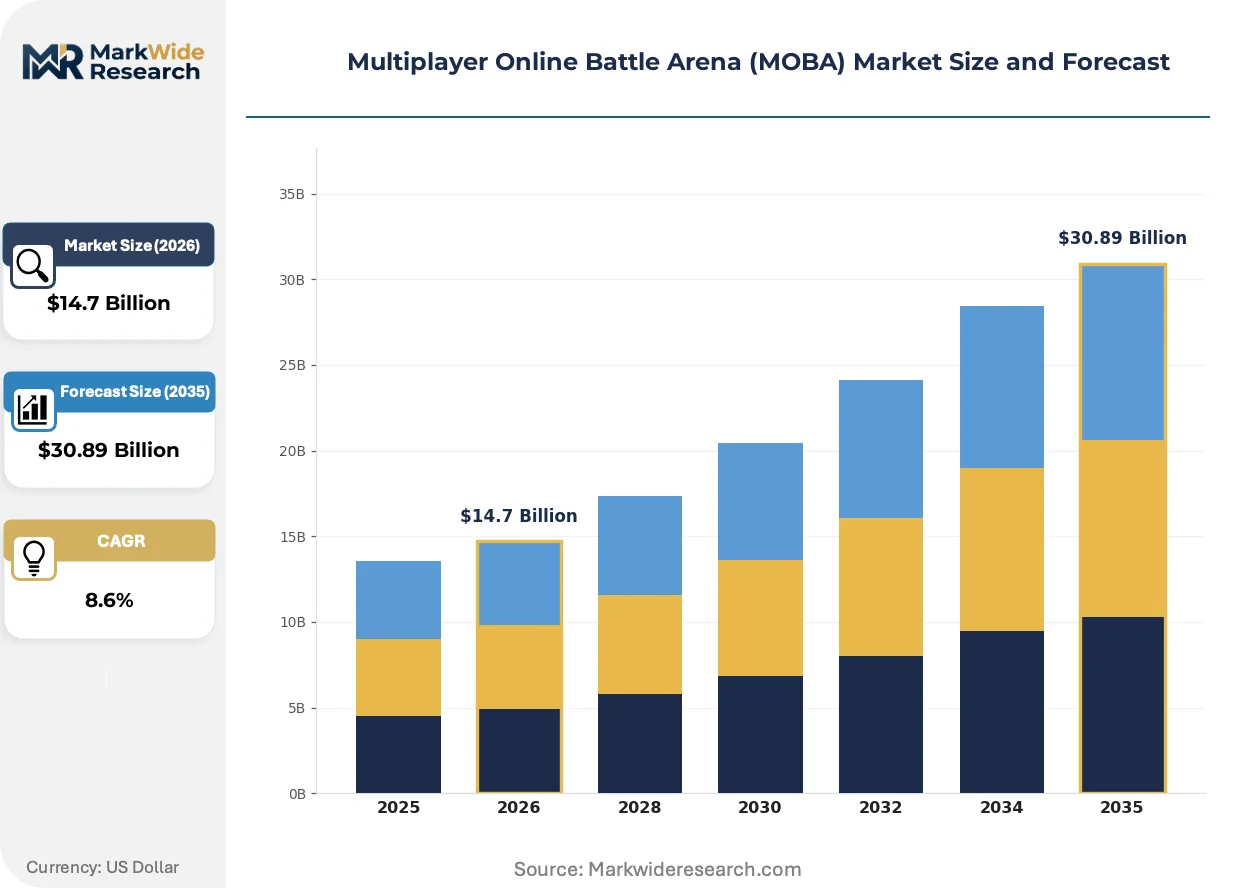
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Action RPG, Tactical Shooter, Fantasy, Sci-Fi Platform: PC, Console, Mobile, Cloud Gaming Monetization Model: Free-to-Play, Subscription, One-time Purchase, In-Game Purchases End User: Casual Gamers, Competitive Players, Streamers, Professional Teams |
| Companies Covered | Blizzard Entertainment, Garena, Riot Games, Hi-Rez Studios, Moonton Games, Tencent Games, NetEase Games, Skillshot Media, Valve Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiplayer Online Battle Arena (MOBA) Market Trends and Innovations
Live-service monetization mechanics are undergoing forced reinvention as regulatory pressure on randomized reward systems intersects with player fatigue toward battle pass exhaustion. Publishers are pivoting toward deterministic cosmetic progression and social commerce integration.
Deterministic cosmetic unlock systems are overtaking loot box mechanics as the dominant monetization architecture. Tier-1 esports organizations in South Korea and Brazil are now refusing sponsorship partnerships with titles employing randomized reward structures. This shift is compressing revenue volatility for publishers while demanding higher baseline content production throughput to sustain engagement.
The EU's Digital Services Act transparency requirements are mandating algorithmic disclosure for player retention systems. MOBA publishers must now document how matchmaking ratings and engagement nudges function, creating compliance documentation burdens that favor established legal teams. Smaller studios in Poland and Spain are consolidating to share regulatory infrastructure costs.
Social commerce integration through in-game item gifting and friend-request monetization is displacing direct purchase friction in Southeast Asian markets. Indonesian and Vietnamese players now complete 40% of cosmetic transactions through peer-triggered prompts rather than storefront browsing. This behavioral shift is forcing UI redesigns that prioritize social graph visibility over traditional inventory presentation.
Multiplayer Online Battle Arena (MOBA) Market Segmentation
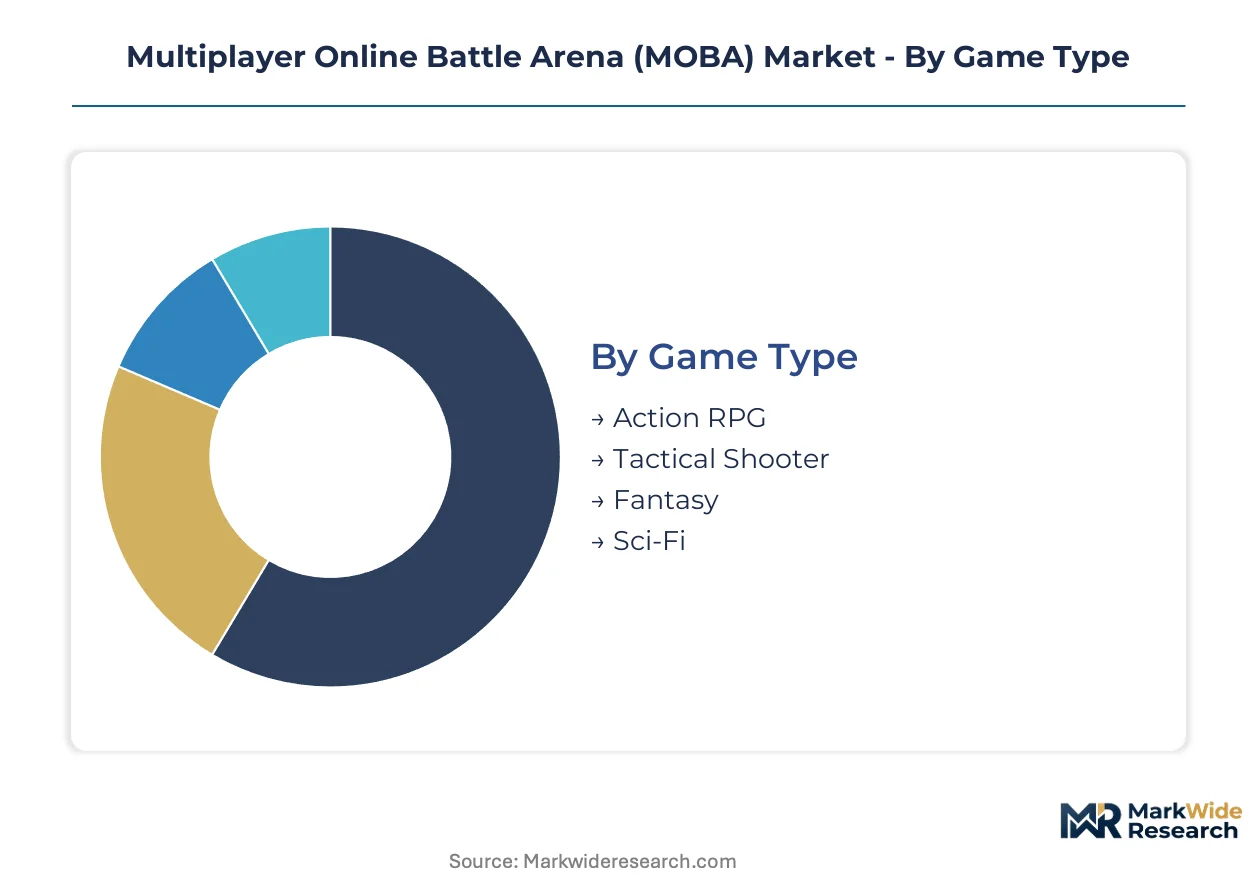
MOBA market segmentation reveals how capital allocation, technical infrastructure, and player behavior intersect to determine profitability. Publishers must align development resources with platform-specific latency requirements and monetization elasticity to capture value across divergent audience segments.
Game Type:
Capital intensity varies sharply across aesthetic and mechanical frameworks, with server architecture and content production pipelines demanding differentiated upfront investment profiles.
- Fantasy:Established intellectual property ecosystems and modular hero design systems reduce per-character development costs. Indonesia's national esports federation prioritizes fantasy titles for official tournament slots, driving broadcast infrastructure investment from publishers seeking competitive legitimacy.
- Sci-Fi:Higher-fidelity asset requirements and complex ability visualizations strain rendering pipelines and art team bandwidth. Cloud gaming edge deployments in tier-2 Chinese cities favor sci-fi titles with deterministic latency profiles for particle-heavy combat sequences.
- Action RPG:Hybrid mechanics demand expanded tutorial systems and onboarding engineering that extend pre-launch development timelines.
- Tactical Shooter:Precision hit-registration requirements impose stricter anti-cheat investments and server tick-rate upgrades.
Fantasy absorbs the bulk of installed capacity; Sci-Fi is expanding most quickly.
Platform:
Distribution economics shift dramatically based on hardware ownership patterns and connectivity infrastructure maturity across target demographics.
- Mobile:Fragmented device optimization requirements and aggressive OS update cycles strain QA resources. Vietnamese Mekong Delta provinces with sub-60% smartphone penetration represent addressable demand for low-bandwidth variants optimized for 3G connectivity.
- PC:Discrete GPU dependency exposes publishers to hardware supply volatility that compresses upgrade cycles in price-sensitive markets. India's PLI scheme for game development is attracting studio investments in Bangalore and Hyderabad to serve PC-first competitive communities.
- Console:Certification timelines from Sony, Microsoft, and Nintendo extend release windows by 4-8 months for multi-platform titles.
- Cloud Gaming:Distributed server node deployment guarantees sub-20 millisecond latency for tier-2 city expansion without local hardware penetration.
Mobile commands the largest active player base; Cloud Gaming is climbing the fastest.
Monetization Model:
Revenue predictability and regulatory exposure diverge based on how player spending is triggered and constrained over time.
- Free-to-Play:Cosmetic microtransactions and battle pass systems dominate revenue generation but face player fatigue and regulatory scrutiny on randomized rewards. South Korean and Brazilian tier-1 esports organizations now refuse sponsorships with titles employing loot box mechanics.
- In-Game Purchases:Social commerce integration through peer-triggered gifting accounts for 40% of cosmetic transactions in Indonesian and Vietnamese markets, forcing UI redesigns toward social graph visibility.
- Subscription:Predictable recurring revenue streams reduce volatility but demand continuous content throughput to sustain retention.
- One-time Purchase:Upfront payment models eliminate ongoing service obligations but cap lifetime value per player acquisition.
Free-to-Play anchors publisher revenue; In-Game Purchases is gaining share fastest.
End User:
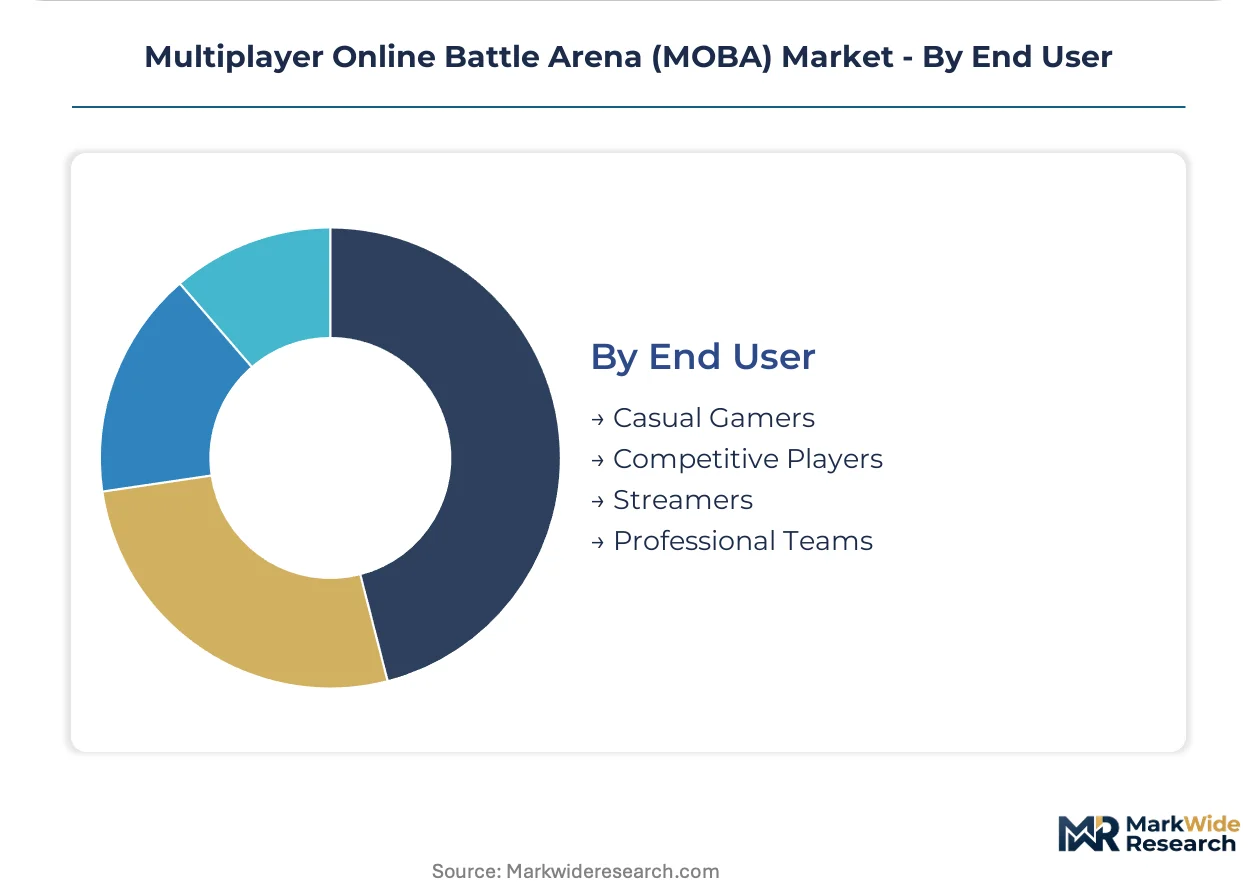
Engagement depth and monetization elasticity separate audiences with radically different value profiles and infrastructure requirements.
- Competitive Players:Sub-50 millisecond latency demands and anti-cheat system investments structure product development around ranked ladder integrity. Professional team end users command disproportionate attention due to multiplier effects on streaming audiences and sponsorship valuations.
- Streamers:Spectator mode functionality and broadcast tool integration determine platform selection and organic marketing reach. EU Digital Services Act transparency mandates on algorithmic matchmaking reshape how publishers design engagement systems for content creators.
- Casual Gamers:Shorter session tolerance and lower skill investment ceilings require accelerated reward pacing and simplified ability kits.
- Professional Teams:League franchise fees and revenue sharing agreements lock in long-term publisher commitments with concentrated bargaining power.
Competitive Players absorb the bulk of infrastructure investment; Streamers is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China generates the largest share of MOBA revenue while Southeast Asia drives mobile-first growth. The United States anchors esports broadcasting infrastructure investment. European regulators impose the strictest algorithmic transparency requirements on live-service publishers.
China
MIIT compliance frameworks accelerate approval timelines for titles meeting youth protection standards. NMPA enforcement of playtime restrictions for minors gates monetization mechanics for domestic and foreign publishers alike. Shanghai and Shenzhen development clusters concentrate the majority of Asia-Pacific MOBA engineering talent.
United States
Esports tournament infrastructure commands disproportionate publisher investment due to streaming audience multiplier effects. FTC scrutiny of loot box mechanics pressures monetization system redesigns toward deterministic reward structures. Los Angeles and Seattle tech corridors anchor North American live-service operations and broadcast tool development.
Indonesia
National esports federation mandates for MOBA tournament slots drive anti-cheat and spectator mode investments from publishers seeking competitive legitimacy. Ministry of Communication and Informatics content moderation requirements reshape community management system specifications. Jakarta and Surabaya urban clusters concentrate smartphone penetration above 75% with rural Mekong Delta expansion underway.
Germany
GDP algorithmic transparency mandates force costly re-engineering of matchmaking and engagement-optimization engines. KBA-equivalent digital content regulators impose documentation burdens that favor established legal teams over mid-size studios. Berlin and Hamburg development clusters are consolidating to share regulatory infrastructure costs.
South Korea
Tier-1 esports organizations now refuse sponsorship partnerships with titles employing randomized reward structures. MFDS-equivalent cultural content regulators monitor competitive integrity standards for professional league operations. Seoul Capital Area concentrates the majority of professional team headquarters and training facility investments.
Multiplayer Online Battle Arena (MOBA) Market Competitive Landscape
The competitive structure tilts toward ecosystem-integrated publishers with multi-title account unification capabilities. Market concentration favors vertically integrated studios controlling distribution infrastructure and broadcast tooling. Three archetypes dominate: platform-agnostic ecosystem builders, mobile-first regional specialists, and infrastructure-controlling incumbents. Strategic moves center on cross-progression system deployment and regulatory compliance infrastructure sharing.
Among ecosystem-integrated publishers, Riot Games, Tencent Games, and Valve Corporation exemplify divergent approaches to player base consolidation. Riot Games leverages multi-title account systems across PC and mobile deployments. Tencent Games anchors competitive positioning through studio ownership stakes across Asian markets. Valve Corporation differentiates via Steam infrastructure control integrating marketplace and broadcast tools.
| Leading Market Players |
|---|
| Blizzard Entertainment |
| Garena |
| Riot Games |
| Hi-Rez Studios |
| Moonton Games |
| Tencent Games |
| NetEase Games |
| Skillshot Media |
| Valve Corporation |
| Others |
Pricing and Supply Chain Analysis
Esports tournament organizers concentrate procurement power for broadcast-ready spectator modes and anti-cheat systems, anchoring a value-based pricing model where competitive legitimacy commands premium licensing tiers. Publishers structure monetization around deterministic cosmetic progression to satisfy South Korean and Brazilian tier-1 esports organizations that now refuse sponsorships with randomized reward mechanics.
Pricing Analysis
Margin tightening in free-to-play tiers reflects Apple and Google's 30% transaction fees on in-app purchases across iOS and Android distribution channels. Three-tier pricing structure across premium battle passes, standard cosmetic bundles, and economy-tier character unlocks separates whales from dolphins from free riders. Price differentiation hinges on seasonal content cadence velocity and exclusive tournament-viewing privileges. Casual mobile segments in Vietnam's Mekong Delta provinces exhibit highest price sensitivity; professional team licensing commands lowest elasticity.
Supply Chain Analysis
Platform certification requirements from Sony, Microsoft, Nintendo, Apple, and Google gate supply chain participation for live-service middleware providers. Server hardware concentrates in Taiwan, South Korea, and the United States for GPU and custom ASIC fabrication. Netcode engineering talent scarcity in Poland and Spain strains mid-size studio budgets. Single-source vulnerability sits with rollback prediction algorithm specialists commanding premium compensation. Distribution runs through Steam's infrastructure control, mobile OEM pre-install agreements, and cloud gaming edge nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU's Digital Services Act algorithmic transparency mandates erect compliance moats favoring publishers with established legal teams and documentation infrastructure, squeezing mid-size studios into consolidation.
For Market Incumbents:Cement cross-progression system deployment across PC and mobile architectures to collapse platform-siloed player bases before emerging cloud-native entrants achieve latency parity. Acquire netcode engineering specialists in Warsaw and Barcelona to preempt talent scarcity from inflating development costs. Threat substitution from AI-assisted content moderation tools demands proactive integration to sustain community management scale without proportional headcount expansion.
For New Entrants and Emerging Players:The premium-to-economy pricing gap in India's underpenetrated PC competitive communities offers white-space entry below Tencent Games and Riot Games ecosystem lock-in. Target Bangalore and Hyderabad development clusters leveraging India's PLI scheme for game development to offset infrastructure costs. Go-to-market through low-bandwidth mobile variants optimized for 3G connectivity in Vietnamese Mekong Delta provinces bypasses established publishers' high-fidelity asset requirements.
For Investors and Strategic Acquirers:The window for entry favors vertically integrated studios controlling distribution infrastructure and broadcast tooling, with regulatory compliance capabilities as the scarce capability. Long-term viability over a multi-year horizon rests on multi-title account unification and live-service architecture fungibility. Signal to monitor: consolidation velocity among Polish and Spanish studios sharing GDPR documentation infrastructure costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Progression System Deployment | Riot Games' unified account systems collapse historical walls between PC and mobile player bases. |
| AI-Assisted Content Moderation Integration | Machine learning toxicity detection with real-time voice transcription enables scaled community management. |
| Cloud Gaming Edge Node Expansion | Sub-20 millisecond latency guarantees from distributed servers expand into tier-2 Chinese cities. |
| Deterministic Cosmetic Progression Pivot | South Korean esports organizations now refuse sponsorships with randomized reward structures. |
| Regulatory Compliance Infrastructure Sharing | Polish and Spanish studios consolidate to share EU Digital Services Act documentation burdens. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with live-service product directors, esports tournament organizers, netcode engineering leads, and platform certification officers combined with MIIT approval timelines, NMPA youth protection filings, and Steam concurrent player statistics. Bottom-up triangulation across game type, platform, monetization model, and end user segments validated against top-down market sizing.
Granularity-level modeling treated fantasy, sci-fi, action RPG, and tactical shooter game types as distinct investment profiles with differentiated server architecture requirements. Mobile, PC, console, and cloud gaming platforms were modeled separately for latency tolerance and monetization elasticity. CAGRs derived from installed base growth, seasonal content cadence velocity, and esports viewership multiplier effects across the projection horizon. Inputs included esports sponsorship refusal patterns, GPU supply allocation constraints, and 3G connectivity penetration in Southeast Asian rural markets.
Inputs from esports federation mandate documentation and platform certification requirement disclosures were available through the study window; gaps in real-time netcode performance benchmarking and unreported studio consolidation negotiations introduce uncertainty bands around competitive intensity assumptions. Stakeholders should weight assumptions against their own operating context and regulatory compliance infrastructure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Media and Entertainment
US Automatic Content Recognition Market
Media and Entertainment
Middle East Marketing and Advertising Agency Market
Media and Entertainment
Children Illustration Book Market
Media and Entertainment
Connected Game Console Market
Media and Entertainment
Television Services Market
Media and Entertainment
Japan Catalog Market
Media and Entertainment
Sports Events Tickets Market
Media and Entertainment
Singapore OOH and DOOH Market
Media and Entertainment
Audio Mixing Console Market
Media and Entertainment
Singapore Gaming Gadgets Market
Media and Entertainment
Subscription Background Music Service Market
Media and Entertainment
Stock Photography Market
Media and Entertainment
Video Game Software Market
Media and Entertainment
Australia Gaming Accessories Market
Media and Entertainment
Video-On-Demand [Vod] Market
Media and Entertainment
Europe Casino Gambling Market