
 Middle East and Africa Men's Grooming Products Market | 2026-2036
Middle East and Africa Men's Grooming Products Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Men's Grooming Products Market Foresight
Clean-label formulation technology is tilting manufacturing priorities across the Middle East and Africa men's grooming landscape. L'Oreal SA leverages its dermatological science heritage to anchor premium positioning in Gulf markets. Procter & Gamble sustains mass-market dominance through extensive distribution networks spanning North African retail corridors. Unilever PLC competes aggressively on price-accessibility matrices tailored to East African consumer segments.
Middle East and Africa men's grooming products encompass topical preparations engineered for male hair management, facial skin conditioning, and beard maintenance, typically incorporating emollients, active botanical extracts, and pH-balanced surfactant systems manufactured through cold-process emulsification or hot-melt compounding. These formulations serve commercial purposes ranging from daily hygiene compliance to professional appearance standards in service-sector employment. Shaving cream and beard oil categories capture disproportionate margin pools as male facial hair culture intensifies across the region. E-commerce distribution channels exhibit the steepest trajectory as digital payment infrastructure penetrates secondary cities. Specialty stores retain defensive strength in United Arab Emirates and South Africa where experiential retail drives premium conversion.
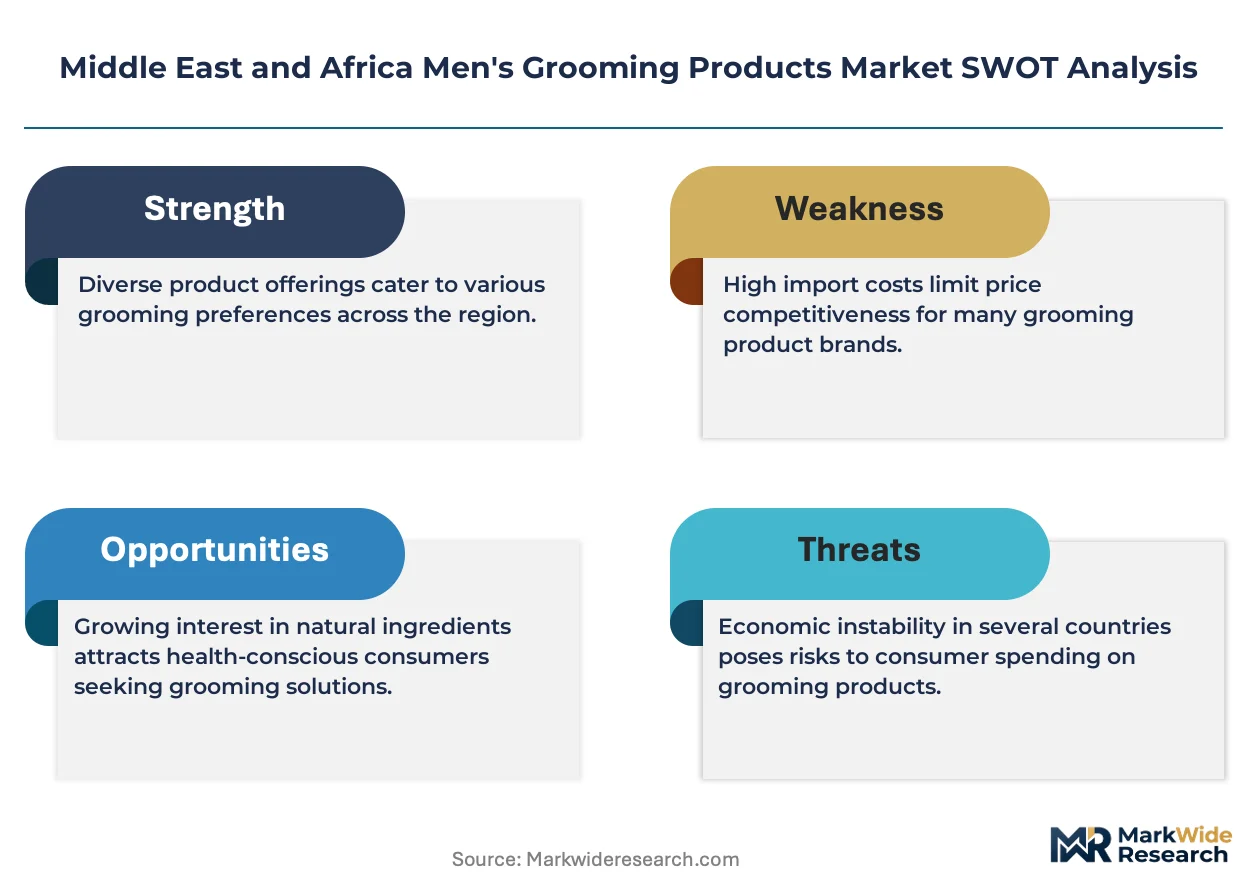
Saudi Food and Drug Authority registration mandates compel reformulation of alcohol-based aftershave products entering Gulf markets. South Africa's National Regulator for Compulsory Specifications enforces labeling and ingredient disclosure standards that elevate compliance costs for import-dependent operators. Nigeria's national standards body applies functional quality thresholds to hair relaxers and colorants circulating through informal trade channels. Stakeholders must monitor regulatory divergence between Francophone and Anglophone African jurisdictions when designing pan-regional product portfolios.
Market Dynamics
Clean-label formulation mandates are compressing product development cycles across the Middle East and Africa men's grooming sector, forcing manufacturers to re-engineer preservative systems and surfactant bases while maintaining performance claims.
Growth Catalysts
- SFDA Registration Mandates:Saudi Arabia's cosmetic registration requirements are elevating formulation standards across Gulf markets, compelling manufacturers to invest in halal-certified ingredient sourcing and stability testing infrastructure.
- Digital Payment Penetration:Secondary cities across Nigeria and Kenya are integrating mobile money platforms with e-commerce logistics, unlocking direct-to-consumer channels previously constrained by cash-on-delivery limitations.
- Beard Culture Intensification:Young urban professionals in Dubai, Riyadh, and Lagos are driving disproportionate margin capture in beard oil and conditioning categories, shifting portfolio weight toward facial hair maintenance SKUs.
Market Restraints
- Import Dependency Concentration:South Africa's personal care manufacturing base relies on Chinese and European surfactant suppliers, exposing margins to freight cost volatility and currency fluctuation against the rand.
- Informal Channel Taxation Evasion:Nigeria's open-air market distribution for mass-market shaving creams operates outside formal VAT collection, compressing price-realization for compliant operators competing against untaxed parallel imports.
- Water Scarcity Formulation Constraints:Gulf Cooperation Council water tariffs are forcing reformulation of rinse-dependent products toward waterless or low-water formats, requiring capital-intensive manufacturing retooling.
Strategic Opportunities
- East African Underpenetration:Ethiopia and Tanzania present white-space expansion potential for mid-tier grooming brands, with urbanization rates outstripping organized retail infrastructure development.
- Subscription Model Convergence:UAE-based platforms are bundling personalized beard care regimens with tele-dermatology consultations, capturing recurring revenue from affluent male demographics.
- MOHAP Clean Beauty Incentives:Dubai's health authority is fast-tracking registration for products meeting defined sustainability criteria, creating regulatory arbitrage for compliant entrants against legacy formulations.
Industry Challenges
- Halal Certification Timeline Compression:Gulf market entry now requires dual certification from Islamic accreditation bodies and national regulators, extending product launch cycles by four to six months.
- Fragrance Compound Sourcing Complexity:Reformulation away from alcohol-based aftershaves demands alternative solvent systems with comparable dry-down characteristics, straining R&D capacity at mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Men's Grooming Products Market |
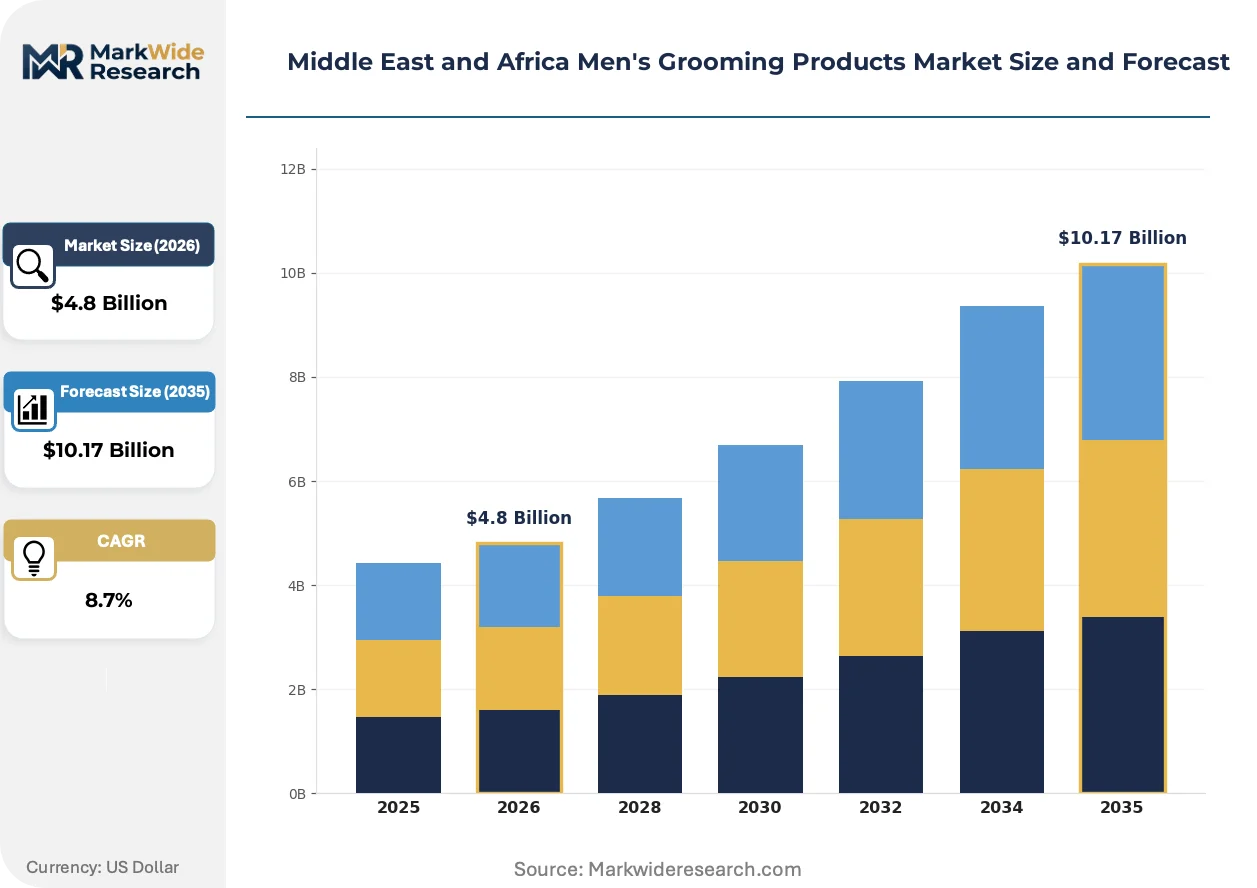
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shaving Cream, Beard Oil, Hair Gel, Aftershave Balm Application: Daily Use, Special Occasions, Professional Grooming, Travel Customer Type: Retail Consumers, Salons, Spa Professionals, Online Shoppers Distribution Channel: Supermarkets, Specialty Stores, E-commerce, Pharmacies |
| Companies Covered | Beiersdorf AG, Revlon Inc, L'Oreal SA, Estee Lauder Companies, Inc., Johnson & Johnson, Procter & Gamble, Edgewell Personal Care Company, BIC Group, Unilever PLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Men's Grooming Products Market Shifts & Advancements
Biotechnology-derived actives and cold-process emulsification methods are restructuring manufacturing economics across the Middle East and Africa men's grooming landscape, compressing energy requirements while enabling botanical claim substantiation.
Plant-based surfactant systems derived from date palm and argan biomass are collapsing the cost differential between synthetic and natural cleansing bases. Gulf-based contract manufacturers are adopting these inputs to satisfy SFDA disclosure requirements. The shift is enabling price parity between premium natural-positioned SKUs and conventional formulations in Saudi and UAE markets.
South Africa's National Regulator for Compulsory Specifications is enforcing expanded ingredient disclosure thresholds for hair relaxers and colorants circulating through formal retail channels. Compliance investments are diverting working capital from marketing spend among import-dependent distributors. The regulations most acutely affect mass-market ethnic hair care segments serving Afro-descendant consumer bases in Johannesburg and Cape Town metropolitan areas.
Young male consumers in Lagos and Nairobi are compressing purchase decision cycles through social commerce discovery, bypassing traditional retail browsing. Instagram and TikTok storefront integrations are displacing supermarket aisle conversion for first-time brand trials. This behavioral shift concentrates marketing ROI pressure on influencer partnership strategies rather than trade promotion budgets.
Middle East and Africa Men's Grooming Products Market Segmentation
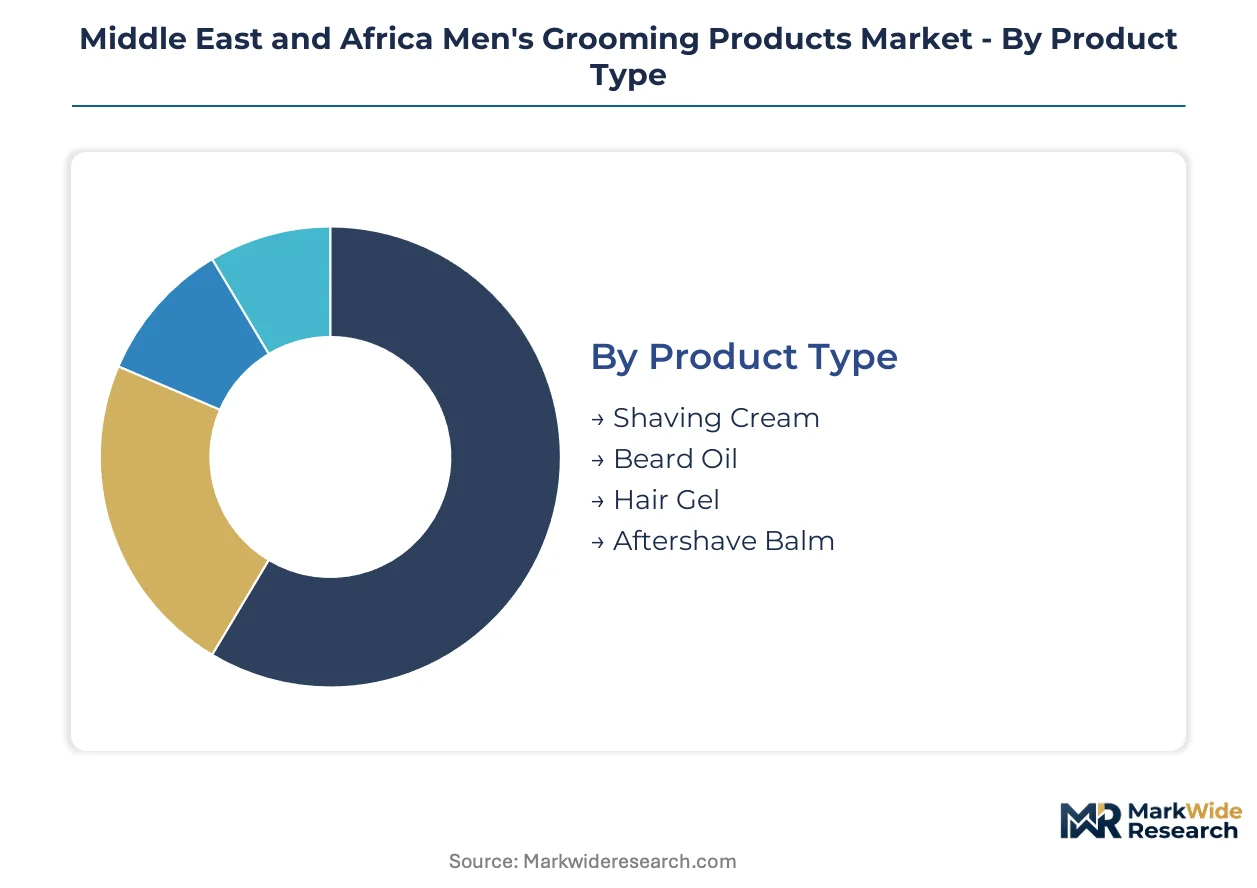
Segmentation in the Middle East and Africa men's grooming market reveals divergent margin structures across product categories and channel configurations. Distinct formulation requirements and regulatory compliance burdens create tiered profitability profiles that reshape portfolio allocation decisions for manufacturers operating across Gulf and sub-Saharan markets.
Product Type:
After-sales service intensity varies sharply across grooming product categories, with beard oil and shaving cream demanding formulation troubleshooting support that elevates customer retention economics.
- Shaving Cream:Emulsion-based formulations incorporating pH-balanced surfactants and glycerin humectants serve the mass-market daily shave ritual. Demand concentrates in Saudi Arabia and UAE hypermarket channels where SFDA registration requirements favor established suppliers with stability testing infrastructure.
- Beard Oil:Cold-pressed carrier oil blends with argan and jojoba extracts target the facial hair maintenance segment. Young professionals in Dubai and Riyadh drive disproportionate margin capture as beard culture intensifies across Gulf cities, shifting portfolio weight toward premium-positioned SKUs.
- Hair Gel:Polymer-thickened styling preparations with alcohol-free bases comply with halal certification requirements. Nigerian informal retail channels concentrate mass-market demand for water-soluble variants.
- Aftershave Balm:Alcohol-free soothing formulations with aloe and witch hazel extracts replace traditional splash products. Reformulation mandates from Saudi and UAE regulators compel preservative system redesigns.
Shaving cream holds the largest share; momentum sits with beard oil.
Application:
Cost tier differentiation separates daily-use formulations from occasion-driven premium SKUs, with professional grooming commanding the highest per-unit economics.
- Daily Use:Standardized formulations with extended shelf stability serve routine hygiene compliance. Mass-market pricing dominates supermarket and pharmacy channels across Cairo and Casablanca metropolitan areas.
- Special Occasions:Fragrance-forward preparations with enhanced packaging aesthetics target gift and celebration demand. UAE specialty stores capture premium conversion during Eid and wedding seasons.
- Professional Grooming:High-performance formulations meeting service-sector appearance standards concentrate in salon and spa procurement channels. Johannesburg and Cape Town corporate grooming services drive institutional volume.
- Travel:TSA-compliant sizing and leak-resistant packaging configurations address mobility requirements. Kenyan mobile money integration with e-commerce logistics unlocks direct-to-consumer distribution for this segment.
Daily use commands volume leadership; professional grooming climbs the fastest.
Customer Type:
Volume concentration patterns diverge between institutional procurement and individual purchase behaviors, with salon channels demanding technical training support.
- Retail Consumers:Individual purchasers selecting mass-market and mid-tier SKUs through supermarket and e-commerce channels. Lagos and Nairobi social commerce discovery compresses decision cycles for first-time brand trials.
- Salons:Professional service providers requiring bulk formulations and application training. South Africa's formal retail compliance costs affect import-dependent distributor margins serving Johannesburg ethnic hair care segments.
- Spa Professionals:Premium wellness channel operators sourcing dermatologically tested preparations. UAE tele-dermatology bundling creates subscription revenue opportunities.
- Online Shoppers:Digital-native consumers accessing direct-to-consumer platforms with personalized regimen recommendations. Secondary city penetration in Nigeria and Kenya accelerates with mobile payment infrastructure.
Retail consumers hold the largest share; momentum sits with online shoppers.
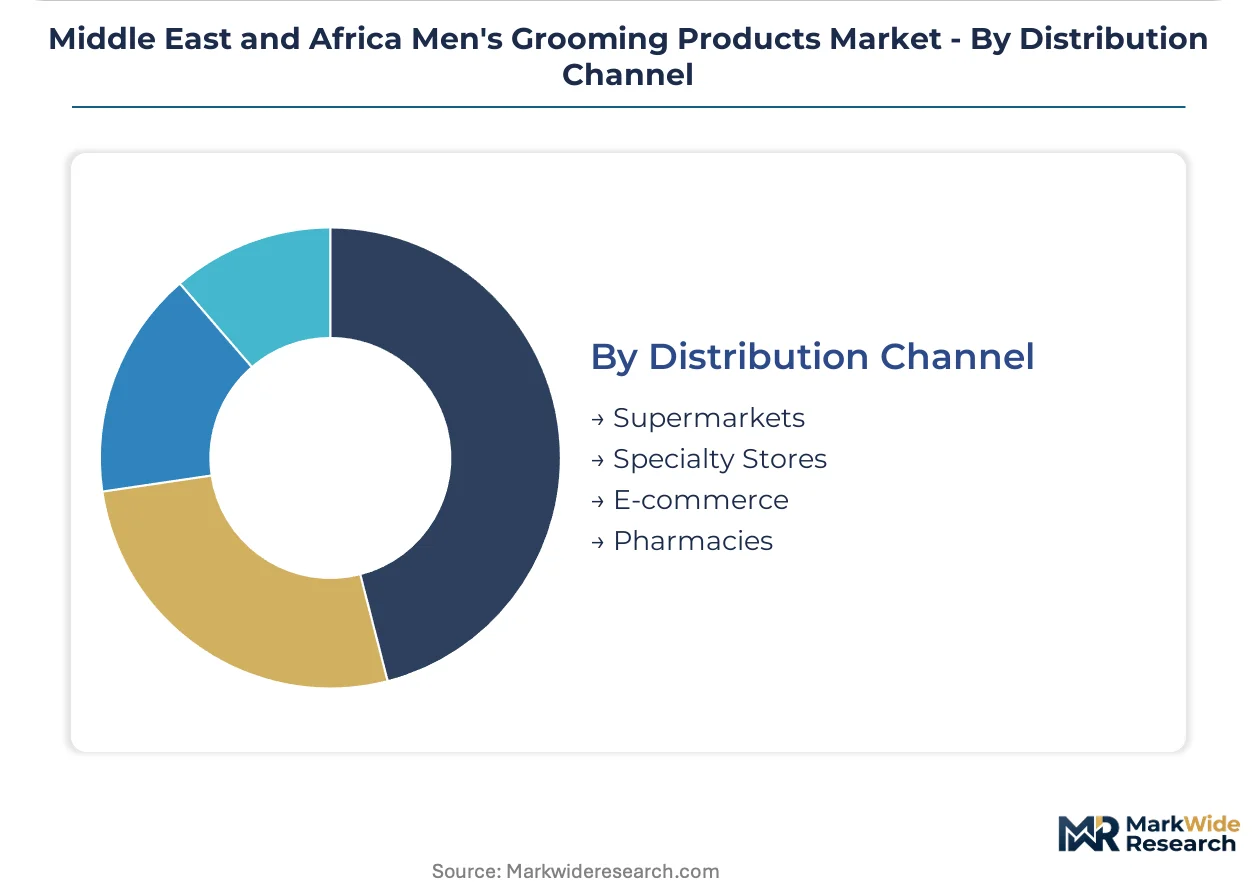
Distribution Channel:
Margin structure varies by channel control intensity, with specialty stores defending premium positioning through experiential retail investments.
- Supermarkets:Mass-market volume concentration with trade promotion dependency. North African retail corridors sustain Procter & Gamble's distribution dominance.
- Specialty Stores:Experiential retail environments driving premium conversion in UAE and South Africa. Staff training investments elevate customer acquisition costs.
- E-commerce:Steepest trajectory channel as digital payment infrastructure penetrates secondary cities. Instagram and TikTok storefront integrations displace traditional aisle conversion.
- Pharmacies:Dermatological credibility positioning for sensitive skin formulations. Saudi SFDA registration alignment supports channel legitimacy.
Supermarkets hold the largest share; e-commerce gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE-based distributors export grooming formulations across Gulf Cooperation Council corridors, with Saudi Arabia absorbing the largest cross-border volume. South Africa serves as the primary import hub for sub-Saharan markets, channeling European and Asian surfactant supplies into Nigerian and Kenyan retail networks.
Saudi Arabia
Young urban professionals in Riyadh and Jeddah drive beard oil and premium aftershave demand. SFDA registration mandates compel halal-certified ingredient sourcing and extended stability testing for all cosmetic entrants. The Riyadh industrial corridor hosts contract manufacturers retooling cold-process emulsification lines to meet disclosure requirements.
United Arab Emirates
Dubai's male grooming service sector and high-net-worth consumer base anchor premium positioning for facial hair maintenance products. MOHAP fast-tracks registration for formulations meeting defined sustainability criteria, creating regulatory arbitrage opportunities. Jebel Ali free zone concentration supports re-export logistics to Kuwait, Qatar, and Bahrain markets.
South Africa
Johannesburg and Cape Town metropolitan areas concentrate demand for professional grooming services and ethnic hair care segments. The National Regulator for Compulsory Specifications enforces expanded ingredient disclosure for hair relaxers and colorants. Durban port infrastructure handles surfactant imports from China and Europe, exposing margins to rand volatility.
Nigeria
Lagos and Abuja urban corridors drive mass-market consumption of shaving creams and water-soluble hair gels. The national standards body applies functional quality thresholds to products circulating through informal open-air markets. Kano and Onitsha trading clusters channel untaxed parallel imports, compressing price-realization for VAT-compliant operators.
Kenya
Nairobi's young male professionals adopt social commerce discovery for first-time brand trials in beard conditioning categories. M-Pesa mobile money integration with e-commerce logistics unlocks direct-to-consumer channels previously constrained by cash-on-delivery limitations. Mombasa port serves as East African distribution gateway for Ethiopian and Tanzanian underpenetrated markets.
Middle East and Africa Men's Grooming Products Market Competitive Landscape
On the supply side, the industry is consolidating around dermatological science capabilities and halal certification infrastructure. Multinational consumer goods conglomerates occupy premium and mass-market tiers through divergent channel strategies. Three archetypes dominate: science-anchored premium specialists, price-accessibility mass-market operators, and regional contract manufacturers with regulatory compliance depth. Geographic expansion through Gulf distributor partnerships and portfolio diversification into waterless formulations represent the dominant competitive moves.
Within the premium-tier vector, L'Oreal SA and Estee Lauder Companies, Inc. exemplify dermatological heritage positioning. Procter & Gamble occupies the mass-market scale archetype through extensive North African retail corridor penetration. Beiersdorf AG represents the mid-tier convergence of pharmaceutical credibility with accessible price points.
| Leading Market Players |
|---|
| Beiersdorf AG |
| Revlon Inc |
| L'Oreal SA |
| Estee Lauder Companies, Inc. |
| Johnson & Johnson |
| Procter & Gamble |
| Edgewell Personal Care Company |
| BIC Group |
| Unilever PLC |
| Others |
Supply & Pricing Matrix
Chinese surfactant suppliers anchor formulation costs for South African contract manufacturers, concentrating margin pressure on mid-tier brands serving Nigerian informal retail channels. This upstream dependency compresses pricing power at the import-dependent distributor level while Gulf-based halal-certified producers capture premium realizations through regulatory arbitrage.
Pricing Analysis
Conventional emulsion technology versus biotechnology-derived actives versus waterless format innovation defines the pricing gap across Middle East and Africa men's grooming. Three-tier pricing structure across premium, standard, and economy levels separates dermatologically tested beard oils from mass-market shaving creams and untaxed parallel imports. Price differentiation rests on halal certification grade and after-sales formulation support. Pricing pressure stems from rand volatility elevating import costs for South African distributors. Informal channel shoppers in Lagos and Kano exhibit highest price sensitivity; UAE spa professionals show lowest.
Supply Chain Analysis
Gulf-based contract manufacturers including Riyadh industrial corridor specialists and Jebel Ali free zone operators hold halal-certified production capacity. Raw material flows draw from Chinese surfactant suppliers, European fragrance compound houses, and Moroccan argan oil cooperatives. Supply chain risk centers on single-source vulnerability for alcohol-free solvent systems replacing traditional aftershave bases. Distribution runs through UAE re-export hubs serving Gulf Cooperation Council markets, with Mombasa and Durban ports feeding East and Southern African networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity intensifies as social commerce discovery compresses brand loyalty cycles, creating entry points for niche positioning across beard care and waterless formulations.
For Market Incumbents: Build regulatory compliance moats through dual SFDA-MOHAP certification infrastructure to defend against emerging direct-to-consumer challengers. Deepen backward integration into cold-process emulsification capacity at Riyadh and Dubai manufacturing sites. Prioritize subscription bundling with tele-dermatology platforms to lock in recurring revenue from affluent Gulf demographics. For New Entrants and Emerging Players: Build out white-space presence in Ethiopia and Tanzania where urbanization outpaces organized retail development. Target Nairobi and Lagos social commerce channels for first-mover beard oil positioning. Leverage M-Pesa and mobile money integration to bypass cash-on-delivery constraints plaguing established competitors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biotechnology-derived active manufacturing as cold-process equipment requirements escalate. Long-term viability favors pan-regional portfolios spanning Gulf premium and East African volume tiers. Acquire regional contract manufacturers with existing halal certification timelines. Monitor SFDA disclosure requirement expansion as signal for compliance-cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Fast-Track Investment | MOHAP expedited registration creates four-to-six month launch advantage over legacy formulations. |
| Waterless Formulation R&D Scale-Up | Gulf Cooperation Council water tariffs force capital retooling toward low-rinse product lines. |
| East African Distribution Partnership | Mombasa port integration unlocks Ethiopian and Tanzanian underpenetrated urban corridors. |
| Social Commerce Platform Integration | Instagram and TikTok storefronts displace supermarket aisle conversion for trial purchases. |
| Subscription-Telemedicine Bundling | UAE tele-dermatology convergence captures recurring revenue from high-net-worth male segments. |
Research Methodology
Desk research of customs trade databases, SFDA registration filings, and Nielsen retail audit data preceded structured interviews with brand managers at multinational consumer goods conglomerates, procurement leads at UAE distributor networks, and category buyers at South African pharmacy chains. Primary fieldwork with contract manufacturing executives in Riyadh and Dubai validated formulation cost structures. Secondary sources included Procter & Gamble and Unilever PLC SEC disclosures, MOHAP regulatory bulletins, and East African mobile money transaction reports. Bottom-up SKU-level volume builds were cross-checked against top-down category spending estimates.
Assumptions held fixed across the modeling period include SFDA disclosure requirement timelines, Gulf Cooperation Council water tariff trajectories, and rand-yuan exchange rate bands; variables stress-tested included social commerce adoption velocity and halal certification body processing delays. Segmentation dimensions encompassed product type, application occasion, customer archetype, and distribution channel. CAGRs were derived from logistic curve fitting to technology adoption patterns and regulatory implementation schedules. Forecast inputs incorporated mobile money penetration rates and cold-process equipment installation timelines.
Stress conditions across surfactant import cost volatility, SFDA registration backlog scenarios, and social commerce platform algorithm changes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including regulatory divergence between Francophone and Anglophone African jurisdictions. Quarterly review of SFDA processing queue lengths and M-Pesa merchant adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Smart Massage Appliances Market
Consumer Goods
Home Theater Seating Market
Consumer Goods
Global Organic Personal Care and Cosmetic Products Market
Consumer Goods
Refrigerator Market
Consumer Goods
Europe Smart TV Market
Consumer Goods
Bath and Shower Products Market
Consumer Goods
Global Probiotic Cosmetic Products Market
Consumer Goods
India Lab Grown Diamond Jewelry Market
Consumer Goods
Baby Bottle Holder Market
Consumer Goods
Household Pet Water Dispenser Market
Consumer Goods
United States Electronics and Appliance Stores Market
Consumer Goods
Fishing Tackle Box Market
Consumer Goods
Electrical Appliances Market
Consumer Goods
Pillow Holder for Tablets Market
Consumer Goods
Kids Wear Market
Consumer Goods
Cloth Diapers Market