
 Metal Straws Market | 2026-2036
Metal Straws Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Straws Market Outlook
Precision laser-welding in straw manufacturing is narrowing the cost gap between stainless steel and premium titanium variants. Klean Kanteen leverages its vacuum-insulation expertise to bundle metal straws with beverage containers. Bambaw anchors its European supply chain through direct partnerships with Vietnamese workshops. Final Straw competes on portability with collapsible designs that fit keychain carriers.
Metal straws are hollow cylindrical drinking tubes, typically 6–8 mm in diameter and 150–215 mm in length, fabricated from food-grade stainless steel through tube drawing and electropolishing to eliminate interior roughness. They serve the commercial foodservice and consumer goods sectors as durable, sanitizable alternatives to disposable polymer straws. Stainless steel variants dominate unit volume due to corrosion resistance and dishwasher-safe certification, while titanium commands premium positioning in gift and outdoor segments. The cafe and restaurant end-user channel generates the densest order flow, though retail packaged sets for households yield wider margins per unit.
The EU Single-Use Plastics Directive and FDA food-contact substance regulations govern material composition and migration limits across the two largest demand regions. California's statewide straw-upon-request law and similar municipal ordinances in Seattle and Vancouver create patchwork compliance obligations for distributors. Stakeholders must monitor how extended producer responsibility frameworks in Germany and France reshape packaging and take-back obligations for reusable utensil brands.
Market Dynamics
The EU Single-Use Plastics Directive compresses substitution timelines for foodservice operators, forcing rapid stainless steel procurement decisions across European cafe chains while simultaneously tightening migration testing protocols for imported metalware.
Growth Catalysts
- EU Single-Use Plastics Directive:The framework mandates phased elimination of disposable plastic straws across member states, compelling cafe and restaurant operators to source reusable alternatives ahead of enforcement deadlines.
- Electropolishing automation:Robotic finishing lines in Vietnamese and Chinese workshops reduce unit labor costs for interior surface smoothing, narrowing the premium over plastic disposables.
- Urban foodservice corridors:Dense clustering of specialty coffee shops in Melbourne, Portland, and Berlin generates concentrated order volumes that justify distributor inventory positioning.
Market Restraints
- Nickel price volatility:304-grade stainless steel contains 8-10.5% nickel, exposing manufacturers to London Metal Exchange fluctuations that compress margin buffers on fixed-price contracts.
- Electropolishing capacity concentration:Food-grade surface finishing for interior straw channels clusters in Guangdong province workshops, creating single-source vulnerability for Western brands.
- Silicone-tip substitution:Foldable silicone straws with integrated cleaning brushes capture price-sensitive outdoor recreation demand that metal cannot satisfy.
Strategic Opportunities
- German extended producer responsibility frameworks:France and Germany are implementing take-back obligation pilots for reusable utensil brands, creating first-mover advantage for compliance-ready suppliers.
- Vacuum-insulation bundling:Metal straw attachment to double-wall tumblers opens household retail channels beyond foodservice procurement.
- Airline amenity kits:Premium cabin service contracts for collapsible titanium straws represent untapped volume in aviation catering supply chains.
Industry Challenges
- FDA food-contact substance notification timelines:Novel coating chemistries for colored straws face 120-day pre-market review cycles that delay product launches.
- Tube-drawing die refurbishment:Precision mandrel wear in straw-diameter production requires capital-intensive tooling replacement every 18 months at high-volume facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Straws Market |
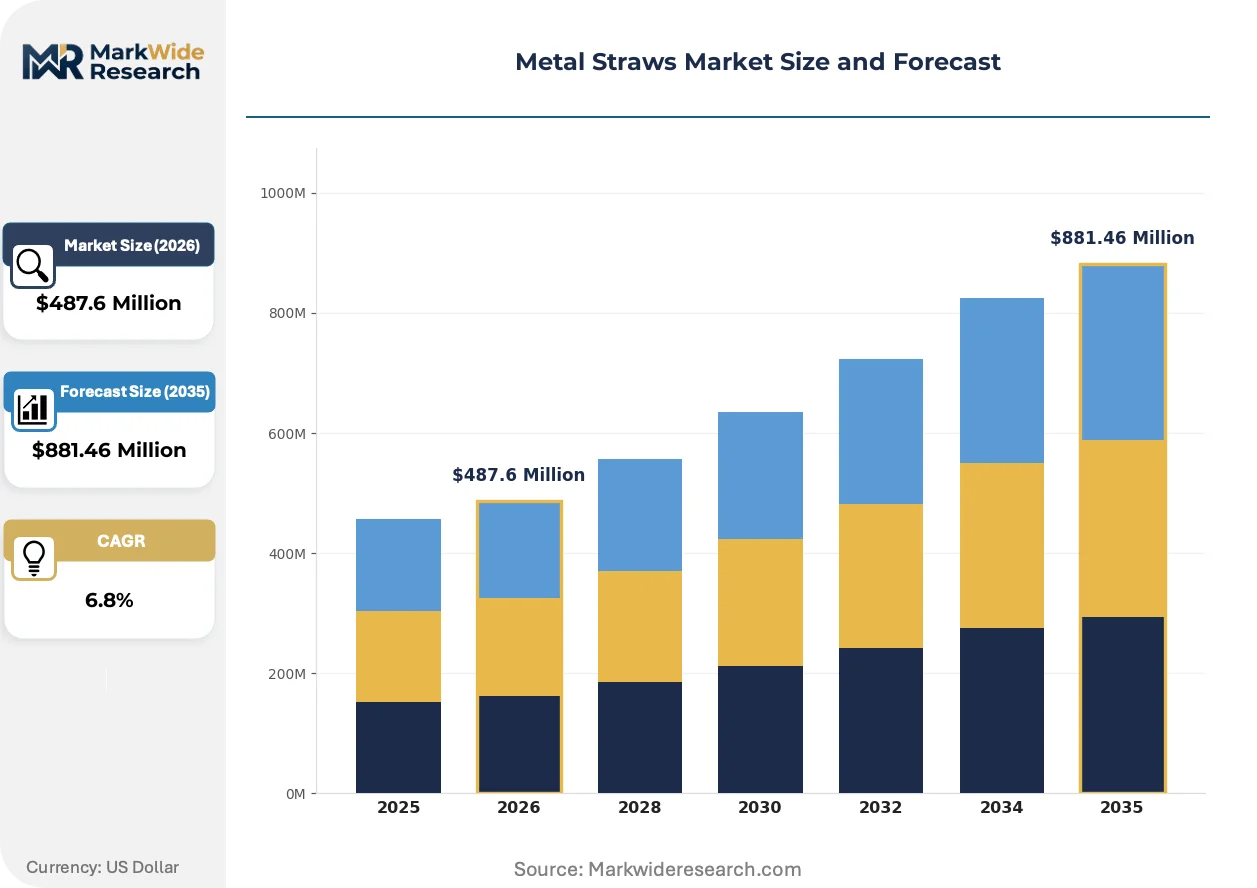
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smooth, Bent, Collapsible, Retail Packaged Material: Stainless Steel, Titanium, Aluminum, Copper Feature: Reusable, Eco-Friendly, Dishwasher Safe, Insulated End User: Households, Cafes, Restaurants, Events |
| Companies Covered | Simply Straws, Bambaw, Klean Kanteen, Mulled Mind, Final Straw, Hydro Flask, Cheeki, Jungle Straws, Strawesome, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Straws Market Strategic Shifts
Laser-welding precision is compressing cost structures across metal straw fabrication, while regulatory migration testing tightens material specifications. These forces are reshaping competitive differentiation from price toward certified compliance and design portability.
Ultrafast laser seam welding eliminates interior burrs in stainless steel straw joints without post-machining, is rendering obsolete traditional TIG welding followed by manual grinding in mid-tier production facilities. German and Australian cafe suppliers are adopting these systems to meet shortened delivery windows from chain procurement teams. The technology compresses the viable production scale threshold, enabling smaller regional workshops to compete on lead time against Asian volume manufacturers.
REACH Annex XVII nickel release restrictions are tightening migration limits for prolonged skin-contact metalware, forcing reformulation of 304-grade alloys or supplemental PVD coating investments. The regulation elevates compliance documentation burdens for direct-importing foodservice distributors. Scandinavian markets are responding fastest, with Stockholm and Copenhagen cafe chains now requiring batch-specific testing certificates from suppliers.
Corporate sustainability officers at US and UK quick-service chains are consolidating utensil procurement under single-source reusable contracts that bundle straws with cutlery and stirrers. This purchasing concentration displaces fragmented distributor relationships that previously handled disposable and reusable lines separately. The shift is most visible in Seattle and Vancouver, where municipal plastic bans have synchronized procurement calendar cycles across competing restaurant groups.
Metal Straws Market Segmentation
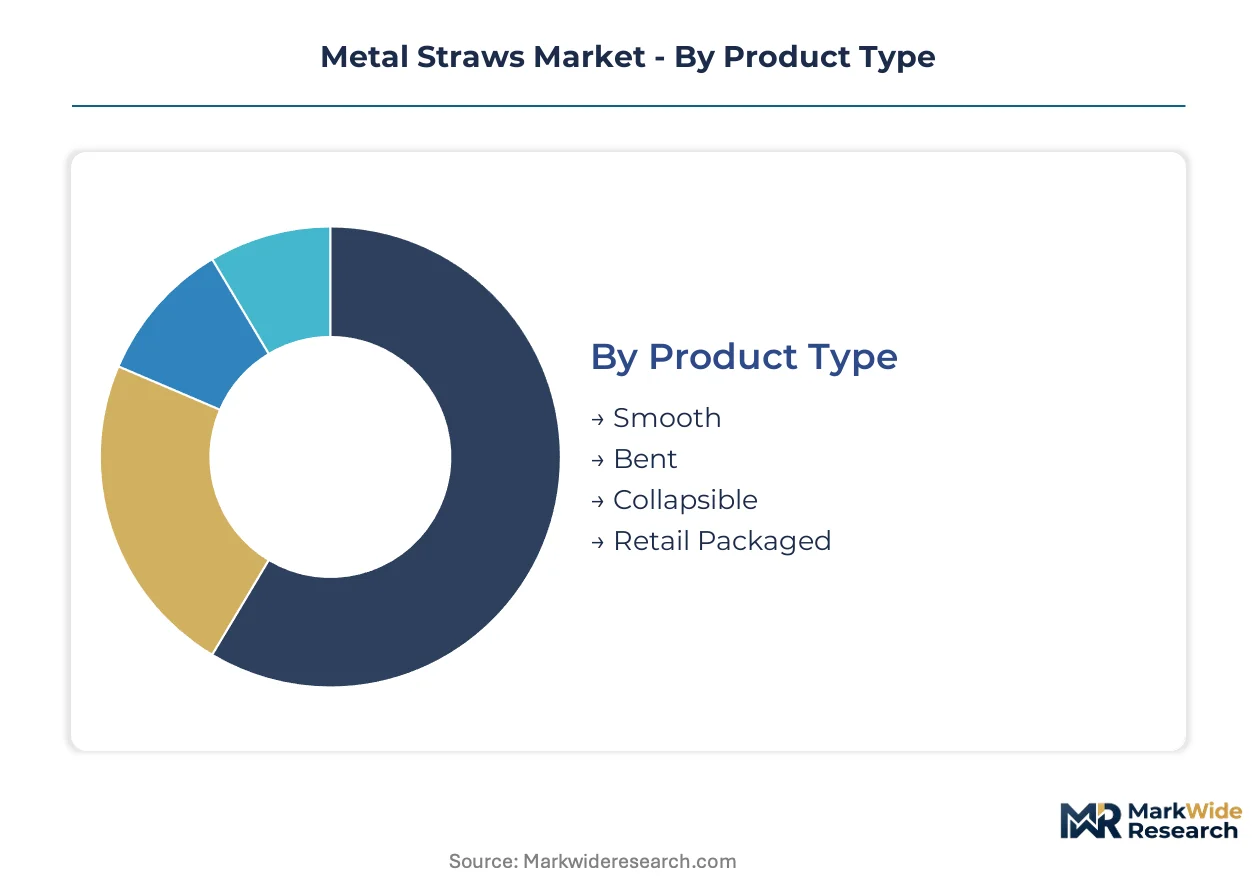
Metal straw purchasing patterns diverge sharply between foodservice procurement teams and household retail buyers. Each segment demands distinct material certifications, packaging formats, and after-sales support intensity that reshape supplier margin structures.
Product Type:
After-sales-service intensity varies dramatically across product formats, with collapsible designs requiring replacement-part programs and bent variants needing dimensional consistency guarantees.
- Smooth:Straight cylindrical tubes with uniform 6–8 mm interior diameter dominate high-volume foodservice contracts. Melbourne and Portland cafe chains specify electropolished 304-grade smooth straws for standardized cleaning protocols.
- Bent:Angled neck designs with 45-degree curvature accommodate tumbler lids and travel mugs. German specialty coffee roasters favor bent straws for branded merchandise programs targeting commuter segments.
- Collapsible:Telescoping segments with silicone joint seals enable pocket-sized portability. Outdoor recreation retailers in Australia stock collapsible variants for hiking and camping accessory sets.
- Retail Packaged:Multi-piece sets with cleaning brushes and carrying pouches command premium shelf positioning. Scandinavian design retailers bundle retail packaged straws with matching cutlery for gift-market penetration.
Smooth straws hold the largest share; momentum sits with collapsible designs gaining traction in outdoor recreation channels.
Material:
Cost tier stratification separates commodity-grade stainless from aerospace titanium, with aluminum and copper occupying niche positioning.
- Stainless Steel:304-grade austenitic alloys with 18% chromium and 8% nickel content provide food-grade corrosion resistance. REACH Annex XVII compliance documentation from Vietnamese electropolishing workshops satisfies EU distributor requirements.
- Titanium:Grade 2 commercially pure titanium offers 40% weight reduction and hypoallergenic properties. Japanese outdoor equipment manufacturers source titanium straws for ultralight backpacking kit integrations.
- Aluminum:Anodized 6061-T6 alloy variants appeal to price-sensitive promotional markets. Event catering suppliers in California specify aluminum for single-season festival contracts.
- Copper:Antimicrobial surface properties attract wellness-positioned hospitality brands. Ayurvedic-focused cafe concepts in India procure copper straws for traditional beverage service differentiation.
Stainless steel commands volume leadership; titanium is climbing the fastest as premium outdoor and aviation segments expand procurement.
Feature:
Application requirements dictate which feature bundles justify price premiums versus baseline compliance.
- Reusable:Core value proposition validated through lifecycle assessment documentation. Corporate sustainability officers at US quick-service chains mandate reusable certification for supplier qualification.
- Eco-Friendly:Carbon footprint labeling and recycled-content claims support retail marketing. EU Green Deal alignment requirements elevate eco-friendly positioning in German and French procurement tenders.
- Dishwasher Safe:High-temperature tolerance testing to 70°C ensures automated sanitation compatibility. Seattle and Vancouver municipal health departments require dishwasher safe verification for foodservice permits.
- Insulated:Double-wall construction with vacuum-sealed air gaps reduces thermal transfer. Klean Kanteen bundles insulated straws with temperature-retention tumblers for household channel expansion.
Dishwasher safe specifications dominate foodservice procurement; insulated variants are gaining share fastest in premium household retail.
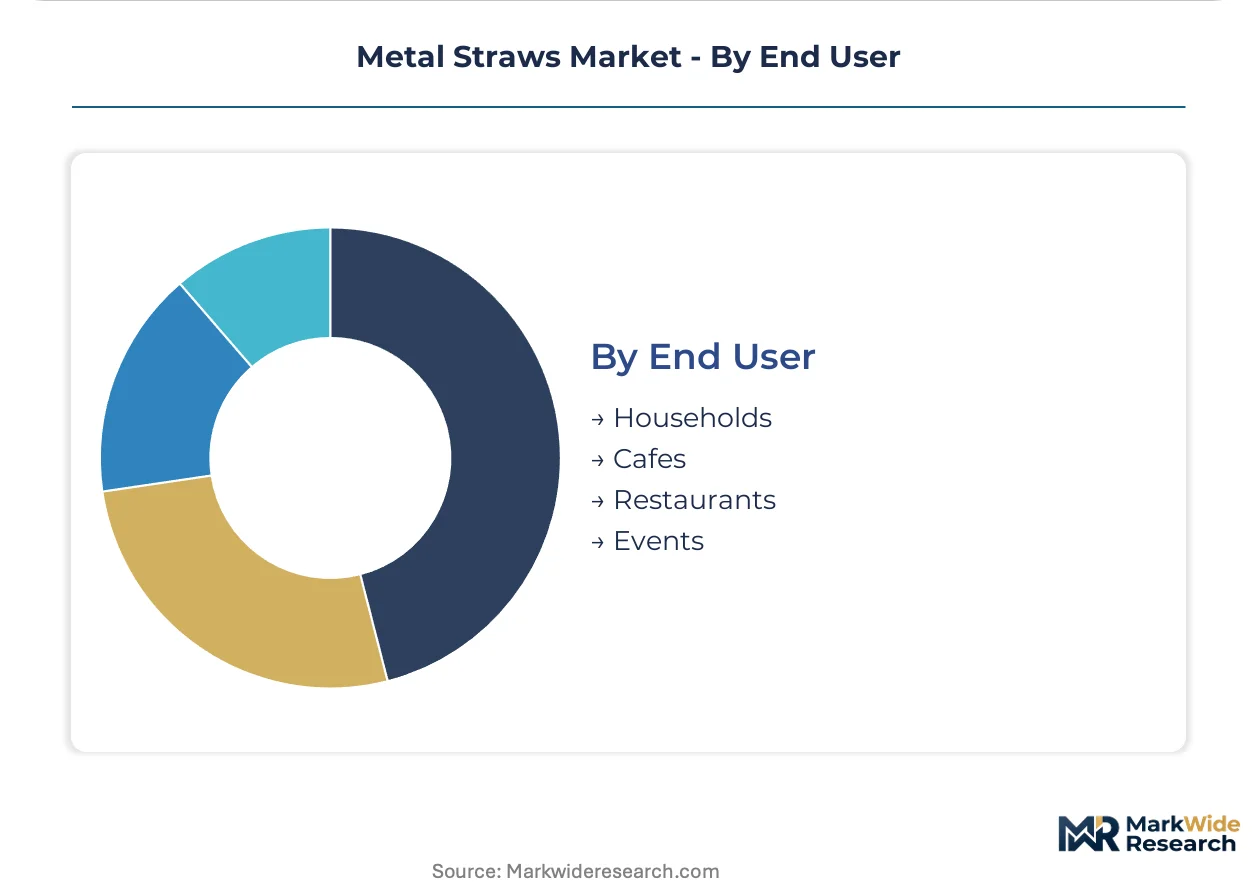
End User:
Customer type determines order frequency, batch size, and contract structure across the demand base.
- Households:Individual consumers purchasing 4–6 piece sets through retail and direct-to-consumer channels. Amazon and specialty kitchenware retailers drive seasonal volume spikes around holiday gifting periods.
- Cafes:Independent and chain coffee shops replacing plastic straws with branded reusable alternatives. Berlin and Copenhagen cafe clusters consolidate procurement through regional distributor partnerships.
- Restaurants:Full-service dining establishments requiring coordinated tableware aesthetics. California's statewide straw-upon-request law accelerates restaurant procurement decisions.
- Events:Festival organizers and wedding planners sourcing bulk disposable-replacement inventory. Australian outdoor event operators specify metal straws for sustainability credentialing of major music festivals.
Cafes and restaurants hold the largest combined share; events represent the steepest expansion trajectory as festival sustainability mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foodservice procurement teams in urban corridor markets drive regional demand concentration, with regulatory enforcement timelines determining adoption velocity across national boundaries.
United States
California's statewide straw-upon-request law and municipal ordinances in Seattle and Portland accelerate cafe procurement decisions. FDA food-contact substance regulations govern material composition and migration limits for imported metalware. Specialty coffee shop clusters in the Pacific Northwest generate dense order volumes that justify distributor inventory positioning.
Germany
Berlin cafe chains and Munich restaurant groups consolidate procurement through regional distributor partnerships. Extended producer responsibility frameworks reshape packaging and take-back obligations for reusable utensil brands. The North Rhine-Westphalia industrial corridor hosts electropolishing workshops serving EU distributor requirements.
Australia
Melbourne's specialty coffee density generates concentrated order volumes from independent and chain operators. TGA food-contact standards align with FDA migration protocols for imported stainless steel products. Outdoor event operators in Queensland specify metal straws for sustainability credentialing of major music festivals.
France
Parisian cafe chains require batch-specific REACH Annex XVII nickel release testing certificates from suppliers. The EU Single-Use Plastics Directive compresses substitution timelines for foodservice operators. Île-de-France procurement teams bundle reusable straws with coordinated cutlery programs for quick-service contracts.
Vietnam
Ho Chi Minh City workshops supply electropolished 304-grade straws to EU and Australian distributors. Vietnamese manufacturers leverage robotic finishing lines to reduce unit labor costs for interior surface smoothing. Direct partnerships with European brands anchor Bambaw's regional supply chain control.
Metal Straws Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. Stainless steel fabricators from Vietnamese workshops and Chinese manufacturing clusters supply private-label programs for Western distributors. Three archetypes dominate: beverage-container bundlers leveraging vacuum-insulation expertise, direct-import specialists controlling Asian workshop relationships, and collapsible-design innovators competing on portability. Consolidation moves center on distributor partnership exclusivity and electropolishing capacity lock-ups.
Within the bundler archetype, Klean Kanteen exemplifies channel expansion through tumbler-straw attachment systems. Bambaw represents direct-import specialists with Vietnamese workshop partnerships. Final Straw occupies the portability-driven tier with collapsible designs. These three anchors illustrate how competitive positioning diverges between foodservice procurement and household retail channels without requiring specific product or technology claims.
| Leading Market Players |
|---|
| Simply Straws |
| Bambaw |
| Klean Kanteen |
| Mulled Mind |
| Final Straw |
| Hydro Flask |
| Cheeki |
| Jungle Straws |
| Strawesome |
| Others |
Value Chain & Pricing Dynamics
Guangdong province electropolishing workshops anchor global food-grade surface finishing capacity, concentrating margin capture among Vietnamese and Chinese contract manufacturers while Western brands absorb London Metal Exchange nickel volatility through indexed contract structures.
Pricing Analysis
Cost-plus contracts with London Metal Exchange nickel indexation dominate 304-grade stainless procurement, with foodservice distributors facing compressed buffers when LME prices spike during fixed-price retail commitments. Price differentiation hinges on REACH Annex XVII certification tier and robotic finishing line scale, with Scandinavian cafe chains paying premiums for batch-specific testing documentation. Pricing pressure stems from silicone-tip collapsible alternatives capturing outdoor recreation demand. Household retail buyers exhibit highest price sensitivity, while German extended producer responsibility compliance-ready suppliers command lowest sensitivity.
Supply Chain Analysis
Feedstock 304-grade stainless steel coil draws from Chinese, Indonesian, and Indian mill complexes, with nickel content tethering finished straw costs to volatile commodity benchmarks. Robotic electropolishing equipment, precision laser-welding systems, and food-grade cleaning brush accessories constitute critical component dependencies. Single-source vulnerability concentrates in Guangdong province finishing workshops serving Western brand specifications. Distribution runs through regional foodservice distributors in Berlin, Melbourne, and Portland, with direct-to-consumer retail bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Replacement-part programs for collapsible straw silicone seals represent a service-attach layer expanding faster than hardware unit sales, as outdoor recreation retailers build recurring revenue through joint and brush subscription replenishment.
For Market Incumbents: Entrench electropolishing capacity through exclusive Vietnamese workshop partnerships before German take-back obligation pilots harden compliance barriers. Lock Berlin and Copenhagen cafe distributor relationships against direct-import specialists. FDA food-contact substance notification timelines for novel color coatings threaten product launch velocity; preemptive 120-day pre-market review submissions defend launch cadence. For New Entrants and Emerging Players: Establish a beachhead in Australian outdoor event sustainability credentialing, where festival operators face procurement mandates without established supplier relationships. Queensland music festival operators and Western Australian camping retailers present white-space targets. A go-to-market angle bundling metal straws with carbon-offset documentation penetrates corporate sustainability officer procurement committees faster than commodity positioning. For Investors and Strategic Acquirers: Capital is best deployed toward direct-import specialists controlling Ho Chi Minh City workshop relationships and REACH compliance documentation capabilities. Long-term viability over the mid-decade horizon favors suppliers with backward integration into robotic finishing lines rather than pure trading intermediaries. The signal to watch is consolidation of Scandinavian cafe procurement under single-source reusable utensil contracts, indicating tipping point velocity for compliant supplier M&A premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Electropolishing Capacity Lock-up | Exclusive Vietnamese workshop partnerships secure REACH-compliant supply against German EPR tightening. |
| Replacement-Part Subscription Launch | Silicone seal and brush replenishment programs capture recurring revenue from outdoor retailers. |
| FDA Pre-Market Notification Pipeline | 120-day review cycle management accelerates colored straw launches ahead of competitor delays. |
| Airline Amenity Kit Penetration | Premium cabin catering contracts open titanium straw volume in aviation supply chains. |
| Extended Producer Responsibility Compliance | German and French take-back pilot readiness creates first-mover distributor exclusivity. |
Study Parameters
Initial hypotheses were tested against primary input from foodservice procurement directors, sustainability officers at quick-service chains, Vietnamese workshop operations managers, and electropolishing equipment suppliers, then refined against customs trade records, FDA food-contact substance filings, EU Single-Use Plastics Directive implementation timelines, and REACH Annex XVII testing documentation databases. Bottom-up cafe and restaurant order volume estimates triangulated with top-down metal straw import value aggregation across the analysis window.
Demand-supply balance modeling across product type, material grade, end-user channel, and regional regulatory cluster generated volume and value outputs throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against macroeconomic consumption indicators. Industry-specific forecast inputs incorporated Berlin and Melbourne cafe opening rates, California straw-upon-request enforcement intensity, and London Metal Exchange nickel price band assumptions.
Stress conditions across LME nickel volatility, FDA notification backlog duration, and German EPR implementation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about electropolishing automation adoption curves and municipal plastic ban synchronization. Cross-checking against Pacific Northwest cafe distributor inventory positioning data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
United States Electric Vegetable Choppers Market
Consumer Goods
North America Athletic Footwear Market
Consumer Goods
Mushroom Beauty Products Market
Consumer Goods
Cordless Garden Equipment Market
Consumer Goods
Pearl Jewelry Market
Consumer Goods
Luxury Vegan Men's Fashion Market
Consumer Goods
Russia Household Electric Grill Market
Consumer Goods
Gaming Mouse Market
Consumer Goods
Decompression Toys Market
Consumer Goods
Magnetic Fake Eyelashes Market
Consumer Goods
US Pet Wearable Market
Consumer Goods
Hair Removal Wax Market
Consumer Goods
Global Monitor Headphones (in-Ear Monitors) Market
Consumer Goods
Europe Vegan Cosmetics Market
Consumer Goods
Home Theater Systems Market
Consumer Goods
Global Swimming Pool Market