
 Menthol Cigarette Market | 2026-2036
Menthol Cigarette Market Size, Share, and Industry Trends Forecast 2026-2036
Menthol Cigarette Market Intelligence
Southeast Asia is reconfiguring menthol cigarette manufacturing capacity as regional consumption patterns shift. British American Tobacco p.l.c. leverages its integrated supply chain across Indonesia and Malaysia to sustain cost advantages. Philip Morris International Inc. anchors its heated-tobacco menthol portfolio in Japan while navigating regulatory complexity. Imperial Brands PLC specializes in slim-format menthol variants for price-sensitive African markets.
Menthol cigarettes contain tobacco blended with L-menthol crystals, typically applied at 0.3–1.0% by weight through casing or top-dressing processes to produce cooling sensory effects. The product serves commercial demand for flavored tobacco experiences that mask harshness and appeal to younger demographics. King Size formats dominate volume across convenience store channels where impulse purchasing drives turnover. Super Slim segments attract urban female smokers in East Asian cities, while Premium price tiers capture margin pools in Gulf state duty-free environments.
The FDA's ongoing menthol ban proposal and EU Tobacco Products Directive flavor restrictions create divergent compliance landscapes for multinational manufacturers. Japan's Ministry of Health, Labour and Welfare maintains stricter additive disclosure standards than ASEAN regulators, fragmenting product formulation strategies. Stakeholders must monitor regulatory enforcement timelines and pre-position alternative portfolios before flavor prohibitions crystallize in core revenue markets.
Market Dynamics
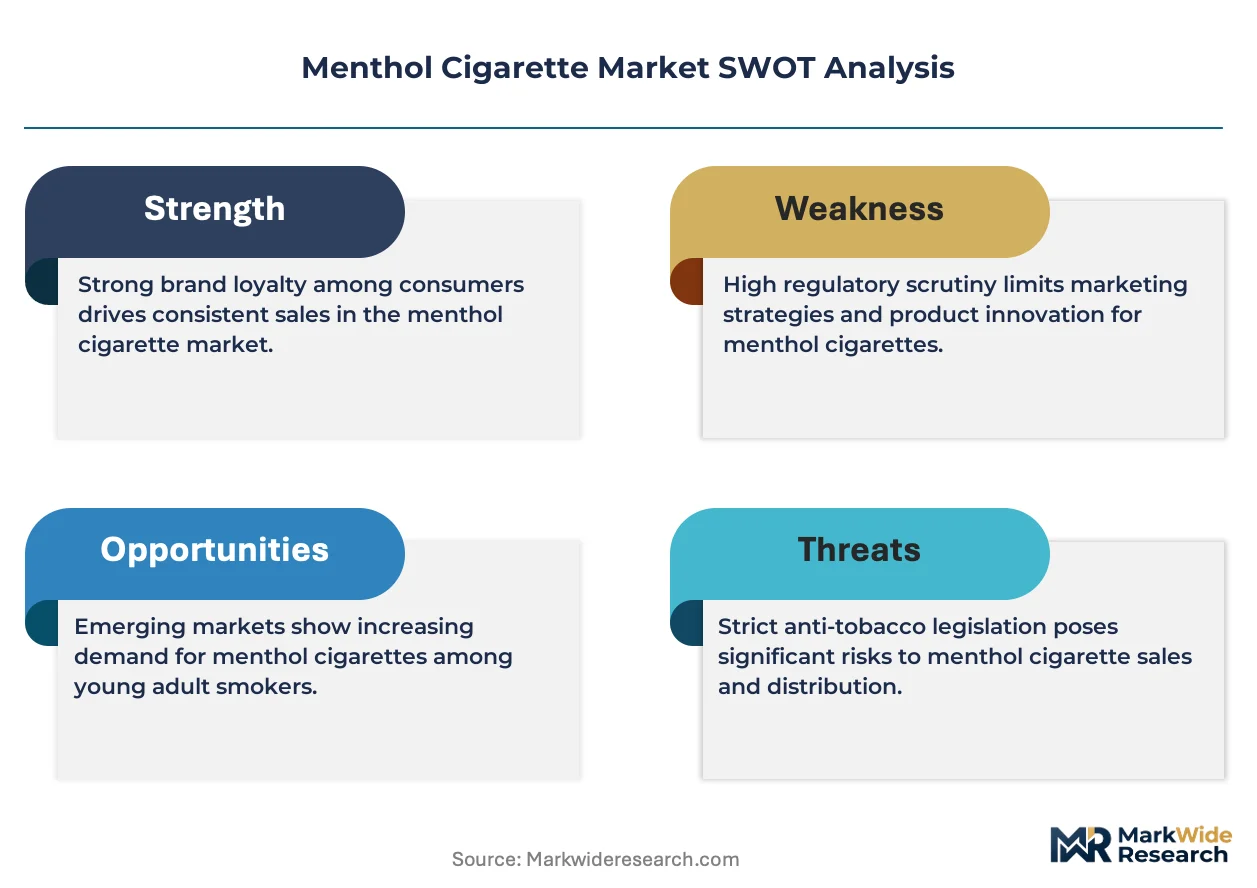
Regulatory fragmentation between flavor-permissive and flavor-restrictive jurisdictions is forcing manufacturers to maintain dual product portfolios, inflating compliance costs and compressing margins on standardized production runs.
Growth Catalysts
- Young adult uptake in emerging economies:Indonesia, Philippines, and Vietnam exhibit sustained preference for menthol variants among smokers aged 18-25, driving volume expansion in convenience retail channels.
- EU Tobacco Products Directive gaps:Certain member states maintain transitional exemptions for menthol capsule filters, creating temporary market windows before full prohibition enforcement.
- Heated-tobacco platform migration:Device-compatible menthol consumables are capturing smokers transitioning from combustible products in Japan and South Korea.
Market Restraints
- L-menthol input cost volatility:Synthetic menthol production concentrates in Chinese chemical manufacturing clusters, exposing formulations to feedstock price swings.
- FDA deeming rule uncertainty:Pending menthol cigarette ban proposals in the United States freeze capital allocation decisions for North American manufacturing footprint.
- Heated-tobacco substitution:IQOS and competing platforms displace combustible menthol volume in premium urban segments across Tokyo, Seoul, and Milan.
Strategic Opportunities
- African slim-format penetration:Nigeria, Kenya, and Ghana present underdeveloped menthol variant distribution relative to total tobacco consumption.
- ASEAN regulatory arbitrage:Indonesia and Malaysia maintain permissive flavor additive standards while Thailand and Singapore tighten restrictions, enabling portfolio optimization.
- Duty-free channel premiumization:Gulf state airports and Southeast Asian border zones sustain higher-margin menthol SKUs exempt from domestic excise structures.
Industry Challenges
- Dual-formulation manufacturing complexity:Parallel production lines for menthol and non-menthol variants strain equipment utilization and quality control protocols.
- Flavor disclosure standardization gaps:Japan's Ministry of Health, Labour and Welfare mandates additive specificity that conflicts with ASEAN regulatory reporting thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Menthol Cigarette Market |
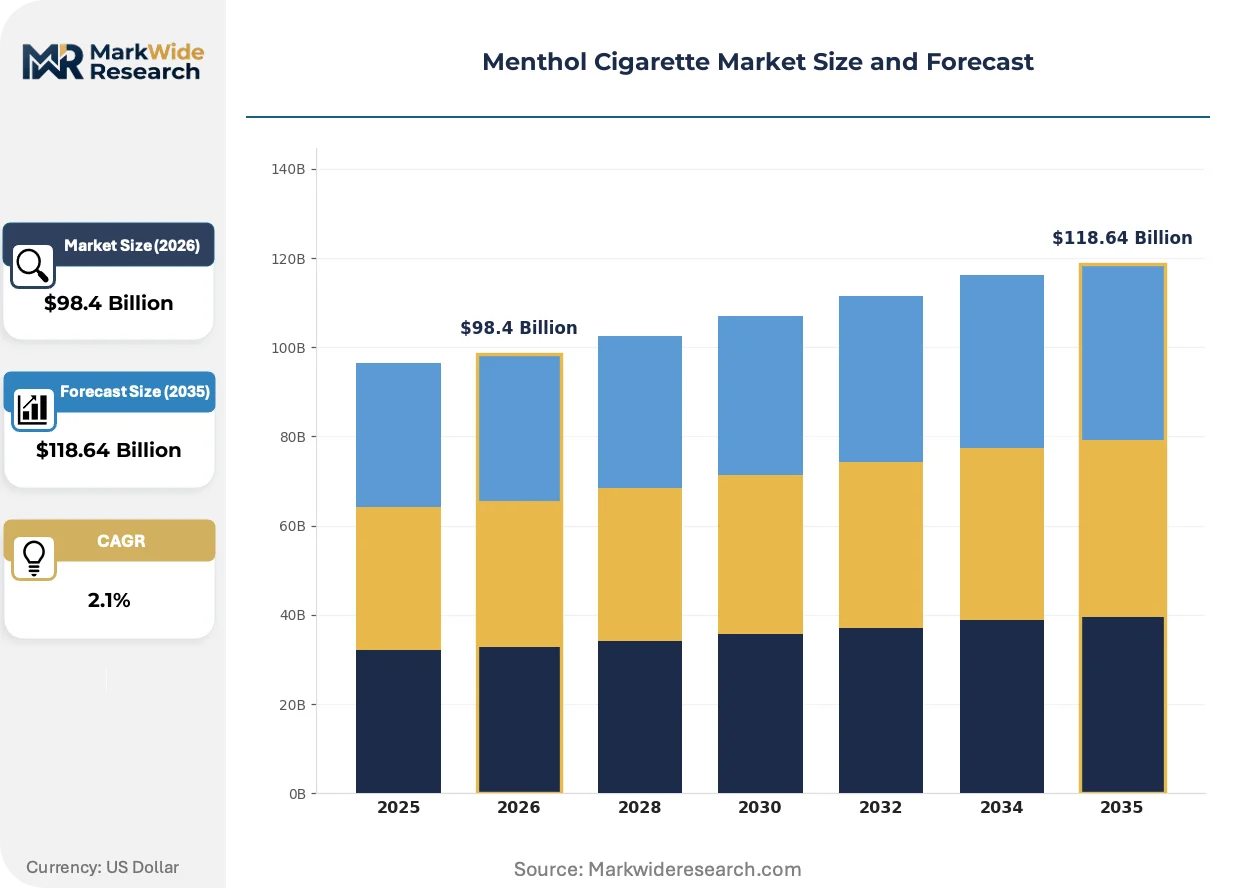
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $118.64 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, King Size, Super Slim, Menthol Infused End User: Seasoned Smokers, Occasional Smokers, New Smokers, Cessation Seekers Distribution Channel: Convenience Stores, Supermarkets, Online Retailers, Tobacco Shops Price Tier: Premium, Mid-Range, Budget, Value Packs |
| Companies Covered | Reynolds American Inc., Japan Tobacco Inc., Philip Morris International Inc., KT&G Corporation, China National Tobacco Corporation, Altria Group, Imperial Brands PLC, Liggett Vector Brands LLC, British American Tobacco p.l.c., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Menthol Cigarette Market Strategic Shifts & Innovations
Product engineering and distribution models are adapting to bifurcated regulatory environments, with manufacturers deploying distinct technical and commercial strategies for flavor-restrictive versus flavor-permissive markets.
Capsule-in-filter technology is digitizing quality assurance protocols across manufacturing lines. High-speed imaging systems and spectral analysis now verify menthol bead integrity at 20,000 units per minute. BAT and JTI facilities in Indonesia and Malaysia are retrofitting legacy equipment with these systems to reduce defect rates and compress batch release cycles.
REACH chemical registration requirements are reshaping menthol sourcing strategies for European-bound products. ECHA substance evaluation protocols now demand granular supply chain documentation for synthetic versus natural L-menthol origins. Manufacturers are dual-qualifying Indian and Chinese chemical suppliers to maintain formulation flexibility as registration deadlines approach.
Urban female smokers in East Asian metropolitan centers are fragmenting demand toward ultra-slim and superslim formats. Convenience retailers in Tokyo, Taipei, and Shanghai report capsule-activated variants outselling conventional menthol cigarettes among demographic cohorts under 35. This consumption-pattern shift is compressing SKU lifecycle timelines and accelerating packaging refresh cycles.
Menthol Cigarette Market Segmentation
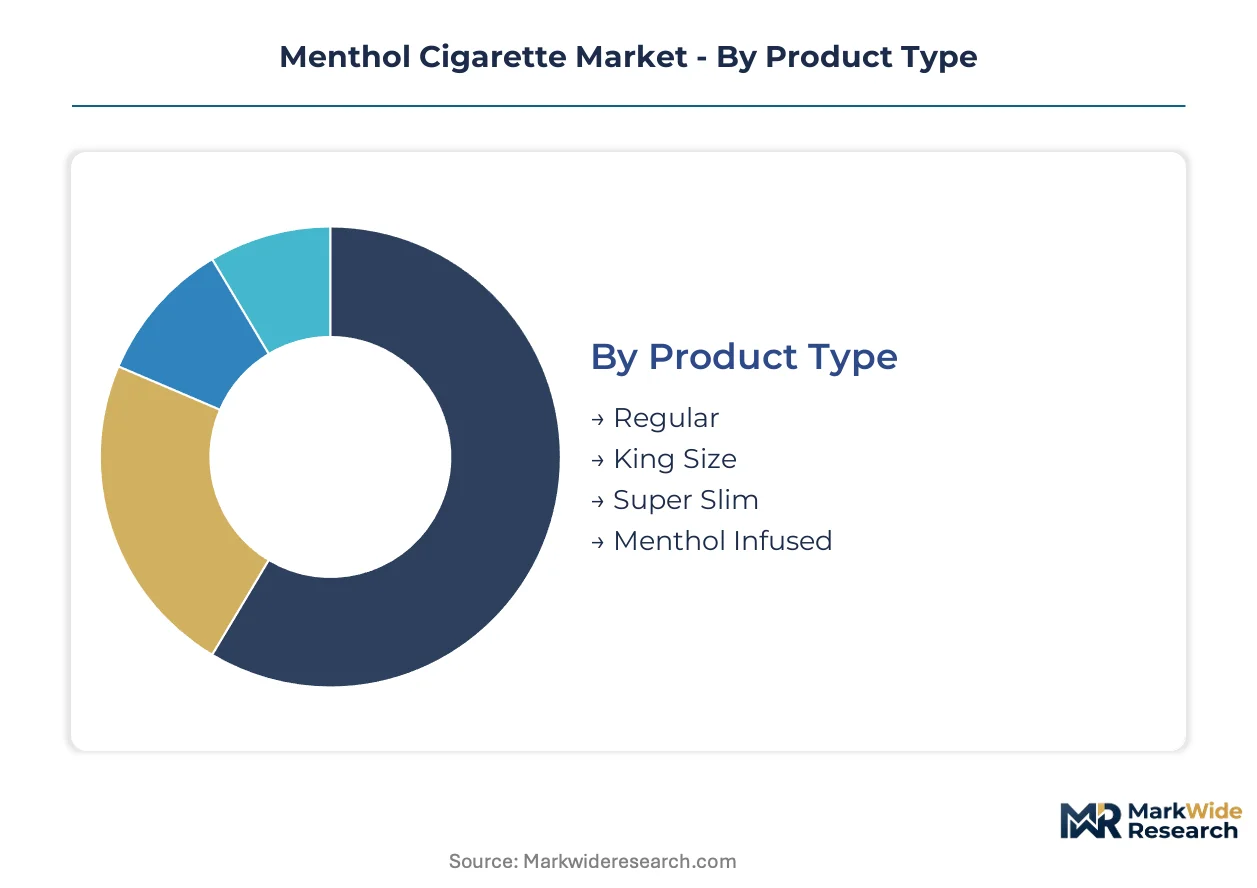
Menthol cigarette manufacturers configure production lines around four distinct segmentation axes. Each dimension commands separate inventory management, pricing architecture, and channel allocation strategies that determine margin capture across regulatory environments.
Product Type:
Physical format determines manufacturing equipment, menthol application method, and retail placement priority.
- King Size:Standard 84mm length with conventional filter construction dominates convenience store velocity. Indonesian and Malaysian factories run dedicated high-speed lines for this format to serve ASEAN impulse purchasing patterns.
- Super Slim:17mm circumference variants incorporate capsule-in-filter technology for activation-controlled menthol release. Urban female smokers in Tokyo and Shanghai drive demand concentration for this format.
- Regular:Traditional 70-72mm length maintains volume in price-sensitive African markets where packaging simplicity reduces unit economics.
- Menthol Infused:Enhanced casing processes apply L-menthol at upper concentration thresholds for pronounced sensory impact in Gulf state duty-free channels.
King Size holds installed capacity. Super Slim is rotating up the share rankings.
End User:
Smoker lifecycle stage dictates product positioning, nicotine engineering, and communication strategy.
- New Smokers:Young adult initiates aged 18-25 in Indonesia, Philippines, and Vietnam exhibit strong preference for menthol's masking properties. Regulatory scrutiny of youth-targeted flavor marketing constrains promotional tactics in this segment.
- Seasoned Smokers:Established consumers maintain brand loyalty but demonstrate willingness to migrate toward heated-tobacco menthol alternatives in Japanese and South Korean urban centers.
- Occasional Smokers:Social consumption patterns favor single-stick or small-pack purchases through convenience retail in Southeast Asian cities.
- Cessation Seekers:Declining cohort seeking reduced-harm alternatives; menthol's sensory satisfaction partially offsets switching friction toward nicotine replacement therapies.
Seasoned Smokers anchor current revenue. New Smokers are climbing the fastest despite regulatory headwinds.
Distribution Channel:
Channel selection determines excise exposure, price realization, and consumer access architecture.
- Convenience Stores:Impulse-driven high-frequency outlets dominate volume in Indonesia and Philippines. Point-of-sale display regulations vary by municipality, fragmenting merchandising protocols.
- Tobacco Shops:Specialist retailers capture enthusiast demand for premium capsule variants and limited-edition releases in Japanese metropolitan districts.
- Supermarkets:Self-service formats face escalating flavor restriction compliance in EU member states transitioning menthol SKUs toward clearance.
- Online Retailers:Digital channels face prohibition in multiple jurisdictions; where permitted, age verification requirements add transaction friction.
Convenience Stores maintain the broadest footprint. Tobacco Shops are gaining margin contribution fastest.
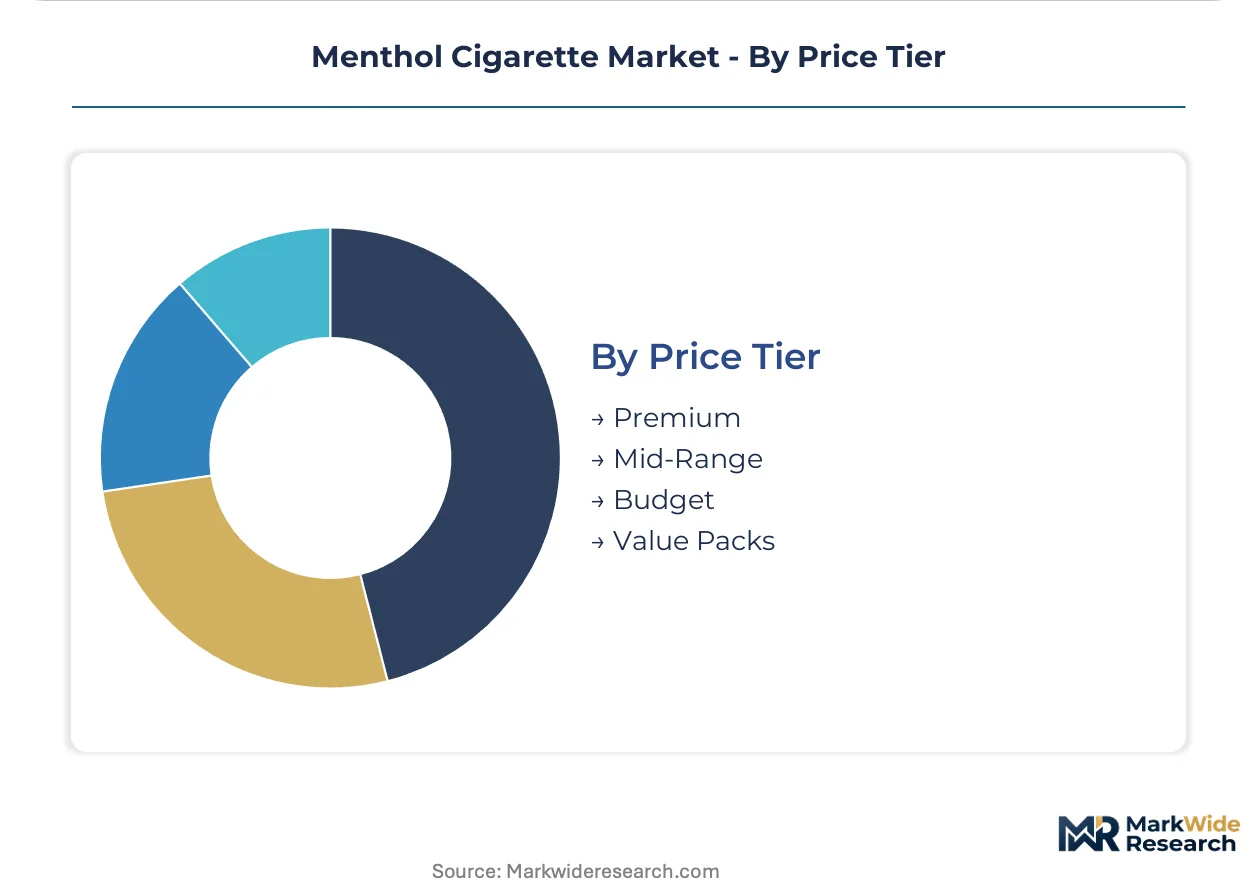
Price Tier:
Pricing architecture segments consumers by willingness-to-pay and occasions of consumption.
- Premium:Gulf state airports and Southeast Asian border zones sustain higher-margin SKUs exempt from domestic excise structures. Packaging innovation and capsule technology justify price elevation.
- Mid-Range:Standard menthol variants balance quality signaling with accessibility across Malaysian and Thai urban retail networks.
- Budget:Price-competitive positioning targets rural Indonesian and Vietnamese markets where excise incidence compresses manufacturer margins.
- Value Packs:Multi-unit bundling reduces per-stick cost for heavy consumption households in African markets including Nigeria and Kenya.
Premium commands absolute margin dollars. Mid-Range is expanding most quickly across emerging market middle-class cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic menthol production clusters in Chinese chemical manufacturing hubs, while finished cigarette assembly concentrates in Southeast Asian free-trade zones. Manufacturers maintain dual-formulation capabilities to serve flavor-restrictive and flavor-permissive jurisdictions simultaneously.
United States
FDA deeming rule uncertainty freezes capital allocation for North American manufacturing footprint. The agency's pending menthol ban proposal forces portfolio pre-positioning toward non-flavored alternatives. Tobacco production concentrates in North Carolina and Kentucky, where manufacturers test reduced-risk product lines.
Indonesia
Young adult smokers aged 18-25 drive sustained menthol variant preference through convenience retail channels. The national regulator maintains permissive flavor additive standards relative to ASEAN neighbors. Manufacturing clusters in Java and Sumatra export throughout Southeast Asia.
Japan
Heated-tobacco menthol consumables capture smokers transitioning from combustible products in Tokyo and Osaka. The Ministry of Health, Labour and Welfare mandates stricter additive disclosure than regional counterparts. Nagoya-based production facilities specialize in device-compatible cartridge assembly.
Germany
EU Tobacco Products Directive enforcement eliminates domestic menthol sales while transitional capsule filter exemptions persist in certain member states. ECHA REACH registration requirements reshape L-menthol sourcing documentation. Hamburg and Bremen ports handle import logistics for residual continental demand.
United Arab Emirates
Gulf state airports sustain premium-tier menthol SKUs exempt from domestic excise structures. Duty-free channels capture margin pools from transit passengers. Dubai and Abu Dhabi distribution hubs serve re-export flows into African markets.
Menthol Cigarette Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream. The menthol cigarette sector exhibits consolidated structure among multinational tobacco conglomerates with integrated supply chains. Three archetypes dominate: vertically integrated leaf-to-retail operators, heated-tobacco platform owners, and regional specialists in slim-format variants. Competitive moves center on dual-formulation manufacturing investments and heated-tobacco portfolio migration.
Among Anglo-American conglomerates, British American Tobacco p.l.c. and Imperial Brands PLC occupy positions spanning combustible and reduced-risk categories. Philip Morris International Inc. anchors the heated-tobacco platform tier. These three exemplify divergent strategic responses to regulatory fragmentation—portfolio diversification versus platform substitution versus regional specialization.
| Leading Market Players |
|---|
| Reynolds American Inc. |
| Japan Tobacco Inc. |
| Philip Morris International Inc. |
| KT&G Corporation |
| China National Tobacco Corporation |
| Altria Group |
| Imperial Brands PLC |
| Liggett Vector Brands LLC |
| British American Tobacco p.l.c. |
| Others |
Cost & Logistics Intelligence
The Malacca Strait shipping corridor connects Chinese L-menthol chemical clusters to Indonesian and Malaysian manufacturing hubs, with freight cost volatility directly amplifying margin compression in budget-tier SKUs while enabling premium-tier price elevation in Gulf duty-free channels.
Pricing Analysis
The EU Tobacco Products Directive dictates the pricing tier structure across European markets, with three-tier pricing separating premium capsule variants from standard menthol from economy formats based on additive disclosure compliance costs. Price differentiation rests on certification-grade menthol sourcing and Gulf state excise exemptions. Pricing pressure stems from FDA deeming rule uncertainty freezing North American capital allocation. Budget-tier buyers in rural Indonesia exhibit highest price sensitivity; premium-tier purchasers in UAE airports show lowest.
Supply Chain Analysis
China National Tobacco Corporation and British American Tobacco p.l.c. hold captive menthol production capacity across Java and Sumatra facilities. Geographic supply concentrates in China for synthetic L-menthol, Indonesia for finished assembly, and Malaysia for regional distribution. Raw material dependencies include mentha arvensis feedstock, chemical synthesis catalysts, and specialty filter papers. Single-source vulnerability runs through Chinese chemical manufacturing clusters. Distribution runs through ASEAN free-trade zone logistics networks and Gulf state duty-free retail concessions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The menthol cigarette market functions as a regulatory entrenchment story, where established operators leverage dual-formulation manufacturing capabilities and pre-existing flavor-permissive market access to sustain competitive moats against new entrants facing prohibitive compliance barriers.
For Market Incumbents: Harden dual-formulation manufacturing flexibility by retrofitting Indonesian and Malaysian lines for rapid menthol-to-non-menthol switching ahead of ASEAN regulatory divergence. Deepen backward integration into Chinese L-menthol supply through long-term offtake agreements with state-affiliated chemical manufacturers. Prioritize heated-tobacco platform migration in Japanese and South Korean urban centers where IQOS substitution threatens combustible volume.
For New Entrants and Emerging Players: Establish a beachhead in African slim-format segments where Imperial Brands PLC's premium positioning leaves price-sensitive volume undefended in Nigeria, Kenya, and Ghana. Target menthol capsule technology licensing from established ASEAN suppliers rather than proprietary R&D investment. Pursue distribution partnerships with convenience retail chains in Indonesian secondary cities where regulatory scrutiny remains lighter than Jakarta.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors heated-tobacco platform owners over pure combustible specialists given Japanese and South Korean migration patterns. Long-term viability hinges on regulatory arbitrage duration across ASEAN markets versus EU and US prohibition timelines. Acquisition target archetype: regional slim-format specialists with established African distribution. Signal to watch: FDA menthol ban enforcement timing and EU Tobacco Products Directive transitional exemption expirations.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Formulation Manufacturing Retrofit | Enables rapid product line switching between menthol and non-menthol variants as ASEAN regulatory divergence accelerates. |
| Heated-Tobacco Platform Migration | Captures smoker transition in Tokyo and Seoul where IQOS devices displace combustible menthol volume. |
| African Slim-Format Distribution Expansion | Penetrates underdeveloped menthol variant markets in Lagos and Nairobi where premium positioning leaves volume gaps. |
| L-Menthol Supply Backward Integration | Secures formulation flexibility against Chinese chemical cluster price volatility and REACH registration deadlines. |
| Duty-Free Channel Premiumization | Maximizes margin capture in Dubai and Abu Dhabi airports exempt from domestic excise structures. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with brand managers at multinational tobacco conglomerates, regulatory affairs leads navigating FDA and EU Tobacco Products Directive compliance, convenience retail category buyers in Jakarta and Manila, and plant managers at Indonesian manufacturing facilities. Secondary validation drew from FDA deeming rule dockets, ECHA REACH substance registrations, ASEAN trade statistics, and SEC 10-K filings of listed tobacco manufacturers. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user lifecycle stage, distribution channel, and price tier dimensions.
Calibration anchored volume and value outputs across the projection horizon to historical regulatory enforcement patterns and smoker cohort transition elasticities observed in Japanese heated-tobacco adoption. Segmentation dimensions modeled include physical format specifications, smoker lifecycle positioning, channel excise exposure, and price tier architecture. CAGRs derived from regression analysis against demographic smoking incidence trends and regulatory timeline probability-weighting. Industry-specific forecast inputs incorporated L-menthol feedstock price indices and capsule technology penetration rates in East Asian metropolitan centers.
Sensitivities concentrate around FDA menthol ban enforcement timing, EU Tobacco Products Directive transitional exemption durations, and ASEAN regulatory harmonization pressures. Forecasts embed assumptions regarding smoker substitution elasticity toward heated-tobacco platforms and African market excise trajectory. Cross-checking against customs data for L-menthol feedstock imports and cigarette manufacturing equipment shipments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Heated Tobacco Products Market
Tobacco Products
Flavored Cigar Market
Tobacco Products
Disposable E-Cigarettes Market
Tobacco Products
United States E-Cigarette Market
Tobacco Products
Cigar Tubes Market
Tobacco Products
Cigarette Market
Tobacco Products
Asia-Pacific E Cigarettes Market
Tobacco Products
Tobacco Products Market
Tobacco Products
United States Pipe Tobacco Market
Tobacco Products
Premium Cigarette Market
Tobacco Products
Smokeless Cigarettes Market
Tobacco Products
Liquor Flavored Cigars Market
Tobacco Products
Homemade Cigars Market
Tobacco Products
Premium Tobacco Products Market
Tobacco Products
Europe Cigarette Market
Tobacco Products
Luxury Cigarette Market