
 Mens Pre-Shave Market | 2026-2036
Mens Pre-Shave Market Size, Share, and Industry Trends Forecast 2026-2036
Mens Pre-Shave Market Foresight
The premium-commodity split in men's pre-shave is expanding along ingredient transparency lines. Procter & Gamble (Gillette) leverages scale economics to dominate mass-market gel and foam distribution through supermarket and drugstore channels. Beiersdorf AG anchors its position in European pharmacies with dermatologically tested formulations targeting sensitive skin applications. Proraso specializes in artisanal oil and cream formats that command shelf space in independent barbershops across Italy and export markets.
Men's pre-shave encompasses topical formulations applied before razor contact to soften facial hair, reduce friction, and minimize epidermal trauma; these products typically incorporate humectants, emollients, and lubricating agents such as glycerin, essential oils, or silicones in aqueous or oil-based carriers. Foam and gel formats lead volume through supermarket and drugstore channels, though oil and lotion segments capture disproportionate margin pools in specialty retail and e-commerce where consumers trade up for natural-ingredient positioning. The distribution channel dimension shows online platforms and specialty stores growing fastest as millennials and Gen Z end users research ingredient lists and seek curated shaving experiences beyond mass-market availability.
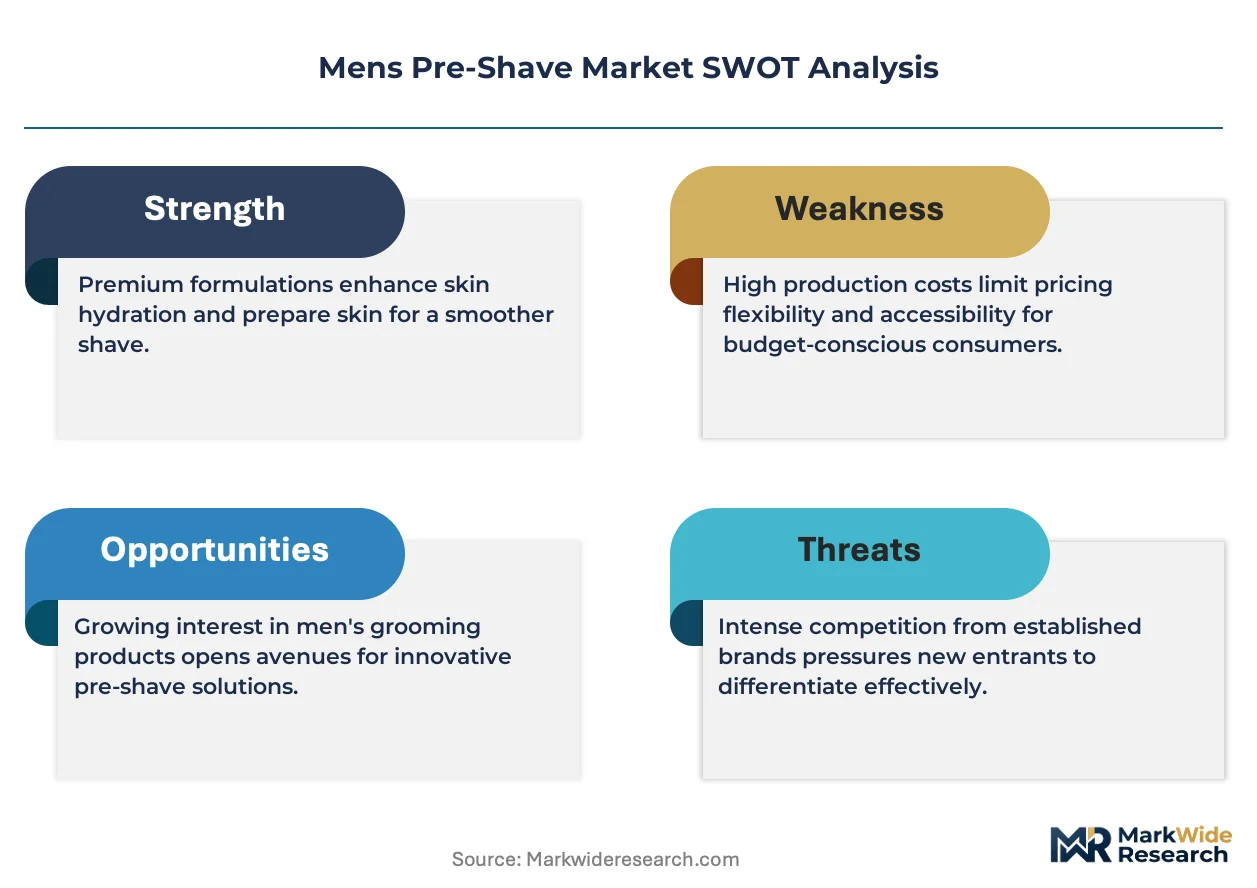
FDA oversight in the United States classifies pre-shave products as cosmetics with strict labeling requirements under the Fair Packaging and Labeling Act, while REACH and the EU Green Deal in Europe mandate hazard communication and restrict certain synthetic preservatives. These frameworks elevate compliance costs for commodity producers but create market access advantages for brands with clean-formulation credentials and documented supply chain transparency. Stakeholders must monitor evolving chemical restriction lists and channel migration patterns to align portfolio investments with where premiumization and regulatory compliance intersect.
Market Dynamics
Barber shops and professional grooming lounges are elevating product expectations among male consumers, creating a bifurcation between mass-market foam formats and artisanal oil-based formulations. This professional channel influence is pulling ingredient transparency requirements upstream into retail.
Growth Catalysts
- EU Green Deal chemical disclosure mandates:REACH regulations are tightening hazard communication requirements for personal care formulations, advantaging brands with documented supply chain transparency over commodity producers.
- Traditional wet-shaving culture in Germany:Sustained premium consumption of pre-shave oils and balms in this market validates higher-margin positioning for natural-ingredient formulations.
- Millennial and Gen Z research behavior:Online platform penetration enables ingredient-list scrutiny and curated shaving experience discovery beyond mass-market availability.
Market Restraints
- Glycerin and essential oil input volatility:Agricultural commodity price swings compress margins for natural-positioned formulations dependent on plant-derived feedstocks.
- Silicone supply concentration in China:Synthetic lubricant ingredient sourcing creates geopolitical exposure for mass-market gel and foam producers.
- FDA cosmetic labeling friction:Strict Fair Packaging and Labeling Act requirements elevate compliance costs for new market entrants relative to established brands with regulatory infrastructure.
Strategic Opportunities
- Underpenetrated Indian male grooming:Rising disposable incomes and urbanization create whitespace for pre-shave education and premium format introduction.
- E-commerce direct-to-consumer channel innovation:Subscription models bypass supermarket shelf-space competition and enable personalized regimen bundling.
- Convergence of skincare and shaving:Dermatologically tested formulations incorporating niacinamide or ceramides capture crossover demand from facial care routines.
Industry Challenges
- Reformulation capex for preservative substitution:Brands must invest in stability testing and shelf-life validation when replacing restricted synthetic preservatives with natural alternatives.
- Barber channel relationship management:Securing placement in independent shops requires field sales investment and education support that mass retail does not demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mens Pre-Shave Market |
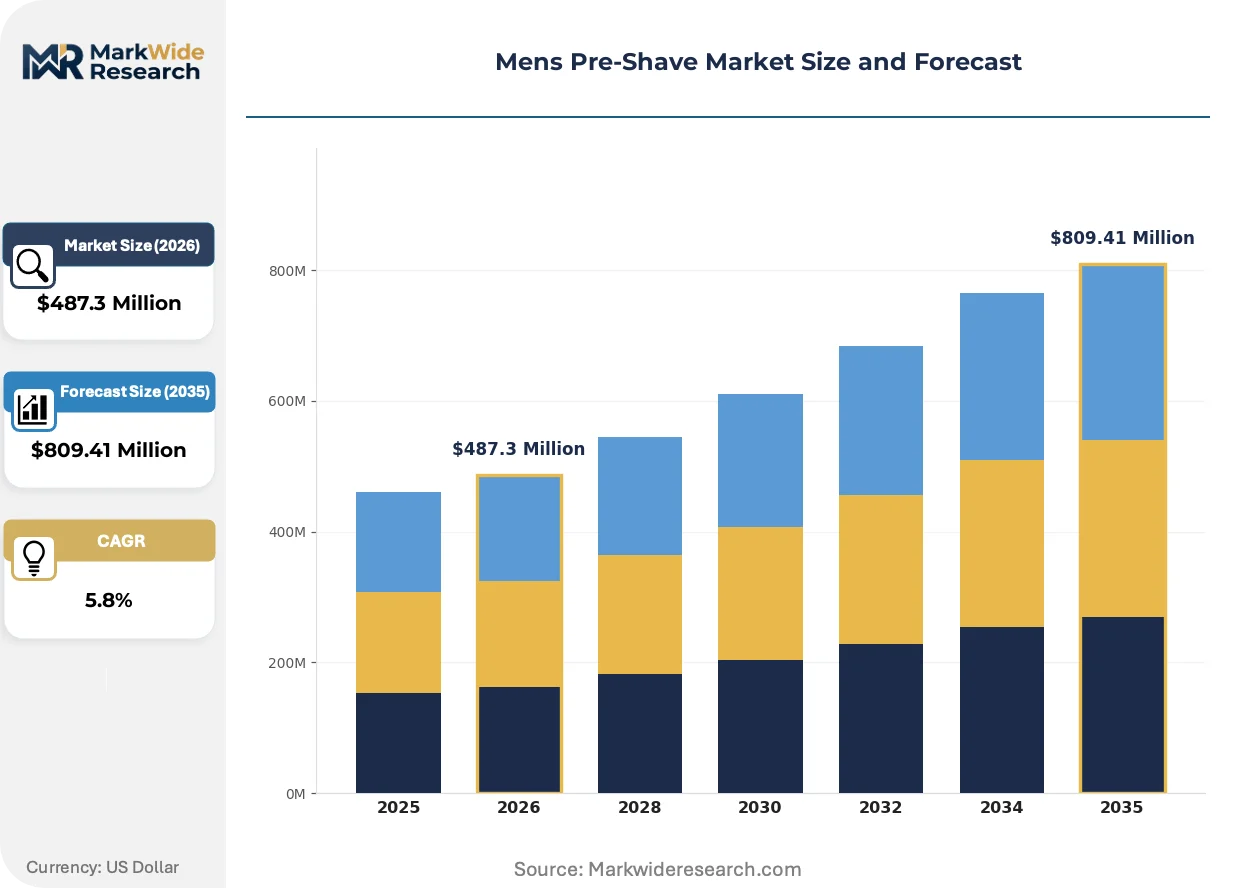
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Gel, Oil, Lotion Application: Sensitive Skin, Normal Skin, Oily Skin, Dry Skin Distribution Channel: Online, Supermarkets, Specialty Stores, Drugstores End User: Millennials, Gen Z, Professionals, Athletes |
| Companies Covered | Procter & Gamble (Gillette), L'Oréal SA, Unilever, Beiersdorf AG, Edgewell Personal Care, The Art of Shaving, Proraso, Colgate-Palmolive Company, Coty Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mens Pre-Shave Market Shifts & Advancements
Ingredient transparency and professional-channel influence are compressing the mass-premium divide, forcing simultaneous innovation in formulation chemistry and distribution architecture.
Plant-derived emollient systems are consolidating market positioning around clean-formulation credentials. Independent barbershops and specialty retailers are adopting these oil and balm formats fastest, displacing petroleum-based predecessors. This consolidation is compressing shelf space for synthetic-dominant mass-market lines in premium channels.
REACH authorization requirements and the EU Green Deal restriction roadmap are accelerating preservative substitution timelines. Formulators must document hazard profiles and source alternatives before sunset dates. Small-batch producers in Italy and Germany are responding fastest, leveraging shorter reformulation cycles than multinational commodity lines.
Subscription-based replenishment is fragmenting traditional supermarket and drugstore purchasing patterns. Younger male consumers in North American and Western European urban centers are abandoning periodic stock-up trips for automated delivery of curated shaving systems. This behavioral shift is compressing brand-switching windows and elevating loyalty program design as a competitive discipline.
Mens Pre-Shave Market Segmentation
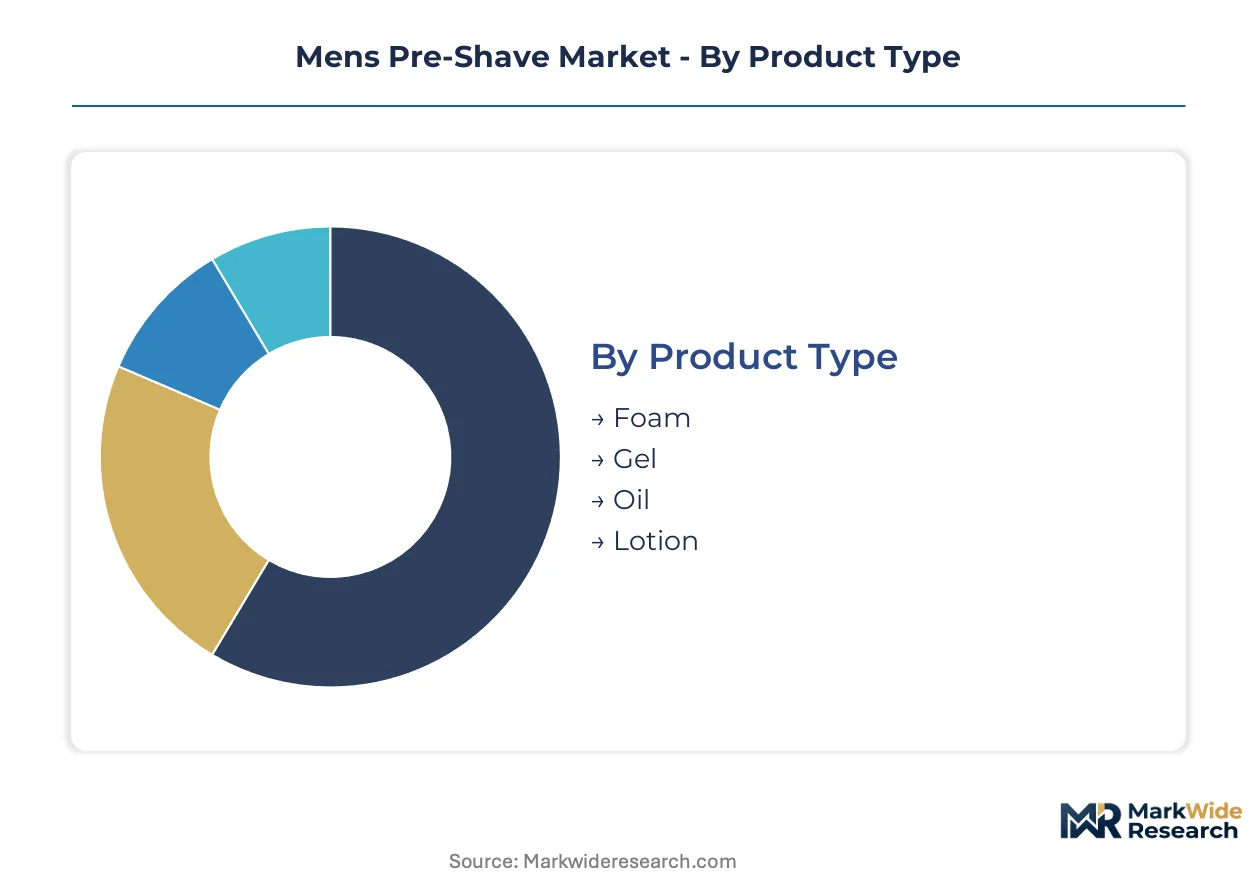
Pre-shave segmentation reveals how capital deployment, regulatory exposure, and channel economics fragment manufacturing priorities. Formulation chemistry and distribution infrastructure create divergent margin profiles across product types and customer cohorts.
Product Type:
Foam and gel production demands the heaviest capital outlay for aerosol propellant systems and high-speed filling lines, while oil and balm manufacturing requires smaller batch equipment but premium ingredient sourcing.
- Foam:Aerosol-dispensed formulations rely on hydrocarbon or compressed gas propellants combined with surfactant-stabilized emulsions. German drugstore chains and US mass retailers move the highest volumes, though REACH propellant restrictions are forcing reformulation investments.
- Gel:Transparent or translucent aqueous systems thickened with carbomers or cellulose derivatives deliver controlled lubrication with visual appeal. Supermarket placement in France and Italy favors gel formats for their shelf stability and consumer familiarity.
- Oil:Plant-derived lipid formulations with jojoba, argan, or sandalwood oils target barbershop channels and e-commerce discovery.
- Lotion:Lower-viscosity aqueous emulsions bridge foam convenience and oil conditioning for transitional users.
Foam absorbs the bulk of installed capacity; oil is expanding most quickly.
Application:
Skin-type targeting determines clinical validation requirements and dermatological testing budgets, with sensitive-skin formulations commanding the steepest R&D investment.
- Sensitive Skin:Fragrance-free, hypoallergenic formulations with minimal preservative loads and barrier-supporting ingredients like allantoin or bisabolol. German pharmacy demand validates premium positioning for dermatologically tested lines.
- Normal Skin:Standard formulations with moderate surfactant loads and conventional preservative systems serve the broadest addressable base. US supermarket and drugstore channels concentrate volume here.
- Oily Skin:Astringent-leaning formulations with witch hazel or tea tree oil to reduce sebum interference with blade glide.
- Dry Skin:Emollient-heavy preparations with shea butter or ceramide complexes for barrier-compromised users.
Normal-skin applications dominate current volume; sensitive-skin positioning gains share fastest.
Distribution Channel:
Channel selection dictates packaging format, margin structure, and customer acquisition cost, with digital-native routes requiring upfront platform investment versus trade spend for physical retail.
- Online:Direct-to-consumer and marketplace platforms enable subscription replenishment and ingredient transparency storytelling. North American millennials and Gen Z cohorts concentrate here, drawn to curated regimen bundling.
- Supermarkets:High-velocity, low-margin environments favor standardized foam and gel formats with prominent shelf placement fees. Volume concentrates in US and UK grocery chains.
- Specialty Stores:Barbershops and grooming lounges in Italy and Germany drive artisanal oil and balm discovery through professional endorsement.
- Drugstores:Pharmacy-regulated environments in France and Germany elevate dermocosmetic credibility for sensitive-skin lines.
Supermarkets absorb the bulk of installed capacity; online channels are climbing the fastest.
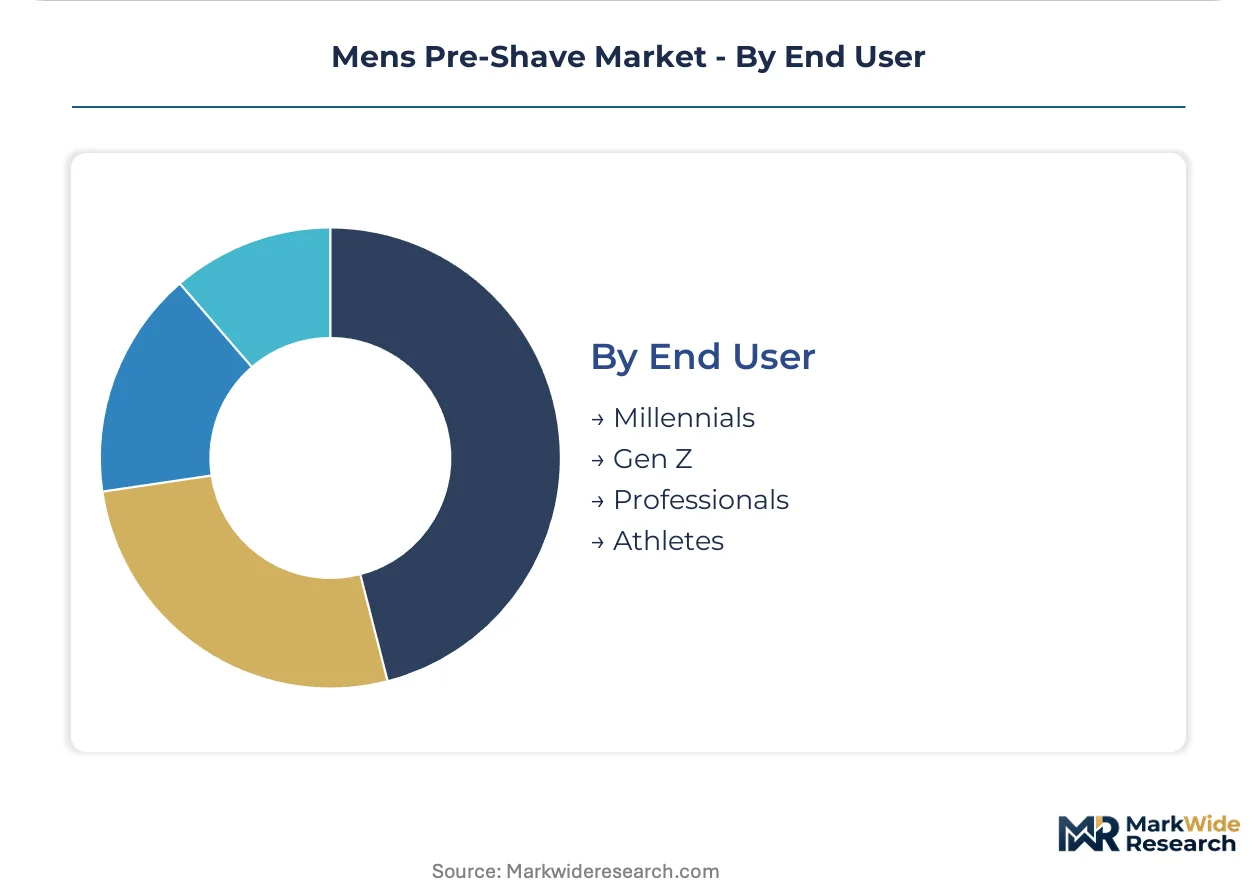
End User:
Generational and occupational cohorts exhibit divergent research behaviors, price sensitivity, and channel loyalty that reshape product development priorities.
- Millennials:Digital-native purchasers prioritizing ingredient transparency and brand values alignment. Subscription adoption concentrates among this cohort in US and UK urban centers.
- Gen Z:TikTok and Instagram-driven discovery with preference for clean-formulation credentials and sustainable packaging. German and French markets show early concentration.
- Professionals:Time-constrained users favoring efficient foam or gel formats with reliable retail availability.
- Athletes:Performance-oriented users seeking anti-irritation and post-workout recovery benefits in pre-shave routines.
Millennials represent the largest installed user base; Gen Z is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milan anchors European pre-shave innovation through its dense concentration of artisanal barbershops and heritage grooming brands that export oil-based formulations worldwide.
Germany
Traditional wet-shaving culture in Berlin and Hamburg sustains premium consumption of pre-shave oils and balms through pharmacy and specialty retail channels. REACH authorization requirements under the EU Green Deal mandate documented hazard profiles for synthetic preservatives, accelerating reformulation timelines for domestic producers. The Bavarian manufacturing corridor around Munich hosts concentrated production of dermatologically tested sensitive-skin formulations.
United States
Millennial and Gen Z cohorts in New York and Los Angeles drive subscription-based replenishment and direct-to-consumer discovery of curated shaving systems. FDA cosmetic labeling enforcement under the Fair Packaging and Labeling Act elevates compliance infrastructure requirements for market entrants. The Pacific Northwest cluster around Seattle incubates clean-formulation startups targeting ingredient transparency positioning.
Italy
Independent barbershops in Rome and Turin elevate artisanal oil and cream formats through professional endorsement and experiential retail. ECHA restriction roadmaps under REACH accelerate preservative substitution investments among small-batch producers. The Emilia-Romagna region concentrates heritage manufacturing operations with shorter reformulation cycles than multinational commodity lines.
India
Rising disposable incomes in Mumbai and Bangalore create whitespace for pre-shave education and premium format introduction among urban male consumers. BIS quality standards for personal care products establish baseline safety requirements for imported and domestic formulations. The Maharashtra industrial belt around Pune attracts contract manufacturing investment serving both domestic demand and export markets.
Mens Pre-Shave Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation chemistry and distribution architecture. The market structures around three tiers: multinational FMCG conglomerates with aerosol filling infrastructure, mid-cap dermocosmetic specialists with pharmacy channel relationships, and artisanal batch producers serving barbershop and direct-to-consumer routes. Strategic moves concentrate on preservative substitution R&D to satisfy REACH timelines and subscription platform acquisition to capture recurring revenue streams.
Among mass-market FMCG conglomerates, Procter & Gamble (Gillette) and Unilever occupy positions defined by supermarket and drugstore scale economics. Beiersdorf AG exemplifies the dermocosmetic specialist archetype through its pharmacy-regulated positioning. Proraso represents the artisanal tier with heritage oil and cream formats concentrated in Italian barbershop channels.
| Leading Market Players |
|---|
| Procter & Gamble (Gillette) |
| L'Oréal SA |
| Unilever |
| Beiersdorf AG |
| Edgewell Personal Care |
| The Art of Shaving |
| Proraso |
| Colgate-Palmolive Company |
| Coty Inc. |
| Others |
Supply & Pricing Matrix
Premium-commodity bifurcation between artisanal oil formats and mass-market foam production generates divergent margin structures and sourcing strategies across the men's pre-shave category. REACH authorization timelines and EU Green Deal restriction roadmaps impose compliance cost gradients that compound these tier separations, with natural-ingredient positioning commanding formulation premiums while synthetic-dependent lines face input volatility.
Pricing Analysis
Value-based pricing anchors on dermatological outcomes and professional endorsement credibility, with sensitive-skin formulations validated through German pharmacy channels capturing substantial premiums over supermarket-available alternatives. Three-tier pricing structure across premium, standard, and economy levels separates barbershop-distributed oils from drugstore gels and mass-market foams, with certification grade and volume scale as primary differentiation drivers. Cost compression in foam and gel segments intensifies because silicone feedstock concentration in China exposes producers to geopolitical pricing shocks. Price-sensitive procurement concentrates among professional users seeking efficient formats, while least-sensitive buyers populate specialty retail pursuing curated ingredient transparency.
Supply Chain Analysis
Essential oil and plant-derived emollient supply rests on agricultural producers in Morocco, India, and Indonesia for argan, jojoba, and sandalwood feedstocks. Glycerin sourcing draws from Malaysian and Indonesian palm oil derivatives, while silicone lubricant production concentrates in Chinese specialty chemical manufacturers. Single-source vulnerability in synthetic lubricant inputs creates exposure for mass-market gel producers dependent on concentrated Asian supply. Distribution runs through supermarket and drugstore wholesale networks for commodity formats, with direct-to-consumer platforms and barbershop specialty distributors serving premium oil and balm segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance costs and EU Green Deal documentation requirements construct a cost-of-compliance moat that advantages established players with regulatory infrastructure over new entrants lacking stability-testing capabilities.
For Market Incumbents: Hedge against preservative substitution timelines by accelerating reformulation investments in natural alternatives before ECHA sunset dates, while securing backward integration into jojoba and argan supply through Moroccan and Indian agricultural partnerships to buffer commodity volatility. For New Entrants and Emerging Players: Begin with underpenetrated Indian urban markets where rising disposable incomes and limited pre-shave education create whitespace for premium format introduction, leveraging subscription-based direct-to-consumer channels to bypass supermarket shelf-space competition. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap dermocosmetic specialists possessing pharmacy channel relationships and documented clean-formulation credentials given accelerating regulatory preference for transparency. Long-term viability across the analysis window favors acquisition targets with established REACH compliance infrastructure and barbershop distribution networks. Watch ECHA restriction roadmap acceleration as the signal indicating margin compression timing for synthetic-dependent commodity producers.| Strategic Initiative | Industry Significance |
|---|---|
| Preservative Substitution R&D | REACH compliance timelines force accelerated investment in natural stability systems ahead of synthetic sunset dates. |
| Barbershop Channel Expansion | Professional endorsement in Italian and German independent shops validates premium oil positioning and discovery. |
| Direct-to-Consumer Subscription Launch | Automated replenishment captures millennial and Gen Z loyalty while bypassing mass retail trade spend. |
| Backward Integration into Feedstocks | Captive supply of Moroccan argan and Indian jojoba buffers agricultural commodity price volatility exposure. |
| Dermatological Certification Investment | Pharmacy-regulated positioning in Germany and France elevates credibility for sensitive-skin premium pricing. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with brand managers at heritage grooming companies, category buyers at German and Italian pharmacy chains, procurement leads at aerosol filling contractors, and formulation chemists at dermocosmetic laboratories. Bottom-up volume modeling triangulated against top-down expenditure estimates derived from ECHA registration databases, FDA cosmetic labeling enforcement records, and Nielsen retail audit data across supermarket, drugstore, and specialty channels.
Granularity-level modeling operated at product-type, application, distribution channel, and end-user cohort dimensions, with additional segmentation by regional regulatory cluster reflecting REACH, FDA, and BIS compliance requirements. CAGRs were derived through trend extrapolation validated against input cost trajectories and channel migration patterns, incorporating glycerin and essential oil price indices, silicone supply concentration metrics, and e-commerce penetration rates as industry-specific forecast inputs.
Underlying measurement precision varies by segment; online channel and artisanal oil volumes carry tighter precision than emerging market estimates given data availability constraints. Forecasts reflect assumptions around regulatory timeline adherence and agricultural commodity stability, with ECHA restriction acceleration, silicone supply disruption, and Indian market development velocity as triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Outdoor Apparel and Accessories Market
Consumer Goods
Glow Sticks Market
Consumer Goods
Rolling Papers Market
Consumer Goods
Goggles Market
Consumer Goods
Anti-Fatigue Cosmetics Market
Consumer Goods
Perfume Vials Market
Consumer Goods
GCC School Stationery Supplies Market
Consumer Goods
France Lip Care Products Market
Consumer Goods
Yoga Clothing Market
Consumer Goods
Brazil Beauty and Personal Care Products Market
Consumer Goods
Natural Fragrance Market
Consumer Goods
Compound Bow and Crossbows Market
Consumer Goods
North America Pocket Knives Market
Consumer Goods
Guzheng (Zheng) Market
Consumer Goods
Ironing Beads Market
Consumer Goods
Model Train Market