
 Mens Post-Shave Market | 2026-2036
Mens Post-Shave Market Size, Share, and Industry Trends Forecast 2026-2036
Mens Post-Shave Market Foresight
Asset-light licensing and contract manufacturing is reconfiguring competitive dynamics for emerging challengers in men's grooming. Gillette leverages its captive blade-subscriber base to push bundled post-shave SKUs through controlled retail channels. Nivea Men anchors European shelf space with alcohol-free balms formulated for sensitive skin. L'Oréal Men Expert competes through R-heavy investments in biomimetic hydrators that blur pharmacy and prestige positioning.
Men's post-shave products comprise topical formulations applied after facial hair removal to restore skin barrier function, reduce inflammation, and deliver targeted actives such as allantoin, witch hazel, or hyaluronic acid at specified pH levels between 4.5 and 5.5. Balm and gel formats now lead volume as consumers abandon stinging alcohol-based splashes, while soothing and hydrating applications capture margin pools as dermatological claims justify price premiums. Natural and organic formulations represent the fastest-expanding formulation category, though synthetic bases still dominate barbershop and salon professional channels due to longer shelf stability and lower unit costs.
FDA cosmetic labeling requirements and the EU REACH framework govern ingredient disclosure and allergen restrictions, compelling reformulation of legacy synthetic preservatives across export-bound portfolios. The EU Green Deal's chemical hazard classifications are accelerating alcohol-free and plant-derived substitutions before full enforcement timelines crystallize. Stakeholders must monitor divergence between FDA's cosmetic modernization trajectory and EU chemical hazard expansion to avoid portfolio fragmentation across Atlantic regulatory zones.
Market Dynamics
Alcohol-free formulation mandates under the EU Green Deal are forcing manufacturers to rebuild supply chains around plant-derived actives, compressing margins for legacy synthetic portfolios while creating first-mover advantages for botanical ingredient suppliers.
Growth Catalysts
- REACH chemical hazard reclassification:The EU's tightening restrictions on synthetic preservatives push brands toward witch hazel and allantoin-based alternatives, expanding the addressable market for natural ingredient formulators.
- Dermatological certification demand:Urban professionals in Germany and Japan now prioritize pH-balanced, clinically tested balms over traditional splashes, rewarding R&D investment in skin barrier science.
- Barbershop channel premiumization:Professional grooming establishments in the United States are upgrading post-shave protocols, creating volume pull for salon-grade hydrating gels with extended ingredient decks.
Market Restraints
- Botanical supply concentration:Witch hazel and aloe vera sourcing clusters in specific agricultural zones, exposing formulators to climate-driven harvest volatility and price spikes.
- Reformulation capex burden:FDA cosmetic labeling modernization and EU REACH compliance require simultaneous portfolio overhauls, straining mid-tier manufacturers with limited regulatory affairs capacity.
- Shelf stability trade-offs:Plant-derived actives degrade faster than synthetic bases, complicating inventory management for distributors serving professional channels with slower turnover.
Strategic Opportunities
- Biomimetic hydrator convergence:Hyaluronic acid paired with ceramide analogs is virtualizing traditional balm textures, enabling pharmacy-positioned products to capture prestige price points.
- Direct-to-subscriber bundling:Blade subscription services in the United States create captive audiences for post-shave add-ons, reducing customer acquisition costs versus retail shelf competition.
- Japan's sensitive-skin segment:METI-backed cosmetic safety initiatives elevate dermatologically tested formulations, opening white space for alcohol-free entrants with clinical validation.
Industry Challenges
- Cross-Atlantic regulatory divergence:FDA's slower cosmetic modernization timeline versus EU REACH enforcement creates portfolio fragmentation, forcing parallel SKU maintenance for export-bound manufacturers.
- pH stability technical gaps:Maintaining 4.5-5.5 pH ranges without synthetic buffers requires novel encapsulation expertise, tightening talent competition among formulation chemists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mens Post-Shave Market |
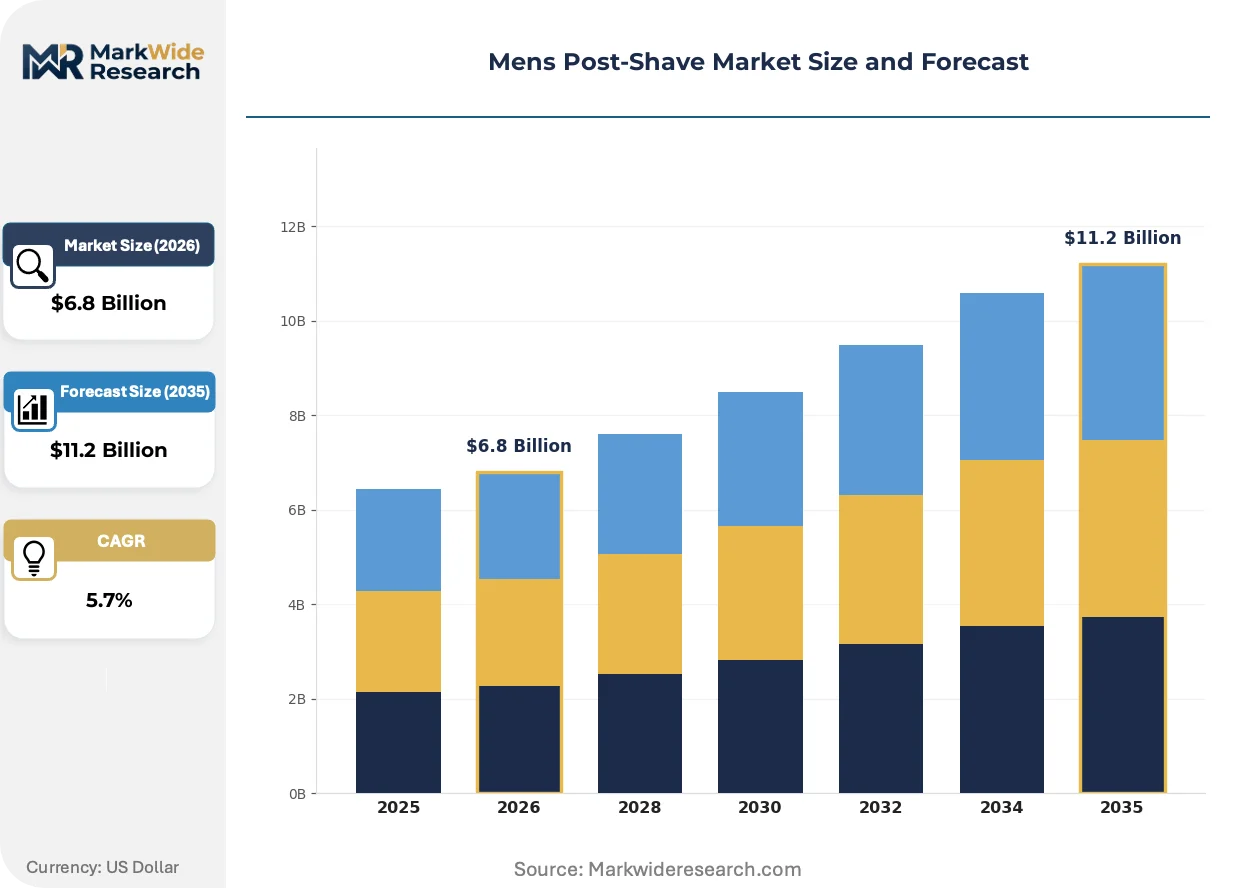
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream, Gel, Balm, Lotion Application: Soothing, Hydrating, Anti-Aging, Antiseptic Formulation: Natural, Organic, Synthetic, Alcohol-Free Customer Type: Personal Care, Barbershops, Salons, E-Commerce |
| Companies Covered | Gillette, Nivea Men, L'Oréal Men Expert, Edgewell Personal Care, Shiseido Men, Kiehl’s, Baxter of California, American Crew, Jack Black, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mens Post-Shave Market Shifts & Advancements
Formulation science is converging with digital skin diagnostics, enabling personalized post-shave protocols that match individual barrier conditions to specific active concentrations and delivery formats.
Biomimetic lipid technology is virtualizing traditional emollient functions. Ceramide NP and phytosphingosine complexes now replicate stratum corneum architecture, delivering occlusive protection without petrolatum heaviness. Premium grooming brands in Germany and Japan are adopting these materials at accelerated pace, compressing the performance gap between pharmacy and clinical skincare positioning.
REACH authorization requirements for synthetic preservatives are accelerating alcohol-free substitutions. ECHA's 2024-2025 sunset dates for legacy biocides force reformulation of splash-format products toward phenoxyethanol-free alternatives. Professional barbershop channels face the steepest compliance costs, driving consolidation toward contract manufacturers with dedicated regulatory compliance infrastructure.
Subscription bundling is reshaping replenishment patterns. Urban professionals now expect post-shave products integrated with blade delivery cycles, displacing impulse pharmacy purchases. This shift concentrates buyer power among platform operators in the United States, pressuring standalone brands to negotiate access terms or build captive subscription infrastructure.
Mens Post-Shave Market Segmentation
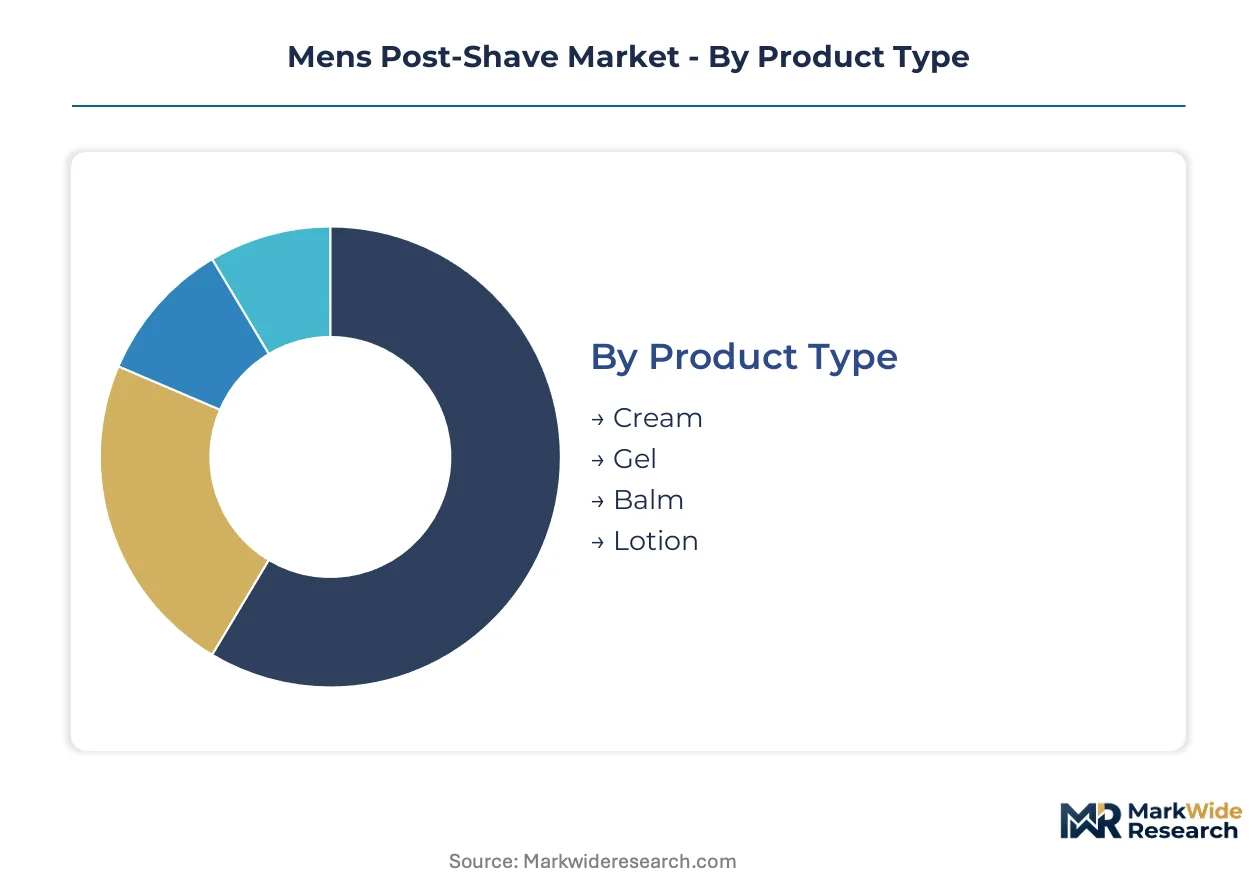
Post-shave segmentation determines margin capture and channel strategy. Texture preferences, dermatological positioning, and professional versus retail distribution each create distinct competitive arenas with separate pricing power and regulatory exposure.
Product Type:
Use-case spectrum spans immediate relief through sustained barrier repair.
- Balm:Occlusive emulsions with ceramide complexes and shea butter derivatives seal moisture for sensitive skin protocols. German pharmacy channels and Japanese department store counters drive premium positioning as pH-balanced formulations displace legacy alcohol splashes.
- Gel:Lightweight hydro-gel matrices deliver rapid absorption without residue, favored by urban professionals requiring immediate makeup or sunscreen compatibility. United States subscription bundling and Southeast Asian humid climates accelerate volume.
- Cream:Medium-viscosity emulsions balance spreadability with occlusive function, serving mass-market retail shelves across European supermarkets.
- Lotion:Fluid aqueous bases enable spray or pour applications, retaining barbershop channel presence where rapid coverage and cost efficiency matter.
Established volume favors Balm; emerging adoption favors Gel.
Application:
Functional claims stratify across dermatological depth and regulatory substantiation burden.
- Hydrating:Hyaluronic acid and glycerin-based formulations restore transepidermal water loss post-trauma. Clinical validation requirements in Japan and pharmacy positioning in Germany reward brands with barrier science expertise and toxicology dossiers.
- Soothing:Allantoin, bisabolol, and centella asiatica extracts target erythema reduction without pharmacological claims. United States clean beauty retailers and French dermo-cosmetic channels drive fastest expansion as consumers reject stinging alcohol sensations.
- Anti-Aging:Retinol alternatives and peptide complexes address photoaging concerns, concentrated in prestige urban markets with aging demographics.
- Antiseptic:Witch hazel and tea tree oil formulations serve traditional wet-shaving enthusiasts, contracting in regulated markets where biocide restrictions tighten.
Hydrating commands current shelf space; Soothing climbs the fastest on dermatological certification tailwinds.
Formulation:
Ingredient sourcing geography and stability science separate margin tiers.
- Natural:Plant-derived actives from certified agriculture meet EU Green Deal hazard classification deadlines. Witch hazel distilleries in North America and aloe vera plantations in Mexico supply formulators rebuilding portfolios around REACH-compliant ingredient decks.
- Alcohol-Free:Synthetic preservative exclusions align with sensitive-skin positioning and professional channel requirements. Japanese METI safety initiatives and German dermatological testing protocols elevate this category from niche to default expectation.
- Organic:Certified organic supply chains command price premiums in French and Scandinavian markets with strong eco-label recognition.
- Synthetic:Petrolatum and silicone-based formulations retain professional barbershop presence where shelf stability and unit economics outweigh clean-label preferences.
Synthetic retains professional volume; Natural gains share fastest on regulatory substitution mandates.
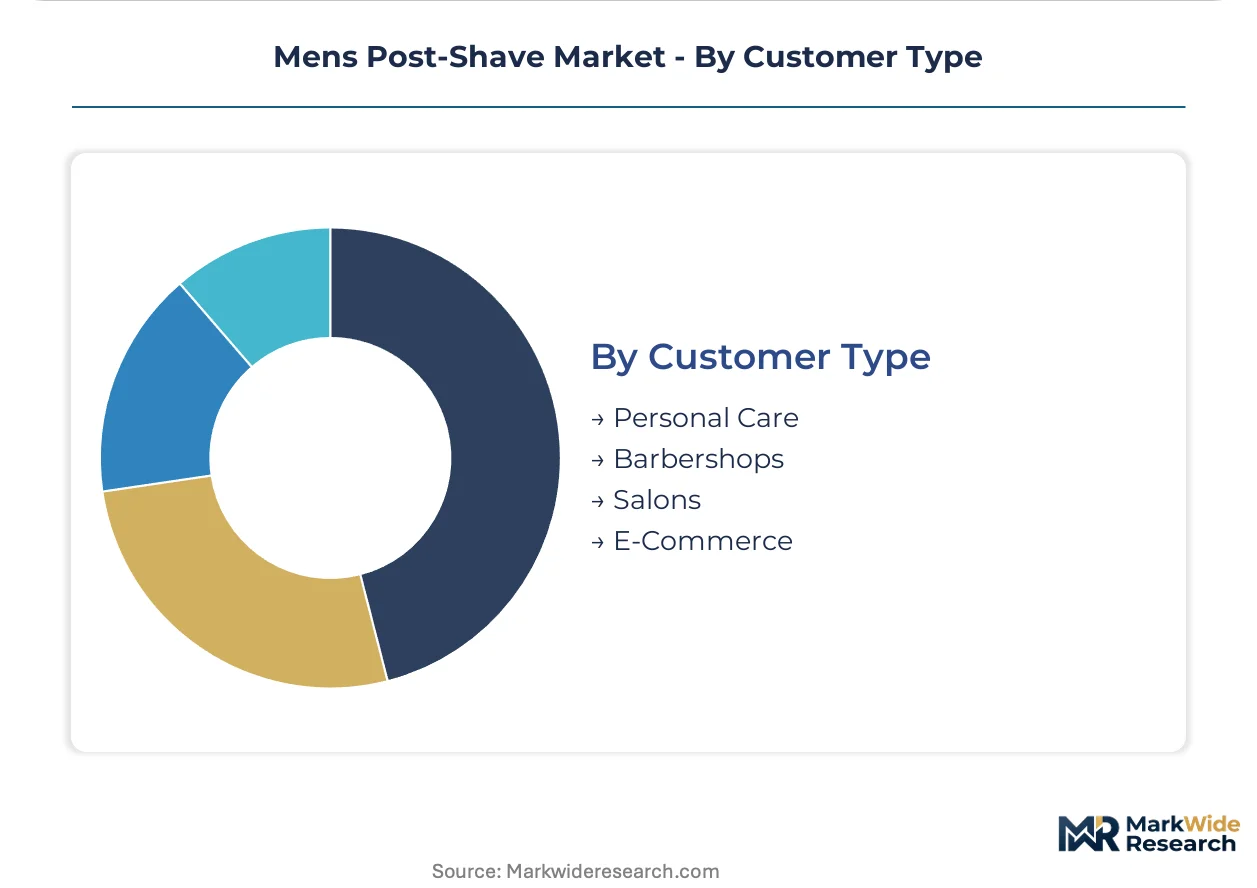
Customer Type:
Channel economics determine formulation complexity and replenishment cadence.
- Personal Care:Direct-to-consumer and mass retail purchases dominate volume, with United States subscription platforms capturing recurring revenue through blade-bundle mechanics.
- E-Commerce:Digital-native brands bypass shelf-space competition, leveraging review infrastructure and ingredient transparency to convert trial.
- Barbershops:Professional protocol integration requires bulk formats, extended stability, and training support, concentrating procurement among contract manufacturers with dedicated salon distribution.
- Salons:Premium service positioning demands retail-size SKUs with clinical aesthetic packaging, bridging professional protocol and home-use continuity.
Personal Care anchors current revenue; E-Commerce shows steepest expansion trajectory on customer acquisition cost advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH chemical hazard reclassifications and Japan's METI cosmetic safety initiatives are redirecting formulation investments toward dermatologically tested, alcohol-free alternatives in concentrated urban markets.
Germany
Pharmacy-channel dermatological balms command premium shelf space as pH-balanced formulations displace traditional alcohol splashes. The EU Green Deal's biocide sunset timelines accelerate phenoxyethanol-free substitutions across export-bound portfolios. Berlin and Hamburg anchor contract manufacturing clusters serving sensitive-skin protocol development.
United States
Subscription bundling with blade delivery services concentrates buyer power among platform operators, displacing impulse pharmacy purchases. FDA cosmetic labeling modernization drives parallel SKU maintenance for Atlantic export compliance. Greater Boston and Pacific Northwest metro areas host digital-native brands leveraging review infrastructure for trial conversion.
Japan
METI-backed cosmetic safety initiatives elevate dermatologically tested formulations from niche to default expectation among urban professionals. pH stability requirements without synthetic buffers tighten formulation chemist competition. Tokyo and Osaka department store counters drive premium positioning for ceramide-complex balms.
France
Dermo-cosmetic channels accelerate soothing formulation adoption as consumers reject stinging alcohol sensations. ANSM allergen disclosure requirements compel ingredient transparency investments. Paris and Lyon concentrate clean beauty retail infrastructure serving professional grooming establishments.
United Kingdom
Barbershop channel premiumization creates volume pull for salon-grade hydrating gels with extended ingredient decks. Post-Brexit regulatory divergence from EU REACH complicates portfolio standardization. London anchors professional grooming protocol upgrading and contract manufacturer procurement consolidation.
Mens Post-Shave Market Competitive Landscape
On the supply side, the industry is consolidating around three structural tiers: multinational consumer goods conglomerates with captive blade-subscriber bases, European dermo-cosmetic specialists with pharmacy-channel anchoring, and digital-native challengers leveraging direct-to-consumer infrastructure. Strategic archetypes include bundling-platform operators, barrier-science R&D investors, and clean-label formulation specialists. Dominant competitive moves encompass subscription infrastructure acquisition and biomimetic hydrator technology licensing.
Within the conglomerate tier, Gillette leverages its captive blade-subscriber base to push bundled post-shave SKUs through controlled retail channels. Nivea Men anchors European shelf space with alcohol-free balms formulated for sensitive skin. L'Oréal Men Expert occupies a position exemplifying R&D-heavy investments in biomimetic hydrators that blur pharmacy and prestige positioning.
| Leading Market Players |
|---|
| Gillette |
| Nivea Men |
| L'Oréal Men Expert |
| Edgewell Personal Care |
| Shiseido Men |
| Kiehl's |
| Baxter of California |
| American Crew |
| Jack Black |
| Others |
Supply & Pricing Matrix
EU REACH biocide sunset timelines concentrate reformulation risk among mid-tier manufacturers lacking dedicated regulatory affairs capacity, compressing margins on legacy synthetic portfolios while expanding price spreads between phenoxyethanol-free certified tiers and conventional formulations. This regulatory chokepoint simultaneously reshapes procurement patterns toward witch hazel distilleries in North America and contract manufacturers with compliance infrastructure.
Pricing Analysis
Certification level creates the primary spread between pharmacy-positioned balms and mass-market retail SKUs, with dermatologically tested formulations commanding premiums through German and Japanese channels. Three-tier pricing structure across premium, standard, and economy levels reflects R&D investment depth, brand heritage positioning, and clinical validation burden. Cost compression in synthetic-based tiers is intensifying because REACH-compliant reformulation capex concentrates among smaller formulators. Urban professionals in subscription programs show lowest price sensitivity; barbershop procurement managers face highest pressure on unit economics.
Supply Chain Analysis
Tariff exposure between North American witch hazel suppliers and European formulators dominates supply chain risk calculus for alcohol-free portfolio transitions. Raw material sourcing draws from witch hazel distilleries in Connecticut and North Carolina, aloe vera plantations in Mexico, and ceramide suppliers in Japan. Single-source vulnerability in certified organic shea butter from West African cooperatives complicates clean-label scaling. Distribution runs through contract manufacturers with dedicated salon and pharmacy channel infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States blade-subscription platforms and German pharmacy chains, fragmenting pricing leverage for standalone brands without captive distribution or clinical validation assets.
For Market Incumbents: Pre-empt biomimetic hydrator commoditization by securing exclusive licensing for ceramide-analog complexes from Japanese specialty chemical suppliers. Anchor pharmacy shelf space through pH-balanced balm line extensions before REACH sunset deadlines force competitor reformulation. Defend against digital-native challengers by integrating post-shave SKUs into existing blade-subscriber replenishment cycles. For New Entrants and Emerging Players: Southeast Asian humid-climate metros represent underpenetrated white space where lightweight gel formats face limited incumbent positioning. Target professional barbershop channels in London and New York with bulk-format hydrating gels featuring extended ingredient transparency. Accelerate trial conversion through ingredient-education content and review infrastructure rather than retail slotting fee competition. For Investors and Strategic Acquirers: EU Green Deal enforcement milestones reshape the acquisition landscape toward formulators with pre-built REACH-compliant ingredient decks and toxicology dossiers. Five-to-ten-year viability favors targets combining botanical supply relationships with contract manufacturing infrastructure. Watch for FDA cosmetic labeling modernization announcements as signal for parallel portfolio overhaul requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Biomimetic Hydrator Licensing | Ceramide-analog complexes from Japanese suppliers enable pharmacy-prestige positioning convergence. |
| Direct-to-Subscriber Bundling | Blade subscription platforms in the United States capture recurring revenue and reduce customer acquisition costs. |
| REACH-Compliant Reformulation | Phenoxyethanol-free substitutions ahead of ECHA sunset dates secure German and French pharmacy access. |
| Professional Channel Certification | Dermatological testing protocols from METI-backed Japanese initiatives open premium department store placement. |
| Botanical Supply Integration | Direct relationships with North American witch hazel distilleries hedge climate-driven harvest volatility. |
Research Methodology
Desk research of regulatory filings from ECHA and FDA, trade flow databases, and retail audit data preceded structured interviews with formulation chemists, contract manufacturing procurement heads, pharmacy category buyers, and barbershop supply managers. Secondary validation drew from EU REACH authorization lists, METI cosmetic safety guidance, and customs records of witch hazel and aloe vera imports. Bottom-up volume modeling triangulated against top-down market sizing from grooming industry associations.
Assumptions held fixed include REACH enforcement timelines, FDA cosmetic modernization trajectory, and blade-subscription platform market concentration. Segmentation dimensions modeled encompass product texture, functional claim depth, formulation certification tier, and channel type across the projection horizon. CAGRs derived from regression analysis of historical grooming category growth rates adjusted for regulatory substitution elasticity and professional channel premiumization trends. Industry-specific inputs included pH stability technical requirements and botanical active degradation curves.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by multinational consumer goods conglomerates or rapid regulatory acceleration beyond published timelines would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
United Kingdom Pet Food Market
Consumer Goods
China Hair Care Market
Consumer Goods
Vegan Face Cream Market
Consumer Goods
US Pet Daycare Market
Consumer Goods
Asia Pacific Household Electric Grills Market
Consumer Goods
Kids Training Pant Market
Consumer Goods
Turkey Cookware Market
Consumer Goods
North America Hair Conditioner Market
Consumer Goods
Pet Safe Cleaners Market
Consumer Goods
US Garden Planter Market
Consumer Goods
Porcelain Tableware Market
Consumer Goods
Baby Safety Products Market
Consumer Goods
Towel Warmers Market
Consumer Goods
Hair Conditioner Market
Consumer Goods
Portable Kayaks Market
Consumer Goods
Fishing Line Market