
 Mens Grooming Product Market | 2026-2036
Mens Grooming Product Market Size, Share, and Industry Trends Forecast 2026-2036
Mens Grooming Product Market Intelligence
Buyer concentration across the mens grooming product market is rebalancing as direct-to-consumer subscriptions fragment traditional retail dependence while professional salon channels consolidate procurement leverage. Unilever PLC sustains global manufacturing scale across mass-market deodorants and hair care lines. L'Oréal S.A. differentiates through dermatological science positioning in premium skin and beard segments. Beiersdorf AG anchors European market presence with Nivea Men formulations engineered for sensitive skin profiles.
Mens grooming products comprise topical preparations including shaving creams, beard oils, hair gels, and aftershave balms, formulated with emollients, active botanicals, and fragrance compounds designed for male skin pH and hair density characteristics. These products serve commercial purposes ranging from daily hygiene maintenance to aesthetic grooming rituals in professional and social contexts. Shaving cream and beard oil categories occupy established margin pools as repeat-purchase staples with proven formulation stability. Online retail channels represent the fastest-growing distribution vector, capturing younger demographics through influencer-driven discovery and subscription replenishment models. Specialty stores retain defensive positioning among premium seekers demanding tactile product evaluation and personalized consultation.
FDA oversight governs cosmetic safety labeling and ingredient disclosure requirements for products distributed in the United States, while REACH compliance mandates chemical substance registration and hazard communication throughout European supply chains. The EU Green Deal's sustainability benchmarks are forcing reformulation investments as brands confront biodegradable packaging mandates and restricted substance lists. EMA-aligned cosmetic ingredient assessments in select European jurisdictions add layered compliance complexity for multinational portfolios. Stakeholders must monitor regulatory divergence between jurisdictions while calibrating R&D allocation toward clean-label credentials that satisfy escalating consumer scrutiny and preemptive compliance obligations.
Market Dynamics
The EU Green Deal's chemical safety mandates are forcing wholesale reformulation of preservative systems and surfactant chemistry across men's grooming portfolios, compressing R&D timelines while elevating compliance costs for multinational brands.
Growth Catalysts
- Biodegradable Surfactant Mandates:The EU Green Deal's restrictions on petrochemical-based cleansing agents are accelerating plant-derived alkyl polyglucoside adoption in shaving creams and facial cleansers.
- Subscription Commerce Infrastructure:Direct-to-consumer replenishment platforms are capturing repeat-purchase loyalty through algorithmic personalization and just-in-time inventory management.
- Urban Professional Cohorts:Concentrated demand in New York and Los Angeles is sustaining premium pricing for specialized beard oils and dermatological skincare regimens.
Market Restraints
- Palm Oil Derivative Volatility:Fluctuating feedstock costs for emollient bases are compressing gross margins on mass-market hair care and body wash formulations.
- Chinese Manufacturing Concentration:Heavy reliance on Guangdong and Zhejiang province suppliers for packaging components creates geopolitical exposure and logistics vulnerability.
- Preservative Efficacy Limitations:Plant-derived antimicrobial alternatives demonstrate shorter shelf stability versus synthetic parabens, constraining distribution reach.
Strategic Opportunities
- Indian Tier-II Urban Expansion:Underpenetrated markets in Pune, Hyderabad, and Ahmedabad present whitespace for mid-priced grooming kits targeting first-time male skincare adopters.
- Waterless Formulation Innovation:Solid shampoo bars and anhydrous beard balms align with drought-conscious consumption patterns in water-stressed regions.
- CSRD-Aligned Sustainability Reporting:The EU Corporate Sustainability Reporting Directive creates competitive differentiation for brands with verified supply chain transparency and carbon accounting.
Industry Challenges
- Cosmetic Chemist Talent Scarcity:Formulation expertise bridging natural ingredient efficacy with regulatory compliance commands premium compensation and extended recruitment cycles.
- REACH Registration Timelines:Novel botanical actives face 18-24 month ECHA evaluation periods, delaying product launch windows and tying up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mens Grooming Product Market |
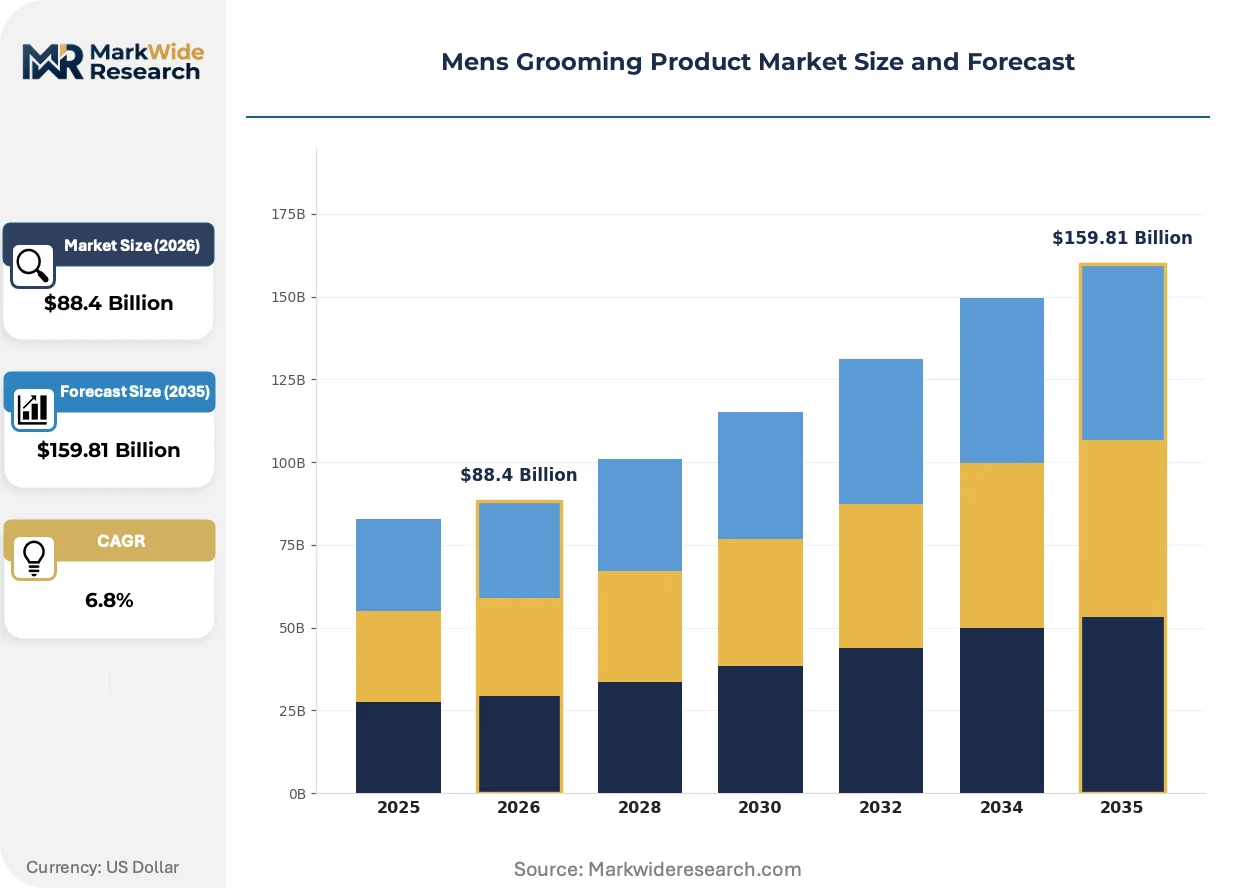
| Market Size in 2026 | $88.4 Billion |
| Market Size in 2035 | $159.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shaving Cream, Beard Oil, Hair Gel, Aftershave Balm Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Drugstores End User: Teenagers, Young Adults, Middle-aged Men, Seniors Form: Cream, Gel, Spray, Balm |
| Companies Covered | The Procter & Gamble Company, Unilever PLC, L'Oréal S.A., Beiersdorf AG, Coty Inc., Edgewell Personal Care Company, Colgate-Palmolive Company, Shiseido Company, Limited, Kao Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mens Grooming Product Market Strategic Shifts & Innovations
Digital-native discovery mechanisms and algorithmic personalization are displacing traditional brand loyalty architectures, while clean-label chemistry and water-conscious formats redefine product architecture from formulation through packaging.
Microbiome-targeted skincare technology is modularizing the men's grooming category by enabling segment-specific probiotic and prebiotic ingredient platforms. Young adult consumers in metropolitan markets are adopting these science-backed regimens at accelerating velocity. The technology is modularizing supply chains by allowing contract manufacturers to swap active modules across multiple brand clients without full line revalidation.
REACH chemical substance restrictions are compelling reformulation roadmaps that phase out microplastics and persistent organic pollutants from rinse-off products. European manufacturers face the steepest compliance burden as ECHA updates restricted substance lists on accelerated cycles. Premium beard oil and exfoliating cleanser categories are absorbing the highest per-unit cost increases as brands absorb certification and testing expenditures.
Social media-driven education is compressing the path from product discovery to purchase decision among male consumers previously resistant to multi-step skincare routines. Influencer-led tutorials on TikTok and Instagram are displacing traditional advertising and in-store consultation as primary awareness channels. This behavioral shift concentrates most intensely among 18-34 year old demographics in the United States and United Kingdom, where platform engagement rates for male beauty content have tripled since 2022.
Mens Grooming Product Market Segmentation
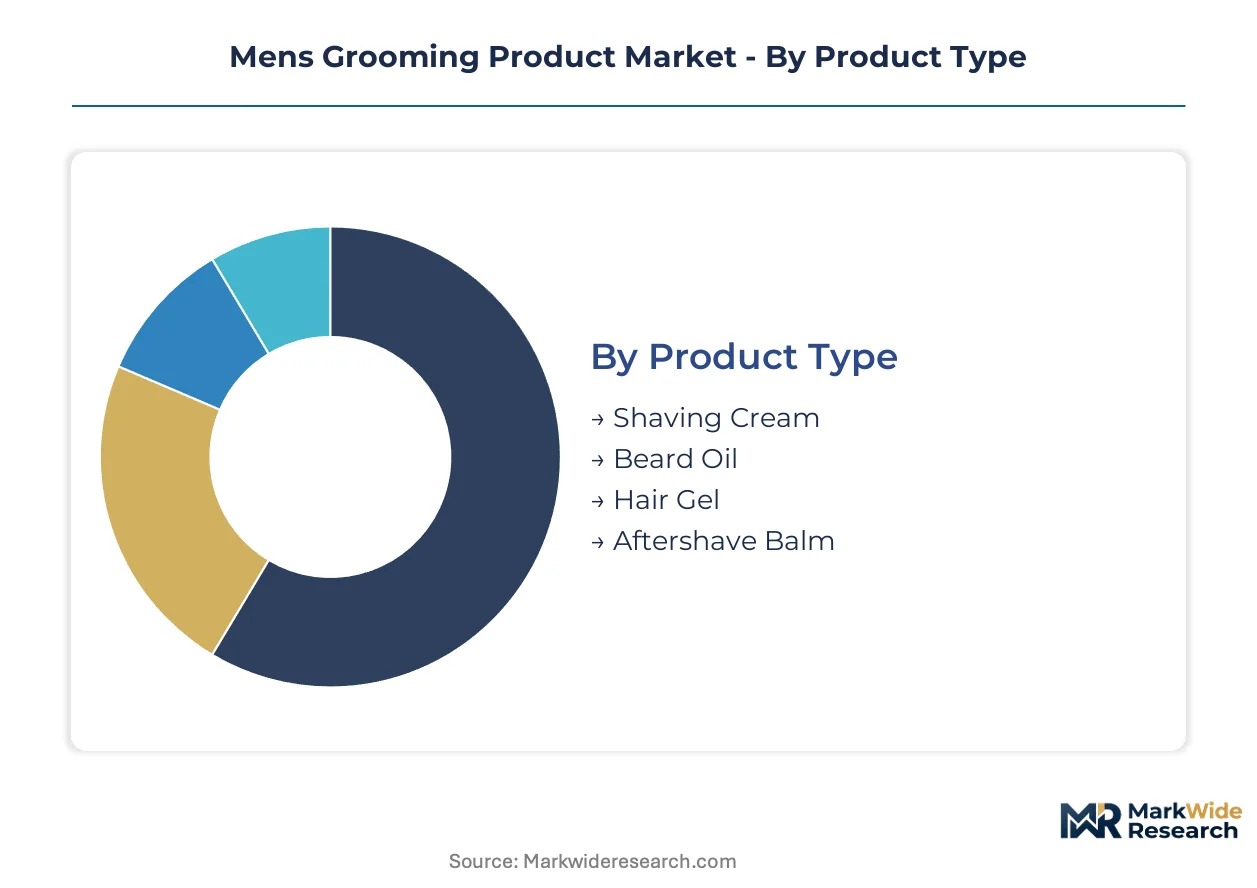
Men's grooming portfolios require granular segmentation to capture divergent purchase rhythms across age cohorts and channel preferences. Reformulation mandates and subscription commerce are fragmenting traditional category boundaries, forcing brands to align SKUs with specific usage occasions and replenishment behaviors.
Product Type:
Upgrade cycles vary dramatically by product type, with beard oils and specialized serums commanding annual replenishment while shaving creams sustain monthly repurchase velocity.
- Shaving Cream:Emulsion-based formulations combining stearic acid, glycerin, and surfactant systems to reduce friction during blade contact. Mass-market penetration remains highest in United States urban corridors where professional dress codes sustain daily shaving rituals; synthetic paraben alternatives are compressing shelf-life windows and forcing smaller pack sizes.
- Beard Oil:Anhydrous blends of jojoba, argan, and essential oils targeting facial hair conditioning and underlying skin hydration. Premium pricing concentrates in Los Angeles and New York metro areas where social media visibility elevates grooming investment; EU Green Deal mandates on biodegradable packaging are elevating per-unit costs for glass dropper formats.
- Hair Gel:Polymer-thickened styling preparations offering hold and finish control across varying hair densities.
- Aftershave Balm:Post-shave moisturizers incorporating soothing botanicals and light fragrance for irritation relief.
Volume placements concentrate in Shaving Cream; the faster expansion belongs to Beard Oil.
Distribution Channel:
Channel selection directly shapes margin capture, with direct-to-consumer platforms retaining 25-40 point gross margin advantages over brick-and-mortar intermediaries despite higher customer acquisition costs.
- Online Retail:Algorithmic personalization and subscription replenishment models capturing 18-34 demographic loyalty through influencer-driven discovery. TikTok and Instagram storefronts are displacing traditional search-based ecommerce in United States and United Kingdom markets; FDA cosmetic labeling requirements apply to all imported formulations sold through domestic platforms.
- Specialty Stores:Tactile evaluation environments staffed with trained consultants for premium beard and skincare regimens. Manhattan and Brooklyn flagships sustain highest per-transaction values through bundled ritual consultations; REACH-compliant ingredient disclosure mandates add operational complexity for European locations.
- Supermarkets:Mass-market deodorant and hair care velocity through high-frequency foot traffic.
- Drugstores:Convenience-positioned replenishment for standardized personal care staples.
Transaction density peaks in Supermarkets; the steepest expansion trajectory runs through Online Retail.
End User:
Life-stage segmentation determines regimen complexity, with younger cohorts adopting multi-step skincare earlier while older demographics maintain simplified hygiene-focused routines.
- Young Adults:Digital-native consumers normalizing comprehensive grooming rituals through platform-mediated peer influence. Social media tutorial consumption in United States metropolitan markets drives fastest category expansion; EU Green Deal-aligned clean-label preferences elevate willingness-to-pay for verified sustainable formulations.
- Teenagers:Entry-point consumers establishing brand loyalties through acne-targeted and introductory grooming products.
- Middle-aged Men:Established routine adherents with lower switching propensity and price sensitivity.
- Seniors:Skin-aging focused segments prioritizing dermatological credibility and simplified application formats.
Volume concentration sits with Middle-aged Men; Young Adults are gaining share fastest.
Form:
Physical format selection intersects with sustainability positioning, as waterless and solid formats reduce shipping weights and align with drought-conscious consumption patterns.
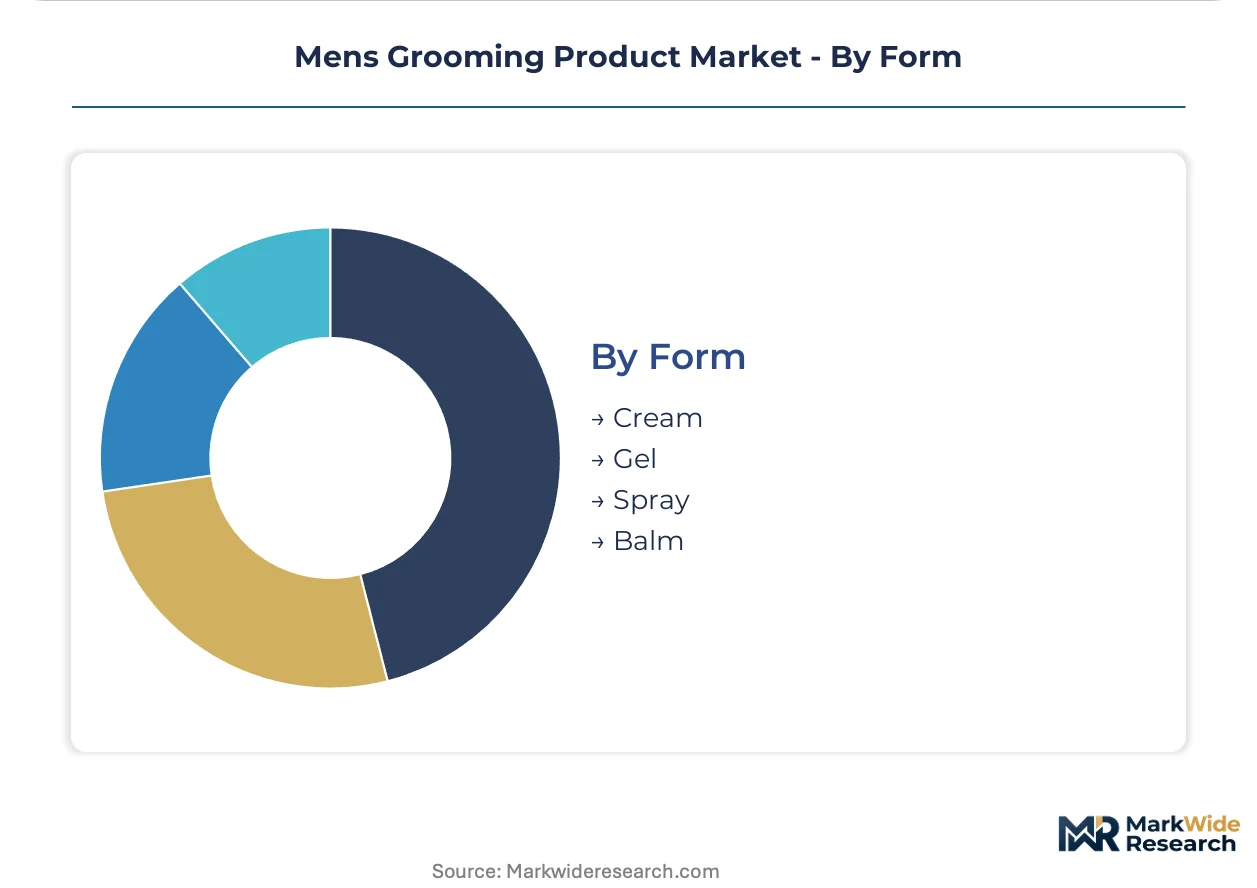
- Cream:Emulsion-based delivery systems dominating shaving and moisturizing categories through familiar application rituals.
- Gel:Clear, quick-drying formats preferred for hair styling and post-shave cooling sensations.
- Spray:Aerosol and pump-dispersed formats for deodorant and lightweight hair product applications.
- Balm:Dense, occlusive preparations for intensive beard conditioning and targeted skin repair.
Production scale concentrates in Cream; Balm formats are climbing the fastest on premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban professional demand concentrates in the United States, where specialized beard and skincare regimens command premium pricing. The EU Green Deal's chemical safety mandates are pressuring reformulation investments across European supply chains. Asian markets present expansion whitespace as digital-native consumers normalize comprehensive grooming rituals.
United States
New York and Los Angeles metro areas sustain the highest per-transaction values for premium beard oils and dermatological skincare regimens. FDA cosmetic safety labeling and ingredient disclosure requirements govern all products distributed through domestic platforms. Manhattan and Brooklyn specialty store flagships anchor tactile evaluation environments where bundled ritual consultations drive loyalty.
Germany
REACH chemical substance registration mandates force 18-24 month ECHA evaluation periods for novel botanical actives, compressing product launch windows. The EU Green Deal's biodegradable packaging requirements elevate per-unit costs for glass dropper formats in premium categories. North Rhine-Westphalia hosts manufacturing clusters serving sensitive skin formulation demand across European markets.
United Kingdom
TikTok and Instagram storefronts displace traditional search-based ecommerce among 18-34 year old male demographics, with platform engagement rates for male beauty content tripling since 2022. EMA-aligned cosmetic ingredient assessments in select jurisdictions add layered compliance complexity for multinational portfolios. London anchors influencer-driven discovery infrastructure that funnels demand toward subscription replenishment models.
India
Tier-II urban markets in Pune, Hyderabad, and Ahmedabad present whitespace for mid-priced grooming kits targeting first-time male skincare adopters. BIS standards govern product safety certification for domestic distribution. Maharashtra and Karnataka manufacturing corridors scale production to serve price-sensitive mass-market segments while building clean-label capabilities for export qualification.
Japan
METI industrial policy supports waterless formulation innovation as solid shampoo bars and anhydrous beard balms align with drought-conscious consumption patterns. PMDA cosmetic oversight maintains stringent safety documentation requirements for imported formulations. Tokyo-Osaka corridor retailers specialize in microbiome-targeted skincare technology adoption among metropolitan consumers.
Mens Grooming Product Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer subscription channels and clean-label positioning. The market structure consolidates around multinational FMCG conglomerates with mass-market deodorant and hair care scale, while specialty dermatological brands fragment premium beard and skincare segments. Three archetypes dominate: science-backed premium specialists, mass-market volume leaders, and digital-native subscription disruptors. Competitive moves concentrate on portfolio diversification into plant-derived formulations and geographic expansion into underpenetrated Asian urban markets.
Among European-based dermatological specialists, Beiersdorf AG occupies a position exemplifying sensitive skin engineering expertise, while L'Oréal S.A. anchors the science-backed premium tier through dermatological positioning. Unilever PLC represents the mass-market volume archetype with global manufacturing scale across deodorant and hair care lines. These three entities illustrate the competitive tension between regulatory compliance investment and channel fragmentation management.
| Leading Market Players |
|---|
| The Procter & Gamble Company |
| Unilever PLC |
| L'Oréal S.A. |
| Beiersdorf AG |
| Coty Inc. |
| Edgewell Personal Care Company |
| Colgate-Palmolive Company |
| Shiseido Company, Limited |
| Kao Corporation |
| Others |
Cost & Logistics Intelligence
EU Green Deal mandates on biodegradable surfactants and plant-derived preservatives are forcing reformulation investments that compress R&D timelines and elevate per-unit costs across men's grooming portfolios, compelling suppliers to absorb certification expenditures or pass through to buyers.
Pricing Analysis
Volume placements concentrate in mass-market shaving creams and hair gels through supermarket and drugstore channels, while margin capture peaks in premium beard oils and dermatological skincare sold through direct-to-consumer subscriptions and specialty retail. Three-tier pricing structure across premium, standard, and economy levels separates subscription-formulated clean-label serums from conventional mass-market staples, with price differentiation driven by certification grade (EU Green Deal compliance, REACH registration status) and vertical integration depth. Pricing pressure stems from palm oil derivative volatility in emollient bases, eroding gross margins on high-volume hair care and body wash formulations. Young adult digital-native consumers demonstrate lowest price sensitivity for verified sustainable formulations, while mass-market middle-aged segments resist premiumization.
Supply Chain Analysis
Single-source vulnerability sits with Guangdong and Zhejiang province suppliers for glass dropper packaging and pump-dispenser components, creating geopolitical exposure and logistics vulnerability for brands dependent on Chinese manufacturing concentration. Raw material dependencies center on jojoba and argan oil feedstocks from Morocco and Argentina, alkyl polyglucoside surfactants from European biotech processors, and palm oil derivatives from Indonesian and Malaysian plantations. Tariff exposure on imported packaging components amplifies cost volatility as brands navigate REACH registration timelines for novel botanical actives. Distribution runs through direct-to-consumer platforms capturing 25-40 point gross margin advantages, though specialty store flagships in Manhattan and Brooklyn retain defensive positioning for tactile evaluation and bundled consultation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
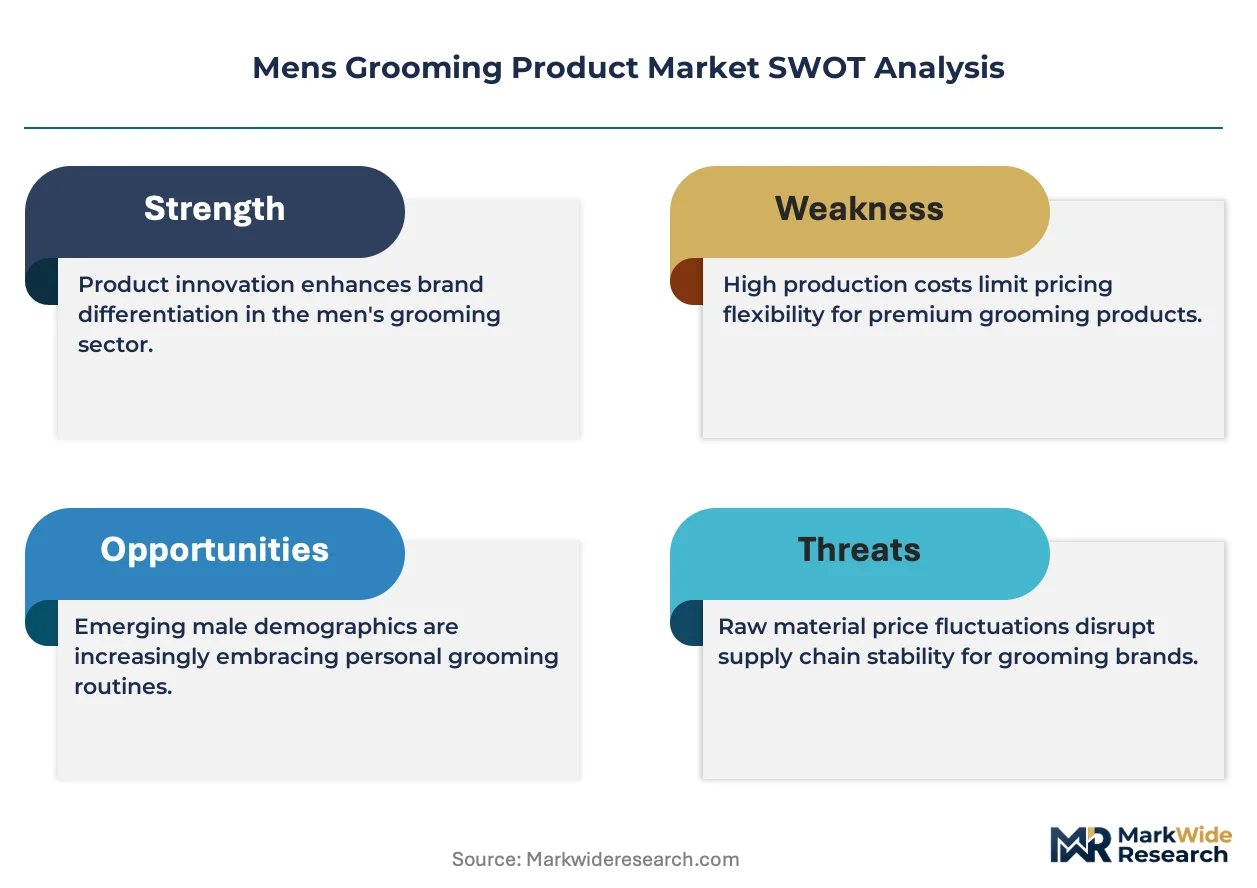
Men's grooming is transitioning from synthetic-paraben formulations to microbiome-targeted probiotic platforms, with clean-label chemistry and waterless formats displacing legacy emulsion-based architectures.
For Market Incumbents: To counter direct-to-consumer subscription disruptors capturing young adult loyalty through algorithmic personalization, Unilever PLC and mass-market volume leaders should deepen backward integration into plant-derived surfactant production to secure feedstock cost stability. L'Oréal S.A. and dermatological specialists must accelerate CE marking and EMA-aligned cosmetic ingredient assessments to preempt REACH compliance delays that compress launch windows.
For New Entrants and Emerging Players: Capture whitespace in Indian Tier-II urban markets—Pune, Hyderabad, Ahmedabad—where first-time male skincare adoption remains underpenetrated and mid-priced grooming kits face limited incumbent saturation. Waterless formulation innovation (solid shampoo bars, anhydrous beard balms) offers differentiated entry against established liquid-format portfolios, with drought-conscious positioning aligning with METI-supported Japanese consumption patterns.
For Investors and Strategic Acquirers: The window for entry favors digital-native subscription brands with verified EU Green Deal compliance and captive microbiome technology platforms, positioned for consolidation by multinational FMCG conglomerates seeking clean-label credibility. Long-term viability hinges on CSRD-aligned sustainability reporting capabilities that satisfy escalating European transparency mandates. Watch for REACH registration backlog resolution at ECHA as inflection indicator for novel botanical active commercialization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | EU Green Deal compliance secures European market access and satisfies young adult willingness-to-pay premiums. |
| Direct-to-Consumer Launch | Algorithmic personalization through TikTok and Instagram storefronts captures 18-34 demographic loyalty. |
| Waterless Product Introduction | Solid formats reduce shipping weights and align with drought-conscious consumption in water-stressed regions. |
| Backward Integration into Surfactants | Captive alkyl polyglucoside production insulates margins from palm oil derivative volatility. |
| CSRD Sustainability Reporting | Verified supply chain transparency creates competitive differentiation under EU Corporate Sustainability Reporting Directive. |
Research Approach
Multi-period observation of subscription commerce penetration rates, REACH registration timelines, and social media platform engagement metrics anchored the trend analysis, supplemented by interviews with cosmetic chemists, brand managers at multinational FMCG conglomerates, category buyers at specialty retailers, and regulatory affairs leads navigating ECHA compliance. Secondary validation drew from FDA cosmetic labeling databases, ECHA restricted substance lists, EU Green Deal policy documentation, and Nielsen retail audit data. Bottom-up SKU-level demand modeling and top-down macroeconomic anchoring were triangulated against primary field intelligence.
Segment-weighting applied differential growth assumptions across product type (shaving cream, beard oil, hair gel, aftershave balm), distribution channel (online retail, specialty stores, supermarkets, drugstores), end user (young adults, teenagers, middle-aged men, seniors), and form (cream, gel, spray, balm) throughout the forecast period. CAGRs were derived from regression analysis of historical volume trajectories and elasticity-adjusted price evolution, with inputs including urban professional cohort expansion in New York and Los Angeles, EU biodegradable packaging mandate compliance costs, and Indian Tier-II market penetration curves.
The model holds under stable regulatory enforcement timelines and continued social media platform monetization; deviation in ECHA evaluation acceleration, geopolitical disruption to Chinese packaging supply, or consumer preference reversal toward synthetic preservatives would shift trajectory bounds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Smart Pacifier Market
Consumer Goods
Wearable Gaming Technology Market
Consumer Goods
Accessible Luxury Goods Market
Consumer Goods
North America Glassware Market
Consumer Goods
Umbrella Market
Consumer Goods
Cast Iron Cookware Market
Consumer Goods
UK Pet Boarding Market
Consumer Goods
Global Massage Oil Market
Consumer Goods
Smart DJ Controller Market
Consumer Goods
Kitchen Appliances Market
Consumer Goods
Sports Bras Market
Consumer Goods
Natural and Organic Personal Care Market
Consumer Goods
Private Label Cosmetics Manufacturing Service Market
Consumer Goods
Triple Barrel Waver Market
Consumer Goods
Closed Back Studio Headphone Market
Consumer Goods
Hairstyling Products Market