
 Medical Simulation Education Market | 2026-2036
Medical Simulation Education Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Simulation Education Market Insights
The gap between premium immersive platforms and commodity mannequin systems is realigning procurement patterns across academic medical centers. Laerdal Medical leverages its long-standing installed base in resuscitation training to sustain recurring revenue from consumables and software subscriptions. CAE Healthcare competes through aerospace-derived fidelity standards that anchor its position in anesthesia and critical care simulation. Gaumard Scientific differentiates via proprietary wireless physiology engines that occupy the mid-tier hospital segment.
Medical simulation education encompasses the design, deployment, and validation of synthetic learning environments that replicate clinical encounters, procedural tasks, and team-based care delivery using physical mannequins, virtual reality headsets, haptic interfaces, or hybrid configurations. These systems integrate physiologic modeling software, scenario authoring tools, and debriefing analytics to reduce patient risk during clinician skill acquisition. Virtual reality and hybrid simulations represent the fastest-expanding technology categories as hardware costs fall and software fidelity rises. Surgical procedures and emergency response applications command the deepest margin pools due to credentialing requirements and liability exposure. Medical schools and teaching hospitals remain the dominant end-user channel, though specialized training centers are gaining share through contract-based workforce development programs.
The FDA regulates software-as-medical-device components embedded in simulation platforms, while the EU AI Act and MDR impose conformity obligations on European-deployed systems with automated assessment features. ISO 9001 and ISO 13485 certifications shape vendor eligibility for institutional procurement frameworks across North America and Europe. Stakeholders must monitor how accreditation bodies integrate simulation-based competency benchmarks into licensure pathways, as this will determine which technology investments achieve mandatory rather than discretionary budget status.
Market Dynamics
The Medical Simulation Education Market is undergoing a structural realignment driven by the FDA's evolving guidance on software-as-medical-device components, which is forcing platform developers to prioritize validated, interoperable systems over proprietary silos. This regulatory pressure is compressing vendor margins while elevating compliance costs across the value chain.
Growth Catalysts
- Credentialing mandates:Accreditation bodies in the United States are embedding simulation-based competency benchmarks into surgical residency licensure pathways, converting discretionary training budgets into mandatory institutional expenditures.
- EU AI Act conformity obligations:European-deployed systems with automated assessment features face accelerated validation requirements, creating first-mover advantages for vendors holding ISO 13485 and MDR certifications.
- Wireless physiology engines:Proprietary sensor arrays enabling untethered mannequin mobility are expanding deployment scenarios from fixed simulation centers to point-of-care training environments in mid-tier hospitals.
Market Restraints
- High-fidelity hardware costs:Haptic interface components and VR headset arrays require capital outlays that strain departmental budgets at non-teaching community hospitals.
- Software validation timelines:FDA premarket review pathways for algorithm-driven assessment modules extend development cycles by 18-24 months, delaying revenue recognition for platform developers.
- Substitute training modalities:Cadaveric procedural labs and apprenticeship-based surgical observation retain institutional preference in several Asian medical education systems, limiting addressable market expansion.
Strategic Opportunities
- Rural hospital networks:Federally qualified health centers in the United States are accessing HRSA-funded simulation equipment grants to address workforce retention through local skill development programs.
- Hybrid reality convergence:Integration of physical mannequin tactile feedback with immersive VR visualization is opening procedural training applications previously restricted to live operating rooms.
- Specialized training centers:Contract-based workforce development programs for emergency medical services and military medical corps are bypassing traditional academic procurement channels.
Industry Challenges
- Debriefing analytics standardization:The absence of cross-platform performance metrics complicates competency tracking as institutions deploy mixed-vendor simulation fleets.
- Biomedical engineering talent scarcity:Vendors struggle to recruit professionals capable of bridging clinical physiology modeling with real-time software architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Simulation Education Market |
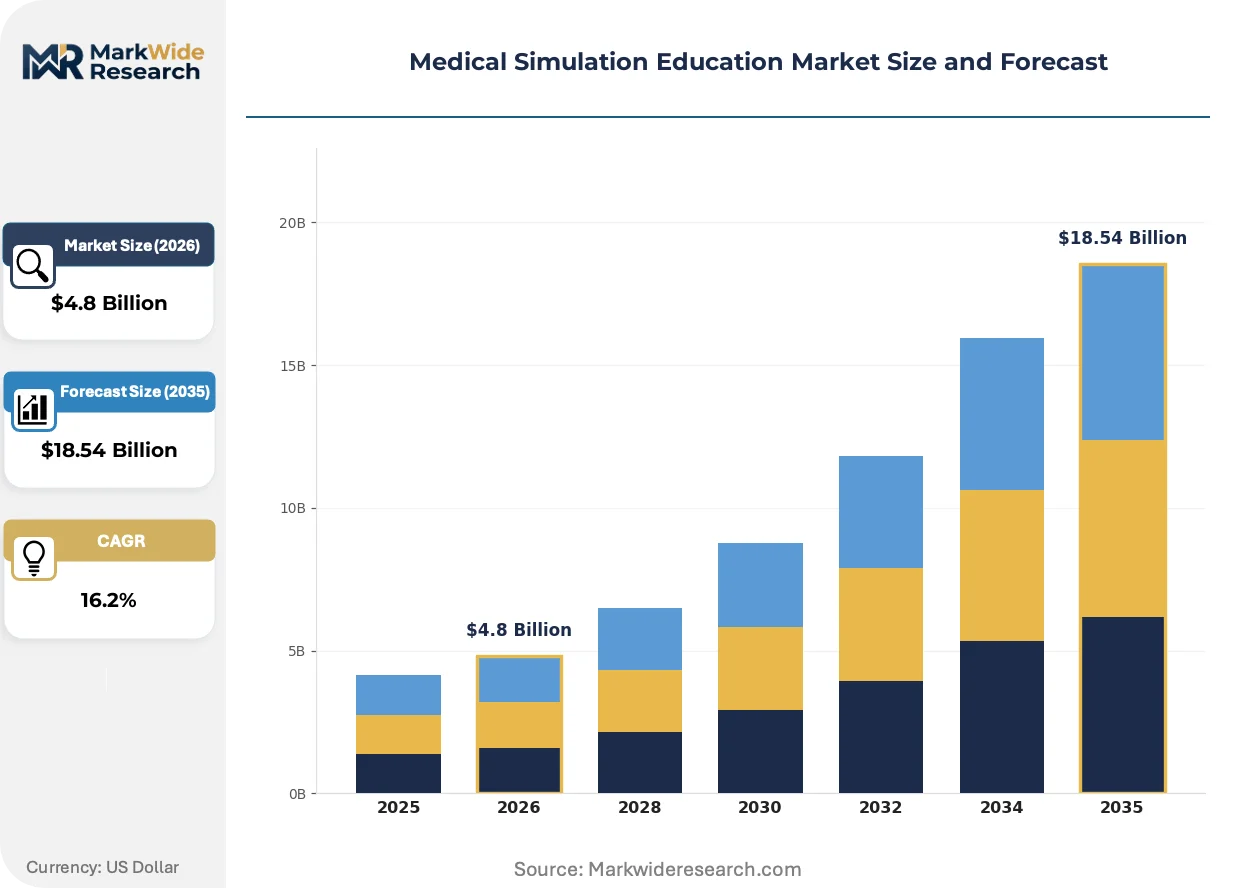
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $18.54 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Virtual Reality, Augmented Reality, Hybrid Simulations, Traditional Simulations Application: Medical Training, Surgical Procedures, Emergency Response, Nursing Education End User: Medical Schools, Hospitals, Training Centers, Academic Institutions Scenario Type: Realistic Scenarios, Standardized Patients, Mannequin-Based Scenarios, Procedural Tasks |
| Companies Covered | Laerdal Medical, CAE Healthcare, Gaumard Scientific, Simulab Corporation, Limbs & Things, 3B Scientific, VirtaMed, Surgical Science Sweden AB, 3D Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Simulation Education Market Trends and Innovations
Artificial intelligence is penetrating assessment layers of simulation platforms, automating performance scoring that previously required expert facilitator observation. This shift is compressing instructor-to-learner ratios while raising questions about algorithmic transparency in high-stakes credentialing decisions.
Cloud-native scenario authoring tools are consolidating curriculum development workflows that previously required on-premise software installations and site-specific technical support. Medical schools in Germany and university hospitals in the United States are adopting browser-based platforms that enable remote scenario customization and centralized content libraries. This architecture is consolidating vendor revenue models from perpetual licenses toward recurring subscription structures.
The EU AI Act and MDR are imposing conformity obligations on European-deployed systems with automated assessment features, creating compliance moats for certified vendors. Teaching hospitals in France and Germany are prioritizing procurement frameworks that bundle ISO 13485 certification with scenario content aligned to national competency catalogs. This regulatory layering is consolidating competitive positioning around validated software platforms rather than hardware fidelity alone.
Service-based contracting is displacing capital equipment purchases at several academic medical centers in the United States. Institutions in California and Massachusetts are negotiating per-learner pricing models that bundle hardware refresh cycles, software updates, and facilitator training into multi-year agreements. This shift transfers obsolescence risk to vendors while aligning supplier incentives with learner throughput metrics.
Medical Simulation Education Market Segmentation
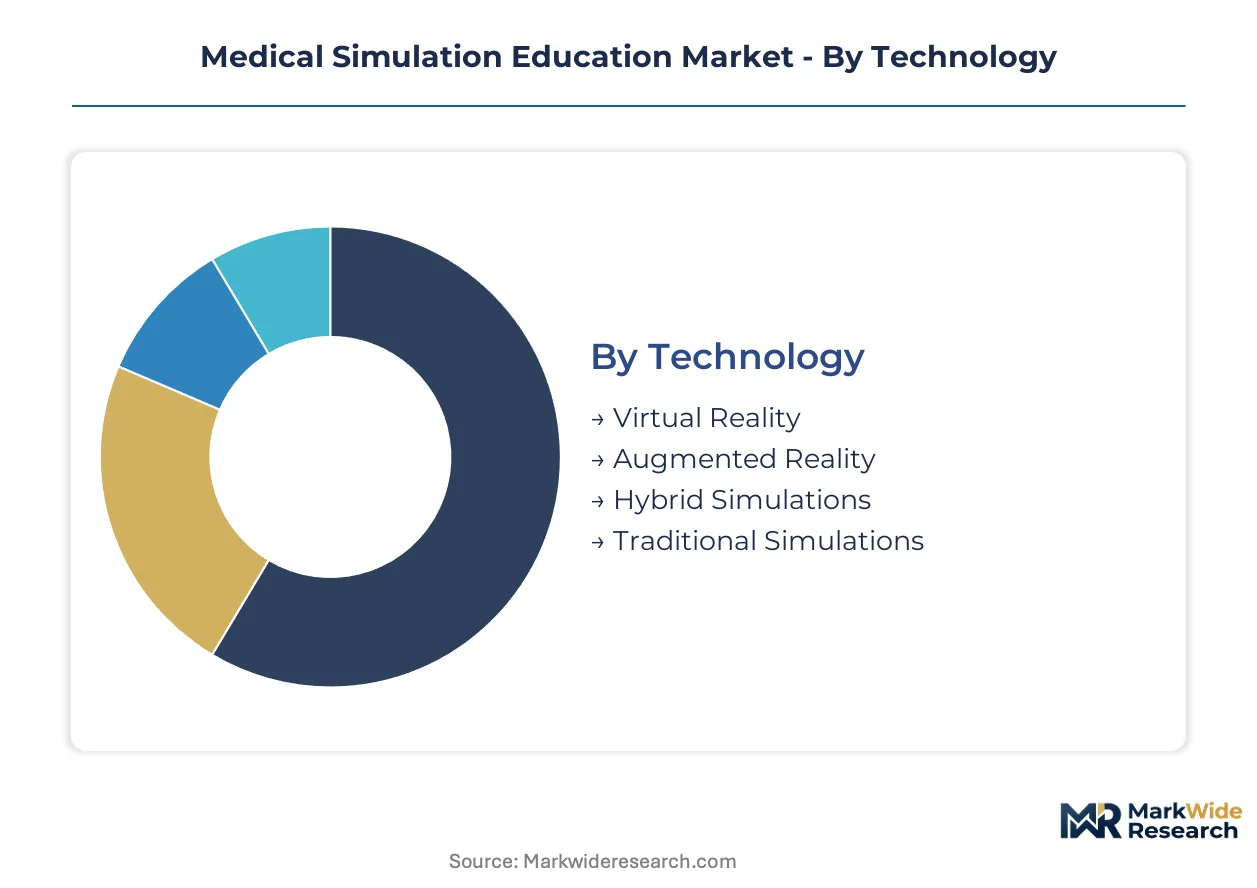
Capital allocation across simulation technologies varies dramatically by fidelity requirements and hardware intensity. Procurement committees weigh upfront infrastructure against per-use operational costs when segmenting institutional budgets.
Technology:
Capital intensity stratifies sharply across this category, with immersive hardware demanding specialized facility investments while traditional platforms leverage existing infrastructure.
- Virtual Reality:Headset arrays and motion tracking systems require dedicated simulation suites with calibrated spatial boundaries. Demand concentrates in teaching hospitals across Germany where university medical centers are building centralized simulation institutes to meet EU AI Act conformity timelines.
- Hybrid Simulations:Integration of physical mannequin tactile feedback with immersive visualization demands the highest capital outlays but enables procedural training previously restricted to live operating rooms. United States academic medical centers in California and Massachusetts are negotiating per-learner service contracts that bundle hardware refresh cycles into multi-year agreements.
- Augmented Reality:Overlay systems project anatomical visualizations onto physical task trainers, reducing headset hardware requirements while maintaining spatial grounding.
- Traditional Simulations:Screen-based scenarios and standardized patient encounters operate on commodity computing infrastructure with minimal facility modification.
Hybrid simulations absorb the bulk of installed capacity; virtual reality is expanding most quickly as hardware costs fall and software fidelity rises.
Application:
Margin profiles diverge based on credentialing requirements and liability exposure, with regulated procedures commanding premium pricing over discretionary training modules.
- Surgical Procedures:High-stakes operative simulations integrate haptic feedback with anatomical modeling software to replicate tissue resistance and instrument handling. Accreditation bodies in the United States are embedding these benchmarks into residency licensure pathways, converting discretionary budgets into mandatory institutional expenditures.
- Emergency Response:Team-based crisis scenarios require synchronized multi-learner platforms with real-time physiologic deterioration algorithms. Training centers in France and Germany prioritize procurement frameworks bundling ISO 13485 certification with scenario content aligned to national competency catalogs.
- Medical Training:Foundational clinical skills modules span history-taking through physical examination protocols.
- Nursing Education:Medication administration and patient communication scenarios emphasize repetitive competency validation over high-fidelity environmental immersion.
Surgical procedures capture the deepest margin pools; emergency response is climbing the fastest as specialized training centers bypass traditional academic procurement channels.
End User:
Procurement authority and budget flexibility vary substantially across institutional types, with teaching hospitals holding capital equipment authority while medical schools navigate shared governance structures.
- Hospitals:Teaching institutions in the United States are scaling immersive training programs for surgical residents, leveraging credentialing mandates to secure departmental funding. Federally qualified health centers access HRSA-funded simulation equipment grants to address workforce retention through local skill development programs.
- Training Centers:Contract-based workforce development programs for emergency medical services and military medical corps operate on per-learner pricing models that transfer obsolescence risk to vendors.
- Medical Schools:Curriculum integration requirements and accreditation reporting obligations shape procurement toward platforms with standardized assessment analytics.
- Academic Institutions:Research-oriented simulation deployments prioritize scenario authoring flexibility and data export capabilities for publication requirements.
Hospitals dominate current installed base; training centers are gaining share fastest through non-traditional procurement channels.
Scenario Type:
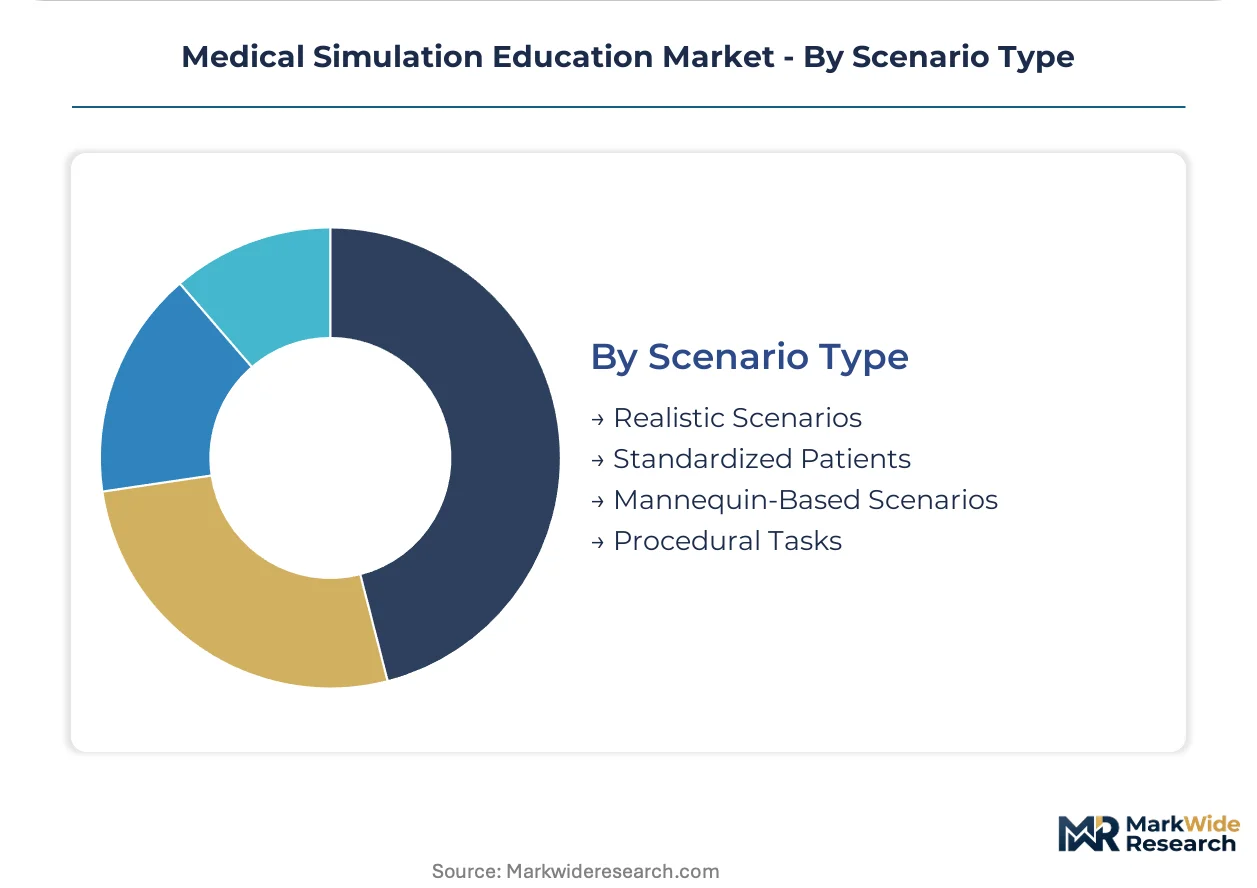
Development cost structures range from standardized patient recruitment logistics to complex physiologic modeling, with proprietary wireless sensor arrays occupying the mid-tier positioning.
- Mannequin-Based Scenarios:Proprietary wireless physiology engines enable untethered mobility, expanding deployment from fixed simulation centers to point-of-care training environments in mid-tier hospitals. Laerdal Medical leverages its installed base to sustain recurring revenue from consumables and software subscriptions.
- Procedural Tasks:Task trainers isolate specific technical skills—central line placement, lumbar puncture, airway management—within reproducible physical forms. CAE Healthcare anchors its position through aerospace-derived fidelity standards in anesthesia and critical care applications.
- Realistic Scenarios:Environmental fidelity including moulage, sound design, and family member actors creates immersive clinical encounters.
- Standardized Patients:Trained actors deliver consistent patient portrayals with structured feedback protocols, minimizing capital requirements while maximizing communication skill assessment.
Mannequin-based scenarios hold the largest installed footprint; procedural tasks are expanding most quickly as hardware miniaturization enables distributed training networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American simulation education infrastructure through its dense concentration of academic medical centers and teaching hospitals scaling immersive surgical residency programs.
United States
Teaching hospitals in California and Massachusetts are negotiating per-learner service contracts that bundle hardware refresh cycles into multi-year agreements. The FDA's evolving guidance on software-as-medical-device components is forcing platform developers toward validated, interoperable systems. Federally qualified health centers access HRSA-funded simulation equipment grants to address workforce retention through local skill development programs.
Germany
University medical centers in Germany are building centralized simulation institutes to meet EU AI Act conformity timelines for automated assessment features. The EU MDR and AI Act impose accelerated validation requirements on European-deployed systems. Medical schools in Bavaria and Baden-Württemberg are adopting browser-based platforms that enable remote scenario customization and centralized content libraries.
United Kingdom
Academic medical centers in London and the Southeast are prioritizing procurement frameworks that bundle ISO 13485 certification with scenario content aligned to national competency catalogs. The Medicines and Healthcare products Regulatory Agency (MHRA) enforces post-Brexit conformity assessment procedures for simulation platforms with embedded software. Research-oriented institutions in the Midlands emphasize scenario authoring flexibility and data export capabilities for publication requirements.
France
Training centers in France are prioritizing procurement frameworks bundling ISO 13485 certification with scenario content aligned to national competency catalogs. The ANSM (Agence Nationale de Sécurité du Médicament) oversees medical device regulations including simulation platforms. Medical simulation institutes in the Île-de-France region are expanding team-based crisis scenario deployments for emergency response credentialing.
Japan
Medical schools in Japan are integrating simulation-based competency benchmarks into residency licensure pathways under PMDA oversight. METI (Ministry of Economy, Trade and Industry) supports digital health innovation through regulatory harmonization initiatives. The Kanto region around Tokyo hosts the densest concentration of university hospitals deploying haptic-enabled surgical training platforms.
Medical Simulation Education Market Competitive Landscape
Premium-margin players sit above commodity-margin players across fidelity standards and certification depth, with aerospace-derived engineering and wireless physiology engines commanding pricing power over basic mannequin systems. The vendor base stratifies into three tiers: integrated platform developers sustaining recurring software revenue, fidelity specialists anchoring high-stakes procedural applications, and regional fabricators serving price-sensitive institutional segments. Dominant competitive moves include service-based contracting displacing capital purchases and cloud-native scenario authoring consolidating curriculum development workflows.
Within the integrated platform tier, Laerdal Medical and CAE Healthcare exemplify contrasting fidelity strategies. Laerdal leverages its installed base in resuscitation training to sustain recurring revenue from consumables and software subscriptions. CAE Healthcare occupies a position anchored by aerospace-derived standards in anesthesia and critical care applications. Gaumard Scientific sits within the mid-tier wireless physiology segment, enabling untethered mannequin mobility that expands deployment scenarios from fixed simulation centers to point-of-care training environments.
| Leading Market Players |
|---|
| Laerdal Medical |
| CAE Healthcare |
| Gaumard Scientific |
| Simulab Corporation |
| Limbs & Things |
| 3B Scientific |
| VirtaMed |
| Surgical Science Sweden AB |
| 3D Systems |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between FDA-validated platforms and commodity mannequin systems manifests in both pricing premiums and supply chain complexity. Tier-one vendors command recurring subscription structures through ISO 13485 compliance, while regional fabricators compete on hardware margins with minimal software attach rates.
Pricing Analysis
Per-learner throughput pricing anchors institutional procurement in the United States, with teaching hospitals negotiating multi-year service contracts bundling hardware refresh cycles and facilitator training. Price differentiation separates aerospace-derived fidelity systems from basic task trainers through automated assessment capabilities and debriefing analytics. Cost compression in mid-tier wireless physiology segments intensifies as Gaumard Scientific and comparable vendors expand point-of-care deployment scenarios. Federally qualified health centers exhibit highest price sensitivity, constrained by HRSA grant funding timelines and limited departmental capital authority.
Supply Chain Analysis
Precision sensor arrays and haptic interface components rest on Taiwanese semiconductor foundries and German precision engineering clusters. Proprietary wireless physiology engines draw from South Korean battery cell suppliers and Japanese motion control specialists. Single-source vulnerability concentrates in FDA-grade software validation partners, where premarket review pathways extend development cycles. Distribution runs through GPO contracts at academic medical centers and direct vendor relationships at specialized training centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around validated software platforms as regulatory compliance costs force hardware-only vendors toward exit or acquisition. The FDA's software-as-medical-device guidance accelerates this pressure.
For Market Incumbents: Anchor recurring revenue through cloud-native scenario authoring tools that consolidate curriculum development workflows. Defend position by deepening ISO 13485 certification moats and acquiring regional fabricators with installed base in price-sensitive segments. Threat substitution from VR headset commoditization demands aerospace-derived fidelity differentiation in anesthesia and critical care applications. For New Entrants and Emerging Players: Capture federally qualified health center networks through HRSA-funded simulation equipment grants addressing rural workforce retention. White-space concentrates in browser-based platforms enabling remote scenario customization for German university medical centers. Go-to-market leverage rests on per-learner pricing models transferring obsolescence risk from capital-constrained buyers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated platform developers seeking wireless physiology capabilities or aerospace-derived engineering talent. Long-term viability favors vendors with validated software architectures over hardware-dependent revenue models. Signal to watch: accreditation body integration of simulation-based competency benchmarks into mandatory licensure pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-Medical-Device Validation | FDA premarket review pathways secure recurring subscription revenue from teaching hospitals. |
| EU AI Act Conformity Investment | ISO 13485 certification bundles open procurement frameworks in France and Germany. |
| Cloud-Native Scenario Authoring | Browser-based platforms consolidate curriculum development at Bavarian medical schools. |
| Per-Learner Service Contracting | Multi-year agreements transfer obsolescence risk to vendors while aligning with hospital throughput metrics. |
| Wireless Physiology Engine Development | Untethered sensor arrays expand deployment from fixed simulation centers to mid-tier hospital point-of-care environments. |
Research Methodology
SEC filings, FDA premarket notification databases, and hospital procurement contract records formed the secondary backbone, cross-referenced with primary interviews involving simulation center directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at platform developers. Bottom-up triangulation across vendor revenue disclosures and top-down validation through accreditation body policy documents anchored segmentation estimates.
Historical trendline analysis of capital equipment procurement and service contract adoption informed projection frameworks across the analysis window. Segmentation dimensions modeled include technology fidelity tier, application area by credentialing requirement, end-user institutional type, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to disclosed installed base figures and replacement cycle assumptions, with surgical residency program expansion and EU AI Act implementation timelines as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to accreditation body policy shifts and FDA software validation pathway modifications. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare
Drug Designing Tools Market
Healthcare
Global Smart Hospital Market
Healthcare
North America Alopecia Market
Healthcare
Europe Electric Wheelchair Market
Healthcare
Androgens and Anabolic Steroids Market
Healthcare
Thyroid Gland Disorders Treatment Market
Healthcare
Audiology Devices Market
Healthcare
Technology Spending on Revenue Cycle Management Market
Healthcare
X Ray Crystallography Market
Healthcare
Cardiovascular Repair and Reconstruction Devices Market
Healthcare
Oculoplastic Surgery Market
Healthcare
Australia Laser Hair Removal Market
Healthcare
France Wound Care Market
Healthcare
Arthroscopic Shaver Market
Healthcare
Global Endodontics Market
Healthcare
Pressure Relief Mattress Market