
 Meat Market | 2026-2036
Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Market Intelligence
Grass-fed and organic certifications are redrawing the competitive landscape for premium beef and lamb products. Tyson Foods leverages its vast processing infrastructure and integrated distribution network to supply multiple market segments. JBS S.A. dominates production in South America, controlling significant portions of the global beef supply chain. WH Group specializes in pork processing, with a strong presence in both China and the United States.
Meat refers to the edible muscle tissue of animals, primarily composed of water, protein, and fat. Its commercial value is determined by factors like marbling, cut, and aging, serving as a primary protein source for human consumption. Poultry represents the largest product type by volume, while the frozen processing method gains share in retail and foodservice applications. Supermarkets command the retail channel, but the foodservice segment is expanding at a quicker pace.
Regulatory oversight from bodies such as the USDA in the United States, the EFSA in Europe, and China's SAMR governs food safety, labeling, and import protocols. These frameworks directly impact production costs, enforcing strict standards for hygiene, animal welfare, and supply chain traceability. Processors must now balance investments in automation for efficiency with meeting diverse and stringent international food safety requirements.
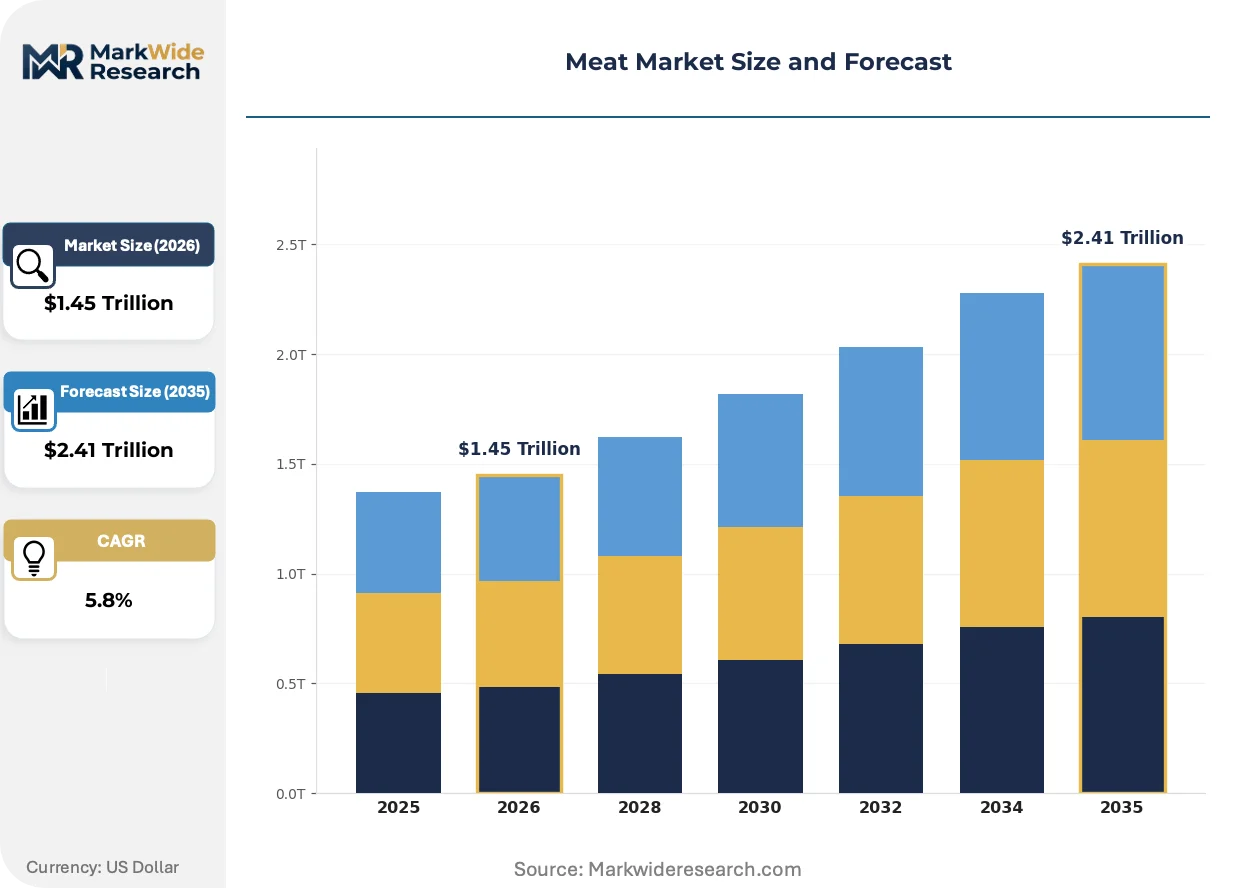
Market Dynamics
The meat market is shaped by a fundamental tension between the industrial drive for processing efficiency and the escalating complexity of global food safety and animal welfare regulations. This dynamic forces processors to balance investments in automation against the need to meet divergent standards set by bodies like the USDA, EFSA, and SAMR.
Growth Catalysts
- Foodservice Demand:The expanding foodservice sector's requirement for portion-controlled and precooked beef and poultry products accelerates growth, as commercial kitchens seek to improve labor efficiency and menu consistency.
- Premiumization in Asia:Rising disposable incomes in China and South Korea are concentrating demand for high-marbled, premium cuts of pork and beef, creating lucrative export opportunities for producers who can meet specific quality standards.
- Certification-Driven Access:Adherence to animal welfare and traceability frameworks, guided by bodies like the European Food Safety Authority, is becoming a prerequisite for accessing high-value international markets, rewarding producers with certified supply chains.
Market Restraints
- Regulatory Divergence:Conflicting and frequently updated food safety and labeling protocols between major trading blocks, such as the US and EU, create significant compliance costs and logistical hurdles for exporters.
- Feed Cost Volatility:The market's profitability is consistently exposed to price fluctuations in core feed commodities like corn and soybeans, which can dramatically increase production costs and squeeze processor margins.
- Plant-Based Substitution:The increasing consumer acceptance and retail availability of plant-based protein alternatives present a direct substitution threat, particularly in product categories like ground meat and processed items.
Strategic Opportunities
- Value-Added Processing:Opportunity exists in expanding portfolios of value-added products, such as marinated, ready-to-cook, and heat-and-eat meat items that cater to consumer demand for convenience.
- Blockchain for Traceability:Implementing blockchain technology offers a method to provide immutable, transparent traceability records from farm to fork, meeting both regulatory mandates and consumer demand for provenance information.
- Halal and Kosher Expansion:There is significant opportunity to develop and market certified Halal and Kosher meat products in Western Europe and North America, serving growing demographic segments with specific dietary requirements.
Industry Challenges
- Automation Capital Costs:The substantial capital investment required to automate cutting, deboning, and packaging lines presents a significant barrier for small and medium-sized processors seeking to improve efficiency and workplace safety.
- Animal Welfare Compliance:Maintaining and documenting consistent compliance with evolving, often subjective, animal welfare standards across vast, geographically dispersed supply chains is a major operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Market |
| Market Size in 2026 | $1.45 Trillion |
| Market Size in 2035 | $2.41 Trillion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Poultry, Lamb, Game Meat Processing Method: Fresh, Frozen, Cured, Smoked, Precooked Application: Retail, Foodservice, Manufacturing, Institutional Dining, Catering End User: Supermarkets, Butcher Shops, Restaurants, Hotels, Food Distributors |
| Companies Covered | WH Group, Marfrig Global Foods, JBS S.A., Danish Crown, Hormel Foods Corporation, Tyson Foods, BRF S.A., National Beef Packing Company, Cargill Meat Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Market Strategic Shifts & Innovations
Technological advancements in genetics, monitoring, and processing are converging to address dual pressures for greater supply chain transparency and operational sustainability. These innovations are transforming how meat is produced, tracked, and marketed, aligning industrial practices more closely with consumer and regulatory expectations for safety and ethics.
Precision livestock farming utilizes IoT sensors and AI-powered analytics to monitor individual animal health, welfare, and growth in real time. Large-scale beef and poultry producers are the primary adopters, using the data to optimize feed conversion and preemptively manage disease. This data-centric management model is supplanting traditional, reactive methods of animal husbandry, leading to improved yields and resource efficiency.
The European Union's Farm to Fork Strategy is a significant regulatory driver impacting production methods far beyond Europe's borders. It imposes stringent targets for reducing antibiotic use, promoting animal welfare, and enhancing sustainability across the food system. Pork and poultry producers exporting to the EU are most affected, compelled to re-engineer their production processes to maintain market access.
A clear behavioral shift is evident as consumer purchasing criteria pivot from brand loyalty to verifiable production ethics and provenance. This change disrupts retail dynamics, with on-package QR codes that link to detailed farm and processing data beginning to replace simple origin labels. This demand for radical transparency is most pronounced in the premium beef and organic poultry segments in North America and Western Europe.
Meat Market Segmentation
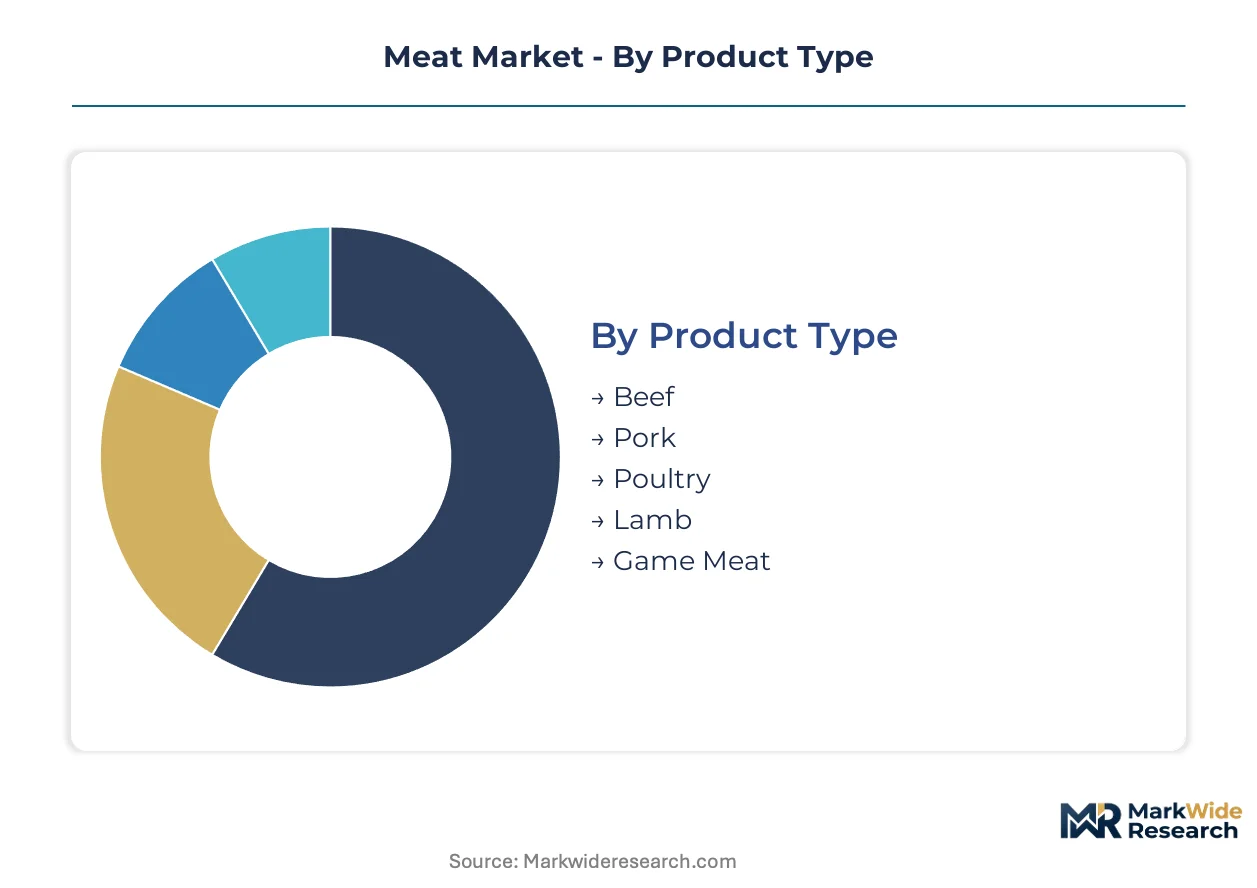
The meat market's segmentation reflects diverse consumer preferences, processing requirements, and distribution channels, each commanding distinct operational strategies and investment profiles. Understanding these divisions is essential for producers and distributors to align product offerings with specific demand drivers and regulatory frameworks. Market dynamics vary significantly across product types, processing methods, and end-user applications.
Product Type:
Margin pools within this category are heavily influenced by consumer demand for premium cuts and specific regional dietary preferences.
- Beef:Comprises muscle tissue from cattle, valued for its rich flavor and protein content, with commercial grades like Prime, Choice, and Select. Demand for high-marbled, premium beef cuts concentrates heavily in sophisticated markets such as China and South Korea, driven by rising disposable incomes.
- Pork:Derived from domesticated pigs, offering a versatile range of cuts from lean loin to fatty belly. Global supply chains are significantly influenced by large processors like WH Group, which control substantial production and distribution networks in key markets such as the United States and China.
- Poultry:Encompasses chicken, turkey, and duck, representing the largest product type by volume due to its affordability and versatility. Processing operations benefit from high automation levels, particularly in large-scale facilities supplying both retail and foodservice sectors.
- Lamb:Meat from young sheep, characterized by its distinct flavor and tenderness, often associated with specific culinary traditions.
- Game Meat:Includes venison, bison, and wild boar, typically sourced from wild or semi-domesticated animals, appealing to niche markets seeking exotic or leaner protein alternatives.
The dominant share belongs to Poultry, while Beef is closing the gap fastest in terms of premiumization and value concentration.
Processing Method:
Supply concentration in this category dictates production scale and technological investment, particularly for methods requiring specialized equipment or cold chain logistics.
- Frozen:Meat products rapidly cooled to below 0°C to preserve quality and extend shelf life, facilitating long-distance distribution. This method gains significant share in both retail and foodservice applications, driven by convenience and reduced waste.
- Precooked:Meat that has been fully or partially cooked before packaging, requiring minimal preparation by the end-user. The foodservice sector increasingly demands precooked poultry and beef products to enhance operational efficiency and ensure menu consistency.
- Fresh:Unprocessed or minimally processed meat sold without freezing or curing, requiring strict temperature control and rapid distribution.
- Cured:Meat preserved using salt, sugar, nitrates, or nitrites, altering its flavor and extending its shelf life, as seen in bacon or ham production.
- Smoked:Meat treated with smoke from burning wood, imparting distinct flavors and contributing to preservation, commonly applied to sausages and certain cuts of beef or pork.
Frozen processing represents the fastest-growing trajectory, with Precooked products expanding most quickly in specific commercial applications.
Application:
Customer type variations within this category drive differing demands for product forms, packaging sizes, and delivery frequencies across the market.
- Foodservice:Supplies restaurants, cafes, and catering operations with bulk, portion-controlled, and precooked meat products. This segment is expanding at a quicker pace than traditional retail, driven by consumer dining habits and labor efficiency needs.
- Retail:Involves direct sales to consumers through supermarkets, hypermarkets, and specialized butcher shops. Supermarkets command the retail channel, offering a wide array of fresh, frozen, and processed meat options.
- Manufacturing:Provides meat as an ingredient for further processing into products like ready meals, sausages, or deli meats.
- Institutional Dining:Caters to large-scale establishments such as schools, hospitals, and corporate cafeterias, often requiring standardized products and bulk deliveries.
- Catering:Supplies events and functions with prepared or semi-prepared meat dishes, emphasizing presentation and specific culinary requirements.
The Foodservice segment experiences the steepest expansion trajectory, while Retail maintains its significant volume base.
End User:
The maturity of distribution networks for this category influences market access and pricing strategies across different consumer touchpoints.
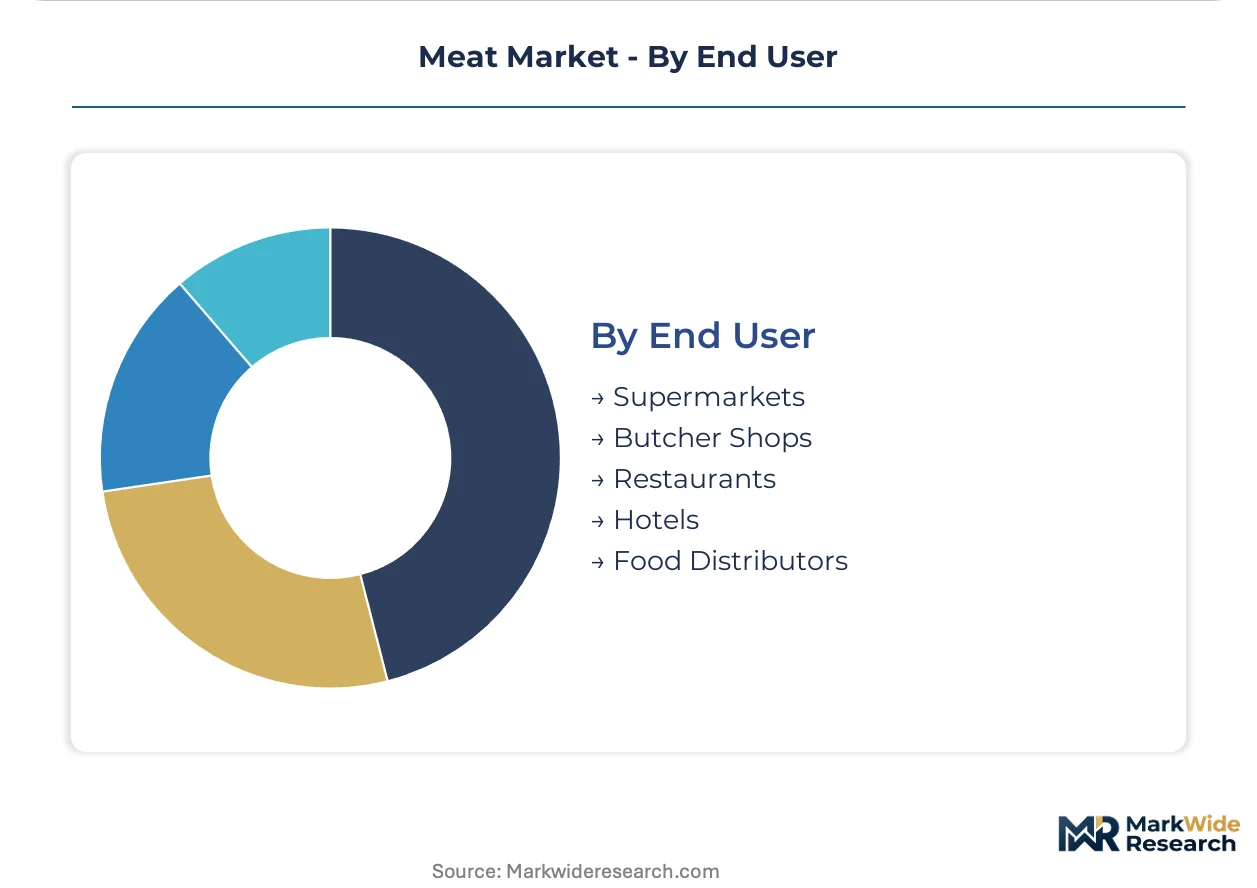
- Supermarkets:Large retail stores offering a wide selection of fresh, frozen, and processed meat products to a broad consumer base. These outlets leverage extensive supply chains and strong brand recognition.
- Restaurants:Commercial establishments preparing and serving meals to diners, demanding specific cuts, quality, and portion control for their menus. The expansion of the foodservice sector directly correlates with restaurant demand.
- Butcher Shops:Specialized retail outlets focusing on fresh, often custom-cut meats, catering to consumers seeking specific quality or artisanal products.
- Hotels:Provide meat products for their in-house dining, room service, and banquet facilities, often requiring premium quality and consistent supply.
- Food Distributors:Intermediaries that procure meat from processors and supply it to various end-users including restaurants, hotels, and smaller retail operations, managing complex logistics.
Supermarkets hold the largest volume share, with Restaurants demonstrating the most dynamic growth in demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration significantly influences global meat market dynamics, particularly in regions where large-scale processing infrastructure and extensive livestock farming converge. This concentration shapes trade flows and regulatory compliance challenges across different geographies. Processors must navigate varying standards while meeting diverse consumer demands.
United States
The United States experiences robust demand for poultry volume and a rapidly expanding foodservice sector. USDA regulations dictate stringent food safety, labeling, and animal welfare standards for domestic production and imports. Large-scale beef and pork processing clusters in Midwestern states like Nebraska and Iowa drive significant national output.
Brazil
Brazilian producers are major global beef exporters, benefiting from vast grazing lands and efficient production systems. ANVISA, the national health surveillance agency, alongside agricultural ministries, oversees food safety and export certifications. The states of Mato Grosso and São Paulo serve as key hubs for cattle ranching and meat processing facilities.
China
China's expanding middle class drives concentrated demand for premium pork and beef cuts, reflecting rising disposable incomes. SAMR, the State Administration for Market Regulation, enforces strict food safety and import protocols, influencing global supply chains. Shandong and Henan provinces are central to domestic pork production and consumption markets.
Germany
German consumers prioritize animal welfare and sustainability, influencing procurement patterns for diverse meat products. The European Food Safety Authority (EFSA) and the EU Farm to Fork Strategy impose stringent environmental and ethical production targets. North Rhine-Westphalia and Lower Saxony host significant pork and poultry processing operations.
South Korea
South Korean demand concentrates on high-marbled premium beef and specific pork cuts, deeply embedded in local culinary traditions. The Ministry of Food and Drug Safety (MFDS) sets rigorous import standards for meat products, ensuring quality and safety. The Seoul metropolitan area represents a critical distribution and consumption market for high-value meat.
Meat Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the global meat market. The industry structure shows consolidation among a few global giants, while numerous smaller, specialized processors cater to niche markets. Dominant strategic archetypes include globally integrated processors, regional specialists, and value-added product innovators. Key competitive moves involve extensive mergers and acquisitions to expand geographic reach and significant investments in processing capacity.
Globally integrated processors like JBS S.A., a Brazilian company, and Tyson Foods, an American corporation, exemplify the scale-driven end of the market, controlling vast supply chains from farm to distribution. WH Group, a Chinese company, represents a significant player specializing in pork processing with substantial operations across China and the United States. These companies anchor the industry through their extensive infrastructure and ability to meet diverse market demands across multiple continents.
| Leading Market Players |
|---|
| WH Group |
| Marfrig Global Foods |
| JBS S.A. |
| Danish Crown |
| Hormel Foods Corporation |
| Tyson Foods |
| BRF S.A. |
| National Beef Packing Company |
| Cargill Meat Solutions |
| Others |
Cost & Logistics Intelligence
Cold chain lead times for fresh meat products directly influence inventory management and pricing power, particularly for perishable premium cuts. This dynamic forces processors to balance logistical efficiency with market demand fluctuations.
Pricing Analysis
USDA regulations dictate the pricing tier structure for beef and poultry products, influencing commercial grades. The dominant pricing model is a hybrid of commodity spot pricing for bulk items and contract-based long-term offtake agreements for specialized products. Price differentiation drivers include marbling grade and specific animal welfare certifications. Pricing pressure stems from volatility in core feed commodity costs, impacting processor margins. Foodservice buyers demonstrate lower price sensitivity due to consistency requirements, while manufacturing segments are highly price-sensitive for ingredient procurement.
Supply Chain Analysis
Brazil and the United States anchor global beef and poultry production, with China dominating pork processing. The meat supply chain draws from critical agricultural inputs like corn and soybeans, which are susceptible to global market fluctuations. A key structural supply chain risk is commodity price volatility, particularly for animal feed. Distribution runs through a dual model, with large food distributors serving the expanding foodservice sector and supermarkets commanding the retail channel for consumer sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Meat Market is in an early-cycle expansion phase, driven by increasing foodservice demand for value-added products and premiumization trends in Asia.
For Market Incumbents: Compound existing processing infrastructure by investing in advanced automation for efficiency and worker safety. This mitigates rising labor costs and the threat of plant-based substitution by maintaining cost competitiveness. Deepen supply chain traceability through blockchain technology, leveraging certification investments to meet evolving regulatory standards from EFSA and USDA. Expand value-added product R&D to capture convenience-driven consumer demand.
For New Entrants and Emerging Players: Anchor in niche segments with high-margin potential, such as certified Halal and Kosher meat products. Western Europe and North America represent penetrable geographies for these offerings, driven by specific demographic requirements. Target premium organic poultry with verifiable provenance, utilizing specialized distributors and direct-to-consumer channels to build trust and capture discerning consumers. Focus on transparent supply chains using QR codes linking to farm data.
For Investors and Strategic Acquirers: Carve-out targets emerge from large, diversified food conglomerates seeking to divest non-core meat processing assets. The long-term viability of the meat market remains strong due to fundamental protein demand, particularly for premium cuts in Asia. Investors should seek regional specialists with robust animal welfare compliance or technology innovators in precision livestock farming. The signal to watch is the stabilization of global feed commodity prices, which directly impacts processor margins.
| Strategic Initiative | Industry Significance |
|---|---|
| Automation Investment | Enhances processing efficiency and worker safety, addressing labor shortages and cost pressures in US plants. |
| Blockchain Traceability | Provides immutable records from farm to fork, meeting EFSA and SAMR regulatory demands for provenance. |
| Halal/Kosher Certification | Unlocks access to growing demographic segments in Western Europe and North America with specific dietary needs. |
| Value-Added Product Expansion | Caters to foodservice and retail demand for convenience, increasing margin potential for poultry and beef items. |
| Precision Livestock Farming Adoption | Optimizes feed conversion and animal health, improving resource efficiency for large-scale beef producers. |
Research Approach
A standing panel of meat processors, foodservice procurement leads, retail category managers, and animal welfare advocates provided ongoing calibration. Primary interviews with these industry stakeholders were complemented by extensive secondary validation. Data sources included USDA production reports, EFSA food safety guidelines, national customs data, and public company 10-K filings. This approach ensured robust bottom-up and top-down triangulation.
Market size and growth outputs were consistently checked against external benchmarks and historical trade volumes across the analysis window. The analytical framework modeled segmentation dimensions including product type, processing method, application, end-user, and animal welfare certification level. Compound annual growth rates were derived through correlation analysis of historical trends and projected market drivers. Key forecast inputs included global grain prices and regional disposable income trends.
Material uncertainties — including geopolitical trade disputes and novel animal disease outbreaks — sit outside the modeled envelope, representing potential revision triggers. Forecasts reflect assumptions regarding regulatory stability and consumer behavioral patterns. Recalibration cycles align with material shifts in global feed commodity markets or major regulatory frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Organic Lamb Market
Meat Products
Organic Meat Market
Meat Products
Meat Flavors Market
Meat Products
United States Processed Pork Meat Market
Meat Products
Beef Tallow Market
Meat Products
Organic Meat Products Market
Meat Products
Global Edible Meat Market
Meat Products
Vegan Meatball Market
Meat Products
Grassfed Jerky Market
Meat Products
Mechanically Separated Meat Market
Meat Products
Germany Meat Products Market
Meat Products
Global Canned Meat Market
Meat Products
Global Lab-Based Meat Market
Meat Products
Non-Veg Rte and Rtc Market
Meat Products
Global Red Meat Market
Meat Products
North America Processed Pork Meat Market