
 Malaysia Data Center Power Market | 2026-2036
Malaysia Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Data Center Power Market Insights
ISO 50001 energy management certification is redrawing vendor qualification standards for Malaysian data center operators. Schneider Electric SE leverages its integrated EcoStruxure platform to anchor large-scale deployments across Peninsular Malaysia. ABB Ltd competes through high-efficiency UPS architectures that sustain power quality at tropical ambient temperatures. Delta Electronics specializes in modular power modules that dominate retrofit installations in legacy facilities.
Data center power encompasses the generation, conditioning, distribution, and backup infrastructure that delivers uninterrupted electrical supply to server halls, with critical specifications including UPS switching times below 4 milliseconds and generator start sequences under 10 seconds to prevent workload interruption. UPS Systems command the largest installed base due to mandatory redundancy requirements in Tier III and IV facilities, while Renewable Sources represent the fastest-expanding category as Malaysia's Green Building Index and corporate renewable energy tariffs reshape procurement criteria. Fuel Cells occupy a nascent but strategically watched position for long-duration backup in hyperscale campuses.
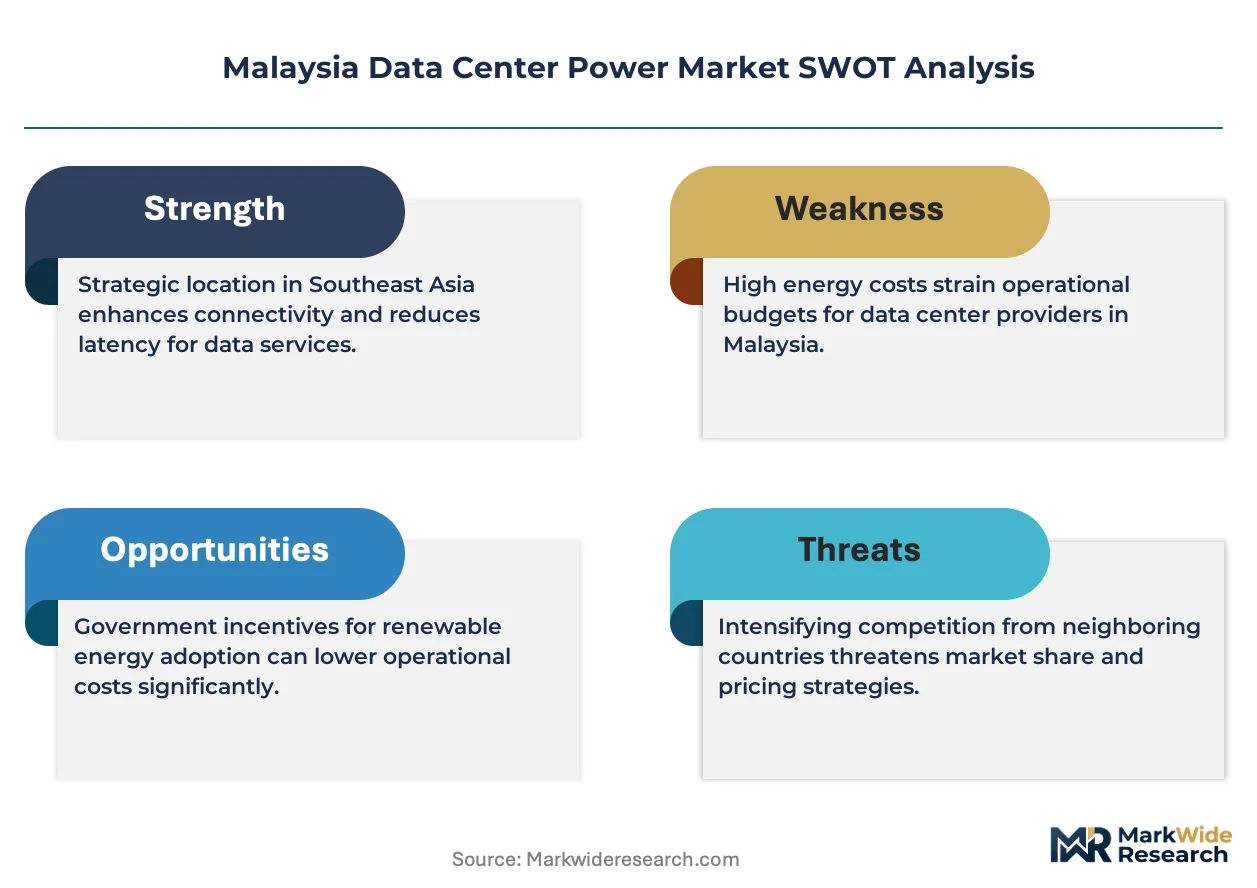
Malaysia's Energy Commission (ST) regulates grid interconnection standards for facilities above 10 MW, while the Green Building Index and Suruhanjaya Tenaga efficiency mandates shape equipment selection and operational compliance. The Department of Environment enforces thermal discharge limits that push operators toward liquid cooling and higher-efficiency power conversion. Stakeholders must monitor how Malaysia's renewable energy transition policies and cross-border carbon border adjustments reshape total cost of ownership calculations for power infrastructure investments.
Market Dynamics
Malaysia's hyperscale cloud buildouts are compressing power infrastructure procurement cycles from 18 months to under 9 months, forcing equipment vendors to reconfigure supply chains around tropical-rated specifications and local assembly capacity.
Growth Catalysts
- Green Building Index mandates:Malaysia's GBI certification now requires renewable energy integration for new data center builds, accelerating procurement of solar-hybrid power architectures.
- Cloud provider concentration:Hyperscale operators are clustering 50+ MW campuses in Cyberjaya and Iskandar Puteri, creating anchor demand for high-redundancy UPS and medium-voltage switchgear.
- Corporate renewable energy tariffs:Malaysia's regulatory framework for direct power purchase agreements allows data center operators to secure long-term clean electricity contracts.
Market Restraints
- Copper and rare earth price volatility:Transformer and busbar input costs fluctuate with commodity markets, squeezing margins on fixed-price EPC contracts.
- Southeast Asian semiconductor supply concentration:Power electronics component sourcing remains concentrated in Thailand and Vietnam, exposing Malaysian projects to cross-border logistics friction.
- Grid interconnection queues:Suruhanjaya Tenaga approval timelines for 10+ MW facilities extend 14-18 months, delaying revenue commencement for power infrastructure investments.
Strategic Opportunities
- Johor Bahru corridor expansion:Iskandar Malaysia's designated technology zone offers tax incentives and streamlined permitting for second-campus developments.
- Liquid cooling convergence:Integration of direct-to-chip cooling with high-efficiency power distribution creates integrated thermal-electrical design opportunities.
- Fuel cell long-duration backup:Hydrogen fuel cell systems for multi-hour outage protection remain underdeployed in Malaysian Tier III facilities.
Industry Challenges
- ISO 50001 certification timelines:Energy management system audits require 12-18 months of operational data, delaying vendor qualification for new market entrants.
- Legacy low-voltage retrofit complexity:Existing facilities built to 400V standards face integration friction with modern 415/480V hyperscale equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Data Center Power Market |
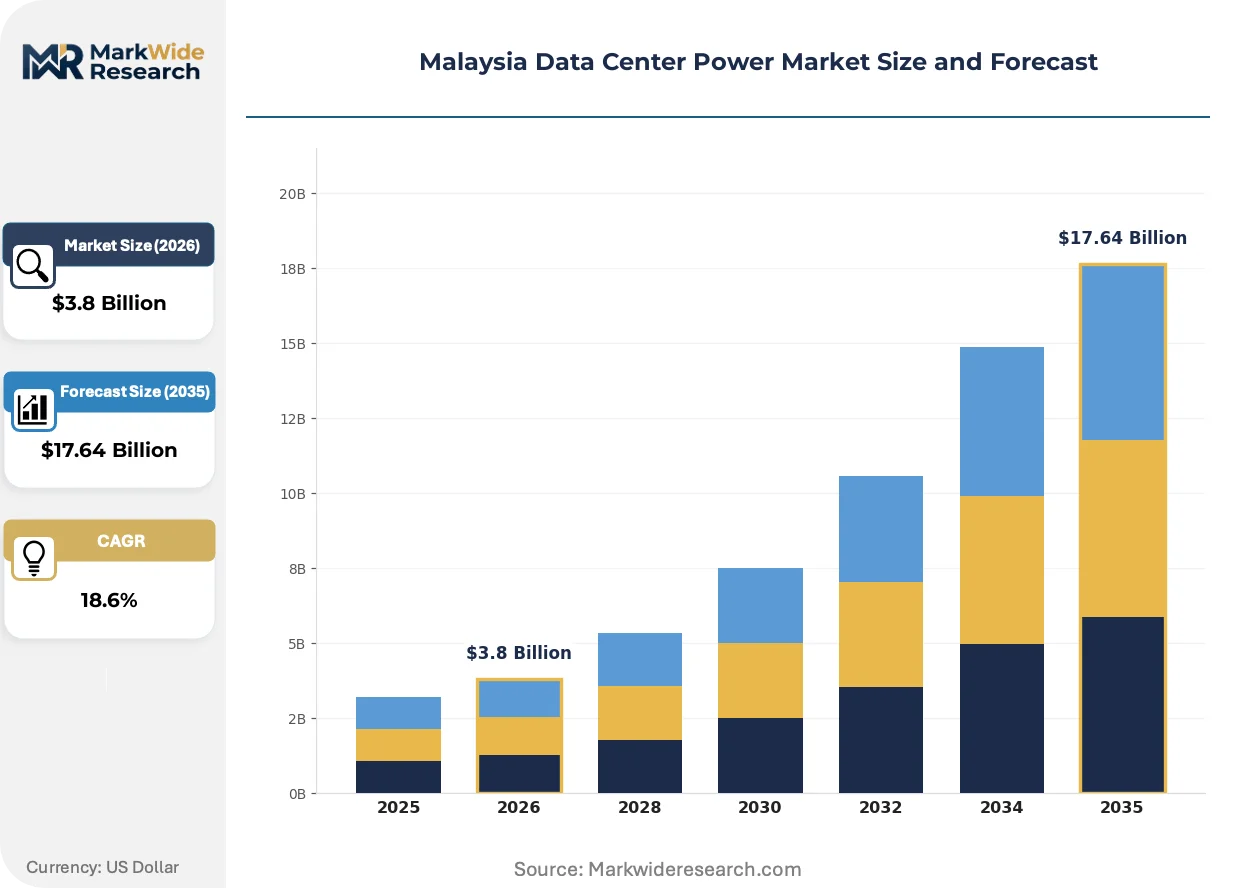
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Type: UPS Systems, Generators, Renewable Sources, Fuel Cells End User: Telecommunications, Cloud Providers, IT Services, E-commerce Power Capacity: Below 1 MW, 1-5 MW, 5-10 MW, Above 10 MW Service Type: Managed Services, Consulting, Maintenance, Installation |
| Companies Covered | ABB Ltd, Schneider Electric SE, Vertiv Group Corp., Eaton Corporation, Caterpillar Inc., Delta Electronics, Legrand Group, Hitachi Energy, Rittal GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Data Center Power Market Trends and Innovations
Power architecture modularity is rewriting equipment specification standards across Malaysian data center developments, compressing deployment timelines while raising thermal performance requirements for tropical installations.
Modular UPS architectures with distributed static switches are decomposing traditional centralized backup power designs. Hyperscale operators in Cyberjaya are specifying containerized 2.5 MW power modules for phased capacity expansion. This approach is decomposing the capital commitment structure, allowing incremental deployment aligned to actual server rack activation rather than front-loaded infrastructure overbuild.
Malaysia's Department of Environment thermal discharge regulations are tightening effluent temperature limits for data center cooling systems. Operators must now demonstrate heat rejection efficiency above 85% or face operational restrictions. Facilities in the Klang Valley corridor are responding by specifying adiabatic cooling towers and liquid-cooled server racks to maintain compliance margins.
Power purchase agreement structures are displacing traditional utility tariff dependency among Malaysian colocation providers. Large operators are negotiating 15-20 year renewable energy contracts directly with solar and biomass generators. This pattern concentrates most visibly in Johor, where land availability supports captive solar installations adjacent to data center campuses.
Malaysia Data Center Power Market Segmentation
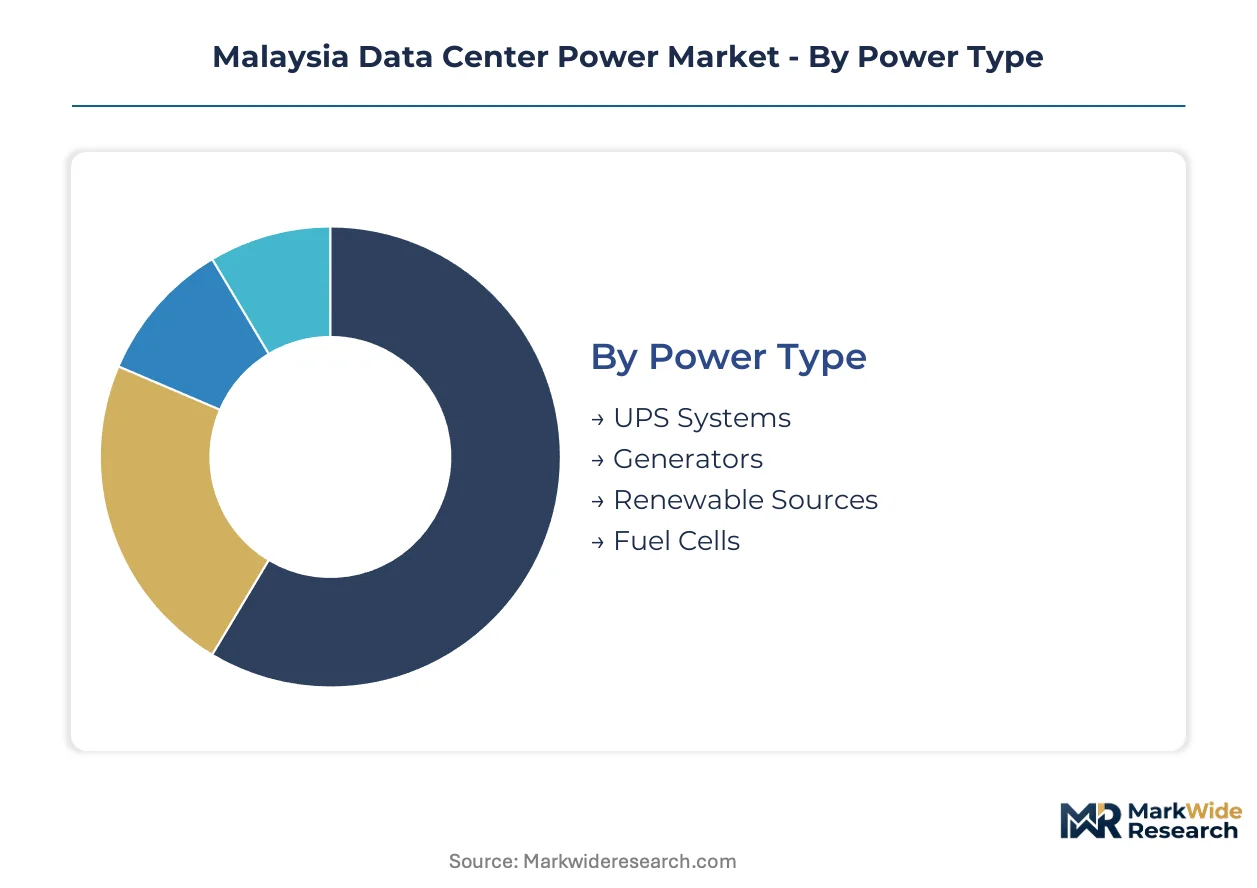
Segmentation reveals how procurement patterns diverge across Malaysia's data center landscape. Hyperscale operators in Cyberjaya and Iskandar Puteri prioritize high-capacity modular architectures, while legacy facilities in the Klang Valley drive retrofit demand for integrated power services.
Power Type:
Channel distribution varies sharply by power category. UPS Systems and Generators flow primarily through EPC contractors serving Tier III and IV builds, while Renewable Sources and Fuel Cells increasingly route through energy service companies managing corporate PPA structures.
- UPS Systems:Double-conversion online systems with sub-4 millisecond switching times form the backbone of hyperscale redundancy architectures. Demand concentrates in Cyberjaya's 50+ MW campuses where Schneider Electric and ABB anchor supply relationships through integrated EcoStruxure and high-efficiency tropical-rated platforms.
- Renewable Sources:Solar-hybrid architectures with battery storage integration are displacing conventional backup configurations under Green Building Index mandates. Johor's Iskandar Puteri zone leads deployment where land availability supports captive solar installations adjacent to data center campuses.
- Generators:Diesel and gas turbine systems provide 10-second start sequence backup for grid interconnection resilience.
- Fuel Cells:Hydrogen fuel cell systems for multi-hour outage protection remain nascent in Malaysian Tier III facilities.
By volume, UPS Systems leads. By growth pace, Renewable Sources is ahead.
End User:
Customer type dictates procurement scale and service bundling intensity. Cloud Providers and IT Services favor integrated managed service contracts, while Telecommunications and E-commerce segment procurement across multiple vendors.
- Cloud Providers:Hyperscale operators specify containerized 2.5 MW power modules with phased deployment clauses. Cyberjaya and Iskandar Puteri campuses compress procurement cycles from 18 months to under 9 months, forcing vendor supply chain reconfiguration around tropical-rated specifications.
- IT Services:Colocation providers negotiate 15-20 year renewable energy contracts directly with solar and biomass generators. Johor's land-rich environment supports this PPA concentration, displacing traditional utility tariff dependency.
- Telecommunications:Telco-owned facilities prioritize legacy system interoperability with 400V infrastructure.
- E-commerce:Fulfillment-integrated data centers demand rapid-scaling modular architectures.
Cloud Providers command the largest project scale. IT Services show the steepest expansion trajectory in renewable-integrated procurement.
Power Capacity:
Capacity tier correlates with regulatory jurisdiction and approval complexity. Facilities above 10 MW trigger Suruhanjaya Tenaga grid interconnection queues extending 14-18 months, while sub-5 MW projects navigate streamlined municipal permitting.
- Above 10 MW:Hyperscale campuses require medium-voltage switchgear and dedicated substation infrastructure. Suruhanjaya Tenaga mandates 14-18 month approval timelines, concentrating development in Johor Bahru corridor where Iskandar Malaysia's designated technology zone offers tax incentives and streamlined permitting.
- 5-10 MW:Mid-scale facilities balance redundancy requirements with grid connection feasibility.
- 1-5 MW:Enterprise and colocation builds dominate this tier with standardized UPS-generator configurations.
- Below 1 MW:Edge and micro data centers drive modular power module adoption for rapid deployment.
Above 10 MW captures dominant capital deployment. Below 1 MW is climbing the fastest as edge infrastructure proliferates.
Service Type:
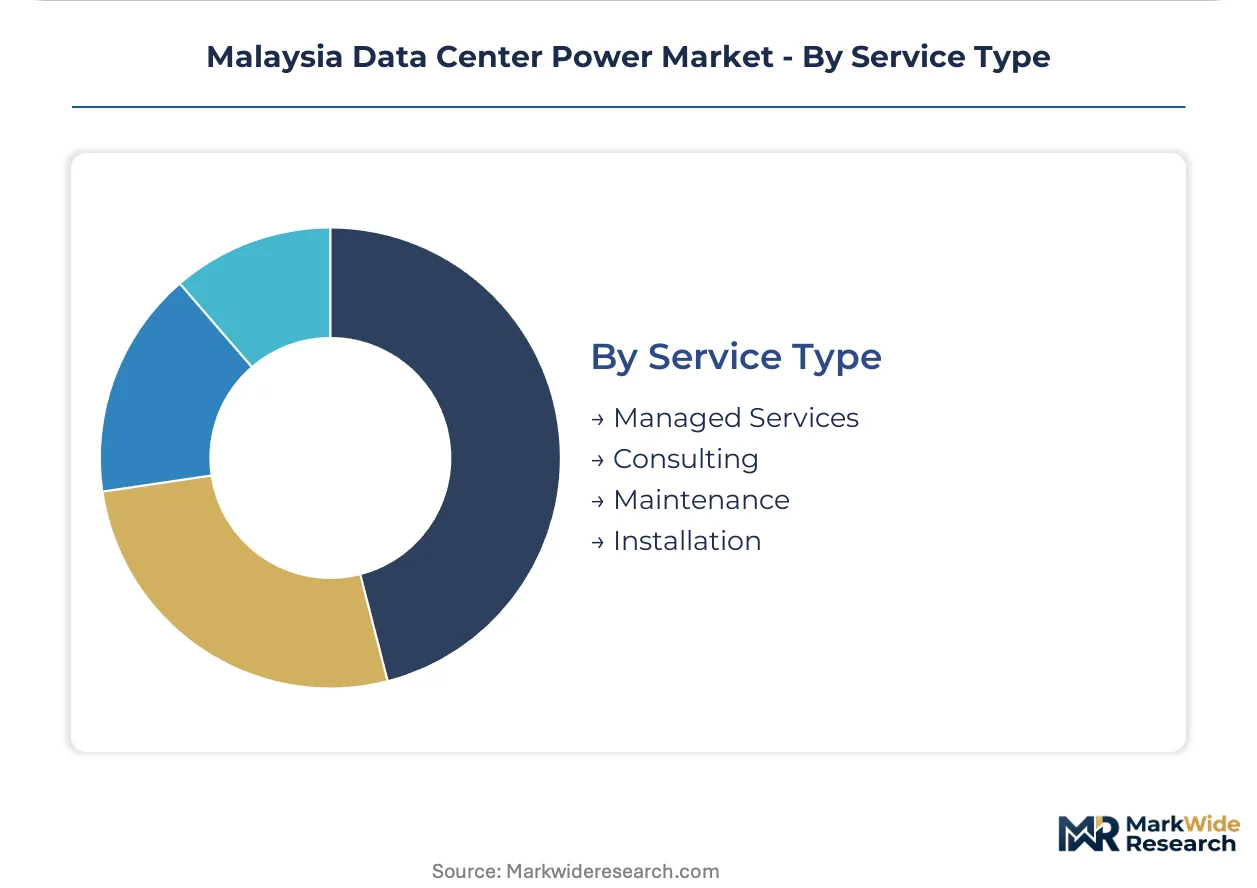
Service bundling intensity rises with facility complexity. Managed Services and Consulting command premium pricing for ISO 50001-aligned energy management, while Installation and Maintenance compete on cost efficiency.
- Managed Services:Comprehensive energy management including real-time monitoring and predictive maintenance. ISO 50001 certification requirements drive 12-18 month operational data collection periods, creating vendor qualification barriers for new market entrants.
- Consulting:Power architecture design and Green Building Index compliance planning. Demand concentrates among hyperscale operators navigating Malaysia's renewable energy transition policies and cross-border carbon border adjustment exposures.
- Maintenance:Preventive and corrective service contracts for UPS and generator fleets.
- Installation:EPC execution with fixed-price contracting exposure to copper and rare earth commodity volatility.
Managed Services leads by contract value. Consulting is gaining share fastest on compliance complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's national technology zone incentives and Green Building Index mandates are concentrating data center power infrastructure investment across three distinct sub-regional corridors, each shaped by differentiated regulatory treatment and land availability profiles.
Klang Valley Corridor
Cyberjaya anchors hyperscale campus development with 50+ MW facilities driving demand for containerized 2.5 MW power modules. Suruhanjaya Tenaga regulates grid interconnection for facilities above 10 MW with 14-18 month approval timelines. The corridor compresses procurement cycles from 18 months to under 9 months as cloud providers cluster redundant UPS and medium-voltage switchgear deployments.
Johor Bahru Corridor
Iskandar Puteri's designated technology zone offers tax incentives and streamlined permitting for second-campus developments. The Department of Environment enforces thermal discharge limits above 85% heat rejection efficiency, pushing operators toward adiabatic cooling towers and liquid-cooled server racks. Land availability supports captive solar installations adjacent to data center campuses, enabling 15-20 year renewable power purchase agreements.
Penang-Northern Region
Legacy industrial zones are retrofitting 400V infrastructure to accommodate modern 415/480V hyperscale equipment. Delta Electronics dominates modular power module installations in these legacy facilities. The Green Building Index mandates renewable energy integration for new builds, accelerating solar-hybrid procurement across Penang's expanding technology parks.
East Malaysia (Sarawak)
Hydropower-rich Sarawak offers alternative clean energy sourcing for data center operators seeking carbon-neutral power architectures. The state's utility regulator facilitates direct corporate renewable energy contracts outside Peninsular Malaysia's grid framework. Kuching and Miri are emerging as edge infrastructure locations for below-1 MW modular deployments serving Borneo connectivity needs.
Malaysia Data Center Power Market Competitive Landscape
Player mix skews toward integrated platform providers with tropical-rated equipment portfolios, creating a tiered structure where global electrical majors anchor premium hyperscale contracts and regional specialists capture retrofit fragmentation. Three archetypes dominate: full-stack infrastructure integrators with energy management software layers, component specialists in high-efficiency power conversion, and modular system fabricators serving rapid-deployment edge markets. Competitive moves concentrate on supply chain localization for tropical specifications and strategic partnerships with EPC contractors holding Suruhanjaya Tenaga grid interconnection expertise.
Within the integrated platform tier, Schneider Electric SE and ABB Ltd exemplify contrasting approaches to the Malaysian market—Schneider anchoring large-scale deployments through its EcoStruxure energy management architecture, while ABB competes through high-efficiency UPS platforms engineered for tropical ambient temperatures. Delta Electronics occupies a distinct modular specialist position, dominating retrofit installations in legacy Klang Valley facilities with distributed static switch architectures that decompose traditional centralized backup designs.
| Leading Market Players |
|---|
| ABB Ltd |
| Schneider Electric SE |
| Vertiv Group Corp. |
| Eaton Corporation |
| Caterpillar Inc. |
| Delta Electronics |
| Legrand Group |
| Hitachi Energy |
| Rittal GmbH |
| Others |
Pricing and Supply Chain Analysis
Containerized 2.5 MW power modules replacing traditional centralized UPS architectures are simultaneously shifting procurement geography toward Cyberjaya and Iskandar Puteri while compressing vendor margins through accelerated deployment timelines and tropical-rated specification premiums.
Pricing Analysis
Certification level under ISO 50001 energy management standards creates the primary spread between premium managed service contracts and commodity installation-only bids. Three-tier pricing structure across premium, standard, and economy levels reflects bundling intensity of real-time monitoring, predictive maintenance, and Green Building Index compliance consulting. Cost compression in standard-tier EPC contracts is intensifying because copper and rare earth commodity volatility squeezes fixed-price agreements. Cloud providers show the least price sensitivity due to 15-20 year renewable PPA horizons, while telecommunications operators retrofitting 400V legacy facilities drive hardest bargain on modular power modules.
Supply Chain Analysis
Inventory lead times for tropical-rated switchgear and high-efficiency UPS platforms have extended as Malaysian hyperscale procurement cycles compress from 18 months to under 9 months. Manufacturing concentration rests on Thailand and Vietnam for power electronics components, with Schneider Electric and ABB anchoring premium-tier supply through regional assembly hubs. Transformer copper windings, silicon carbide semiconductors, and lithium-ion battery cells constitute critical input dependencies. Single-source vulnerability concentrates in Southeast Asian semiconductor fabrication exposure to cross-border logistics friction. Distribution runs through EPC contractors holding Suruhanjaya Tenaga grid interconnection expertise for facilities above 10 MW.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent power infrastructure vendors face substitution defense against fuel cell long-duration backup systems and liquid-cooled thermal-electrical integrated designs that could displace traditional UPS-generator architectures in Tier III facilities.
For Market Incumbents: Compound defensive positioning through backward integration into tropical-rated switchgear manufacturing and captive supply of silicon carbide power modules. Anchor ISO 50001 certification services to multi-year managed service contracts before fuel cell vendors establish operational data credibility. Deepen channel control by acquiring EPC contractors with Suruhanjaya Tenaga approval track records for 10+ MW grid interconnections. For New Entrants and Emerging Players: Anchor in Johor Bahru corridor's Iskandar Malaysia technology zone where streamlined permitting and tax incentives reduce regulatory barriers for second-campus developments. Target below-1 MW edge infrastructure deployments in Sarawak's Kuching and Miri zones where hydropower-rich clean energy sourcing attracts carbon-neutral power architecture demand. Penetrate through modular fuel cell backup systems for multi-hour outage protection currently underdeployed in Malaysian Tier III facilities. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed EPC contractors holding Suruhanjaya Tenaga grid interconnection expertise and established relationships with hyperscale cloud operators. Five-to-ten year viability hinges on renewable-integrated power architecture deployment velocity outpacing traditional diesel generator retrofit demand. Watch for inflection signal when Johor's captive solar PPA structures achieve cost parity with utility tariffs across the Klang Valley corridor.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 50001 Certification Program | Energy management system audits create 12-18 month vendor qualification barriers for new entrants. |
| Backward Integration into Power Modules | In-house production of containerized 2.5 MW systems compresses deployment timelines for hyperscale campuses. |
| Long-term Renewable PPA Structure | Direct contracts with solar and biomass generators displace utility dependency for Johor colocation providers. |
| Liquid Cooling Convergence Partnership | Integration with direct-to-chip thermal systems addresses Department of Environment 85% heat rejection mandates. |
| Fuel Cell Backup Deployment | Hydrogen systems for multi-hour outage protection penetrate Tier III facilities where diesel generators dominate. |
Research Methodology
The analysis maps UPS systems, renewable sources, generators, and fuel cells, each validated through data center facility managers, EPC contractor procurement leads, Suruhanjaya Tenaga grid interconnection officers, and Green Building Index assessors. Primary interviews with hyperscale cloud operators and colocation providers combined with secondary validation against Energy Commission regulatory filings, Department of Environment thermal discharge records, and corporate renewable energy tariff disclosures. Bottom-up equipment procurement tracking and top-down infrastructure investment flow triangulation anchored market sizing.
Consistency checks against hyperscaler capex disclosures and EPC contract award databases validated volume and value outputs across the projection horizon. Segmentation modeling incorporated power type, end user archetype, capacity tier, and service bundling intensity. CAGRs derived from equipment procurement cycle compression rates and renewable integration policy trajectories. Forecast inputs included Suruhanjaya Tenaga approval timeline distributions and Green Building Index mandate phase-in schedules.
Material uncertainties — copper and rare earth commodity volatility, cross-border semiconductor logistics disruptions, and grid interconnection queue extensions — sit outside the modeled envelope. Forecasts reflect documented assumptions about policy continuity and hyperscale demand concentration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
China Data Center Server Market
Data Center Infrastructure
US Multi-Tenant (Colocation) Data Center Market
Data Center Infrastructure
United States Data Center Power Market
Data Center Infrastructure
United Arab Emirates Data Center Physical Security Market
Data Center Infrastructure
Data Center Modeling and Simulation Tools Market
Data Center Infrastructure
North America Data Center Power Market
Data Center Infrastructure
Mexico Data Center Rack Market
Data Center Infrastructure
Spain Data Center Physical Security Market
Data Center Infrastructure
Asia-Pacific Hyperscale Data Center Market
Data Center Infrastructure
Norway Data Center Storage Market
Data Center Infrastructure
UAE Data Center Construction Market
Data Center Infrastructure
Philippines Data Center Physical Security Market
Data Center Infrastructure
GCC Data Center Market
Data Center Infrastructure
Malaysia Data Center Server Market
Data Center Infrastructure
Advanced Data Center Infrastructure Market
Data Center Infrastructure
Converged Infrastructure Management Market