
 Makeup Remover Pen Market | 2026-2036
Makeup Remover Pen Market Size, Share, and Industry Trends Forecast 2026-2036
Makeup Remover Pen Market Foresight
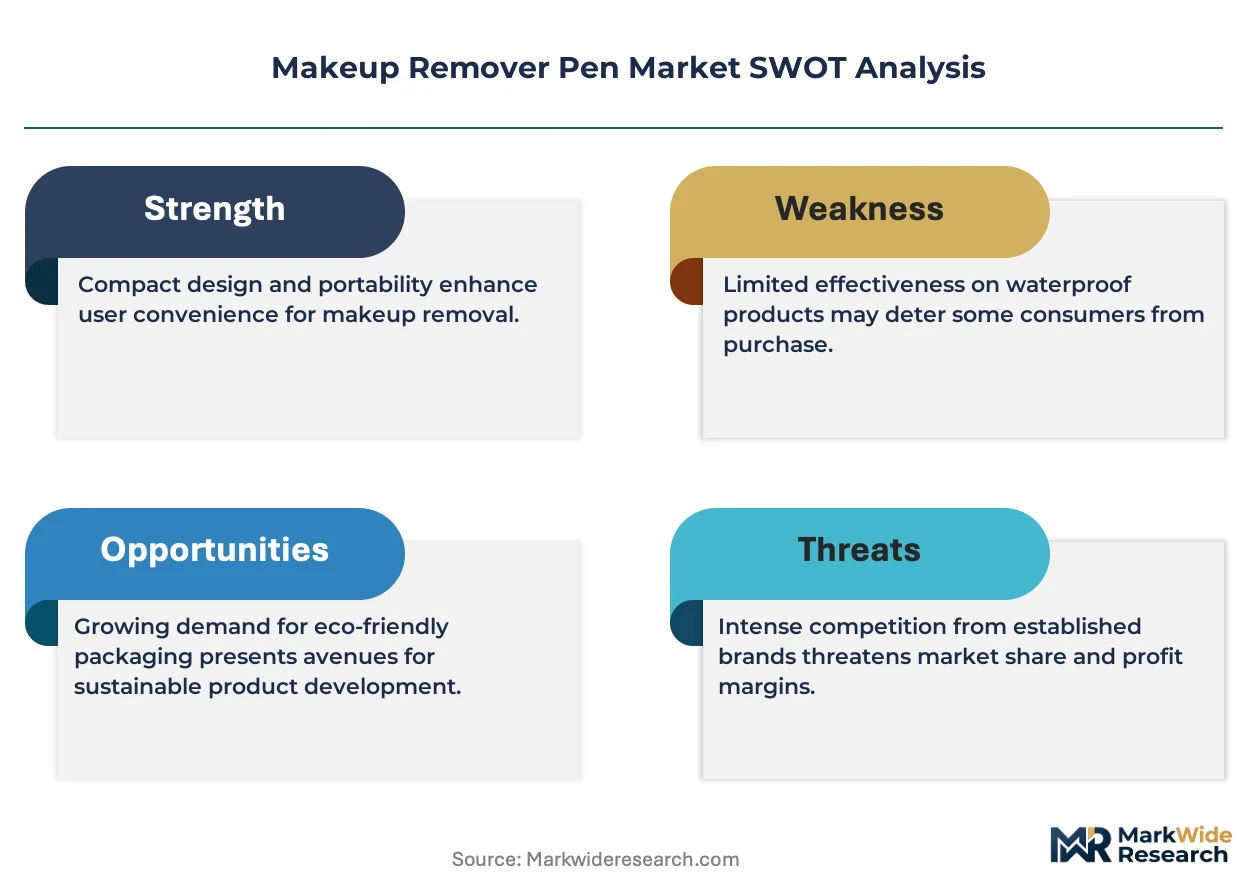
Professional salon and film-studio demand is shifting toward precision-format removers as makeup artists replace cotton swabs and bottled liquids with portable pen applicators. L'Oréal S.A. leverages its professional-division distribution network to dominate salon-channel placement. Shiseido Company anchors its position through advanced emulsion chemistry developed in its Tokyo laboratories. Colorbar Cosmetics competes aggressively on price in emerging Asian markets.
A makeup remover pen is a portable, pen-shaped cosmetic applicator containing pre-loaded solvent or emulsion formulation, typically dispensed through a felt or foam tip with a click mechanism or twist base, engineered for targeted removal of eye and lip colorants without skin abrasion. The device serves commercial users requiring portability, hygiene control, and precise application in mobile or high-turnover settings. Liquid formulations lead absolute volume due to faster saturation and broader compatibility with waterproof pigments, though gel formats are gaining share among sensitive-skin positioning strategies. Single-use packs remain marginal in value terms but occupy critical placement in airline amenity kits and hotel toiletry programs.
The US Food and Drug Administration enforces cosmetic labeling requirements under the Federal Food, Drug, and Cosmetic Act, compelling manufacturers to disclose full ingredient lists and allergen warnings that directly shape formulation transparency and consumer trust. The EU's REACH framework and Cosmetics Regulation restrict certain preservatives and mandate safety assessments, elevating compliance costs for exporters targeting European pharmacy and specialty retail channels. South Korea's MFDS maintains stringent standards for quasi-drug cosmetics that influence regional formulation norms. Stakeholders must monitor evolving microplastic bans and clean-beauty certification schemes to anticipate which chemistries will retain market access.
Market Dynamics
The EU Cosmetics Regulation's microplastic restrictions are forcing formulators to rebuild solvent chemistry from molecular foundations, eliminating polyethylene beads and film-forming polymers that once anchored waterproof removal efficacy.
Growth Catalysts
- Film and television production:Professional makeup artists on location shoots demand portable precision tools that eliminate cross-contamination risks between talent. Pen formats replace cotton swabs and open bottles in mobile kit configurations.
- REACH framework compliance:European safety assessments for preservatives elevate transparency standards that premium brands leverage for pharmacy-channel positioning. Clean-beauty certification schemes amplify this regulatory pull.
- Biodegradable felt tips:Plant-derived applicator materials from cellulose and bamboo fiber address disposal concerns in amenity kit programs. Airlines and hotel chains specify these formats in procurement tenders.
Market Restraints
- Petrochemical feedstock volatility:Solvent base stocks including isododecane and cyclopentasiloxane track crude oil derivatives, compressing margin predictability for value-positioned brands.
- Seoul manufacturing cluster concentration:K-beauty contract manufacturers around Seoul control specialized emulsion filling equipment, creating single-source vulnerability for Western brands without captive Korean facilities.
- Waterproof pigment incompatibility:Silicone-heavy long-wear colorants resist water-based pen formulations, limiting efficacy claims and forcing dual-format inventory burdens on retailers.
Strategic Opportunities
- India's pharmacy channel:Urban dermatology clinics and cosmetic surgery centers lack dedicated professional removal tools, presenting first-mover positioning for precision-format entrants.
- Refillable cartridge systems:Twist-base mechanisms with replaceable solvent pods align with circular economy mandates in France and Germany. Premium brands capture recurring revenue streams.
- Quasi-drug cosmetics pathway:South Korea's MFDS framework permits acne-treatment claims for specific remover chemistries, opening clinical positioning beyond basic cleansing.
Industry Challenges
- Emulsion stability expertise:Formulating oil-in-water systems that resist phase separation during temperature cycling requires cosmetic chemists with specialized training, talent that concentrates in Tokyo and Seoul laboratories.
- Microplastic-free certification timelines:Third-party verification for clean-beauty claims extends 14-18 months, delaying product launches behind formulation completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Makeup Remover Pen Market |
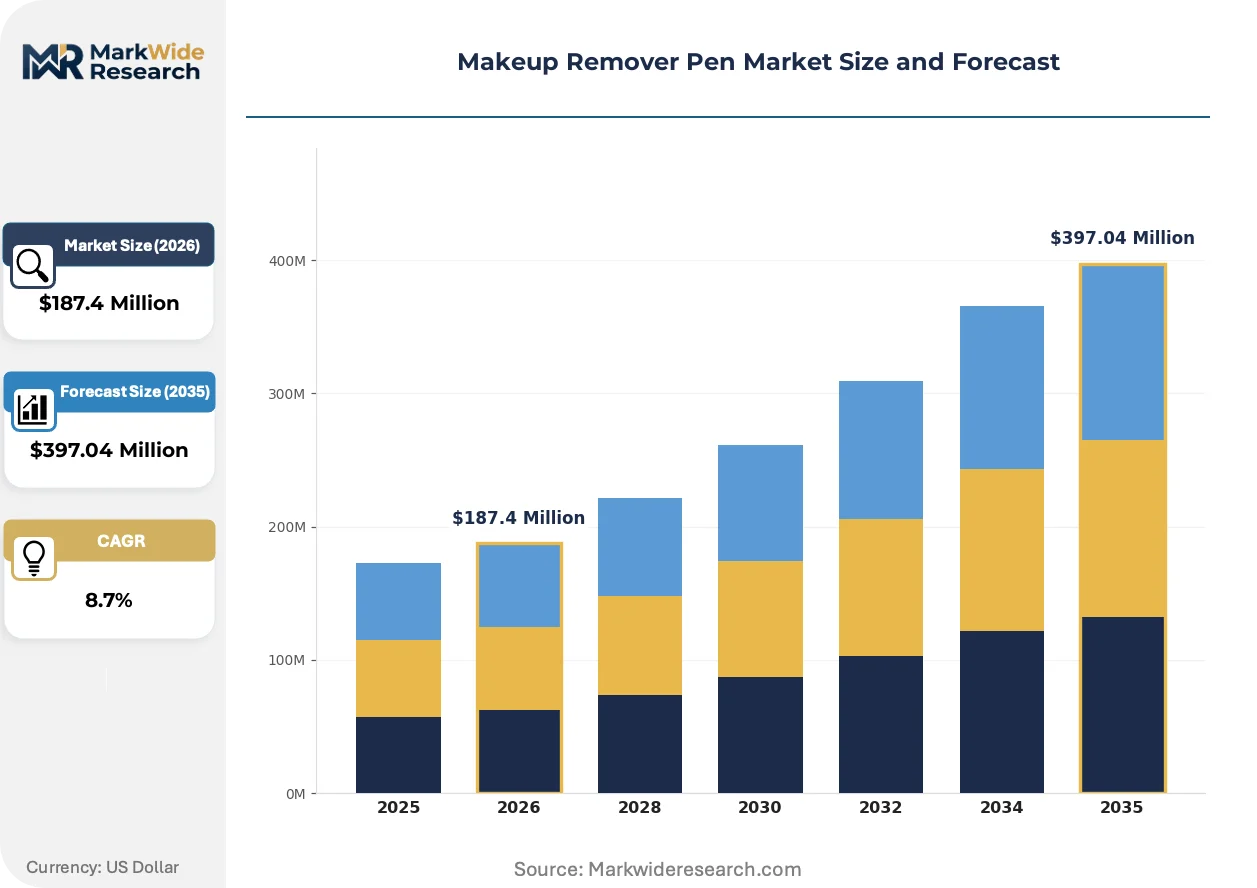
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Wipes, Foam, Gel Application: Personal Use, Professional Use, Travel Size, Sensitive Skin Packaging Type: Tubes, Bottles, Pens, Single-Use Packs Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Revlon, Maybelline Inc, Colorbar Cosmetics, Lashfood Group, L’Oréal S.A, e.l.f, Karadium, Oceane, Shiseido Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Makeup Remover Pen Market Shifts & Advancements
Formulation chemistry and applicator engineering are diverging sharply as regulatory pressure separates compliant from legacy compositions. Three developmental trajectories now define competitive investment priorities.
Cellulose-derived felt tips are expanding into premium product lines as brands eliminate synthetic foam applicators ahead of pending microplastic bans. Professional makeup artists in film production have adopted these formats fastest, demanding biodegradable disposal profiles for location shoots with strict waste protocols. The shift is compressing equipment supplier margins while elevating raw material specifications for tip manufacturers.
REACH microplastic restrictions are eliminating polyethylene film-formers and synthetic glitter carriers from remover formulations, forcing complete solvent base redesigns. Manufacturers must reformulate without compromising waterproof pigment lift efficacy, a technical balance that favors laboratories with advanced emulsion capabilities. European pharmacy channels are responding by consolidating supplier lists around compliant chemistries.
Airline amenity kit procurement now specifies single-use pen formats with compostable packaging, displacing traditional bottled minis in first-class and business cabin programs. Hotel toiletry operators follow this specification, consolidating volume around vendors with certified sustainable supply chains. South Korean contract manufacturers have captured disproportionate share of this conversion through integrated bioplastic molding capabilities.
Makeup Remover Pen Market Segmentation
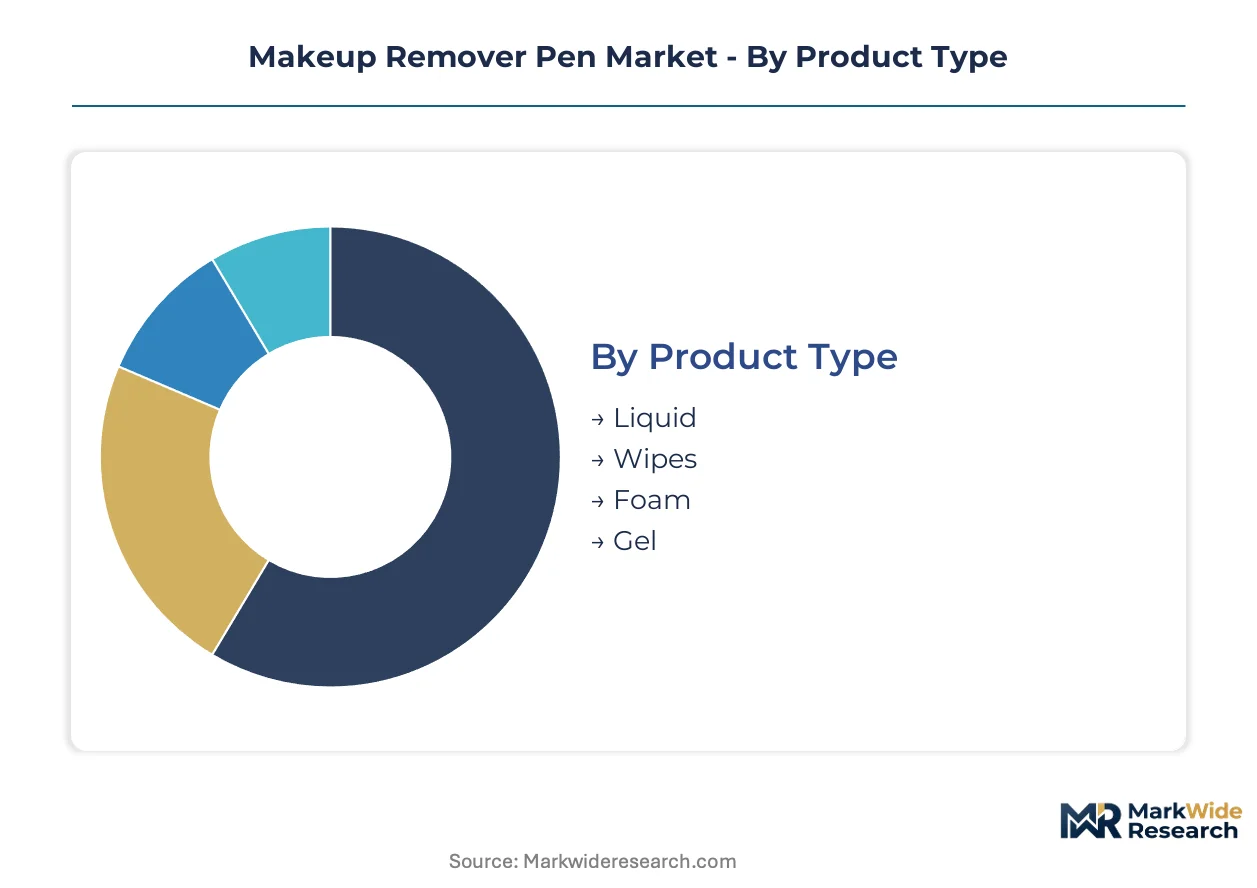
Segmentation in makeup remover pens reveals how formulation chemistry, applicator engineering, and channel access create distinct competitive battlegrounds. Each dimension carries different margin profiles and regulatory exposure, shaping where capital deploys for maximum return.
Product Type:
Supply concentration around solvent chemistry expertise in Tokyo and Seoul laboratories determines which formats command premium positioning versus commodity pricing.
- Liquid:Oil-in-water emulsions with isododecane or cyclopentasiloxane bases saturate felt tips rapidly and lift waterproof pigments efficiently. Film production makeup artists in Los Angeles and London specify liquid pens for location shoots requiring fast turnover between talent. REACH microplastic restrictions are forcing reformulation of film-forming polymers in European-sourced liquids.
- Gel:Thickened aqueous systems suspend mild surfactants in carbomer matrices for reduced drip during vertical application. Demand concentrates in German and French pharmacy channels where dermatologists recommend gel formats for rosacea-prone patients. Clean-beauty certification schemes favor gel positioning for sensitive-skin claims.
- Wipes:Pre-saturated towelettes in pen-shaped dispensers target gym and office use cases.
- Foam:Aerosolized or pump-dispensed mousse formats occupy niche airbrush-makeup removal applications.
Today's leader: Liquid. Tomorrow's challenger: Gel.
Application:
Cost tier separation between professional-grade specifications and mass-market convenience drives portfolio architecture decisions across manufacturers.
- Professional Use:Film and television production crews demand pen formats with replaceable tips, calibrated solvent flow rates, and batch-coded traceability for hygiene audits. Los Angeles-based entertainment industry suppliers specify biodegradable cellulose applicators to comply with studio sustainability mandates. The segment commands 3-4x unit pricing versus personal-use equivalents.
- Personal Use:Mass-market consumers prioritize one-click convenience and travel compliance under TSA liquid restrictions. Online retail channels in the United States and United Kingdom dominate volume, with subscription models capturing recurring revenue.
- Travel Size:Sub-100ml formats engineered for airline amenity kits and hotel toiletry programs.
- Sensitive Skin:Fragrance-free, preservative-minimized formulations targeting eczema and allergy-prone demographics.
Professional Use commands absolute margin dollars. Personal Use delivers volume scale.
Packaging Type:
Volume concentration in South Korean contract manufacturing clusters shapes which formats achieve cost competitiveness at scale.
- Pens:Click-mechanism or twist-base dispensers with felt or foam tips represent the core market definition. Seoul-area manufacturers control specialized emulsion filling equipment for pen formats, creating supply bottlenecks for Western brands without Korean partnerships. Biodegradable tip specifications from airline procurement tenders are accelerating equipment upgrades.
- Single-Use Packs:Individually wrapped sachets or pods target hospitality and aviation sectors with strict hygiene protocols.
- Tubes:Squeeze formats for high-volume salon backbar usage.
- Bottles:Traditional open-vessel packaging declining in professional segments due to contamination risk.
Pen formats dominate value creation. Single-Use Packs expand fastest in hospitality procurement.
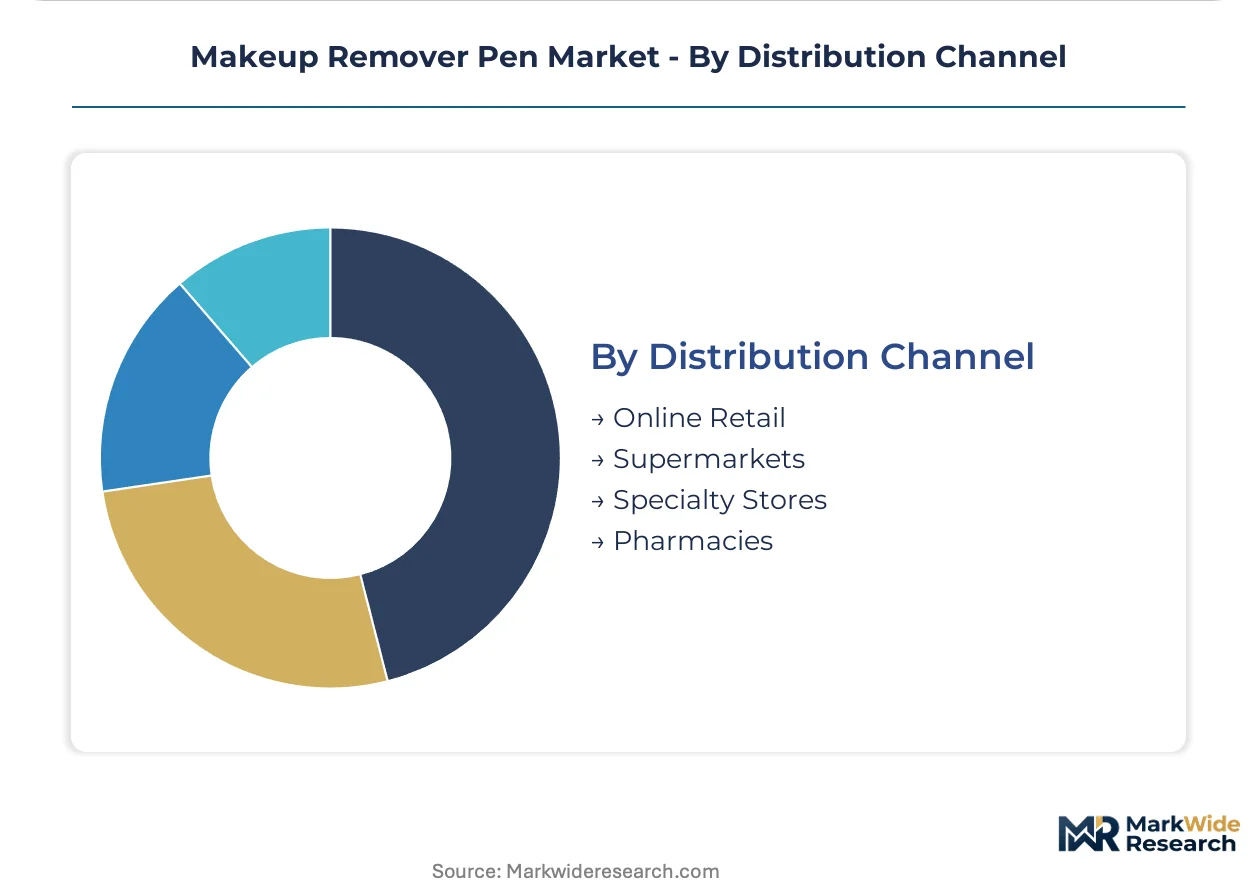
Distribution Channel:
Customer type separation between institutional buyers and individual consumers determines channel investment priorities and working capital requirements.
- Specialty Stores:Sephora, Ulta, and equivalent beauty retailers provide brand-building placement and professional makeup artist endorsement. Staff training programs and in-store demonstration fixtures elevate conversion rates for premium pen formats. The channel captures disproportionate share of refillable cartridge system introductions.
- Pharmacies:European pharmacy chains leverage REACH compliance credentials to position remover pens alongside dermocosmetic skincare. French and German pharmacy procurement favors brands with third-party clean-beauty certification.
- Online Retail:Direct-to-consumer and marketplace platforms dominate personal-use volume with subscription mechanics.
- Supermarkets:Mass-market price positioning with limited SKU depth.
Specialty Stores anchor brand equity. Pharmacies deliver regulatory-validated credibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting formulation chemistry investments toward jurisdictions with aligned compliance costs, as manufacturers seek to avoid dual-track development for microplastic-free portfolios. South Korea's integrated bioplastic molding capabilities and Japan's emulsion expertise attract Western brands seeking single-source compliant production.
United States
Film production makeup artists in Los Angeles drive professional-grade pen demand with strict studio sustainability mandates requiring biodegradable cellulose applicators. FDA cosmetic labeling enforcement under the Federal Food, Drug, and Cosmetic Act elevates formulation transparency requirements for pharmacy-channel entrants. West Coast contract manufacturers are upgrading filling equipment to capture airline amenity kit procurement shifting from bottled minis to single-use pen formats.
Germany
German pharmacy chains leverage REACH framework compliance credentials to position remover pens alongside dermocosmetic skincare for rosacea-prone patients. ECHA microplastic restrictions are eliminating polyethylene film-formers from formulations, forcing complete solvent base redesigns for brands targeting European market access. Frankfurt-area logistics hubs consolidate distribution for refillable cartridge systems aligned with circular economy mandates.
South Korea
Seoul's K-beauty manufacturing cluster controls specialized emulsion filling equipment for pen formats, creating supply bottlenecks for Western brands without Korean partnerships. MFDS quasi-drug cosmetics standards permit acne-treatment claims for specific remover chemistries, opening clinical positioning beyond basic cleansing. Gyeonggi-do bioplastic molding facilities capture disproportionate share of airline and hotel amenity kit conversions.
Japan
Tokyo laboratories anchor advanced oil-in-water emulsion development that resists phase separation during temperature cycling, concentrating scarce cosmetic chemistry talent. METI standards influence regional formulation norms that extend across Asia-Pacific export markets. Osaka-based equipment suppliers are retrofitting production lines for plant-derived felt tip specifications demanded by professional makeup artists.
India
Urban dermatology clinics and cosmetic surgery centers in Mumbai and Delhi lack dedicated professional removal tools, presenting first-mover positioning for precision-format entrants. CDSCO cosmetic regulations are tightening preservative disclosure requirements that favor transparent formulation portfolios. Maharashtra-based contract manufacturers are investing in pen-format filling capacity to serve domestic pharmacy channel growth.
Makeup Remover Pen Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents extend from core cosmetics into precision-format removal tools. The vendor base spans multinational conglomerates with professional-division distribution networks, mid-cap specialists with regional emulsion expertise, and emerging challengers competing on price in high-growth Asian markets. Three archetypes define positioning: laboratory-driven formulators with captive chemistry capabilities, scale manufacturers leveraging South Korean contract partnerships, and direct-to-consumer disruptors with subscription mechanics. Competitive intensity centers on M&A activity targeting emulsion stability expertise and strategic partnerships with airline amenity kit procurement programs.
Among multinational conglomerates with professional-channel anchoring, L'Oréal S.A. and Shiseido Company exemplify laboratory-driven archetypes with differentiated emulsion capabilities developed in captive European and Japanese facilities. Colorbar Cosmetics occupies a position within the price-competitive challenger tier targeting emerging market volume expansion. These three entities collectively illustrate how geographic clustering of formulation expertise and channel access determine competitive viability across regulatory jurisdictions.
| Leading Market Players |
|---|
| Revlon |
| Maybelline Inc |
| Colorbar Cosmetics |
| Lashfood Group |
| L'Oréal S.A |
| e.l.f |
| Karadium |
| Oceane |
| Shiseido Company |
| Others |
Supply & Pricing Matrix
Clean-beauty certification divergence between pharmacy-grade and mass-market tiers splits both pricing power and supplier qualification requirements across European and Asian manufacturing clusters. Premium brands command 3-4x unit multiples through REACH-validated formulations that lock out value-positioned competitors from German pharmacy chains, while Seoul contract manufacturers absorb volume scale through integrated bioplastic molding capabilities.
Pricing Analysis
Distributor margins in European pharmacy channels absorb the steepest markup layers as REACH compliance documentation passes through wholesale consolidation points. Three-tier pricing structure across premium, standard, and economy levels separates biodegradable cellulose-tip specifications from synthetic foam alternatives, with professional film-studio procurement showing least price sensitivity due to talent liability considerations. Pricing pressure stems from petrochemical feedstock volatility in isododecane and cyclopentasiloxane bases, compressing margin predictability for brands without backward integration into solvent chemistry.
Supply Chain Analysis
Freight cost differentials between air and sea lanes determine whether Western brands source finished pens from Seoul or ship bulk emulsion for local filling. Supply concentration in South Korea, Japan, and Germany shapes raw material access, with isododecane solvents and cellulose felt tips drawing from distinct regional specialties. Single-source vulnerability concentrates around Gyeonggi-do bioplastic molding facilities, where specialized emulsion filling equipment creates bottlenecks for brands lacking Korean partnerships. Distribution runs through Frankfurt logistics hubs for European pharmacy channels and Los Angeles entertainment-industry suppliers for professional-grade procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where professional makeup artists in film production have shifted demand toward precision-format specifications with batch-coded traceability and biodegradable disposal profiles.
For Market Incumbents: Cement pharmacy-channel positioning through accelerated REACH microplastic compliance documentation ahead of third-party certification timelines that extend 14-18 months. Deepen captive emulsion capabilities in Tokyo or Seoul laboratories to defend against contract manufacturer margin capture, while locking airline amenity kit procurement through compostable packaging specifications that displace bottled minis.
For New Entrants and Emerging Players: The gap between premium professional-grade pens and economy personal-use formats offers white-space positioning for mid-tier entrants targeting Indian dermatology clinics and cosmetic surgery centers in Mumbai and Delhi. Capture share through refillable cartridge systems aligned with French and German circular economy mandates, leveraging domestic Maharashtra-based filling capacity to bypass Seoul supply bottlenecks.
For Investors and Strategic Acquirers: Asymmetric upside sits with laboratory-driven formulators possessing captive oil-in-water emulsion expertise that resists phase separation during temperature cycling. Long-term viability hinges on acquisition targets with integrated bioplastic molding capabilities and existing airline procurement relationships, with the inflection signal being MFDS quasi-drug cosmetics approvals that permit acne-treatment claims beyond basic cleansing.
| Strategic Initiative | Industry Significance |
|---|---|
| Refillable Cartridge System Launch | Captures recurring revenue streams under French and German circular economy mandates. |
| Biodegradable Tip Specification Upgrade | Secures airline and hotel amenity kit procurement tenders with compostable packaging. |
| Quasi-Drug Cosmetics Pathway Pursuit | Opens clinical positioning through MFDS acne-treatment claims beyond basic cleansing. |
| Backward Integration into Solvent Chemistry | Defends margin predictability against isododecane and cyclopentasiloxane feedstock volatility. |
| Professional Channel Distribution Lock | Leverages L'Oréal and Shiseido salon-network anchoring against emerging price competitors. |
Research Methodology
Direct dialogue with cosmetic chemists at Tokyo and Seoul laboratories, professional makeup artists in Los Angeles film production, European pharmacy procurement managers, and airline amenity kit sourcing directors grounded qualitative findings in operational reality. Secondary validation drew from FDA cosmetic labeling enforcement records, ECHA REACH microplastic restriction filings, MFDS quasi-drug cosmetics registrations, and South Korean customs data on bioplastic molding equipment imports. Bottom-up and top-down triangulation cross-checked volume assumptions across these sources.
Top-down macroeconomic drivers and bottom-up segment-specific demand curves converged in the analytical framework. Segmentation dimensions modeled include formulation chemistry, applicator engineering, end-use application, and distribution channel access, with regional regulatory clusters treated as distinct demand environments. CAGRs were derived from trend extrapolation anchored in disclosed professional procurement volumes and pharmacy-channel inventory turns, with waterproof pigment incompatibility constraints and emulsion stability expertise scarcity serving as industry-specific forecast inputs across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for silicone-free solvent chemistry would alter the outlook if REACH restrictions accelerate beyond polyethylene film-former elimination. Forecasts reflect assumptions about professional segment growth sustainability and K-beauty manufacturing cluster capacity expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Lipstick Market
Cosmetics & Skincare
Skin Care Products Market
Cosmetics & Skincare
Caffeine Eye Creams Market
Cosmetics & Skincare
Qatar Cosmetic Products Market
Cosmetics & Skincare
Scalp Scrub Market
Cosmetics & Skincare
Dark Circles Removing Eye Cream Market
Cosmetics & Skincare
Loose Setting Powder Market
Cosmetics & Skincare
E Commerce Cosmetic and Fragrance Market
Cosmetics & Skincare
Eye Shadow Market
Cosmetics & Skincare
Thailand Skin Care Products Market
Cosmetics & Skincare
Natural and Organic Lipstick Market
Cosmetics & Skincare
Detox Face Oil Market
Cosmetics & Skincare
Night Cream Market
Cosmetics & Skincare
Waterproof Temporary Tattoo Sticker Market
Cosmetics & Skincare
Microbiome Cosmetic Products Market
Cosmetics & Skincare
Makeup Setting Powder Market