
 Luxury Fabric Market | 2026-2036
Luxury Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Fabric Market Analytics
Organic cotton and regenerated cellulosic fibers is rebalancing cost structures across premium textile tiers. Ermenegildo Zegna N.V. anchors its competitive stance through vertical control over Australian merino wool sourcing. LVMH Moët Hennessy Louis Vuitton leverages captive ateliers in France to sustain artisanal finishing techniques. Pierre Frey competes on archival pattern revival combined with digital weaving integration.
Luxury fabric denotes textile substrates engineered to exceed 80 threads per centimeter in warp density, utilizing natural protein fibers or rare cellulosic bases for apparel, upholstery, and decorative applications requiring tactile distinction and dimensional stability. Satin and silk categories dominate current margin pools due to bridal and haute couture offtake, while velvet is accelerating fastest among interior decorators specifying acoustic-dampening wall treatments. Cashmere occupies a mature niche where supply scarcity from Mongolian herding cooperatives limits volume expansion regardless of price elasticity.
EU REACH restrictions on azo dyes and perfluorinated compounds constrain chemical finishing options for European mills, while China's MEE enforces wastewater discharge thresholds that raise compliance costs in Zhejiang and Jiangsu production zones. ISO 14001 environmental management certification increasingly gates supplier eligibility for luxury fashion houses operating across multiple jurisdictions. Stakeholders must monitor how biodegradability mandates from France's AGEC law and emerging digital product passport requirements reshape material specification protocols and supplier qualification timelines.
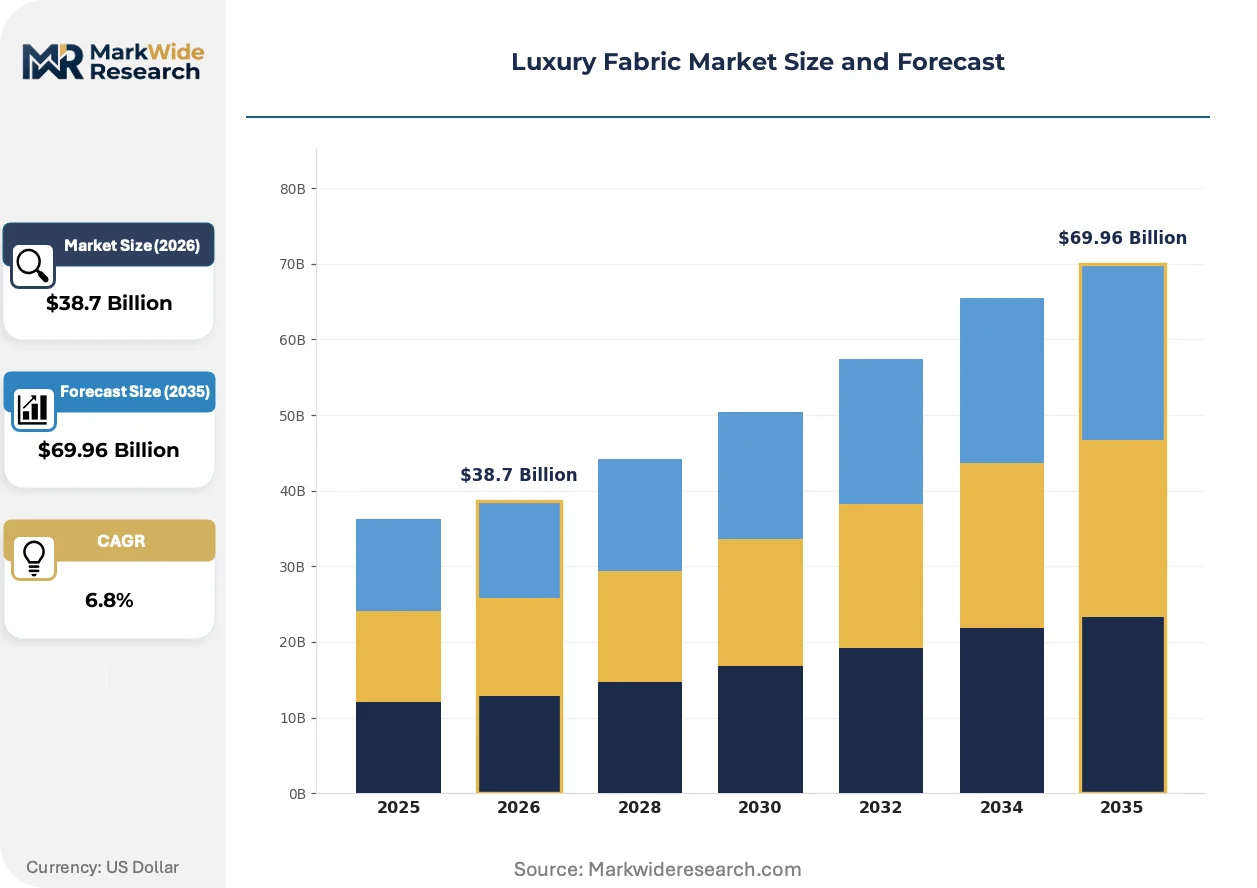
Market Dynamics
REACH compliance and China's dual carbon goals are compressing chemical finishing options while concentrating supply in heritage silk districts, forcing mills to absorb compliance costs or exit premium tiers entirely.
Growth Catalysts
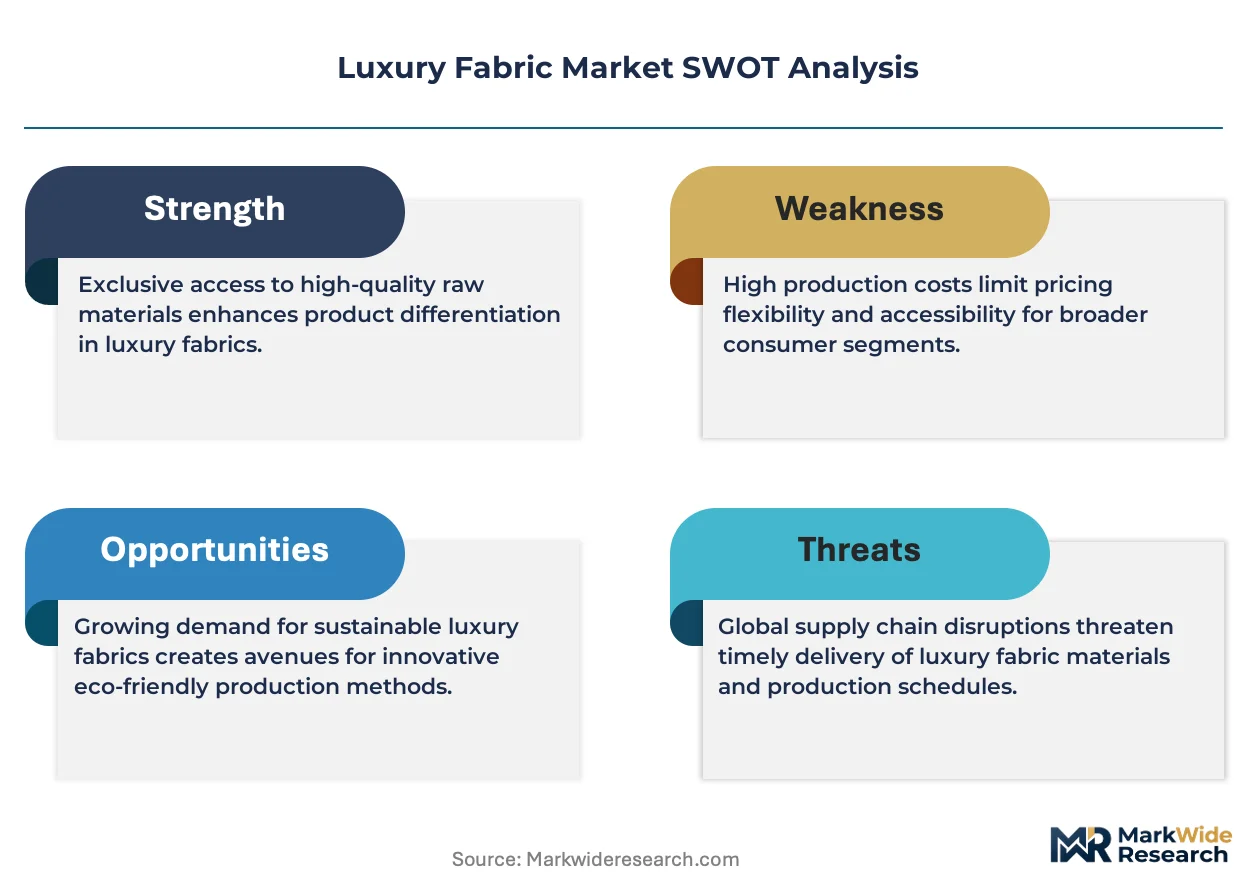
- Heritage cluster consolidation:Italy's Como silk district and India's Varanasi weaving cluster are capturing specification share from dispersed suppliers through authenticated provenance systems.
- EU Green Deal alignment:France's AGEC law mandates biodegradability disclosures that favor natural protein fibers over synthetic alternatives in bridal and haute couture procurement.
- Acoustic performance specification:Interior decorators in certified sustainable velvets are specifying wall treatments that dampen sound for luxury hospitality and residential projects.
Market Restraints
- Mongolian cashmere scarcity:Herding cooperative output limits remain fixed regardless of price elasticity, capping volume expansion in the mature cashmere tier.
- Input cost volatility:Australian merino wool auction prices fluctuate with climate-driven fleece quality variation, destabilizing cost structures for worsted producers.
- REACH azo dye restrictions:ECHA limitations on perfluorinated compounds eliminate legacy finishing chemistries without fully scaled replacements.
Strategic Opportunities
- Digital product passport integration:EU textile traceability mandates create first-mover advantage for mills that embed blockchain-linked fiber provenance before 2027 enforcement.
- Regenerated cellulosic fiber substitution:TENCEL and modal blends offer cost repositioning in premium tiers previously reserved for silk and fine wool.
- Atelier-direct channel expansion:Captive finishing workshops in France bypass wholesale margin extraction for couture houses seeking artisanal control.
Industry Challenges
- ISO 14001 certification timelines:Environmental management system audits gate supplier eligibility for multi-jurisdiction luxury houses, stretching qualification cycles.
- Artisan skill attrition:Jacquard weaving and hand-finishing competencies concentrate in aging workforces across European and South Asian heritage centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Fabric Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fabric Type: Satin, Velvet, Silk, Cashmere End User: Fashion Designers, Upholsterers, Retailers, Interior Decorators Manufacturing Process: Spinning, Weaving, Dyeing, Finishing Design Style: Modern, Classic, Bohemian, Minimalist |
| Companies Covered | Jim Thompson Fabrics, Pierre Frey, Sanderson Design Group, The Romo Group, Kravet Inc., Sattler Group, Perennials and Sutherland L.L.C., LVMH Moët Hennessy Louis Vuitton, Ermenegildo Zegna N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Fabric Market Evolving Landscape
Digital weaving integration and biomaterial substitution are compressing traditional craft timelines while regulatory traceability mandates restructure supplier qualification protocols across European and Asian production zones.
Digital jacquard looms equipped with CAD-driven pattern libraries are absorbing hand-drawn design workflows previously executed by master draftsmen in Como and Lyon ateliers. Bridal houses and haute couture studios are adopting these systems to compress sampling cycles from weeks to days. This absorption of manual processes is compressing employment in heritage drafting roles while expanding output capacity for complex archival revivals.
France's AGEC law and emerging EU digital product passport requirements are mandating fiber-level traceability disclosures that extend upstream to raw material origins. Mills in Zhejiang and Jiangsu face MEE wastewater discharge thresholds that compound compliance burdens alongside European chemical restrictions. The silk and velvet categories face the steepest adaptation costs due to multi-stage dyeing and finishing intensity.
Certification-driven specification is displacing tactile-only procurement criteria among North American interior decorators and European fashion houses. ISO 14001 and OEKO-TEX credentials now gate entry to vendor pools previously accessible through relationship-based sourcing. This shift is most visible in Italy's upholstery fabric segment, where architects specify wall coverings exclusively from audited supply chains.
Luxury Fabric Market Segmentation
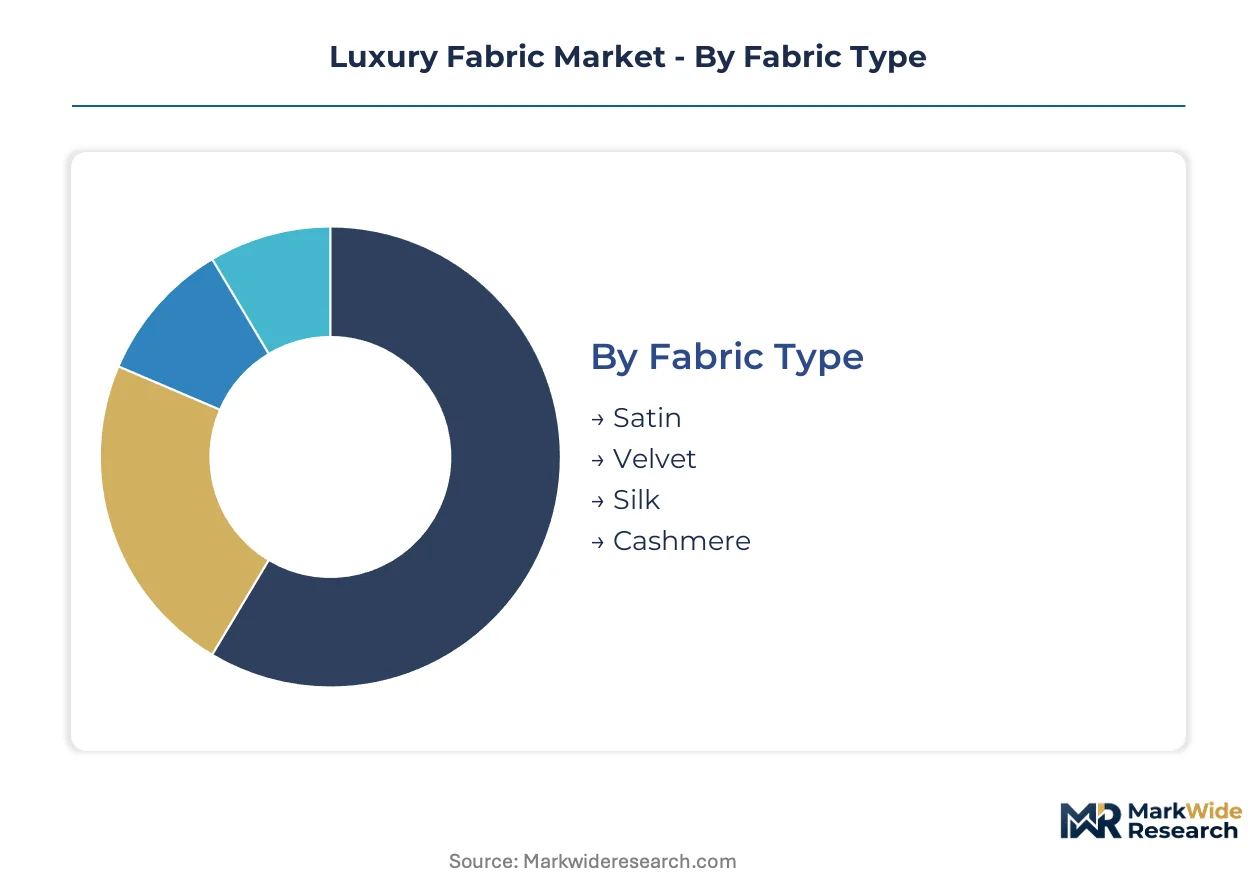
Segmentation in luxury fabrics reveals how capital allocation, regulatory exposure, and artisan skill concentration vary across production methods and customer channels. Procurement patterns diverge sharply between fashion houses prioritizing fiber provenance and interior specialists demanding acoustic performance certification.
Fabric Type:
Silk and velvet installations demand the heaviest upfront capital for multi-stage dyeing equipment and MEE-compliant wastewater systems, while cashmere processing requires lower fixed investment but faces binding supply constraints.
- Silk:Natural protein fiber woven above 80 warp threads per centimeter for bridal and haute couture applications. Como district mills capture specification share through authenticated provenance systems as France's AGEC law mandates biodegradability disclosures favoring natural fibers.
- Velvet:Dense pile construction utilizing cut or uncut loops for acoustic-dampening wall treatments. North American interior decorators are expanding procurement of certified sustainable velvets for luxury hospitality projects requiring sound absorption performance.
- Satin:Warp-faced weave with minimal interlacing points producing characteristic luster. High thread-count specifications dominate margin pools in formalwear segments.
- Cashmere:Down fiber from Mongolian herding cooperatives with fixed output limits regardless of price elasticity. Mature niche constrained by supply scarcity rather than production capacity.
Most installed capacity flows through silk. Expansion is steepest in velvet.
End User:
Customer type determines specification complexity, with fashion designers driving archival pattern revivals and interior decorators imposing acoustic and sustainability certifications.
- Fashion Designers:Haute couture and bridal houses specifying fiber-level traceability through digital product passport integration. LVMH captive ateliers in France sustain artisanal finishing techniques bypassing wholesale margin extraction.
- Interior Decorators:Certified sustainable velvet procurement for acoustic-dampening wall treatments in luxury hospitality and residential projects. ISO 14001 credentials now gate vendor pool entry previously accessible through relationship-based sourcing.
- Upholsterers:Volume buyers of velvet and satin for furniture applications with shorter qualification cycles than certified architectural specifications.
- Retailers:Multi-brand distributors bridging heritage mills and end consumers with inventory risk concentrated in seasonal bridal demand.
Specification authority concentrates with interior decorators. Volume throughput peaks with upholsterers.
Manufacturing Process:
Process stage determines regulatory exposure intensity, with dyeing and finishing facing REACH azo dye restrictions and China's MEE wastewater thresholds.
- Dyeing:Multi-stage color fixation for silk and velvet categories facing steepest adaptation costs from ECHA limitations on perfluorinated compounds without fully scaled replacements.
- Finishing:Chemical and mechanical surface treatments for dimensional stability and tactile distinction. EU Green Deal alignment compresses legacy finishing chemistries while biodegradable alternatives scale.
- Weaving:Digital jacquard looms with CAD-driven pattern libraries absorbing hand-drawn workflows previously executed by master draftsmen in Como and Lyon ateliers.
- Spinning:Fiber preparation for worsted and woolen systems with Australian merino wool auction price volatility destabilizing cost structures.
Compliance burden concentrates in dyeing. Automation penetration is deepest in weaving.
Design Style:
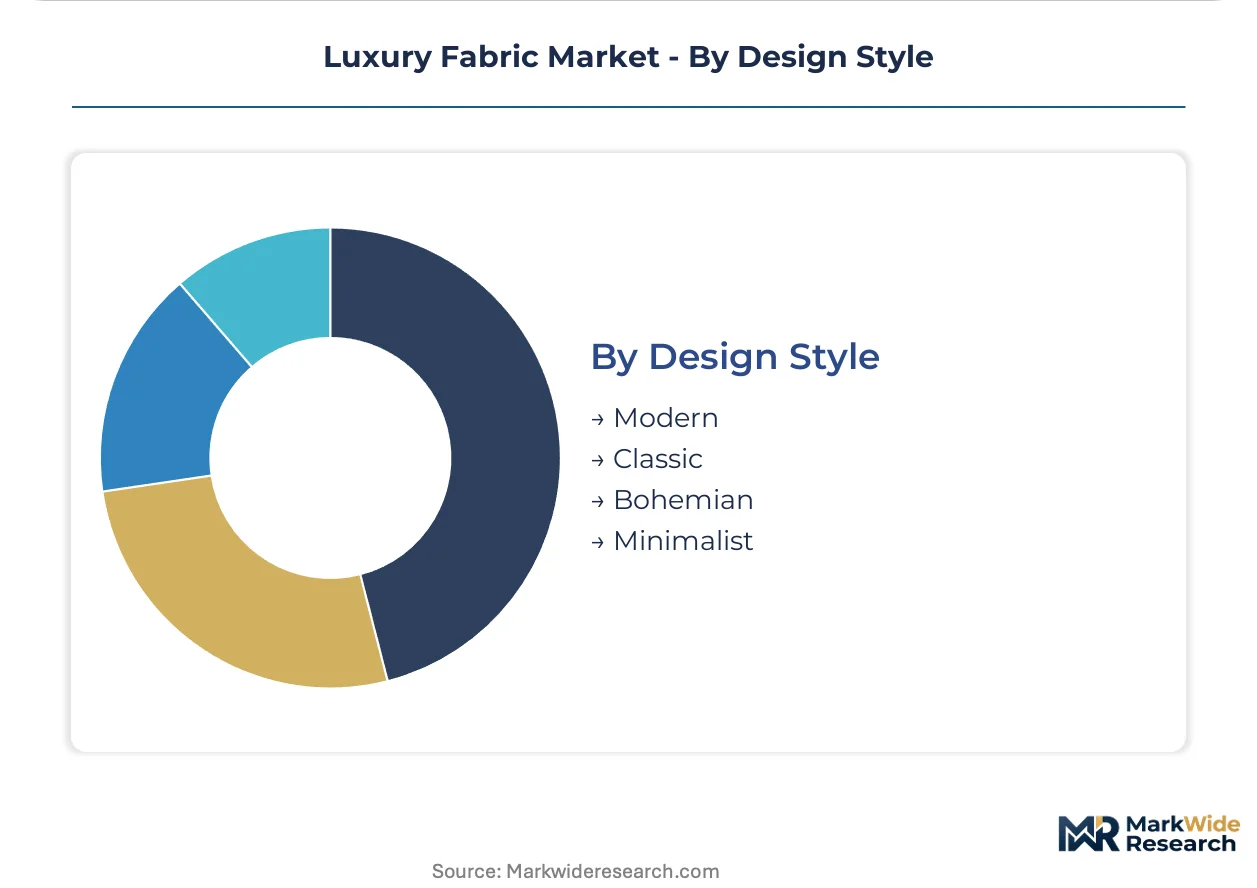
Aesthetic positioning determines archival revival frequency versus digital-native production, with classic and modern styles diverging in pattern library investment.
- Classic:Archival pattern revivals from heritage mill libraries requiring digital weaving integration to compress sampling cycles from weeks to days.
- Modern:CAD-native designs with shorter development timelines and lower artisan dependency as Jacquard weaving competencies concentrate in aging workforces.
- Minimalist:Reduced pattern complexity favoring substrate quality and fiber provenance disclosure over visual ornamentation.
- Bohemian:Hand-finished irregularities and artisanal variation commanding premium positioning in boutique retail channels.
Pattern investment concentrates in classic. Speed-to-market advantage sits with modern.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's Como silk district anchors production gravity for luxury fabric manufacturing, with heritage mills leveraging authenticated provenance systems to capture specification share from dispersed suppliers across bridal and haute couture segments.
Italy
Como district mills supply authenticated silk to European fashion houses responding to France's AGEC law biodegradability mandates. REACH compliance through ECHA restricts azo dyes and perfluorinated compounds, forcing dyeing adaptation. Digital jacquard looms in Lombardy compress sampling cycles from weeks to days.
France
Haute couture ateliers in Paris sustain artisanal finishing techniques through captive production bypassing wholesale margin extraction. AGEC law mandates fiber-level traceability disclosures favoring natural protein fibers. Lyon-based heritage mills integrate CAD-driven pattern libraries for archival revivals.
China
Zhejiang and Jiangsu production zones face MEE wastewater discharge thresholds raising compliance costs for multi-stage dyeing operations. Dual carbon goals tighten energy intensity standards across finishing facilities. Shanghai-based procurement offices coordinate specification compliance for export markets.
India
Varanasi weaving cluster concentrates handloom silk production for bridal export markets requiring ISO 14001 certification. BIS standards govern textile quality marking for domestic premium positioning. Maharashtra-based finishers invest in effluent treatment to meet international buyer qualification timelines.
United States
Interior decorators in New York and California expand certified sustainable velvet procurement for acoustic-dampening hospitality projects. EPA regulations on textile chemical discharge influence import sourcing criteria. High-end residential architects specify wall coverings exclusively from audited European supply chains.
Luxury Fabric Market Competitive Landscape
Global majors compete with regional champions across heritage craftsmanship and digital integration dimensions, producing a tiered structure where vertically integrated European houses face specialized Asian silk traders and North American upholstery distributors. Three archetypes dominate: captive atelier operators controlling in-house finishing, heritage mill owners leveraging archival pattern libraries, and certified sustainable specialists qualifying for ISO 14001-gated vendor pools. Competitive moves concentrate on backward integration into fiber sourcing and blockchain-linked provenance systems ahead of EU digital product passport enforcement.
Within the captive atelier tier, LVMH Moët Hennessy Louis Vuitton and Ermenegildo Zegna N.V. exemplify upstream control over artisanal finishing workflows, while Pierre Frey occupies a position bridging heritage pattern revival with digital weaving integration.
| Leading Market Players |
|---|
| Jim Thompson Fabrics |
| Pierre Frey |
| Sanderson Design Group |
| The Romo Group |
| Kravet Inc. |
| Sattler Group |
| Perennials and Sutherland L.L.C. |
| LVMH Moët Hennessy Louis Vuitton |
| Ermenegildo Zegna N.V. |
| Others |
Value Network & Pricing Analysis
European haute couture houses and North American interior decorators concentrate specification authority for certified sustainable silks and velvets, anchoring a three-tier pricing structure across premium, standard, and economy levels that reflects fiber provenance authentication and compliance certification depth.
Pricing Analysis
Australian merino wool auction volatility and REACH-compliant dyeing cost absorption drive input-cost pass-through into finished fabric pricing. Price differentiation hinges on ISO 14001 certification tier and fiber traceability depth via blockchain-linked provenance systems. Cost compression in mid-tier cellulosic alternatives is intensifying because TENCEL and modal blends reposition against heritage silk. Upholsterers exhibit highest price sensitivity due to volume procurement cycles, while bridal houses show lowest elasticity for authenticated Como silk.
Supply Chain Analysis
Regional distribution centers in Milan, Paris, and Shanghai coordinate hub-and-spoke patterns for finished fabric delivery to ateliers and decorators. Supply concentrates in Italy's Como district, India's Varanasi cluster, and China's Zhejiang province. Raw material dependencies draw from Mongolian cashmere cooperatives, Australian merino auctions, and cultivated silk farms in Jiangsu. Single-source vulnerability in Mongolian herding cooperative output constrains cashmere tier expansion. Distribution runs through captive atelier networks for couture houses and certified wholesale channels for interior specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where France's AGEC law biodegradability mandates and EU digital product passport requirements are restructuring supplier qualification protocols and procurement criteria across European and North American demand centers.
For Market Incumbents: Anticipate margin compression from regenerated cellulosic fiber substitution by securing backward integration into Australian merino wool sourcing and embedding blockchain traceability ahead of enforcement timelines. Defensive consolidation through ISO 14001 certification investment gates competitor entry into LVMH and Zegna-tier vendor pools. Heritage mills must compress sampling cycles via digital jacquard loom deployment to offset artisan skill attrition in Como and Lyon ateliers.
For New Entrants and Emerging Players: Begin with certified sustainable velvet production for North American acoustic-dampening hospitality projects, where ISO 14001 credentials now gate vendor access previously reachable through relationship-based channels. Target Maharashtra-based finishers investing in effluent treatment for international buyer qualification as the most penetrable supply node. Pursue atelier-direct channel partnerships with boutique bridal houses seeking shorter lead times than heritage mill queues.
For Investors and Strategic Acquirers: Luxury fashion conglomerates with captive finishing infrastructure are the most active acquirers in this space, consolidating heritage mills to secure archival pattern libraries and authenticated provenance systems. Long-term viability over the next decade rests on digital product passport compliance capability and fiber-level traceability infrastructure. Watch for ECHA enforcement actions on perfluorinated compound replacements as the inflection signal for dyeing technology winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Linked Provenance Integration | EU digital product passport mandates reward first-mover mills embedding fiber traceability before enforcement. |
| Regenerated Cellulosic Fiber Scale-Up | TENCEL and modal blend expansion repositions premium tiers against silk-dependent cost structures. |
| Captive Atelier Network Expansion | LVMH-style in-house finishing bypasses wholesale margin extraction for couture quality control. |
| ISO 14001 Certification Acceleration | Environmental management credentials now gate supplier eligibility for multi-jurisdiction luxury houses. |
| Digital Jacquard Loom Deployment | CAD-driven pattern libraries compress sampling cycles from weeks to days in Como and Lyon. |
Research Methodology
Bottom-up interior decorator and fashion house procurement modeling reconciled against top-down heritage mill capacity tracking forms the analytical core of this study. Primary interviews with textile mill owners, haute couture atelier managers, interior design specification directors, and dyeing equipment suppliers combined with secondary validation against REACH enforcement databases, BIS textile quality markings, and MEE wastewater discharge records. Trade flow analysis across Italian, Indian, and Chinese customs data triangulates production volume claims against downstream offtake patterns.
Historical trendline analysis of silk, velvet, and cashmere price indices across Australian wool auction reports and Mongolian cooperative output disclosures informs projection baselines. Segmentation modeling spans fabric type, end-user archetype, manufacturing process stage, and design style aesthetic across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating France's AGEC law implementation pace and EU digital product passport technical specification evolution. Climate-driven fleece quality variation and herding cooperative output constraints factor as supply-side boundary conditions.
Several conditions sit outside the modeled scope, including geopolitical disruption to Mongolian cashmere export routes and accelerated synthetic fiber biodegradability breakthroughs. Forecasts reflect documented assumptions around regulatory enforcement timing and certification adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textiles
High Temperature Fabric Market
Textiles
South Korea Textile Market
Textiles
Percussion Vests Market
Textiles
Equestrian Apparel Market
Textiles
Saddle Stitching Machine Market
Textiles
Knitted Fabric Market
Textiles
Russia Home Textile Market
Textiles
Textile Mill Electric Drives Market
Textiles
Sun Protective Clothing Market
Textiles
Nonwoven Flanging Market
Textiles
Disposable Garment Bags Market
Textiles
Textile Winding Machine Market
Textiles
Cationic Dyes Market
Textiles
Active Smart Textiles Market
Textiles
Carbon Fiber Strands Market
Textiles
Organic Textile Market