
 Lossless Music Streaming Services Market | 2026-2036
Lossless Music Streaming Services Market Size, Share, and Industry Trends Forecast 2026-2036
Lossless Music Streaming Services Market Insights
Hi-resolution audio tier migration is collapsing the boundary between studio-master fidelity and mass-market accessibility. Tidal leverages exclusive MQA catalog depth to anchor its audiophile subscriber base. Qobuz sustains European market presence through classical and jazz specialization. Apple Music competes via spatial audio integration with proprietary hardware ecosystems.
Lossless music streaming services deliver uncompressed or minimally compressed digital audio at bit depths and sample rates matching or exceeding CD quality, typically 16-bit/44.1 kHz FLAC or 24-bit/96 kHz high-resolution formats, preserving full dynamic range for critical listening environments. The primary commercial purpose centers on subscription monetization of perceptibly superior sound reproduction against commodity MP3 and AAC offerings. Subscription service type captures the dominant revenue pool through recurring billing predictability, while high-resolution audio content type commands premium pricing tiers against standard lossless catalogs. Device compatibility segmentation shows home audio systems generating disproportionate per-user value despite smaller installed bases versus smartphone-dominant volume.
FCC broadband labeling rules in the United States mandate transparent speed disclosures that shape consumer expectations for uninterrupted 24-bit streaming throughput. EU Digital Services Act content moderation obligations intersect with music licensing transparency demands across EMA-member jurisdictions. Japan's METI guides hi-res audio certification standards that filter market access for platform providers. Stakeholders must monitor codec royalty structures and carrier zero-rating negotiations as these determine effective cost-to-consumer for bandwidth-intensive streams.
Market Dynamics
The migration from lossy compression to hi-resolution streaming is compressing hardware upgrade cycles and forcing platform differentiation around codec ecosystems rather than catalog size alone.
Growth Catalysts
- Net neutrality enforcement:Germany's Federal Network Agency mandates equal bitrate delivery, preventing carrier throttling of high-bandwidth audio streams and preserving quality consistency for subscribers.
- Hi-res hardware penetration:Japan's metropolitan markets sustain deepest adoption of 24-bit/192kHz-capable DACs and headphone amplifiers, creating installed bases that monetize premium tiers.
- FLAC encoding standardization:Universal container compatibility across Android, iOS, and embedded automotive systems removes friction from cross-device listening workflows.
Market Restraints
- Bandwidth cost asymmetry:Mobile carrier data caps in emerging markets impose effective surcharges on lossless streaming versus compressed alternatives, constraining addressable subscriber pools.
- MQA licensing concentration:Proprietary codec royalties concentrate with a single licensor, creating input cost volatility risk for platforms dependent on studio-master authentication.
- Perceptual equivalence threshold:ABX testing demonstrates majority listeners cannot distinguish 320kbps AAC from CD-quality FLAC on consumer earbuds, limiting mass-market conversion.
Strategic Opportunities
- Automotive integration:Premium vehicle cabin acoustics in Germany and Japan create white space for native hi-res streaming apps with steering-wheel voice control.
- Spatial audio convergence:Dolby Atmos and Sony 360 Reality Audio formats merging with lossless catalogs enable immersive tier pricing above standard hi-res subscriptions.
- EU Digital Services Act transparency:Licensing disclosure mandates create regulatory tailwind for artist-centric platforms emphasizing payout visibility as competitive wedge.
Industry Challenges
- Mastering engineer scarcity:Authentic hi-res catalog expansion requires archival tape digitization and remastering expertise concentrated among aging specialists in Tokyo, London, and Nashville.
- Certification timeline compression:Japan's METI hi-res audio certification demands extended validation cycles that delay platform market entry against uncertified competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lossless Music Streaming Services Market |
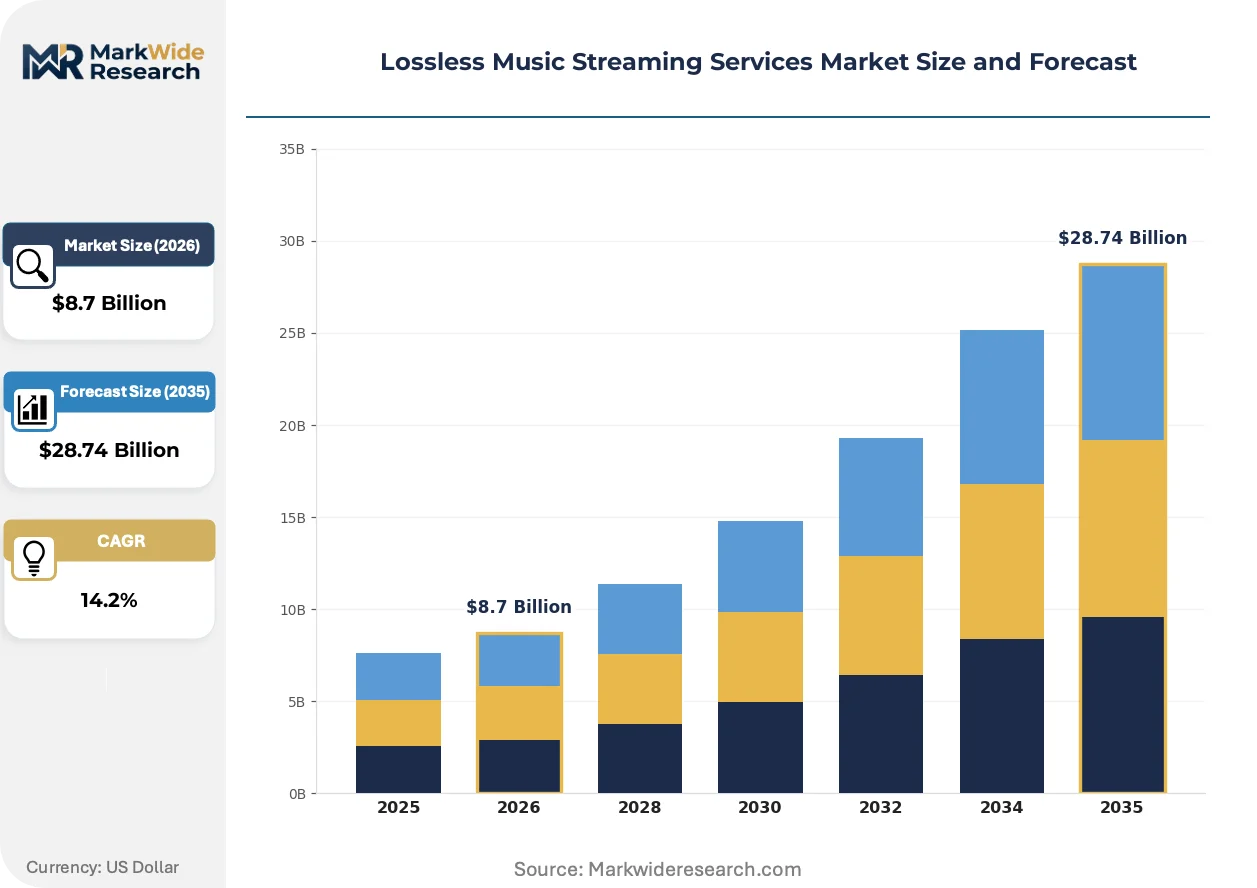
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription, Ad-Supported, Direct Purchase, Bundled Services Pricing Model: Freemium, Tiered Pricing, Pay-Per-Stream, One-Time Payment Content Type: High-Resolution Audio, Classical, Rock, Jazz Device Compatibility: Smartphones, Tablets, Laptops, Home Audio Systems |
| Companies Covered | Qobuz, YouTube Music Premium, Spotify, SoundCloud, Deezer, Apple Music, Amazon Music Unlimited, MusicGremlin, Tidal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lossless Music Streaming Services Market Trends and Innovations
Codec abstraction and hardware-agnostic delivery are dissolving platform lock-in while spatial audio rendering shifts competitive differentiation toward immersive format depth.
FLAC container adoption is decomposing proprietary format moats that previously anchored subscriber retention. Audiophile collectors and critical listeners are migrating catalogs to platform-agnostic local storage at accelerating velocity. This decomposing of walled-garden architecture is compressing switching costs and forcing platforms to compete on editorial curation and exclusive live recordings rather than technical exclusivity.
EU Digital Services Act content moderation obligations are intersecting with music licensing transparency demands across member jurisdictions. Platforms must now disclose algorithmic recommendation weights and content removal rationales alongside royalty flow documentation. Classical and jazz specialists in France, Germany, and the Netherlands face disproportionate compliance burden given complex estate-held recording rights.
Subscription fatigue among digital entertainment consumers is shortening audio service tenure and elevating free-tier conversion friction. Bundled offerings combining lossless music with podcast and audiobook verticals are displacing standalone audio subscriptions in North American and Nordic markets. Japan resists this pattern, where unbundled hi-res purity maintains pricing power among hardware-enthusiast segments.
Lossless Music Streaming Services Market Segmentation
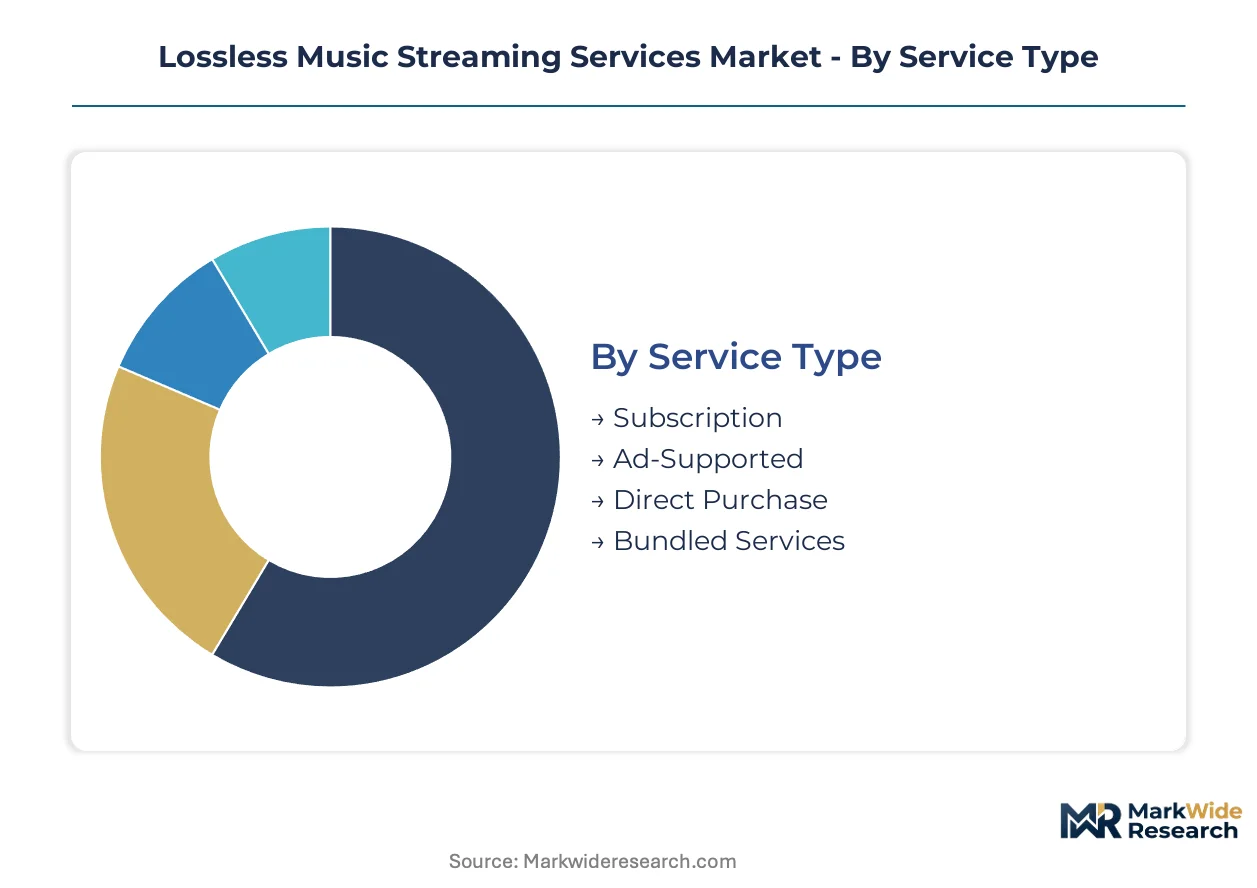
Segmentation in lossless music streaming reveals how platform economics bifurcate between recurring subscription infrastructure and transactional revenue pools. Codec compatibility and hardware integration create divergent margin profiles across service delivery modes.
Service Type:
Subscription services capture the dominant recurring revenue pool through predictable billing cycles and reduced churn versus ad-supported alternatives.
- Subscription:Monthly or annual billing for unlimited lossless catalog access. Germany's BNetzA net neutrality enforcement preserves bitrate consistency for paying subscribers across carrier networks. Recurring revenue concentration here funds exclusive content acquisition and MQA licensing.
- Ad-Supported:Free-tier access with compressed audio quality and intermittent advertising. Mobile data cap constraints in emerging markets limit addressable reach for bandwidth-intensive lossless ad inventory. Revenue per user remains fractional against premium tiers.
- Direct Purchase:Permanent digital ownership of high-resolution album downloads. Japan's METI-certified hi-res catalogs command premium per-unit pricing among audiophile collectors seeking platform-agnostic libraries.
- Bundled Services:Lossless audio packaged with video streaming or telecommunications contracts. Nordic markets show displacement of standalone subscriptions as telecom operators aggregate entertainment verticals.
Subscription holds installed capacity. Bundled Services is rotating up the share rankings.
Pricing Model:
Revenue concentration clusters around tiered structures that extract graduated willingness-to-pay across hardware-enthusiast segments.
- Freemium:Base-tier compressed streaming with lossless upsell prompts. Conversion friction is climbing as subscription fatigue shortens audio service tenure in North American markets.
- Tiered Pricing:Three-level differentiation across standard lossless, high-resolution, and immersive spatial audio. FLAC standardization enables this structure by removing codec compatibility friction across Android and iOS ecosystems.
- Pay-Per-Stream:Micropayment per track for non-subscribers. Bandwidth cost asymmetry in mobile-first markets constrains viability against unlimited subscription alternatives.
- One-Time Payment:Lifetime access or prepaid annual blocks. Japan's hardware-enthusiast segments sustain demand for unbundled purity without recurring billing.
Tiered Pricing anchors current revenue. Freemium is expanding most quickly as platforms widen top-funnel acquisition.
Content Type:
Catalog specialization creates defensible positioning against commodity streaming through mastering depth and estate-held recording rights.
- High-Resolution Audio:Studio-master fidelity at 24-bit/96kHz or above. Archival tape digitization expertise concentrates among aging specialists in Tokyo, London, and Nashville, constraining authentic catalog expansion velocity.
- Classical:Orchestral and chamber recordings demanding extended dynamic range. EU Digital Services Act transparency mandates impose disproportionate compliance burden given complex estate-held rights across French, German, and Dutch specialists.
- Rock:Back-catalog remasters and live concert recordings. Standardized FLAC containers accelerate migration from physical media collections to streaming libraries.
- Jazz:Improvisational recordings with spatial nuance. Qobuz sustains European market presence through editorial depth in this vertical.
High-Resolution Audio commands premium tier anchoring. Classical is gaining share fastest among discerning subscriber cohorts.
Device Compatibility:
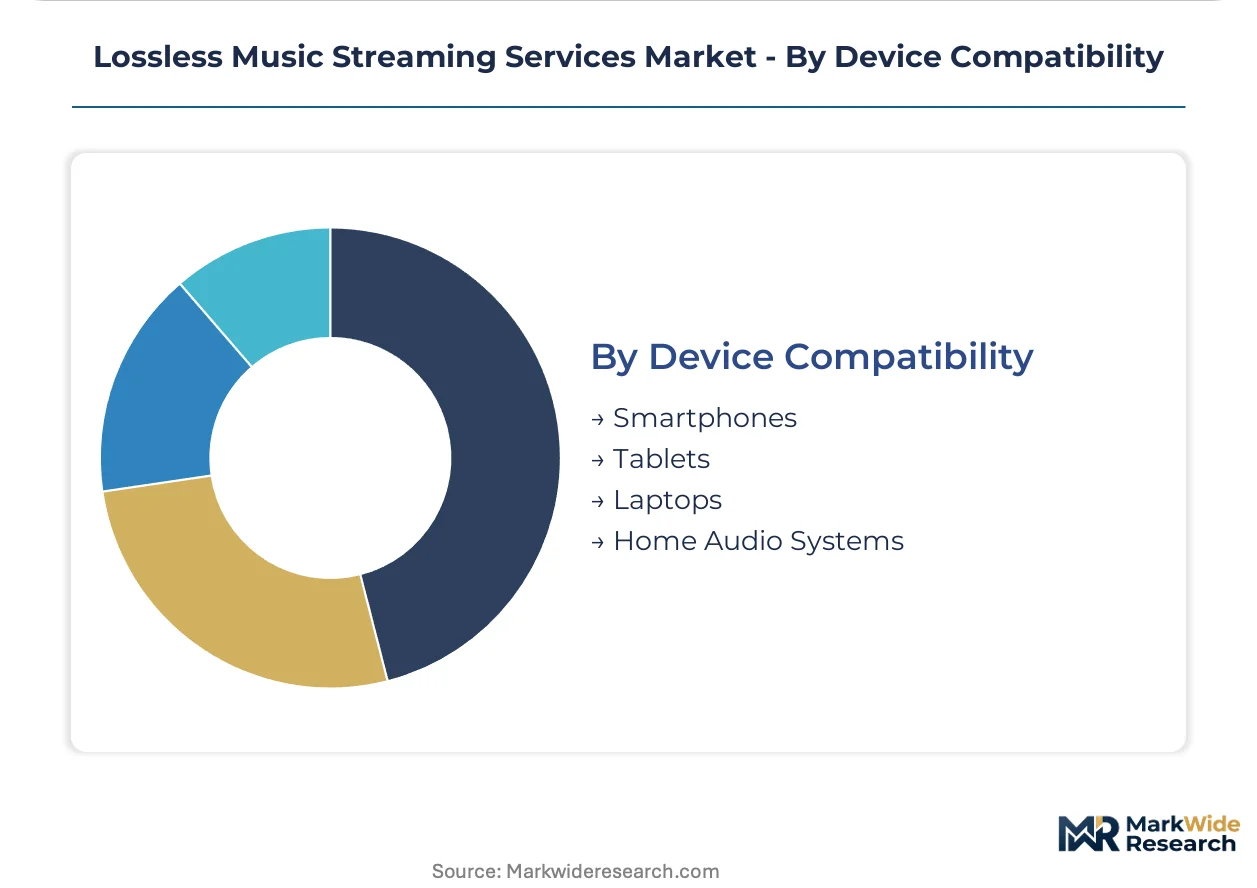
Per-user value generation concentrates in home audio installations despite smaller installed bases relative to smartphone volume.
- Smartphones:Dominant streaming volume through iOS and Android native apps. Perceptual equivalence testing shows majority listeners cannot distinguish 320kbps AAC from CD-quality FLAC on consumer earbuds, limiting mass-market conversion.
- Tablets:Secondary mobile consumption with larger screen editorial browsing. Cross-device workflow continuity benefits from FLAC container standardization.
- Laptops:Desktop-critical listening and local library management. Audiophile collectors accelerate migration to platform-agnostic storage, compressing switching costs.
- Home Audio Systems:Dedicated DACs, amplifiers, and loudspeaker configurations. Premium vehicle cabin acoustics in Germany and Japan create white space for native hi-res apps with voice control integration.
Home Audio Systems generates disproportionate per-user value. Smartphones retains volume dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform licensing concentration clusters in Western Europe and East Asia where regulatory frameworks for digital audio standards have matured fastest. Subscriber monetization depth correlates with metropolitan hardware penetration and net neutrality enforcement.
Germany
Bundesnetzagentur net neutrality mandates prevent carrier throttling of high-bandwidth FLAC streams, preserving quality consistency across mobile networks. Berlin and Munich anchor the deepest European installed base of external DACs and headphone amplifiers. Automotive OEMs in Stuttgart and Ingolstadt integrate native hi-res streaming apps into premium cabin acoustics.
Japan
Tokyo and Osaka sustain the world's highest penetration of 24-bit/192kHz-capable playback hardware among consumer segments. METI hi-res audio certification standards filter platform market entry through extended validation cycles. Nagoya's precision electronics cluster supplies DAC components to domestic and export markets.
United States
FCC broadband labeling rules mandate transparent speed disclosures that shape consumer expectations for uninterrupted 24-bit streaming throughput. Los Angeles and Nashville concentrate archival tape digitization expertise for authentic hi-res catalog expansion. Seattle and San Francisco anchor cloud infrastructure serving North American subscriber bases.
United Kingdom
Ofcom regulatory oversight ensures competitive parity in audio streaming delivery across fixed and mobile networks. London's mastering engineer concentration supports remastering pipelines for estate-held classical and jazz recordings. Manchester and Glasgow sustain secondary clusters of audiophile retail and hardware distribution.
France
ANSM and CNIL data governance frameworks intersect with EU Digital Services Act transparency mandates for music licensing disclosure. Paris anchors Qobuz's editorial specialization in classical and jazz verticals. Lyon and Bordeaux support regional audiophile communities with dedicated hi-fi retail networks.
Lossless Music Streaming Services Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the lossless streaming ecosystem. The market structure fragments across codec licensors, platform operators, and hardware-integrated services rather than consolidating around pure scale. Three archetypes dominate: MQA-licensed premium specialists, FLAC-standard mass-market platforms, and ecosystem-locked hardware bundlers. Competitive moves concentrate on exclusive content acquisition and spatial audio format differentiation rather than price undercutting.
Within the premium-specialist tier, Tidal and Qobuz exemplify codec-ecosystem anchoring strategies. Tidal occupies a position tied to MQA studio-master authentication, while Qobuz represents European market presence through genre editorial depth. Among mass-market platforms with lossless tiers, Apple Music and Amazon Music Unlimited sit within hardware-ecosystem bundling archetypes. Spotify exemplifies the freemium-to-lossless conversion challenge despite compressed-audio heritage.
| Leading Market Players |
|---|
| Qobuz |
| YouTube Music Premium |
| Spotify |
| SoundCloud |
| Deezer |
| Apple Music |
| Amazon Music Unlimited |
| MusicGremlin |
| Tidal |
| Others |
Pricing and Supply Chain Analysis
Codec licensing scale economies concentrate MQA royalty obligations with a single licensor while FLAC standardization democratizes container access, compressing price floors for mass-market tiers and anchoring premium tiers to authentication scarcity.
Pricing Analysis
Japan's METI hi-res audio certification dictates the pricing tier structure across authentic studio-master catalogs. Three-tier pricing separates immersive spatial audio from high-resolution FLAC from standard lossless, with certification grade and hardware ecosystem integration as primary price differentiation drivers. Pricing pressure stems from MQA licensing concentration that creates input cost volatility for authentication-dependent platforms. Mobile-first subscribers in emerging markets exhibit highest price sensitivity, while Japan's hardware-enthusiast collectors demonstrate lowest sensitivity to tier premiums.
Supply Chain Analysis
Inventory cycles for archival tape digitization extend lead times for authentic hi-res catalog expansion, constraining supply velocity against streaming demand growth. Mastering engineer expertise concentrates in the United States, United Kingdom, and Japan, with analog-to-digital conversion hardware and studio facility access as critical input dependencies. Single-source vulnerability runs through Tokyo's aging specialist pool for estate-held classical and jazz remastering. Distribution feeds from cloud infrastructure nodes in Seattle and San Francisco to subscriber endpoints across North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lossless music streaming services are recovering from compressed-audio commoditization as hardware upgrade cycles accelerate and audiophile subscription tenure lengthens.
For Market Incumbents: Shield exclusive catalog depth through accelerated archival tape digitization partnerships with Tokyo and Nashville mastering houses. Prioritize backward integration into MQA licensing negotiations to reduce royalty volatility exposure. Defensive patenting around spatial audio rendering algorithms preserves immersive tier pricing power against FLAC-standard competitors. For New Entrants and Emerging Players: Anchor in Germany's automotive OEM integration channel where premium cabin acoustics create white space for native hi-res streaming apps with steering-wheel voice control. Target classical and jazz verticals in France and the Netherlands where EU Digital Services Act transparency mandates disadvantage estate-rights-heavy incumbents. Pursue artist-centric payout visibility as editorial differentiation against commodity streaming platforms. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-agnostic codec specialists over ecosystem-locked hardware bundlers. Long-term viability hinges on catalog exclusivity duration and spatial audio format penetration rates. Acquisition target archetypes include classical-specialist platforms with estate-held recording rights and automotive-integrated streaming services. The inflection signal to monitor is Japan's METI certification timeline compression against uncertified competitor entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| MQA Licensing Renegotiation | Reduces royalty concentration risk for Tidal-dependent authentication tiers. |
| Archival Digitization Partnership | Secures Tokyo and Nashville mastering capacity for authentic hi-res expansion. |
| Automotive OEM Integration | Captures Stuttgart and Ingolstadt premium vehicle cabin acoustic deployments. |
| Spatial Audio Format Investment | Enables Dolby Atmos tier pricing above standard hi-res subscriptions. |
| Artist Payout Transparency Platform | Leverages EU Digital Services Act mandates for competitive differentiation. |
Research Methodology
Operator-level perspectives from streaming platform executives, mastering engineers, automotive infotainment product managers, and hi-fi retail channel owners anchored the qualitative base. Primary fieldwork combined with secondary validation against FCC broadband labeling disclosures, Japan METI certification databases, EU Digital Services Act implementation guidance, and music licensing transparency filings. Bottom-up subscriber modeling triangulated against top-down market sizing across service type, pricing model, content type, and device compatibility dimensions.
Sensitivity analysis tested forecast robustness across the projection horizon. Segmentation modeling incorporated service delivery mode, codec ecosystem allegiance, hardware integration depth, and regional regulatory cluster. CAGRs derived from subscriber growth trajectories, tier migration velocity, and per-user revenue expansion patterns. Industry-specific inputs included MQA licensing cost curves, METI certification timeline distributions, and automotive OEM integration pipeline visibility.
Decision-makers should treat outputs as directional under sustained net neutrality enforcement and hardware upgrade cycle continuity; material deviation in carrier zero-rating policy or perceptual equivalence threshold shifts would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Media and Entertainment
United States Live Music Market
Media and Entertainment
Subscription Background Music Service Market
Media and Entertainment
China Catalog Market
Media and Entertainment
Holographic TV Market
Media and Entertainment
South East Asia Advertising Market
Media and Entertainment
Arcade Games Market
Media and Entertainment
Global Influencer Market
Media and Entertainment
AI in Media and Entertainment Market
Media and Entertainment
Global Free Music Making Software Market
Media and Entertainment
Argentina OOH and DOOH Market
Media and Entertainment
Volumetric Video Market
Media and Entertainment
Social Media Analytics Market
Media and Entertainment
LED Stadium Screens Market
Media and Entertainment
PC Games Market
Media and Entertainment
Events and Exhibition Market
Media and Entertainment
Middle East and Africa Animation, VFX and Post Production Market