
 Living and Dining Room Market | 2026-2036
Living and Dining Room Market Size, Share, and Industry Trends Forecast 2026-2036
Living and Dining Room Market Intelligence
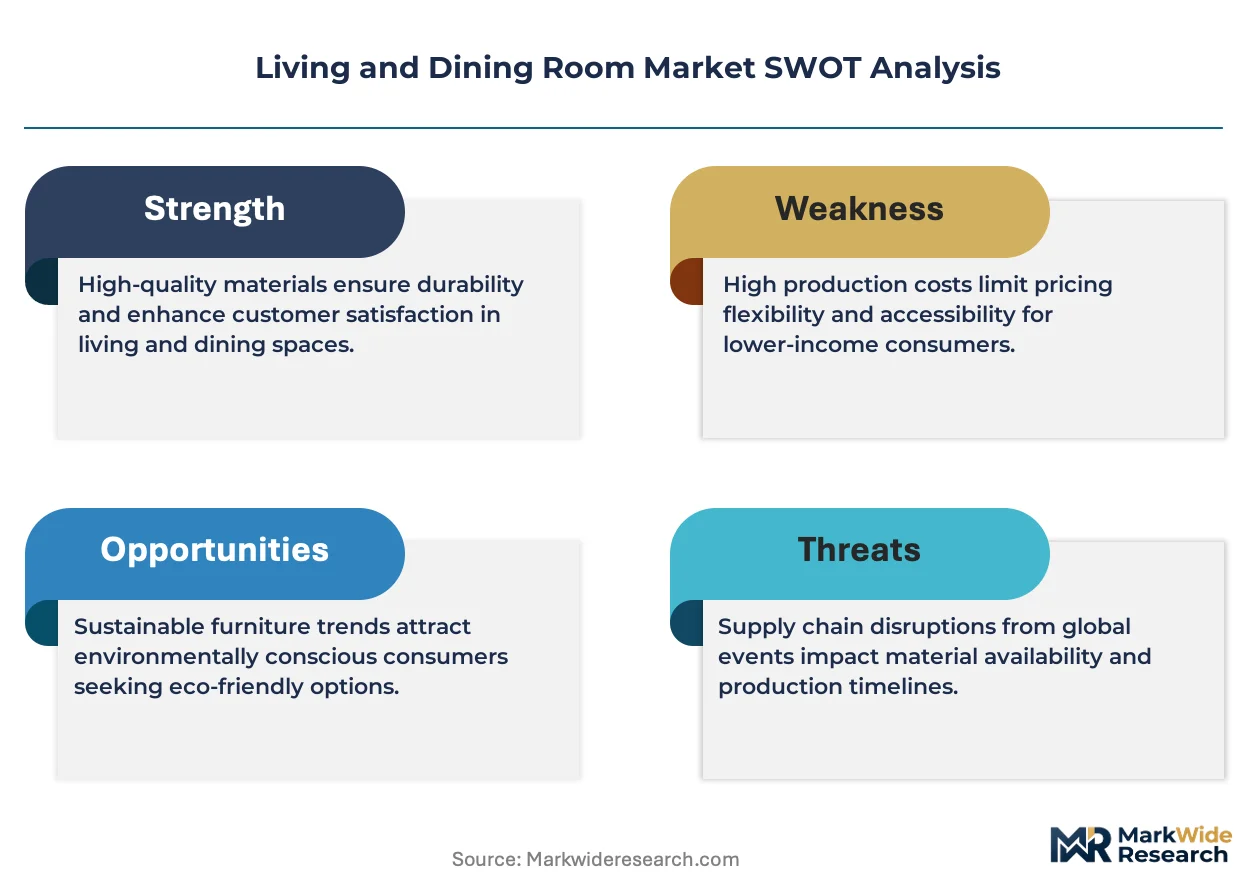
The European Union's Corporate Sustainability Reporting Directive (CSRD) is rebalancing the cost-of-entry calculus by mandating extensive supply chain disclosures. This regulatory shift benefits large-scale operators like Inter IKEA Systems B.V., which leverages its vast, controlled supply network for compliance. Williams-Sonoma Inc. differentiates through its focus on artisanal and sustainably sourced premium collections. Ashley Furniture Industries, Inc. competes on manufacturing scale and distribution efficiency across key markets.
Living and dining room furniture encompasses a range of freestanding or modular items designed for residential social and eating areas. These products are typically constructed from engineered wood, solid wood, or metal, often featuring specific finishes and upholstered elements. Sofas and dining tables continue to anchor the product type segment by total value. The modern and minimalist style categories are seeing accelerated adoption, particularly in online channels, driven by younger consumer preferences for clean aesthetics.
Compliance frameworks, including the U.S. EPA's regulations on volatile organic compounds (VOCs) in furniture finishes and China's GB standards for material safety, directly define market access. Global manufacturers also widely adhere to ISO standards for quality management and product durability testing. Navigating these fragmented material and chemical safety regulations remains a primary strategic consideration for companies aiming for a broad geographic footprint.
Market Dynamics
The central dynamic shaping the living and dining room market is the collision between mass-market demand from rapid urbanization and a tightening global regulatory framework focused on sustainability, forcing a re-evaluation of material sourcing and supply chain transparency.
Growth Catalysts
- Sustainable Product Mandates:The EU's Ecodesign for Sustainable Products Regulation is creating demand for furniture designed for longevity, repairability, and circularity, benefiting manufacturers who can document and certify their material lifecycles.
- Residential Construction Expansion:Sustained growth in multi-family housing projects, particularly in urban centers across India and Southeast Asia, directly expands the addressable market for foundational furniture items like sofas and dining sets.
- Advancements in Engineered Materials:Innovations in engineered wood, such as high-density fiberboard (HDF) and cross-laminated timber, offer cost-effective and aesthetically versatile alternatives to solid wood, aligning with minimalist design trends.
Market Restraints
- Input Cost Volatility:Manufacturers face margin pressure from unpredictable price fluctuations in core raw materials, including solid wood, steel, and petrochemicals used for upholstery foams and synthetic fabrics.
- Fragmented Regulatory Compliance:Navigating disparate chemical safety standards, such as the U.S. EPA's rules on VOCs and China's GB standards for formaldehyde, creates significant administrative and testing overhead for global brands.
- Supply Chain Concentration:Heavy reliance on a concentrated set of Southeast Asian and Chinese manufacturing hubs for finished goods and components exposes the market to geopolitical tensions and logistical disruptions.
Strategic Opportunities
- Direct-to-Consumer (DTC) Channels:Online DTC models allow brands to control the customer experience, capture higher margins, and use data analytics to quickly respond to shifting consumer preferences for modular and customizable furniture.
- Smart Furniture Integration:Incorporating technology such as built-in charging ports, integrated lighting, and smart-fabric controls into sofas and tables opens a new, value-added product category for tech-savvy consumers.
- Circular Economy Business Models:Developing furniture rental, refurbishment, and take-back programs provides new revenue streams while addressing consumer and regulatory demands for greater sustainability and reduced waste.
Industry Challenges
- Supply Chain Traceability:Implementing the systems required to track and verify material origins throughout complex, multi-tiered supply chains to comply with regulations like the CSRD is a significant operational and financial challenge.
- Last-Mile Logistics Complexity:Managing the delivery, assembly, and potential return of large, bulky, and often fragile furniture items is a persistent logistical hurdle, especially with the growth of e-commerce sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Living and Dining Room Market |
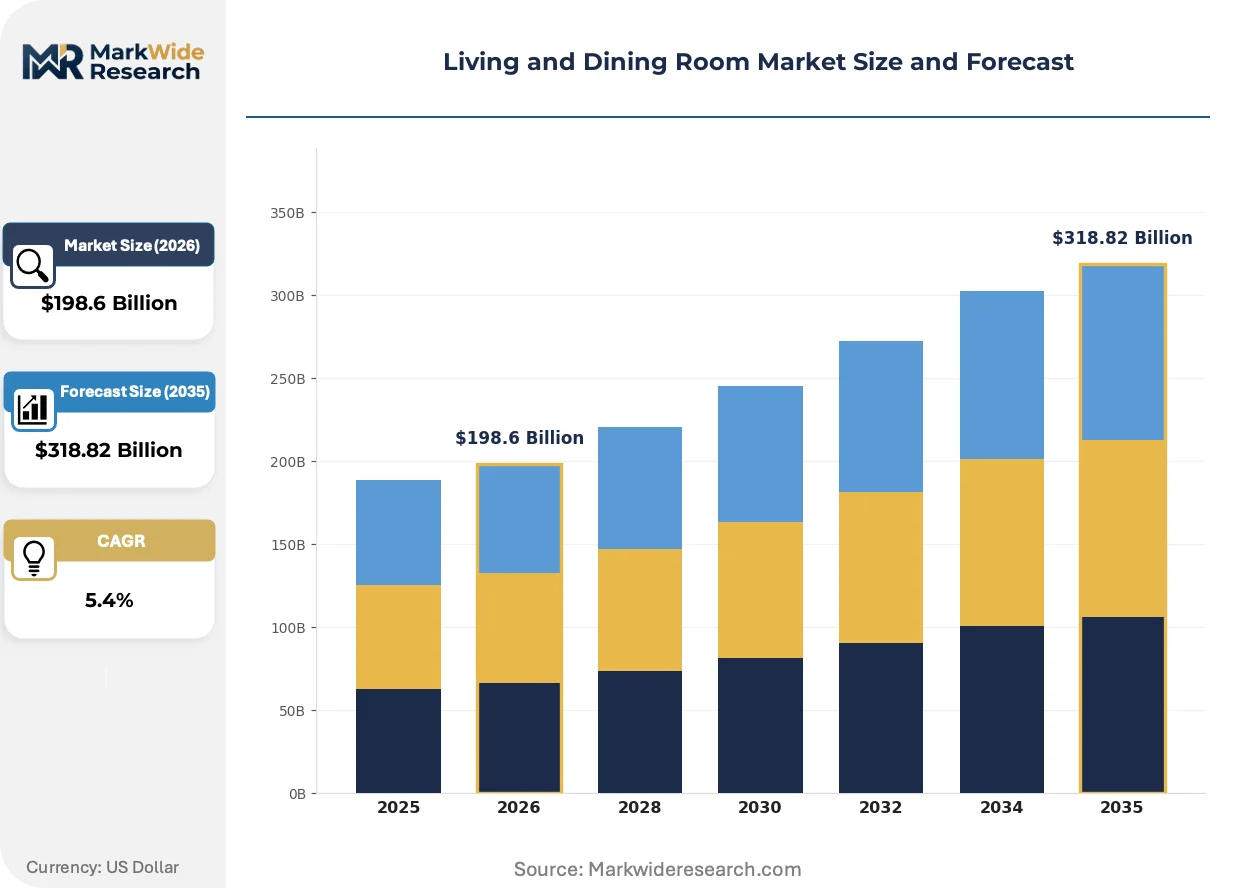
| Market Size in 2026 | $198.6 Billion |
| Market Size in 2035 | $318.82 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Dining Tables, Chairs, Coffee Tables Material: Wood, Metal, Glass, Fabric Style: Modern, Traditional, Rustic, Minimalist Delivery Model: Online, In-Store, Custom Orders, Ready-to-Assemble |
| Companies Covered | Inter IKEA Systems B.V., Ashley Furniture Industries, Inc., Herman Miller, Inc., HNI Corporation, Okamura Corporation, KOKUYO Co., Ltd., Godrej & Boyce Manufacturing Company Limited, Williams-Sonoma Inc., Wayfair Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Living and Dining Room Market Strategic Shifts & Innovations
Product design and go-to-market strategies are being transformed by the dual forces of digital visualization tools and a non-negotiable sustainability agenda. This shift favors manufacturers capable of delivering both aesthetic personalization and documented environmental credentials.
Augmented reality (AR) and 3D configuration tools are key enabling technologies for online furniture retail. These platforms allow consumers to visualize products to scale within their own homes, directly addressing a primary barrier to purchasing large items online. Younger, digitally-native buyers are adopting these tools rapidly, and their use is rewriting the role of the physical showroom and reducing product return rates.
Regulatory frameworks are increasingly focused on lifecycle transparency. The European Union's Corporate Sustainability Reporting Directive (CSRD) compels large companies to provide extensive disclosures on their supply chain's environmental and social impacts. This forces manufacturers exporting to the EU to invest heavily in traceability, impacting product categories like upholstered furniture that rely on complex, global material inputs.
A notable behavioral shift is the move away from purchasing complete, matched furniture sets. Consumers now curate eclectic spaces by mixing individual pieces, styles, and brands, a practice amplified by social media platforms like Instagram and Pinterest. This disrupts the traditional retail floor model and creates an advantage for brands that excel at selling individual "hero" pieces through compelling digital storytelling, a trend most visible in North American and European markets.
Living and Dining Room Market Segmentation
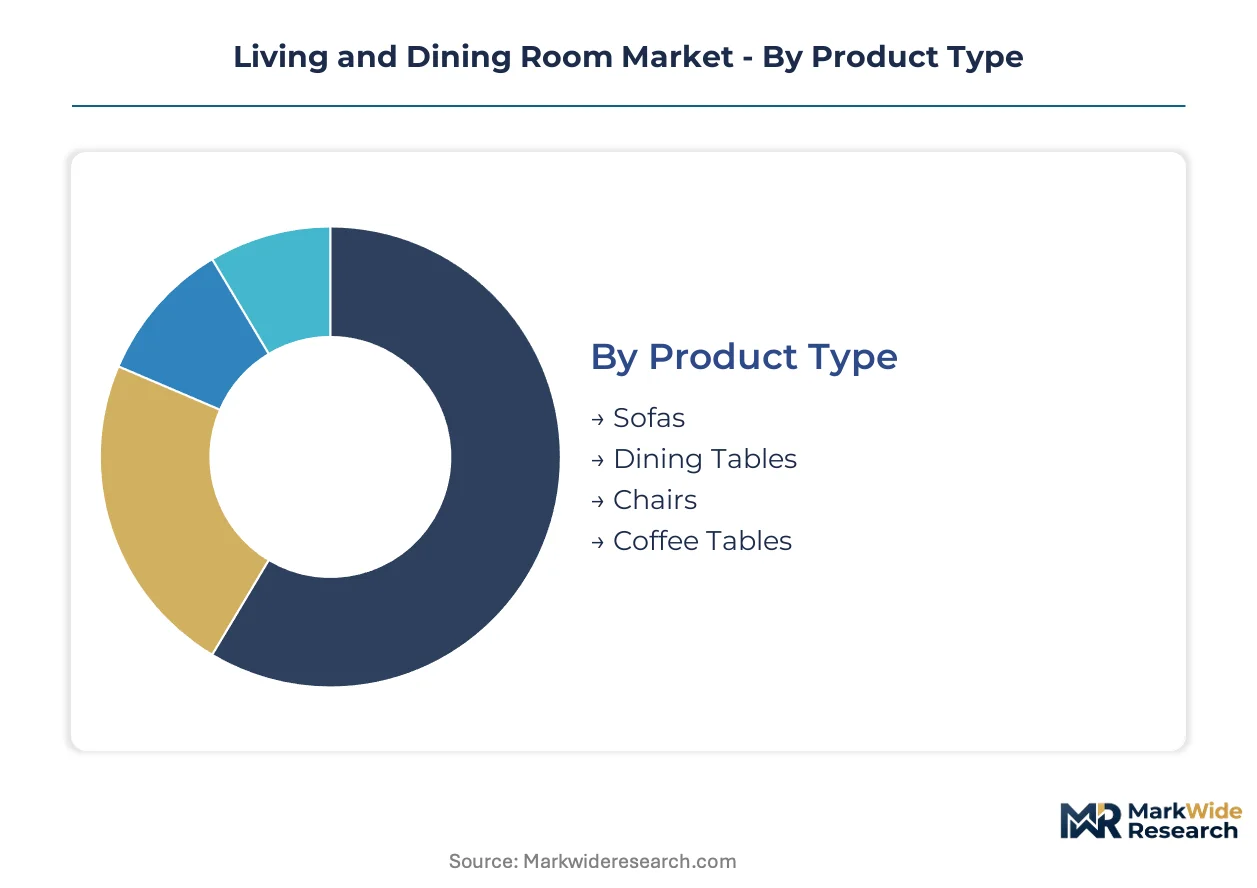
Understanding the varied segments within the living and dining room market is critical for manufacturers and retailers to align product development and distribution strategies with specific consumer needs. This segmentation reveals distinct purchasing behaviors and product preferences across different categories.
Product Type:
A consumer's primary decision driver for living and dining room furniture often revolves around the core function and aesthetic impact of individual pieces within their space.
- Sofas:These upholstered seating units form the centerpiece of living areas, constructed with frames of solid wood or engineered wood, often featuring various fabric or leather coverings. Demand for modular and customizable sofa configurations is high in urban centers across Europe, driven by smaller living spaces and a desire for flexible design.
- Dining Tables:Central to eating areas, dining tables are typically crafted from solid wood, engineered wood, or metal with glass or stone tops, serving as focal points for social gatherings. Their market expansion is directly linked to new housing developments in India, where family-oriented living spaces prioritize communal eating.
- Chairs:Complementing dining tables or providing accent seating, chairs are produced in diverse materials like wood, metal, or plastic, often with upholstered seats for comfort. Younger consumers frequently seek lightweight, stackable designs for versatility in multi-functional rooms.
- Coffee Tables:Positioned in living rooms, coffee tables offer surface utility and aesthetic appeal, commonly made from wood, metal, or glass. Minimalist designs are particularly popular in North American markets, reflecting clean aesthetic preferences.
Volume sits with Sofas; growth tilts toward Dining Tables.
Material:
Material selection frequently depends on a balance between cost considerations and desired durability for different furniture types.
- Wood:This category includes both solid wood, prized for its durability and natural aesthetic, and engineered wood such as MDF or HDF, valued for cost-effectiveness and design versatility. The EU's Ecodesign for Sustainable Products Regulation is increasing demand for sustainably sourced and certified wood materials.
- Metal:Utilized for frames, legs, and decorative accents, metal offers strength and a modern aesthetic, with steel and aluminum being common choices. Innovations in lightweight metal alloys are improving logistical efficiency for large furniture components.
- Glass:Often used for tabletops and display cabinet doors, glass provides a sleek, transparent finish, contributing to a sense of openness in smaller living spaces. Its integration into modern furniture designs is prominent in European markets.
- Fabric:Essential for upholstery on sofas and chairs, fabrics range from natural fibers like cotton and linen to synthetic blends, influencing comfort and style. Chemical safety regulations, such as China's GB standards, impact the selection and treatment of upholstery materials.
Wood products maintain significant market presence, while engineered materials continue gaining share fastest.
Style:
Consumer preferences for specific aesthetics dictate style choices, with younger buyers increasingly opting for clean lines and functional designs.
- Modern:Characterized by clean lines, geometric shapes, and a focus on functionality, modern furniture often incorporates materials like metal, glass, and minimalist wood finishes. This style resonates strongly with urban consumers in North America seeking contemporary living environments.
- Minimalist:Emphasizing simplicity, uncluttered spaces, and a neutral color palette, minimalist designs prioritize essential forms and practical utility. Online channels in Europe show accelerated adoption of this aesthetic among younger demographics.
- Traditional:Defined by classic designs, ornate detailing, and often crafted from rich, solid woods, traditional furniture evokes a sense of heritage and formality. This style retains consistent demand in established residential markets.
- Rustic:Featuring natural textures, distressed finishes, and robust construction, rustic furniture brings an earthy, natural feel to interiors. Demand for this style is particularly consistent in rural and suburban housing markets.
Modern and minimalist styles are seeing accelerated adoption, particularly in online channels, driven by younger consumer preferences for clean aesthetics.
Delivery Model:
The accessibility and convenience of product acquisition heavily influence the chosen delivery model for furniture purchases.
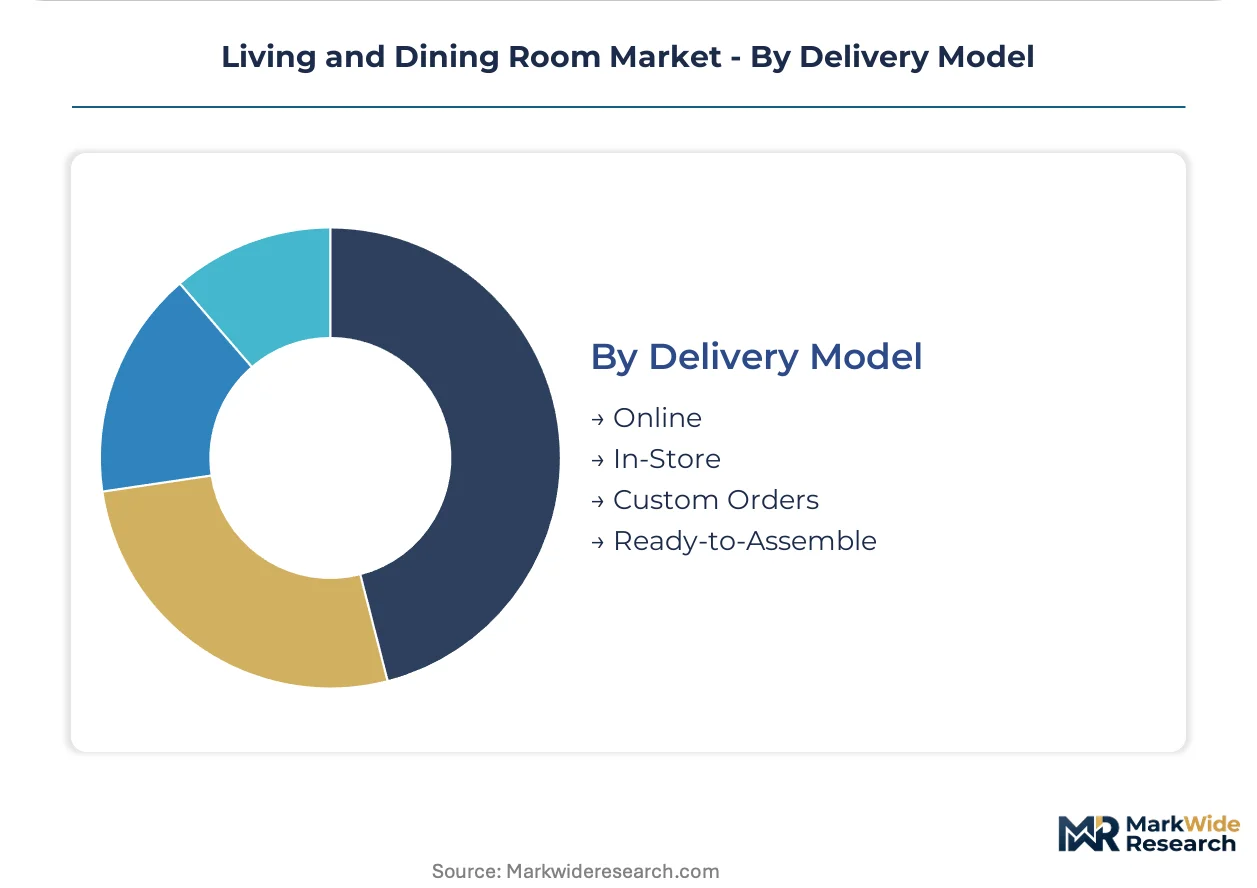
- Online:This model leverages e-commerce platforms, offering extensive product catalogs, digital visualization tools, and direct shipping to consumers. The growth of online sales is reshaping last-mile logistics for bulky furniture items across global markets.
- In-Store:Traditional brick-and-mortar showrooms allow customers to physically inspect furniture, experience materials, and receive personalized sales assistance. This model remains crucial for high-value and custom furniture purchases, particularly in established retail landscapes.
- Custom Orders:This model allows consumers to specify materials, dimensions, finishes, and configurations, resulting in unique, made-to-order pieces. Artisanal and premium brands, like Williams-Sonoma Inc., leverage custom orders for differentiation.
- Ready-to-Assemble:Furniture designed for consumer self-assembly reduces shipping costs and simplifies logistics, often featuring modular components and standardized fittings. This model is popular among budget-conscious consumers and e-commerce platforms.
In-store purchases still represent a significant channel, with online models expanding most quickly across urban centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive network of industrial production zones underpins significant manufacturing output for the global living and dining room market. These zones facilitate large-scale production and export, positioning China as a central hub for furniture supply chains. Regulatory shifts towards sustainability and material traceability are now influencing production methods across these key regions.
United States
The United States market experiences strong demand from ongoing urbanization and expanding e-commerce channels for home furnishings. U.S. EPA regulations on volatile organic compounds (VOCs) directly influence finish formulations and material choices for manufacturers. High Point, North Carolina, remains a prominent furniture manufacturing and design hub, attracting significant industry investment and trade events.
Germany
Germany's robust consumer base drives demand for high-quality, sustainably produced living and dining room furniture. The EU's Ecodesign for Sustainable Products Regulation mandates greater longevity and repairability for furniture items. North Rhine-Westphalia hosts a strong furniture industry, emphasizing design innovation and advanced manufacturing techniques.
India
India's rapid urbanization and new housing developments, particularly multi-family residential projects, significantly expand the addressable market for foundational furniture pieces. BIS standards ensure product quality and safety, shaping local manufacturing practices and material specifications. Major urban centers like Mumbai and Delhi-NCR are experiencing concentrated demand and new retail expansions.
China
China's significant domestic market, coupled with its role as a global manufacturing powerhouse, influences living and dining room furniture production and consumption. China's GB standards for material safety dictate stringent requirements for product composition and finishes. Guangdong province serves as a primary furniture manufacturing and export hub, driving global supply chain dynamics.
Japan
Japan's discerning consumers prioritize high-quality, durable furniture designed for compact living spaces and modern aesthetics. JIS standards for quality and product durability guide manufacturing processes and material selection for domestic and imported goods. The Tokyo metropolitan area demonstrates strong consumer demand for innovative, space-saving designs and smart furniture integration.
Living and Dining Room Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the living and dining room market. This structure creates distinct strategic archetypes, including large-scale manufacturers, premium artisanal brands, and e-commerce-centric distributors. Companies frequently pursue geographic expansion and supply chain optimization to enhance their competitive positioning.
Major players like Inter IKEA Systems B.V. and Ashley Furniture Industries, Inc. represent scale-driven efficiency, leveraging extensive manufacturing capacity and controlled supply networks. Williams-Sonoma Inc. anchors the premium segment, differentiating through artisanal collections and sustainably sourced materials. These companies navigate complex global regulatory frameworks while responding to shifting consumer preferences for clean aesthetics and online purchasing.
| Leading Market Players |
|---|
| Inter IKEA Systems B.V. |
| Ashley Furniture Industries, Inc. |
| Herman Miller, Inc. |
| HNI Corporation |
| Okamura Corporation |
| KOKUYO Co., Ltd. |
| Godrej & Boyce Manufacturing Company Limited |
| Williams-Sonoma Inc. |
| Wayfair Inc. |
| Others |
Cost & Logistics Intelligence
The EU's Ecodesign for Sustainable Products Regulation gates both qualified supply and premium-tier pricing access for living and dining room furniture. This regulatory push elevates the importance of documented material lifecycles and sustainable sourcing, rebalancing cost structures for compliant manufacturers.
Pricing Analysis
Short lead times command a premium in the living and dining room market, while spot inventory often receives discounts. The dominant pricing model remains per-unit transactional, though custom orders allow for value-based pricing. Price differentiation stems from material certification levels and brand premium, particularly for artisanal collections. Pricing pressure stems from input cost volatility, impacting margins across the board. Budget-conscious consumers, especially those purchasing ready-to-assemble items, exhibit the highest price sensitivity.
Supply Chain Analysis
Logistics and freight costs significantly influence the final pricing of bulky living and dining room furniture items. Geographic supply concentration remains high, drawing heavily from manufacturing hubs in China and Southeast Asian nations like Vietnam. Raw material dependencies include solid wood, steel, and petrochemicals for upholstery foams. Geopolitical tensions in key manufacturing regions pose a structural supply chain risk. Distribution runs through a hybrid model, combining direct-to-consumer online sales with traditional in-store retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The living and dining room market is a vertical-integration race, with players pursuing upstream control over material sourcing to ensure regulatory compliance and cost stability.
For Market Incumbents:
Lock in long-term supply agreements for sustainably sourced wood and metal components. This mitigates input cost volatility and strengthens compliance with regulations like the EU's Ecodesign mandate. Invest in advanced manufacturing technologies to enhance production efficiency and reduce waste, countering margin pressure from emerging online-first brands. Control over the last-mile logistics experience for large furniture items also reinforces brand loyalty.
For New Entrants and Emerging Players:
Launch via direct-to-consumer online channels, leveraging digital visualization tools to reduce customer acquisition costs. Target the minimalist and modern aesthetic segments, particularly among younger, urban demographics in European and North American markets. Focus on modular and customizable furniture designs that cater to smaller living spaces. A compelling digital storytelling strategy can differentiate products in a crowded online marketplace.
For Investors and Strategic Acquirers:
Growth in multi-family housing projects in India is the leading indicator that foundational furniture demand will sustain. Long-term viability rests on companies capable of navigating complex global regulatory frameworks while offering aesthetic personalization. Acquisition targets should include digitally native brands with strong direct-to-consumer capabilities and robust supply chain traceability systems. Watch for significant investments in circular economy business models as an inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Supply Chain Traceability Platforms | Ensures compliance with EU CSRD and other global material safety regulations for upholstered furniture. |
| Expand Direct-to-Consumer E-commerce Capabilities | Captures higher margins and provides direct access to shifting consumer preferences for modular designs. |
| Develop Circular Economy Business Models | Creates new revenue streams through furniture rental and refurbishment, addressing sustainability demands. |
| Acquire Advanced Manufacturing Technologies | Enhances production efficiency and material utilization, reducing input cost pressures for large-scale operators. |
| Target Smart Furniture Integration Partnerships | Opens a new value-added product category for tech-savvy consumers in urban centers. |
Research Approach
Industry association reports, trade publications, and regulatory databases formed the secondary backbone, providing foundational market data. This secondary research was triangulated with primary interviews conducted with furniture designers, procurement managers, logistics heads, and retail buyers. The combined approach ensured a comprehensive understanding of market dynamics and competitive landscapes.
A bottom-up and top-down analytical framework was employed to generate market size and forecast data across the analysis window. Segmentation by product type, material, style, delivery model, and key regional markets like India and Germany informed the quantitative model. Compound annual growth rates were derived from historical trends and projected market influences, considering factors like housing starts and consumer spending on home furnishings.
Raw material price spikes, new trade barriers, and shifts in consumer finance are the dominant revision risks for market projections. Forecasts reflect assumptions documented through extensive primary and secondary research. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture & Home Decor
Australia Do-It-Yourself (DIY) Home Improvement Retailing Market
Furniture & Home Decor
Collapsible Wardrobe Market
Furniture & Home Decor
North America Awnings Market
Furniture & Home Decor
Contract Furniture and Furnishing Market
Furniture & Home Decor
Pullout Faucets Market
Furniture & Home Decor
Vietnam DIY Home Improvement Market
Furniture & Home Decor
Global OFF-THE-SHELF Second Hand Furniture Market
Furniture & Home Decor
Entryway Furniture Market
Furniture & Home Decor
Freestanding Retractable Awnings Market
Furniture & Home Decor
Ergonomic Office Furniture Market
Furniture & Home Decor
North America Wall Bed Market
Furniture & Home Decor
China Mattress Market
Furniture & Home Decor
India Furniture Market
Furniture & Home Decor
Residential Interior Wood Doors Market
Furniture & Home Decor
Kitchen Linens Market
Furniture & Home Decor
Smart Bed Market