
 Lithium-Ion Battery Metal Market | 2026-2036
Lithium-Ion Battery Metal Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Battery Metal Market Insights
Battery-grade metal specifications is rotating toward higher-purity thresholds as automakers demand consistent cathode performance. Albemarle Corporation leverages its brine extraction dominance in Chile to sustain long-term lithium carbonate supply. Ganfeng Lithium Co., Ltd. anchors its position through backward integration into spodumene mining and salt lake operations. Glencore International AG competes by controlling cobalt flows from the Democratic Republic of Congo.
Lithium-ion battery metals encompass refined lithium compounds, cobalt cathode precursors, nickel sulfate, and manganese derivatives processed to electrochemical-grade purity for cell manufacturing. These materials enable ion transfer between anode and cathode during charge-discharge cycles, with nickel-rich NMC formulations now dominating high-energy-density applications. Lithium and nickel segments attract the deepest margin pools as cathode chemistry pivots away from cobalt-heavy formulations. Electric Vehicles within the Application dimension leads absolute offtake volumes, while Renewable Energy Storage represents the fastest-expanding demand corridor as grid-scale deployments multiply.
EPA tailpipe rules in the United States, the EU Battery Regulation's carbon footprint declarations, and China's MIIT new-energy vehicle mandates collectively reshape extraction and refining compliance burdens. ECHA REACH restrictions on cobalt conflict sourcing and Indonesia's nickel export ban are forcing processors to localize supply chains or secure qualified supplier status. Stakeholders must track which jurisdictions impose binding recycled-content minimums before committing to smelter investments.
Market Dynamics
Cathode chemistry migration toward nickel-rich NMC formulations is compressing cobalt offtake while amplifying nickel sulfate demand intensity per kilowatt-hour, forcing metal processors to reconfigure refining capacity toward higher-purity nickel intermediates.
Growth Catalysts
- EPA tailpipe rules:The United States EPA mandates drive automakers to secure long-term battery-grade metal offtake contracts, accelerating direct procurement from refiners.
- Electric vehicle manufacturers:OEMs are expanding cathode plant joint ventures to lock in nickel sulfate and lithium hydroxide supply streams for high-nickel chemistries.
- Indonesia's nickel processing cluster:The country's intermediate product export restrictions are drawing hydrometallurgical investment to satisfy battery-grade specifications.
Market Restraints
- Lithium carbonate price volatility:Brine extraction concentration in Chile and Argentina exposes contract pricing to water availability and evaporation rate fluctuations.
- Cobalt supply concentration:Democratic Republic of Congo artisanal mining dominance creates ESG compliance burdens under ECHA REACH conflict-mineral tracing requirements.
- Solid-state battery substitution:Lithium-metal anode development threatens conventional cathode metal demand intensity per unit energy storage.
Strategic Opportunities
- Renewable energy storage:Grid-scale battery deployments in India represent underpenetrated demand for long-duration lithium iron phosphate systems.
- EU Battery Regulation recycled-content mandates:The framework's binding minimums for recovered lithium and cobalt create first-mover advantages for integrated recycler-smelters.
- Direct recycling technology:Hydrometallurgical cathode regeneration is converging with black mass preprocessing to bypass primary refining for nickel and manganese recovery.
Industry Challenges
- Battery-grade purity certification:Electrochemical-grade specifications for transition metal sulfates require 12-18 month qualification timelines with cathode manufacturers.
- Smelter retooling capex:Converting Class 1 nickel matte to battery-grade sulfate demands specialized HPAL circuits costing several hundred million dollars per train.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Battery Metal Market |
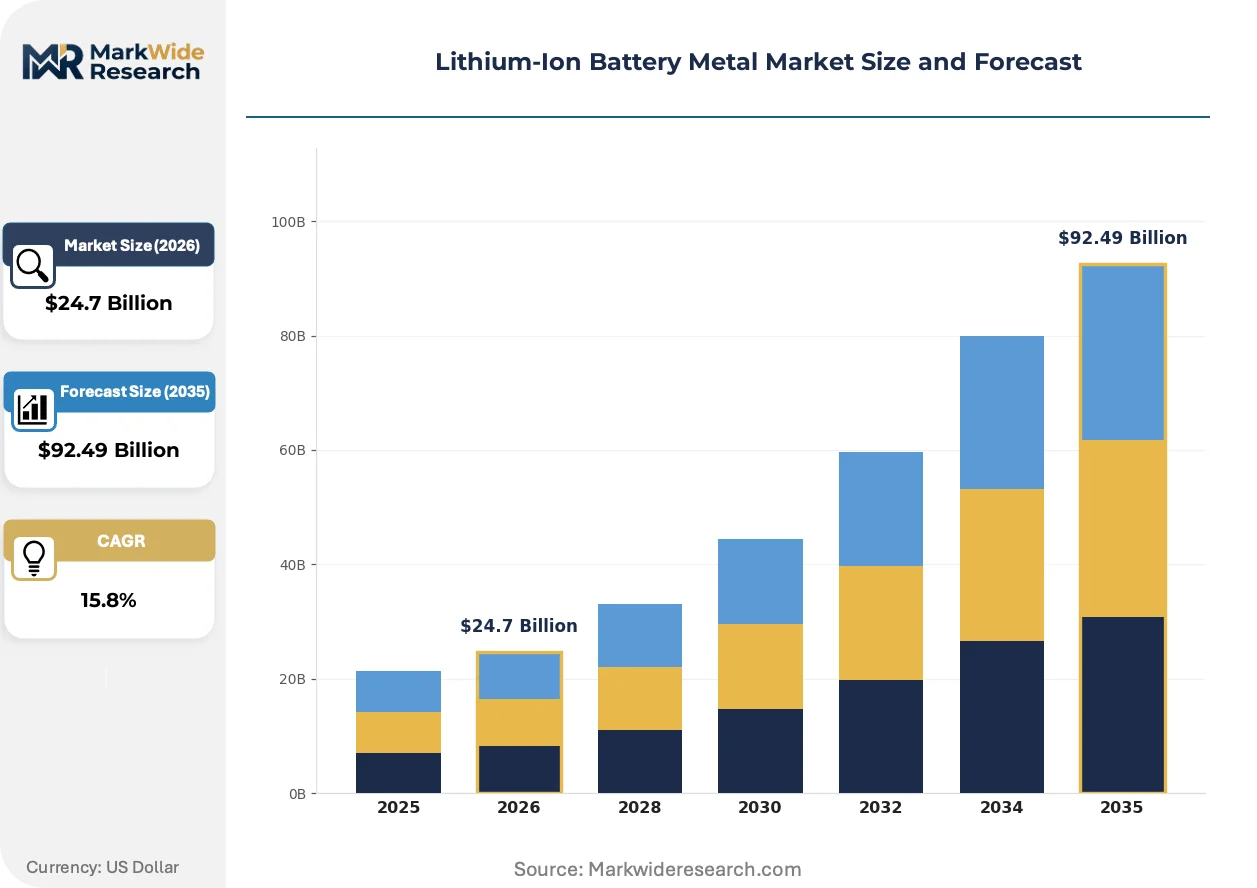
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $92.49 Billion |
| CAGR (2026 – 2036) | 15.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
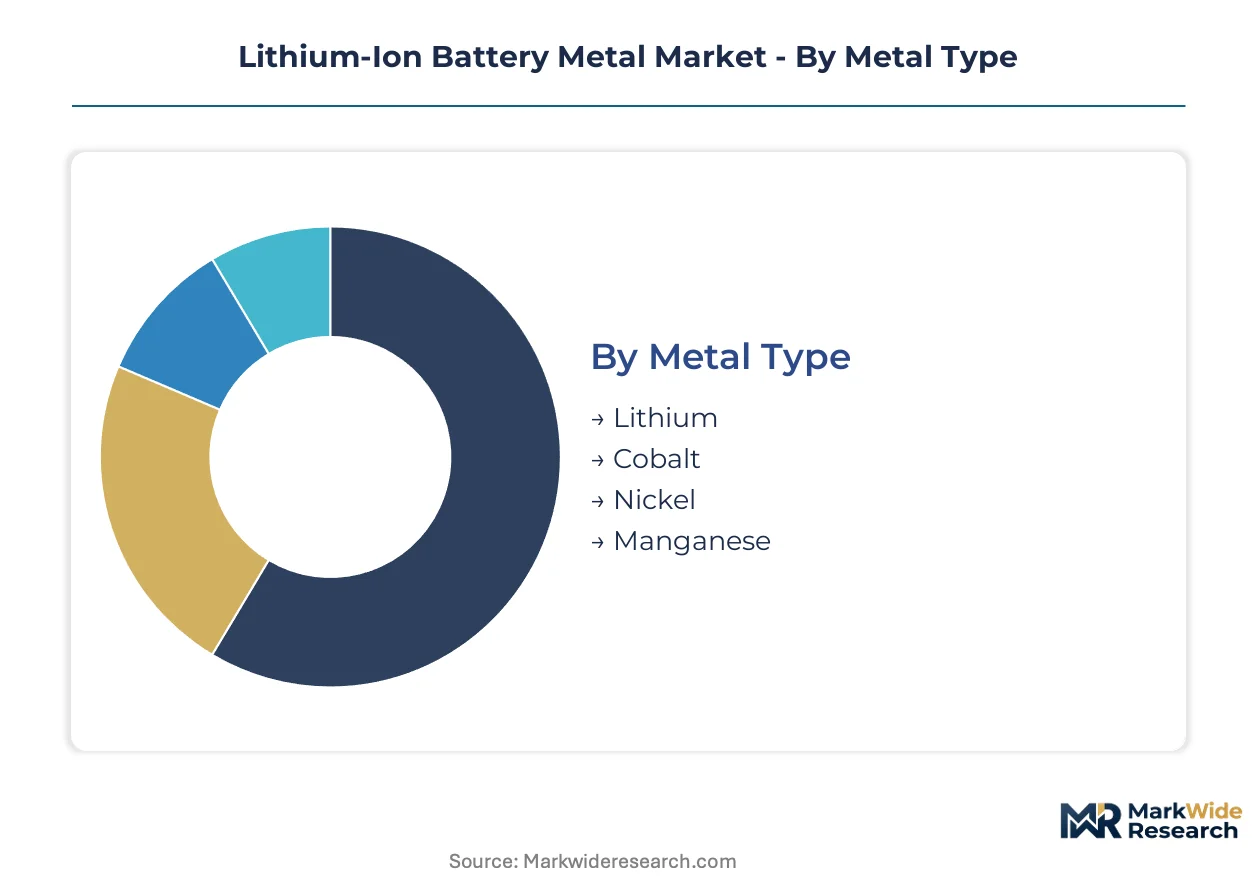
| Segmentation | Metal Type: Lithium, Cobalt, Nickel, Manganese Application: Consumer Electronics, Electric Vehicles, Renewable Energy Storage, Grid Storage End User: Automotive Manufacturers, Electronics Producers, Energy Suppliers, Industrial Equipment Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesalers |
| Companies Covered | Albemarle Corporation, Tianqi Lithium, SQM S.A., Ganfeng Lithium Co., Ltd., Glencore International AG, China Molybdenum Co., Ltd., Sumitomo Metal Mining Co., Ltd., Umicore, Vale, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Battery Metal Market Trends and Innovations
Processing technology and supply chain governance are converging to reshape how battery-grade metals achieve electrochemical purity, with three distinct vectors altering competitive positioning across extraction, refining, and procurement.
Direct lithium extraction from geothermal brines is miniaturizing the environmental footprint of lithium carbonate production while shortening project development timelines. Developers in California's Salton Sea and Germany's Upper Rhine Valley are piloting selective adsorption and electrochemical separation units that bypass traditional evaporation ponds. This technology is compressing water consumption per ton of lithium equivalent and enabling production adjacent to European cathode plants.
The EU Battery Regulation's carbon footprint declaration requirements are forcing nickel refiners to document scope 1-3 emissions for battery-grade sulfate sold in European markets. Industrial consequence includes exclusion of coal-powered Indonesian rotary kiln electric furnace output from qualifying supply chains. High-pressure acid leach operations powered by renewable electricity in Indonesia and Australia are securing qualified supplier status ahead of 2027 enforcement deadlines.
Automaker direct offtake contracting is displacing merchant market spot purchasing for cathode-grade nickel and lithium compounds. Tesla, Ford, and Volkswagen Group are negotiating multi-year prepay structures with miners and refiners, bypassing traditional trader intermediaries. This pattern concentrates most visibly in binding supply agreements for Indonesian HPAL nickel and Chilean brine lithium destined for North American cell plants.
Lithium-Ion Battery Metal Market Segmentation
Battery-grade metal procurement splits across purity thresholds, cathode chemistry requirements, and automaker qualification timelines. Each segmentation axis carries distinct margin profiles and regulatory exposure that reshape supplier competitive positioning.
Metal Type:
EPA tailpipe rules, ECHA REACH conflict-mineral tracing, and China's MIIT new-energy vehicle mandates each impose divergent compliance burdens on metal-specific supply chains.
- Lithium:Refined lithium carbonate and lithium hydroxide enable ion transfer in anode-cathode electrochemistry. Brine extraction in Chile's Atacama and Argentina's salt flats concentrates supply, with water availability constraints tightening under local environmental agency oversight. Lithium handles the majority of throughput; Nickel is the fastest mover on share.
- Nickel:Battery-grade nickel sulfate processed through high-pressure acid leach circuits supports nickel-rich NMC cathode formulations. Indonesia's export ban on unprocessed ore has redirected investment toward domestic HPAL facilities serving Korean and Chinese cathode plants. Nickel sulfate demand intensifies as cobalt content diminishes in high-energy-density cells.
- Cobalt:Cathode precursor materials sourced primarily from Democratic Republic of Congo concentrate ESG compliance costs under ECHA REACH due diligence requirements. Artisanal mining dominance forces processors to implement blockchain tracing or pivot toward recycled feedstock.
- Manganese:Manganese sulfate derivatives stabilize cathode crystal structures in lower-cost LMO and NMC formulations. South African and Gabonese ore bodies supply refining operations in China and Belgium with lower purity thresholds than nickel or lithium.
Cost tier separation between brine-extracted lithium and laterite-derived nickel sulfate determines project financing structures and offtake contract duration.
Application:
Volume concentration and margin capture diverge sharply between consumer electronics saturation and electric vehicle scale-up phases.
- Electric Vehicles:OEM cathode plant joint ventures in Nevada, Hungary, and China lock in multi-year nickel sulfate and lithium hydroxide supply streams. EPA rules and EU Battery Regulation carbon footprint declarations force direct refiner relationships bypassing merchant markets. Electric Vehicles handles the majority of throughput; Renewable Energy Storage is expanding most quickly.
- Renewable Energy Storage:Grid-scale lithium iron phosphate deployments in India and Texas prioritize cost stability over energy density, sourcing lower-purity lithium carbonate from salt lake operations. Long-duration storage contracts favor fixed-price structures over spot-linked volatility.
- Consumer Electronics:Smartphone and laptop manufacturers source cobalt-heavy LCO cathodes through established trading houses with shorter contract horizons than automotive offtake.
- Grid Storage:Utility-scale battery installations integrate with renewable generation assets, requiring manganese and nickel blends that balance cycle life against capital cost constraints under FERC interconnection rules.
Customer procurement scale separates automotive direct contracting from electronics spot purchasing.
End User:
Backward integration depth varies by sector, with automakers most aggressive in capturing upstream refining capacity.
- Automotive Manufacturers:Tesla, Ford, and Volkswagen Group negotiate prepay structures with Indonesian HPAL operators and Chilean brine extractors. Binding supply agreements now span cathode plant construction timelines in Tennessee, Kentucky, and Ontario. Automotive Manufacturers handles the majority of throughput; Energy Suppliers is climbing the fastest.
- Energy Suppliers:Utility and independent power producers deploy grid-scale storage under state renewable portfolio standards, procuring lithium iron phosphate systems through engineering-procurement-construction contractors rather than direct metal offtake.
- Electronics Producers:Consumer device assemblers rely on cathode material traders with limited visibility into upstream mine-level ESG compliance.
- Industrial Equipment:Forklift and material handling electrification sources nickel-manganese-cobalt blends through distributor networks with 6-12 month inventory cycles.
Margin pool concentration follows cathode chemistry complexity rather than end-user revenue scale.
Distribution Channel:
Channel selection reflects contract duration and qualification burden, with direct sales commanding premium positioning.
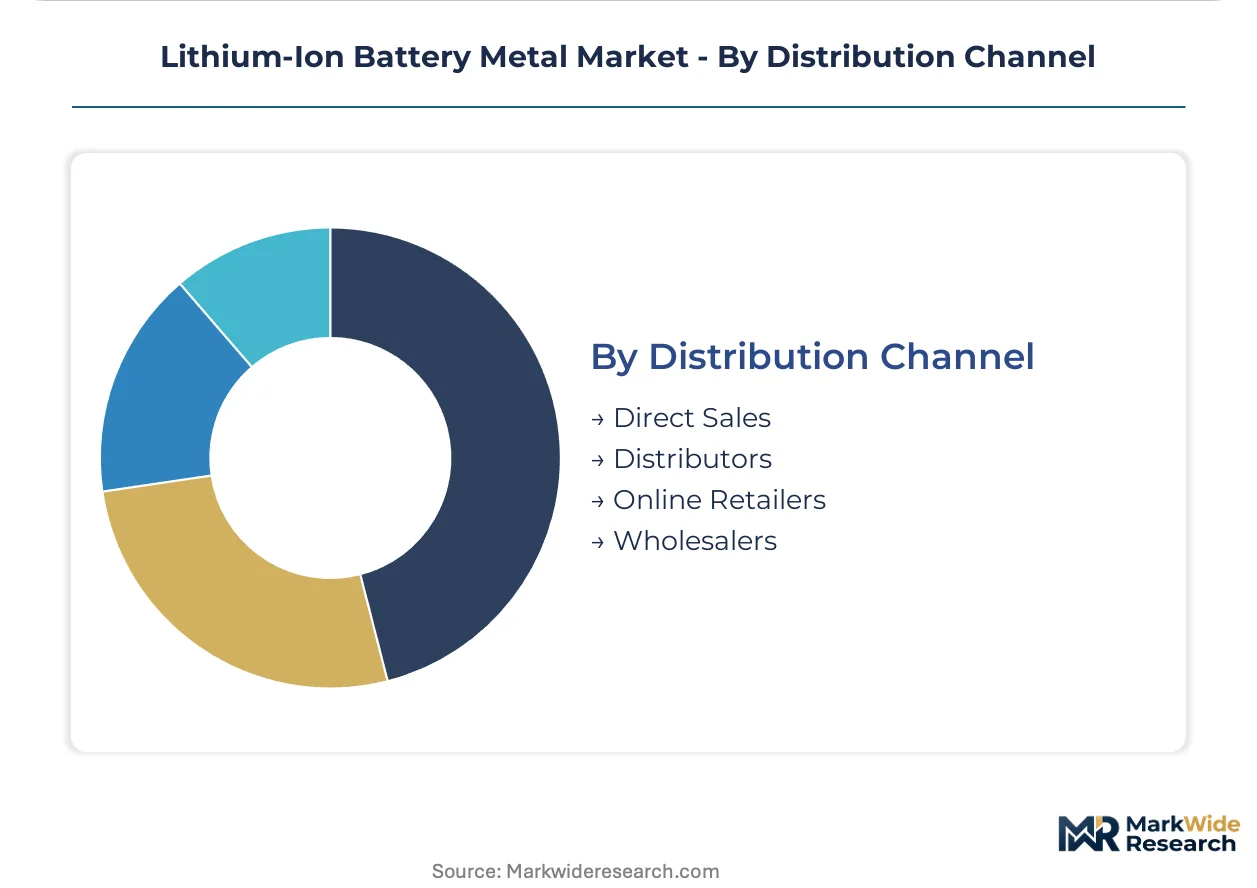
- Direct Sales:Automaker-refiner partnerships eliminate trader intermediaries for battery-grade nickel sulfate and lithium hydroxide. Multi-year prepay structures in Indonesian HPAL and Chilean brine operations concentrate volume through this channel. Direct Sales handles the majority of throughput; Distributors is gaining share fastest.
- Distributors:Specialty chemical traders manage inventory and logistics for mid-tier cathode plants lacking scale for direct refiner negotiations. European distributors now screen suppliers against EU Battery Regulation carbon footprint thresholds.
- Wholesalers:Bulk metal merchants aggregate Class 1 nickel matte and cobalt concentrate for processors without captive mine supply, operating on shorter hedging horizons than direct sales contracts.
- Online Retailers:Laboratory-grade and small-batch cathode precursor materials for research institutions and pilot line testing move through specialized e-commerce platforms with minimal regulatory documentation.
Channel power consolidates around direct sales as automaker vertical integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in battery-grade metals are redirecting investment flows toward processing hubs with captive ore supply. Chile and Indonesia now run structural surpluses in lithium carbonate and nickel intermediates respectively. Import-dependent manufacturing clusters in Germany, South Korea, and the United States are negotiating long-term offtake to secure cathode plant feedstock.
United States
EPA tailpipe rules and Inflation Reduction Act domestic content credits are accelerating cathode plant construction in Tennessee and Kentucky. Automakers negotiate direct prepay structures with Chilean brine extractors and Indonesian HPAL operators to satisfy IRA critical mineral sourcing thresholds. The Nevada lithium triangle is attracting geothermal brine developers to bypass traditional evaporation constraints.
Germany
EU Battery Regulation carbon footprint declarations are excluding coal-powered Indonesian nickel from qualifying supply chains. High-pressure acid leach operations in Australia and renewable-powered Indonesian facilities are securing qualified supplier status ahead of 2027 enforcement. BASF and Umicore are expanding cathode precursor capacity in Schwarzheide and Antwerp to serve European cell plants.
China
MIIT new-energy vehicle mandates and dual carbon goals are tightening domestic refining emissions standards while expanding cathode production capacity in Fujian and Hunan. Ganfeng Lithium anchors backward integration into Argentine salt lakes and African spodumene assets. Indonesia's nickel export ban has redirected Chinese investment toward domestic HPAL joint ventures in Sulawesi.
Indonesia
Nickel intermediate product export restrictions are drawing hydrometallurgical investment from Korean and Chinese cathode manufacturers to satisfy battery-grade sulfate specifications. The Weda Bay and Obi Island industrial clusters are concentrating HPAL capacity to process laterite ore into MHP and mixed hydroxide precipitate. Local content requirements are forcing foreign investors into minority partnerships with state-owned enterprises.
South Korea
POSCO and LG Chem are securing long-term nickel sulfate offtake from Indonesian HPAL operations to feed cathode plants in Gwangyang and Ochang. The country's mineral processing expertise is concentrating on high-purity refining rather than upstream mining exposure. KBA emissions standards for domestic EV sales are accelerating demand for certified low-carbon battery metals.
Lithium-Ion Battery Metal Market Competitive Landscape
Concentration sits with integrated miners controlling upstream ore bodies and captive refining capacity. The vendor base stratifies across three tiers: diversified mining conglomerates with battery metal divisions, pure-play lithium specialists with brine or hard rock assets, and trading houses managing cobalt flows from Central African sources. Competitive moves center on backward integration into spodumene mining and salt lake operations, plus joint venture structures with automaker cathode plant investments.
Among the diversified mining tier, Glencore International AG exemplifies traders pivoting toward direct offtake contracting to bypass merchant market volatility. Within lithium specialists, Albemarle Corporation and Ganfeng Lithium Co., Ltd. occupy positions defined by brine extraction dominance in Chile and dual salt lake-spodumene integration respectively. These three names anchor the competitive structure while representing distinct strategic archetypes: trading house conversion, Western brine incumbent, and Chinese integrated expansion.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Tianqi Lithium |
| SQM S.A. |
| Ganfeng Lithium Co., Ltd. |
| Glencore International AG |
| China Molybdenum Co., Ltd. |
| Sumitomo Metal Mining Co., Ltd. |
| Umicore |
| Vale |
| Others |
Pricing and Supply Chain Analysis
Nickel sulfate substitution for cobalt cathode precursors simultaneously redraws processing geography toward Indonesian HPAL corridors and compresses margin capture for traditional cobalt traders. This chemistry pivot concentrates pricing power with integrated refiners commanding battery-grade purity certification while exposing merchant market participants to volume erosion.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that bypass spot volatility through multi-year prepay arrangements with Chilean brine extractors and Indonesian hydrometallurgical operators. Price differentiation hinges on electrochemical-grade purity thresholds and carbon footprint certification tiers under EU Battery Regulation compliance. Cost compression in standard-grade nickel intermediates is intensifying because Indonesian capacity additions outpace cathode plant qualification timelines. Energy storage developers exhibit highest price sensitivity due to fixed-price procurement mandates, while automotive OEMs absorb premiums for qualified low-carbon supply.
Supply Chain Analysis
Port congestion across the Shanghai-Singapore trade lane elevates inbound logistics costs for European and North American cathode plants dependent on Asian refining output. Geographic concentration centers on Chile for lithium carbonate, Indonesia for nickel intermediates, and the Democratic Republic of Congo for cobalt feedstock. Raw material dependencies draw from laterite ore deposits, Atacama brine reserves, and Central African artisanal mining. Single-source vulnerability around Indonesian nickel export policy shifts threatens supply continuity. Distribution runs through direct automaker-refiner partnerships that displace traditional merchant traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lithium-ion battery metal market sits at a high-growth inflection where EPA tailpipe mandates and EU carbon footprint rules are simultaneously expanding demand and tightening supply qualification thresholds.
For Market Incumbents: Consolidate control over captive brine assets in Chile and Argentina to defend against direct lithium extraction technology disruption. Lock in HPAL offtake partnerships with Indonesian state enterprises before local content requirements harden. Prioritize carbon footprint certification investment to maintain qualified supplier status under EU Battery Regulation enforcement.
For New Entrants and Emerging Players: EU Battery Regulation recycled-content certification fast-track offers entry into cathode precursor supply without upstream mining exposure. Target grid-scale energy storage procurement in India and Texas where qualification timelines compress and purity thresholds relax. Pursue direct recycling technology partnerships to bypass primary refining capital intensity.
For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors integrated miner-refiners with captive ore and renewable-powered processing. Long-term viability over the next decade rests on positioning ahead of binding recycled-content mandates and solid-state battery substitution risk. Monitor cathode chemistry patent filings as the critical inflection signal for nickel demand intensity trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| HPAL Capacity Expansion | Indonesian hydrometallurgical investment secures battery-grade nickel sulfate supply for Korean cathode plants. |
| Backward Integration into Brine Assets | Direct lithium extraction from Argentine salt lakes compresses project timelines versus traditional evaporation. |
| Carbon Footprint Certification Program | EU Battery Regulation compliance enables qualified supplier status for European automotive offtake. |
| Direct Recycling Technology Partnership | Hydrometallurgical cathode regeneration bypasses primary smelting for nickel and manganese recovery. |
| Long-term Supply Agreement | Automaker prepay structures with Chilean extractors eliminate merchant market price exposure. |
Research Methodology
Desk research of customs trade databases, SEC filings from diversified mining conglomerates, and EU regulatory documentation preceded structured interviews with cathode plant procurement directors, HPAL project developers, and automaker supply chain strategists. Primary fieldwork with lithium brine operators and nickel laterite miners combined with secondary validation against MIIT production statistics and EIA energy storage deployment data. Bottom-up capacity modeling triangulated against top-down demand aggregation across electric vehicle and grid storage applications.
Variance decomposition across metal type, cathode chemistry, application segment, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from supply-demand balance modeling incorporating qualification timeline lags, HPAL ramp curves, and recycled-content mandate phase-ins. Forecast inputs integrated EPA rule stringency scenarios and Indonesian export policy trajectory assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained electric vehicle penetration and nickel-rich chemistry dominance; material deviation in solid-state battery commercialization or cobalt substitution would warrant model refresh. Recalibration cycles align with material shifts in cathode chemistry patents, EU regulatory enforcement dates, and Indonesian local content policy revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Automotive 48V Lithium Battery Market
Lithium-ion Battery
Canada Electric Vehicle Battery Anode Market
Lithium-ion Battery
Portable Lithium Battery Energy Storage Products Market
Lithium-ion Battery
North America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium-Ion Battery Packs Market
Lithium-ion Battery
Liquid Lithium Ion Battery Market
Lithium-ion Battery
China Electric Vehicle Battery Anode Market
Lithium-ion Battery
Europe Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium Ion Battery Cathodes Market
Lithium-ion Battery
Lithium-Ion Batteries Electric Bike Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium Ion Battery Wet Coated Diaphragm Market
Lithium-ion Battery
Lithium-Ion Battery Anode Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
Lithium Nickel Manganese Cobalt Oxide Battery Market
Lithium-ion Battery
South America Electric Vehicle Battery Electrolyte Market